
 Digital Biomarkers Market | 2026-2036
Digital Biomarkers Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Biomarkers Market Intelligence
Asset-light licensing models for algorithm platforms is tilting competitive dynamics toward firms that avoid hardware manufacturing overhead. Biofourmis leverages its FDA-cleared analytics to anchor hospital-at-home programs across multiple health systems. Empatica specializes in wrist-worn sensors for neurology and psychiatry endpoints, sustaining a defensible position in CNS trial recruitment. AliveCor dominates handheld ECG capture, extending its reach through direct-to-consumer channels alongside enterprise contracts.
Digital biomarkers comprise quantifiable physiological and behavioral indicators collected through connected sensors, processed via validated algorithms, and submitted to regulators as trial endpoints or clinical decision inputs; these systems typically integrate accelerometry, photoplethysmography, and machine learning inference to detect disease progression or treatment response with temporal granularity impossible through conventional lab testing. Wearable devices occupy the largest technology position due to established reimbursement for cardiac monitoring, while smartphone apps represent the fastest-expanding segment as cognitive assessments and voice biomarkers reduce trial site burden. Clinical research commands the deepest margin pool among applications, since pharmaceutical sponsors pay premium licensing fees for regulatory-grade digital endpoints that accelerate approval timelines.
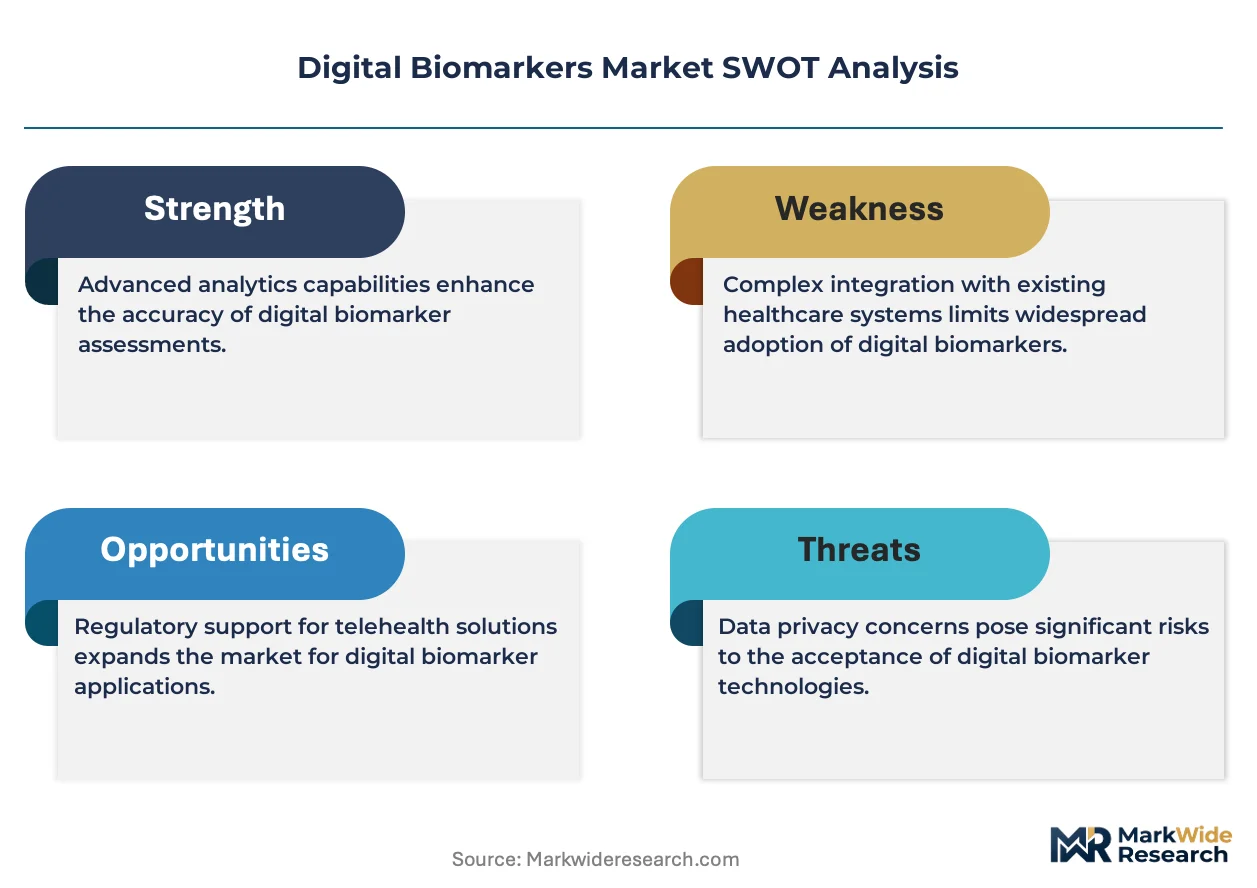
FDA's Digital Health Center of Excellence and the 21st Century Cures Act framework shape validation requirements, compelling developers to demonstrate analytical and clinical validity before endpoint qualification; in Europe, EMA's qualification opinion process and MDR device classification determine whether biomarker software requires notified body certification. Stakeholders must monitor evolving evidentiary standards for algorithm updates, as regulators increasingly treat machine learning-enabled biomarkers as living systems subject to continuous performance verification rather than one-time clearance.
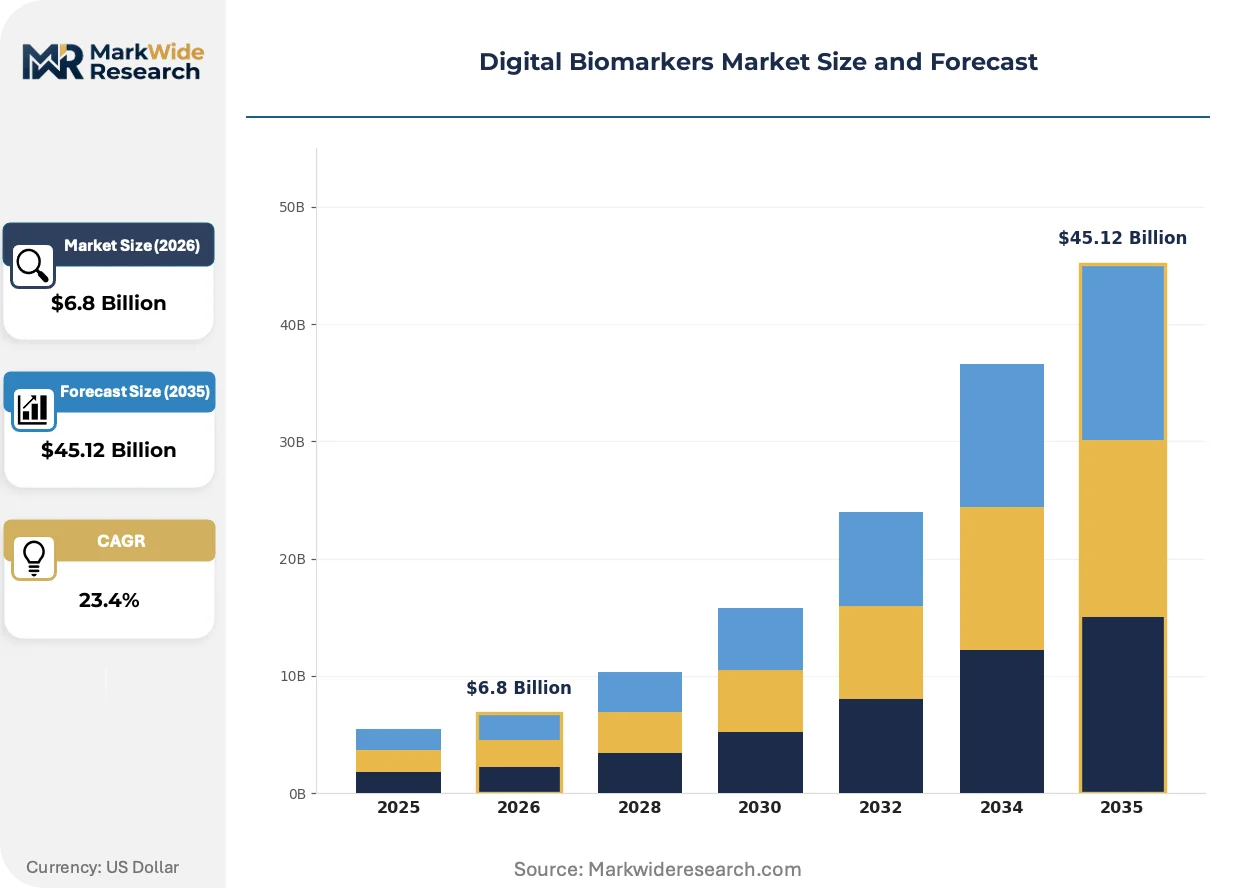
Market Dynamics
Pharmaceutical sponsors now demand regulatory-grade endpoints that compress trial timelines, forcing algorithm developers to validate software-as-medical-device pipelines under FDA's 21st Century Cures Act framework rather than pursuing hardware manufacturing scale.
Growth Catalysts
- Decentralized trial infrastructure:Contract research organizations deploy wearable-derived endpoints to reduce site visit burdens, accelerating patient recruitment for neurology and cardiology studies.
- FDA Digital Health Center of Excellence:The agency's streamlined qualification pathways reduce validation timelines for algorithm platforms seeking 510(k) clearance for biomarker extraction.
- Photoplethysmography advances:Optical sensor miniaturization enables continuous cardiac monitoring through consumer-grade wristbands, expanding addressable populations beyond implantable device candidates.
Market Restraints
- Algorithm update verification costs:FDA treats machine learning-enabled biomarkers as living systems requiring continuous performance documentation, inflating post-market surveillance expenditures.
- EMA MDR classification uncertainty:European software-as-medical-device determinations vary across notified bodies, creating compliance fragmentation for multi-country trial deployment.
- Silicon photonics supply concentration:Specialized optical sensor fabrication concentrates among East Asian foundries, exposing hardware developers to input cost volatility.
Strategic Opportunities
- Rural health system penetration:Hospital-at-home reimbursement expansion creates demand for remote physiological monitoring in underserved US geographies lacking specialty cardiology access.
- Voice biomarker integration:Smartphone-based cognitive assessments converge with natural language processing to detect early Parkinson's progression without dedicated hardware.
- Japan's Sakigake designation:PMDA's accelerated review pathway for breakthrough digital therapeutics attracts developers seeking priority regulatory access for neurology endpoints.
Industry Challenges
- Biostatistician talent scarcity:Validated algorithm development requires specialists combining clinical domain knowledge with regulatory submission experience, creating hiring bottlenecks.
- Electronic health record integration complexity:Proprietary hospital IT architectures resist standardized biomarker data ingestion, forcing costly custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Biomarkers Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $45.12 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wearable Devices, Smartphone Apps, Remote Monitoring, Cloud-Based Solutions Application: Chronic Disease Management, Mental Health, Fitness Tracking, Clinical Research End User: Healthcare Providers, Research Institutions, Pharmaceuticals, Consumers Data Type: Physiological Data, Behavioral Data, Biomarker Data, Activity Data |
| Companies Covered | Biofourmis, AliveCor Inc., Empatica Inc., Koneksa Health Inc., Altoida Inc., BioSensics LLC, ActiGraph LLC, VivoSense Inc., Clario, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Biomarkers Market Strategic Shifts & Innovations
Algorithm-centric business models are displacing hardware-dependent revenue streams as developers prioritize recurring licensing over device sales, while regulatory frameworks coalesce around continuous validation rather than one-time clearance.
Edge computing architectures for biomarker inference is migrating from cloud-dependent processing to on-device execution, reducing latency for real-time clinical alerts. Cardiac monitoring sponsors in the United States now require sub-second arrhythmia detection to enable timely intervention protocols. This shift compresses infrastructure costs for trial operators while demanding more sophisticated semiconductor design from sensor manufacturers.
EMA's qualification opinion process for novel methodologies now explicitly addresses digital biomarker evidentiary standards, compelling European developers to submit prospective validation studies before endpoint integration into pivotal trials. Cardiovascular and respiratory indications face the steepest documentation requirements under this framework. German and French academic medical centers are responding by building internal biostatistics capabilities rather than outsourcing algorithm validation.
Pharmaceutical procurement of digital endpoints now favors multi-therapeutic-area platforms over single-indication tools, consolidating vendor relationships and reducing contract negotiation overhead. Sponsors in immuno-oncology and rare disease verticals lead this consolidation, seeking standardized data formats across trial portfolios. This pattern is most pronounced among mid-cap biotech firms headquartered in the Boston and San Diego clusters.
Digital Biomarkers Market Segmentation
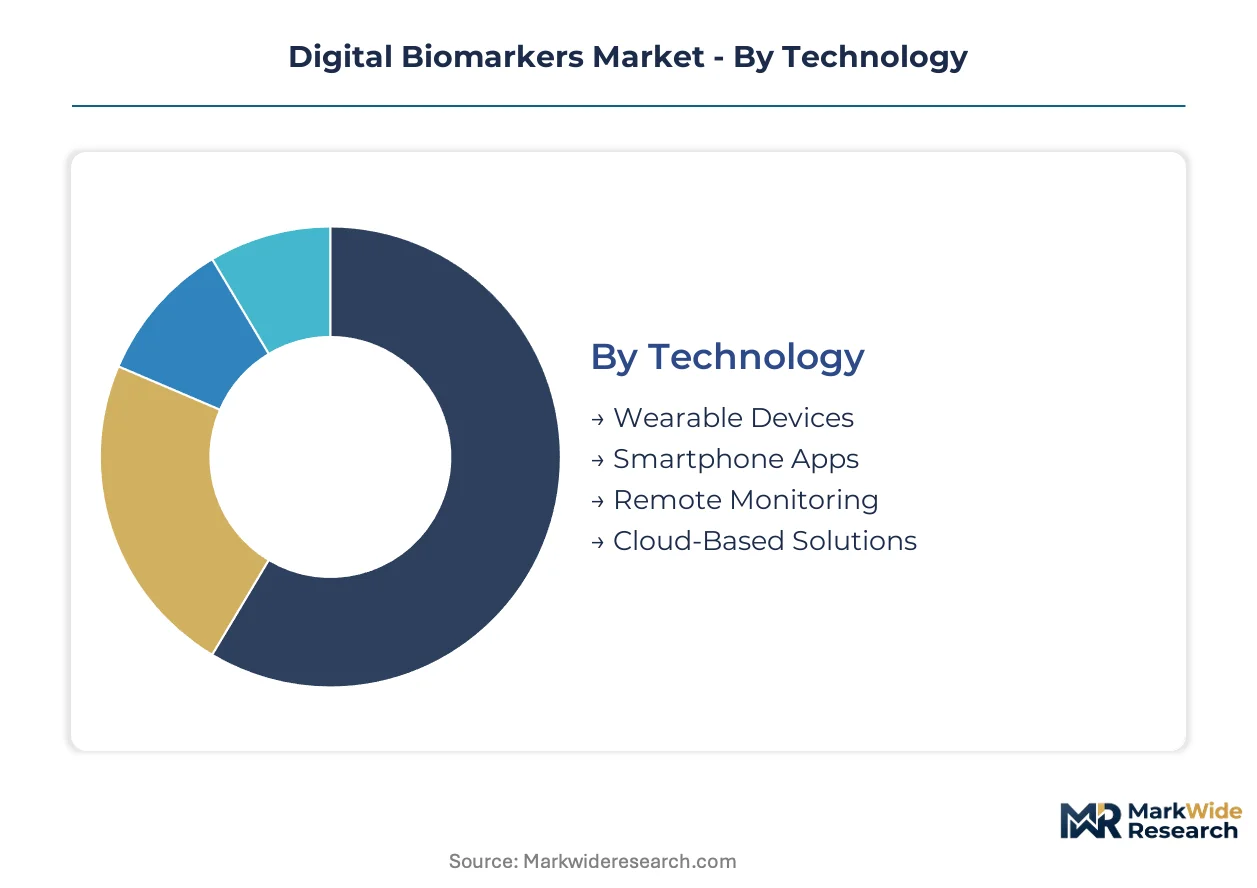
Digital biomarker segmentation reveals divergent commercial models across hardware-dependent and software-native technologies. Application context determines reimbursement pathways and regulatory burden, while end-user concentration shapes pricing power and contract structure.
Technology:
Use-case spectrum spans continuous physiological capture to episodic data collection, with infrastructure requirements dictating margin profiles.
- Wearable Devices:Accelerometry and photoplethysmography sensors enable uninterrupted cardiac and activity monitoring through wrist-worn or patch form factors. Pharmaceutical sponsors in the United States pay premium licensing fees for FDA-cleared endpoints that compress neurology trial timelines.
- Smartphone Apps:Voice biomarkers and cognitive assessments eliminate dedicated hardware requirements, reducing patient burden in decentralized trials. Academic medical centers in Boston and San Diego deploy these tools for remote Parkinson's progression tracking.
- Remote Monitoring:Hospital-at-home programs integrate multi-parameter telemetry for post-acute surveillance.
- Cloud-Based Solutions:Algorithm platforms process edge-device inputs through centralized inference pipelines.
Established volume favors wearable devices; emerging adoption favors smartphone apps.
Application:
Revenue concentration aligns with reimbursement certainty and regulatory validation depth.
- Clinical Research:Regulatory-grade endpoints command the deepest margin pool as sponsors seek accelerated approval pathways under FDA's 21st Century Cures Act framework. Contract research organizations build proprietary analytics pipelines for biomarker extraction.
- Chronic Disease Management:Continuous glucose and cardiac monitoring sustains recurring revenue through durable medical equipment reimbursement. Health systems in Germany and France prioritize these tools for heart failure remote monitoring.
- Mental Health:Digital phenotyping through sleep and activity patterns addresses psychiatry trial recruitment challenges.
- Fitness Tracking:Consumer-grade wellness metrics operate outside medical device classification, limiting clinical adoption.
Contract value concentrates in clinical research; patient volume expansion favors chronic disease management.
End User:
Procurement sophistication varies from enterprise licensing to direct-to-consumer subscription.
- Pharmaceuticals:Sponsors demand validated algorithm platforms with pre-negotiated FDA qualification pathways, consolidating vendor relationships across therapeutic portfolios.
- Healthcare Providers:Hospital-at-home reimbursement expansion drives health system investment in remote physiological monitoring infrastructure.
- Research Institutions:Academic medical centers develop internal biostatistics capabilities rather than outsourcing algorithm validation.
- Consumers:Direct-to-consumer cardiac monitoring extends reach through retail channels alongside enterprise contracts.
Enterprise procurement favors pharmaceuticals; addressable population scale favors consumers.
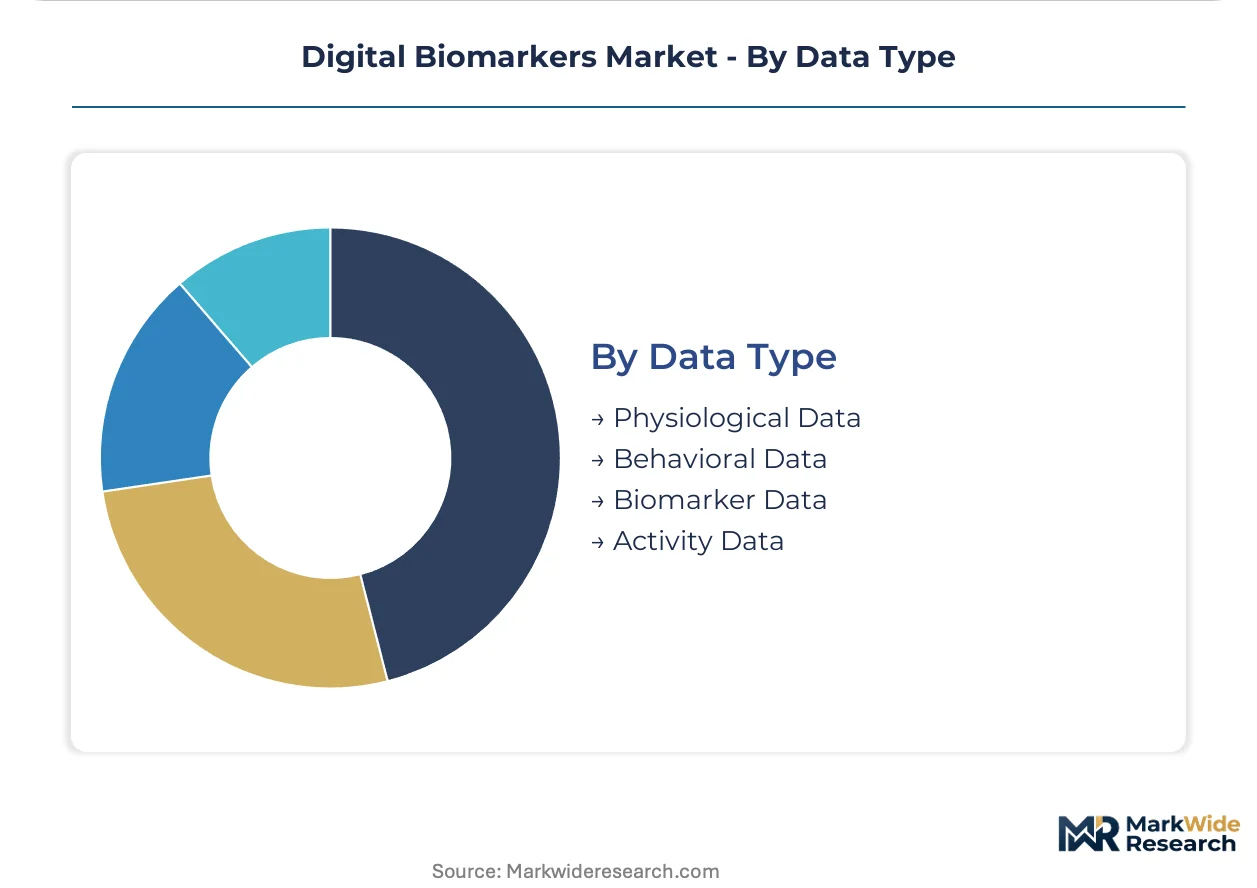
Data Type:
Regulatory acceptance correlates with analytical validity demonstration and clinical utility evidence.
- Physiological Data:Electrocardiography and photoplethysmography outputs dominate endpoint qualification submissions to FDA's Digital Health Center of Excellence.
- Biomarker Data:Validated algorithm-derived indicators from continuous streams support regulatory decision-making.
- Behavioral Data:Sleep architecture and circadian patterns enable psychiatric and neurological endpoint development.
- Activity Data:Accelerometry-based functional assessments quantify mobility decline in neurodegenerative conditions.
Regulatory maturity favors physiological data; innovation velocity favors behavioral data.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial trade surplus in digital biomarker algorithm licensing, while hardware component imports from East Asian foundries dominate physical device trade flows. European and Asian markets exhibit net importer status for regulatory-grade endpoint platforms, driving cross-border R&D service contracts.
United States
FDA's Digital Health Center of Excellence accelerates 510(k) clearances for algorithm platforms, attracting pharmaceutical sponsors seeking compressed trial timelines. Academic medical centers in Boston and San Diego build proprietary analytics pipelines for neurology endpoint extraction. Hospital-at-home reimbursement expansion drives health system procurement of remote cardiac monitoring infrastructure.
Germany
EMA's qualification opinion process for novel methodologies compels developers to submit prospective validation studies before pivotal trial integration. Baden-Württemberg and Bavaria host biostatistics clusters where academic medical centers develop internal algorithm validation capabilities. Health insurers increasingly reimburse continuous glucose and heart failure remote monitoring.
Japan
PMDA's Sakigake designation for breakthrough digital therapeutics attracts developers prioritizing neurology endpoints for accelerated review. Tokyo and Osaka metropolitan areas concentrate pharmaceutical sponsor offices demanding multi-therapeutic-area platform consolidation. METI funding supports edge computing semiconductor design for on-device biomarker inference.
United Kingdom
NICE technology appraisals determine reimbursement eligibility for digital biomarker-enabled chronic disease management tools. London and Cambridge clusters house contract research organizations deploying wearable-derived endpoints for decentralized trials. MHRA post-Brexit regulatory pathways diverge from EMA timelines, creating parallel submission requirements.
Switzerland
Swissmedic's streamlined software-as-medical-device classifications enable faster market entry for algorithm platforms relative to EU MDR processes. Basel and Zurich pharmaceutical headquarters drive demand for regulatory-grade endpoints across rare disease and immuno-oncology portfolios. Swiss academic medical centers specialize in cardiovascular and respiratory indication validation studies.
Digital Biomarkers Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the sensor and semiconductor layers. The vendor base organizes around three strategic archetypes: algorithm-centric licensors avoiding hardware manufacturing overhead, wearable device manufacturers with FDA-cleared endpoints, and full-stack hospital-at-home operators. Competitive dynamics center on M&A activity consolidating multi-therapeutic-area platforms and strategic partnerships between pharmaceutical sponsors and algorithm developers for pre-negotiated qualification pathways.
Within the algorithm-centric tier, Biofourmis leverages FDA-cleared analytics to anchor hospital-at-home programs, while Empatica occupies a specialized position in wrist-worn sensors for neurology and psychiatry endpoints. AliveCor represents the handheld diagnostic segment, extending reach through direct-to-consumer channels alongside enterprise contracts. These three companies exemplify divergent hardware-software positioning strategies within the broader competitive set.
| Leading Market Players |
|---|
| Biofourmis |
| AliveCor Inc. |
| Empatica Inc. |
| Koneksa Health Inc. |
| Altoida Inc. |
| BioSensics LLC |
| ActiGraph LLC |
| VivoSense Inc. |
| Clario |
| Others |
Cost & Logistics Intelligence
Single-source dependency on East Asian optical sensor foundries compresses margin structures across hardware tiers while amplifying price volatility for FDA-cleared device manufacturers. This concentration forces tiered spreads between premium algorithm-licensing contracts and economy hardware bundles.
Pricing Analysis
Pharmaceutical sponsors anchor pricing structures through multi-year algorithm licensing agreements with volume-scaled royalty tiers. Price differentiation rests on FDA 510(k) clearance status and analytical validation depth, with regulatory-grade endpoints commanding substantial premiums over wellness-tier alternatives. Cost compression in hardware manufacturing intensifies as optical sensor miniaturization commoditizes wrist-worn form factors. Contract research organizations exhibit highest price sensitivity due to trial budget constraints, while health systems demonstrate lowest sensitivity where hospital-at-home reimbursement guarantees margin protection.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk profiles for wearable device assemblers. Specialized semiconductor fabrication concentrates in Taiwan, South Korea, and Japan, with photoplethysmography sensors and edge-computing chips drawing from these nodes. Silicon photonics supply bottlenecks create single-source vulnerability for continuous cardiac monitoring hardware. Distribution runs through contract research organization procurement channels and health system group purchasing organizations, with direct-to-consumer retail emerging as secondary pathway.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated algorithm development capability sits at acute scarcity, with biostatisticians combining clinical domain expertise and regulatory submission experience commanding premium compensation. This talent gap constrains expansion velocity for platform developers.
For Market Incumbents: Harden regulatory moats through pre-negotiated FDA qualification opinion pathways that lock in sponsor relationships across therapeutic portfolios. Deepen backward integration into edge-computing semiconductor design to reduce dependency on East Asian foundry allocation. Threat exposure centers on emerging smartphone-native voice biomarker platforms that eliminate dedicated hardware requirements.
For New Entrants and Emerging Players: Establish a beachhead in psychiatric digital phenotyping where behavioral endpoint validation remains underdeveloped and trial recruitment challenges create sponsor urgency. Voice biomarker integration for Parkinson's progression monitoring represents the most penetrable white space. Go-to-market execution should prioritize academic medical center partnerships in Boston and San Diego clusters to generate publication-backed validation.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors multi-therapeutic-area platform aggregators over single-indication point solutions. Long-term viability favors algorithm-centric licensors with recurring revenue models and minimal hardware manufacturing overhead. Acquisition target archetypes include FDA-cleared analytics platforms with existing pharmaceutical sponsor relationships. The signal to watch is EMA MDR classification harmonization progress, which would unlock European trial deployment scale.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates pharmaceutical sponsor adoption through pre-validated endpoint qualification. |
| Academic Medical Center Partnership | Generates peer-reviewed validation studies that anchor regulatory submission packages. |
| Multi-Therapeutic Platform Integration | Reduces vendor consolidation risk for sponsors managing cross-portfolio trial programs. |
| Hospital-at-Home Reimbursement Strategy | Unlocks health system procurement budgets through Medicare remote monitoring codes. |
| Edge Computing Semiconductor Investment | Enables sub-second arrhythmia detection required for real-time clinical intervention protocols. |
Research Approach
The analysis maps wearable device hardware, algorithm platforms, smartphone applications, and cloud-based analytics pipelines, each validated through pharmaceutical development executives, regulatory affairs leads at digital health firms, contract research organization procurement managers, and hospital biomedical engineering directors. Primary interview findings triangulate against FDA 510(k) clearance databases, EMA qualification opinion records, ClinicalTrials.gov endpoint specifications, and CMS reimbursement code filings. Bottom-up revenue estimates from individual platform developers converge with top-down market sizing derived from pharmaceutical R&D expenditure allocations.
Forecast assumptions hold FDA Digital Health Center of Excellence qualification timelines and 21st Century Cures Act framework stability constant across the projection horizon, while varying decentralized trial adoption rates and hospital-at-home reimbursement expansion scenarios. Segmentation dimensions span technology type, application context, end-user procurement sophistication, and data regulatory maturity. CAGRs derive from fitted growth curves against historical pharmaceutical digital endpoint licensing patterns. Industry-specific inputs include photoplethysmography sensor cost decline trajectories and biostatistician labor market tightness indices.
Stress conditions across EMA MDR classification uncertainty, East Asian foundry capacity allocation, and algorithm update verification cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumption sets and acknowledge machine learning-enabled biomarker regulatory evolution as primary revision risk. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Digital Assistants in Healthcare Market
Digital Health Solutions
United Kingdom Digital Health Market
Digital Health Solutions
Global Microservices in Healthcare Market
Digital Health Solutions
Cloud Technologies in Healthcare Market
Digital Health Solutions
Medically Prescribed Apps Market
Digital Health Solutions
Lifestyle Diseases Apps Market
Digital Health Solutions
Econsent in Healthcare Market
Digital Health Solutions
Medical Animation Market
Digital Health Solutions
Global Digital Medicines Market
Digital Health Solutions
Virtual Reality (VR) in Healthcare Market
Digital Health Solutions
Electronic Data Capture Systems Market
Digital Health Solutions
Digital Healthcare Solutions Market
Digital Health Solutions
VR in Healthcare Market
Digital Health Solutions
Digital Patient Engagement Solutions Market
Digital Health Solutions
Global Patient Engagement Solution Market
Digital Health Solutions
Care Management Solutions Market