
 Advanced Clinical Decision Support Platforms Market | 2026-2036
Advanced Clinical Decision Support Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Clinical Decision Support Platforms Market Outlook
North American health IT infrastructure is hardening around real-time analytics requirements. Oracle Health leverages extensive EHR integration depth to anchor enterprise contracts across integrated delivery networks. Epic Systems Corporation sustains dominance in academic medical centers through proprietary interoperability protocols that limit vendor switching.
Advanced clinical decision support platforms synthesize patient data, medical literature, and institutional protocols to generate evidence-based recommendations at the point of care, typically processing structured and unstructured inputs through machine learning pipelines with sub-second inference latency. Diagnostic assistance tools lead product type revenue as radiology and pathology departments prioritize FDA-cleared algorithms for lesion detection and malignancy scoring. Cloud-based deployment is expanding fastest among telehealth providers seeking elastic compute for episodic consultation volumes without capital-intensive server commitments.
FDA software-as-a-medical-device frameworks and HIPAA security rule enforcement shape product architecture requirements, compelling vendors to maintain predicate device clearance pathways and encrypted data governance. The EU AI Act risk classification system and CE marking obligations under MDR create parallel compliance burdens for platform developers seeking transatlantic commercialization. Stakeholders must monitor evolving FDA guidance on adaptive algorithms and predetermined change control plans to sustain market access.
Market Dynamics
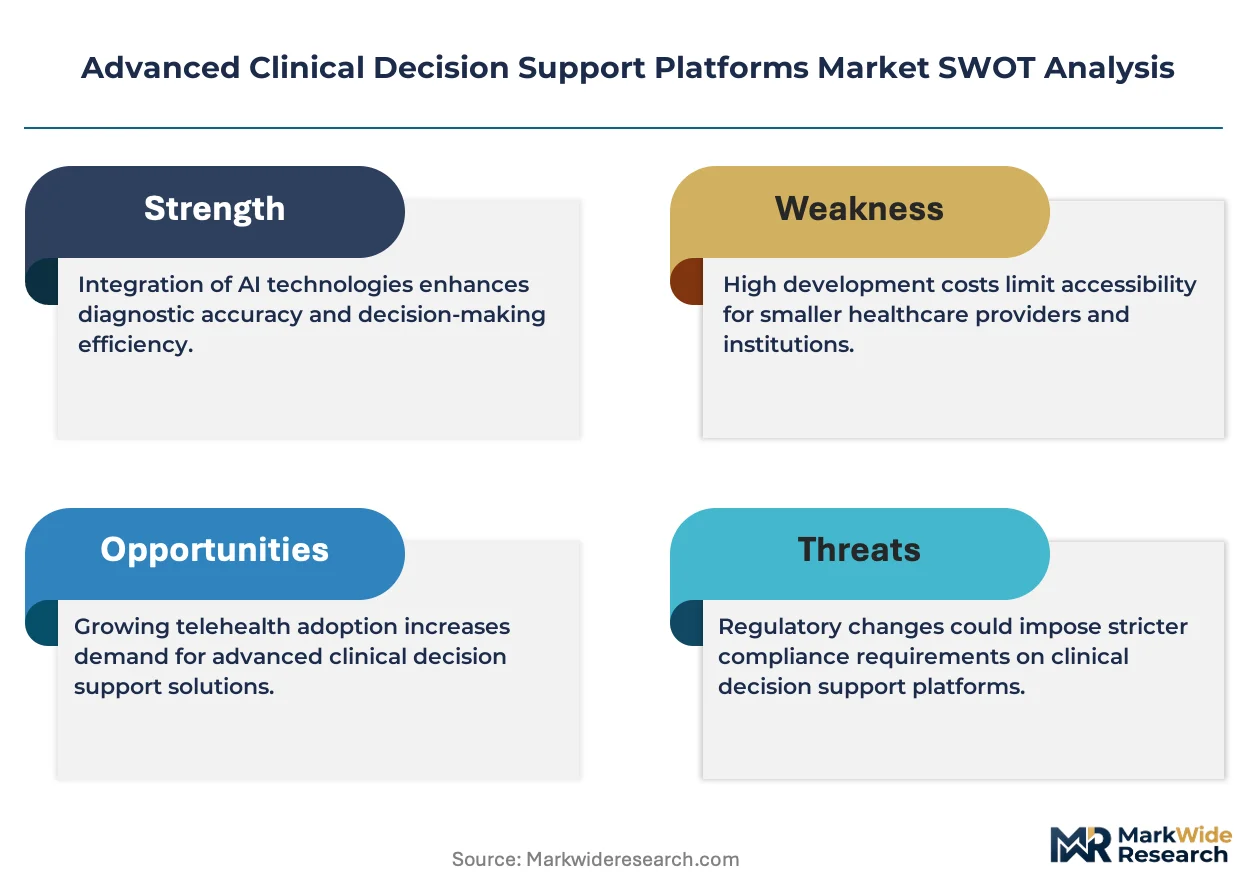
FDA's evolving guidance on adaptive algorithms is compressing product development cycles while fragmenting vendor compliance pathways, forcing platform developers to architect for predetermined change control plans before initial 510(k) submission.
Growth Catalysts
- EU AI Act risk classification:High-risk system designations for diagnostic assistance modules are accelerating vendor investment in explainable AI pipelines to secure CE marking under MDR conformity assessment routes.
- Cloud-native telehealth providers:Episodic consultation volumes without capital-intensive infrastructure are driving elastic compute procurement for real-time inference at the point of care.
- Radiology department prioritization:Lesion detection and malignancy scoring algorithms cleared through FDA 510(k) pathways are anchoring enterprise procurement decisions across integrated delivery networks.
Market Restraints
- HIPAA security rule enforcement:Encrypted data governance requirements and business associate agreement complexity are extending sales cycles for on-premise deployment models.
- Specialized machine learning engineering talent:Scarce expertise in healthcare-specific model validation and clinical workflow integration is inflating R&D compensation costs.
- Proprietary interoperability protocols:Dominant EHR vendors limit third-party integration depth, constraining platform functionality and switching flexibility for hospital systems.
Strategic Opportunities
- Pathology department digitization:Whole-slide imaging adoption creates whitespace for algorithmic quantification of immunohistochemical staining patterns in oncology workflows.
- Predetermined change control plans:FDA's emerging framework for algorithm modification without new submissions offers first-mover advantage to vendors with robust post-market surveillance infrastructure.
- Germany and United Kingdom hospital modernization:NHS trusts and university hospitals are prioritizing cloud-based deployment during IT infrastructure refresh cycles.
Industry Challenges
- Sub-second inference latency requirements:Real-time clinical decision support demands edge computing architecture that fragments deployment models and complicates vendor support structures.
- Unstructured data pipeline engineering:Natural language processing of clinical notes requires specialized expertise in medical ontologies and semantic interoperability standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Clinical Decision Support Platforms Market |
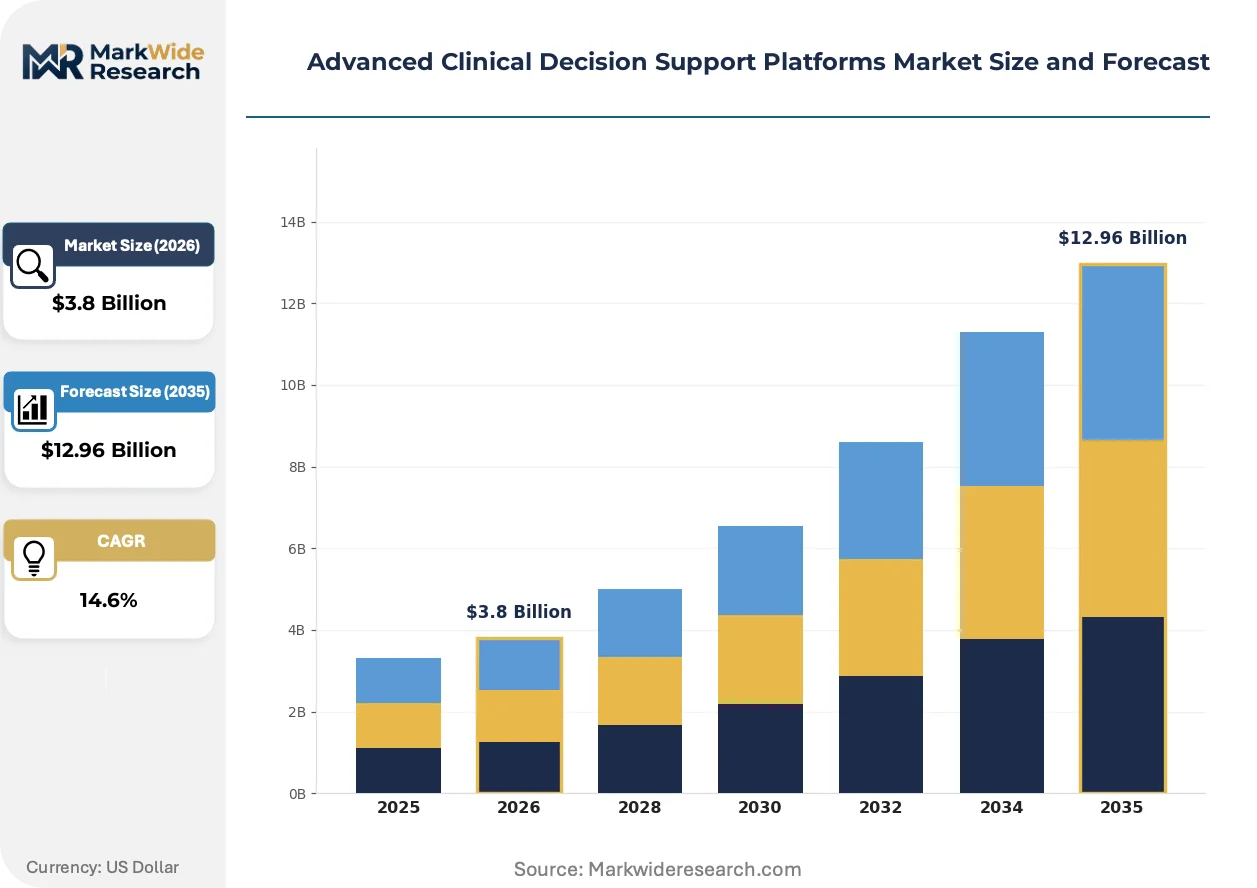
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Physician Support Tools, Diagnostic Assistance, Treatment Guidelines, Risk Assessment Systems End User: Hospitals, Primary Care Clinics, Specialty Clinics, Telehealth Providers Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Applications Technology: Machine Learning, Natural Language Processing, Predictive Analytics, Rule-Based Systems |
| Companies Covered | Oracle Health, GE HealthCare, Wolters Kluwer Health, McKesson Corporation, Meditech, Philips Healthcare, Cerner Corporation, IBM Watson Health, Epic Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Clinical Decision Support Platforms Market Strategic Shifts
Machine learning inference architectures are compressing from cloud-centric to hybrid-edge configurations, driven by latency-sensitive clinical applications and evolving data residency requirements across jurisdictions.
Foundation models trained on multimodal clinical data are rewriting diagnostic assistance capabilities, enabling single-platform deployment across radiology, pathology, and genomics workflows. Academic medical centers in the United States are piloting these systems for cross-specialty consultation support. The technology is rewriting competitive positioning by collapsing the traditional segmentation between point-solution vendors and enterprise platform providers.
The EU AI Act's high-risk system obligations are mandating human oversight interfaces and algorithmic transparency documentation for diagnostic assistance modules. This regulatory architecture is elevating compliance costs for transatlantic commercialization while creating differentiation for vendors with established quality management systems. Radiology departments across Germany and France are prioritizing CE-marked solutions with embedded explainability features to satisfy clinical governance committees.
Hospital procurement committees are unbundling decision support licensing from EHR enterprise agreements, creating direct purchasing relationships with specialized platform vendors. This pattern is displacing traditional channel structures where EHR vendors controlled third-party application access. The United Kingdom's NHS trusts are most advanced in this transition, with explicit frameworks for standalone clinical AI procurement outside core electronic health record contracts.
Advanced Clinical Decision Support Platforms Market Segmentation
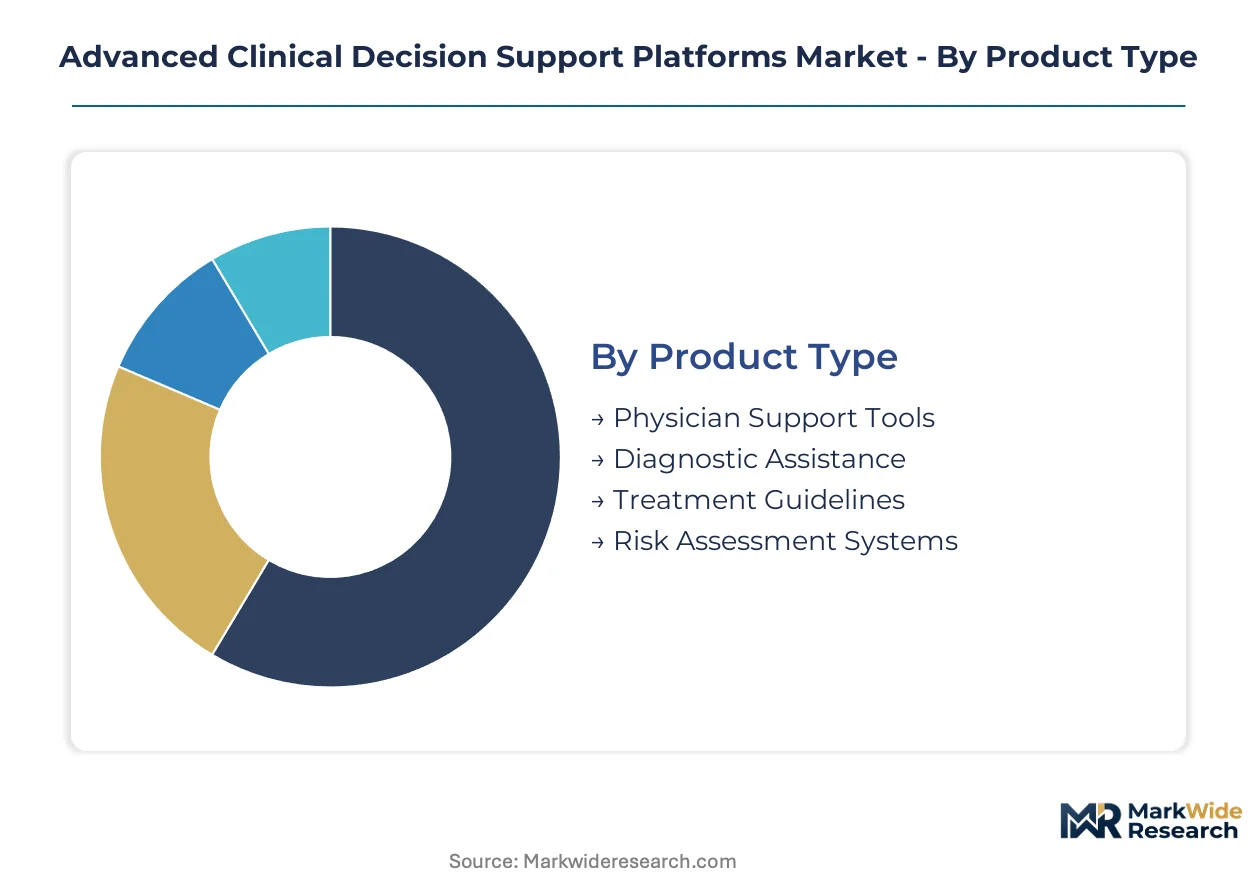
Advanced clinical decision support platforms fragment across four critical dimensions that shape procurement patterns and vendor positioning. Product architecture, deployment infrastructure, and underlying technology stack determine compliance pathways and integration complexity for healthcare delivery organizations.
Product Type:
Volume concentration clusters in workflow-embedded modules, while premium pricing attaches to specialized diagnostic algorithms requiring regulatory clearance.
- Diagnostic Assistance:FDA-cleared algorithms for lesion detection and malignancy scoring process medical imaging with sub-second inference latency. Radiology departments across integrated delivery networks anchor enterprise procurement decisions around these modules. Mature deployment sits with Diagnostic Assistance. Newer deployment is concentrated in Risk Assessment Systems.
- Physician Support Tools:Real-time clinical documentation assistance and order set recommendations integrate directly into EHR workflows through proprietary interoperability protocols. Academic medical centers prioritize these tools for reducing cognitive load during high-volume consultation periods.
- Treatment Guidelines:Evidence-based protocol engines synthesize institutional pathways with patient-specific parameters to standardize care delivery across distributed clinical teams.
- Risk Assessment Systems:Predictive models for readmission probability and sepsis onset detection leverage longitudinal patient data streams to flag deteriorating conditions before clinical manifestation.
Diagnostic Assistance commands premium licensing through regulatory moats, while Physician Support Tools scale through volume-based EHR integration contracts.
End User:
Procurement authority separates between capital-equipped hospital systems and agile telehealth platforms with elastic infrastructure requirements.
- Hospitals:Enterprise-wide platform deployments spanning multiple service lines require hardened cybersecurity architecture and business associate agreement complexity. These organizations dominate absolute spending on clinical decision support infrastructure.
- Telehealth Providers:Episodic consultation volumes without capital-intensive server commitments drive cloud-native procurement for real-time inference at the point of care. United Kingdom NHS trusts and Germany's university hospitals are expanding fastest in this category.
- Specialty Clinics:Cardiology and oncology ambulatory centers prioritize condition-specific modules with embedded clinical pathway automation.
- Primary Care Clinics:Resource-constrained settings favor lightweight decision support with minimal IT overhead and subscription-based pricing models.
Hospital systems anchor current installed base. Telehealth Providers are gaining share fastest as virtual care models proliferate.
Deployment:
Data residency requirements and latency sensitivity fragment architecture choices across jurisdictions with divergent privacy enforcement.
- Cloud-Based:Elastic compute provisioning enables telehealth providers and distributed clinic networks to scale inference capacity without hardware procurement cycles. Germany and United Kingdom health systems are prioritizing this model during IT modernization. Cloud-Based represents the fastest-growing trajectory.
- Hybrid:Edge computing configurations process latency-sensitive diagnostic queries locally while aggregating training data in central repositories for model refinement.
- On-Premises:Air-gapped installations satisfy HIPAA security rule enforcement for organizations with restrictive data governance policies, though extended sales cycles constrain vendor growth.
- Mobile Applications:Point-of-care tablet and smartphone deployments support bedside consultation workflows with offline inference capabilities for intermittent connectivity environments.
On-Premises dominates legacy installations. Cloud-Based is climbing the fastest as NHS trusts and German university hospitals refresh infrastructure.
Technology:
Foundation model architectures are collapsing traditional boundaries between statistical and symbolic reasoning approaches.
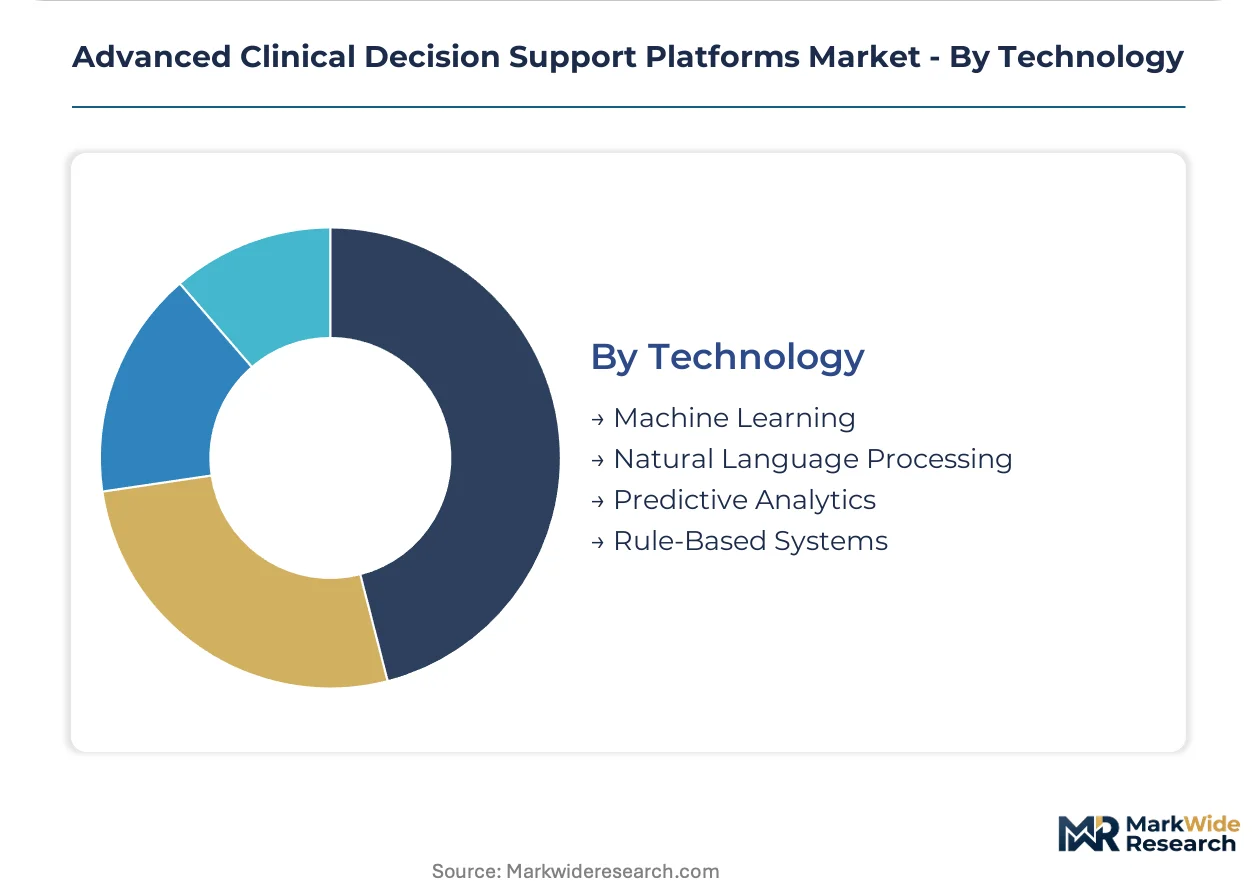
- Machine Learning:Supervised and self-supervised neural architectures trained on multimodal clinical data enable cross-specialty diagnostic assistance spanning radiology, pathology, and genomics workflows. Academic medical centers in the United States are piloting these systems for consultation support.
- Natural Language Processing:Clinical note comprehension engines extract structured phenotypes from unstructured documentation to populate decision support inputs without manual abstraction.
- Predictive Analytics:Time-series forecasting models project disease progression and treatment response probabilities to personalize intervention timing.
- Rule-Based Systems:Deterministic clinical logic engines provide transparent, auditable recommendations for high-stakes decisions requiring explainable reasoning pathways.
Rule-Based Systems anchor established quality management frameworks. Machine Learning is expanding most quickly as multimodal foundation models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's concentration of health AI engineering talent anchors United States platform development. Cloud infrastructure investments across Germany and the United Kingdom are accelerating European procurement cycles.
United States
FDA 510(k) clearance pathways for diagnostic assistance modules drive enterprise procurement across integrated delivery networks. The agency's emerging predetermined change control plan framework is compressing product development timelines for adaptive algorithms. Academic medical centers in Boston and the San Francisco Bay Area pilot multimodal foundation models for cross-specialty consultation support.
Germany
University hospitals in Bavaria and North Rhine-Westphalia prioritize cloud-based deployment during IT infrastructure modernization cycles. The EU AI Act's high-risk system designation for diagnostic modules mandates explainable AI pipelines under MDR conformity assessment. Berlin's digital health cluster anchors vendor compliance investment for CE-marked solutions with embedded transparency documentation.
United Kingdom
NHS trusts in London and the Midlands are unbundling decision support licensing from EHR enterprise agreements. The Medicines and Healthcare products Regulatory Agency aligns with EU AI Act risk classifications for transatlantic commercialization pathways. Manchester's health innovation district concentrates pilot programs for standalone clinical AI procurement frameworks.
Japan
PMDA's software-as-a-medical-device guidance shapes architecture requirements for diagnostic assistance platforms entering the market. METI's digital transformation subsidies accelerate hospital IT modernization in the Kanto and Kansai regions. Tokyo's academic medical centers validate edge computing configurations for sub-second inference latency in radiology workflows.
India
CDSCO's evolving framework for AI-enabled medical devices creates parallel compliance pathways for diagnostic assistance modules. Telehealth providers in Maharashtra and Karnataka leverage cloud-native deployment for episodic consultation volumes without capital-intensive infrastructure. Bangalore's health technology cluster concentrates engineering talent for clinical workflow integration and model validation.
Advanced Clinical Decision Support Platforms Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized diagnostic niches and cloud-native delivery models. The vendor base stratifies across three maturity tiers: legacy EHR-integrated platforms, standalone AI specialists, and hybrid-edge infrastructure providers. Oracle Health and Epic Systems Corporation exemplify the EHR-anchored archetype with proprietary interoperability protocols. Wolters Kluwer Health and Philips Healthcare represent the standalone clinical content and device-integrated segments. Competitive dynamics center on M&A activity for workflow integration capabilities and strategic partnerships for foundation model licensing.
Within the EHR-anchored tier, Oracle Health and Epic Systems Corporation occupy positions defined by extensive integration depth across integrated delivery networks. Cerner Corporation and Meditech sit within the same structural category with varying geographic concentration. GE HealthCare and Philips Healthcare exemplify the device-integrated archetype, leveraging imaging hardware relationships to anchor diagnostic assistance module deployment. IBM Watson Health represents the technology-licensing approach, positioning around enterprise AI infrastructure rather than point-of-care workflow embedding. McKesson Corporation anchors the pharmaceutical distribution-linked segment, with clinical decision support serving adjacent medication management workflows.
| Leading Market Players |
|---|
| Oracle Health |
| GE HealthCare |
| Wolters Kluwer Health |
| McKesson Corporation |
| Meditech |
| Philips Healthcare |
| Cerner Corporation |
| IBM Watson Health |
| Epic Systems Corporation |
| Others |
Value Chain & Pricing Dynamics
Foundation model architectures trained on multimodal clinical data are compressing R&D cost curves while concentrating compute infrastructure among hyperscale cloud providers, simultaneously lowering per-inference costs and tightening vendor dependency on NVIDIA GPU supply chains and AWS-Google-Azure compute reservations.
Pricing Analysis
Post-market surveillance and algorithm update warranties separate premium diagnostic assistance tiers from unbundled entry offerings. Three-tier pricing structure across FDA-cleared premium modules, CE-marked standard deployments, and economy workflow-embedded tools anchors procurement negotiations. Price differentiation centers on regulatory clearance tier and explainable AI pipeline depth. Cost compression in cloud-native tiers is intensifying because telehealth providers negotiate elastic compute rates at scale. Primary care clinics exhibit highest price sensitivity; academic medical centers anchored to Epic and Oracle EHR ecosystems show lowest.
Supply Chain Analysis
Reverse-logistics flows for edge computing hardware refurbishment and GPU cluster redeployment create secondary supply channels for budget-constrained hospital systems. Silicon Valley, Taiwan, and Ireland concentrate machine learning inference chip fabrication and cloud data center buildouts. Raw material dependencies span NVIDIA A100/H100 GPUs, high-bandwidth memory modules, and specialized medical-grade edge servers. Single-source vulnerability sits with TSMC's advanced node concentration for AI accelerators. Distribution runs through direct enterprise sales teams and GPO-negotiated framework agreements with health system procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized machine learning engineering talent scarcity props pricing power for vendors with validated clinical workflow integration capabilities, constraining supply expansion despite demand acceleration from NHS trusts and integrated delivery networks.
For Market Incumbents: Anchor enterprise retention through proprietary interoperability protocol deepening and predetermined change control plan infrastructure investment. Defend against standalone AI specialists by embedding diagnostic assistance modules directly into EHR order entry workflows. Prioritize FDA 510(k) clearance pathway acceleration to maintain regulatory moats against cloud-native challengers.
For New Entrants and Emerging Players: Enter via pathology department digitization whitespace created by whole-slide imaging adoption lagging radiology AI penetration. Target Germany and United Kingdom hospital modernization cycles for cloud-based deployment first-mover positioning. Pursue direct procurement frameworks outside EHR enterprise agreements as the go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with hybrid-edge infrastructure providers given EU AI Act human oversight interface mandates and latency-sensitive diagnostic application proliferation. Long-term viability favors vendors with established quality management systems spanning FDA and MDR conformity assessment routes. Monitor predetermined change control plan FDA guidance finalization as inflection signal for adaptive algorithm platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Predetermined Change Control Plan Infrastructure | FDA's emerging framework for algorithm modification without new submissions compresses product development timelines for adaptive diagnostic assistance platforms. |
| CE Marking Pathway Acceleration | EU AI Act high-risk system designation for diagnostic modules mandates explainable AI pipelines under MDR conformity assessment routes. |
| Hospital System Partnership | NHS trusts unbundling decision support licensing from EHR enterprise agreements creates direct procurement relationships with specialized platform vendors. |
| Software Companion Development | Human oversight interfaces and algorithmic transparency documentation satisfy clinical governance committees in Germany and France radiology departments. |
| Reimbursement Strategy | CPT code establishment for AI-assisted diagnosis anchors procurement justification for integrated delivery network capital committees. |
Study Parameters
FDA 510(k) clearance databases, EU MDR conformity assessment records, and hospital procurement contract filings formed the secondary backbone. Primary interviews with hospital purchasing committee chairs, biomedical informatics officers, GPO contracts managers, and regulatory affairs leads at platform developers cross-validated deployment model preferences and pricing benchmarks. Bottom-up triangulation against top-down health IT spending estimates anchored volume and value projections.
Bottom-up modeling of cloud compute provisioning costs, licensing fee structures, and implementation service revenues across product type, deployment infrastructure, end user, and technology stack dimensions fed into CAGR derivation through regression analysis against historical health AI investment patterns. Hyperscaler capex disclosures and NVIDIA data center revenue segmentations provided infrastructure scaling parameters.
Revisions become necessary when FDA adaptive algorithm guidance finalization, EU AI Act enforcement timelines, or HIPAA security rule amendments materialize differently than modeled assumptions. Practitioners should monitor PMDA software-as-a-medical-device guidance evolution and CDSCO AI-enabled medical device framework development for early signals of transatlantic regulatory divergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Econsent in Healthcare Market
Digital Health Solutions
Connected Healthcare Market
Digital Health Solutions
Digital Healthcare Solutions Market
Digital Health Solutions
Healthcare Mobile Application Market
Digital Health Solutions
Cloud Technologies in Healthcare Market
Digital Health Solutions
Mhealth Apps Market
Digital Health Solutions
Teleradiology Software Market
Digital Health Solutions
Pharmacovigilance (PV) and Drug Safety Software Market
Digital Health Solutions
Digital Assistants in Healthcare Market
Digital Health Solutions
Global Patient Centric Healthcare App Market
Digital Health Solutions
North America Digital Health Market
Digital Health Solutions
US Digital Health Market
Digital Health Solutions
Women Digital Health Solutions Market
Digital Health Solutions
Connected Health and Wellness Devices Market
Digital Health Solutions
Mobile Tablets in Healthcare Market
Digital Health Solutions
Digital Therapeutics Market