
 US Digital Signage Market | 2026-2036
US Digital Signage Market Size, Share, and Industry Trends Forecast 2026-2036
US Digital Signage Market Intelligence
Market Context
LED backlighting is repositioning LCD panel economics across the US digital signage value chain. Samsung Electronics Co. Ltd leverages vertical integration in display semiconductor manufacturing to control cost curves in high-brightness outdoor units. LG Electronics anchors its competitive stance through OLED differentiation in premium indoor retail environments. Daktronics dominates sports venue and transportation hub installations with specialized large-format LED engineering.
Technical Definition and Segment Structure
US digital signage encompasses networked electronic display systems—comprising LED, LCD, OLED, and projection technologies—that deliver dynamic visual content for commercial communication, wayfinding, advertising, and audience engagement. These systems integrate media players, content management software, and connectivity protocols to enable remote scheduling and real-time updates across distributed screen networks. LED product types capture the fastest expansion as pixel pitch compression and thermal management advances open indoor corporate and retail applications previously reserved for LCD. Outdoor installations command premium pricing due to IP-rated enclosure requirements and ambient light compensation engineering, while wall-mounted configurations retain volume leadership in quick-service restaurant and healthcare waiting room deployments.
Regulatory Framework and Outlook
FCC equipment authorization mandates govern RF-emitting smart signage modules, constraining product design cycles for wireless-enabled displays. OSHA workplace safety standards influence mounting hardware specifications and electrical installation protocols in commercial environments. ADA accessibility guidelines shape screen placement, tactile interface requirements, and audible content alternatives in public facilities. Stakeholders must monitor evolving state-level energy efficiency codes and utility rebate programs that increasingly favor low-power display technologies over legacy fluorescent-backlit systems.
Market Dynamics
LED pixel pitch compression below 1.2mm is electrifying indoor corporate and luxury retail deployments, collapsing the historical performance gap with LCD while enabling seamless architectural integration previously unattainable with legacy display technologies.
Growth Catalysts
- OSHA workplace safety standards:Mandated electrical installation protocols and mounting hardware specifications in commercial environments are accelerating certified contractor networks and professional installation services, expanding addressable project value per deployment.
- Quick-service restaurant chains:Drive-thru menu board modernization and in-store promotional screen networks are pulling demand for high-brightness outdoor and wall-mounted indoor configurations across franchise systems.
- Texas and California media production clusters:Corporate headquarters concentration and entertainment industry post-production facilities are driving large-format LED volume for command centers, screening rooms, and experiential marketing installations.
Market Restraints
- Display semiconductor supply concentration:Taiwan and South Korea foundry capacity constraints for high-brightness LED driver ICs create lead time volatility for outdoor unit manufacturers dependent on specialized thermal management components.
- FCC equipment authorization cycles:RF-emitting smart signage modules face 12-16 week certification timelines, constraining product launch velocity for wireless-enabled display portfolios targeting retail and hospitality networks.
- Fluorescent-backlit LCD substitution ceiling:Legacy installed base in cost-sensitive healthcare waiting rooms and municipal transit systems resists upgrade cycles despite utility rebate program incentives for low-power alternatives.
Strategic Opportunities
- Midwestern sports venue infrastructure:Underpenetrated collegiate athletic facilities and minor league stadiums in Ohio, Michigan, and Illinois present white space for specialized large-format LED engineering previously concentrated in coastal professional venues.
- Utility rebate program expansion:State-level energy efficiency codes in New York and Massachusetts increasingly favor low-power display technologies, creating procurement preference shifts toward OLED and fine-pitch LED in public facility renovations.
- Content management software convergence:Integration of AI-driven audience analytics with cloud-native scheduling platforms enables real-time creative optimization for retail advertisers, opening subscription revenue streams beyond hardware margins.
Industry Challenges
- Network security certification complexity:NIST cybersecurity framework compliance for connected signage infrastructure extends deployment timelines for federal and healthcare clients requiring encrypted content distribution and remote monitoring protocols.
- Legacy AV integration friction:Hybrid environments mixing new IP-based display networks with existing SDI video infrastructure demand specialized signal conversion engineering, complicating unified content workflows in broadcast-adjacent corporate settings.
Report Scope
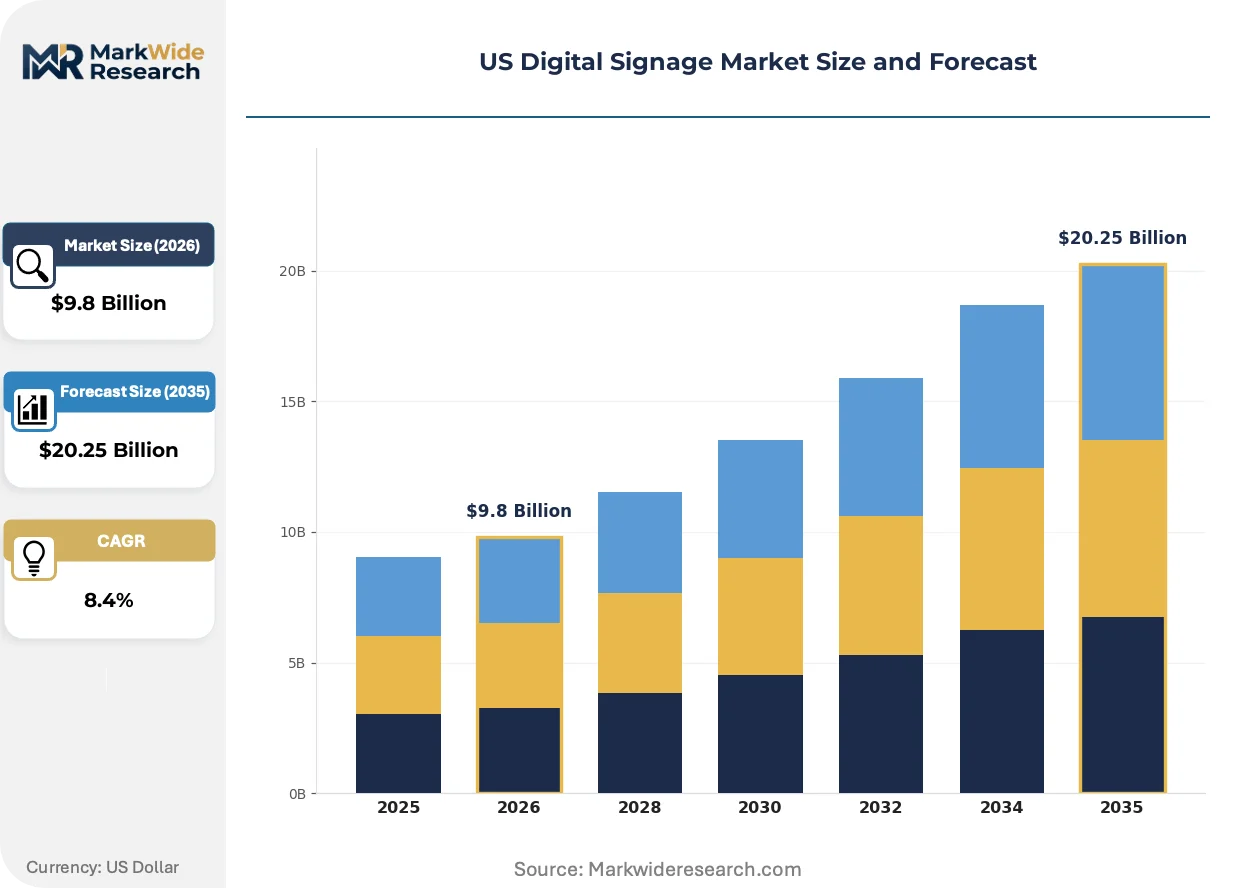
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Digital Signage Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, LCD, Projector, OLED End User: Retail, Transportation, Hospitality, Education Installation Type: Indoor, Outdoor, Wall-mounted, Freestanding Distribution Channel: Direct Sales, Online Retailers, Resellers, Distributors |
| Companies Covered | Samsung Electronics Co. Ltd, LG Electronics, SHARP NEC Display Solutions Ltd, Panasonic Corporation, Cisco Systems, Inc., Sony Corporation, BrightSign, LLC, Daktronics, Scala, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Digital Signage Market Strategic Shifts & Innovations
Mini-LED backlighting arrays and direct-view micro-LED prototypes are compressing the performance hierarchy across indoor display categories, while FCC equipment authorization evolution and shifting procurement governance reshape competitive positioning.
Mini-LED full-array local dimming is electrifying high-end retail and corporate lobby installations by delivering OLED-contrast performance without burn-in risk, enabling 24/7 operational reliability for luxury brands and financial services headquarters. Department store chains and premium automotive showrooms are adopting 85-inch and larger formats at accelerated replacement cycles. This technology is compressing the premium LCD segment and forcing OLED suppliers to defend position through transparent and flexible form factors.
FCC Part 15 unintentional radiator rules are tightening electromagnetic compatibility testing requirements for Wi-Fi and cellular-enabled smart signage, extending pre-market authorization timelines and increasing compliance engineering headcount for display OEMs. The industrial consequence is delayed product launches for interactive wayfinding and retail analytics-integrated screens. Outdoor transportation hub deployments are most affected, with manufacturers responding through modular RF subsystem pre-certification strategies.
Managed service procurement is displacing capital expenditure ownership models in quick-service restaurant and convenience store chains, compressing hardware margin capture while expanding recurring software and content subscription revenue pools. Equipment financing vehicles and per-screen monthly fee structures are replacing outright purchase in franchise systems. This shift is most visible in the Southeast and Southwest, where private equity-backed restaurant rollup strategies favor operational expenditure treatment for technology investments.
US Digital Signage Market Segmentation
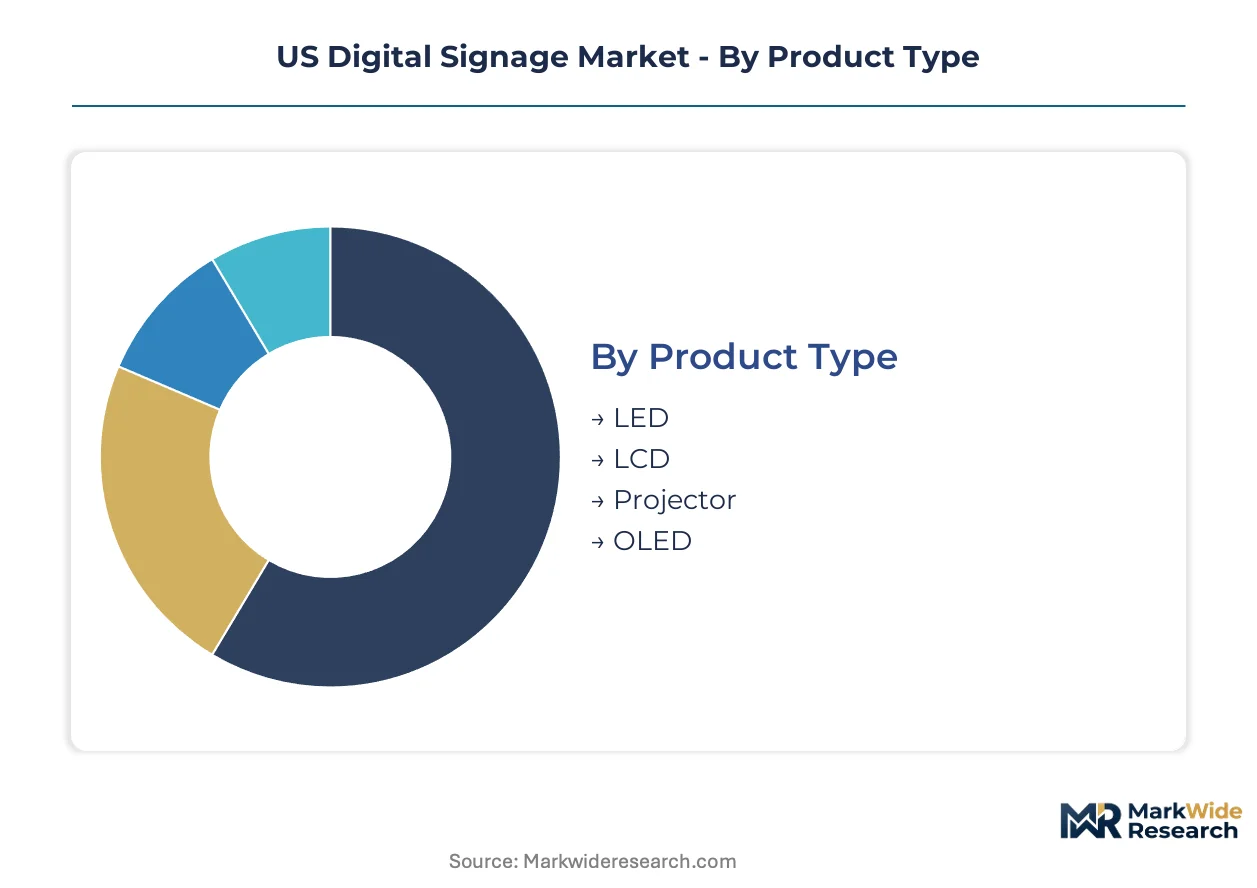
US digital signage segmentation reveals how display technology economics, installation environment requirements, and procurement channel structures create distinct competitive battlegrounds. Each dimension carries unique margin profiles, certification burdens, and customer concentration patterns that shape vendor strategy.
Product Type:
Supply concentration in LED driver ICs and OLED panel fabrication concentrates margin capture among vertically integrated display manufacturers, while LCD and projector segments face commoditization pressure from Asian panel oversupply.
- LED:Direct-view LED arrays with pixel pitch below 1.2mm now penetrate corporate lobbies and luxury retail previously reserved for LCD. Texas and California media production clusters command large-format LED volume for command centers and experiential installations.
- LCD:Mini-LED full-array local dimming is repositioning premium LCD economics in high-end retail and financial services headquarters, delivering OLED-contrast performance without burn-in risk for 24/7 operations.
- Projector:Short-throw laser projection retains niche positioning in temporary event installations and museum immersive environments where screen flexibility outweighs ambient light limitations.
- OLED:Transparent and flexible form factors defend premium positioning against mini-LED encroachment in flagship automotive showrooms and department store flagship locations.
Today's leader: LED. Tomorrow's challenger: OLED transparent formats.
End User:
Customer procurement maturity varies sharply across sectors, with quick-service restaurant chains and collegiate athletic programs driving volume through managed service contracts while transportation authorities impose extended security certification timelines.
- Retail:Franchise system standardization across quick-service restaurant drive-thru menu boards and in-store promotional networks pulls high-brightness outdoor and wall-mounted indoor configurations at accelerated replacement cycles.
- Transportation:FCC Part 15 electromagnetic compatibility requirements and NIST cybersecurity framework compliance extend deployment timelines for federal and municipal transit authority installations requiring encrypted content distribution.
- Hospitality:Hotel lobby and conference center deployments favor seamless architectural integration through fine-pitch LED and large-format LCD, with procurement shifting toward operational expenditure models under private equity-backed property management.
- Education:Underpenetrated collegiate athletic facilities in Ohio, Michigan, and Illinois present white space for specialized large-format LED engineering previously concentrated in coastal professional venues.
Retail commands current volume. Education offers the steepest expansion trajectory.
Installation Type:
Environmental protection engineering and mounting hardware certification requirements create tiered margin structures, with outdoor IP-rated enclosures and ADA-compliant tactile interfaces commanding premium pricing over standard indoor configurations.
- Indoor:Corporate headquarters and healthcare waiting rooms drive volume for wall-mounted and freestanding configurations, with utility rebate programs in New York and Massachusetts favoring low-power OLED and fine-pitch LED alternatives.
- Outdoor:IP-rated enclosure requirements and ambient light compensation engineering command premium pricing for transportation hub and sports venue installations, though Taiwan and South Korea foundry constraints for high-brightness LED driver ICs create lead time volatility.
- Wall-mounted:Quick-service restaurant chains and healthcare waiting rooms retain volume leadership for this configuration, with OSHA workplace safety standards mandating certified contractor networks for commercial electrical installation.
- Freestanding:Interactive wayfinding and retail analytics-integrated screens in shopping malls and hotel lobbies face delayed product launches due to extended FCC equipment authorization cycles for RF-emitting smart signage modules.
Wall-mounted dominates unit volume. Outdoor captures highest project value.
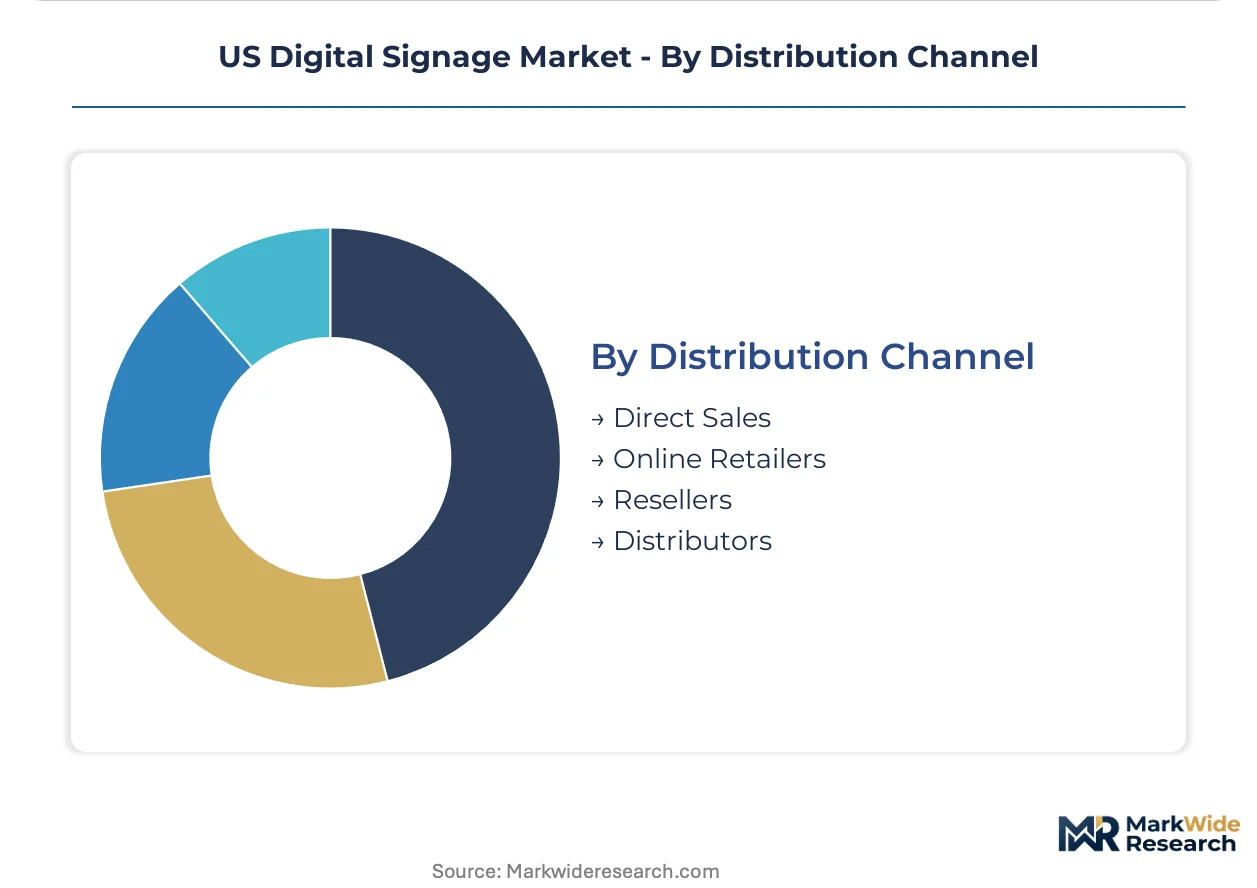
Distribution Channel:
Channel structure determines margin capture mode, with direct sales enabling solution bundling while reseller networks extend geographic reach into fragmented municipal and educational procurement environments.
- Direct Sales:Large-format LED engineering for sports venues and corporate command centers flows through manufacturer direct relationships, enabling integrated content management software and installation service bundling.
- Online Retailers:Standardized indoor LCD and projector SKUs for small business and hospitality procurement concentrate in this channel, with price transparency compressing hardware margins.
- Resellers:Regional AV integrators serve mid-market corporate and education clients requiring hybrid legacy SDI and new IP-based display network integration engineering.
- Distributors:Inventory carrying capacity for high-brightness outdoor units and specialized mounting hardware supports contractor networks in Texas and California construction markets.
Direct sales anchor premium projects. Resellers penetrate fragmented mid-market accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and California media production clusters anchor US digital signage demand through corporate headquarters concentration and entertainment industry infrastructure. State-level energy efficiency codes and utility rebate programs increasingly favor low-power display technologies in public facility renovations. Regional procurement patterns concentrate large-format LED volume in coastal command centers and experiential marketing installations.
California
Entertainment industry post-production facilities and technology sector headquarters drive demand for fine-pitch LED in screening rooms and corporate lobbies. The California Energy Commission Title 24 standards incentivize low-power OLED and mini-LED alternatives in public building renovations. Los Angeles and San Francisco media production clusters command premium large-format installations for experiential marketing and broadcast-adjacent corporate environments.
Texas
Corporate headquarters relocation trends and energy sector command center requirements pull high-brightness outdoor and indoor LED configurations. ERCOT grid reliability concerns accelerate backup power integration specifications for critical signage infrastructure. Dallas-Fort Worth and Austin metropolitan construction markets support distributor inventory carrying capacity for specialized mounting hardware and outdoor IP-rated enclosures.
New York
Financial services headquarters and retail flagship concentration demand 24/7 operational reliability through mini-LED full-array local dimming installations. The New York State Energy Research and Development Authority rebate programs favor low-power display technologies in commercial building retrofits. Manhattan corporate lobby and department store flagship deployments drive accelerated replacement cycles for 85-inch and larger formats.
Illinois
Underpenetrated collegiate athletic facilities and convention center infrastructure present expansion opportunities for specialized large-format LED engineering. State procurement guidelines increasingly reference ADA accessibility requirements for screen placement and tactile interface specifications in public facilities. Chicago metropolitan transportation hub deployments face extended FCC equipment authorization timelines for wireless-enabled smart signage modules.
Florida
Hospitality sector concentration and quick-service restaurant franchise density drive managed service procurement models favoring operational expenditure treatment. Hurricane-resistant outdoor enclosure specifications command premium engineering for transportation and entertainment venue applications. Miami and Orlando hotel lobby and conference center deployments favor seamless architectural integration through fine-pitch LED configurations.
US Digital Signage Market Key Industry Players
Global majors compete with regional champions across display technology integration and content management software bundling. The market structure tiers between vertically integrated semiconductor manufacturers, specialized large-format LED engineers, and cloud-native software platforms. Three archetypes dominate: captive component producers controlling cost curves, application-specific engineering specialists, and subscription-based managed service orchestrators. Competitive moves concentrate on strategic partnerships for content management integration and modular RF subsystem pre-certification strategies to compress FCC authorization timelines.
Within the captive component tier, Samsung Electronics Co. Ltd and LG Electronics exemplify vertically integrated display semiconductor manufacturing positions. Daktronics occupies a specialized large-format LED engineering position for sports venue and transportation hub installations. These three anchors represent distinct strategic postures: upstream cost curve control, premium indoor OLED differentiation, and outdoor application-specific thermal management expertise respectively.
| Leading Market Players |
|---|
| Samsung Electronics Co. Ltd |
| LG Electronics |
| SHARP NEC Display Solutions Ltd |
| Panasonic Corporation |
| Cisco Systems, Inc. |
| Sony Corporation |
| BrightSign, LLC |
| Daktronics |
| Scala |
| Others |
Cost & Logistics Intelligence
Performance-tier divergence between fine-pitch LED command centers and commodity LCD healthcare waiting rooms manifests in both margin capture and component sourcing strategies, with premium installations drawing captive semiconductor supply while cost-sensitive segments absorb Asian panel oversupply.
Pricing Analysis
Input-cost pass-through from Taiwan and South Korea LED driver IC foundries shapes project-based pricing for outdoor high-brightness units, with FCC certification grade and thermal management specification driving price differentiation between transportation hub installations and quick-service restaurant menu boards. Cost compression in indoor LCD segments is intensifying because of Chinese panel oversupply, while retail franchise systems show highest price sensitivity and corporate command centers demonstrate lowest sensitivity due to operational expenditure treatment preferences.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Los Angeles anchor hub-and-spoke patterns for specialized mounting hardware and IP-rated outdoor enclosures, with inventory concentration supporting Texas and California construction markets. Taiwan, South Korea, and China supply LED driver ICs, OLED panels, and LCD substrates respectively, drawing from gallium nitride substrates, indium tin oxide coatings, and polarizer films. Single-source vulnerability in high-brightness LED driver ICs creates lead time volatility, while distribution runs through manufacturer-direct relationships for large-format projects and AV integrator networks for mid-market accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Digital Signage Market functions as a stable compounder, with franchise system standardization across quick-service restaurant networks generating recurring hardware refresh cycles and managed service subscription revenues.
For Market Incumbents: Deepen backward integration into LED driver IC supply through strategic foundry partnerships in Taiwan and South Korea, mitigating lead time volatility that constrains outdoor unit delivery. Invest in modular RF subsystem pre-certification to compress FCC Part 15 authorization timelines for wireless-enabled smart signage portfolios. For New Entrants and Emerging Players: Cloud-native content management platforms offer the most penetrable entry vector, targeting underpenetrated collegiate athletic facilities in Ohio, Michigan, and Illinois with AI-driven audience analytics bundled on subscription tiers. Pursue managed service procurement relationships with private equity-backed restaurant rollup strategies in the Southeast and Southwest. For Investors and Strategic Acquirers: Consolidation pressure builds where content management software convergence outpaces standalone hardware margin capture, favoring acquisition targets with recurring SaaS revenue streams and federal NIST cybersecurity framework compliance. Watch for inflection where utility rebate program expansion in New York and Massachusetts accelerates low-power display procurement preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Modular RF Subsystem Pre-Certification | FCC Part 15 compliance acceleration compresses 12-16 week authorization timelines for wireless-enabled retail analytics screens. |
| Managed Service Procurement Expansion | Per-screen monthly fee structures displace capital expenditure ownership in quick-service restaurant franchise systems. |
| AI-Driven Audience Analytics Integration | Real-time creative optimization opens subscription revenue streams beyond hardware margins for retail advertisers. |
| Collegiate Athletic Facility Penetration | Underpenetrated Midwestern stadiums present white space for specialized large-format LED engineering capabilities. |
| Utility Rebate Program Alignment | State-level energy efficiency codes in New York and Massachusetts favor low-power OLED and fine-pitch LED alternatives. |
Research Approach
Coverage spans Texas, California, New York, Illinois, and Florida, with primary inputs from each state informing demand calibration. The analysis combines interviews with AV integrators, display OEM procurement directors, franchise operations technology leads, and content management software developers with secondary validation against FCC equipment authorization databases, OSHA workplace safety filings, and state energy commission rebate program records. Bottom-up project pipeline triangulation with top-down media production cluster economic indicators ensures segmentation integrity.
Rate-of-change decomposition separates volume expansion from value mix shift across the projection horizon. The analytical framework models display technology, end-user sector, installation environment, and procurement channel dimensions, with CAGRs derived from replacement cycle analysis and utility incentive program adoption curves. Inputs include franchise system standardization timelines, collegiate athletic facility renovation pipelines, and federal cybersecurity compliance cost burdens.
The model assumes a particular technology adoption path; alternative pathways for direct-view micro-LED commercialization would alter the outlook for mini-LED and OLED premium positioning. Forecasts reflect assumptions around FCC authorization timeline stability and Taiwan foundry capacity allocation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Work Order Management Systems Market
Digital Solutions
Global Interactive Voice Response Market
Digital Solutions
OTA Transmission Platform Market
Digital Solutions
Search Engine Optimization Services Market
Digital Solutions
Middle East and Africa Cloud Integration Market
Digital Solutions
Global Digital Experience Platform Market
Digital Solutions
Utility App Market
Digital Solutions
Interactive Kiosk Market
Digital Solutions
Global Enterprise Information Archiving Market
Digital Solutions
Digital Experience Technology Market
Digital Solutions
Green IT Services Market
Digital Solutions
UAE Digital Twin Market
Digital Solutions
Healthcare Video Conferencing Solutions Market
Digital Solutions
Mainframe Modernization Services Market
Digital Solutions
Returnless Refund Fraud Detection Market
Digital Solutions
Hiking Apps Market