
 Restaurant Delivery Robot Market | 2026-2036
Restaurant Delivery Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Restaurant Delivery Robot Market Analytics
Foodservice distribution channels are tilting toward automated last-yard fulfillment inside restaurant properties. Pudu Robotics anchors production scale across Asia-Pacific assembly plants. Bear Robotics differentiates through vertical integration into its own navigation stack. Starship Technologies navigates sidewalk regulatory complexity across multiple municipalities.
Restaurant delivery robots are wheeled or legged autonomous systems equipped with lidar, ultrasonic arrays, and machine-vision cameras, designed to transport prepared food and beverages from kitchen to table or curbside pickup point without human carriage. Autonomous robots lead unit shipments while semi-autonomous platforms retain cost advantages for smaller footprints. Food delivery commands the largest service-type revenue pool, though beverage delivery applications are gaining traction in high-turnover café formats.
China's SAMR enforces GB standards for service robot electrical safety and electromagnetic compatibility, while the US FDA coordinates with state health departments on food-contact surface protocols for robotic carriers. Japan's METI promotes service robot adoption through revised building codes that widen corridor widths for autonomous passage. Stakeholders must track how municipal sidewalk-rights rulings and food-handler certification requirements for machine surfaces reshape deployment economics and site-selection criteria.
Market Dynamics
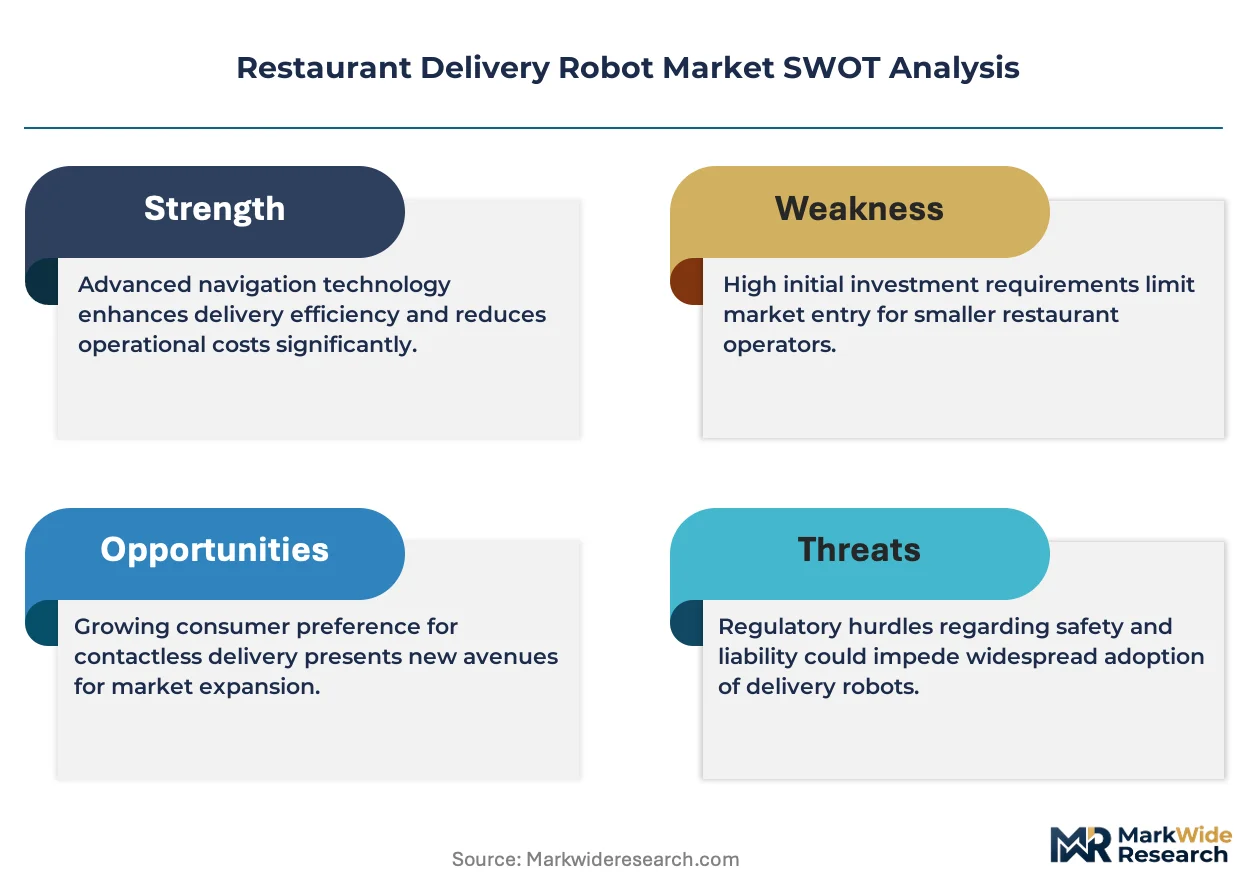
Lidar sensor costs have collapsed below the threshold where mid-size restaurant chains can justify fleet deployment, converting a capital barrier into a volume enabler across table-service formats.
Growth Catalysts
- GB Standard Electrical Safety Mandate:China's SAMR certification streamlines robot deployment across franchise networks by unifying safety protocols. This reduces site-by-site compliance friction.
- Machine-Vision Navigation Convergence:Fusion of lidar with depth cameras enables operation in cluttered dining floors without pre-mapped infrastructure. Operators retrofit existing footprints.
- Urban Labor Cost Compression:Minimum-wage escalations in tier-one Chinese cities push QSR chains toward kitchen-to-curbside automation. Wage arbitrage erodes within five-year payback windows.
Market Restraints
- LiDAR Supply Concentration:Solid-state lidar modules concentrate among Asian component foundries. Single-source dependency creates procurement vulnerability during demand spikes.
- Sidewalk Right-of-Way Fragmentation:Municipal ordinances in US cities impose divergent insurance, speed-limit, and weight restrictions. Compliance multiplicity inflates deployment costs.
- Human Waitstaff Substitution Threshold:Full-service formats retain tip-based labor economics that undercut robot ROI. Premium dining segments resist carrier-style automation.
Strategic Opportunities
- Hospital and Care Facility Catering:Isolated tray delivery in healthcare campuses bypasses sidewalk regulatory complexity. Infection-control protocols favor sealed autonomous carriers.
- Japan METI Building Code Revision:Widened corridor mandates in new construction embed robot passage infrastructure. Developers pre-wire charging stations and elevator interfaces.
- Beverage-First Café Formats:High-turnover coffee chains with standardized cup dimensions reduce payload variability. Simpler gripping mechanisms compress unit costs.
Industry Challenges
- Food-Handler Certification for Machine Surfaces:US FDA state-level protocols lack uniformity on sanitization validation. Operators face duplicate testing across jurisdictions.
- Legacy POS Integration:Kitchen display systems require API middleware to trigger robot dispatch. Custom integration timelines stretch deployment schedules.
- Ultrasonic Array Calibration Labor:Field technicians with robotics and foodservice dual competency remain scarce. Training pipelines lag fleet expansion rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Restaurant Delivery Robot Market |
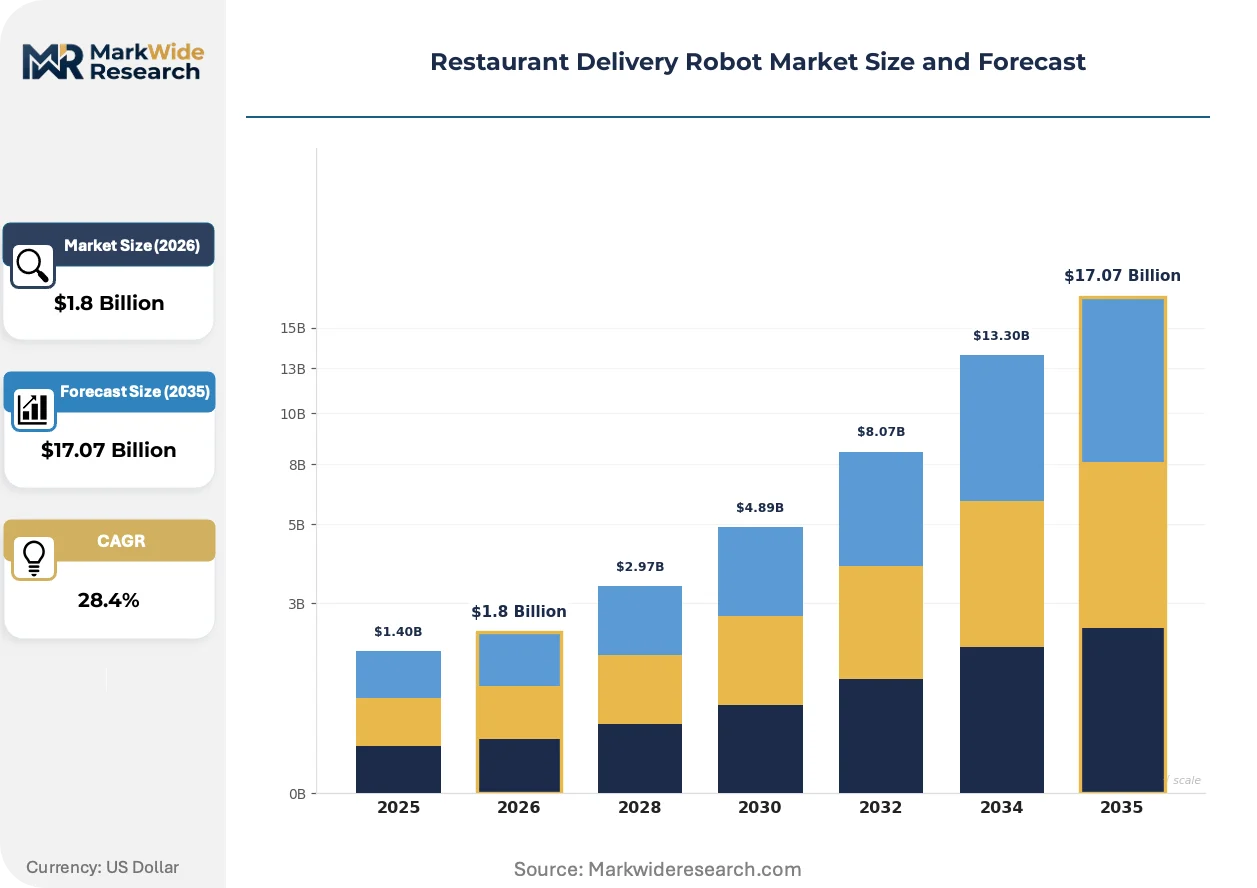
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.07 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Robots, Semi-Autonomous Robots, Drones, Walkable Robots Service Type: Food Delivery, Beverage Delivery, Grocery Delivery, Catering Services Customer Type: Restaurants, Cafés, Fast Food Chains, Hotels Technology: Navigation Systems, Artificial Intelligence, Sensor Technology, Communication Protocols |
| Companies Covered | Bear Robotics, Pudu Robotics, Keenon Robotics, Starship Technologies, Miso Robotics, Serve Robotics, Boston Dynamics, Relay Robotics, Kitchen Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Restaurant Delivery Robot Market Evolving Landscape
Navigation hardware commoditization is compressing differentiation timelines, forcing vendors toward software-defined fleet management and vertical service bundles.
Solid-state lidar arrays with MEMS beam steering are rendering obsolete mechanical spinning sensors in indoor deployment scenarios. Mid-size restaurant operators now specify sub-$500 perception stacks for tableside logistics. The cost floor collapse is accelerating replacement cycles from seven-year amortization to three-year refresh schedules.
Japan's METI revised building code standards now mandate minimum corridor widths and elevator call-button heights compatible with autonomous passage. Commercial real estate developers in Tokyo and Osaka pre-install inductive charging pads and fleet docking bays. New construction permits face faster approval when robot infrastructure is documented.
Franchise procurement committees now bundle robot fleet contracts with preventive maintenance and software upgrade clauses, displacing capital-purchase models. US-based full-service chains negotiate throughput-guarantee terms with vendors. The shift concentrates contract value with fleet operators capable of remote diagnostics and predictive component replacement.
Restaurant Delivery Robot Market Segmentation
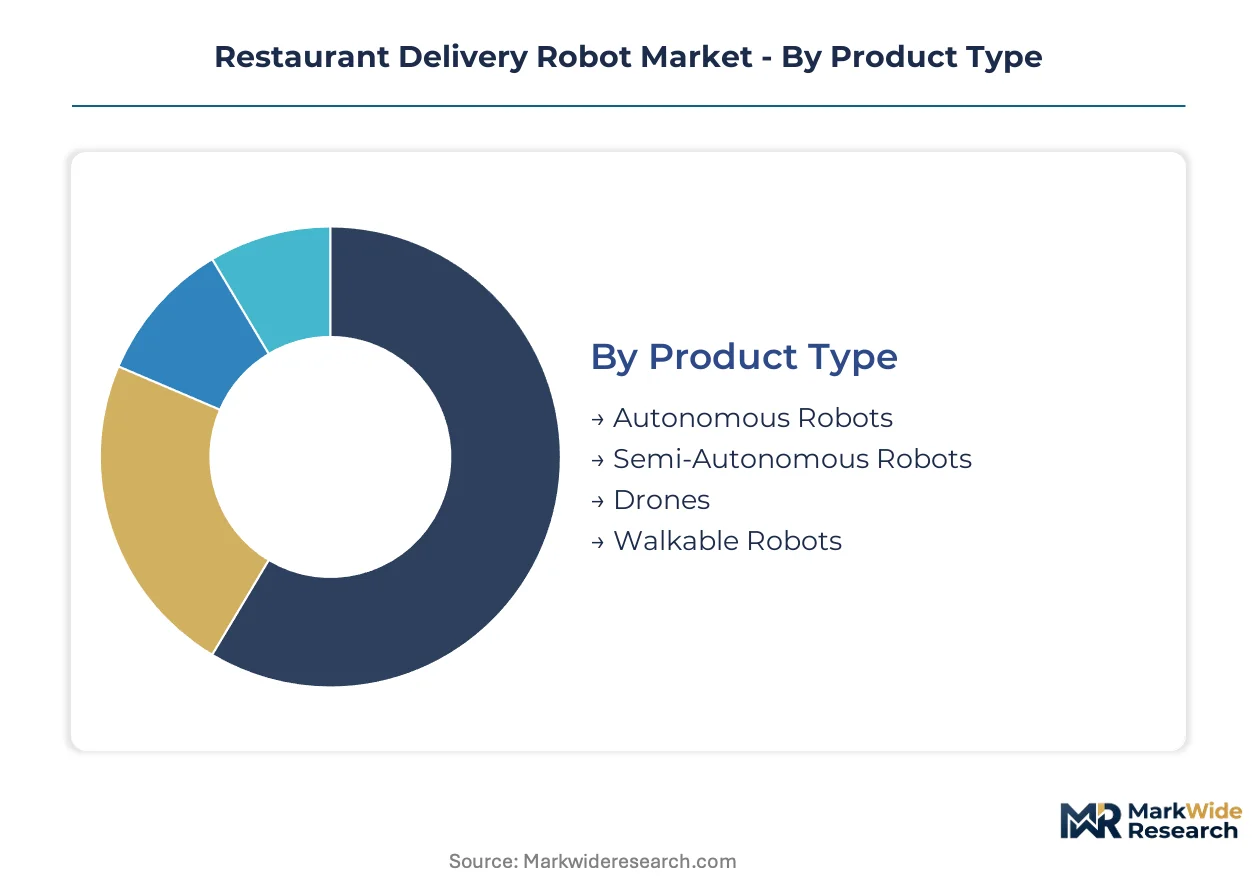
Restaurant delivery robot segmentation reveals how deployment economics vary across autonomy levels, service applications, and venue formats. Understanding these divides helps vendors align hardware specifications with operational constraints and regulatory exposure.
Product Type:
Mature wheeled platforms coexist with emerging legged architectures as cost curves diverge sharply.
- Autonomous Robots:Fully self-navigating units deploy lidar-vision fusion for dynamic obstacle avoidance in unstructured dining floors. Demand concentrates in urban China, where SAMR certification and labor cost compression accelerate franchise fleet rollouts.
- Semi-Autonomous Robots:Human-supervised carriers reduce sensor payload requirements and enable operation in legacy buildings without infrastructure retrofit. Smaller footprints in Japan and South Korea favor this tier for narrow corridor navigation.
- Drones:Aerial platforms bypass ground-level congestion for rooftop-to-curbside delivery in dense metropolitan clusters.
- Walkable Robots:Bipedal or quadrupedal designs traverse stairs and uneven outdoor surfaces where wheeled units fail.
Autonomous robots retain volume leadership; walkable robots hold the steepest expansion curve.
Service Type:
Application complexity ranges from standardized beverage transport to variable-grocery logistics with diverging payload engineering.
- Food Delivery:Hot-meal transport dominates current deployment, with sealed thermal compartments maintaining temperature bands across kitchen-to-table distances. Fast-food chains in China and the United States drive procurement volume.
- Beverage Delivery:Standardized cup dimensions enable simpler gripping mechanisms and faster cycle times in high-turnover café formats.
- Grocery Delivery:Variable package sizes and weight distributions demand adaptive payload platforms with higher motor torque specifications.
- Catering Services:Tray-based hospital and corporate campus delivery leverages isolated corridor networks to bypass sidewalk regulatory complexity.
Food delivery commands installed base leadership; catering services are climbing the fastest as healthcare infection-control protocols favor sealed autonomous carriers.
Customer Type:
Venue operational models dictate fleet sizing, with tip-based labor economics resisting automation in full-service formats.
- Restaurants:Table-service establishments deploy back-of-house logistics robots while resisting front-of-house substitution where gratuity structures underpin staff compensation.
- Cafés:Beverage-first formats with standardized menus and rapid turnover compress payback windows through high daily trip frequency.
- Fast Food Chains:Kitchen-to-curbside automation aligns with drive-through and pickup-only footprints, minimizing customer-robot interaction complexity.
- Hotels:Room-service and banquet logistics leverage existing elevator infrastructure and isolated vertical circulation paths.
Fast-food chains anchor procurement volume; hotels represent the most rapid adoption trajectory as METI building codes embed robot passage infrastructure.
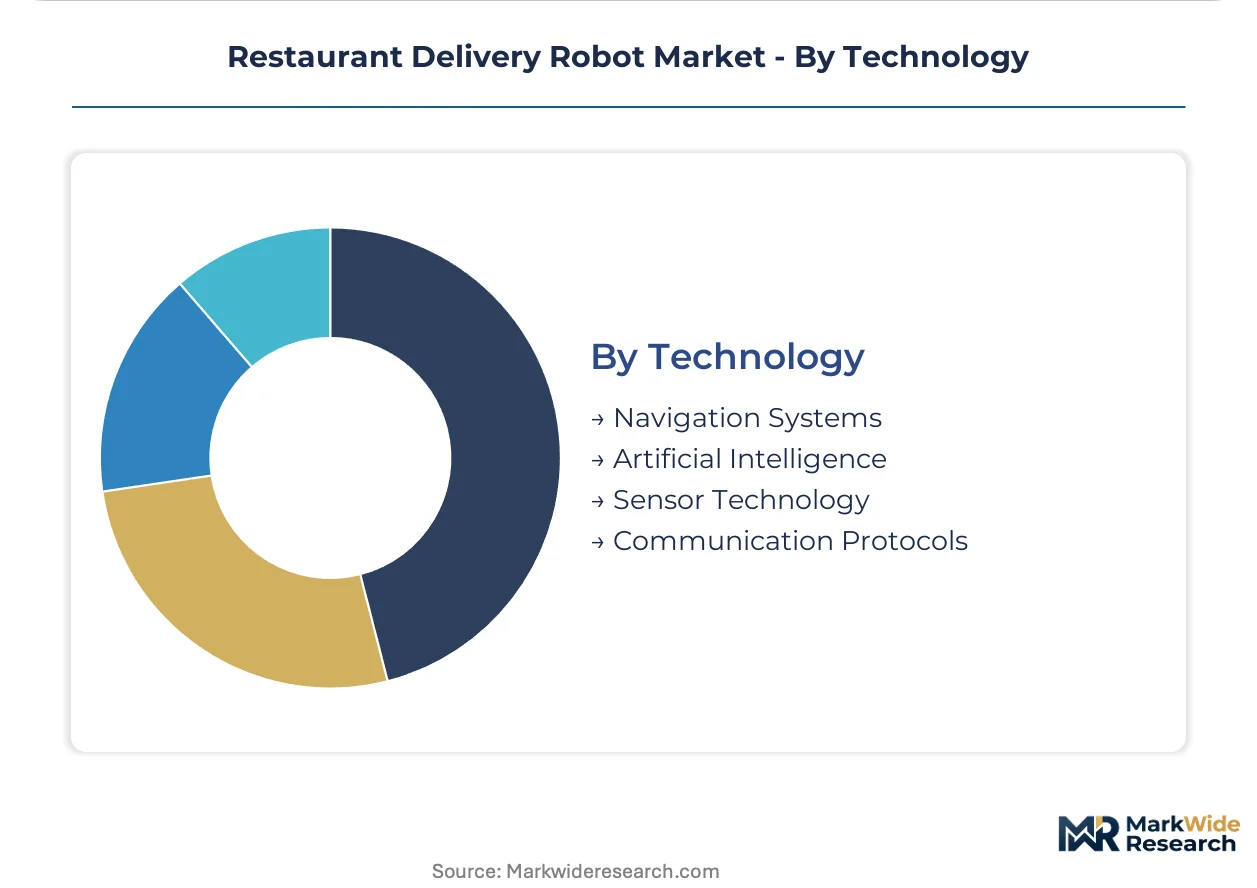
Technology:
Hardware commoditization shifts vendor differentiation toward software-defined fleet orchestration and predictive maintenance layers.
- Navigation Systems:Lidar-odometry fusion with MEMS beam steering replaces mechanical spinning sensors, collapsing perception stack costs below thresholds for mid-size operator adoption.
- Artificial Intelligence:Machine-vision inference engines enable real-time path replanning in cluttered environments without pre-mapped infrastructure.
- Sensor Technology:Ultrasonic arrays and depth cameras provide redundant proximity detection for food-safety-compliant surface sanitization protocols.
- Communication Protocols:API middleware bridges kitchen display systems with robot dispatch triggers, though legacy POS integration timelines stretch deployment schedules.
Navigation systems hold installed base dominance; artificial intelligence layers are expanding most quickly as vendors compete on fleet optimization software.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR certification and METI building code revisions are redirecting deployment capital toward jurisdictions with harmonized safety protocols and embedded infrastructure mandates.
China
Franchise networks in Shanghai and Beijing are accelerating kitchen-to-table robot deployment as tier-one city minimum wages compress five-year payback windows. SAMR enforces unified GB standards for electrical safety and electromagnetic compatibility, eliminating site-by-site compliance friction. Shenzhen-based Pudu Robotics anchors regional production scale across Asia-Pacific assembly plants.
Japan
Commercial real estate developers in Tokyo and Osaka are pre-installing inductive charging pads and fleet docking bays in new construction. METI revised building codes mandate minimum corridor widths and elevator call-button heights compatible with autonomous passage. Nagoya industrial clusters supply MEMS beam steering components for solid-state lidar arrays.
United States
Full-service chains negotiate throughput-guarantee terms with vendors as franchise procurement shifts toward bundled fleet contracts. FDA coordination with state health departments on food-contact surface protocols creates compliance multiplicity across jurisdictions. Pittsburgh and San Francisco municipal ordinances impose divergent insurance, speed-limit, and weight restrictions on sidewalk deployment.
South Korea
Seoul Capital Area café formats with standardized cup dimensions are compressing unit costs through simpler gripping mechanisms and faster cycle times. The country's national technology regulator promotes service robot adoption through R&D tax incentives for machine-vision navigation systems. Busan-Ulsan manufacturing corridors produce ultrasonic array components for proximity detection stacks.
Germany
Industrial machinery suppliers in Bavaria and Baden-Württemberg are integrating lidar-odometry fusion systems for European restaurant operators seeking retrofit deployment without pre-mapped infrastructure. CE marking requirements for service robot electrical safety align with emerging EU AI Act risk classification frameworks. Munich technical universities partner with vendors on predictive maintenance algorithm development.
Restaurant Delivery Robot Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: scale-driven Asian manufacturers with captive component supply, North American software specialists with vertical service bundles, and European engineering houses with precision navigation heritage. Strategic archetypes include fleet operators offering throughput-guarantee contracts, component-integrated platform vendors, and middleware providers bridging legacy POS systems. Dominant competitive moves encompass backward integration into lidar sensor production and geographic expansion through municipal regulatory pre-clearance.
Within the scale-driven manufacturing tier, Pudu Robotics and Keenon Robotics exemplify Asia-Pacific production concentration, while Bear Robotics occupies a position among North American vendors pursuing software-defined fleet management differentiation. Starship Technologies represents the regulatory-navigation archetype, having secured sidewalk right-of-way agreements across multiple US municipalities. These three anchors illustrate how vendor positioning stratifies between hardware commoditization and compliance-enabled geographic expansion.
| Leading Market Players |
|---|
| Bear Robotics |
| Pudu Robotics |
| Keenon Robotics |
| Starship Technologies |
| Miso Robotics |
| Serve Robotics |
| Boston Dynamics |
| Relay Robotics |
| Kitchen Robotics |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Asian solid-state lidar foundries compresses pricing tier spreads while amplifying procurement vulnerability during demand spikes. This concentration forces mid-size operators toward longer-term fleet contracts with embedded maintenance clauses, reshaping both cost structures and supplier relationships across the restaurant robotics value chain.
Pricing Analysis
Certification level creates the primary spread between SAMR-grade units for Chinese franchise networks and FDA-aligned platforms for US operators. Three-tier pricing structure across premium, standard, and economy levels reflects navigation stack sophistication, with lidar-vision fusion commanding premiums over ultrasonic-only configurations. Cost compression in entry-level tiers is intensifying because MEMS beam steering commoditization collapses perception stack costs below thresholds for smaller footprints. Fast-food chains with standardized kitchen-to-curbside workflows exhibit highest price sensitivity, while hotel operators prioritizing infection-control protocols demonstrate lowest sensitivity.
Supply Chain Analysis
Export-control restrictions on MEMS beam steering technology limit component flows from Chinese foundries to Western assemblers, fragmenting procurement strategies. Manufacturing gravity centers on China, Japan, and South Korea, with Shenzhen and Nagoya industrial clusters anchoring solid-state lidar production. The supply chain rests on rare-earth magnet dependencies for motor assemblies and semiconductor wafer supplies for sensor fabrication. Single-source vulnerability concentrates in ultrasonic array calibration components sourced from Busan-Ulsan corridors. Distribution runs through franchise procurement committees bundling fleet contracts with preventive maintenance and software upgrade clauses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Franchise procurement consolidation across North American and Asian full-service chains is shifting negotiating leverage toward buyers capable of throughput-guarantee contracting. This buyer-power concentration rewards vendors with remote diagnostics capabilities and predictive component replacement infrastructure.
For Market Incumbents: Build regulatory pre-clearance moats by securing municipal sidewalk right-of-way agreements ahead of competitor filings. Incumbents should deepen backward integration into lidar sensor production to insulate margins from Asian foundry pricing volatility, while expanding API middleware development to compress legacy POS integration timelines that currently stretch deployment schedules. The threat of emerging software-defined fleet management specialists demands accelerated R&D investment in predictive maintenance algorithms. For New Entrants and Emerging Players: German and Bavarian industrial machinery corridors offer underpenetrated retrofit deployment opportunities where CE marking requirements align with EU AI Act risk classification frameworks. New entrants should target European mid-size operators seeking lidar-odometry fusion systems without pre-mapped infrastructure investments, leveraging Munich technical university partnerships for algorithm credibility. A white-space go-to-market angle centers on beverage-first café formats with standardized cup dimensions that reduce payload engineering complexity. For Investors and Strategic Acquirers: Japan's METI building code revision reshapes the acquisition landscape by embedding robot passage infrastructure into new commercial construction permits. Long-term viability favors targets with vertical integration into navigation stacks and established regulatory pre-clearance across multiple municipalities. Acquisition archetypes include fleet operators capable of remote diagnostics and predictive component replacement. The signal to watch is municipal sidewalk-rights ruling density as an inflection indicator for scalable deployment economics.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Clearance Expansion | Municipal sidewalk right-of-way agreements in Pittsburgh and San Francisco reduce deployment friction for fleet operators. |
| Backward Integration into Lidar Production | In-house MEMS beam steering manufacturing insulates margins from Asian foundry concentration risk. |
| API Middleware Development | Kitchen display system integration compresses legacy POS deployment timelines for franchise networks. |
| Predictive Maintenance Algorithm Investment | Munich technical university partnerships enhance fleet optimization software differentiation. |
| Healthcare Campus Catering Pivot | Isolated tray delivery in hospital corridors bypasses sidewalk regulatory complexity while leveraging infection-control protocols. |
Research Methodology
Initial hypotheses were tested against primary input from robotics fleet operators, franchise procurement directors, municipal regulatory affairs officers, and foodservice technology integrators and refined through secondary validation. Primary fieldwork drew from kitchen display system vendors, ultrasonic array calibration technicians, and commercial real estate developers pre-installing inductive charging infrastructure. Secondary sources encompassed SAMR GB standard filings, METI building code revision documents, FDA state-level food-contact surface protocols, and SEC disclosures from publicly traded restaurant chains. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across the analysis window.
Demand-supply balance framing anchored the analytical framework, with deployment economics modeled across autonomy levels, service applications, venue formats, and regional regulatory clusters. Segmentation dimensions included product type, service type, customer type, and technology layer. CAGRs were derived from installed base growth trajectories and average selling price evolution across the projection horizon. Industry-specific forecast inputs incorporated lidar cost curve assumptions and municipal sidewalk-rights ruling density patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by software-defined fleet management specialists would shift outcomes beyond modeled ranges. Forecasts reflect assumptions regarding SAMR certification harmonization continuity and METI building code enforcement consistency. Material shifts in municipal insurance or weight restriction ordinances would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global IT Robotic Automation Market
Robotics and Automation
Mobile Stabilizer Market
Robotics and Automation
Non-Medical Biomimetic Robots Market
Robotics and Automation
Cordless Router Market
Robotics and Automation
UV-C Disinfection Robots Market
Robotics and Automation
South Korea Cloud Robotics Market
Robotics and Automation
Healthcare Robots Market
Robotics and Automation
Smart Remote Control Market
Robotics and Automation
Singapore Cloud Robotics Market
Robotics and Automation
Underwater Jetpack Market
Robotics and Automation
Industrial Robots Market
Robotics and Automation
North America Automated Liquid Handling Market
Robotics and Automation
Biaxial Mobile Phone Stabilizer Market
Robotics and Automation
Palletizing Robots Market
Robotics and Automation
Europe Articulated Robot Market
Robotics and Automation
Clean Room Robot Market