
 Green IT Services Market | 2026-2036
Green IT Services Market Size, Share, and Industry Trends Forecast 2026-2036
Green IT Services Market Outlook
Buyer concentration among hyperscale data center operators is realigning procurement priorities across the Green IT Services landscape. IBM Corporation leverages deep systems integration capabilities to anchor large-scale sustainability transformation programs. Accenture PLC competes through strategy-led advisory layers that bridge carbon accounting with enterprise architecture roadmaps. Microsoft Corporation extends cloud-native tooling to help clients measure and reduce scope emissions across distributed IT estates.
Green IT Services encompass the design, implementation, and management of information technology infrastructure optimized for energy efficiency, reduced carbon footprint, and sustainable resource utilization through techniques such as power usage effectiveness (PUE) targeting below 1.2, liquid cooling deployment, and renewable energy procurement integration. These services enable organizations to meet operational computing requirements while minimizing environmental impact and compliance exposure. Cloud Computing services command the largest revenue pool as enterprises migrate workloads to shared infrastructure with superior utilization rates, while Green Data Centers represent the fastest-expanding segment driven by facility-level efficiency retrofits and new builds targeting net-zero operations. Hybrid deployment models attract disproportionate investment as organizations balance latency-sensitive on-premises workloads with elastic public cloud capacity.
The EPA ENERGY STAR program and EU Ecodesign requirements shape equipment efficiency baselines for servers and storage sold across their respective jurisdictions, while the EU AI Act introduces emerging disclosure obligations for high-impact AI systems' energy consumption. ISO 14001 and ISO 50001 certifications increasingly gate vendor eligibility in enterprise RFP processes, particularly among European and North American buyers. Stakeholders must monitor evolving carbon border adjustment mechanisms and supply chain due diligence rules that will cascade accountability requirements through IT service provider networks.
Market Dynamics
Hyperscale data center operators are consolidating procurement power and mandating carbon transparency across their supplier tiers, forcing IT service providers to restructure delivery models around measurable emissions reduction.
Growth Catalysts
- EU CSRD disclosure mandates:Large enterprises must report scope 3 emissions from IT procurement, creating audit-ready demand for carbon accounting services and green infrastructure retrofits.
- Liquid cooling deployment:High-performance computing clusters in Germany and the United States are adopting direct-to-chip cooling to sustain power densities above 50kW per rack while containing facility energy use.
- India's national efficiency codes:The Bureau of Energy Efficiency has tightened data center performance standards, accelerating domestic demand for PUE optimization consulting and renewable energy integration.
Market Restraints
- Copper and rare earth price volatility:Transformer windings and permanent magnets for efficient motors face input cost swings that compress margins on fixed-price infrastructure contracts.
- Supply concentration in Chinese battery manufacturing:Stationary storage systems for data center backup power rely heavily on cell production concentrated in East Asia, exposing buyers to geopolitical supply interruptions.
- Legacy DC power architecture lock-in:Existing facilities built on 480V AC distribution cannot easily migrate to 380V DC topologies that eliminate conversion losses, slowing efficiency gains in brownfield sites.
Strategic Opportunities
- Edge computing nodes in Tier-2 Indian cities:Latency-sensitive applications are driving distributed infrastructure investment where greenfield construction can embed net-zero design from foundation to rooftop solar.
- EU AI Act energy disclosure rules:High-impact AI systems must document training and inference power consumption, opening advisory services that bridge compliance documentation with infrastructure right-sizing.
- Convergence of digital twin simulation with sustainability software:Real-time facility modeling combined with carbon accounting platforms enables predictive optimization that static audits cannot match.
Industry Challenges
- Shortage of certified energy auditors:ISO 50001 lead assessor credentials are scarce relative to enterprise demand, elongating project initiation timelines and inflating day-rate costs for qualified personnel.
- Multi-vendor integration complexity:Facilities blending on-premises workloads with multi-cloud orchestration face fragmented emissions visibility across incompatible monitoring tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green IT Services Market |
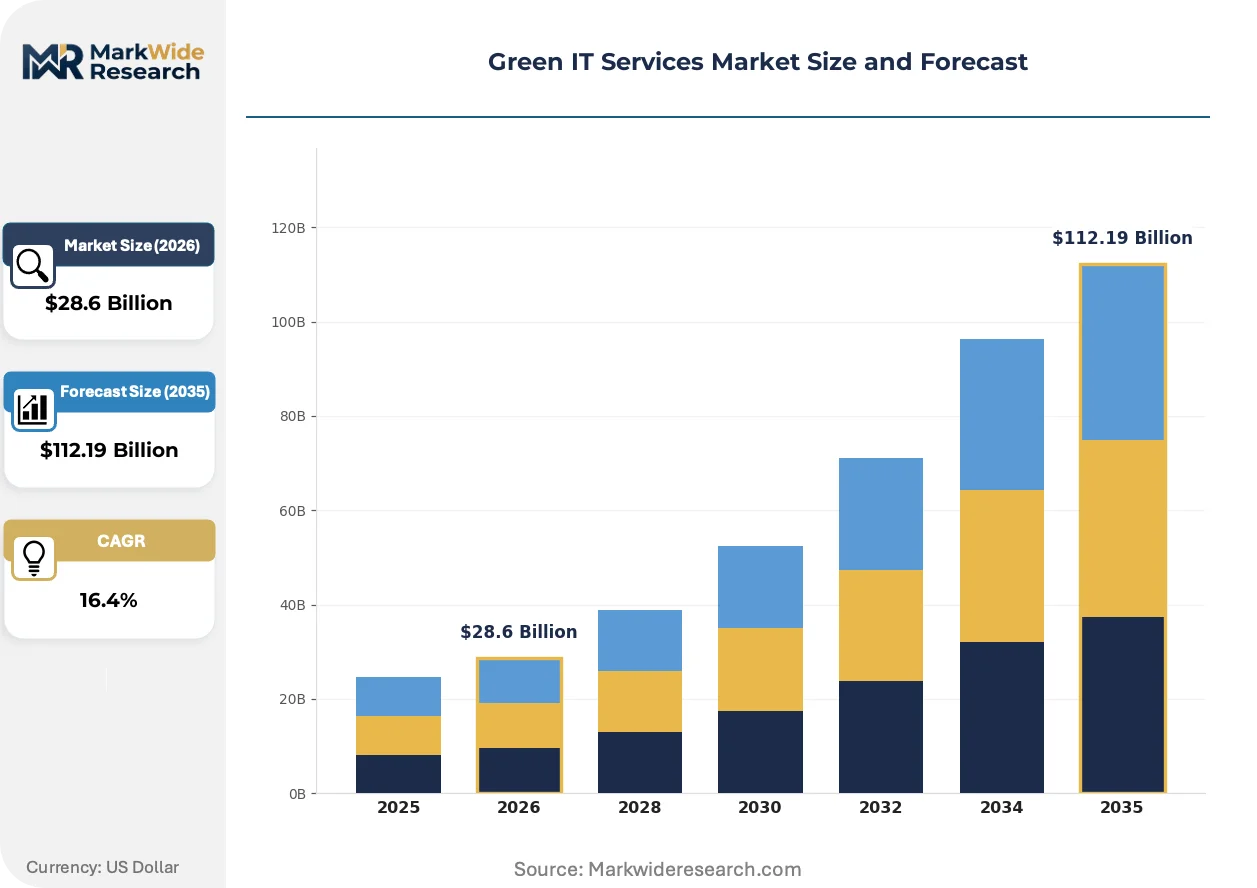
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Computing, Energy Management, Virtualization, Green Data Centers End User: Government, Healthcare, Education, Manufacturing Deployment Type: On-Premises, Hybrid, Public Cloud, Private Cloud Technology: AI, IoT, Blockchain, Renewable Energy Solutions |
| Companies Covered | IBM Corporation, Accenture PLC, Microsoft Corporation, Schneider Electric SE, Hewlett Packard Enterprise, Dell Technologies, SAP SE, Cisco Systems, Inc., Google LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green IT Services Market Strategic Shifts
Software-defined power management and AI-driven workload orchestration are compressing the gap between theoretical infrastructure efficiency and operational reality. These tools are redistributing competitive advantage toward providers with granular telemetry capabilities.
Immersion cooling systems using engineered dielectric fluids are absorbing heat loads that air-cooled infrastructure cannot physically manage. Hyperscale operators in Singapore and the Netherlands are piloting two-phase immersion for AI training clusters. This thermal approach is absorbing capital allocation that would otherwise flow to conventional chiller plant expansion.
The EU AI Act introduces mandatory documentation of energy consumption for high-impact foundation models deployed within the bloc. Cloud providers must now instrument their GPU clusters for granular power telemetry. German automotive and pharmaceutical buyers are prioritizing providers with pre-built compliance reporting modules.
Enterprise buyers are unbundling sustainability advisory from infrastructure implementation contracts. Procurement teams in the United States are engaging specialized carbon accounting firms for scope 3 baselining before selecting hardware vendors. This separation of advisory and execution is most pronounced among Fortune 500 manufacturers with complex global supplier networks.
Green IT Services Market Segmentation
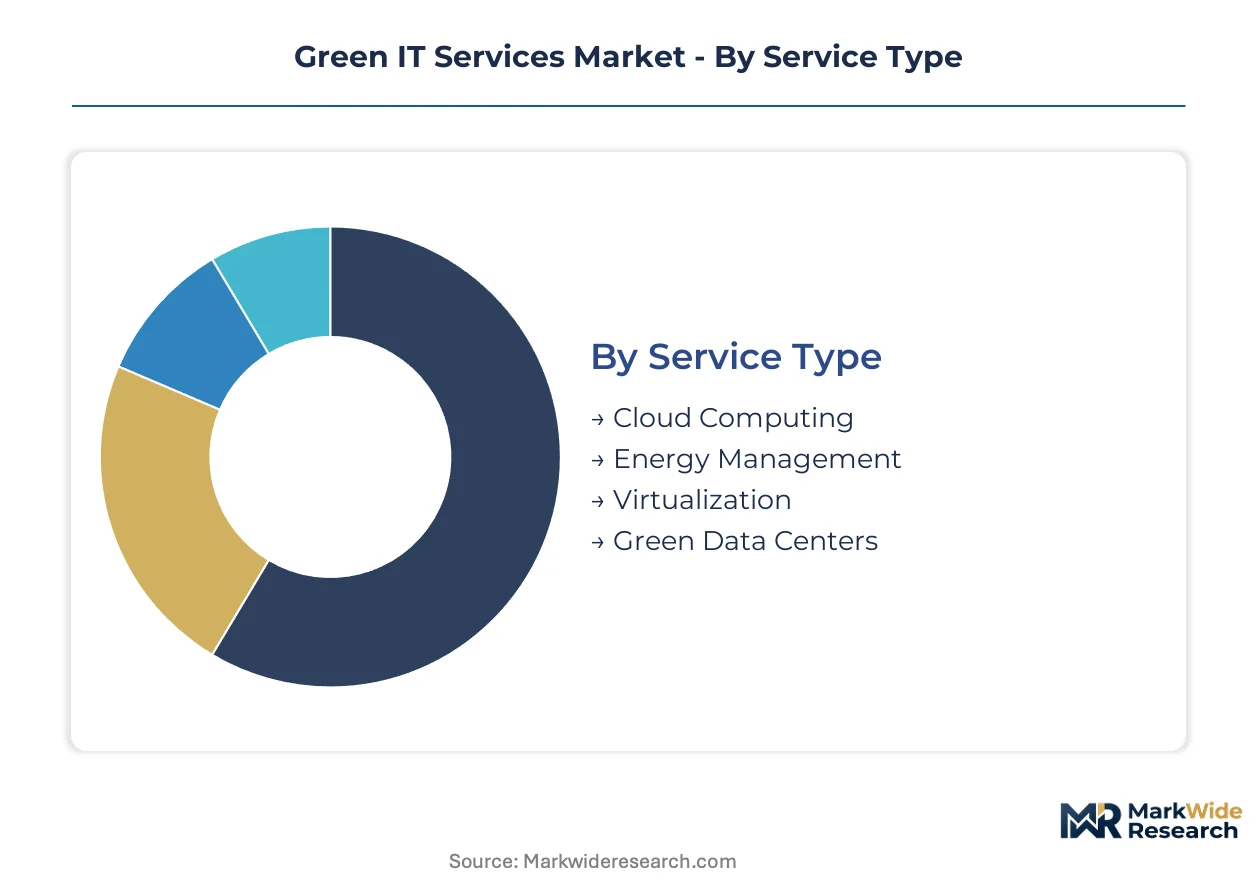
Procurement teams in this market segment their spending around workload placement decisions, carbon accounting obligations, and infrastructure lifecycle stages. Understanding these dimensions reveals where efficiency investments concentrate versus where compliance-driven retrofit demand emerges.
Service Type:
Buyers prioritize services based on whether their primary pain point is operational cost reduction, regulatory disclosure readiness, or infrastructure modernization.
- Cloud Computing:Shared infrastructure delivers superior server utilization rates compared to dedicated on-premises deployments. Enterprise migrations to hyperscale facilities in Germany and the United States concentrate procurement spend where PUE ratios already sit below industry averages.
- Green Data Centers:Facility-level retrofits and new construction targeting net-zero operations absorb capital allocation from operators facing EU CSRD disclosure deadlines. Liquid cooling adoption in high-performance computing clusters accelerates as rack densities exceed air-cooling physical limits.
- Energy Management:Continuous monitoring and optimization of IT power consumption through software-defined controls.
- Virtualization:Server consolidation and workload abstraction to improve hardware utilization rates.
Volume sits with Cloud Computing; growth tilts toward Green Data Centers.
End User:
Carbon reporting maturity and capital availability separate high-investment buyers from compliance-minimum adopters.
- Manufacturing:Complex global supply chains and scope 3 disclosure obligations drive integrated sustainability transformations. Automotive and pharmaceutical producers in Germany demand pre-built compliance reporting modules from IT service providers.
- Government:Public sector procurement codes increasingly mandate energy efficiency certifications. India's Bureau of Energy Efficiency standards accelerate domestic demand for PUE optimization consulting across federal and state data center portfolios.
- Healthcare:Patient data sovereignty requirements constrain cloud migration, preserving on-premises infrastructure investment.
- Education:Budget-constrained institutions prioritize virtualization over greenfield construction.
Manufacturing commands procurement volume; government contracts are climbing the fastest on regulatory mandate timelines.
Deployment Type:
Latency requirements and data residency rules fragment infrastructure placement across multiple environments.
- Hybrid:Balances latency-sensitive on-premises workloads with elastic public cloud capacity. Fortune 500 manufacturers with distributed supplier networks disproportionately invest here to maintain operational continuity.
- On-Premises:Legacy facilities built on 480V AC distribution face conversion loss penalties that 380V DC topologies would eliminate.
- Public Cloud:Shared infrastructure with renewable energy procurement integration.
- Private Cloud:Dedicated resources for regulated workloads requiring isolation.
Hybrid deployment attracts the steepest investment trajectory; on-premises maintains installed base volume.
Technology:
Instrumentation capabilities and telemetry granularity determine competitive positioning in sustainability reporting.
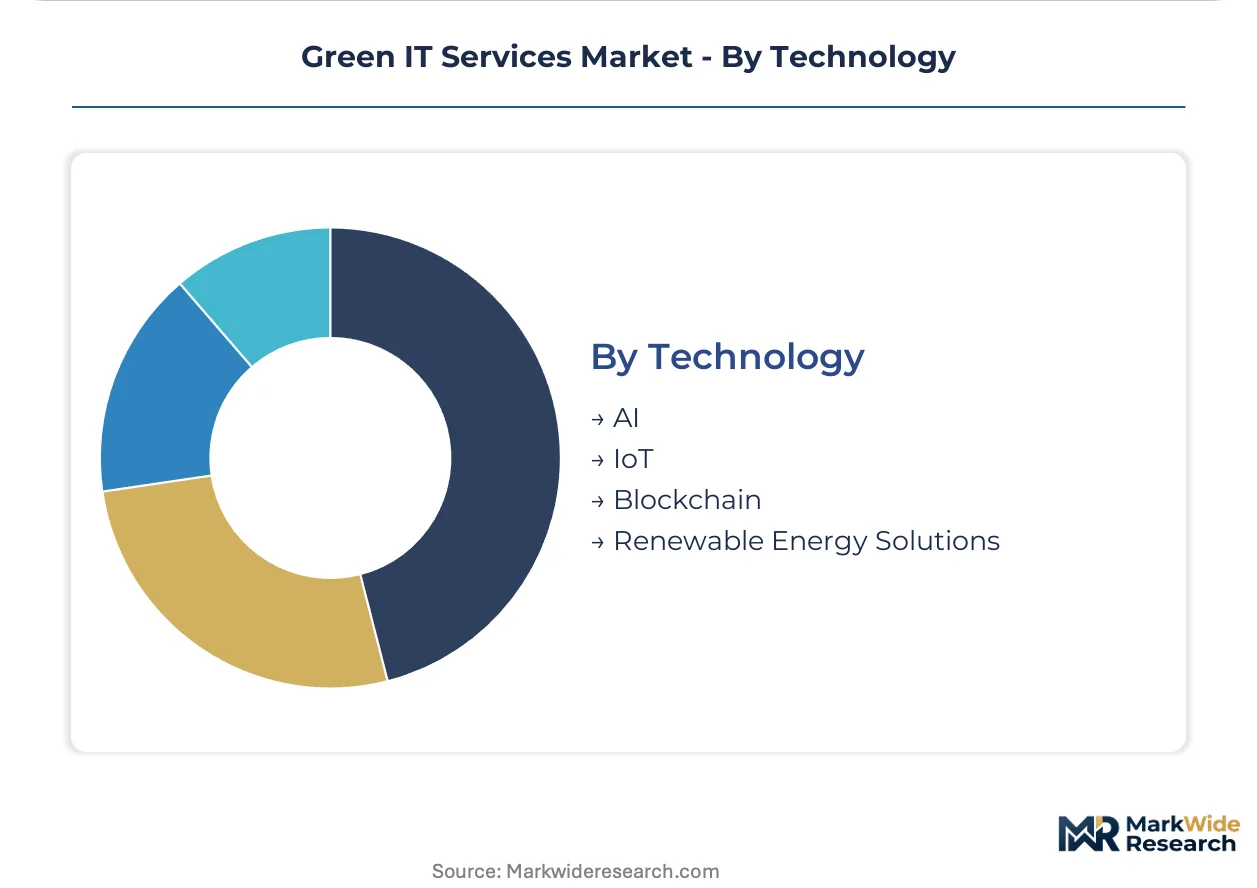
- AI:Workload orchestration and predictive optimization compress gaps between theoretical and operational efficiency. EU AI Act energy disclosure mandates for high-impact foundation models force GPU cluster instrumentation upgrades.
- IoT:Granular sensor networks enable real-time facility modeling combined with carbon accounting platforms.
- Blockchain:Distributed ledger applications for supply chain emissions verification.
- Renewable Energy Solutions:On-site solar and storage integration for data center power procurement.
AI absorbs R&D concentration; IoT deployment scales fastest through retrofit sensor installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium extraction in Chile's Atacama salt flats and cobalt mining in the Democratic Republic of Congo anchor the upstream material flows powering data center energy storage procurement decisions across major markets.
United States
Hyperscale operators in Northern Virginia and Dallas-Fort Worth are mandating renewable energy matching for new capacity additions. The EPA ENERGY STAR program certifies server efficiency baselines that federal procurement codes enforce. Liquid cooling pilots in Phoenix and Hillsboro sustain rack densities exceeding 50kW for AI training clusters.
Germany
Automotive and pharmaceutical manufacturers in Stuttgart and Munich demand pre-built CSRD compliance modules from IT service providers. The EU AI Act forces GPU cluster instrumentation for energy disclosure of high-impact foundation models. Frankfurt's banking sector concentrates procurement of hybrid cloud infrastructure with embedded carbon accounting.
India
Domestic cloud operators in Mumbai and Hyderabad are expanding renewable energy procurement to meet Bureau of Energy Efficiency data center performance standards. The country's national efficiency codes now mandate PUE reporting for facilities above 5MW capacity. Bangalore's software corridor drives edge computing investment in Tier-2 cities with greenfield net-zero construction.
Singapore
Tropical heat constraints have accelerated two-phase immersion cooling pilots for AI training infrastructure. The city-state's carbon tax regime and data center moratorium force efficiency-first design in limited new builds. Jurong and Tuas industrial zones concentrate deployment of direct-to-chip cooling for financial services workloads.
Netherlands
Amsterdam's data center cluster faces F-Gas Regulation limits on conventional chiller expansion, redirecting capital toward immersion cooling and free-air cooling designs. The EU Green Deal's carbon border adjustment mechanisms pressure scope 3 disclosure from IT procurement teams. Eindhoven's high-tech manufacturing ecosystem sources specialized dielectric fluids for thermal management systems.
Green IT Services Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue carbon accounting specialization and edge infrastructure niches. The market structures around three tiers: global systems integrators anchoring enterprise transformation programs, cloud-native platforms delivering emissions measurement tooling, and hardware specialists optimizing facility-level efficiency. Consolidation pressures concentrate among mid-tier consultancies lacking ISO 50001 certification depth. Competitive moves center on strategic partnerships binding software telemetry with hardware retrofits, plus geographic expansion into Indian and Southeast Asian markets where efficiency codes are tightening.
Within the global systems integration tier, IBM Corporation and Accenture PLC exemplify providers bridging carbon accounting with enterprise architecture roadmaps. Microsoft Corporation occupies a position anchoring cloud-native emissions measurement across distributed IT estates. These three represent distinct archetypes: hardware-software convergence, strategy-led advisory layers, and hyperscale platform delivery.
| Leading Market Players |
|---|
| IBM Corporation |
| Accenture PLC |
| Microsoft Corporation |
| Schneider Electric SE |
| Hewlett Packard Enterprise |
| Dell Technologies |
| SAP SE |
| Cisco Systems, Inc. |
| Google LLC |
| Others |
Value Chain & Pricing Dynamics
EU CSRD disclosure mandates for scope 3 emissions reporting are forcing enterprise buyers to unbundle sustainability advisory from infrastructure implementation, compelling suppliers to restructure service packaging and compressing margins on fixed-price efficiency retrofit contracts.
Pricing Analysis
Warranty and post-deployment optimization services increasingly separate premium providers from commodity competitors in enterprise RFP processes. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 50001 certification depth and real-time telemetry granularity. Cost compression in standard-tier consulting is intensifying because certified energy auditor scarcity elongates project timelines. Small and mid-sized enterprises exhibit highest price sensitivity, while hyperscale data center operators prioritize measurable emissions reduction over unit cost.
Supply Chain Analysis
Reverse-logistics networks for server refurbishment and component remanufacturing are expanding as circular economy mandates tighten across European procurement codes. Manufacturing concentration in China, Taiwan, and South Korea dominates liquid cooling hardware and high-efficiency power supply production. Supply chains draw from copper transformer windings, rare earth permanent magnets, and lithium-ion battery cells. Single-source vulnerability in Chinese battery manufacturing exposes buyers to geopolitical disruption. Distribution runs through systems integrators and direct hyperscale procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid cooling infrastructure is displacing conventional air-cooled architectures in high-performance computing clusters, creating asymmetric opportunity for providers with thermal management expertise.
For Market Incumbents: Acquire specialized carbon accounting software assets to counter unbundling trends separating advisory from implementation. IBM Corporation and Accenture PLC should deepen ISO 50001 certification pipelines to defend against emerging consultancies lacking auditor depth. Hyperscale procurement consolidation threatens mid-tier providers without telemetry-integrated delivery models. For New Entrants and Emerging Players: Cloud-native carbon measurement platforms offer lowest barrier-to-entry penetration in manufacturing verticals facing CSRD deadlines. Target Tier-2 Indian cities for edge computing infrastructure where greenfield construction enables net-zero design from foundation. Partner with renewable energy developers to bundle solar procurement with data center buildout. For Investors and Strategic Acquirers: Re-rating potential sits with carbon accounting specialists given EU AI Act energy disclosure mandates forcing GPU cluster instrumentation upgrades. Five-to-ten year viability favors providers bridging compliance documentation with predictive optimization software. Watch for Bureau of Energy Efficiency enforcement acceleration in India as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Carbon Accounting Specialist | CSRD disclosure mandates create audit-ready demand for integrated reporting capabilities. |
| Liquid Cooling Technology Licensing | Direct-to-chip thermal management sustains rack densities exceeding air-cooling physical limits. |
| ISO 50001 Certification Pipeline Expansion | Scarcity of lead assessors gates vendor eligibility in enterprise procurement processes. |
| Edge Infrastructure Joint Venture in India | Bureau of Energy Efficiency standards accelerate domestic demand for PUE optimization consulting. |
| GPU Cluster Telemetry Platform Integration | EU AI Act forces cloud providers to instrument high-impact foundation models for energy disclosure. |
Study Parameters
Multi-period observation of hyperscale procurement patterns, efficiency code enforcement timelines, and renewable energy integration rates anchored the trend analysis, supplemented by interviews with data center operations directors, sustainability officers at manufacturing enterprises, IT procurement managers, and energy auditor certification bodies. Secondary validation drew from EPA ENERGY STAR filings, EU Ecodesign regulatory databases, Bureau of Energy Efficiency compliance reports, and hyperscaler capital expenditure disclosures. Bottom-up service provider revenue aggregation triangulated against top-down enterprise IT spending surveys.
Input-output matrices modeled deployment type, service category, end-user vertical, and technology layer interactions across the projection horizon. Segmentation dimensions included workload placement architecture, carbon accounting maturity tier, infrastructure lifecycle stage, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to disclosed capacity expansion plans and mandated efficiency improvement trajectories. Forecast inputs incorporated liquid cooling adoption rates and scope 3 disclosure penetration curves.
The model holds under sustained regulatory enforcement of CSRD and EU AI Act timelines; deviation in geopolitical trade restrictions or rare earth supply interruptions would shift infrastructure cost assumptions. Forecasts reflect documented base conditions without contingency for abrupt policy reversal. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
New Zealand ICT Market
Digital Solutions
Saudi Arabia ICT Market
Digital Solutions
Warehouse Digital Twin Simulation and Optimization Market
Digital Solutions
Asia-Pacific API Management Market
Digital Solutions
Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) Market
Digital Solutions
Lead Generation Solutions Market
Digital Solutions
Electronic Document Management System (EDMS) Market
Digital Solutions
India PLM Market
Digital Solutions
Global Inventory Optimization Software Market
Digital Solutions
Express Digitizer Market
Digital Solutions
Assortment and Space Optimization (ASO) Market
Digital Solutions
Germany Smart Office Market
Digital Solutions
HIPAA-Compliant Messaging Services Market
Digital Solutions
Disaster Recovery As a Service (Draas) Market
Digital Solutions
North America Digital Pen Market
Digital Solutions
Global Software Defined Everything (SDE) Market