
 Global Digital Experience Platform Market | 2026-2036
Global Digital Experience Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Experience Platform Market Foresight
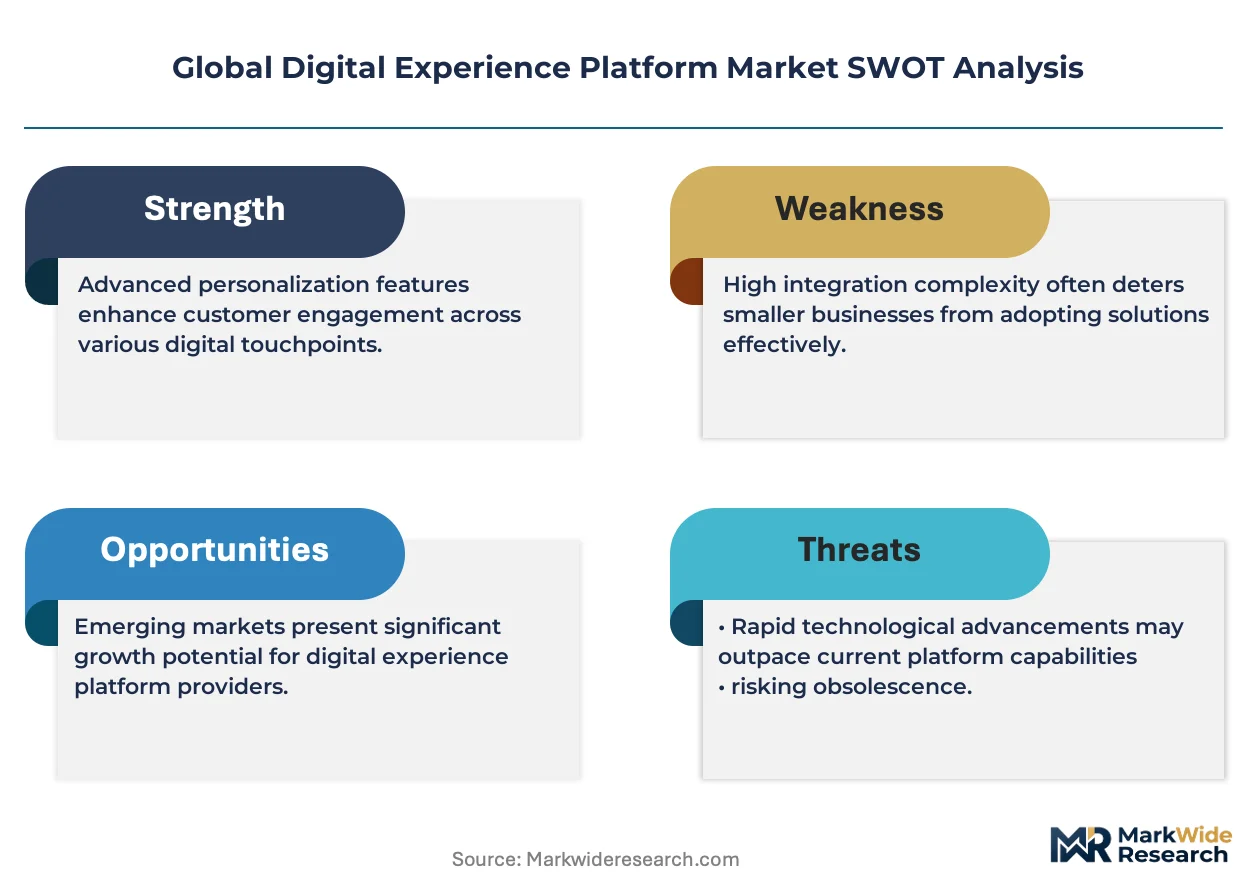
Multi-source vendor strategies is realigning how enterprises procure digital experience capabilities, shifting away from monolithic suites toward composable architectures. Adobe leverages its creative cloud ecosystem to anchor integrated marketing workflows across large enterprises. Sitecore competes through deep personalization engines that sustain premium positioning in financial services deployments. Contentful specializes in API-first content infrastructure, occupying a distinct layer in modern technology stacks.
A digital experience platform integrates content management, customer data orchestration, and real-time analytics through cloud-native or hybrid architectures to deliver personalized interactions across web, mobile, and emerging touchpoints. The solution type dimension reveals content management as the mature revenue base while personalization engines capture expanding margin pools from AI-driven segmentation demand. Deployment patterns show cloud-based delivery dominating new implementations, though hybrid configurations retain traction among banking institutions with stringent data residency requirements.
The EU AI Act, GDPR, and California Consumer Privacy Act collectively impose algorithmic transparency and consent management obligations that elevate compliance costs for platform vendors. India's Digital Personal Data Protection Act and China's GB standards for cross-border data flows add further jurisdictional complexity to product roadmaps. Stakeholders must monitor regulatory divergence between data localization mandates and interoperability standards when evaluating vendor geographic coverage.
Market Dynamics
Composable architecture adoption is fragmenting procurement patterns across enterprise technology stacks, as organizations dismantle monolithic suites in favor of API-orchestrated best-of-breed components that demand new integration competencies from vendor ecosystems.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements are forcing platform refreshes across European banking and insurance deployments, creating replacement cycles for legacy personalization engines.
- Headless CMS migration:Retail chains are decoupling content repositories from presentation layers to enable simultaneous deployment across mobile apps, kiosks, and in-store displays.
- India:The Digital Personal Data Protection Act is accelerating consent-management infrastructure investments among domestic e-commerce platforms and fintech operators.
Market Restraints
- Cloud concentration risk:Hyperscaler dependency in Western Europe and North America creates single-point-of-failure exposure during regional outages or jurisdictional data access disputes.
- Specialized talent scarcity:Shortages of MLOps engineers and customer data platform architects are extending implementation timelines and inflating professional services costs.
- GDPR-EU AI Act overlap:Conflicting documentation requirements between automated decision-making transparency and data minimization principles are forcing redundant compliance architectures.
Strategic Opportunities
- Germany:Mittelstand manufacturers remain underpenetrated for B2B commerce orchestration, presenting whitespace for industrial distributor portal deployments.
- Real-time CDP convergence:Streaming data infrastructure is merging with identity resolution to enable sub-second personalization in sports betting and live event ticketing verticals.
- California Consumer Privacy Act expansion:CPRA enforcement is mandating granular consent preference centers that vendors can productize as compliance accelerators for mid-market clients.
Industry Challenges
- Integration debt accumulation:Point-to-point connections between composable components are creating maintenance nightmares as enterprise stacks scale beyond twenty vendor relationships.
- ISO 27001 certification timelines:Extended audit cycles for cloud-native platforms are delaying enterprise sales cycles in financial services and healthcare verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Experience Platform Market |
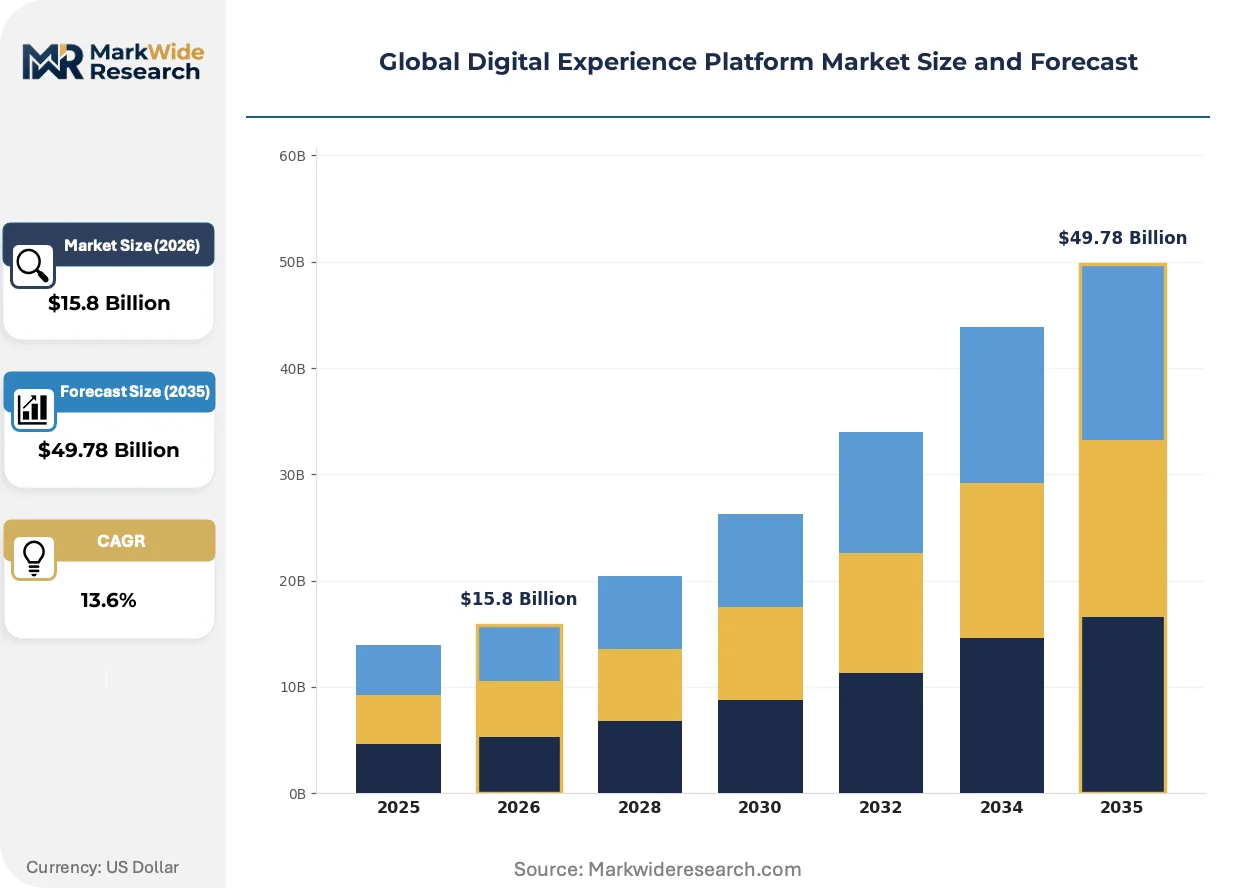
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $49.78 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services Solution Type: Content Management, Customer Data Management, Analytics & Insights, Personalization Engines, Omnichannel Orchestration Application: E-Commerce, Financial Services, Telecommunications, Media & Entertainment, Education Platforms End User Industry: Retail Chains, Banking Institutions, Service Providers, Digital Publishers, Academic Organizations |
| Companies Covered | Sitecore, Magnolia, Optimizely, Bloomreach, Contentful, Adobe, Progress, Qualtrics, Acquia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Experience Platform Market Shifts & Advancements
Real-time data streaming infrastructure is compressing the latency window between behavioral signal capture and content delivery, collapsing traditional batch-processing architectures in favor of event-driven personalization engines.
Edge computing nodes are integrating content delivery networks with serverless compute to execute personalization logic within 50 milliseconds of end-user interaction. Telecommunications operators and streaming media services are deploying these architectures most aggressively across Southeast Asian markets. The technology is integrating decisioning capabilities directly into CDN infrastructure, eliminating round-trip latency to centralized cloud regions.
The EU AI Act's risk classification framework is mandating human-in-the-loop review mechanisms for high-risk automated decisioning systems. Platform vendors must now embed audit trails and explanation interfaces that satisfy both GDPR data subject access requests and AI Act conformity assessments. Financial services deployments across France and Germany are absorbing the highest compliance engineering costs as they retrofit credit scoring and insurance pricing workflows.
Enterprise sourcing committees are consolidating vendor relationships around platforms that bundle consent management, identity resolution, and journey orchestration under unified data governance. Mid-market retailers in the United States are abandoning point solutions in favor of suite alternatives that reduce integration overhead. Procurement patterns in India show similar consolidation pressure as digital-first brands scale beyond initial pilot implementations.
Global Digital Experience Platform Market Segmentation
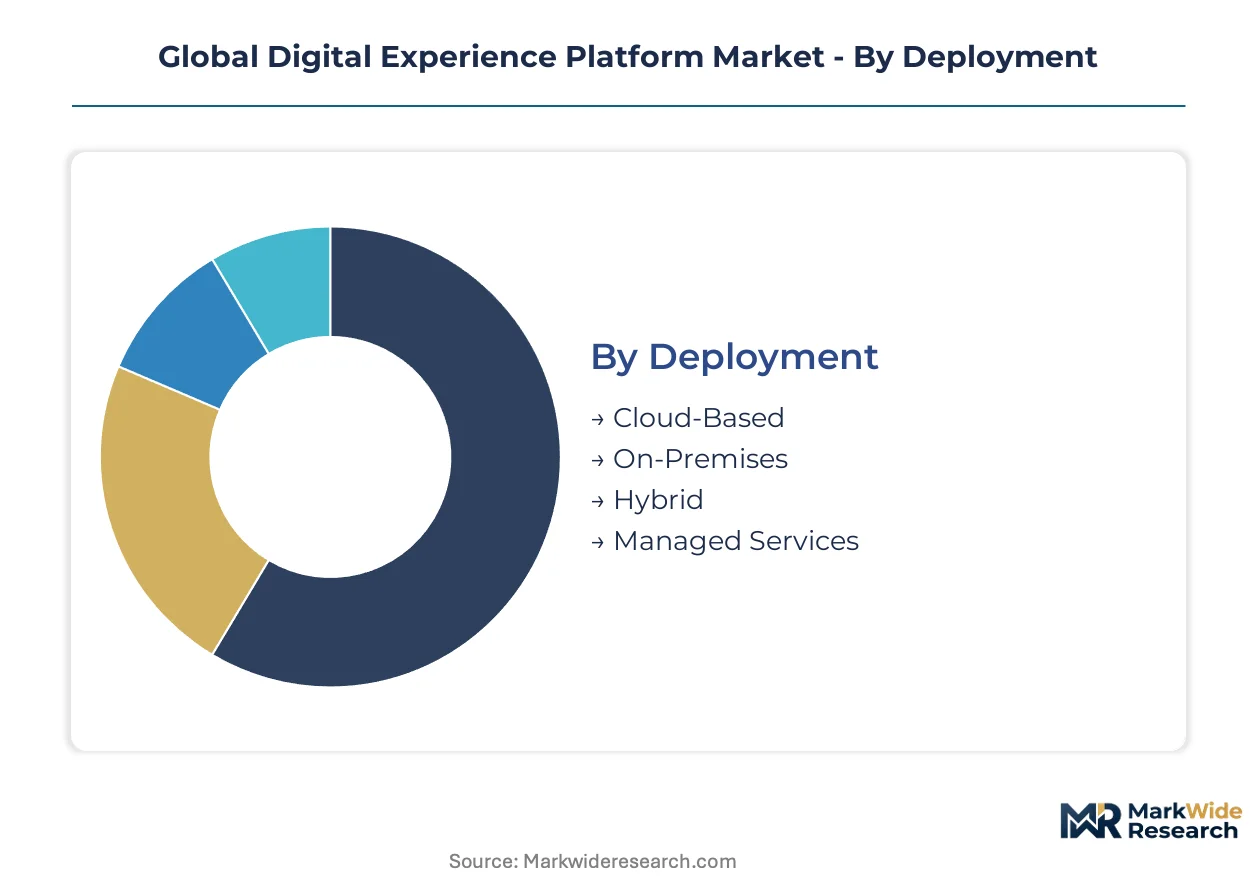
Digital experience platform procurement patterns fragment sharply across deployment architectures and solution layers, with vendor specialization forcing enterprises into multi-source strategies. Each segmentation dimension reveals distinct margin pools, compliance burdens, and integration complexity that reshape competitive positioning.
Deployment:
Cloud infrastructure concentration among hyperscalers in Ireland, Germany, and Virginia creates geographic lock-in risks that hybrid architectures attempt to mitigate.
- Cloud-Based:Multi-tenant SaaS delivery dominates new implementations, with hyperscaler regions in Frankfurt, Mumbai, and Singapore capturing workload gravity. GDPR data residency requirements and India's Digital Personal Data Protection Act are accelerating in-country cloud region expansion by AWS, Azure, and Google Cloud.
- Hybrid:Split architectures maintain sensitive customer data on-premises while pushing content delivery to edge nodes. German automotive manufacturers and French insurance conglomerates favor this model to satisfy BaFin and ACPR oversight while achieving sub-100-millisecond response times.
- On-Premises:Legacy installations persist in Swiss private banking and Saudi sovereign wealth operations where data localization mandates override cloud economics.
- Managed Services:Third-party operations of dedicated instances appeal to mid-market retailers lacking internal SRE capabilities.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
Solution Type:
Margin capture varies dramatically by layer, with infrastructure components commoditizing while intelligence engines sustain pricing power.
- Personalization Engines:Real-time decisioning systems ingest behavioral signals across touchpoints to trigger individualized content delivery. EU AI Act compliance costs are reshaping vendor R&D priorities, with French and German deployments requiring embedded explanation interfaces for credit and insurance use cases.
- Content Management:Headless architectures decouple repositories from presentation layers, enabling simultaneous deployment across mobile apps, kiosks, and in-store displays. Retail chains in India and the United States are migrating fastest to support omnichannel orchestration.
- Customer Data Management:Identity resolution and consent orchestration layers face regulatory fragmentation between GDPR, CCPA, and India's DPDP Act.
- Analytics & Insights:Batch and streaming analytics modules compete against standalone BI vendors for dashboard and attribution use cases.
- Omnichannel Orchestration:Journey mapping and campaign execution tools integrate across email, SMS, push, and emerging messaging platforms.
Personalization Engines command premium pricing. Content Management faces margin compression from open-source alternatives.
Application:
Vertical-specific compliance requirements and latency tolerances segment demand into distinct procurement patterns.
- Financial Services:Real-time fraud detection and personalized product recommendations operate under strict regulatory oversight. BaFin, ACPR, and the SEC impose audit trail and model governance requirements that elevate platform certification costs.
- E-Commerce:Conversion optimization and cart abandonment recovery drive demand for sub-second personalization. Indian marketplaces and US direct-to-consumer brands represent the most aggressive adopters of edge-compute personalization nodes.
- Telecommunications:Subscriber lifecycle management and churn prediction leverage streaming data infrastructure.
- Media & Entertainment:Content recommendation engines compete for viewer attention across subscription and advertising-supported models.
- Education Platforms:Learning management system integration and student engagement analytics serve K-12 and higher education institutions.
Financial Services absorbs the highest compliance engineering investment. E-Commerce is expanding most quickly across emerging markets.
End User Industry:
Organizational scale and digital maturity determine whether enterprises pursue suite consolidation or best-of-breed assembly.
- Retail Chains:Omnichannel inventory visibility and unified customer profiles span physical and digital touchpoints. German Mittelstand manufacturers and Indian conglomerates are deploying B2B commerce portals to capture distributor relationships.
- Banking Institutions:Core system integration and regulatory reporting requirements favor vendors with established financial services certifications. ISO 27001 and SOC 2 Type II attestations are table stakes for enterprise sales cycles.
- Service Providers:Telecom operators and utilities white-label customer experience capabilities for enterprise clients.
- Digital Publishers:Ad-tech integration and subscription paywall optimization drive specialized requirements.
- Academic Organizations:Learning analytics and alumni engagement operate with constrained procurement budgets.
Retail Chains lead deployment velocity. Banking Institutions impose the steepest vendor qualification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley technology clusters anchor enterprise software procurement patterns, while Frankfurt and Bangalore financial districts drive divergent compliance architectures across three continents.
United States
Retail chains and direct-to-consumer brands dominate platform procurement, with Manhattan media conglomerates and Austin fintech operators deploying real-time personalization engines. The California Consumer Privacy Act and CPRA enforcement mandate granular consent preference centers that vendors productize for mid-market penetration. Chicago-based healthcare systems and Los Angeles entertainment studios represent contrasting deployment velocity benchmarks.
Germany
Mittelstand manufacturers remain underpenetrated for B2B commerce orchestration, creating whitespace for industrial distributor portal deployments across Baden-Württemberg and North Rhine-Westphalia. BaFin oversight and EU AI Act risk classifications impose embedded explanation interfaces for credit and insurance workflows. Munich automotive headquarters and Frankfurt banking towers sustain premium pricing for hybrid deployment architectures.
India
Domestic e-commerce platforms and fintech operators accelerate consent-management infrastructure investments under the Digital Personal Data Protection Act. Mumbai financial services and Bangalore SaaS clusters drive API-first content management adoption for omnichannel retail. Hyderabad pharmaceutical distributors and Delhi-NCR logistics operators represent emerging vertical demand pockets.
United Kingdom
London financial services and Manchester media agencies sustain demand for real-time customer data platforms with streaming identity resolution. Financial Conduct Authority conduct rules and Information Commissioner's Office GDPR guidance elevate audit trail requirements for automated decisioning systems. Edinburgh insurance technology clusters and Cambridge analytics startups fragment procurement between established suites and composable alternatives.
France
Parisian luxury houses and Lyon industrial software vendors deploy edge-compute personalization for sub-100-millisecond response times in high-consideration purchase journeys. ACPR oversight and CNIL algorithmic transparency mandates absorb the highest compliance engineering costs across European deployments. Toulouse aerospace supply chains and Bordeaux wine export platforms represent specialized B2B commerce requirements.
Global Digital Experience Platform Market Competitive Landscape
Global majors compete with regional champions across deployment architecture specialization, with market structure consolidating around three tiers based on creative ecosystem integration depth. Cloud-native specialists fragment the mid-market through API-first positioning, while legacy suite vendors defend installed base relationships through hybrid migration pathways. Strategic archetypes include creative cloud anchors, headless infrastructure pure-plays, and vertical-specific personalization engines. Dominant competitive moves center on M&A for consent-management capabilities and strategic partnerships for edge-compute infrastructure.
Within the creative ecosystem anchor tier, Adobe occupies a position exemplifying integrated marketing workflow dominance across large enterprises. Contentful and Sitecore represent contrasting archetypes: the former anchors API-first content infrastructure layers in modern technology stacks, while the latter exemplifies deep personalization engine specialization sustaining premium positioning in financial services deployments. These three companies illustrate the fundamental strategic divergence between suite consolidation and composable best-of-breed assembly that enterprises navigate.
| Leading Market Players |
|---|
| Sitecore |
| Magnolia |
| Optimizely |
| Bloomreach |
| Contentful |
| Adobe |
| Progress |
| Qualtrics |
| Acquia |
| Others |
Supply & Pricing Matrix
Large enterprise sourcing committees concentrated in United States financial services and German automotive verticals anchor contract value to bundled suite economics, compressing standalone component pricing while elevating premium tiers for AI-enabled personalization engines with embedded compliance architectures.
Pricing Analysis
Input-cost pass-through from hyperscaler infrastructure fees and specialized MLOps talent scarcity flows into SaaS subscription tiers, with three-tier pricing structure across premium, standard, and economy levels separating AI-native personalization engines from legacy content management modules. Price differentiation hinges on GDPR-EU AI Act certification grade and vertical-specific integration depth. Cost compression in mid-market standard tiers intensifies because open-source headless alternatives erode maintenance revenue. Banking institutions exhibit lowest price sensitivity; mid-market retailers in India and Southeast Asia absorb highest budget constraints.
Supply Chain Analysis
India's Digital Personal Data Protection Act and China's GB standards for cross-border data flows are reshaping vendor sourcing patterns, forcing in-country cloud region investments that fragment infrastructure deployment. Supply concentration rests on Ireland, Germany, and Virginia hyperscaler regions for primary compute workloads, with Singapore and Mumbai emerging as secondary nodes for latency-sensitive edge personalization. Dependencies on NVIDIA GPU clusters, streaming data infrastructure, and identity resolution APIs create single-source vulnerability during semiconductor allocation cycles. Distribution runs through direct enterprise sales with professional services attach, supplemented by systems integrator channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in this market rest on AI-enabled tier upgrades and compliance-automation bundling that captures budget reallocation from redundant point-solution consolidation.
For Market Incumbents: Deploy embedded explanation interfaces as the defensive lever against emerging API-first challengers. Fortify hybrid deployment architectures to satisfy BaFin and ACPR data residency mandates while absorbing credit-scoring workflow replacements. Consolidate consent-management acquisitions to preempt standalone GDPR-EU AI Act compliance vendors from fragmenting the customer data layer. For New Entrants and Emerging Players: The mid-market pricing gap between Adobe-Sitecore premium suites and open-source Contentful deployments offers white-space entry through vertical-specific personalization engines for Indian fintech and German Mittelstand B2B commerce. Target underpenetrated industrial distributor portals in Baden-Württemberg and North Rhine-Westphalia with API-first composable stacks. Pursue partnership-led go-to-market with Mumbai and Bangalore systems integrators to bypass direct sales buildout costs. For Investors and Strategic Acquirers: Hyperscaler cloud divisions are the most active acquirer in this space, seeking edge-compute personalization capabilities to embed within CDN infrastructure. Long-term viability centers on platforms bundling streaming identity resolution with journey orchestration under unified data governance. Acquisition target archetype: CDP specialists with real-time consent-management infrastructure. Monitor EU AI Act enforcement velocity in French insurance and German banking deployments as inflection indicator for compliance-engineering valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies consent management with identity resolution for GDPR-EU AI Act compliance. |
| Acquisition of Specialist Firm | Adds real-time CDP streaming capabilities to fill personalization latency gaps. |
| Strategic Partnership | Embeds decisioning logic into AWS CloudFront and Azure CDN edge nodes. |
| Product Launch | Introduces human-in-the-loop audit interfaces for high-risk automated decisioning. |
| Geographic Expansion | Establishes Mumbai and Frankfurt cloud regions for data residency mandates. |
Research Methodology
Multiple input streams — primary interviews with CTOs and IT procurement officers, secondary validation through hyperscaler capex disclosures and SEC filings, and technical architecture reviews — were reconciled through bottom-up and top-down triangulation. Conversations with platform engineers, integration specialists, and channel partners at systems integrators in New York, London, and Bangalore informed deployment pattern assessments. Secondary sources included vendor earnings transcripts, EU AI Act implementation guidance, and India's DPDP Act compliance frameworks.
Data-stream reconciliation across deployment model, organization size, vertical, and integration complexity dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro technology spending indicators. Forecast inputs incorporated cloud infrastructure expansion trajectories in Frankfurt, Mumbai, and Singapore regions, alongside regulatory compliance cost absorption curves for financial services deployments.
Caveats apply where EU AI Act enforcement divergence, hyperscaler regional outage events, or MLOps talent scarcity escalation could materially shift the outlook. Forecasts reflect assumptions about enterprise procurement consolidation velocity and open-source competitive pressure. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
India Digital Twin Market
Digital Solutions
Australia System Integration Market
Digital Solutions
Crew Management Systems Market
Digital Solutions
Sales Acceleration Technology Market
Digital Solutions
Global Asset Tracking Software Market
Digital Solutions
Global Enterprise Metadata Management Market
Digital Solutions
Online Home Service Market
Digital Solutions
Distributed Performance and Availability Management Software Market
Digital Solutions
Water Level and Storage Monitoring Software Market
Digital Solutions
Data Pipeline Market
Digital Solutions
Virtual Workspace Solutions Market
Digital Solutions
Load Balancer Market
Digital Solutions
Route Optimization Software Market
Digital Solutions
Procure-To-Pay Solutions Market
Digital Solutions
Global Cloud Supply Chain Management Market
Digital Solutions
Digital Library Software Market