
 Middle East and Africa Cloud Integration Market | 2026-2036
Middle East and Africa Cloud Integration Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Cloud Integration Market Foresight
Energy companies is broadening the addressable base for cloud integration vendors across the Middle East and Africa. Microsoft Corporation leverages its Azure Stack portfolio to anchor hybrid deployments in regulated industries requiring on-premise data residency. Oracle Corporation sustains competitive positioning through database-centric integration tools that dominate enterprise legacy modernization programs in South African financial institutions.
Cloud integration encompasses the architectural practice of connecting disparate computing environments, applications, and data sources through standardized protocols, API gateways, and middleware layers to enable seamless information flow and unified operational control. The technology employs message queuing, event-driven architectures, and extract-transform-load pipelines to synchronize transactional and analytical workloads across distributed infrastructure. Hybrid Cloud deployments command premium service margins due to complexity premiums in regulated verticals, while Multi-Cloud integration is expanding fastest as enterprises seek to avoid vendor lock-in across AWS, Azure, and regional providers. Integration Platform as a Service offerings concentrate margin pools through recurring subscription revenue models, whereas Consulting Services face pricing pressure from regional system integrators building captive implementation practices.
Saudi Arabia's National Data Management Office and the UAE's National Cybersecurity Council enforce data localization standards that directly shape enterprise cloud architecture decisions across both public and private sectors. South Africa's Protection of Personal Information Act and Egypt's emerging data protection framework impose cross-border transfer restrictions that elevate demand for in-country integration infrastructure. Stakeholders must monitor evolving sovereignty requirements as Gulf Cooperation Council members introduce divergent certification regimes for cloud service providers operating critical national infrastructure.
Market Dynamics
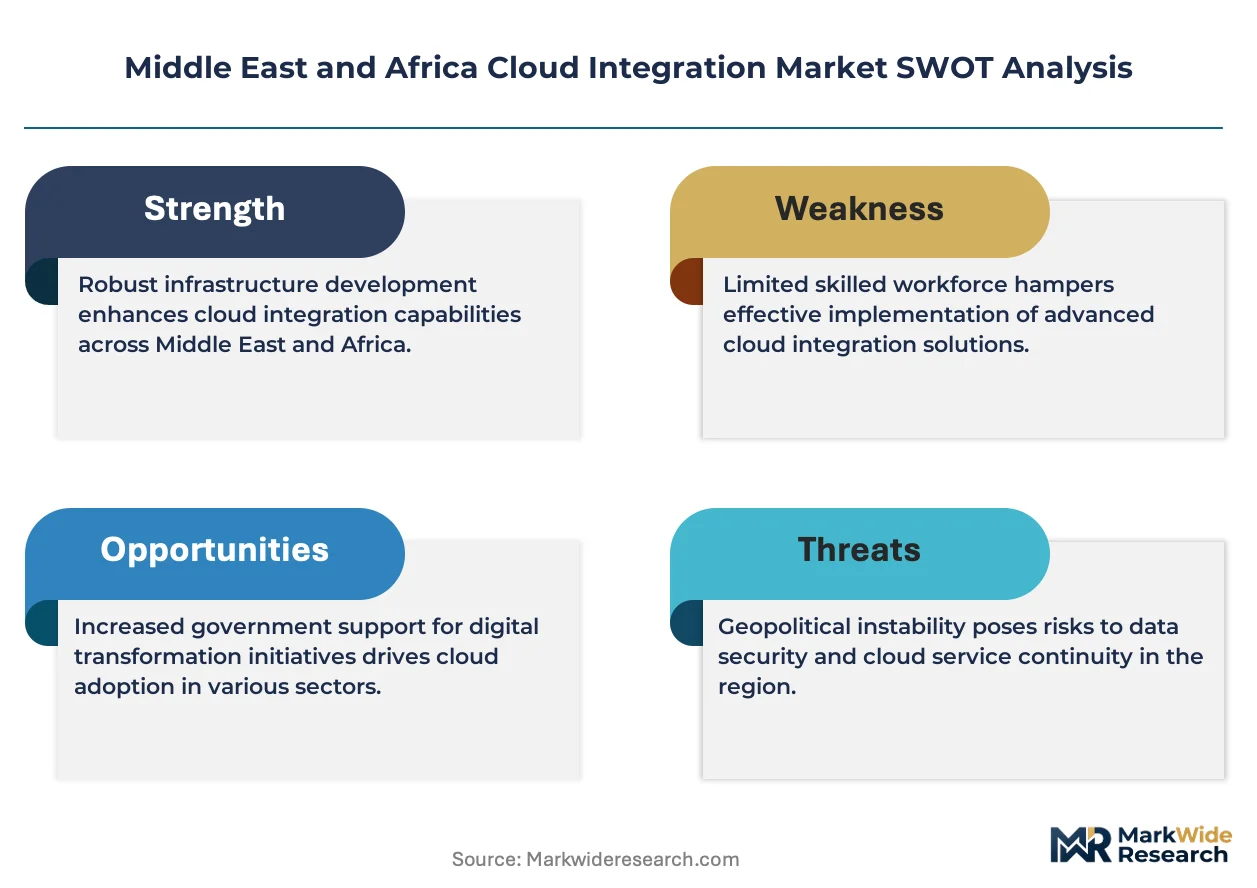
Data sovereignty mandates across Gulf Cooperation Council jurisdictions are forcing enterprises to abandon single-cloud architectures in favor of complex hybrid deployments that fragment vendor relationships and inflate integration spend.
Growth Catalysts
- Saudi Vision 2030 digitalization mandates:Government entities must modernize legacy systems, creating procurement pipelines for integration services that connect on-premise databases with sovereign cloud infrastructure.
- API-first banking modernization:Open banking frameworks in the UAE and South Africa require real-time data exchange between legacy core banking systems and fintech applications.
- Edge computing proliferation:Oil and gas operators in Nigeria and Angola are deploying distributed sensor networks that demand localized integration nodes to process telemetry before cloud transmission.
Market Restraints
- Certification timeline compression:SFDA and MOHAP data residency certifications for healthcare cloud providers extend implementation cycles by eight to fourteen months.
- Skilled integration architect scarcity:The pool of certified professionals capable of designing multi-cloud API gateways remains concentrated in Johannesburg, Dubai, and Riyadh.
- Connectivity infrastructure gaps:Submarine cable reliability issues along East African coastal routes create latency penalties that degrade real-time synchronization performance.
Strategic Opportunities
- Egypt's emerging data protection framework:Draft cross-border transfer restrictions will compel multinationals to establish in-country integration infrastructure ahead of formal enforcement.
- Convergence of AI inference with integration middleware:Enterprises seek platforms that embed machine learning models directly within data pipelines for predictive maintenance in manufacturing.
- Kenya's mobile money ecosystem expansion:M-Pesa interoperability requirements with traditional banking systems create demand for lightweight integration solutions targeting mid-tier financial institutions.
Industry Challenges
- Legacy mainframe synchronization complexity:South African insurers and banks operate COBOL-based core systems that resist standard API wrapper approaches.
- Multi-jurisdiction compliance stacking:Enterprises operating across UAE, Saudi Arabia, and Qatar must architect separate integration paths to satisfy divergent national encryption and audit requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Cloud Integration Market |
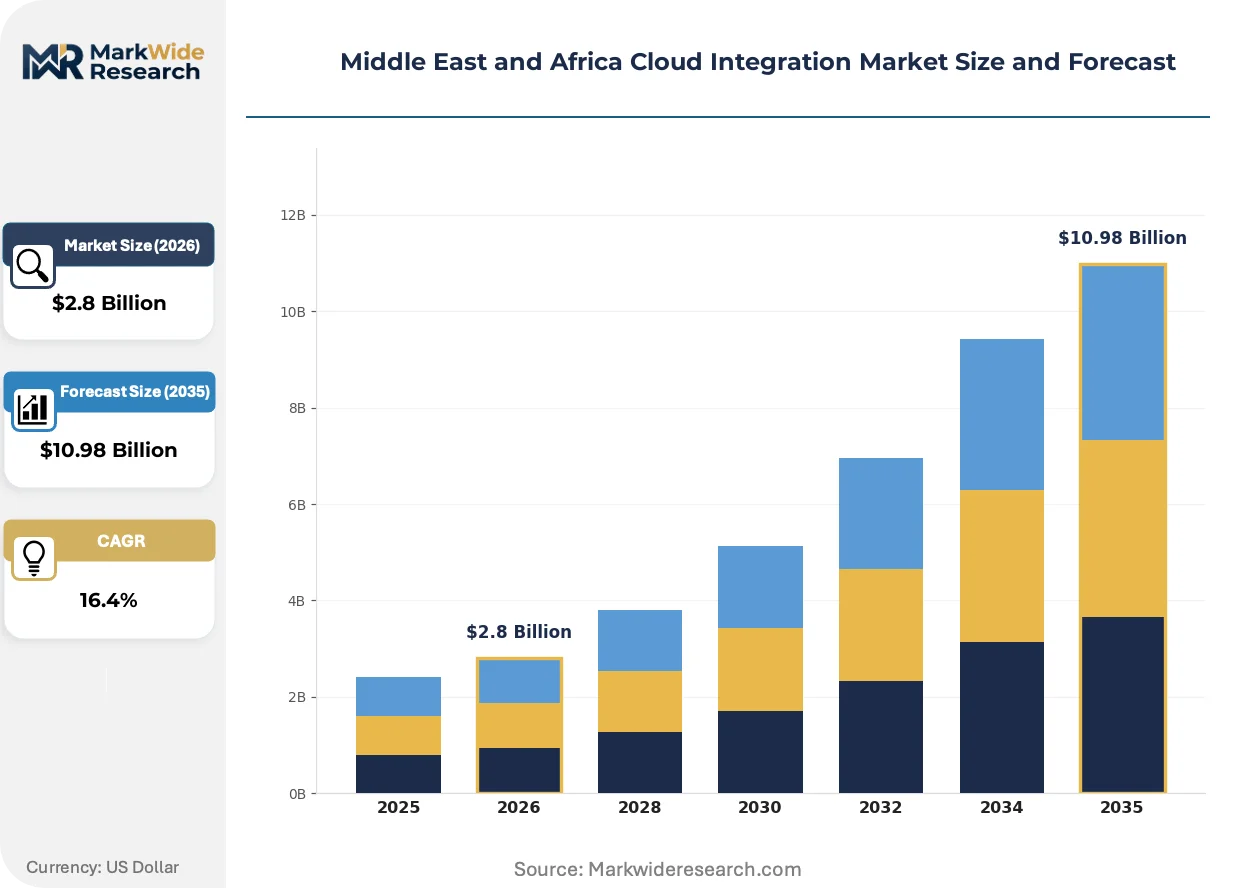
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Integration Platform as a Service, Managed Services, Consulting Services, Support Services End User: BFSI, Healthcare Providers, Retail Enterprises, Energy Companies Solution: Data Integration, Application Integration, API Management, Middleware Solutions |
| Companies Covered | Microsoft Corporation, Oracle Corporation, Informatica Corporation, SAP SE, TIBCO Software Inc., Amazon Web Services, Inc., IBM Corporation, Google LLC, Alibaba Cloud, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Cloud Integration Market Shifts & Advancements
Event-driven architecture patterns are displacing batch-oriented integration approaches across financial services and energy verticals. This shift compresses data latency windows and redefines competitive differentiation for platform vendors.
Event mesh infrastructure is rewriting how distributed enterprises orchestrate data flows. The technology enables publish-subscribe patterns across hybrid environments without centralized broker bottlenecks. Nigerian fintechs and UAE logistics operators are adopting this approach fastest. The architecture is compressing time-to-insight for operational analytics while fragmenting integration vendor market power.
Saudi Arabia's National Data Management Office localization standards are reshaping procurement criteria for critical infrastructure operators. The framework mandates in-country data processing for government and healthcare workloads. Private sector entities are preemptively adopting equivalent architectures to maintain eligibility for public contracts. Compliance investments are diverting budget from application modernization toward foundational integration layers.
Consumption-based pricing for integration platform services is displacing perpetual license models among mid-market enterprises. Subscription metering tied to API call volume or data throughput allows variable cost alignment with transaction seasonality. Kenyan and Egyptian retail banks are driving this transition fastest. The model shifts vendor-customer relationships toward continuous service optimization rather than upfront capital deployment.
Middle East and Africa Cloud Integration Market Segmentation
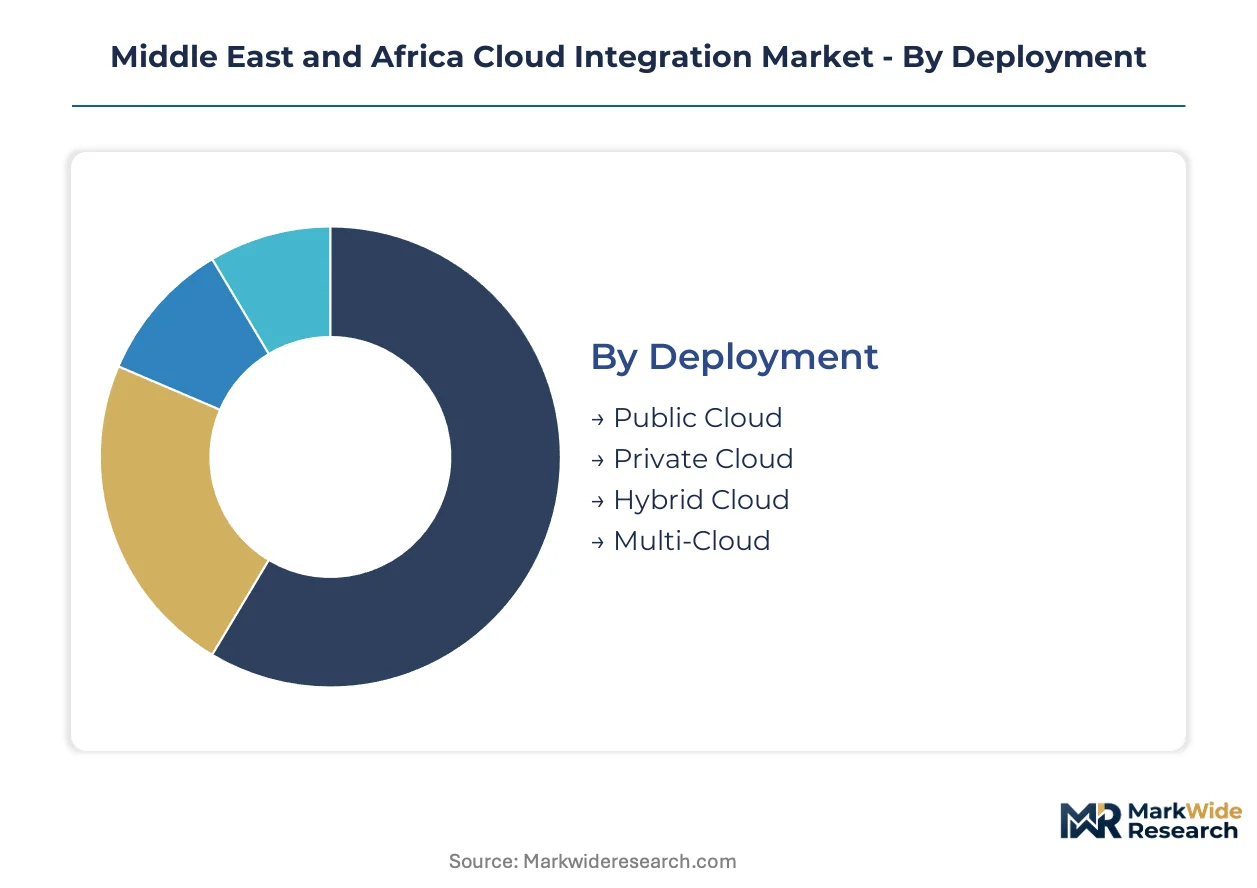
Cloud integration architectures across the Middle East and Africa fragment along deployment topology, service delivery model, end-use vertical, and solution stack. Procurement decisions in this market hinge on data sovereignty mandates, legacy system complexity, and the trade-off between operational control and vendor management overhead.
Deployment:
Supply concentration in hybrid and multi-cloud configurations reflects vendor responses to Gulf Cooperation Council localization requirements.
- Hybrid Cloud:Combines on-premise infrastructure with sovereign cloud nodes to satisfy Saudi Arabia's National Data Management Office and UAE National Cybersecurity Council mandates. South African banks and Saudi healthcare operators drive premium procurement for these architectures due to encryption audit requirements. The complexity premium sustains elevated service margins.
- Multi-Cloud:Distributes workloads across AWS, Azure, and regional providers to eliminate single-vendor dependency. UAE fintechs and Nigerian energy operators adopt this fastest as API gateway standardization matures. Procurement cycles run shorter than hybrid equivalents.
- Public Cloud:Delivers shared infrastructure resources with minimal customization for non-regulated workloads.
- Private Cloud:Provides dedicated single-tenant environments for classified government and defense applications.
Today's leader: Hybrid Cloud. Tomorrow's challenger: Multi-Cloud.
Service Type:
Recurring subscription models concentrate margin pools in platform offerings while professional services face regional system integrator competition.
- Integration Platform as a Service:Cloud-native middleware delivered via metered subscription tied to API call volume or data throughput. Kenyan retail banks and Egyptian mid-market enterprises drive fastest adoption of consumption-based pricing. The model shifts vendor relationships toward continuous optimization.
- Managed Services:Outsourced operation of integration infrastructure including monitoring, patching, and SLA enforcement. Johannesburg-based system integrators capture significant share through captive delivery centers.
- Consulting Services:Architecture design and implementation support for complex multi-cloud transformations.
- Support Services:Break-fix and technical assistance for deployed integration platforms.
Platform-as-a-service subscriptions expand most quickly. Consulting revenue faces compression.
End User:
Vertical specialization determines solution requirements across regulatory intensity and legacy system age.
- BFSI:Banking and financial services institutions operate COBOL-era core systems demanding API wrapper architectures. Open banking frameworks in the UAE and South Africa mandate real-time data exchange with fintech applications. Implementation timelines stretch due to compliance stacking across multiple jurisdictions.
- Healthcare Providers:SFDA and MOHAP certification requirements extend procurement cycles by eight to fourteen months for cloud deployments handling patient records.
- Retail Enterprises:Omnichannel inventory synchronization and payment gateway integration dominate requirements.
- Energy Companies:Edge computing nodes for Nigerian and Angolan oilfield telemetry create demand for localized integration infrastructure.
BFSI commands largest procurement volumes. Energy verticals show steepest expansion trajectory.
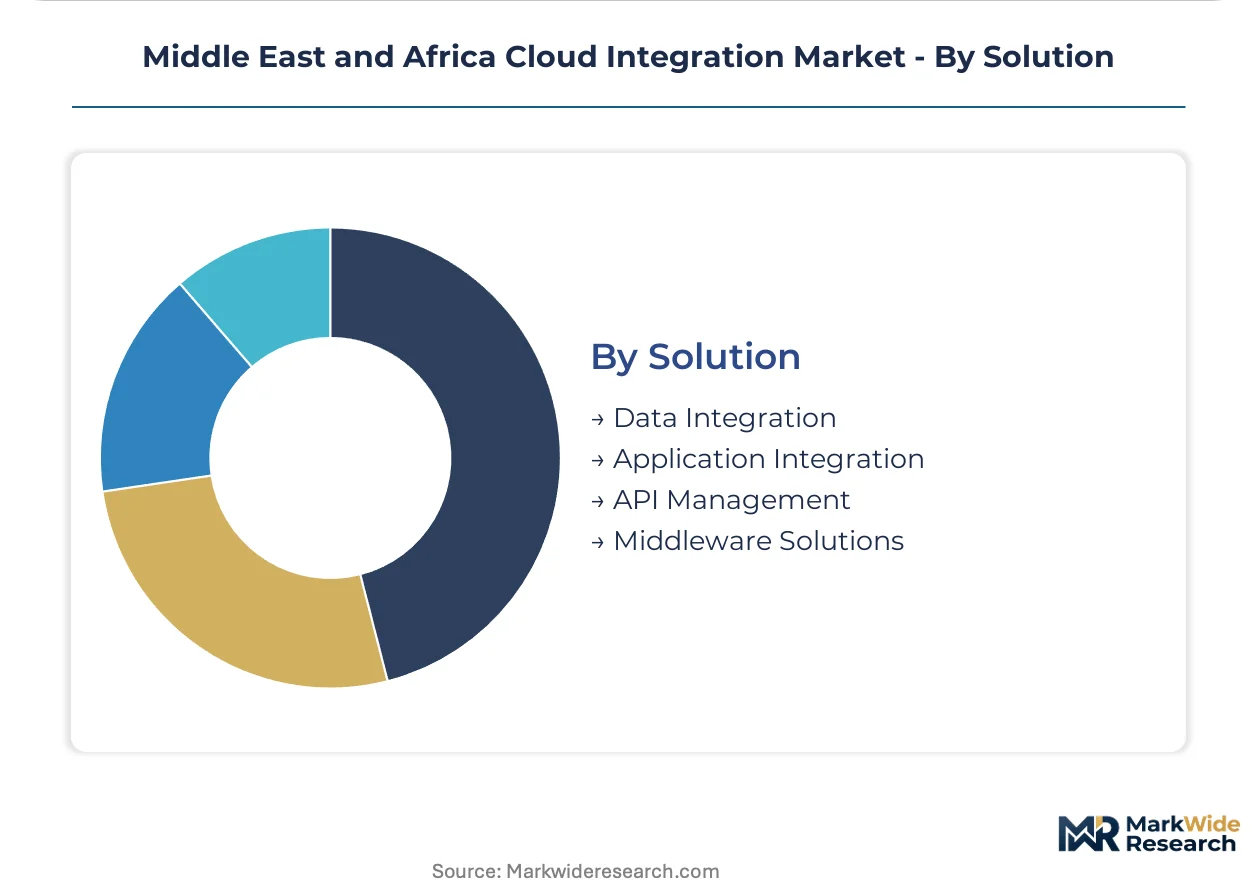
Solution:
Functional specialization in the integration stack maps to enterprise maturity and data architecture complexity.
- Data Integration:ETL pipelines and real-time streaming infrastructure synchronize transactional and analytical workloads. Event-driven patterns displace batch processing across financial services and energy operators. The shift compresses latency windows for operational analytics.
- API Management:Gateway infrastructure, developer portals, and policy enforcement layers govern external data exchange. UAE logistics operators and Nigerian fintechs deploy event mesh architectures to eliminate centralized broker bottlenecks.
- Application Integration:Middleware connecting SaaS applications with on-premise enterprise systems.
- Middleware Solutions:Message queuing and enterprise service bus infrastructure for legacy modernization.
Data integration holds current revenue concentration. API management gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's technology corridor concentrates cloud integration procurement for logistics and fintech operators seeking hybrid architectures. National data sovereignty mandates across the Gulf Cooperation Council reshape enterprise infrastructure decisions.
United Arab Emirates
Abu Dhabi and Dubai host the region's densest concentration of sovereign cloud nodes serving government and financial services workloads. The UAE National Cybersecurity Council enforces localization standards that compel hybrid deployments for critical infrastructure operators. Dubai Internet City clusters house integration specialists supporting real-time API exchanges between legacy banking cores and fintech applications.
Saudi Arabia
Riyadh anchors the largest public sector digital transformation pipeline under Saudi Vision 2030 modernization mandates. The National Data Management Office requires in-country data processing for government and healthcare entities, extending procurement cycles for certified providers. The King Abdullah Financial District concentrates demand from banking institutions modernizing COBOL-era systems.
South Africa
Johannesburg and Cape Town dominate sub-Saharan integration service delivery despite infrastructure constraints along coastal cable routes. The Protection of Personal Information Act imposes cross-border transfer restrictions that elevate demand for local data centers. Sandton's financial district hosts specialists in mainframe API wrapper architectures for legacy insurers.
Egypt
Cairo's emerging technology zone attracts multinational integration infrastructure investments ahead of formal data protection framework enforcement. Draft cross-border transfer restrictions compel preemptive localization strategies among regional headquarters operators. The Smart Village business park clusters mid-market enterprises adopting consumption-based platform pricing.
Nigeria
Lagos anchors West African demand from oil and gas operators deploying edge computing nodes for field telemetry processing. Submarine cable reliability issues create latency penalties that favor localized integration infrastructure over direct cloud transmission. The Lekki Free Trade Zone concentrates energy sector procurement for distributed sensor network architectures.
Middle East and Africa Cloud Integration Market Competitive Landscape
Strategic partnerships dominate the current landscape as hyperscalers anchor hybrid deployments through local system integrator alliances. The vendor base stratifies across three tiers: global platform providers, regional implementation specialists, and niche API management vendors. Two archetypes define positioning: database-centric legacy modernizers and cloud-native middleware specialists. Geographic expansion through certified delivery centers and technology licensing agreements represent the primary competitive vectors.
Within the global platform tier, Microsoft Corporation and Oracle Corporation exemplify divergent integration philosophies. Microsoft leverages Azure Stack deployments to capture regulated verticals requiring on-premise data residency, particularly in Saudi healthcare and UAE government sectors. Oracle sustains positioning through database-centric tools that dominate South African financial institution modernization programs. Informatica Corporation occupies a specialist position in data pipeline orchestration for enterprises migrating analytical workloads to sovereign cloud environments.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Oracle Corporation |
| Informatica Corporation |
| SAP SE |
| TIBCO Software Inc. |
| Amazon Web Services, Inc. |
| IBM Corporation |
| Google LLC |
| Alibaba Cloud |
| Others |
Supply & Pricing Matrix
SFDA and MOHAP data residency certifications gate qualified supply for healthcare cloud integration deployments, restricting premium-tier pricing access to vendors bearing eight-to-fourteen-month compliance investments. This regulatory filter fragments vendor pools and sustains complexity premiums for certified hybrid architectures across Saudi and UAE healthcare operators.
Pricing Analysis
Direct-to-OEM discounts anchor hyperscale buyer negotiations, while system integrator markups inflate mid-market procurement costs. Subscription metering tied to API call volume dominates service delivery, with price differentiation hinging on sovereignty certification tier and after-sales SLA bundling. Cost compression in consulting services is intensifying as Johannesburg-based regional integrators build captive implementation practices. Kenyan retail banks exhibit highest price sensitivity due to consumption-based model adoption, whereas Saudi government entities show lowest sensitivity given mandate-driven procurement.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand, while regional system integrators manage mid-tier enterprise deployments. Supply concentrates in the United Arab Emirates, Saudi Arabia, and South Africa, where sovereign cloud nodes and certified delivery centers cluster. Component dependencies include API gateway infrastructure, edge computing hardware for Nigerian oilfield telemetry, and legacy mainframe wrapper technologies. Single-source vulnerability runs through submarine cable routes along East African coastal corridors. Distribution runs through Dubai Internet City clusters and Johannesburg delivery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa Cloud Integration Market functions as a stable compounder, with national data sovereignty mandates generating recurring procurement pipelines across government digital transformation programs.
For Market Incumbents: Acquire certified delivery center capacity in Riyadh and Dubai to preempt regional system integrator encroachment. Deepen API management platform integration with Azure Stack and Oracle database-centric tools to defend against cloud-native middleware specialists. Prioritize SFDA and MOHAP pre-certification investments to compress healthcare procurement cycles. For New Entrants and Emerging Players: System integrator partnerships in Cairo and Lagos unlock white-space access ahead of Egypt's data protection framework enforcement and Nigerian edge computing proliferation. Target mid-tier Egyptian retail banks adopting consumption-based platform pricing with lightweight M-Pesa interoperability solutions. Lead with event mesh architecture specialization to differentiate from batch-oriented incumbent offerings. For Investors and Strategic Acquirers: Roll-up economics work for regional system integrators with captive Johannesburg delivery centers because skilled integration architect scarcity concentrates margin capture in certified geographies. Five-to-ten-year viability rests on sovereign cloud node deployment density. Monitor Saudi Vision 2030 procurement acceleration as inflection signal for public sector integration spend.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Investment | SFDA and MOHAP compliance investments compress healthcare procurement cycles by eight-to-fourteen months. |
| Event Mesh Architecture Launch | Nigerian fintechs and UAE logistics operators adopt publish-subscribe patterns to eliminate centralized broker bottlenecks. |
| Regional System Integrator Acquisition | Johannesburg-based captive delivery centers capture significant managed services share through localized SLA enforcement. |
| Sovereign Cloud Node Expansion | Abu Dhabi and Riyadh sovereign cloud clusters serve government and financial services workloads under localization mandates. |
| API Gateway Platform Integration | Open banking frameworks in UAE and South Africa mandate real-time data exchange between legacy cores and fintech applications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cloud platform engineers, IT procurement officers at Saudi banks, UAE government digital transformation leads, and Nigerian energy sector CIOs with secondary validation from hyperscaler capex disclosures, SEC filings, and national regulatory framework drafts. Bottom-up deployment topology modeling and top-down sovereign cloud infrastructure tracking were triangulated against regional system integrator capacity assessments.
Historical reference periods anchored the forecast window to pre-mandate baseline infrastructure spend and post-localization enforcement procurement acceleration. The analytical framework modeled deployment topology, service delivery model, end-use vertical, and solution stack dimensions across the projection horizon. CAGRs were derived from compound growth trajectory analysis incorporating API call volume seasonality, certification timeline compression effects, and edge computing node proliferation patterns in Nigerian and Angolan oilfields.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to divergent Gulf Cooperation Council certification regimes, submarine cable reliability disruptions, and legacy mainframe modernization complexity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Smart and Connected Offices Market
Digital Solutions
Digital Experience Technology Market
Digital Solutions
US Digital Signage Market
Digital Solutions
UX Services Market
Digital Solutions
Voice Remote Control Market
Digital Solutions
Business Transcription Market
Digital Solutions
Latin America IT Market
Digital Solutions
Germany Content Services Platform Market
Digital Solutions
China Digital Twin Market
Digital Solutions
Mobile Engagement Market
Digital Solutions
Global Demand Side Platforms (DSP) for Programmatic Advertising Market
Digital Solutions
Graph Technology Market
Digital Solutions
Global Machine Translation (MT) Market
Digital Solutions
Europe API Management Market
Digital Solutions
Global Online Reputation Management Software Market
Digital Solutions
Cinema Point of Sale (POS) Solutions Market