
 Global Enterprise Information Archiving Market | 2026-2036
Global Enterprise Information Archiving Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enterprise Information Archiving Market Foresight
Platform licensing revenue is tilting toward subscription-based cloud archives as enterprises retire perpetual on-premises licenses. Microsoft Corporation leverages its Microsoft 365 ecosystem to embed archiving into productivity workflows. Google LLC anchors its position through Gmail and Google Workspace compliance integrations. Veritas Technologies LLC specializes in hybrid environments that bridge legacy tape systems with cloud repositories.
Enterprise information archiving encompasses the systematic capture, indexing, storage, and retrieval of structured and unstructured business records across email, files, databases, and mobile communications, typically retaining data for seven to ten years with immutable WORM storage and cryptographic integrity verification to satisfy legal hold and audit requirements. Cloud-based deployment captures the fastest expansion as organizations seek elastic capacity without capital-intensive infrastructure. Email archiving remains the largest solution offering by installed base, though social media archiving grows fastest as regulated industries face FINRA and SEC scrutiny of digital communications. Compliance management dominates use case demand, while e-discovery commands premium pricing due to specialist tooling and defensible chain-of-custody workflows.
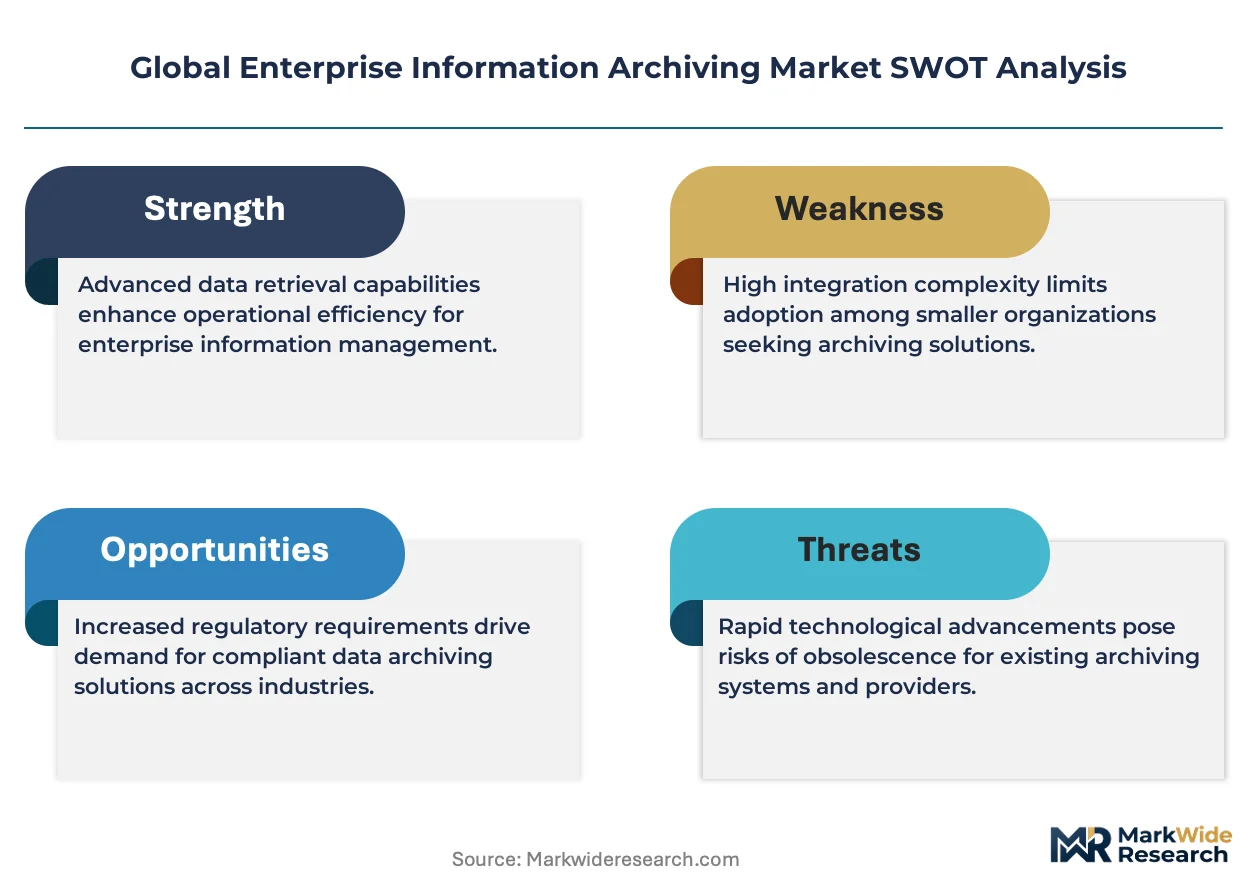
The SEC, FINRA, and GDPR enforcement patterns in the United States and European Union are tightening retention and discoverability standards, forcing enterprises to upgrade archive systems or face penalties. HIPAA in healthcare and the EU AI Act's training data documentation requirements are extending archiving scope into machine learning pipelines. Stakeholders must weigh the trade-off between cloud-native simplicity and hybrid flexibility as regulatory fragmentation across jurisdictions intensifies.
Market Dynamics
Cloud-native immutable storage architectures are compressing replacement cycles for legacy on-premises tape systems as enterprises face simultaneous pressure from data sovereignty mandates and litigation readiness requirements.
Growth Catalysts
- SEC and FINRA digital communications oversight:Broker-dealers and investment advisers must archive mobile messages, social media, and collaboration platforms. Compliance officers are expanding budgets to capture ephemeral channels.
- Healthcare data retention mandates:HIPAA requirements for patient record accessibility are extending retention periods to seven years minimum. Hospital systems are consolidating fragmented departmental archives.
- EU AI Act training data documentation:Machine learning pipeline provenance requirements are forcing enterprises to archive dataset versions, model parameters, and audit trails for algorithmic accountability.
Market Restraints
- Cross-border data transfer friction:GDPR adequacy decisions and Schrems II rulings are complicating cloud archive architectures for multinational corporations operating across EU-US data corridors.
- Specialized cryptographic talent scarcity:Immutable WORM storage design and zero-knowledge proof implementations require skills concentrated in limited labor pools.
- Tape-to-cloud migration capex burden:Petabyte-scale legacy extraction projects demand twelve-to-eighteen-month payback horizons that strain IT capital allocation committees.
Strategic Opportunities
- Japan's financial sector digitization:METI guidelines on electronic record-keeping are accelerating retirement of paper-based archives among regional banks and insurers.
- Convergence of e-discovery and analytics:Natural language processing integration with archived repositories enables proactive litigation risk assessment before external counsel engagement.
- Germany's DORA operational resilience requirements:Financial entities must demonstrate rapid data recovery capabilities, creating demand for geographically distributed active-archive configurations.
Industry Challenges
- Fragmented jurisdictional retention schedules:Enterprises operating across United States, Germany, and Japan must reconcile seven-year SEC requirements with ten-year Japanese commercial code provisions and variable GDPR member-state implementations.
- Chain-of-custody verification complexity:Legal hold processes require cryptographically verifiable timestamps and access logs that resist tampering accusations during adversarial discovery proceedings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enterprise Information Archiving Market |
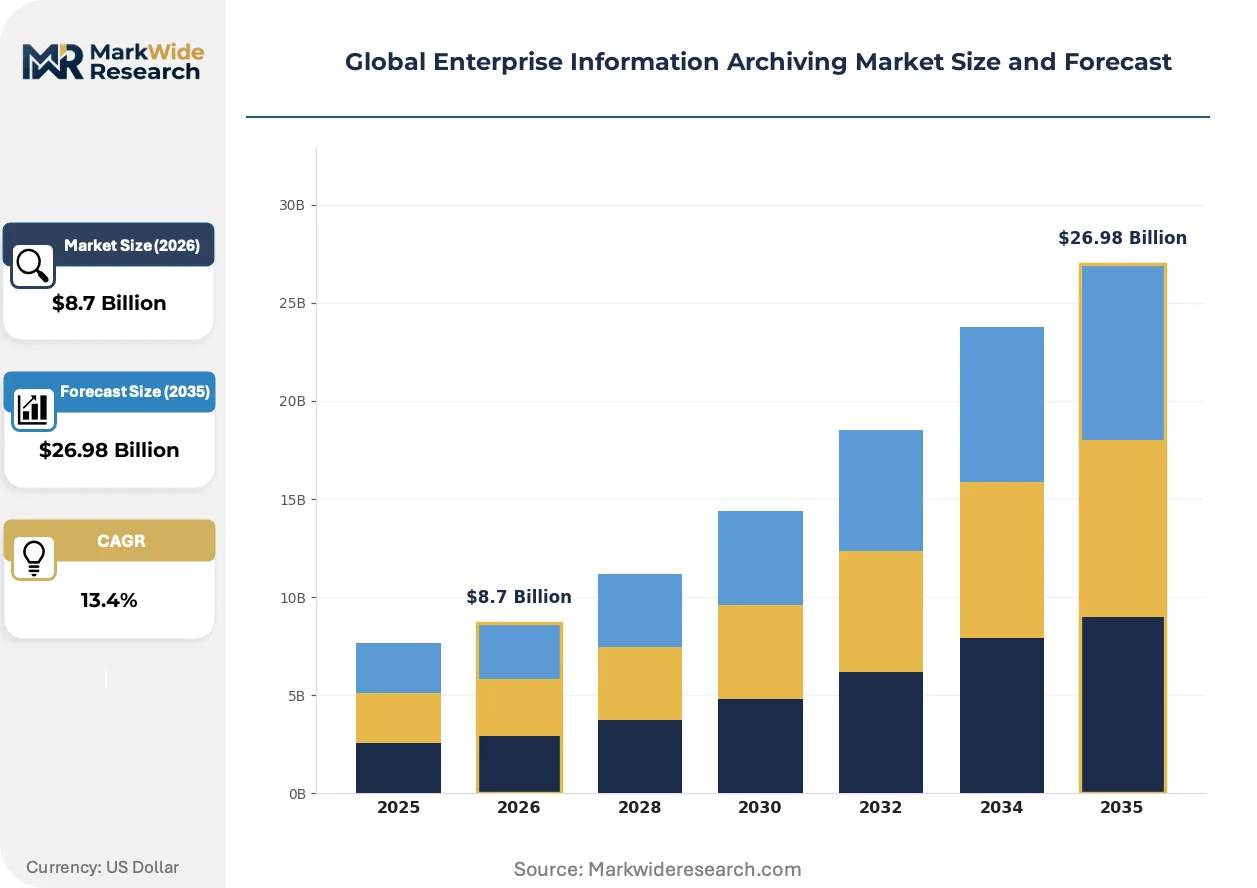
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Virtualized Solution Offering: Email Archiving, File Archiving, Social Media Archiving, Database Archiving, Mobile Archiving Use Case: Compliance Management, E-Discovery, Litigation Support, Data Protection, Records Management End User Industry: BFSI, Government Agencies, Telecommunications, Legal Services, Energy & Utilities |
| Companies Covered | Barracuda Networks, Inc., Microsoft Corporation, International Business Machines Corporation, Veritas Technologies LLC, Google LLC, Proofpoint, Commvault, Smarsh Inc., Mimecast Services Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enterprise Information Archiving Market Shifts & Advancements
Artificial intelligence is penetrating archive systems at ingestion, classification, and retrieval layers simultaneously, compressing the traditional trade-off between storage cost and discoverability speed.
Object storage with S3-compatible APIs and native immutability is rendering obsolete proprietary tape robotics and hierarchical storage management middleware. Capital markets firms in New York and London are migrating petabyte-scale email archives to cloud object stores within eighteen-month windows. The shift eliminates forklift hardware upgrades and enables elastic capacity for episodic e-discovery surges.
The EU AI Act's documentation requirements are extending archiving scope beyond traditional records into training data provenance and model versioning. Pharmaceutical and automotive manufacturers deploying machine learning for quality control must now maintain searchable histories of algorithmic decisions. German industrial conglomerates are engaging specialized vendors to bridge MES data historians with long-term compliance repositories.
Subscription pricing for archive capacity is displacing perpetual license plus maintenance models across mid-market enterprises. Procurement teams in healthcare and professional services are negotiating consumption-based contracts with built-in egress fee caps. This pattern is most visible in United States markets where CFOs prioritize operational expenditure classification for technology investments.
Global Enterprise Information Archiving Market Segmentation
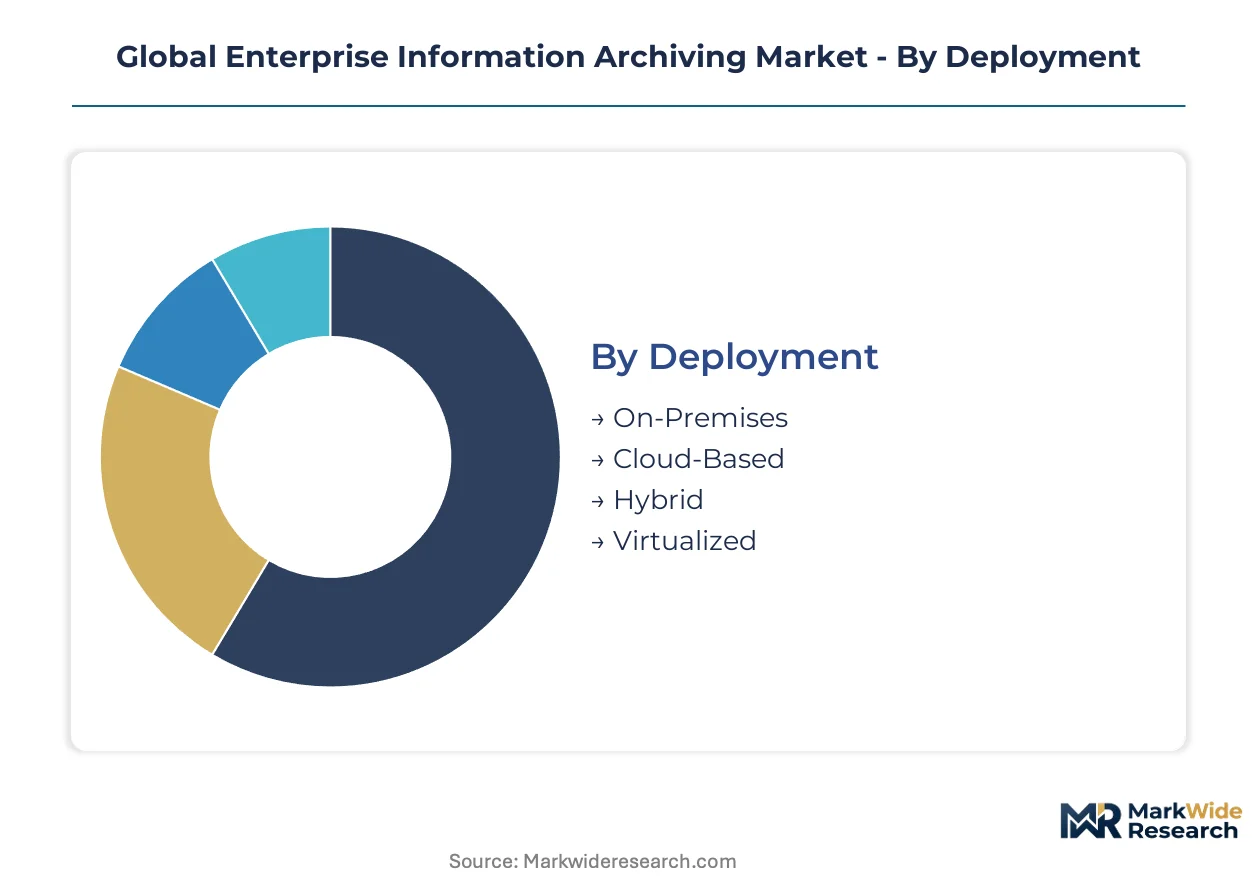
Enterprise information archiving segments diverge sharply in replacement velocity. Cloud-native deployments refresh every three to five years while on-premises tape systems persist for a decade. Procurement teams must align segment selection with regulatory deadlines and litigation risk profiles.
Deployment:
Replacement cycles separate cloud-native architectures from legacy infrastructure. Virtualized and hybrid options occupy intermediate positions with variable refresh timelines.
- Cloud-Based:Elastic capacity provisioning eliminates capital-intensive hardware procurement. Financial services firms in the United States and Germany are migrating email archives to object storage with native immutability to satisfy SEC and GDPR enforcement timelines.
- Hybrid:Bridging configurations preserve legacy tape investments while enabling cloud burst capacity for episodic e-discovery surges. Multinational corporations operating across EU-US data corridors favor this architecture to navigate Schrems II transfer restrictions.
- On-Premises:Dedicated hardware installations persist in defense and classified government environments with air-gapped security mandates.
- Virtualized:Software-defined storage pools abstract physical infrastructure without full cloud dependency, appealing to mid-market enterprises with compliance obligations but limited cloud expertise.
On-Premises dominates installed base. Cloud-Based is where expansion concentrates.
Solution Offering:
Functional scope ranges from mature email repositories to emerging social media capture systems with divergent price points and integration complexity.
- Email Archiving:Systematic capture and indexing of electronic mail with cryptographic integrity verification. BFSI and legal services sectors in the United States maintain the largest installed volumes to satisfy FINRA retention and federal discovery rules.
- Social Media Archiving:Ephemeral channel preservation including mobile messages and collaboration platforms. Broker-dealers facing SEC digital communications oversight are expanding budgets fastest for this capability.
- File Archiving:Unstructured document repositories with automated classification and lifecycle policies.
- Database Archiving:Structured data retention with query-optimized compression for long-term accessibility.
- Mobile Archiving:SMS and application message capture extending compliance coverage to personal devices.
Email Archiving commands the largest revenue pool. Social Media Archiving is climbing the fastest as regulated industries confront ephemeral channel scrutiny.
Use Case:
Commercial value concentrates in defensible legal processes versus routine compliance automation with distinct margin profiles.
- E-Discovery:Specialist tooling for litigation readiness with chain-of-custody documentation and adversarial discovery defense. Law firms and corporate legal departments in the United States pay premium pricing for defensible workflows.
- Compliance Management:Systematic retention scheduling and audit trail generation. Healthcare systems consolidating fragmented departmental archives to satisfy HIPAA accessibility mandates drive volume demand.
- Litigation Support:Active hold management and external counsel collaboration tools.
- Data Protection:Ransomware recovery and disaster resilience through immutable backup integration.
- Records Management:Classification, retention, and disposition policies for unstructured content.
Compliance Management generates the highest transaction volume. E-Discovery captures the steepest expansion trajectory due to specialist pricing power.
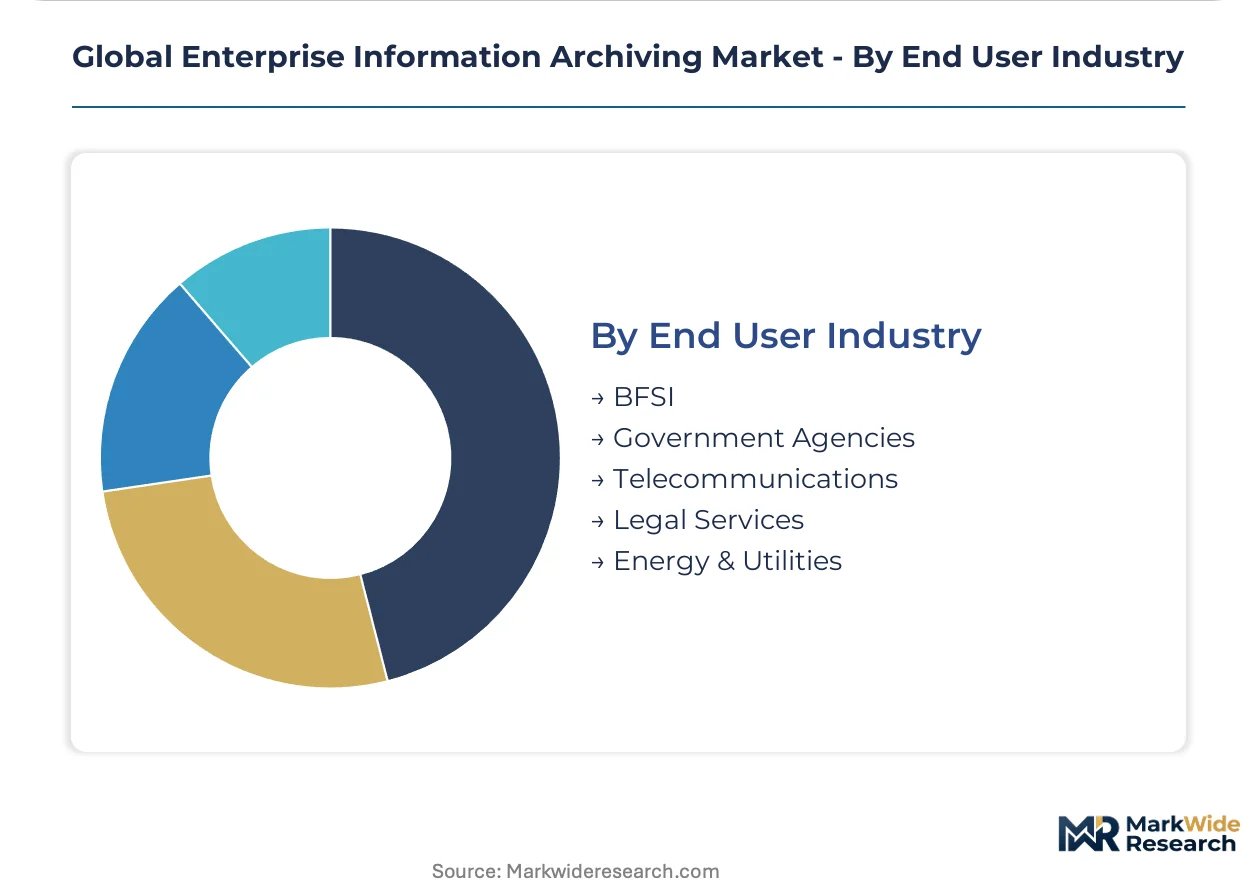
End User Industry:
Regulatory intensity and litigation exposure create divergent procurement patterns across verticals with varying archive sophistication.
- BFSI:Comprehensive capture requirements spanning trading communications, customer records, and audit trails. Japanese regional banks and insurers are accelerating digitization under METI electronic record-keeping guidelines.
- Government Agencies:Classified and unclassified record retention with transparency and national security dual mandates. German federal and state entities are expanding archive investments to satisfy DORA operational resilience demonstrations.
- Legal Services:Matter-centric retention with client confidentiality and ethical wall enforcement.
- Telecommunications:Subscriber data retention with lawful intercept and privacy balance requirements.
- Energy & Utilities:Operational technology data historians merged with compliance repositories for critical infrastructure protection.
BFSI anchors revenue concentration. Government Agencies are gaining share fastest as data sovereignty mandates intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States financial services firms consume archiving capacity for litigation readiness, while German manufacturers prioritize operational resilience documentation and Japanese institutions focus on paper-to-digital transitions. This consumption-mix differential shapes procurement priorities across major markets.
United States
SEC and FINRA enforcement drives broker-dealers to archive mobile messages and collaboration platforms. HIPAA mandates extend retention to seven years for healthcare systems. New York and Chicago capital markets clusters are migrating petabyte-scale email archives to cloud object stores within compressed eighteen-month windows.
Germany
DORA operational resilience requirements force financial entities to demonstrate rapid data recovery capabilities. GDPR adequacy decisions complicate cloud architectures for multinational corporations. Frankfurt and Munich industrial conglomerates are bridging manufacturing execution system data historians with long-term compliance repositories.
Japan
METI electronic record-keeping guidelines accelerate retirement of paper-based archives among regional banks and insurers. Commercial code provisions mandate ten-year retention periods exceeding SEC requirements. Tokyo and Osaka financial centers are consolidating fragmented departmental archives under unified governance frameworks.
United Kingdom
FCA conduct rules and GDPR alignment pressure asset managers to upgrade legacy systems. Post-Brexit data sovereignty concerns redirect procurement toward EU-UK compliant architectures. London legal services and fintech clusters are expanding e-discovery tooling budgets for adversarial discovery defense.
India
SEBI mandate for broker-dealer communications archiving expands addressable market. RBI data localization norms push financial institutions toward domestic cloud or hybrid deployments. Mumbai and Bengaluru banking technology hubs are negotiating consumption-based contracts with built-in egress fee caps.
Global Enterprise Information Archiving Market Competitive Landscape
Capability concentration sits with specialized compliance vendors; scale advantage sits with productivity-suite platforms. The market structures around three tiers: cloud-native productivity ecosystems, hybrid infrastructure specialists, and sector-specific compliance tools. Dominant competitive moves include embedding archiving into adjacent workflow software and constructing geographically distributed active-archive configurations for data sovereignty compliance.
Within the productivity-ecosystem tier, Microsoft Corporation and Google LLC represent scale-driven positioning through embedded compliance integrations. Veritas Technologies LLC occupies the hybrid-specialist archetype, bridging legacy infrastructure with cloud repositories. These three anchors exemplify the capability-scale trade-off defining procurement decisions across regulated industries.
| Leading Market Players |
|---|
| Barracuda Networks, Inc. |
| Microsoft Corporation |
| International Business Machines Corporation |
| Veritas Technologies LLC |
| Google LLC |
| Proofpoint |
| Commvault |
| Smarsh Inc. |
| Mimecast Services Limited |
| Others |
Supply & Pricing Matrix
Specialized cryptographic talent pools concentrated in the United States, Germany, and Israel feed directly into margin capture at the e-discovery and compliance management tiers. Cloud storage commoditization compresses infrastructure costs while cryptographic integrity verification and chain-of-custody tooling sustain premium pricing power for specialist vendors.
Pricing Analysis
Subscription-based SaaS contracts dominate enterprise procurement, displacing perpetual licensing across mid-market buyers. Pricing stratifies across premium, standard, and economy tiers based on immutability guarantees and geographic data residency options. Cost compression in standard-tier cloud storage intensifies as hyperscalers compete on egress fee structures. Healthcare systems and professional services firms exhibit highest price sensitivity; capital markets firms demonstrate lowest sensitivity due to litigation risk premiums.
Supply Chain Analysis
Upstream hardware components for WORM storage systems draw from Taiwan, South Korea, and Japan. Specialized encryption processors and tamper-resistant hardware security modules rest on semiconductor fabrication concentrated in East Asian foundries. Single-source vulnerability around post-quantum cryptographic implementations poses structural risk as NIST standardization proceeds. Distribution runs through direct enterprise sales teams and hyperscaler marketplace integrations for cloud-native deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Native productivity-suite archiving features embedded in Microsoft 365 and Google Workspace threaten standalone vendor margins. Incumbents must articulate hybrid flexibility and regulatory jurisdiction expertise as defensible differentiation against ecosystem substitution.
For Market Incumbents: Insulate installed base relationships by accelerating hybrid archive configurations that bridge legacy tape with cloud object storage. Deepen vertical integration into cryptographic verification tooling to defend against hyperscaler encroachment. Prioritize DORA and EU AI Act compliance certifications as competitive moats. For New Entrants and Emerging Players: Pursue white-space opportunities in Japan's regional banking sector and India's SEBI-mandated broker-dealer communications capture. Target social media archiving for FINRA-regulated investment advisers as the most penetrable segment. Lead with consumption-based pricing and built-in egress fee caps to displace incumbent maintenance contracts. For Investors and Strategic Acquirers: Capital is best deployed toward hybrid-specialist vendors with established EU-US data corridor navigation capabilities and active-archive geographic distribution. Long-term viability hinges on post-quantum cryptographic transition readiness and machine learning pipeline provenance tooling. Watch NIST post-quantum standardization timelines as inflection signal for cryptographic refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Archive Configuration | Bridges legacy tape investments with cloud burst capacity for Schrems II compliance. |
| Post-Quantum Cryptographic Transition | Positions vendors ahead of NIST standardization for tamper-resistant archival integrity. |
| EU AI Act Documentation Integration | Extends archiving scope into training data provenance for pharmaceutical and automotive manufacturers. |
| Geographic Active-Archive Distribution | Satisfies Germany's DORA operational resilience requirements for rapid data recovery. |
| Consumption-Based Pricing Restructure | Aligns with CFO preference for operational expenditure classification in United States healthcare. |
Research Methodology
Operator-level perspectives from compliance officers, legal hold administrators, cloud procurement directors, and information security architects anchored the qualitative base. Primary interview data combined with secondary validation drawn from SEC enforcement releases, FINRA examination findings, GDPR adequacy decision documentation, and hyperscaler compliance certification disclosures. Bottom-up deployment modeling and top-down regulatory mandate sizing were triangulated for segment-level consistency.
Scenario-bracketing around regulatory enforcement intensity and cloud migration velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass deployment architecture, solution offering functional scope, use case commercial value, and end-user industry regulatory intensity. CAGRs were derived from elasticity-adjusted replacement cycle analysis and jurisdictional mandate implementation timelines. Machine learning pipeline provenance requirements and post-quantum cryptographic transition schedules served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting IT capital allocation committees would shift the trajectory. Forecasts reflect assumptions around regulatory enforcement continuity and hyperscaler pricing discipline. Cross-checking against hyperscaler earnings call commentary on compliance workload growth is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Business Support System Market
Digital Solutions
Global Electronic Shift Operations Management Solutions (Esoms) Market
Digital Solutions
Government Open Data Management Platform Market
Digital Solutions
Deviation Management and CAPA Platforms for Cold Chain Logistics Market
Digital Solutions
AI Infrastructure Solutions Market
Digital Solutions
Germany Digital Twin Market
Digital Solutions
Precision Agriculture Software Market
Digital Solutions
Global Delivery Management Software Market
Digital Solutions
Service Mesh Market
Digital Solutions
Utility Bill Management System Market
Digital Solutions
North America Product Design and Development Services Market
Digital Solutions
Supply Side Platform (SSP) Market
Digital Solutions
Incidence Management Software Market
Digital Solutions
Product Data Management Market
Digital Solutions
Mobile Collaboration Market
Digital Solutions
End-User Computing (EUC) Market