
 Global Interactive Voice Response Market | 2026-2036
Global Interactive Voice Response Market Size, Share, and Industry Trends Forecast 2026-2036
Global Interactive Voice Response Market Foresight
The premium IVR tier anchored by natural-language speech recognition and real-time analytics is rebalancing away from commodity call-routing hardware as enterprises prioritize customer-experience differentiation. Cisco Systems Inc. leverages its unified communications ecosystem to sustain hybrid deployment dominance across large financial firms. Twilio Inc. anchors cloud-native programmable voice infrastructure that competes with legacy on-premises incumbents. Nuance Communications Inc. specializes in conversational AI layers that differentiate premium speech-recognition offerings from basic dual-tone multi-frequency menu systems.
Interactive Voice Response denotes an automated telephony system that interacts with callers through pre-recorded voice prompts, dual-tone multi-frequency inputs, and natural-language speech recognition to collect information and route calls without human intervention. These systems process caller inputs through voice-extensible markup language scripting and integrate with customer-relationship management databases to execute tasks ranging from balance inquiries to appointment scheduling. Cloud-based deployment leads structural momentum as enterprises abandon capital-intensive on-premises hardware for subscription models with faster scaling. Speech recognition represents the fastest-expanding solution type as banking services and e-commerce platforms adopt conversational AI to reduce live-agent escalation rates. Call routing remains mature with thinner margins, while analytics commands premium pricing by delivering real-time sentiment scoring and queue-optimization insights.
The Federal Communications Commission shapes US market access through robocall mitigation rules and STIR/SHAKEN authentication mandates that force IVR vendors to upgrade caller-ID verification protocols. The EU AI Act imposes risk-classification requirements on automated decision-making systems, compelling European financial firms to document IVR algorithmic logic for customer-facing credit and payment workflows. The Bureau of Indian Standards and Telecom Regulatory Authority of India enforce quality-of-service benchmarks that accelerate domestic cloud-IVR adoption among telecom operators. Stakeholders must monitor evolving interoperability standards between proprietary speech engines and open-source conversational frameworks to avoid platform lock-in as hybrid architectures become the default enterprise configuration.
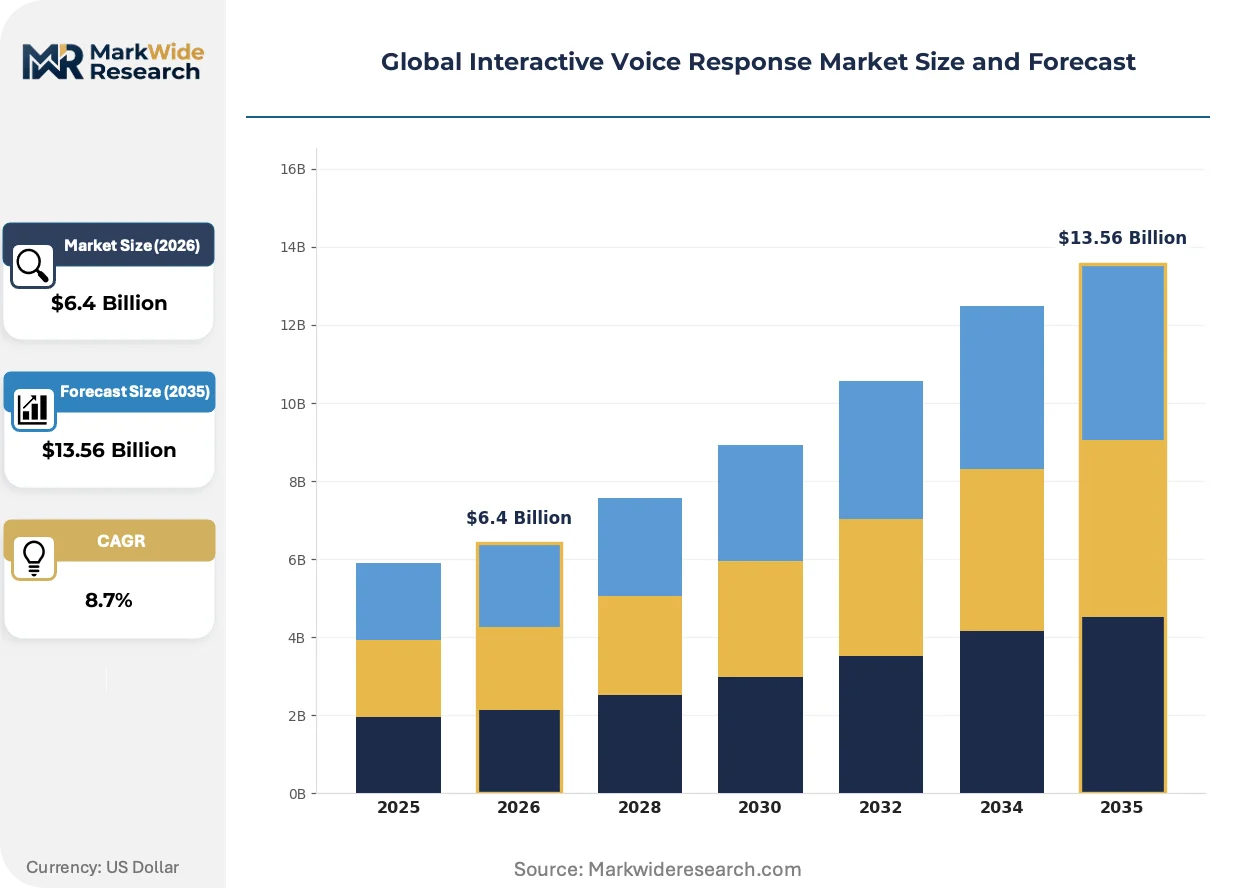
Market Dynamics
Cloud migration mandates under the EU AI Act are forcing European financial institutions to replace legacy on-premises IVR hardware with auditable, scalable cloud infrastructure, compressing deployment timelines and reshaping vendor selection criteria.
Growth Catalysts
- EU AI Act compliance deadlines:European banks face mandatory risk-classification documentation for automated customer-facing workflows, accelerating replacement of opaque legacy systems with transparent cloud-native alternatives.
- Speech recognition advancement:Natural-language processing layers reduce live-agent escalation rates in high-volume banking and e-commerce applications, lowering operational costs per interaction.
- India:TRAI quality-of-service benchmarks and BIS technical standards compel domestic telecom operators to modernize subscriber self-service platforms, driving cloud-IVR procurement at scale.
Market Restraints
- Legacy integration costs:Capital-intensive middleware development is required to bridge proprietary on-premises PBX systems with API-first cloud architectures, extending payback periods for hybrid deployments.
- Data residency requirements:Fragmented national data-localization laws across Germany, France, and India force vendors to maintain region-specific infrastructure, inflating operational complexity.
- Substitute channel proliferation:Mobile app-based self-service and asynchronous messaging platforms capture routine transactional queries, compressing addressable volume for voice-centric automation.
Strategic Opportunities
- Real-time analytics premium tier:Sentiment scoring and queue-optimization insights command pricing multiples above basic call-routing, creating margin expansion for vendors with proprietary data pipelines.
- Healthcare administrative automation:Appointment scheduling, prescription refill workflows, and insurance eligibility verification represent underpenetrated verticals with compliance requirements favoring auditable IVR audit trails.
- Conversational AI and biometric voiceprint convergence:Integrated authentication layers reduce fraud losses in financial services while streamlining caller verification, differentiating next-generation platforms from commodity DTMF menu systems.
Industry Challenges
- Conversational AI talent scarcity:Shortages of linguists and machine-learning engineers with telephony-domain expertise delay deployment timelines and inflate personnel costs for complex natural-language implementations.
- STIR/SHAKEN protocol integration:FCC caller-ID authentication mandates require vendors to rebuild signaling infrastructure, creating compliance friction for legacy system operators serving US financial clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Interactive Voice Response Market |
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $13.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Hosted Solution Type: IVR Software, Speech Recognition, Text to Speech, Call Routing, Analytics Application: Customer Support, Payment Processing, Survey & Feedback, Banking Services, Order Management End User Industry: Telecom Operators, Financial Firms, Government Agencies, Travel & Hospitality, E-commerce Platforms |
| Companies Covered | Verizon Communications Inc., AT&T Inc., Cisco Systems Inc., Twilio Inc., Avaya Inc., Genesys Telecommunication Laboratories Inc., Nuance Communications Inc., 8x8 Inc., Five9 Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Interactive Voice Response Market Shifts & Advancements
Natural-language speech recognition is compressing the viable lifespan of dual-tone multi-frequency menu systems, while regulatory pressure on algorithmic transparency redefines what constitutes a deployable IVR architecture.
Conversational AI engines with real-time intent classification and contextual memory are overtaking static voice-extensible markup language scripts in enterprise deployments. Banking contact centers in the United States and Germany are adopting these platforms to deflect tier-one support volume without live-agent handoff. The technology is overtaking hardware-centric routing appliances as the primary budget line item in telecom procurement cycles.
The EU AI Act's risk-classification framework imposes documentation burdens on automated decision-making systems processing credit and payment workflows. European financial institutions must maintain algorithmic logic records accessible to national supervisory authorities, favoring vendors with built-in audit trails over opaque legacy configurations. German and French retail banks are restructuring procurement specifications to prioritize explainability features.
Subscription-based consumption models are displacing perpetual-license arrangements as the dominant commercial structure. Enterprise buyers in India and the United States favor usage-scaled pricing with rapid scaling provisions over capital-intensive on-premises deployments. This shift is most visible among mid-market financial services firms seeking to match infrastructure costs to seasonal call-volume fluctuations without stranded asset risk.
Global Interactive Voice Response Market Segmentation
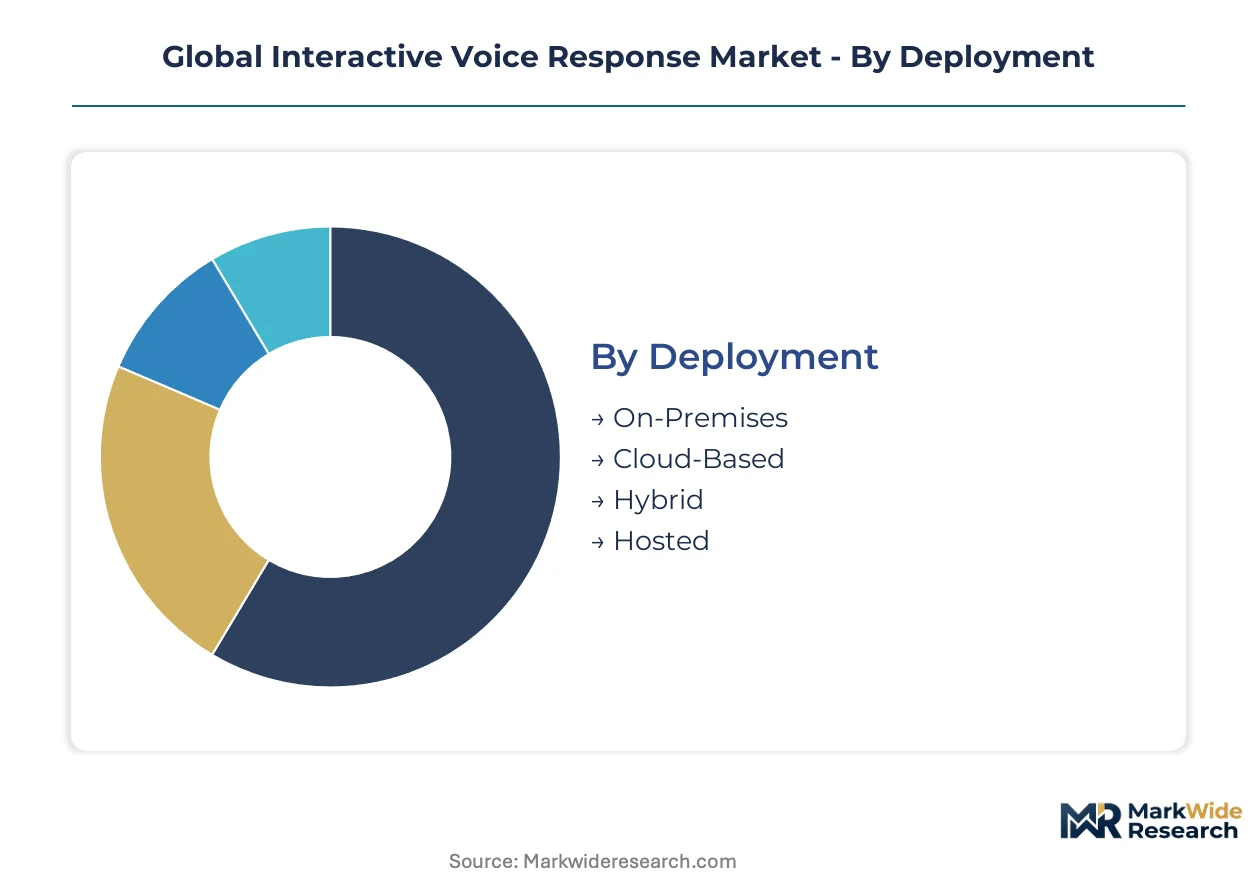
IVR market segmentation reveals how deployment economics, solution sophistication, and vertical compliance requirements fragment purchasing behavior across enterprise tiers. Distinct procurement patterns emerge between regulated financial institutions prioritizing audit trails and cost-sensitive telecom operators optimizing per-call economics.
Deployment:
Customization intensity varies sharply across this spectrum, from rigid on-premises hardware to elastic cloud configurations that enterprises tailor to seasonal volume spikes.
- On-Premises:Physical infrastructure housed within enterprise data centers delivers maximum data sovereignty and sub-millisecond latency for high-frequency trading floors. German and French retail banks maintain these configurations for credit-decision workflows requiring EU AI Act documentation trails.
- Cloud-Based:API-first architectures enable rapid scaling without capital expenditure. Indian telecom operators under TRAI quality mandates are migrating subscriber self-service platforms to these models to match infrastructure costs to call-volume fluctuations.
- Hybrid:Split architectures route sensitive authentication through on-premises nodes while offloading routine queries to cloud instances. Financial firms in the United States deploy this pattern to satisfy internal risk committees while capturing cloud elasticity.
- Hosted:Third-party managed services eliminate operational overhead for mid-market enterprises lacking dedicated telephony engineering teams.
Leading the category by volume: Cloud-Based. Growing fastest: Hybrid.
Solution Type:
Margin structures diverge between commoditized routing functions and proprietary AI layers commanding recurring analytics subscriptions.
- IVR Software:Core platform licenses enabling voice-extensible markup language scripting and CRM integration form the foundational revenue layer across all deployment modes.
- Speech Recognition:Natural-language processing engines with real-time intent classification reduce live-agent escalation in high-volume banking contact centers. United States and German institutions prioritize these platforms for tier-one support deflection without human handoff.
- Text to Speech:Neural voice synthesis generates dynamic prompts from database queries, enabling personalized balance announcements and appointment reminders at scale.
- Call Routing:DTMF-menu and skills-based distribution systems face pricing compression as conversational AI displaces static routing logic.
- Analytics:Real-time sentiment scoring and queue-optimization insights deliver the steepest expansion trajectory as enterprises prioritize experience differentiation over cost reduction alone.
Revenue concentrates in: Speech Recognition. Premium pricing commands: Analytics.
Application:
Use-case complexity scales from transactional automation to emotionally sensitive interactions requiring escalation protocols.
- Customer Support:Automated troubleshooting and account servicing handle the highest call volumes across telecom and e-commerce verticals.
- Payment Processing:PCI-DSS-compliant voice authentication for credit-card and utility payments dominates financial firm procurement specifications.
- Survey & Feedback:Post-interaction satisfaction collection and net-promoter-score polling represent mature, price-sensitive demand.
- Banking Services:Balance inquiries, fund transfers, and fraud alerts generate the deepest integration requirements with core banking systems. Indian and United States institutions are expanding these workflows under regulatory pressure for auditable automation.
- Order Management:Inventory checks, shipping status, and return authorization support e-commerce platforms seeking to deflect routine queries from live agents.
Widest deployment: Customer Support. Tightest compliance integration: Banking Services.
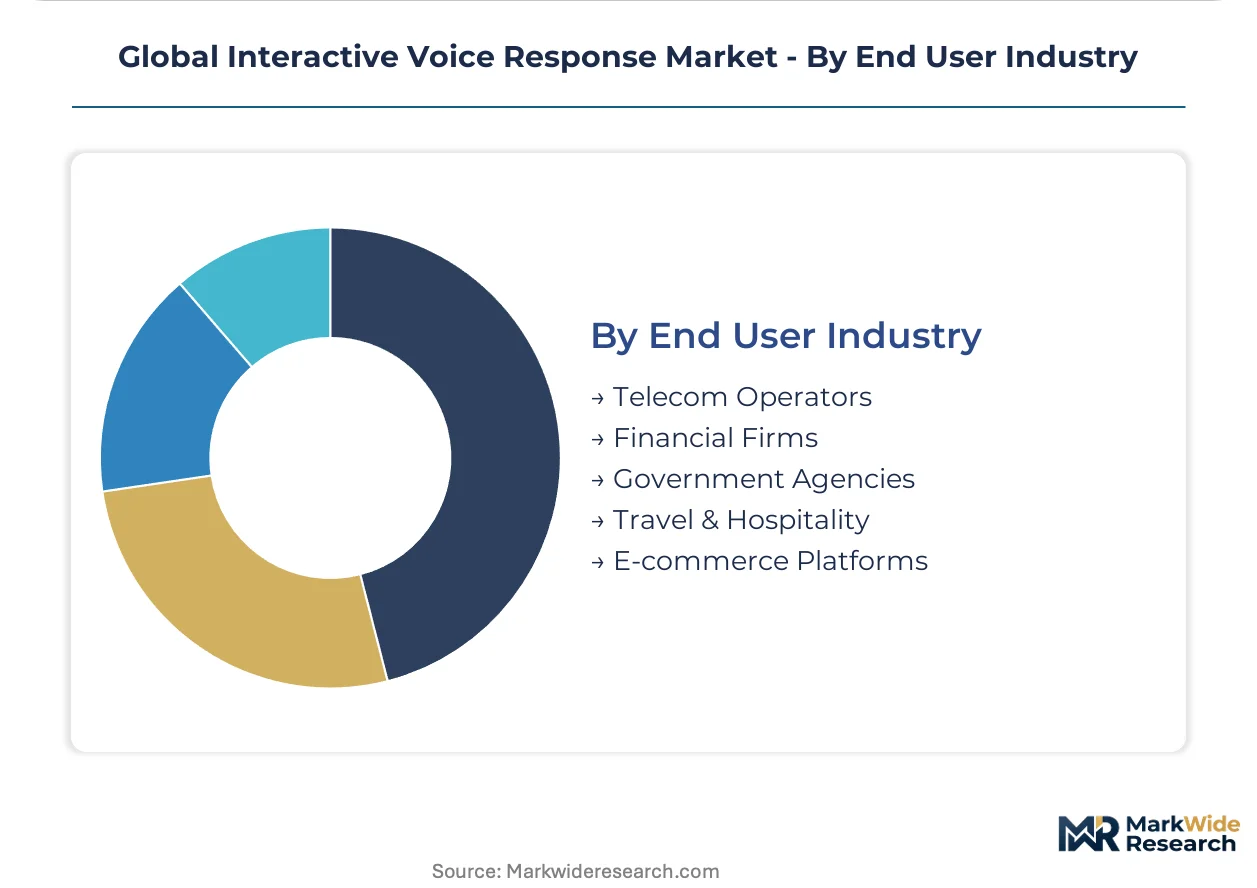
End User Industry:
Procurement sophistication ranges from standardized RFP processes in government to bespoke engineering engagements with tier-one carriers.
- Telecom Operators:Subscriber self-service for plan changes, billing disputes, and network troubleshooting drives the largest absolute seat counts. Indian operators under BIS technical standards are modernizing legacy platforms at scale.
- Financial Firms:Retail banks, insurers, and payment processors demand biometric authentication layers and algorithmic explainability features. EU AI Act risk-classification requirements are restructuring vendor selection criteria across Germany and France.
- Government Agencies:Tax hotlines, benefit enrollment, and emergency notification systems prioritize accessibility compliance and multi-language support over conversational sophistication.
- Travel & Hospitality:Booking modifications, loyalty program servicing, and real-time disruption management require integration with global distribution systems and property management platforms.
- E-commerce Platforms:Order tracking, return initiation, and seller-support routing favor rapid deployment over deep customization, favoring cloud-native vendors.
Seat volume leader: Telecom Operators. Fastest compliance-driven replacement: Financial Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru's technology corridor anchors India's cloud-IVR procurement surge, while Frankfurt's banking cluster drives EU AI Act compliance spending. Enterprise migration patterns concentrate demand in three distinct regulatory zones with divergent infrastructure requirements.
United States
Financial institutions in New York and Chicago are replacing legacy on-premises systems with hybrid cloud architectures. FCC STIR/SHAKEN mandates force carriers to rebuild caller-ID verification infrastructure by 2025. Dallas-Fort Worth hosts the largest concentration of telecom operator procurement teams modernizing subscriber self-service platforms.
Germany
Frankfurt's banking district generates the deepest demand for auditable algorithmic decision-making systems. BaFin supervisory requirements and EU AI Act risk-classification rules compel retail banks to document IVR logic for credit workflows. Munich's insurance cluster is consolidating vendor relationships around explainable AI platforms.
India
TRAI quality-of-service benchmarks and BIS technical standards accelerate cloud-IVR adoption among Mumbai and Delhi telecom operators. Domestic banks under RBI automation guidelines are expanding voice-based balance inquiry and fund transfer capabilities. Hyderabad's technology parks host scaling engineering centers for conversational AI development.
United Kingdom
London's financial services firms are restructuring procurement specifications around post-Brexit data residency requirements. FCA consumer duty rules pressure insurers to demonstrate fair treatment in automated customer journeys. Manchester's emerging fintech cluster favors rapid-deployment cloud-native vendors over legacy integrators.
Japan
Tokyo's megabanks are piloting biometric voiceprint authentication for high-value transaction verification. METI digital transformation subsidies reduce payback periods for mid-market enterprises modernizing contact centers. Osaka's manufacturing conglomerates are integrating IVR with supply-chain notification systems for distributor networks.
Global Interactive Voice Response Market Competitive Landscape
Premium-margin players sit above commodity-margin players across deployment complexity and conversational AI sophistication. The market structures into three tiers: unified communications incumbents with hybrid installation bases, cloud-native programmable voice specialists, and conversational AI layer providers. Consolidation pressure intensifies as enterprise buyers consolidate vendor relationships. Strategic moves center on API ecosystem expansion and vertical-specific compliance certifications.
Within the unified communications tier, Cisco Systems Inc. and Avaya Inc. occupy positions anchored by installed-base migration contracts. Cloud-native infrastructure is represented by Twilio Inc., whose programmable voice APIs exemplify the API-first archetype displacing hardware-centric competitors. Nuance Communications Inc. sits within the conversational AI specialization tier, differentiating through natural-language processing layers that command pricing multiples above basic call-routing systems.
| Leading Market Players |
|---|
| Verizon Communications Inc. |
| AT&T Inc. |
| Cisco Systems Inc. |
| Twilio Inc. |
| Avaya Inc. |
| Genesys Telecommunication Laboratories Inc. |
| Nuance Communications Inc. |
| 8x8 Inc. |
| Five9 Inc. |
| Others |
Supply & Pricing Matrix
EU AI Act risk-classification mandates gate qualified supply for premium-tier IVR deployments, restricting vendor eligibility to providers with auditable algorithmic documentation and compressing pricing power among compliant cloud-native platforms serving European financial institutions.
Pricing Analysis
Outcome-based pricing anchored to live-agent deflection rates and call-resolution accuracy commands premium multiples over basic call-routing subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates conversational AI platforms with real-time analytics from commodity DTMF-menu systems and basic hosted services. Cost compression in the standard tier is intensifying because cloud-native entrants are undercutting legacy on-premises incumbents with usage-scaled models. Mid-market financial firms in India exhibit the highest price sensitivity, while German retail banks prioritize explainability features and audit trails over per-seat economics.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and India anchor hub-and-spoke delivery patterns for cloud-IVR infrastructure, with hyperscaler edge nodes reducing latency for speech recognition workloads. Software development concentrates in the United States and India, while hardware component sourcing draws from Taiwan and South Korea for voice processing chipsets. Single-source vulnerability in proprietary speech engines creates supply chain risk as enterprises face platform lock-in during hybrid architecture transitions. Distribution runs through API-first vendor marketplaces and systems integrator channels serving financial services and telecom verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with control over proprietary NLP training data and biometric voiceprint libraries emerging as the decisive downstream lever separating premium-margin platforms from commodity competitors.
For Market Incumbents: Deploy hybrid architecture migration programs to retain installed-base relationships against cloud-native challengers. Consolidate vendor partnerships around unified communications ecosystems to defend against Twilio's API-first encroachment into financial services. Accelerate certification investment for EU AI Act explainability requirements to maintain procurement eligibility among German and French retail banks.
For New Entrants and Emerging Players: TRAI quality-of-service mandates in India open a window for rapid cloud-IVR deployment among domestic telecom operators modernizing subscriber self-service platforms. Target healthcare administrative automation in the United States, where HIPAA-compliant appointment scheduling and prescription refill workflows remain underpenetrated relative to banking saturation. Lead with conversational AI specialization rather than full-stack competition to avoid direct confrontation with Cisco's hybrid dominance.
For Investors and Strategic Acquirers: Consolidation of vendor relationships by enterprise buyers is the leading indicator that platform-scale M&A will accelerate among mid-tier conversational AI specialists. Frame long-term viability around API ecosystem breadth and vertical-specific compliance certifications rather than hardware revenue streams. Monitor FCC STIR/SHAKEN implementation deadlines as the inflection signal for legacy infrastructure replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Conversational AI Platform Integration | Real-time intent classification reduces live-agent escalation in high-volume banking contact centers. |
| EU AI Act Compliance Certification | Algorithmic explainability features unlock procurement eligibility among German and French retail banks. |
| Biometric Voiceprint Authentication Launch | Integrated security layers differentiate next-generation platforms from commodity DTMF systems. |
| Healthcare Vertical Expansion | HIPAA-compliant workflows capture underpenetrated appointment scheduling and prescription refill demand. |
| API Ecosystem Partnership | Hyperscaler marketplace distribution accelerates mid-market penetration without direct sales overhead. |
Research Methodology
Independent corroboration across primary interviews with contact center operations directors, telephony procurement officers, conversational AI engineering leads, and regulatory compliance specialists underwrites the qualitative findings. Secondary validation draws from FCC robocall mitigation orders, EU AI Act implementation guidance, TRAI quality-of-service circulars, SEC 10-K disclosures from listed vendors, and hyperscaler cloud infrastructure capex reports. Bottom-up deployment modeling and top-down market sizing triangulate volume estimates across the analysis window.
Historical reference periods spanning pre-pandemic baselines through cloud-migration acceleration phases anchor the forecast framework. Segmentation dimensions modeled include deployment mode, solution sophistication tier, application workflow complexity, end-user industry regulatory intensity, and geographic adoption pattern. CAGRs derive from fitted growth curves calibrated to disclosed vendor booking trends and enterprise procurement cycle timing. Speech recognition accuracy benchmarks and live-agent escalation rate improvements serve as key technology adoption inputs.
The model assumes a particular technology adoption path; alternative pathways for generative AI-powered voice synthesis would alter the outlook if latency and cost barriers fall faster than projected. Forecasts reflect documented assumptions about regulatory enforcement timing and enterprise cloud-migration velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Desktop Virtualization Market
Digital Solutions
Global Demand Side Platforms (DSP) for Programmatic Advertising Market
Digital Solutions
North America Smart Card Market
Digital Solutions
IT Operations and Service Management (ITOSM) Market
Digital Solutions
POS Restaurant Management System Market
Digital Solutions
Document Management System Market
Digital Solutions
Germany Smart Office Market
Digital Solutions
Weather Forecasting Systems and Solutions Market
Digital Solutions
Drone Mapping Software for Agriculture Market
Digital Solutions
Cinema Point of Sale (POS) Solutions Market
Digital Solutions
Product Information Management Market
Digital Solutions
Backup-As-A-Service (Baas) Market
Digital Solutions
Voice Remote Control Market
Digital Solutions
Demand Planning Solutions Market
Digital Solutions
On-Shelf Availability Solutions Market
Digital Solutions
Service Virtualization Market