
 Utility App Market | 2026-2036
Utility App Market Size, Share, and Industry Trends Forecast 2026-2036
Utility App Market Intelligence
India's national smart grid modernization program is reshaping competitive dynamics for utility software providers. KUBRA leverages its cloud-native billing architecture to sustain large North American municipal contracts. Enerex differentiates through demand-response analytics, while Nimble Vision dominates India's sub-metering visualization segment with IoT-native dashboards.
A utility app is a purpose-built software application that interfaces with critical infrastructure systems—electricity, water, gas, or waste networks—through APIs, SCADA integrations, or AMI protocols to enable consumption monitoring, outage management, and tariff optimization. Its primary commercial purpose is reducing operational expenditure for utilities while improving billing accuracy and customer engagement. The Platform dimension shows Android deployments leading in emerging markets due to device cost structures, while iOS generates premium subscription revenue in deregulated European and North American energy markets. Monetization Model patterns reveal freemium tiers driving user acquisition among residential end users, with enterprise subscriptions capturing margin pools from business and government accounts requiring SLA-backed support.
The US FCC governs data transmission standards for utility communications infrastructure, while India's BIS mandates mobile application security certifications for public-sector deployments. The EU AI Act imposes algorithmic transparency requirements on predictive consumption forecasting tools, directly shaping R&D allocation for European-facing vendors. Stakeholders must monitor evolving interoperability mandates between legacy SCADA systems and cloud-native architectures as utilities accelerate replacement cycles.
Market Dynamics
Cloud-native billing architectures are forcing incumbent utility software vendors to rebuild core platforms, as municipal water departments and electric cooperatives demand API-first integration with AMI networks and SCADA systems.
Growth Catalysts
- Smart Metering Mandates:India's national smart grid modernization program requires AMI deployment across state electricity boards, creating immediate demand for consumption visualization platforms.
- EU AI Act Algorithmic Transparency:European utilities must document predictive consumption forecasting models, accelerating procurement of auditable analytics software.
- Seoul Metropolitan Digitization:South Korea's city-wide utility integration program is deploying unified billing and outage management interfaces across water, gas, and electric networks.
Market Restraints
- Legacy SCADA Integration Costs:Proprietary protocols from 1990s-era industrial control systems require expensive middleware development for cloud connectivity.
- Semiconductor Supply Concentration:AMI chipsets depend on concentrated East Asian foundry capacity, creating procurement bottlenecks for meter manufacturers.
- Data Localization Requirements:India's BIS mobile app security standards and EU GDPR restrictions fragment cloud hosting architectures, raising compliance overhead.
Strategic Opportunities
- Sub-Metering in Multi-Tenant Buildings:India's commercial real estate sector lacks granular consumption tracking, opening white space for IoT-native visualization tools.
- Demand-Response Aggregation:Convergence of home energy management systems with utility control platforms enables virtual power plant participation for residential users.
- Outcome-Based Service Contracts:Municipal procurement teams in Germany and France are shifting from perpetual licenses to performance-linked SaaS agreements tied to billing accuracy metrics.
Industry Challenges
- Cybersecurity Certification Timelines:India's BIS security testing protocols create 6-12 month approval delays for app updates, complicating agile development cycles.
- SCADA-Cloud Protocol Bridging:Engineering teams struggle to maintain real-time reliability when translating Modbus and DNP3 signals into REST APIs for mobile endpoints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility App Market |
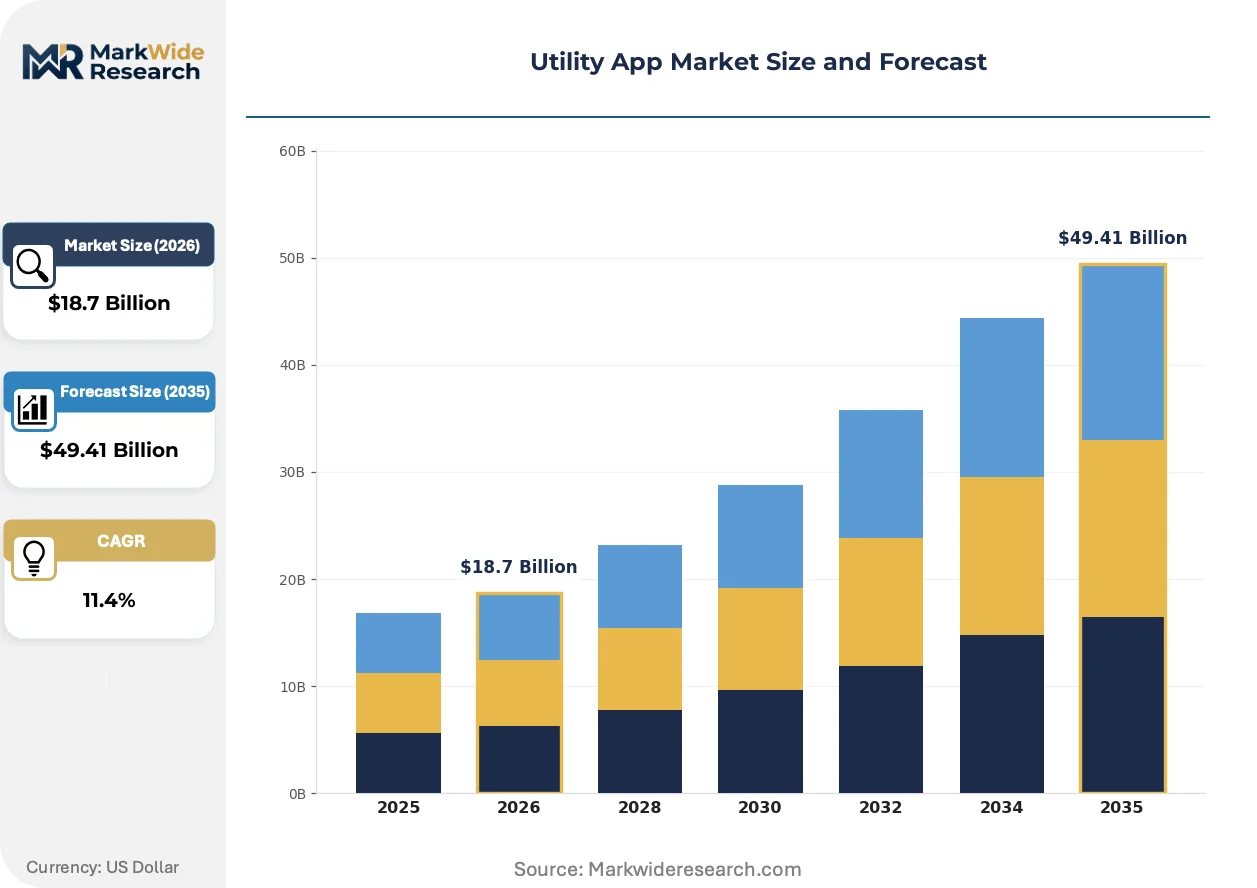
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Productivity, Communication, File Management, Payment Platform: iOS, Android, Web, Desktop End User: Individuals, Businesses, Educational Institutions, Governments Monetization Model: Subscription, Freemium, One-Time Purchase, Ad-Supported |
| Companies Covered | Attune, Enpira, KUBRA, Nimble Vision, Enerex, Energy CX, Soltera Energy, M-PAYA Energy, Bynry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility App Market Strategic Shifts & Innovations
Digital twin technology is compressing deployment timelines for utility network visualization, while regulatory pressure on algorithmic accountability is reshaping vendor R&D priorities across multiple jurisdictions.
Edge computing nodes embedded within smart meters are virtualizing traditional centralized data processing. Water utilities in California and Texas are deploying these distributed architectures to enable real-time leak detection without cloud latency. This topology is virtualizing the hub-and-spoke model that dominated AMI deployments for two decades, reducing bandwidth costs while complicating security perimeter design.
The EU AI Act's risk classification framework for predictive consumption algorithms is mandating explainability documentation for European-facing vendors. Utilities deploying machine learning-based demand forecasting must now maintain model cards and bias audit trails. German municipal energy suppliers are responding by procuring only certified "white-box" analytics platforms, disqualifying opaque neural network approaches from public tenders.
Subscription fatigue among residential ratepayers is fragmenting app engagement patterns. Freemium utility apps in deregulated Texas and UK energy markets face 40-60% annual churn as consumers switch providers frequently. Vendors are responding by unbundling premium features into usage-based microtransactions rather than fixed monthly fees, with the most visible experimentation occurring in Australia's competitive National Electricity Market.
Utility App Market Segmentation
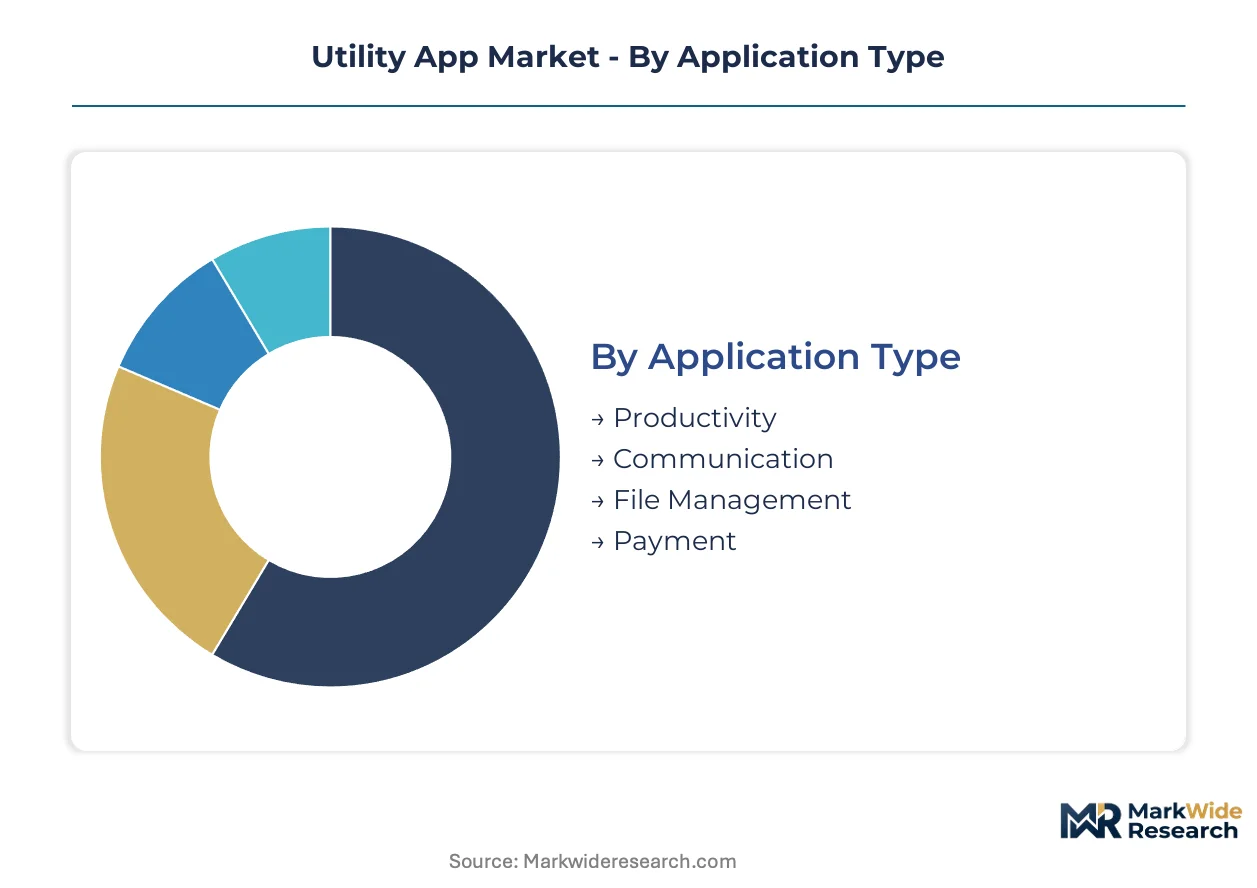
Utility app vendors configure support infrastructure and update cycles differently across segment boundaries. After-sales service intensity varies sharply between enterprise deployments requiring SLA-backed maintenance and consumer-facing downloads with minimal ongoing engagement.
Application Type:
Post-deployment service obligations diverge substantially across functional categories, with infrastructure-integrated apps demanding continuous engineering support while standalone tools require minimal intervention.
- Productivity:Task automation and workflow optimization tools dominate municipal utility back-office deployments. Seoul's metropolitan digitization program standardizes on these platforms for cross-departmental coordination, though India's BIS certification delays complicate rollout timelines.
- Communication:Real-time outage notification systems integrate with SCADA networks through proprietary middleware. German municipal energy suppliers prioritize these tools for customer retention in competitive markets, driving premium pricing for API reliability guarantees.
- File Management:Document digitization platforms serve regulatory compliance needs for EU AI Act audit trails. Demand concentrates among French and German utilities modernizing archival systems.
- Payment:Billing interface apps face shorter replacement cycles due to security patch requirements. India's state electricity boards drive volume through mandatory digital payment adoption.
By volume, Payment leads. By growth pace, Communication is ahead.
Platform:
Development cost structures and distribution economics create divergent margin profiles across deployment architectures.
- iOS:Premium subscription revenue concentrates in deregulated European and North American energy markets. Apple's stringent security review processes align with EU AI Act documentation requirements, accelerating enterprise procurement.
- Android:Lower device cost structures dominate emerging market deployments. India's national smart grid program mandates Android-first distribution for field technician applications.
- Web:Browser-based dashboards bypass app store approval bottlenecks. South Korean utilities favor these for rapid iteration on unified billing interfaces.
- Desktop:Legacy SCADA integration still relies on Windows-native clients for control room operations. Procurement concentrates among US electric cooperatives with 1990s-era infrastructure.
By installed base, Android leads. By revenue per user, iOS climbs the fastest.
End User:
Contract terms and pricing power shift dramatically across buyer categories, with government accounts imposing strictest compliance overhead.
- Individuals:Freemium tiers drive acquisition in competitive retail energy markets. Churn rates reach 40-60% annually in Texas and UK deregulated zones.
- Businesses:Multi-site energy management platforms command enterprise subscriptions. German and French procurement teams increasingly demand outcome-based SaaS contracts.
- Educational Institutions:Campus microgrid visualization tools serve sustainability reporting needs. Adoption trails commercial sectors due to budget constraints.
- Governments:Municipal water departments and state electricity boards require BIS-certified or GDPR-compliant hosting. India's security testing protocols create 6-12 month approval delays.
By contract value, Governments lead. By expansion velocity, Businesses gain share fastest.
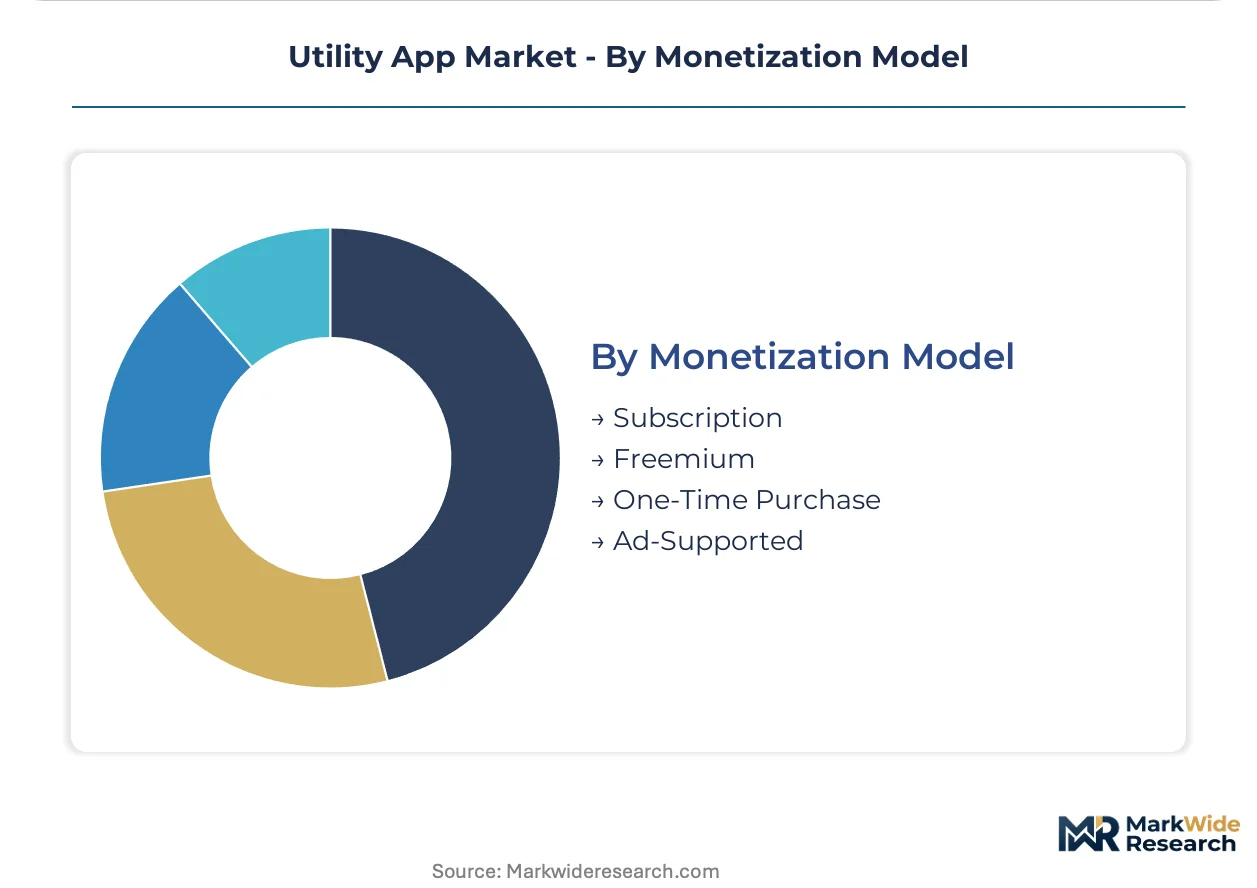
Monetization Model:
Revenue predictability and customer lifetime value vary across pricing architectures, with subscription models capturing preference in regulated utility procurement.
- Subscription:Recurring revenue underpins vendor valuations and supports continuous SCADA-cloud protocol bridging investments. German municipal suppliers favor annual contracts tied to billing accuracy metrics.
- Freemium:User acquisition strategy dominates residential retail markets. Australia's National Electricity Market experiments with unbundled microtransactions to combat churn.
- One-Time Purchase:Perpetual licenses persist in legacy control room deployments with minimal update requirements. Concentrated among US electric cooperatives with stable infrastructure.
- Ad-Supported:Data monetization faces regulatory headwinds under GDPR and India's data localization requirements. Minimal traction in utility-specific applications.
By revenue stability, Subscription leads. By user acquisition speed, Freemium shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
AMI chipset foundries cluster in Taiwan and South Korea, concentrating hardware procurement leverage for meter manufacturers. Cloud-native billing platforms diffuse more broadly, with municipal procurement patterns diverging sharply across regulatory jurisdictions.
United States
Municipal water departments and electric cooperatives drive demand for SCADA-cloud protocol bridging solutions. The FCC governs data transmission standards for utility communications infrastructure, creating compliance baselines for AMI network deployments. California and Texas utilities deploy edge-computing-enabled smart meters for real-time leak detection, virtualizing traditional hub-and-spoke data architectures.
Germany
Municipal energy suppliers procure auditable analytics platforms for demand forecasting compliance. The EU AI Act mandates explainability documentation for predictive consumption algorithms, disqualifying opaque neural network approaches from public tenders. Bavaria and North Rhine-Westphalia cluster procurement teams shifting from perpetual licenses to performance-linked SaaS agreements.
India
State electricity boards mandate AMI deployment across national smart grid modernization programs, creating immediate demand for consumption visualization platforms. BIS mobile app security certifications impose 6-12 month approval delays for field technician applications. Maharashtra and Karnataka concentrate sub-metering visualization adoption in commercial real estate lacking granular consumption tracking.
South Korea
Seoul metropolitan utilities digitization program deploys unified billing and outage management interfaces across water, gas, and electric networks. National smart city mandates accelerate API-first integration requirements for municipal departments. The Seoul Capital Area concentrates vendor activity for multi-utility platform consolidation projects.
Australia
Deregulated National Electricity Market experiments with unbundled microtransactions to combat 40-60% annual churn in freemium utility apps. The country's energy regulator shapes retail competition rules affecting customer engagement platform procurement. New South Wales and Victoria concentrate demand-response aggregation pilots converging home energy management with utility control platforms.
Utility App Market Key Industry Players
Cloud-native specialists and legacy SCADA integrators split the market along architectural fault lines. Vendor concentration remains moderate, with tier-one municipal contracts anchoring revenue stability for established players while IoT-native entrants capture sub-metering niches. Two strategic archetypes dominate: API-first platform builders targeting enterprise SaaS procurement, and hardware-coupled software vendors bundling visualization with AMI deployments. Competitive moves center on middleware development partnerships for legacy protocol bridging and outcome-based contract structuring for European municipal accounts.
Within the cloud-native tier, KUBRA and Enerex exemplify divergent specialization paths, with the former anchoring North American municipal billing contracts and the latter representing demand-response analytics positioning. Nimble Vision occupies a distinct archetype as an India-focused sub-metering visualization specialist, reflecting geographic clustering around national smart grid procurement waves. These three companies collectively illustrate how vendor positioning fragments across platform architecture choices, geographic regulatory alignment, and functional application depth rather than consolidating around unified technology stacks.
| Leading Market Players |
|---|
| Attune |
| Enpira |
| KUBRA |
| Nimble Vision |
| Enerex |
| Energy CX |
| Soltera Energy |
| M-PAYA Energy |
| Bynry |
| Others |
Cost & Logistics Intelligence
Undercapacity in Taiwan's advanced semiconductor foundries is tightening AMI chipset procurement timelines and compressing margin structures for meter manufacturers negotiating cloud-native software bundles.
Pricing Analysis
India's BIS mobile app security certification mandates dictate the pricing tier structure across deployment categories. Three-tier pricing structure across premium, standard, and economy levels separates SLA-backed enterprise subscriptions from freemium residential tiers and perpetual legacy licenses. Price differentiation rests on certification grade and after-sales service intensity. Cost compression in the mid-market tier is intensifying because municipal procurement teams demand outcome-based SaaS contracts tied to billing accuracy metrics. Government accounts show lowest price sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Single-source vulnerability in Taiwan's foundry ecosystem dominates supply chain risk calculations for AMI semiconductor procurement. Hardware concentration centers on Taiwan, South Korea, and China for chipset fabrication. Software development draws from India's engineering talent pools and Germany's industrial automation expertise. Distribution runs through systems integrators bridging legacy SCADA protocols with cloud-native architectures. Tariff exposure between the United States and China complicates cross-border component sourcing for meter manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Utility app procurement is entering a cyclical recovery phase as municipal water departments and electric cooperatives accelerate replacement cycles for 1990s-era SCADA infrastructure.
For Market Incumbents: Entrench cloud-native billing architecture advantages by deepening API-first integration partnerships with AMI network providers. Incumbent vendors must accelerate BIS certification pipeline investments to defend against six-to-twelve-month approval delays threatening agile release cycles. Vertical integration into edge-computing smart meter hardware creates defensive moats against IoT-native entrants. For New Entrants and Emerging Players: Establish a beachhead in India's sub-metering visualization segment where commercial real estate lacks granular consumption tracking infrastructure. New entrants should prioritize white-box analytics platforms for German municipal energy suppliers disqualifying opaque neural network approaches under EU AI Act mandates. Channel partnerships with systems integrators offer fastest route to legacy SCADA integration contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platform builders with entrenched North American municipal billing relationships. Long-term viability over the five-to-ten year horizon favors vendors with demonstrated SCADA-cloud protocol bridging capabilities and BIS-certified product portfolios. Watch for inflection signals in Seoul metropolitan digitization program procurement waves indicating multi-utility platform consolidation appetite.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Enables real-time AMI network connectivity for municipal water departments replacing legacy billing systems. |
| BIS Certification Investment | Accelerates approval timelines for field technician applications in India's national smart grid program. |
| Edge Computing Hardware Partnership | Virtualizes hub-and-spoke data architectures for California and Texas utilities deploying leak detection. |
| White-Box Analytics Development | Qualifies vendors for German municipal tenders under EU AI Act explainability documentation requirements. |
| Outcome-Based SaaS Structuring | Aligns vendor economics with billing accuracy metrics preferred by French and German procurement teams. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with utility software executives, municipal procurement officers, AMI network engineers, and SCADA integration specialists; and secondary validation against SEC filings, FERC infrastructure disclosures, EU regulatory filings, and national smart grid program documentation. Bottom-up segmentation modeling triangulated against top-down market sizing from customs data and hyperscaler utility vertical capex disclosures.
Forecast inputs considered deployment platform, end-user organization type, monetization model, and regional regulatory framework across the analysis window. CAGRs were derived from installed base projections for AMI networks and attach rates for visualization software. Industry-specific inputs included India's BIS certification pipeline velocity, EU AI Act implementation timelines, and Seoul metropolitan digitization procurement schedules.
Sensitivities concentrate around semiconductor supply bottlenecks, BIS approval delays, and legacy SCADA replacement cycle timing. Forecasts reflect assumptions about regulatory enforcement consistency and municipal budget allocation continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Signage Services Market
Digital Solutions
Data Cleansing Tools Market
Digital Solutions
Document Case Management (DCM) Market
Digital Solutions
Global Client Virtualization Market
Digital Solutions
Cognitive Supply Chain Market
Digital Solutions
Global Recommendation Search Engine Market
Digital Solutions
Image Recognition in Retail Market
Digital Solutions
Global Assistive Technologies for Visually Impaired Market
Digital Solutions
Switzerland ICT Market
Digital Solutions
Next Generation Search Engines Market
Digital Solutions
In-App Purchase Market
Digital Solutions
Data Monetization Market
Digital Solutions
Trade Management Software Market
Digital Solutions
Contact Tracing Application Market
Digital Solutions
Remote Integration Solutions Market
Digital Solutions
North America Product Design and Development Services Market