
 UAE Digital Twin Market | 2026-2036
UAE Digital Twin Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Digital Twin Market Insights
The capital-intensity divergence between industrial-grade simulation platforms and lightweight SaaS offerings is redrawing competitive boundaries in the UAE digital twin sector. Siemens AG leverages its automation hardware heritage to anchor large-scale manufacturing deployments across Emirates Global Aluminium and Adnoc facilities. PTC Inc. competes through its ThingWorx IoT integration layer, which sustains recurring revenue from predictive maintenance contracts in Dubai's logistics hubs. Microsoft Corp differentiates via Azure Digital Twins, extending cloud-native scalability to real estate developers building within Dubai South and Masdar City.
A digital twin constitutes a dynamic virtual replica of a physical asset, system, or process, continuously synchronized through real-time sensor data feeds and physics-based simulation engines operating at sub-second latency thresholds. Its primary commercial purpose centers on optimizing operational performance, reducing unplanned downtime, and enabling scenario testing without physical intervention. AI-driven technology segments command premium pricing due to machine learning inference requirements at the edge, while predictive maintenance applications absorb the largest share of end-user spending across the UAE's energy and aviation sectors. Cloud-based deployment models are gaining fastest among mid-market manufacturers in Sharjah's industrial corridor, though hybrid architectures dominate where data sovereignty concerns intersect with MOHAP healthcare digitization mandates.
MOHAP's electronic health record interoperability standards and the UAE's National In-Country Value program collectively shape procurement criteria, favoring vendors with local data residency and Emiratization commitments. The Telecommunications and Digital Government Regulatory Authority enforces cybersecurity certifications that filter market access for foreign platform providers. IBM Corporation navigates these compliance layers through its Dubai-based delivery centers, while Oracle Corporation controls public-sector pipelines via sovereign cloud partnerships. Stakeholders must monitor evolving TDRA data classification rules and Emirate-level sustainability disclosure requirements as these will determine which deployment architectures retain eligibility for federal infrastructure tenders.
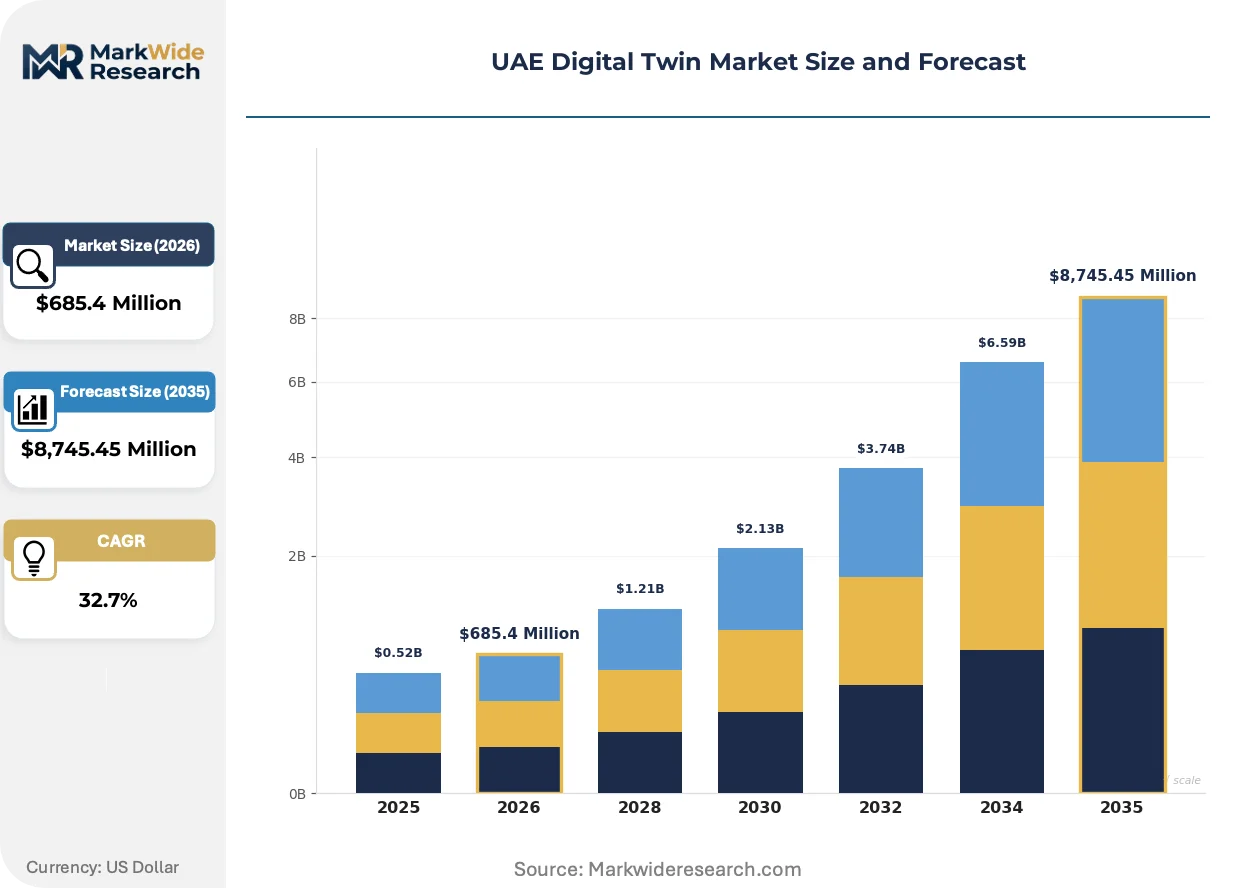
Market Dynamics
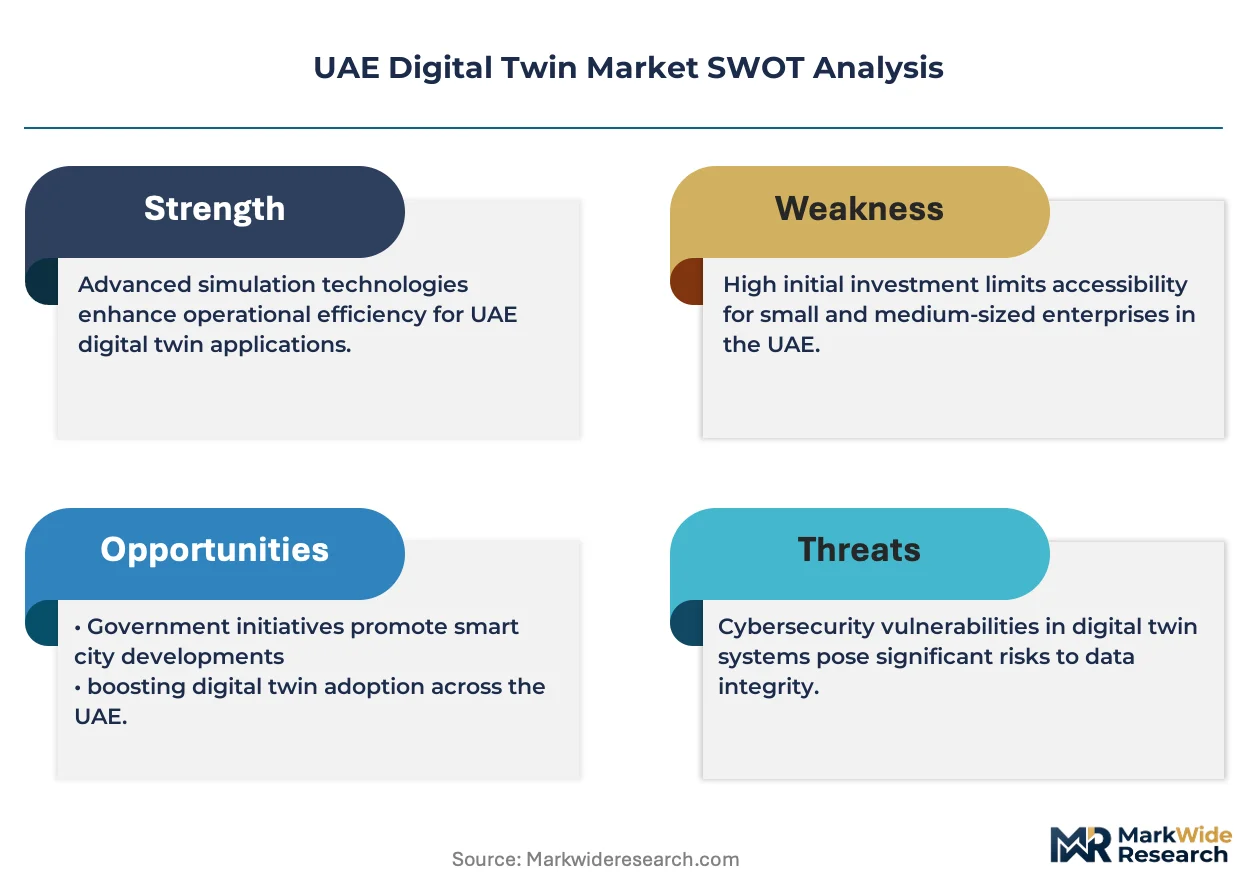
MOHAP's electronic health record interoperability standards and TDRA cybersecurity certifications are compressing vendor qualification timelines while favoring platforms with local data residency capabilities. This regulatory layering is accelerating consolidation around hybrid deployment architectures that balance edge performance with sovereign cloud compliance.
Growth Catalysts
- Smart City Mandates:Abu Dhabi's municipal infrastructure projects under the UAE government's digital transformation directives are creating anchor demand for city-scale simulation platforms across transport and utility networks.
- Industrial Free Zone Expansion:Dubai's logistics and manufacturing clusters are embedding predictive maintenance requirements into tenant lease agreements, institutionalizing digital twin adoption as operational infrastructure.
- AI Inference at Edge:Machine learning-enabled simulation engines operating at sub-second latency thresholds are unlocking real-time optimization use cases previously constrained by cloud round-trip delays.
Market Restraints
- Data Sovereignty Compliance Costs:TDRA data classification rules and MOHAP healthcare digitization mandates require redundant local infrastructure investments that inflate total cost of ownership for foreign platform providers.
- Specialized Talent Scarcity:The intersection of physics-based modeling, IoT systems integration, and Emiratization workforce requirements constrains deployment velocity across federal infrastructure tenders.
- Legacy Asset Digitization Friction:Brownfield industrial facilities in Sharjah's manufacturing corridor lack sensor density and standardized data protocols, forcing expensive retrofitting before twin synchronization becomes viable.
Strategic Opportunities
- Healthcare Digitization Wave:MOHAP's interoperability standards are opening clinical workflow simulation and medical device lifecycle management as underpenetrated application areas beyond industrial use cases.
- Sustainability Disclosure Integration:Emirate-level carbon reporting requirements are positioning digital twins as mandatory infrastructure for real-time emissions monitoring and scenario-based reduction planning.
- SME Manufacturing Adoption:Mid-market producers in Sharjah's industrial corridor represent a greenfield segment where cloud-native SaaS delivery models can bypass the capital intensity barrier of enterprise-grade platforms.
Industry Challenges
- Cross-Domain Integration Complexity:Synchronizing building information modeling, IoT sensor streams, and enterprise asset management systems requires scarce systems integration capabilities that extend implementation timelines.
- Emiratization Workforce Requirements:Federal procurement criteria mandate local staffing ratios that conflict with the specialized skill profiles required for physics-based simulation and edge AI deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Digital Twin Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $8,745.45 Million |
| CAGR (2026 – 2036) | 32.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud-Based, Edge Computing, IoT Integration, AI-Driven End User: Manufacturing, Healthcare, Automotive, Real Estate Application: Urban Planning, Asset Management, Predictive Maintenance, Facility Management Deployment: On-Premise, Hybrid, Public Cloud, Private Cloud |
| Companies Covered | Siemens AG, PTC Inc., Ansys Inc, Autodesk Inc, IBM Corporation, Microsoft Corp, Dassault Systemes SE, Oracle Corporation, GE Aerospace, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Digital Twin Market Trends and Innovations
Generative AI is compressing model development cycles while physics-informed neural networks are narrowing the fidelity gap between data-driven approximations and first-principles simulation. These converging capabilities are redefining performance benchmarks across the vendor landscape.
Physics-informed machine learning architectures are displacing traditional finite element analysis in thermal and structural simulation workloads. Emirates Global Aluminium and Adnoc facilities are piloting these hybrid models for real-time process optimization, collapsing model calibration timelines from months to days while maintaining certifiable accuracy margins.
TDRA's cybersecurity certification framework is filtering market access through mandatory penetration testing and data residency validation. Foreign platform providers must establish Dubai-based delivery centers and sovereign cloud partnerships to retain eligibility for federal tenders, reshaping competitive positioning around compliance infrastructure rather than feature differentiation alone.
Asset-as-a-service contracting is displacing perpetual license sales in Dubai South and Masdar City real estate developments. Developers now procure digital twin capabilities through long-term operational contracts where vendors retain platform ownership and monetize through performance-linked fees, transferring capex risk and aligning vendor incentives with sustained operational outcomes.
UAE Digital Twin Market Segmentation
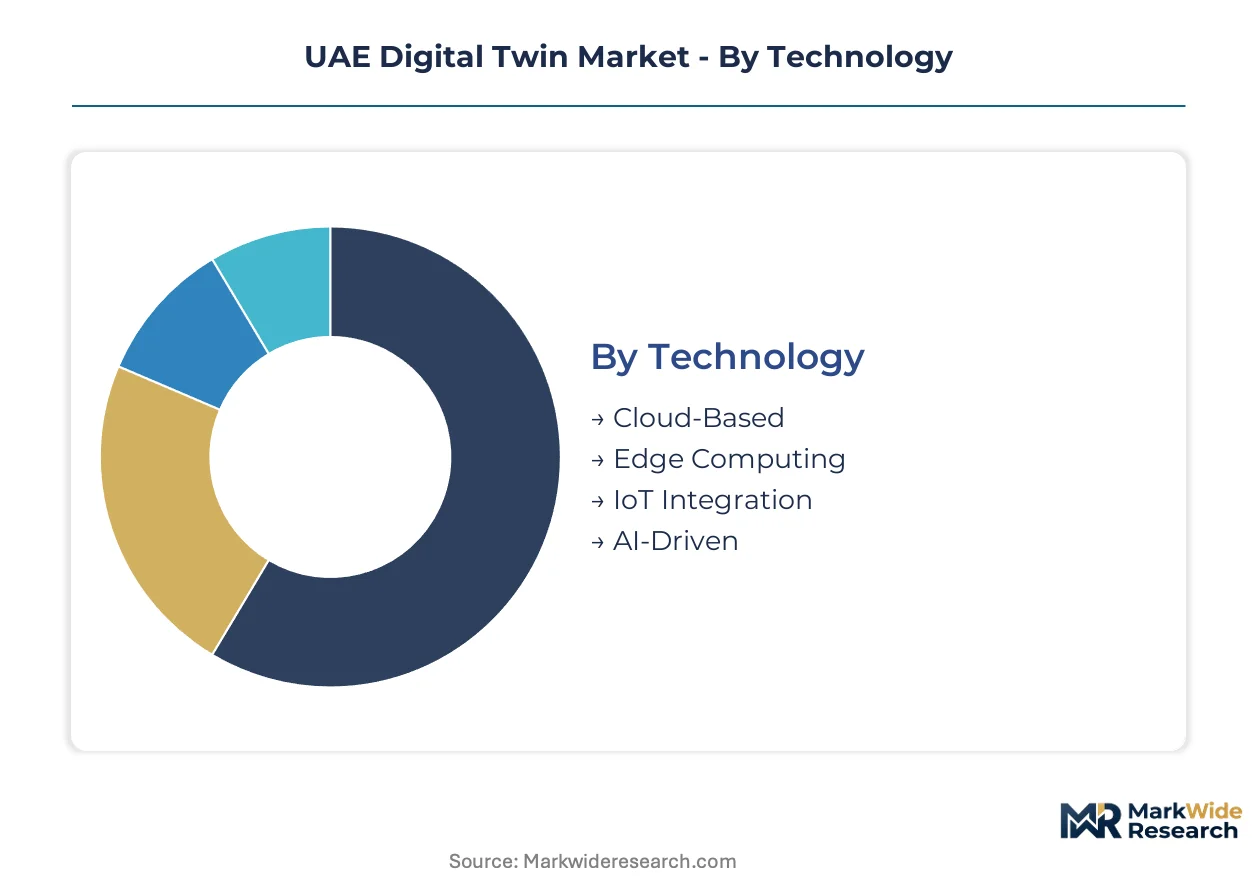
Digital twin architectures in the UAE fragment across technology maturity, regulatory exposure, and asset complexity. Segmentation reveals where capital deployment concentrates versus where cloud-native delivery models bypass infrastructure barriers.
Technology:
Geographic spread varies sharply: AI-Driven and Edge Computing segments serve domestic industrial automation mandates, while Cloud-Based platforms target export-oriented logistics and real estate developments seeking remote accessibility.
- AI-Driven:Machine learning inference engines operating at sub-second latency enable real-time process optimization. Demand concentrates in Adnoc facilities and Emirates Global Aluminium smelters where predictive accuracy directly impacts energy efficiency. MOHAP's healthcare digitization mandates are accelerating clinical workflow simulation adoption.
- Edge Computing:Localized processing architectures synchronize physical assets without cloud round-trip delays. Sharjah's industrial corridor manufacturers prioritize these deployments where connectivity intermittency threatens operational continuity. TDRA data classification rules favor edge localization for sensitive industrial telemetry.
- IoT Integration:Sensor-to-platform pipelines standardizing heterogeneous device protocols.
- Cloud-Based:Scalable SaaS delivery models reducing upfront capital requirements for mid-market manufacturers.
AI-Driven holds the largest share; momentum sits with Edge Computing.
End User:
Cost tier stratification separates sovereign-funded infrastructure from private capital deployment, with federal mandates driving premium platform investment in Healthcare and Manufacturing while Real Estate operates on performance-linked contracting models.
- Manufacturing:Industrial-grade simulation platforms integrating with legacy SCADA systems and brownfield sensor retrofits. Dubai's logistics hubs and Sharjah's manufacturing corridor anchor demand through predictive maintenance requirements embedded in tenant lease agreements.
- Healthcare:Clinical workflow simulation and medical device lifecycle management platforms. MOHAP's electronic health record interoperability standards and data sovereignty requirements favor hybrid architectures with local data residency.
- Automotive:Supply chain visibility and quality assurance simulation for assembly and aftermarket operations.
- Real Estate:Building information modeling integration for Dubai South and Masdar City developments.
Manufacturing captures dominant procurement volume; Healthcare demonstrates steepest expansion trajectory.
Application:
Application maturity correlates with sensor infrastructure density, separating greenfield installations from retrofit-dependent deployments where legacy asset digitization friction extends implementation timelines.
- Predictive Maintenance:Condition-based monitoring systems reducing unplanned downtime through anomaly detection algorithms. Abu Dhabi's municipal infrastructure and Adnoc facilities institutionalize these capabilities as operational infrastructure rather than discretionary technology spend.
- Urban Planning:City-scale simulation platforms modeling transport network optimization and utility load distribution. Federal smart city mandates under UAE digital transformation directives create anchor demand for multi-domain integration.
- Asset Management:Lifecycle tracking and performance optimization for capital-intensive equipment portfolios.
- Facility Management:Energy optimization and space utilization simulation for commercial real estate portfolios.
Predictive Maintenance leads current deployment; Urban Planning is gaining share fastest.
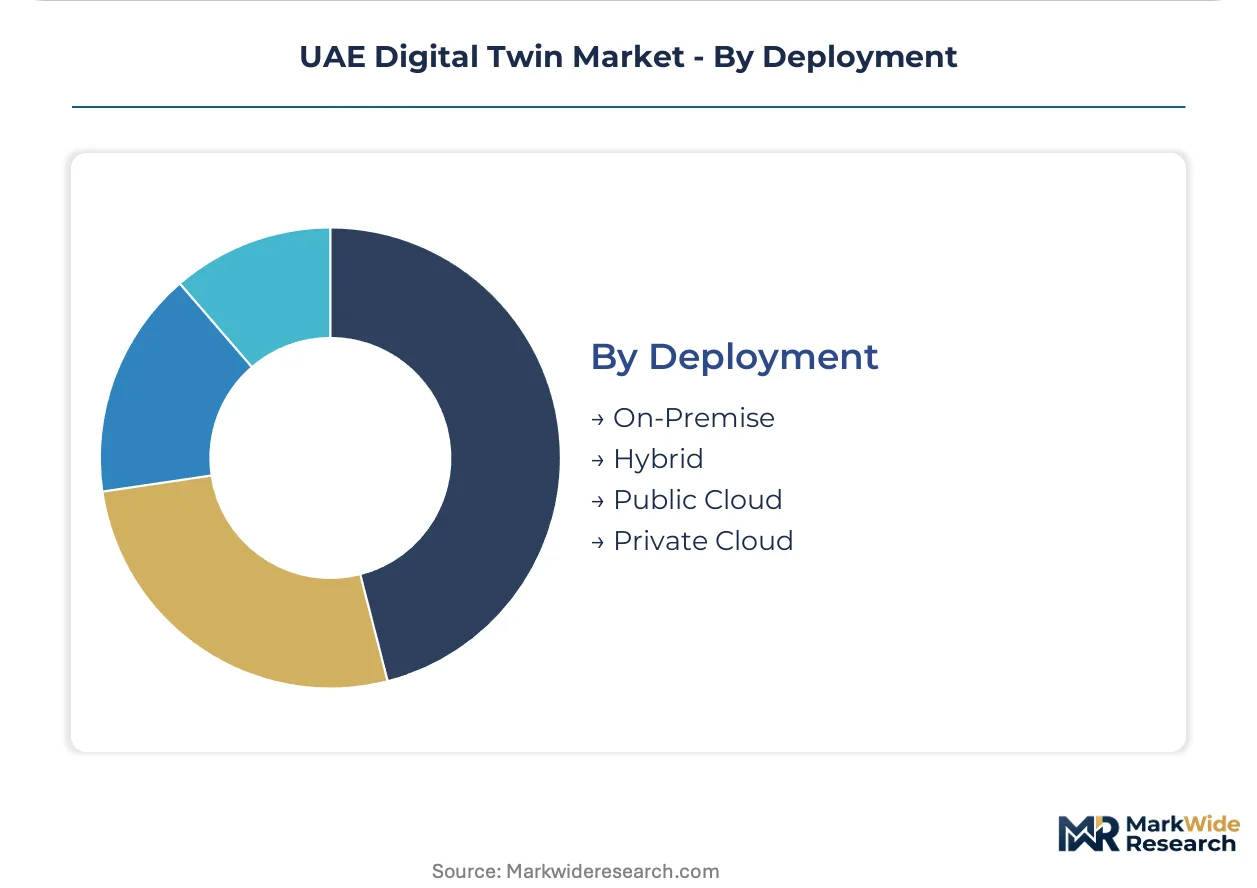
Deployment:
Customer type segmentation separates sovereign entities with data residency mandates from private enterprises prioritizing scalability, with hybrid architectures bridging compliance requirements and operational flexibility.
- Hybrid:Architectures balancing edge performance with sovereign cloud compliance through localized processing and encrypted cloud synchronization. TDRA cybersecurity certifications and MOHAP healthcare mandates effectively mandate this model for federal tenders and clinical applications.
- Private Cloud:Single-tenant infrastructure ensuring complete data sovereignty and customized security postures. Financial services and defense-adjacent industrial applications require these deployments despite elevated total cost of ownership.
- On-Premise:Fully localized infrastructure for air-gapped operational environments.
- Public Cloud:Multi-tenant SaaS delivery for non-sensitive applications prioritizing rapid scalability.
Hybrid dominates procurement eligibility; Public Cloud is climbing the fastest among SME manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across emirates. Dubai's private developers prioritize performance-linked contracting models that transfer capex risk to vendors. Abu Dhabi's sovereign-funded infrastructure projects absorb premium platform costs where federal mandates override budget constraints.
Dubai
Real estate developers at Dubai South and Masdar City drive asset-as-a-service procurement models. TDRA cybersecurity certifications filter vendor eligibility through mandatory penetration testing. Logistics hubs in Jebel Ali embed predictive maintenance requirements into tenant lease agreements.
Abu Dhabi
Adnoc facilities and Emirates Global Aluminium smelters anchor industrial-grade simulation demand. MOHAP's electronic health record interoperability standards accelerate clinical workflow digitization. Smart city infrastructure projects under federal digital transformation directives create city-scale simulation procurement.
Sharjah
Mid-market manufacturers in Sharjah's industrial corridor represent greenfield cloud-native adoption. Brownfield facilities face sensor retrofit costs that delay twin synchronization viability. Edge computing deployments prioritize localized processing where connectivity intermittency threatens operational continuity.
Northern Emirates
Ras Al Khaimah and Fujairah industrial zones lag in sensor density and standardized data protocols. Federal infrastructure tenders in these emirates apply Emiratization workforce requirements that constrain deployment velocity. Hybrid deployment architectures balance compliance mandates with operational flexibility.
UAE Digital Twin Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in the UAE digital twin sector. Industrial automation heritage defines the premium platform tier, while cloud-native delivery models capture mid-market price points. Strategic archetypes include automation-hardware incumbents, IoT integration specialists, and hyperscale cloud providers. Competitive moves center on sovereign cloud partnerships and local delivery center establishment to satisfy TDRA data residency requirements.
Within the automation-hardware tier, Siemens AG anchors large-scale manufacturing deployments through its established presence in Emirates Global Aluminium and Adnoc facilities. PTC Inc. occupies a position in IoT-centric predictive maintenance, while Microsoft Corp exemplifies the cloud-native scale vector through Azure Digital Twins serving real estate developments in Dubai South and Masdar City.
| Leading Market Players |
|---|
| Siemens AG |
| PTC Inc. |
| Ansys Inc |
| Autodesk Inc |
| IBM Corporation |
| Microsoft Corp |
| Dassault Systemes SE |
| Oracle Corporation |
| GE Aerospace |
| Others |
Pricing and Supply Chain Analysis
TDRA cybersecurity certifications and MOHAP data residency mandates simultaneously gate vendor qualification and stratify pricing power across deployment tiers. Foreign platform providers absorb redundant local infrastructure costs to retain federal tender eligibility, while hybrid architecture premiums reflect sovereign cloud compliance overhead.
Pricing Analysis
Recurring service contracts and performance-linked operational fees now drive lifetime value beyond initial platform licensing. Asset-as-a-service models dominate Dubai South and Masdar City real estate developments, transferring capex risk to vendors through long-term operational agreements. Price differentiation stems from edge AI inference capabilities and TDRA certification tier, with mid-market manufacturers in Sharjah's industrial corridor exhibiting highest price sensitivity due to SaaS-delivered alternatives. Cost compression in cloud-native tiers intensifies as Microsoft Azure and Oracle sovereign cloud partnerships expand regional capacity.
Supply Chain Analysis
Jebel Ali port congestion and Red Sea container routing disruptions elevate inbound logistics costs for industrial automation hardware sourced from Germany, USA, and Japan. Physics-based simulation engines and edge computing hardware draw from Taiwanese semiconductor fabrication and South Korean memory module production. Single-source vulnerability concentrates in specialized GPU accelerators for AI-driven inference workloads. Distribution runs through Dubai-based delivery centers established by IBM and Oracle to satisfy TDRA data residency validation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance service contracts and clinical workflow simulation subscriptions expand faster than hardware licensing, reframing the UAE digital twin sector as a service-attach opportunity. Recurring revenue layers now command premium valuations over perpetual license sales.
For Market Incumbents: Shield installed base relationships through sovereign cloud partnerships and local delivery center expansion. Siemens AG and PTC Inc. face margin pressure from hyperscaler SaaS entrants targeting mid-market manufacturers. Prioritize certification investment in TDRA cybersecurity tiers and MOHAP healthcare interoperability standards to maintain federal tender eligibility. For New Entrants and Emerging Players: Anchor in Sharjah's industrial corridor where brownfield sensor retrofit demand outpaces incumbent service capacity. Mid-market manufacturers represent the most penetrable segment given cloud-native SaaS delivery bypasses capital intensity barriers. Pursue channel partnerships with regional systems integrators possessing Emiratization-compliant workforce ratios. For Investors and Strategic Acquirers: TDRA's evolving data classification rules reshape the acquisition landscape toward compliance infrastructure over feature differentiation. Long-term viability centers on platforms with established sovereign cloud partnerships and Dubai-based operational presence. Target specialists in physics-informed machine learning and edge AI deployment. Monitor Emiratization workforce mandate enforcement as inflection indicator for deployment velocity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Oracle's Dubai data center expansion satisfies TDRA residency requirements for federal healthcare tenders. |
| Edge AI Platform Integration | Emirates Global Aluminium pilots hybrid models collapsing calibration timelines from months to days. |
| Asset-as-a-Service Contracting | Masdar City developers procure digital twin capabilities through performance-linked operational agreements. |
| Healthcare Interoperability Certification | MOHAP's electronic health record standards open clinical workflow simulation to qualified vendors. |
| Emiratization Workforce Development | IBM's Dubai delivery center addresses federal procurement staffing ratio mandates. |
Research Methodology
Two parallel data streams informed the analysis: structured conversations with digital twin platform engineers, federal procurement officers, healthcare IT directors, and industrial automation specialists; and secondary validation through TDRA regulatory filings, MOHAP interoperability standards documentation, SEC 10-K disclosures from listed vendors, and UAE National In-Country Value program reports. Bottom-up deployment estimates triangulated against top-down market sizing across technology segments.
Across the projection horizon, the analytical framework modeled technology type, end-user industry, application maturity, and deployment architecture complexity. CAGRs derived from segment-level growth trajectories weighted by federal mandate intensity and private capital deployment patterns. Forecast inputs incorporated sensor infrastructure density benchmarks and Emiratization workforce constraint elasticity.
Underlying assumptions cover sovereign cloud capacity expansion and TDRA certification timeline stability, with deviation risk concentrated in healthcare digitization mandate acceleration and Red Sea logistics disruption persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Harbor Management Software Market
Digital Solutions
End-User Computing (EUC) Market
Digital Solutions
Digital Manufacturing Market
Digital Solutions
Germany Digital Twin Market
Digital Solutions
Online Recruitment Market
Digital Solutions
Digital Business Support System Market
Digital Solutions
Ediscovery Solution Market
Digital Solutions
Global B2B Buyer Intent Data Tools Market
Digital Solutions
Smart Dictation Systems Market
Digital Solutions
Next Generation OSS and BSS Market
Digital Solutions
Global Advocacy Software Market
Digital Solutions
Asia-Pacific Route Optimization Software Market
Digital Solutions
Global Dock and Yard Management System Market
Digital Solutions
Demand Signal Repository Solutions Market
Digital Solutions
Demand Planning Solutions Market
Digital Solutions
Revenue Management Software Market