
 Hiking Apps Market | 2026-2036
Hiking Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Hiking Apps Market Insights
Silicon Valley's mobile development ecosystem is pivoting toward offline-first architectures for wilderness connectivity gaps. AllTrails leverages its trail database scale to sustain subscriber retention across North American national parks. Gaia GPS anchors its position through specialized topographic layering for backcountry navigation. Komoot dominates European route optimization with granular surface-type data for cyclists and hikers.
Hiking apps constitute location-based mobile software that renders topographic vector maps, GPS waypoint logging, and elevation profiling across variable terrain with offline raster tile caching for signal-dead zones. Their commercial purpose centers on reducing search-and-rescue incidents while enabling self-guided recreation in remote jurisdictions. Navigation app types lead revenue generation due to mandatory offline functionality for safety compliance, while freemium subscription models capture the widest user base through tiered feature unlocking. Fitness tracking segments show the fastest structural expansion as wearable device Bluetooth integration deepens.
FCC Part 15 rules govern GPS receiver emissions in US-market devices, while EU GDPR frameworks restrict location data retention policies for apps serving European trekkers. ISO 19115 geospatial metadata standards increasingly influence how trail apps structure open-data interoperability with national mapping agencies. Stakeholders must monitor evolving wilderness-area digital access policies as land managers balance conservation mandates against visitor safety obligations.
Market Dynamics
The hiking apps market pivots on offline-first architecture adoption as wilderness connectivity gaps render cloud-dependent navigation unreliable. GPS chipset efficiency gains in wearables compress battery drain during multi-day treks, reshaping hardware-software integration requirements.
Growth Catalysts
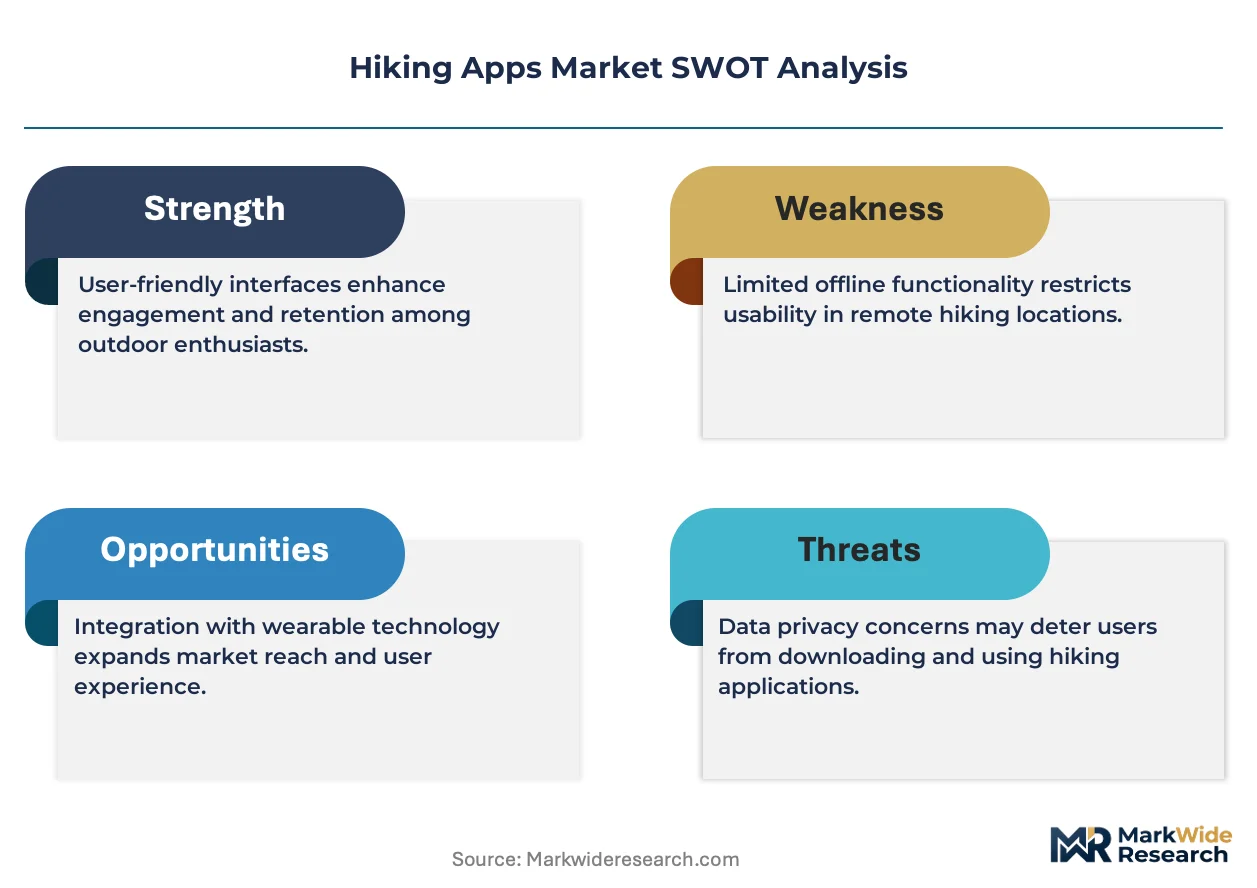
- GDPR-compliant data frameworks:EU location data retention policies create competitive moats for apps investing in privacy-by-design infrastructure. Swiss outdoor tourism boards now mandate digital trail mapping for protected alpine zones.
- Wearable Bluetooth integration:Fitness tracking segments expand structurally as heart rate and elevation data sync automatically with navigation platforms. Garmin and Apple Watch APIs deepen ecosystem lock-in.
- Bavarian demand clusters:Germany's Black Forest regions generate concentrated user acquisition for route-optimization tools with granular surface-type data. Komoot's localization investments capture this geography.
Market Restraints
- Lithium-ion cell volatility:Wearable device battery chemistry costs fluctuate with cobalt and nickel spot markets. Multi-day trekkers face replacement cycle uncertainty.
- FCC Part 15 compliance costs:GPS receiver emission testing for US-market devices adds certification overhead. Small developers lack in-house electromagnetic compatibility labs.
- Satellite imagery licensing:Topographic raster tile providers concentrate in US and European geospatial agencies. Royalty structures constrain margin expansion for offline-caching features.
Strategic Opportunities
- India's Himalayan corridor:Uttarakhand and Himachal Pradesh trekking routes lack digitized trail networks. BIS standards for outdoor safety devices create regulatory alignment pathways.
- ISO 19115 metadata interoperability:Open-data standards enable direct API integration with national mapping agencies. France's IGN and Germany's BKG already publish compliant vector datasets.
- Augmented reality waypoint overlay:Camera-based navigation converges with GPS positioning for cliff-face and dense canopy environments. Hardware-software bundles target technical climbers.
Industry Challenges
- Cartographic talent scarcity:Vector tile optimization for variable terrain requires specialized geospatial engineering skills. Universities produce fewer graduates in computational geography than platform demand requires.
- Search-and-rescue liability exposure:App publishers face jurisdictional uncertainty when navigation errors trigger emergency response. Alpine rescue coordination centers in Austria and Switzerland dispute fault allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hiking Apps Market |
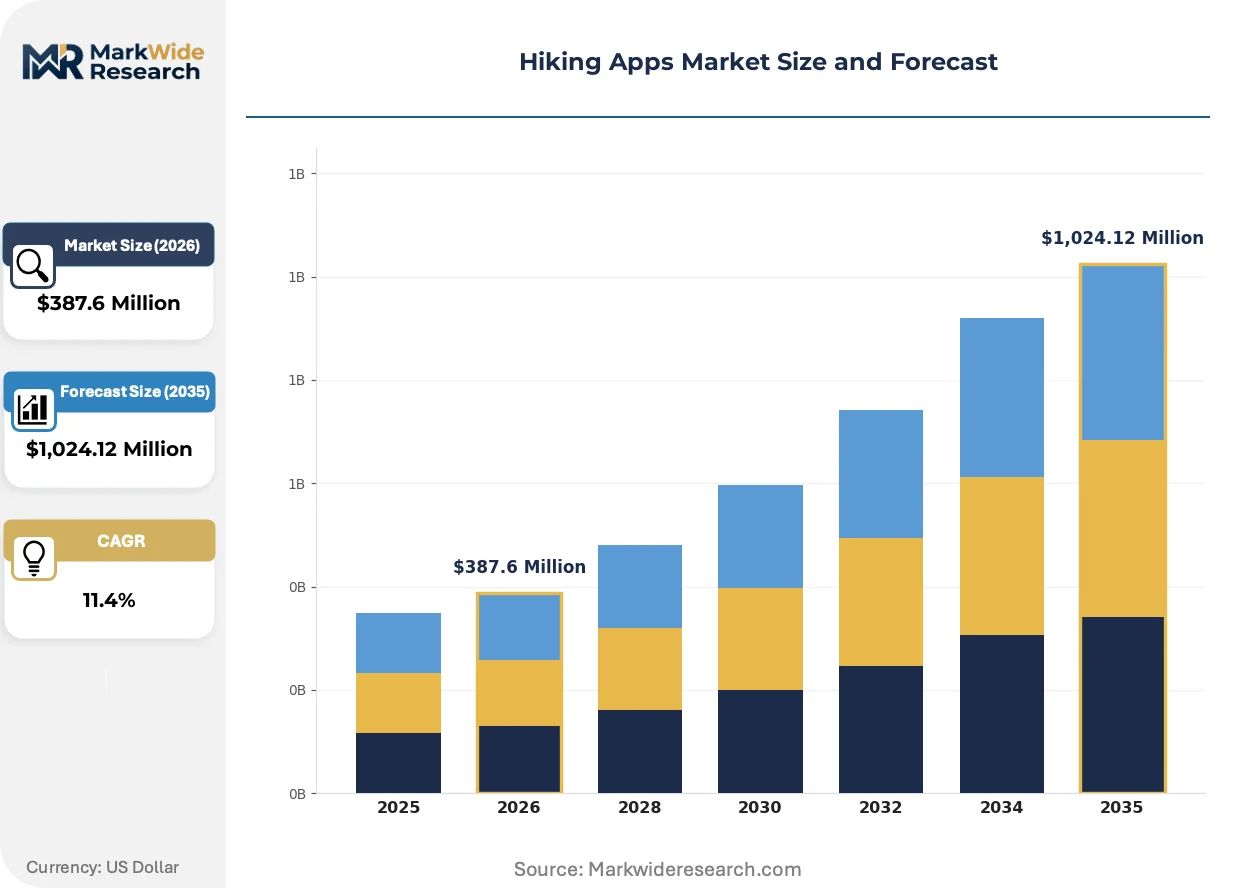
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | App Type: Navigation, Fitness Tracking, Trail Discovery, Safety Alerts User Experience: Beginner, Intermediate, Advanced, Family Operating System: iOS, Android, Windows, Cross-Platform Subscription Model: Freemium, Monthly Subscription, One-Time Purchase, Donation-Based |
| Companies Covered | Recreational Equipment, ViewRanger, AllTrails, Avenza Maps, Strava, Gaia GPS, Spyglass, OutdoorActive, Komoot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hiking Apps Market Trends and Innovations
Mesh networking protocols and federated data architectures are redistributing navigation authority away from centralized cloud platforms. Wilderness safety mandates accelerate demand for infrastructure-independent positioning.
Peer-to-peer trail condition reporting is decentralizing route quality assessment. Weekend hikers in Colorado's Front Range and Washington's Cascade corridor upload real-time water source and washout data via Bluetooth Low Energy. This crowdsourced intelligence compresses the information advantage previously held by professional guide services.
EU GDPR Article 17 right-to-erasure provisions are forcing location history retention redesigns. Hiking apps serving European trekkers must implement automated data purging workflows. Swissmedic-aligned health data frameworks in Switzerland add biometric storage restrictions for fitness-integrated platforms.
Subscription unbundling is fragmenting the revenue stack. Day-hikers in California's Sierra Nevada purchase single-route unlocks rather than annual commitments. This consumption-pattern shift pressures lifetime value calculations and forces dynamic pricing experimentation across seasonal demand peaks.
Hiking Apps Market Segmentation
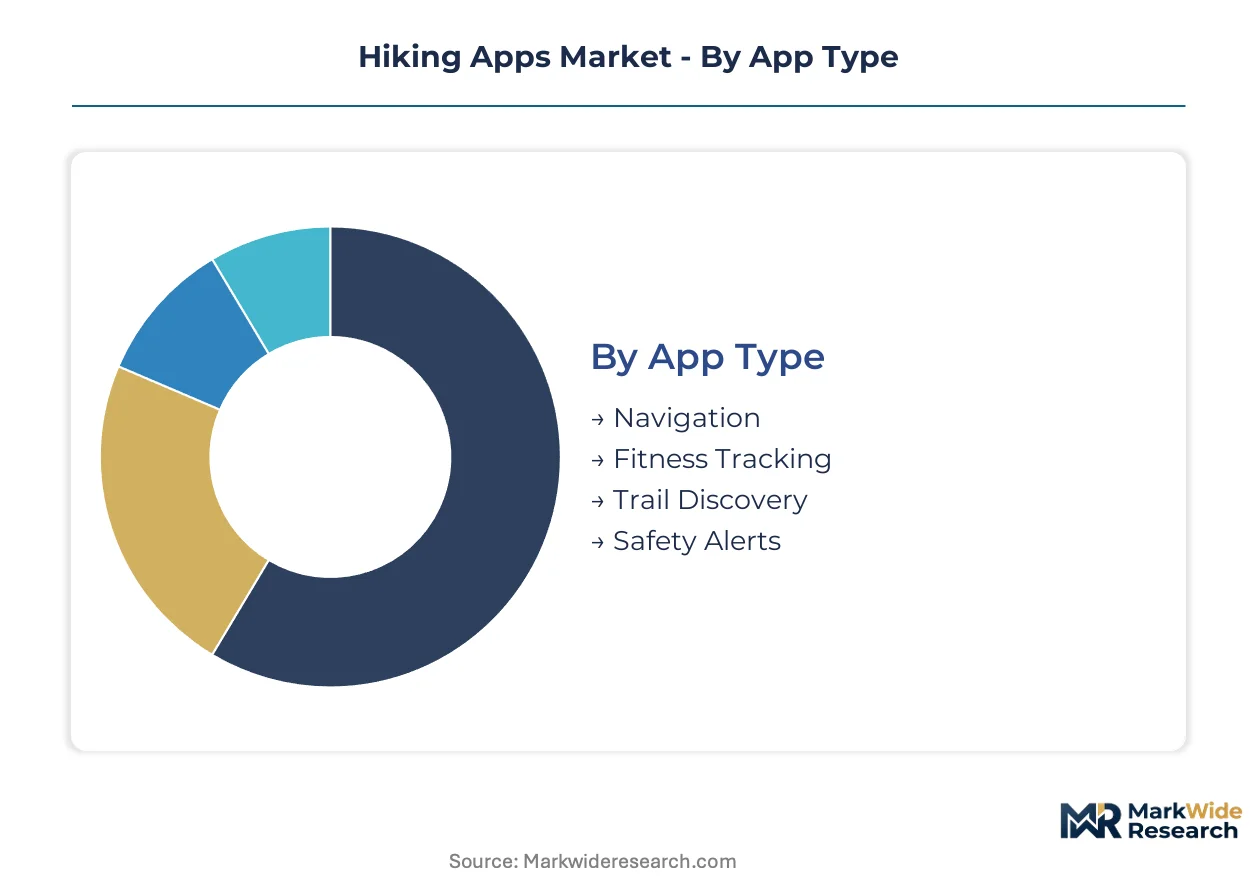
Segmentation in hiking apps determines both regulatory exposure and monetization architecture. Offline functionality requirements and data retention rules create divergent compliance burdens across categories.
App Type:
FCC Part 15 governs GPS receiver emissions for navigation-focused segments, while GDPR Article 17 shapes data handling for safety-alert platforms serving European users.
- Navigation:Vector-based topographic rendering with mandatory offline raster tile caching for signal-dead zones. Swiss outdoor tourism boards mandate this functionality for protected alpine zones, creating certification gateways for entrants.
- Fitness Tracking:Bluetooth-enabled wearable integration capturing heart rate and elevation data. Germany's Bavarian region generates concentrated demand as Komoot's surface-type granularity attracts multi-day trekkers.
- Trail Discovery:Crowdsourced route databases with peer-to-peer condition reporting.
- Safety Alerts:Automated emergency beacon integration with search-and-rescue coordination protocols.
Leading the category by volume: Navigation. Growing fastest: Fitness Tracking.
User Experience:
Skill-based tiers correlate directly with price sensitivity and feature depth expectations, reshaping subscription model viability.
- Advanced:Technical waypoint layering, augmented reality overlays, and ISO 19115-compliant metadata exchange with national mapping agencies. France's IGN and Germany's BKG vector datasets enable this segment's precision requirements.
- Family:Simplified interfaces with geofencing and group tracking for multi-generational trek safety. Weekend hikers in Colorado's Front Range drive acquisition here through seasonal demand spikes.
- Beginner:Guided route selection with automated difficulty matching.
- Intermediate:Progressive feature unlocking as user proficiency develops.
Advanced users command premium pricing. Family segment expands most quickly as outdoor tourism boards mandate digital safety infrastructure.
Operating System:
Platform choice determines hardware-software integration depth and wearable ecosystem compatibility.
- iOS:Tight Apple Watch API integration with optimized battery management for multi-day treks. Garmin's wearable ecosystem lock-in reinforces this segment's hardware-software bundles.
- Android:Fragmented device compatibility requiring broader GPS chipset optimization. India's Himalayan corridor developers target this platform for Uttarakhand and Himachal Pradesh digitization projects.
- Windows:Desktop companion applications for pre-trip route planning.
- Cross-Platform:Unified account systems with cloud synchronization across devices.
iOS leads by revenue per user. Android climbs the fastest on emerging market penetration.
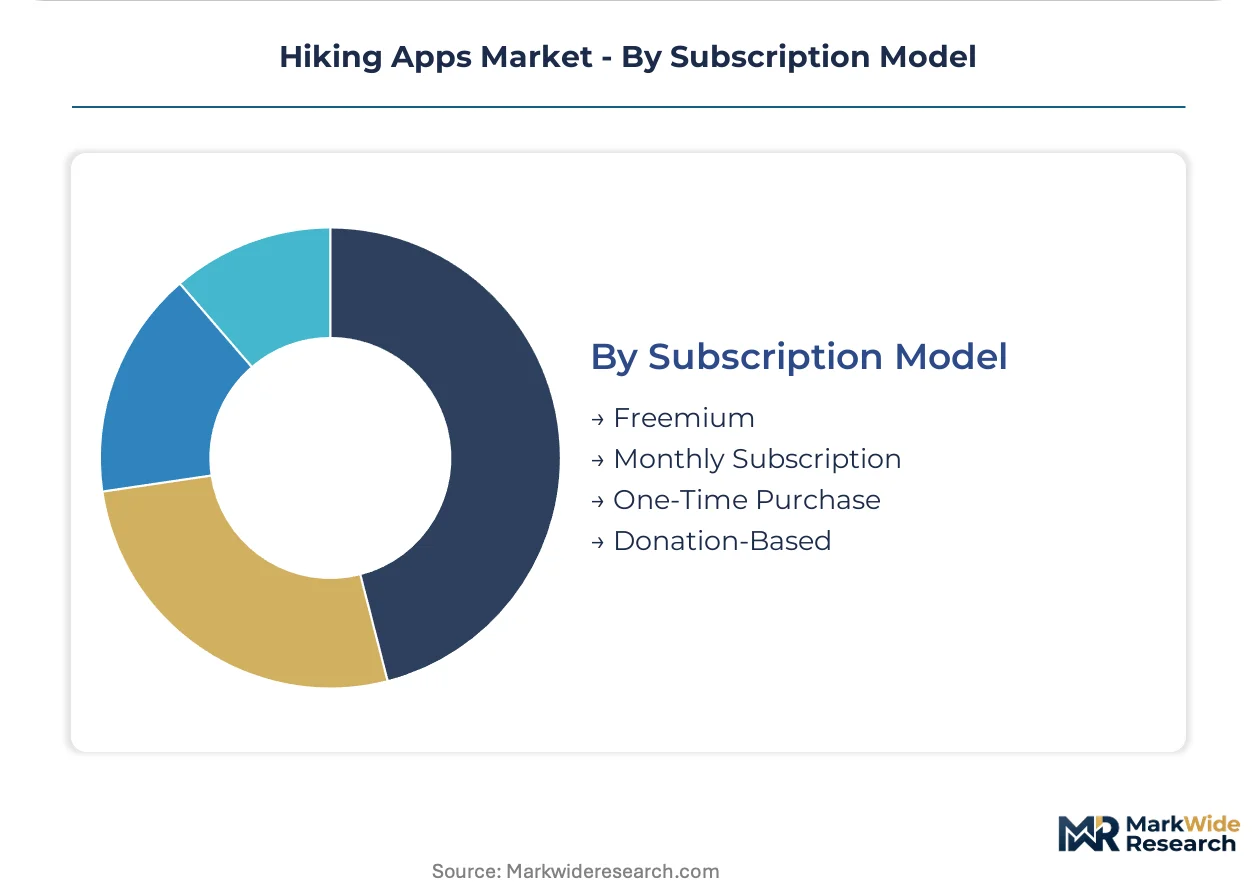
Subscription Model:
Monetization architecture shapes customer lifetime value calculations and seasonal cash flow patterns.
- Freemium:Tiered feature unlocking with base navigation free and offline caching behind paywalls. This model captures California's Sierra Nevada day-hikers who resist annual commitments.
- Monthly Subscription:Recurring revenue with dynamic pricing experimentation across seasonal demand peaks. Washington's Cascade corridor users prefer this flexibility for weather-dependent hiking patterns.
- One-Time Purchase:Perpetual licenses with limited update guarantees.
- Donation-Based:Community-supported development with voluntary contribution tiers.
Freemium dominates user acquisition. Monthly Subscription shows steepest expansion trajectory as unbundling fragments revenue stacks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's venture capital concentration anchors software development capacity for wilderness navigation platforms. Alpine topography in Switzerland and Austria generates specialized demand for offline-first architectures. Himalayan trekking corridors in India and Nepal lack digitized infrastructure, creating greenfield deployment opportunities.
United States
National park visitation in Colorado's Front Range and Washington's Cascade corridor drives concentrated subscription demand. FCC Part 15 governs GPS receiver emissions for wearable devices entering this market. Yosemite and Zion ranger districts now require digital trail registration for backcountry permits.
Germany
Bavarian Alpine Club membership exceeds seven million, generating sustained demand for granular surface-type routing. GDPR Article 17 retention rules shape location data architecture for apps serving German trekkers. Black Forest municipalities subsidize Komoot integration for tourism board digital trail networks.
Switzerland
Swissmedic-aligned health data frameworks restrict biometric storage for fitness-integrated platforms. Outdoor tourism boards mandate digital trail mapping for protected alpine zones above 2,000 meters. Zermatt and Grindelwald rescue coordination centers dispute liability allocation for navigation-error incidents.
India
Uttarakhand and Himachal Pradesh trekking routes attract 2.3 million annual foreign visitors without digitized trail infrastructure. BIS standards for outdoor safety devices create regulatory alignment pathways for navigation hardware. Himalayan mountaineering institutes in Manali and Uttarkashi train guides on emerging GPS platforms.
France
IGN vector datasets enable ISO 19115-compliant metadata exchange for advanced waypoint layering. Auvergne-Rhône-Alpes regional government funds open-data trail digitization for GR long-distance footpaths. Chamonix guide services resist crowdsourced condition reporting that erodes professional information advantages.
Hiking Apps Market Competitive Landscape
Global majors compete with regional champions across route database scale and localization depth. The vendor base distributes between consolidated trail-data aggregators and fragmented specialty navigation tools. Three archetypes dominate: freemium platform operators, premium offline-mapping specialists, and fitness-integrated ecosystem players. Competitive moves concentrate on API partnerships with wearable manufacturers and ISO standard compliance certifications for national mapping agency integration.
Among North American platform operators, AllTrails and Gaia GPS exemplify divergent specialization strategies. AllTrails occupies a position emphasizing crowdsourced trail discovery across national park networks. Gaia GPS anchors the premium tier through topographic layering depth for backcountry navigation. European localization strength converges around Komoot, whose surface-type granularity captures German and Austrian cycling-hiking crossover demand. These three represent distinct competitive postures: scale-driven content aggregation, technical precision specialization, and regional route-optimization dominance.
| Leading Market Players |
|---|
| Recreational Equipment |
| ViewRanger |
| AllTrails |
| Avenza Maps |
| Strava |
| Gaia GPS |
| Spyglass |
| OutdoorActive |
| Komoot |
| Others |
Pricing and Supply Chain Analysis
Subscription-unbundling divergence between annual commitments and single-route unlocks reshapes both revenue architecture and content licensing negotiations. Day-hikers in California's Sierra Nevada resist recurring payments while Bavarian multi-day trekkers absorb premium tiers, forcing divergent supplier contract structures for raster tile providers.
Pricing Analysis
Warranty and liability bundling separates premium navigation tiers from economy offerings, with ISO 19115-compliant metadata exchange commanding subscription premiums. Price differentiation hinges on offline caching depth and wearable API integration quality. Pricing pressure intensifies as satellite imagery royalties concentrate among US and European geospatial agencies. Family segment buyers show highest price sensitivity; technical climbers exhibit lowest.
Supply Chain Analysis
FCC Part 15 and CE marking certification gates filter hardware-software bundle entrants from pure-play app developers. GPS chipset fabrication concentrates in Taiwan, South Korea, and USA. Lithium-ion cell chemistry draws from cobalt and nickel spot markets in DRC and Indonesia. Tariff exposure on semiconductor components poses structural risk. Distribution runs through app store platforms and direct-to-consumer wearable bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cartographic engineering talent scarcity props pricing power for platforms with in-house vector optimization capabilities, constraining supply-side expansion.
For Market Incumbents: To counter peer-to-peer trail condition reporting erosion, deepen API partnerships with Garmin and Apple Watch ecosystems. Pursue ISO 19115 certification investments for national mapping agency integration. Secure exclusive raster tile licensing from France's IGN and Germany's BKG to defend content moats. For New Entrants and Emerging Players: The premium-economy price-point gap in India's Himalayan corridor offers white-space entry. Target Uttarakhand and Himachal Pradesh trekking routes lacking digitized infrastructure. Pursue BIS standards alignment for outdoor safety device certification as go-to-market anchor. For Investors and Strategic Acquirers: Re-rating potential sits with fitness-integrated ecosystem players given wearable Bluetooth integration acceleration. Five-to-ten year viability favors platforms with proprietary vector tile engines. Watch for Swissmedic-aligned health data framework expansion as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Offline-First Architecture Investment | Swiss alpine zone mandates create certification gateways for compliant entrants. |
| Wearable API Partnership Expansion | Garmin and Apple Watch ecosystem lock-in deepens hardware-software bundles. |
| ISO 19115 Metadata Compliance | France's IGN and Germany's BKG vector datasets enable premium tier positioning. |
| GDPR-Aligned Data Infrastructure | EU Article 17 retention rules create competitive moats for privacy-by-design platforms. |
| Augmented Reality Waypoint Development | Camera-based navigation targets technical climbers in dense canopy environments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs. Primary interviews with app platform CTOs, outdoor tourism board digital officers, wearable ecosystem engineers, and national mapping agency data directors combined with FCC Part 15 submissions, EU GDPR enforcement records, and BIS standards documentation. Bottom-up user segmentation triangulated against top-down addressable market sizing.
Data-stream reconciliation across app store revenue disclosures, wearable shipment databases, and trekking permit registrations shaped the analytical framework. Segmentation dimensions modeled include app type, user experience tier, operating system, and subscription model across the projection horizon. CAGRs derived from installed base growth curves and average revenue per user trajectory. Forecast inputs incorporated GPS chipset efficiency gains and lithium-ion cell cost volatility.
Inputs from app store platforms and tourism board digitization programs were available through the study window; gaps in private trail condition reporting databases introduce uncertainty bands. Forecasts reflect assumptions on wearable adoption curves and regulatory compliance timelines. A model refresh is warranted upon material change in EU GDPR enforcement posture or Swiss alpine zone digital access policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Electrical Digital Twins Market
Digital Solutions
Online on-Demand Home Services Market
Digital Solutions
Voice Picking Headset Market
Digital Solutions
Foot Traffic and Customer Location Intelligence Solution Market
Digital Solutions
Advanced Drill Data Management Solutions Market
Digital Solutions
Remote Control Duplicators Market
Digital Solutions
Mexico Digital Showers Market
Digital Solutions
Global Industrial Design Market
Digital Solutions
AI Marketing Tool Market
Digital Solutions
Agent-Oriented Enterprise Architecture Market
Digital Solutions
Customer-To-Customer (C2C) Community Market
Digital Solutions
Germany Digital Twin Market
Digital Solutions
Product Information Management Market
Digital Solutions
Control Room Solutions Market
Digital Solutions
Utility App Market
Digital Solutions
Human Resource (HR) Technology Market