
 Global Digital Utility Market | 2026-2036
Global Digital Utility Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Utility Market Analysis
Grid-scale interoperability standards is redrawing competitive boundaries across the Global Digital Utility Market. Siemens AG leverages its hardware-software convergence to sustain dominance in substation automation. General Electric Company anchors its position through deep vertical integration into grid edge analytics. IBM Corporation differentiates via specialized AI layers for predictive asset management in transmission networks.
Digital utility infrastructure encompasses the integrated hardware, software, and communication systems that enable real-time monitoring, automated control, and data-driven optimization of electricity generation, distribution, and consumption networks, typically operating through sub-second response protocols and IEC 61850-compliant architectures. Its primary commercial purpose centers on reducing technical and non-technical losses while enabling demand-side flexibility for grid operators. Cloud deployment captures the fastest expansion as utilities migrate SCADA and advanced metering infrastructure off legacy on-premise servers. Managed services now claim the deepest margin pools as operators outsource cybersecurity and predictive maintenance rather than building captive capabilities. IoT sensors and AI analytics together form the technology backbone where vendor competition is most intense.
The US Federal Energy Regulatory Commission enforces grid reliability standards that directly shape digital investment timelines for interstate transmission operators. Europe's CSRD and GDPR impose parallel reporting and data governance obligations on utilities deploying customer-facing digital platforms. China's MIIT and dual carbon goals are accelerating domestic smart grid procurement timelines with local content requirements. Stakeholders must weigh regulatory fragmentation against platform standardization when allocating R&D budgets across jurisdictions.
Market Dynamics
Grid modernization mandates are compressing procurement cycles as municipal utilities replace legacy SCADA with IEC 61850-compliant architectures, forcing vendors to converge hardware-software stacks faster than historical replacement timelines allowed.
Growth Catalysts
- EU F-Gas Regulation:Tightening infrastructure efficiency mandates across European distribution networks are accelerating digital retrofit spending on leak detection and thermal monitoring systems.
- AMI deployment waves:Advanced metering infrastructure rollouts in Germany and France are absorbing disproportionate continental deployment capital as utilities prioritize real-time consumption visibility.
- Edge analytics convergence:The fusion of IoT sensors with AI-driven predictive maintenance is pulling software procurement forward by 18-24 months in transmission-heavy utilities.
Market Restraints
- Semiconductor supply concentration:Discrete manufacturing capacity bottlenecks in East Asian foundries are extending lead times for power electronics and communication modules critical to substation automation.
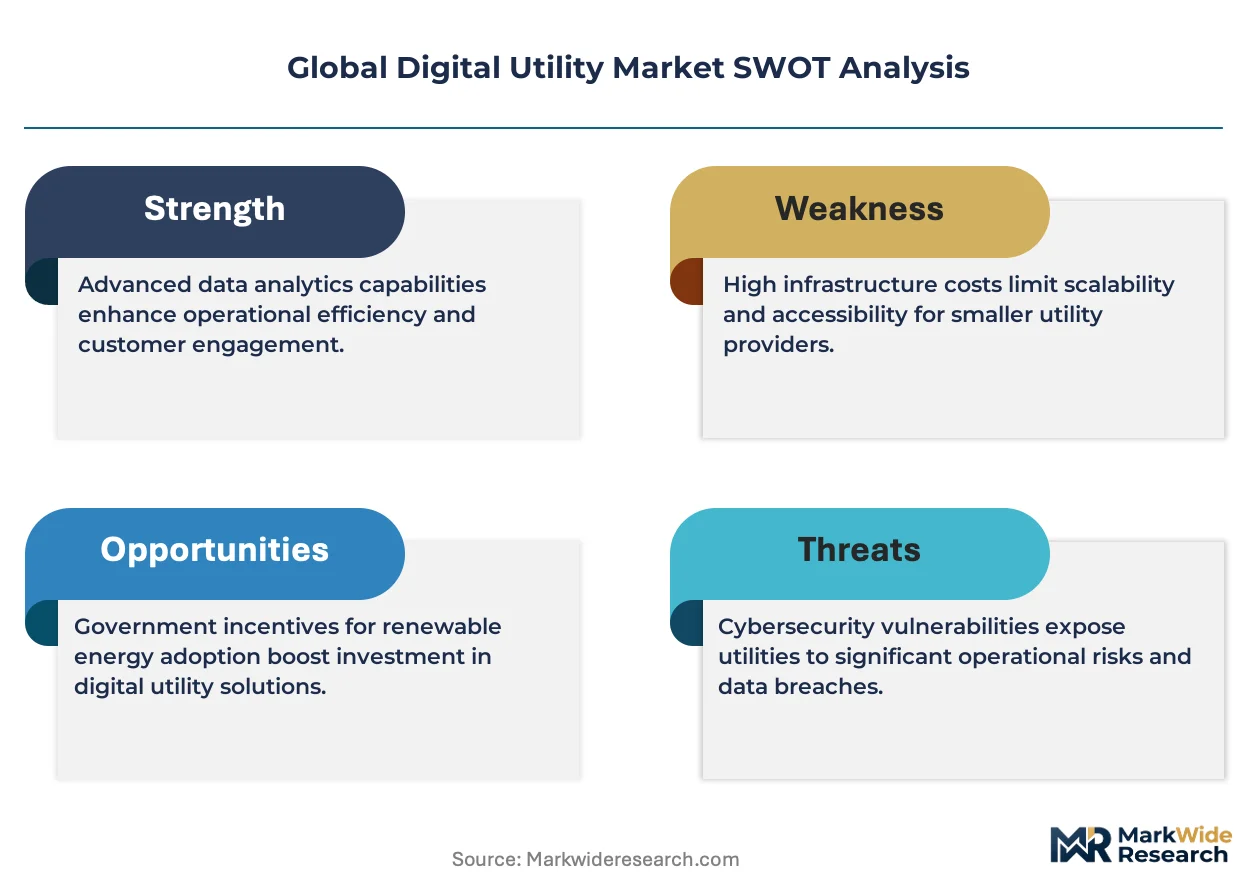
- Cybersecurity compliance costs:NERC CIP standards in North America and GDPR data governance in Europe are imposing parallel certification burdens that inflate project overhead by 15-22%.
- Legacy protocol fragmentation:Persistent DNP3 and Modbus installations in aging distribution networks create interoperability friction that slows cloud migration timelines.
Strategic Opportunities
- India smart grid acceleration:The country's CEA-mandated renewable integration targets are opening procurement windows for digital substation vendors as state discoms modernize rural feeders.
- Managed services white space:Cybersecurity and predictive maintenance outsourcing is claiming margin pools that captive utility IT departments cannot match.
- Digital twin convergence:The pairing of physics-based simulation with live sensor streams is creating new subscription revenue models for asset-intensive transmission operators.
Industry Challenges
- IEC 61850 talent scarcity:Specialized substation automation engineering skills are concentrating at a handful of system integrators, inflating implementation costs and extending commissioning schedules.
- Multi-vendor integration complexity:Utilities stitching together hardware from Siemens, software from specialized AI vendors, and cloud infrastructure from hyperscalers face protracted system validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Utility Market |
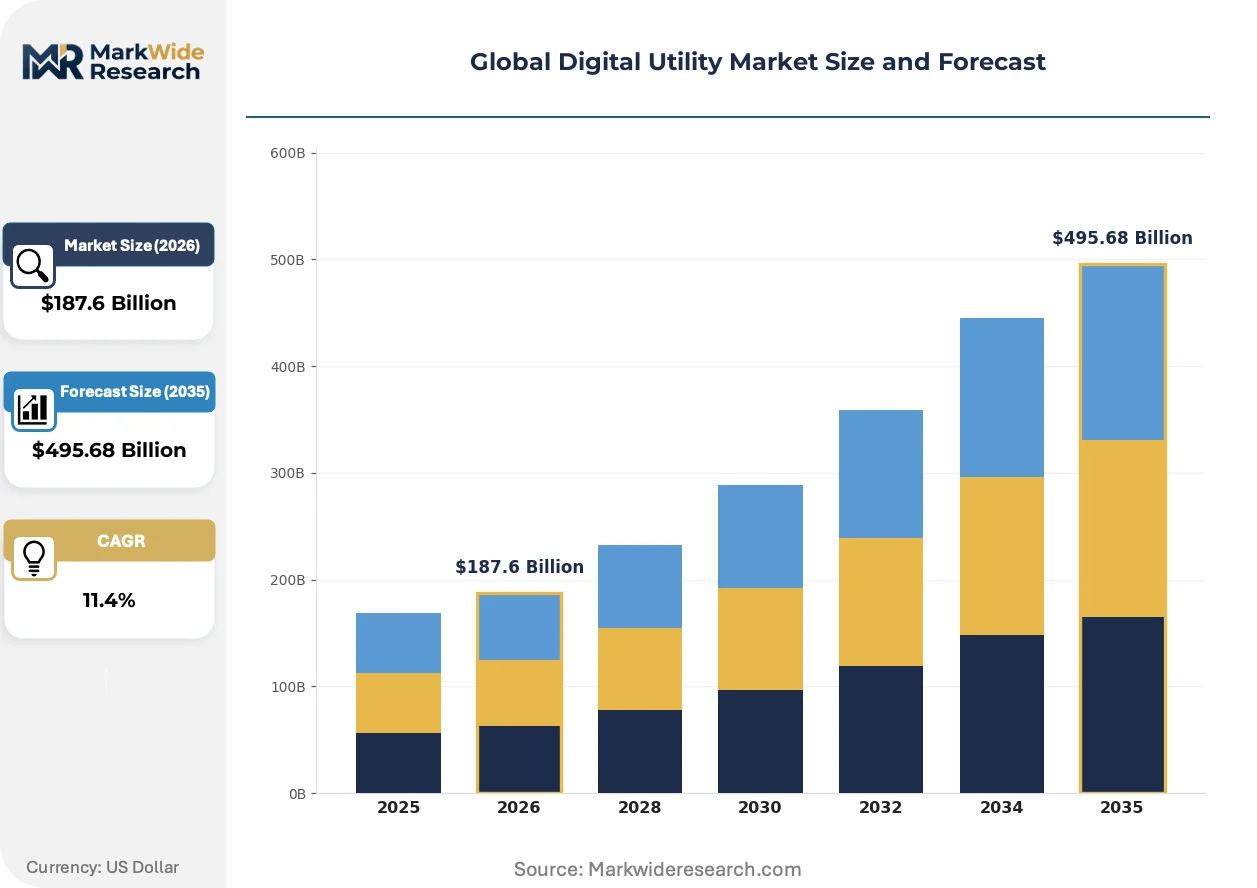
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $495.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Managed Services, Integration Services, Maintenance Services Deployment: On-Premise, Cloud, Hybrid, Edge Computing End User: Residential, Commercial, Industrial, Municipal Technology: IoT, AI, Big Data Analytics, Blockchain |
| Companies Covered | General Electric Company, Siemens AG, ABB Ltd., Schneider Electric SE, Oracle Corporation, Microsoft Corporation, Accenture PLC, IBM Corporation, SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Utility Market Emerging Trajectories
Software-defined architectures are redrawing how utilities procure and operate grid infrastructure, collapsing the traditional boundary between operational technology and enterprise IT.
Containerized microgrids are displacing monolithic control systems. Municipal utilities in California and Texas are deploying Kubernetes-orchestrated distributed energy resource management platforms that modularize control logic. This architecture is displacing centralized SCADA hierarchies and enabling faster feature deployment without hardware swaps.
Europe's CSRD is mandating granular emissions disclosure from grid operators. The regulation forces utilities to instrument transformer fleets and distribution lines with continuous carbon accounting sensors. Transmission system operators in Germany and the Netherlands are responding by embedding lifecycle assessment APIs directly into asset management platforms.
Subscription-based outcome contracting is displacing perpetual license sales for grid analytics software. Procurement teams at large investor-owned utilities are unbundling software acquisition from implementation risk, pushing vendors to guarantee availability and accuracy metrics. This shift is most visible in the United States, where FERC Order 2222 compliance pressures are accelerating performance-based procurement for distributed energy aggregation platforms.
Global Digital Utility Market Segmentation
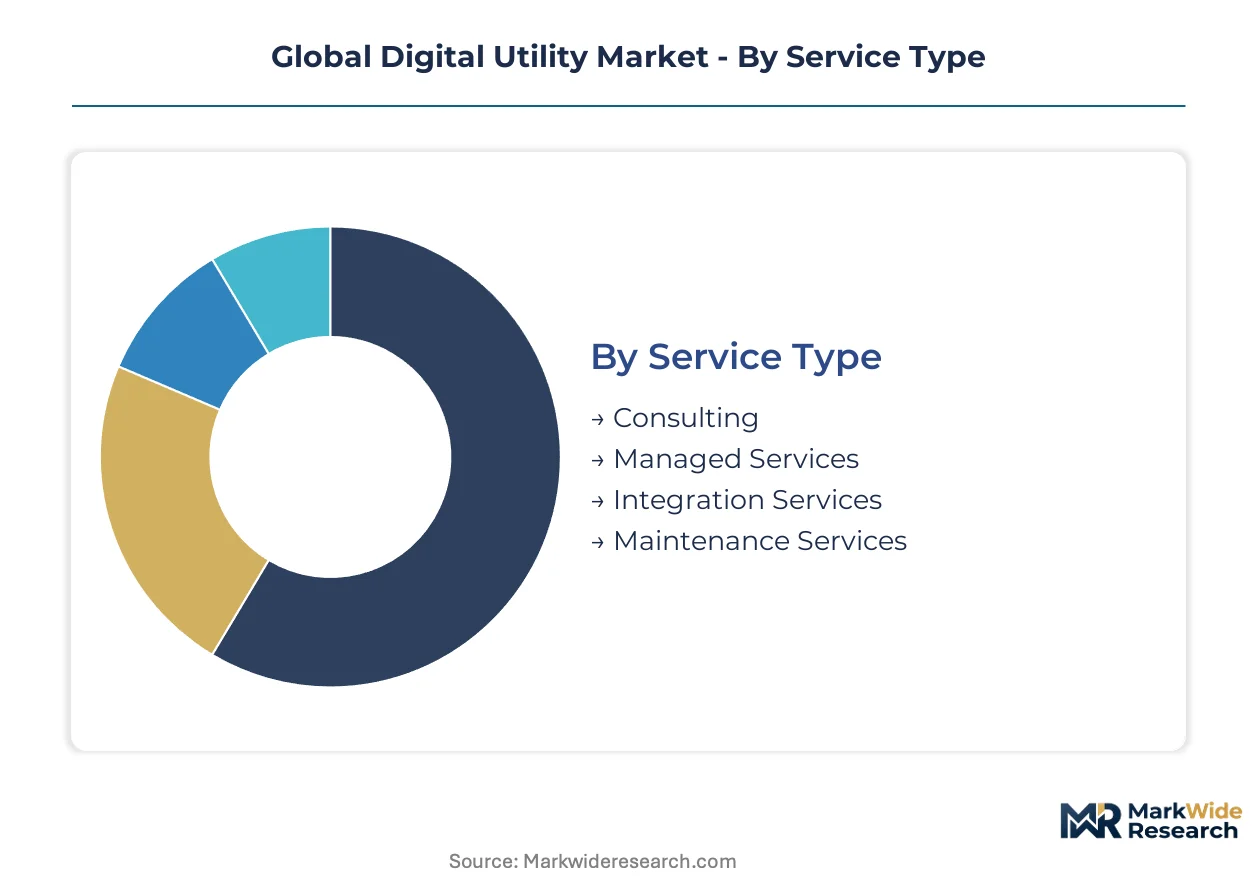
Digital utility procurement patterns diverge sharply across service models, infrastructure layers, and customer archetypes. Vendors must calibrate pricing architectures and delivery mechanisms to each segment's risk tolerance and technical maturity.
Service Type:
Margin pools concentrate most heavily in recurring revenue streams where utilities outsource operational risk rather than building captive capabilities.
- Managed Services:Comprehensive outsourcing of cybersecurity monitoring, predictive maintenance, and 24/7 network operations centers. German municipal utilities and Texas transmission operators are driving demand as NERC CIP compliance costs and IEC 61850 talent scarcity make in-house operations uneconomical.
- Integration Services:Multi-vendor system stitching and protocol translation for utilities migrating from legacy DNP3/Modbus to IEC 61850 architectures. Demand clusters among mid-sized municipal utilities in California and the Netherlands facing compressed procurement timelines from grid modernization mandates.
- Consulting:Strategic advisory on digital transformation roadmaps and regulatory compliance pathways.
- Maintenance Services:Break-fix and scheduled upkeep for deployed hardware-software stacks.
Managed Services commands the dominant share, while Integration Services is gaining share fastest as retrofit cycles accelerate.
Deployment:
Cost tiering separates capital-intensive on-premise builds from operational-expense cloud migrations with diverging total-cost-of-ownership profiles.
- Cloud:SCADA, advanced metering infrastructure, and grid analytics hosted on hyperscaler infrastructure with subscription economics. Investor-owned utilities in the United States and France are migrating fastest, pulled by FERC reliability pressures and EU CSRD reporting obligations that favor elastic compute scaling.
- Edge Computing:Containerized microgrid control and real-time DER orchestration deployed at substation level. Municipal utilities in Texas and California are deploying Kubernetes-orchestrated platforms to meet sub-second response requirements for distributed energy aggregation.
- On-Premise:Legacy server installations retained by risk-averse operators in critical infrastructure sectors.
- Hybrid:Split architectures maintaining sensitive operational technology on-premise while pushing analytics to cloud.
Cloud deployment holds the established position, though Edge Computing is climbing the fastest as latency-sensitive applications multiply.
End User:
Application intensity varies by customer scale, with large operators driving platform standardization and smaller entities demanding modular, pay-as-you-grow configurations.
- Industrial:Heavy manufacturing, data centers, and process industries requiring high-reliability power quality and demand response integration. German automotive clusters and Dutch greenhouse operations are prioritizing digital twin convergence for asset-intensive load management.
- Municipal:City-owned utilities modernizing distribution networks under federal and state mandates. Procurement is accelerating in India as CEA-mandated renewable integration targets force rural feeder digitization.
- Commercial:Office complexes, retail chains, and hospitality seeking energy cost optimization.
- Residential:Smart home integration and time-of-use billing platforms for individual consumers.
Industrial users anchor current spending, while Municipal deployment is expanding most quickly amid infrastructure stimulus programs.
Technology:
Supply concentration for specialized engineering talent is reshaping competitive boundaries across the technology stack.
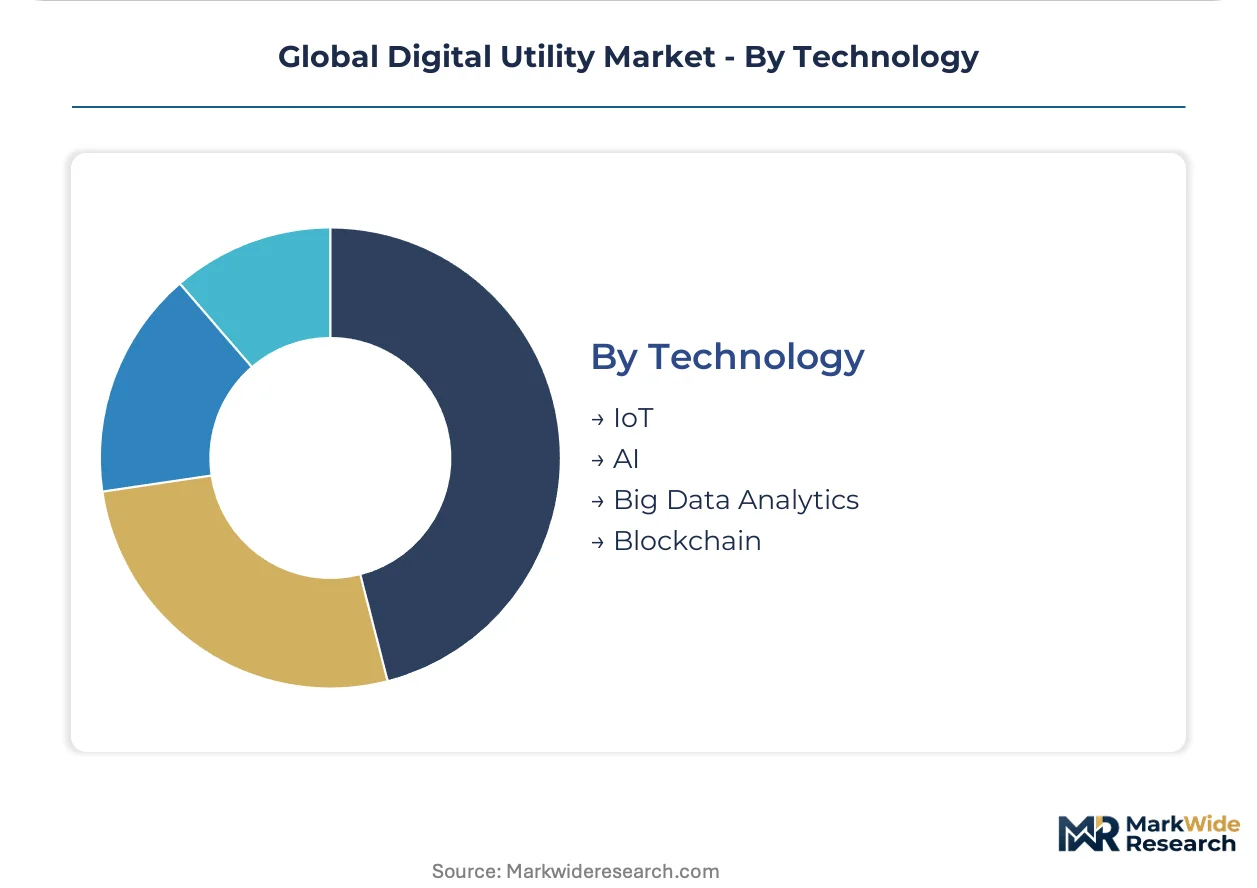
- AI:Predictive asset management, load forecasting, and anomaly detection layers trained on historical SCADA and AMI data. Transmission operators in Germany and the United States are embedding AI directly into asset management platforms to reduce technical losses.
- IoT:Sensor networks for transformer monitoring, line temperature sensing, and leak detection under EU F-Gas Regulation. Deployment is concentrating in Netherlands and Germany where CSRD carbon accounting mandates require continuous emissions instrumentation.
- Big Data Analytics:Pattern recognition across multi-source grid data for operational optimization.
- Blockchain:Distributed ledger applications for peer-to-peer energy trading and renewable energy certificate tracking.
AI captures the deepest vendor investment, while IoT is scaling fastest as hardware costs decline and regulatory instrumentation requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in digital utility infrastructure favor technology-exporting economies. Germany and the United States supply substation automation platforms to import-dependent markets across Southeast Asia and the Middle East. China's MIIT-driven domestic procurement absorbs limited foreign penetration despite massive deployment volumes.
United States
FERC Order 2222 compliance pressures and NERC CIP cybersecurity mandates accelerate procurement of distributed energy aggregation platforms. The Federal Energy Regulatory Commission enforces reliability standards that compress investment timelines for interstate transmission operators. Texas municipal utilities deploy Kubernetes-orchestrated microgrid controls to meet sub-second response requirements for renewable integration.
Germany
Utility digitization programs absorb disproportionate continental deployment spending under EU Green Deal infrastructure mandates. The F-Gas Regulation tightens efficiency requirements across distribution networks, accelerating digital retrofit investment in leak detection systems. Transmission system operators in Bavaria and North Rhine-Westphalia embed lifecycle assessment APIs into asset management platforms to satisfy CSRD emissions disclosure rules.
China
MIIT procurement guidelines and dual carbon goals accelerate domestic smart grid deployment with stringent local content requirements. The Ministry of Industry and Information Technology channels state-backed capital toward indigenous substation automation vendors. State Grid Corporation concentrates deployment in Yangtze River Delta and Pearl River Delta clusters, limiting foreign technology penetration despite massive infrastructure investment.
India
CEA-mandated renewable integration targets open procurement windows for digital substation vendors as state discoms modernize rural feeders. The Central Electricity Authority mandates smart metering rollout timelines that accelerate AMI deployment across Maharashtra and Gujarat. Karnataka and Tamil Nadu utilities prioritize feeder automation to manage distributed solar penetration on aging distribution networks.
Netherlands
CSRD carbon accounting mandates force continuous emissions instrumentation across transformer fleets and distribution lines. The Corporate Sustainability Reporting Directive requires granular disclosure that pulls software procurement forward by 12-18 months. Transmission operators in the Randstad cluster deploy IoT sensor networks for real-time thermal monitoring under parallel EU F-Gas compliance pressures.
Global Digital Utility Market Vendor Landscape
Concentration sits with diversified industrial conglomerates that command hardware-software convergence capabilities. Siemens AG and General Electric Company anchor the upper tier through captive substation automation expertise and deep utility relationships. Mid-tier specialists compete on IEC 61850 implementation speed and managed services flexibility. Strategic moves cluster around M&A for AI analytics capabilities and strategic partnerships with hyperscale cloud providers.
Among diversified industrial technology groups, Siemens AG, General Electric Company, and ABB Ltd. exemplify the hardware-centric archetype that dominates substation automation procurement. IBM Corporation and Microsoft Corporation occupy positions on the software-services vector, supplying predictive analytics and cloud infrastructure layers. Schneider Electric SE and Oracle Corporation represent the integrated platform play that utilities increasingly favor for reduced multi-vendor integration risk.
| Leading Market Players |
|---|
| General Electric Company |
| Siemens AG |
| ABB Ltd. |
| Schneider Electric SE |
| Oracle Corporation |
| Microsoft Corporation |
| Accenture PLC |
| IBM Corporation |
| SAP SE |
| Others |
Supply Flow & Price Mechanics
Extended lead times stretching 26-32 weeks for power electronics modules concentrate pricing power with East Asian foundries and force utilities into premium sourcing agreements that inflate project economics across substation automation deployments.
Pricing Analysis
Industrial OEM buyers anchor subscription-based pricing structures across digital utility platforms. Three-tier pricing stratifies across enterprise-grade, mid-market, and entry-level configurations differentiated by AI layer sophistication and after-sales service bundling. Cost compression in mid-tier SCADA migrations intensifies as municipal utilities consolidate procurement volumes. Municipal utilities in India exhibit highest price sensitivity due to constrained capital budgets, while German transmission operators demonstrate lowest sensitivity given CSRD compliance mandates.
Supply Chain Analysis
China, Taiwan, and South Korea anchor semiconductor fabrication for power electronics and communication modules critical to IEC 61850-compliant architectures. German and US vendors draw from concentrated wafer supply for substation automation hardware, with silicon carbide substrates and FPGA components resting on single-source dependencies. Tariff exposure on East Asian semiconductor imports creates procurement vulnerability for European utilities. Distribution runs through authorized system integrators and direct OEM channels to transmission operators and municipal utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Digital Utility Market represents early-cycle expansion as grid modernization mandates compress replacement timelines and pull software procurement forward by 18-24 months across transmission-heavy utilities.
For Market Incumbents: Shield hardware-software margin pools by deepening captive IEC 61850 engineering capabilities against talent scarcity at specialized system integrators. Accelerate certification investment for EU F-Gas and CSRD compliance to lock out mid-tier competitors from German and Dutch procurement cycles. For New Entrants and Emerging Players: Lead with managed services white space in cybersecurity monitoring and predictive maintenance where captive utility IT departments cannot match margin economics. Target Indian state discoms modernizing rural feeders under CEA-mandated renewable integration targets, positioning via outcome-based contracting that unbundles implementation risk. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because subscription-based outcome contracting displaces perpetual license sales and embeds vendors into utility operational workflows. Acquisition targets cluster around AI analytics specialists with trained SCADA data models. The signal to watch is FERC Order 2222 compliance acceleration driving performance-based procurement for distributed energy aggregation platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Converges hardware-software stacks faster than historical replacement timelines allowed under IEC 61850 mandates. |
| Strategic Partnership | Hyperscale cloud alliances enable elastic compute scaling for CSRD emissions disclosure and AMI analytics workloads. |
| Acquisition of Specialist Firm | AI analytics capabilities trained on historical SCADA data reduce technical losses for transmission operators. |
| Geographic Expansion | Indian state discom modernization opens procurement windows for digital substation vendors under CEA targets. |
| Green Certification Program | Lifecycle assessment APIs embedded in asset management platforms satisfy EU CSRD carbon accounting mandates. |
Methodological Framework
The analysis maps substation automation, AMI deployment, edge analytics, and managed services segments, each validated through utility planning officers, EPC contractors, grid operators, and system integration specialists. Primary fieldwork combined with secondary validation from FERC filings, EIA data, IEA reports, and EU regulatory databases enabled bottom-up and top-down triangulation across the value chain.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeled service type, deployment architecture, end-user scale, and technology layer dimensions. CAGRs derived from utility capital expenditure trajectories, regulatory mandate timelines, and vendor booking patterns triangulated against grid modernization investment databases.
The analysis sits within stated boundaries; outcomes outside sustained grid modernization funding levels or accelerated semiconductor supply normalization would require recalibration. Forecasts reflect documented assumptions on procurement cycle compression and talent scarcity persistence. Recalibration cycles align with material shifts in FERC Order 2222 implementation pace and EU F-Gas enforcement stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Europe Home Energy Management System Market
Energy Management Systems
Portable Air Cooler Market
Energy Management Systems
Intelligent Digital Meter Market
Energy Management Systems
Grid Operations Management Software Market
Energy Management Systems
Global Variable Air Volume (VAV) System Market
Energy Management Systems
Global Data Center Energy Management Solution Market
Energy Management Systems
Noise Mitigation System Market
Energy Management Systems
AI-Driven Lighting Controls Market
Energy Management Systems
GCC Desert Air Coolers Market
Energy Management Systems
Chemical Control Systems Market
Energy Management Systems
Intelligent PDU Market
Energy Management Systems
Energy Management Systems (EMS) Market
Energy Management Systems
Cooling Management System Market
Energy Management Systems
Wi-Fi Smart Thermostat Market
Energy Management Systems
Smart Water Cooler Market
Energy Management Systems
North America Residential Lighting Control System Market