
 Digital Signage Market | 2026-2036
Digital Signage Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Signage Market Analysis
A shift from single-source panel procurement to multi-source display supply is repositioning how vendors secure component capacity. Samsung Electronics leverages its semiconductor foundry assets to sustain captive LED driver supply. LG Electronics anchors its competitive stance through OLED technology leadership in premium indoor installations. Daktronics specializes in large-format outdoor systems and dominates sports venue deployments across North America.
Digital signage encompasses networked electronic displays ranging from 10-inch shelf-edge screens to 100-foot stadium ribbons, typically incorporating 4K or 8K resolution panels with ambient light sensors and thermal management systems for continuous commercial operation. The technology segment shows LED displacing legacy LCD in high-brightness outdoor applications where luminance thresholds exceed 2,500 nits. The end user segment reveals retail and transportation as the primary margin pools, with healthcare emerging through wayfinding and queue management demand. The solution segment positions analytics as the fastest-expanding layer, as computer vision integration turns passive displays into audience measurement tools.
The Federal Communications Commission governs radio-frequency emissions from wireless-connected signage in the United States, while the EU F-Gas Regulation restricts fluorinated greenhouse gases in display cooling systems. China's Ministry of Industry and Information Technology enforces GB standards for electronic display energy consumption and electromagnetic compatibility. Stakeholders must monitor evolving e-waste directives and local content requirements as procurement criteria harden across major deployment markets.
Market Dynamics
LED backlighting economics and EU F-Gas Regulation compliance costs are compressing legacy LCD margins while redirecting procurement budgets toward solid-state display architectures. This structural pressure is fragmenting supplier relationships and accelerating captive production investments across tier-one display vendors.
Growth Catalysts
- Smart City Infrastructure Mandates:China's tier-one cities are embedding networked displays into transit hubs and public service centers, creating standardized deployment templates that reduce installation friction and accelerate procurement cycles.
- EU F-Gas Regulation Phase-Down:Fluorinated greenhouse gas restrictions on display cooling systems are forcing equipment upgrades, generating replacement demand for compliant LED systems in European retail and transportation installations.
- Computer Vision Analytics Layer:Audience measurement software is integrating with hardware deployments, transforming passive screens into data collection nodes that justify premium pricing through measurable engagement metrics.
Market Restraints
- Semiconductor Supply Concentration:LED driver IC fabrication concentrates in Taiwan and South Korea foundries, exposing display manufacturers to geopolitical disruption and allocation rationing during demand spikes.
- High-Brightness LED Cost Structure:Nitride-based emitters for outdoor luminance thresholds above 2,500 nits carry material premiums that constrain adoption in price-sensitive municipal and small-format retail deployments.
- E-Waste Directive Compliance Burden:Extended producer responsibility frameworks in Germany and France impose end-of-life collection costs that erode margin on low-margin commodity screen categories.
Strategic Opportunities
- Healthcare Wayfinding White Space:Hospital systems in the United States and Germany are replacing static signage with networked queue management displays, opening a margin-rich vertical with extended replacement cycles and service attach rates.
- Edge Computing Convergence:On-device processing hardware is merging with display controllers, enabling real-time content adaptation without cloud latency and creating differentiation for vendors with semiconductor design capabilities.
- India Smart City Mission:Central government funding for urban digital infrastructure is unlocking municipal procurement budgets for transit and public safety display networks across Bangalore, Hyderabad, and Pune clusters.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for thermal management and ambient light adaptation lags hardware production capacity, delaying product launches and forcing reliance on third-party software stacks.
- Legacy Network Integration Friction:Existing digital signage estates running proprietary protocols resist migration to IP-based management platforms, complicating upsell paths for analytics-enabled replacement hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Signage Market |
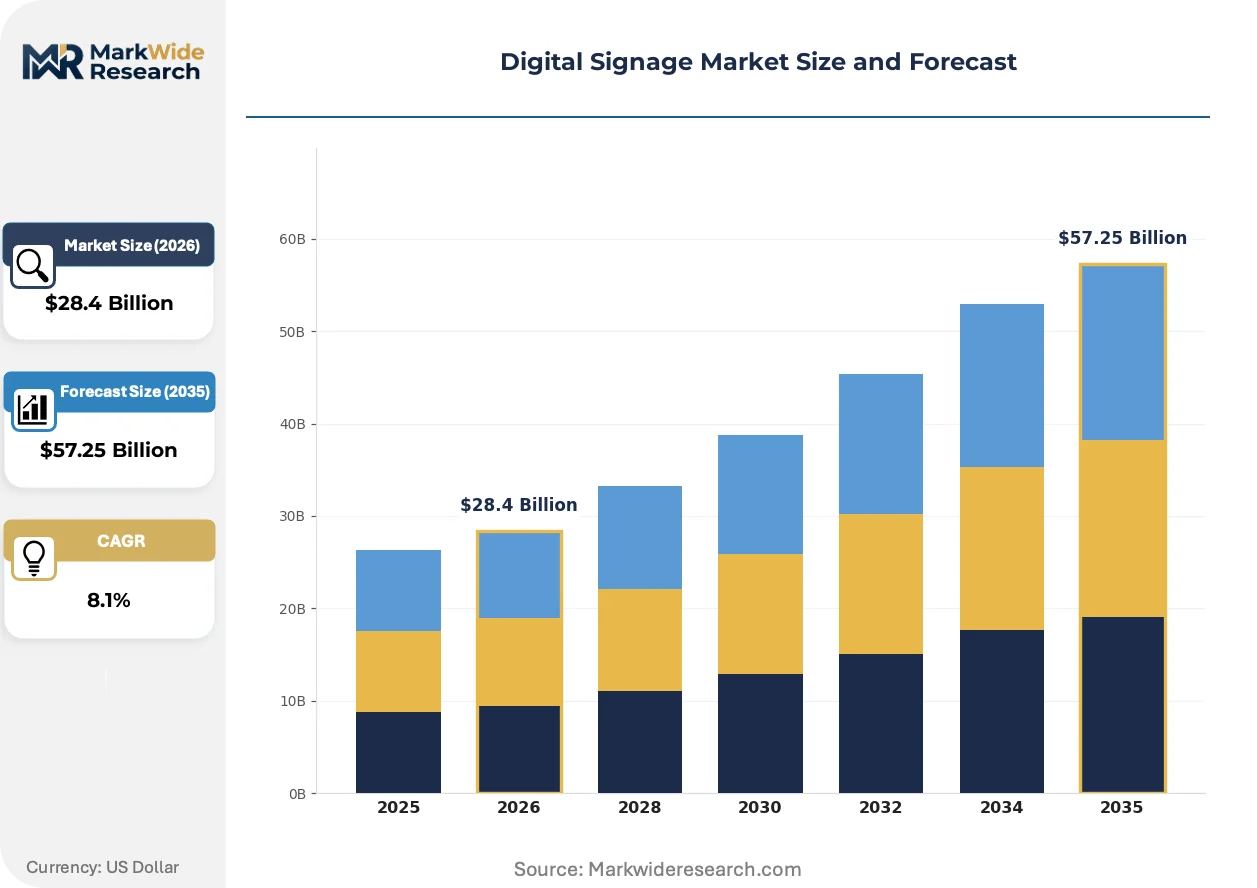
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $57.25 Billion |
| CAGR (2026 – 2036) | 8.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LCD, LED, OLED, Projection End User: Retail, Transportation, Healthcare, Education Solution: Content Management, Hardware, Software, Analytics Installation: Indoor, Outdoor, Wall-mounted, Freestanding |
| Companies Covered | Samsung Electronics, LG Electronics, Panasonic Corporation, Sharp Corporation, NEC Corporation, Sony Corporation, Cisco Systems, Barco, Daktronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Signage Market Emerging Trajectories
Display technology is converging with sensor networks and edge processing, transforming hardware vendors into software-enabled service providers. This architectural shift is compressing hardware margins while expanding recurring revenue potential through data and content management layers.
Mini-LED backlighting is integrating zone-dimming controllers with quantum dot color enhancement, enabling contrast ratios that approach OLED performance at lower burn-in risk. Sports venue operators and luxury retail chains in the United States and United Arab Emirates are specifying these panels for 24/7 operation cycles. The technology is integrating thermal feedback loops that adjust drive current in real time, extending operational lifespan in high-temperature installations.
The EU F-Gas Regulation is accelerating hydrocarbon and CO2 cooling system adoption in outdoor display enclosures, prohibiting hydrofluorocarbon refrigerants above specified global warming potential thresholds. Equipment manufacturers are redesigning thermal architectures to accommodate natural refrigerants with higher operating pressures. Outdoor advertising operators in Germany and France face accelerated depreciation schedules for non-compliant legacy assets.
Retail chains are consolidating display procurement under centralized facilities management functions, displacing decentralized store-level purchasing. This buyer concentration is favoring vendors with national installation and service networks over regional specialists. The shift is most visible in North American big-box retail, where corporate sustainability mandates now override local manager equipment preferences.
Digital Signage Market Segmentation
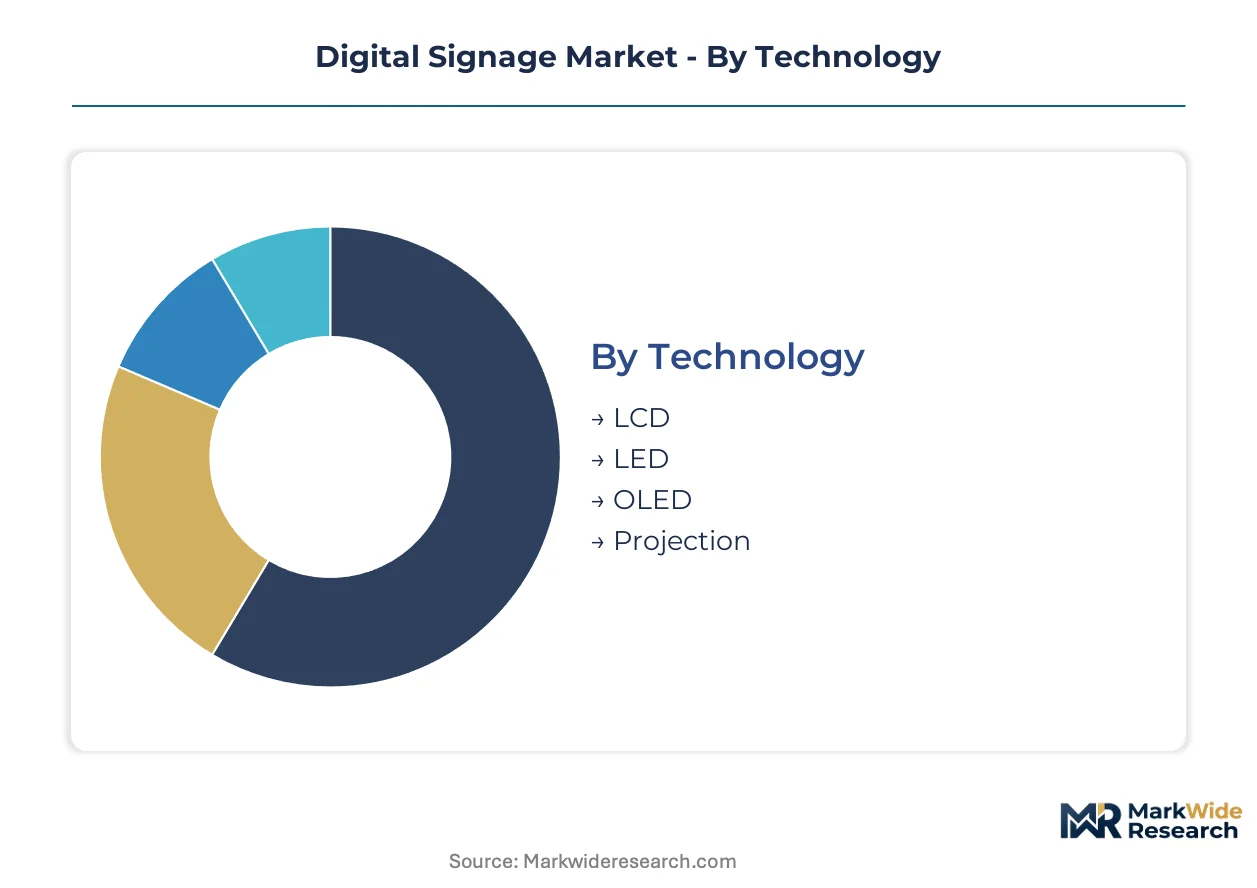
Digital signage procurement decisions cascade through technology choices, end-use requirements, solution architectures, and installation constraints. Each segmentation dimension carries distinct margin profiles and replacement-cycle dynamics that reshape vendor positioning.
Technology:
Upgrade cycles in display technology are compressing as solid-state architectures displace legacy backlighting systems and thermal compliance mandates accelerate fleet turnover.
- LED:Nitride-based emitters deliver luminance thresholds exceeding 2,500 nits for high-ambient environments. Demand concentrates in outdoor advertising networks across Germany and France where EU F-Gas Regulation compliance deadlines force cooling system replacements.
- LCD:Edge-lit and direct-lit configurations with quantum dot enhancement dominate indoor retail deployments. Procurement volumes cluster in China's tier-one city transit hubs where smart city standardization reduces installation friction.
- OLED:Self-emissive organic compounds enable infinite contrast ratios without backlight bleed. Premium indoor installations in luxury retail chains specify these panels for 24/7 operation cycles.
- Projection:Laser phosphor and LED-illuminated systems serve temporary and large-venue applications where physical display mounting proves impractical.
Volume placements concentrate in LED; the faster expansion belongs to OLED.
End User:
Margin pools diverge sharply across verticals based on replacement-cycle length, service attach rates, and software integration depth.
- Retail:Shelf-edge screens through video walls drive networked display demand. North American big-box chains consolidate procurement under centralized facilities management functions that override local manager preferences.
- Transportation:Transit hub and airport deployments require ruggedized enclosures with thermal feedback loops. China's Ministry of Industry and Information Technology GB standards enforce electromagnetic compatibility certification for these installations.
- Healthcare:Wayfinding and queue management systems replace static signage in hospital networks. Extended replacement cycles and high service attach rates characterize this emerging vertical.
- Education:Campus-wide digital communication networks serve administrative and emergency notification functions with moderate brightness requirements.
Transportation commands the largest installation base; healthcare is climbing the fastest as hospital systems digitize patient flow management.
Solution:
Revenue composition is shifting from hardware-centric transactions toward recurring software and data service layers.
- Hardware:Display panels, media players, and mounting systems constitute the foundational procurement layer. Cost pressure from multi-source supply strategies compresses margins on commodity screen categories.
- Software:Content management platforms enable remote scheduling and device monitoring across distributed estates. Legacy network integration friction complicates migration from proprietary protocols to IP-based management.
- Content Management:Cloud-hosted and on-premise systems orchestrate playlist distribution and playback verification. Centralized retail procurement favors vendors with national service networks.
- Analytics:Computer vision integration transforms passive displays into audience measurement nodes. Real-time engagement metrics justify premium pricing through measurable ROI documentation.
Hardware absorbs the majority of current spending; analytics is gaining share fastest as computer vision capabilities mature.
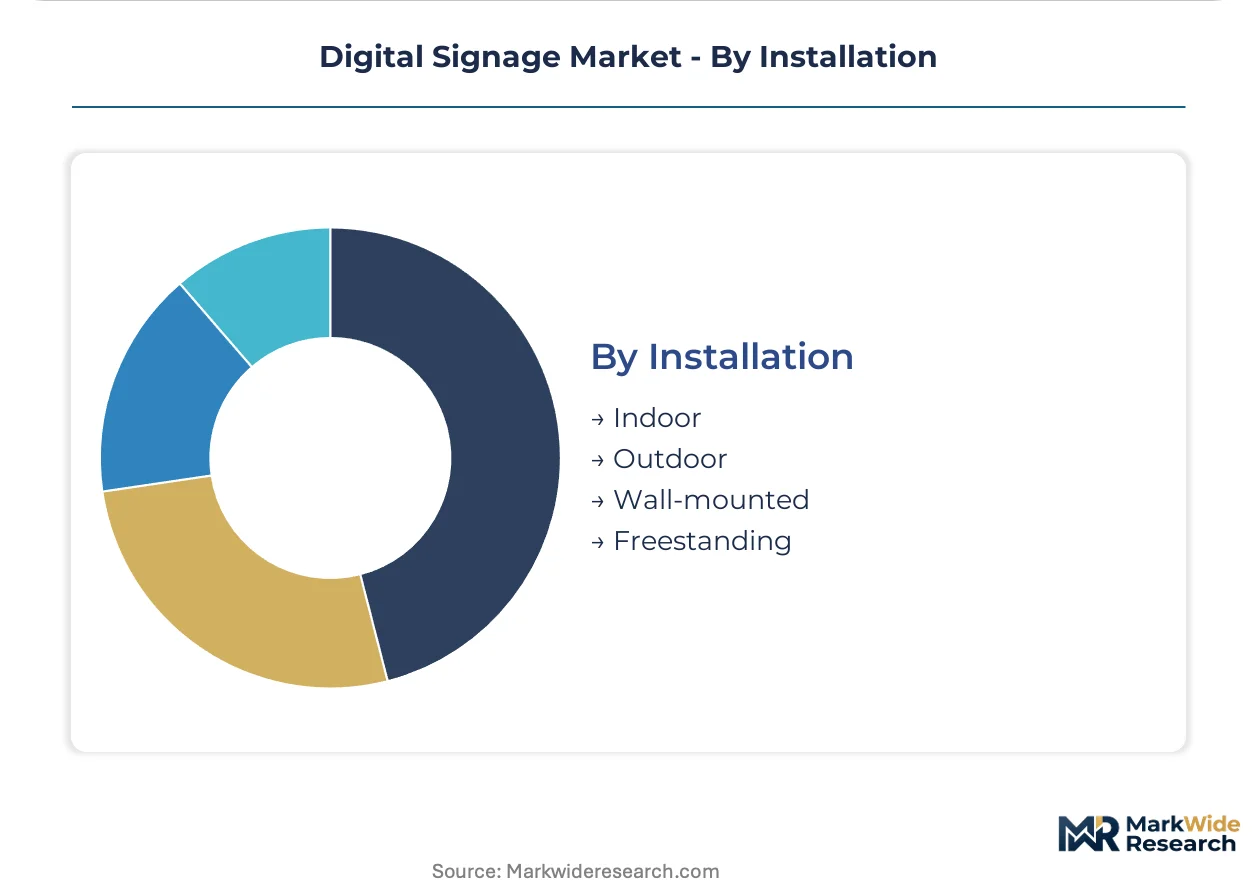
Installation:
Environmental exposure and mounting constraints dictate thermal architecture, enclosure ratings, and service access design.
- Indoor:Climate-controlled environments enable thinner bezels and lower power budgets. Retail chains and corporate campuses drive volume with standardized display formats.
- Outdoor:Direct solar load and precipitation exposure require IP-rated enclosures with active cooling. Hydrocarbon and CO2 refrigeration systems replace hydrofluorocarbon refrigerants under EU F-Gas Regulation phase-down schedules.
- Wall-mounted:Fixed installations maximize floor space efficiency in high-traffic corridors and waiting areas. VESA mounting standards simplify deployment across mixed vendor estates.
- Freestanding:Kiosk and totem formats enable repositioning for seasonal traffic patterns and event-driven placement. Wayfinding applications in healthcare and transportation favor these configurations.
Indoor deployments retain volume leadership; outdoor specifications are expanding most quickly as municipal smart city budgets harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the largest share of procurement volume through tier-one city smart city deployments, while EU regulatory mandates and North American retail consolidation reshape regional competitive dynamics.
United States
Big-box retail chains consolidate display procurement under centralized facilities management functions that override local manager preferences. The FCC governs radio-frequency emissions from wireless-connected signage installations. Deployment clusters concentrate in Dallas-Fort Worth and Chicago metro areas where corporate headquarters drive standardized network rollouts.
Germany
Outdoor advertising operators face accelerated depreciation schedules for non-compliant legacy assets under EU F-Gas Regulation phase-down timelines. The country's national environmental regulator enforces extended producer responsibility frameworks that impose end-of-life collection costs. Industrial demand concentrates in Bavaria and North Rhine-Westphalia where automotive and machinery exhibition centers drive large-format display specifications.
China
Smart city infrastructure mandates in Beijing, Shanghai, and Shenzhen embed networked displays into transit hubs and public service centers. The Ministry of Industry and Information Technology enforces GB standards for electronic display energy consumption and electromagnetic compatibility. Procurement standardization in the Yangtze River Delta reduces installation friction and accelerates deployment cycles.
France
Hydrocarbon and CO2 cooling system adoption accelerates in outdoor display enclosures as hydrofluorocarbon refrigerants face prohibition above specified global warming potential thresholds. The national environmental regulator enforces e-waste directive compliance burdens that erode margin on commodity screen categories. Paris and Lyon municipal budgets harden for transit and public safety display networks.
India
Central government funding for urban digital infrastructure unlocks municipal procurement budgets for transit and public safety display networks. The Bureau of Indian Standards enforces certification requirements for electronic display imports and domestic production. Deployment clusters concentrate in Bangalore, Hyderabad, and Pune where smart city mission funding channels into integrated transit hub installations.
Digital Signage Market Vendor Landscape
Multi-source display supply strategies dominate the current landscape as vendors secure component capacity across fragmented supplier relationships. The vendor base organizes around three strategic archetypes: diversified electronics conglomerates with captive semiconductor assets, specialized display technology firms with premium panel expertise, and systems integrators with vertical application depth. Competitive positioning hardens through backward integration into LED driver supply and geographic expansion of service networks.
Within the diversified electronics tier, Samsung Electronics and LG Electronics exemplify scale-driven positioning through semiconductor foundry assets and OLED technology leadership respectively. Daktronics occupies a position among specialized outdoor systems providers with concentrated presence in sports venue deployments. These three anchors represent distinct competitive vectors: captive component supply, premium display technology, and vertical application specialization.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Panasonic Corporation |
| Sharp Corporation |
| NEC Corporation |
| Sony Corporation |
| Cisco Systems |
| Barco |
| Daktronics |
| Others |
Supply Flow & Price Mechanics
Firmware engineering talent scarcity in Taiwan and South Korea widens pricing spreads between premium service-bundled systems and bare-metal commodity panels. Labor-cost differentials in LED driver IC design centers translate into three-tier pricing structures that separate enterprise-grade managed deployments from unbundled hardware transactions.
Pricing Analysis
Warranty and field-service bundling distinguishes premium LED installations from economy LCD transactions in procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal management certification grade and on-site service attach rates. Cost compression in edge-lit LCD categories intensifies because multi-source panel procurement erodes brand premiums. Municipal buyers in India's smart city clusters exhibit highest price sensitivity, while North American healthcare networks accept premium positioning for 24/7 uptime guarantees.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale retail chain demand, while systems integrators serve fragmented healthcare and education verticals. LED driver IC fabrication concentrates in Taiwan and South Korea, with nitride-based emitter substrates sourced from Japan and China. The supply chain draws from gallium nitride wafers, quantum dot enhancement films, and hydrocarbon refrigerant cooling systems. Single-source vulnerability in Taiwan foundry capacity exposes display manufacturers to geopolitical disruption. Distribution runs through national service networks for centralized retail procurement and regional specialists for municipal deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation compliance deadlines are accelerating fleet turnover and squeezing margin-poor LCD vendors toward exit. Consolidation pressure favors players with captive semiconductor assets or vertical application depth.
For Market Incumbents: Anticipate margin compression in commodity indoor LCD segments as captive LED driver supply becomes the threshold capability for sustainable participation. Secure multi-year foundry allocation agreements before demand spikes trigger rationing. Deepen backward integration into thermal management firmware development to reduce reliance on scarce embedded systems talent. For New Entrants and Emerging Players: Computer vision analytics modules offer a technology-first wedge into healthcare wayfinding and queue management deployments where incumbents lack vertical expertise. India's smart city mission funding channels present the most penetrable geography for municipal transit hub installations. Pursue partnership-based go-to-market models with national facilities management firms rather than direct channel builds. For Investors and Strategic Acquirers: Re-rating potential sits with specialized outdoor systems providers given sports venue replacement cycles and EU regulatory-driven upgrade demand. Long-term viability favors vendors with demonstrated thermal architecture expertise and hydrocarbon cooling system certifications. Monitor LED driver IC allocation announcements from Taiwan foundries as an inflection indicator for sector-wide margin pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Captive LED Driver Supply Investment | Secures semiconductor allocation priority during Taiwan foundry capacity constraints. |
| Hydrocarbon Cooling System Certification | Enables EU F-Gas Regulation compliance for outdoor advertising network replacements. |
| Computer Vision Analytics Integration | Transforms hardware margins into recurring software revenue through audience measurement. |
| Healthcare Vertical Service Network Expansion | Captures extended replacement-cycle revenue from hospital wayfinding deployments. |
| India Smart City Channel Partnership | Unlocks municipal procurement budgets in Bangalore, Hyderabad, and Pune clusters. |
Methodological Framework
Document review covered SEC 10-K filings, EU F-Gas Regulation implementation guidance, and China's MIIT GB standards documentation, complemented by interviews with display technology procurement directors, embedded systems engineering leads, and smart city infrastructure planners. Primary fieldwork engaged facilities management executives at North American retail chains, outdoor advertising operators in Germany and France, and municipal technology officers in India's smart city mission clusters. Secondary validation drew from customs trade data, foundry capacity utilization reports, and hospital procurement database analysis. Bottom-up demand modeling triangulated against top-down market sizing across technology, end-use, and solution segmentation dimensions.
Historical shipment data cross-referenced against panel input from semiconductor foundry contacts and retail chain procurement timelines established baseline calibration. The analytical framework modeled technology transitions, end-use replacement cycles, and solution revenue mix shifts across the projection horizon. Segmentation dimensions included display technology architecture, installation environment, vertical application, and software service attach rates. CAGRs derived from unit economics modeling of LED versus LCD procurement decisions under evolving regulatory compliance costs. Industry-specific inputs encompassed EU F-Gas phase-down schedules, China smart city infrastructure mandates, and healthcare digitization spending patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained Taiwan foundry allocation rationing or accelerated EU e-waste directive enforcement. The analysis reflects assumptions regarding LED cost curve trajectories, hydrocarbon cooling system adoption rates, and computer vision analytics penetration timelines. Periodic stress-testing of base assumptions is recommended against semiconductor supply disruption scenarios and municipal budget austerity measures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Ticketing Solution Market
Digital Solutions
Correspondence Management Solution Market
Digital Solutions
Digital Assistant Market
Digital Solutions
Virtual Office Market
Digital Solutions
Personality Assessment Solutions Market
Digital Solutions
Canada ICT Market
Digital Solutions
Assortment and Space Optimization (ASO) Market
Digital Solutions
Data Converter Market
Digital Solutions
Multichannel Order Management Market
Digital Solutions
Saudi Arabia ICT Market
Digital Solutions
UX Services Market
Digital Solutions
United Kingdom ICT Market
Digital Solutions
Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market
Digital Solutions
Online Dating Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Europe Smart Government Market