
 US Digital Marketing Software Market | 2026-2036
US Digital Marketing Software Market Size, Share, and Industry Trends Forecast 2026-2036
US Digital Marketing Software Market Intelligence
Data science talent scarcity is bifurcating the competitive landscape between platforms that can build proprietary machine learning pipelines and those dependent on third-party inference APIs. Salesforce leverages its Einstein intelligence layer to sustain pricing power in enterprise CRM-adjacent marketing clouds. Adobe anchors its competitive position through Creative Cloud integration that extends into campaign execution workflows. HubSpot competes by specializing in mid-market inbound automation with native CMS-to-CRM connectivity that reduces stack complexity for resource-constrained teams.
Digital marketing software encompasses applications for customer acquisition, engagement measurement, and campaign automation across paid, owned, and earned media channels, typically delivered through API-first architectures that enable real-time bid optimization and cross-channel identity resolution. The primary commercial purpose is to replace intuition-driven media buying with algorithmic decisioning that improves return on ad spend through predictive audience segmentation and dynamic creative assembly. Cloud-based deployment dominates new bookings as enterprises prioritize elastic compute for seasonal campaign spikes, while on-premises installations persist in financial services and healthcare verticals where data residency requirements override cost considerations. Analytics tools represent the fastest-expanding product type as advertisers demand incrementality measurement and privacy-compliant attribution following the deprecation of third-party cookies.
The FTC enforces Section 5 prohibitions against deceptive advertising practices, including native disclosure requirements and influencer marketing transparency mandates that shape how platforms build automated compliance checks into content workflows. The California Consumer Privacy Act and its successor CPRA impose opt-out rights and data minimization obligations that force vendors to engineer consent management and deletion orchestration as core platform capabilities. Stakeholders must monitor the interplay between emerging state privacy statutes and federal preemption debates to determine whether modular compliance architectures or unified national stacks offer superior risk-adjusted investment returns.
Market Dynamics
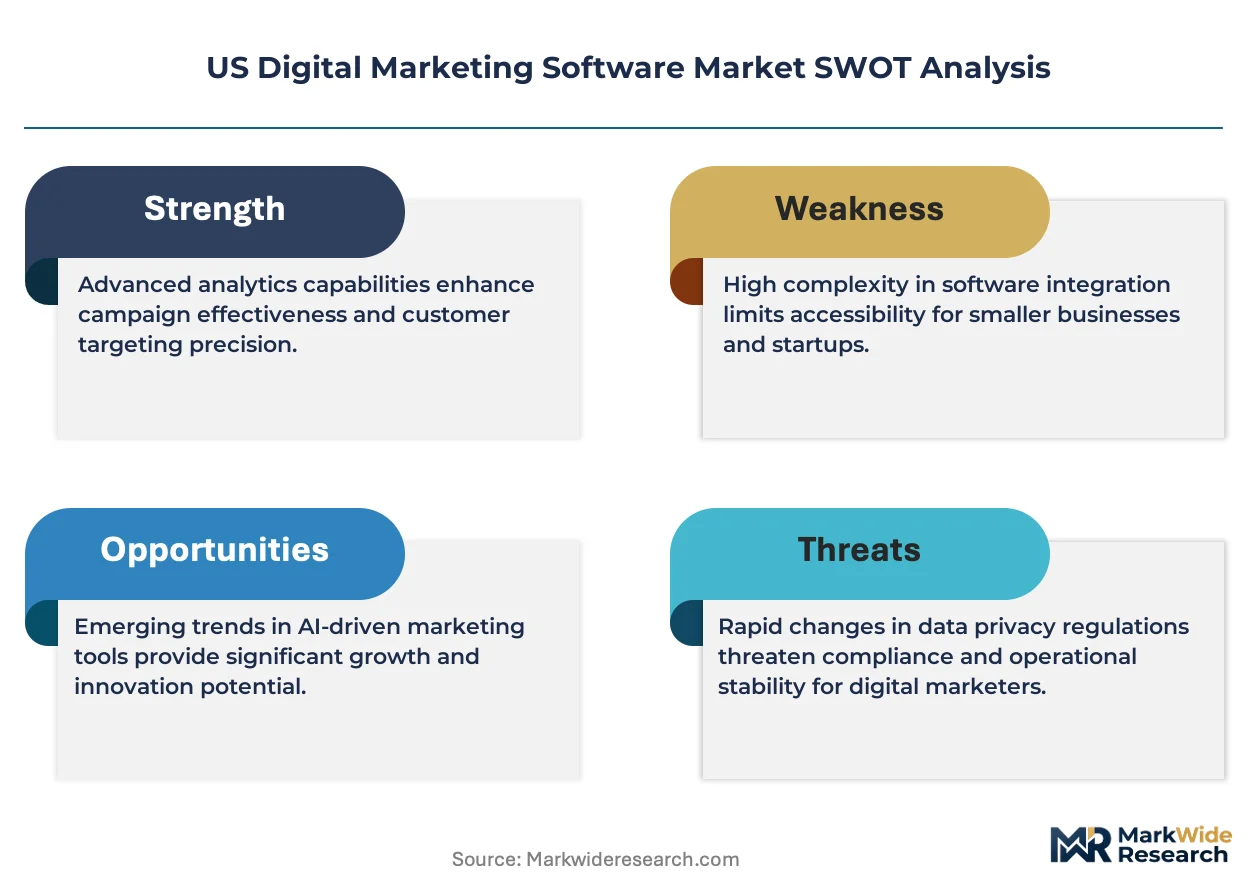
AI-powered campaign orchestration is concentrating competitive advantage among vendors with proprietary machine learning infrastructure, forcing mid-tier platforms into costly build-versus-partner decisions that reshape capital allocation across the sector.
Growth Catalysts
- FTC Algorithmic Transparency Mandates:Compliance requirements around attribution modeling are driving enterprise upgrades to consent-aware analytics stacks. Retail operators prioritize platforms with built-in audit trails.
- Retail Media Networks:Walmart and Target's retail media expansion creates demand for closed-loop measurement tools. CPG brands require software that bridges on-site conversion with off-platform prospecting.
- California Talent Density:The San Francisco-San Jose corridor concentrates platform engineering expertise. Venture deployment in the region accelerates feature velocity for locally headquartered vendors.
Market Restraints
- Cloud Compute Cost Volatility:Training and inference workloads for generative creative tools expose SaaS margins to GPU pricing swings. Tier-two vendors lack volume discounts with hyperscalers.
- Third-Party Cookie Deprecation:Google's Privacy Sandbox delays compress addressable audience availability. Advertisers face measurement gaps that erode algorithmic bidding efficiency.
- First-Party Data Infrastructure:CDP deployment timelines stretch 18-24 months for Fortune 500 retailers. Resource constraints delay migration from legacy DMP architectures.
Strategic Opportunities
- Texas Enterprise Corridor:Austin and Dallas-Fort Worth host expanding Fortune 500 headquarters with underdeveloped martech stacks. Sales cycles shorten for vendors with local implementation partners.
- Healthcare Vertical Expansion:HIPAA-compliant campaign orchestration remains underserved. Platforms with built-in PHI handling capture pharmacy and provider network budgets.
- CTV-Linear Convergence:Connected TV inventory standardization enables cross-screen frequency capping. Software vendors integrating programmatic TV with social buying capture upfront commitments.
Industry Challenges
- Machine Learning Operations Talent:MLOps engineers capable of productionizing attribution models command premium compensation. Vendors compete with hyperscalers and hedge funds for scarce candidates.
- Legacy CRM Integration:On-premises Siebel and early Salesforce instances resist real-time data synchronization. Professional services costs inflate for enterprise deployments requiring custom middleware.
- State Privacy Fragmentation:Divergent statutes across Virginia, Colorado, and Connecticut force modular compliance architectures. Engineering overhead multiplies for national campaign management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Digital Marketing Software Market |
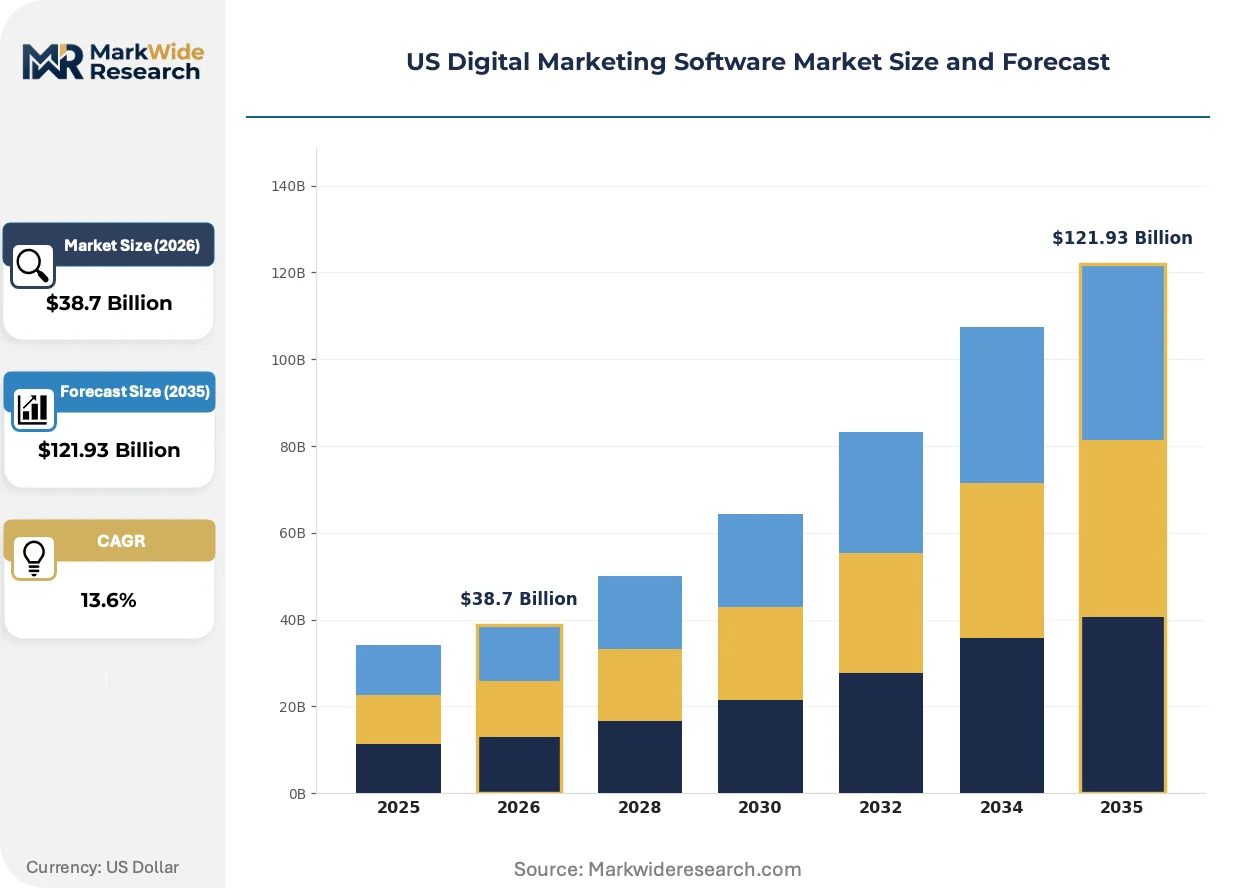
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $121.93 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Content Management, Social Media Management, Email Marketing, Analytics Tools Deployment: Cloud-Based, On-Premises, Hybrid, SaaS User Type: Small Businesses, Enterprises, Agencies, Non-Profits Integration Level: API Integrations, Plug-ins, Native Integrations, Standalone Solutions |
| Companies Covered | Salesforce, Oracle, WebFX, IBM, SAS Institute, HubSpot, Marketo, Sprinklr, Adobe, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Digital Marketing Software Market Strategic Shifts & Innovations
Generative AI deployment is fragmenting vendor roadmaps between proprietary model development and API-dependent feature layers. The regulatory environment around algorithmic decisioning tightens disclosure obligations. Buyer procurement criteria now weight privacy architecture as heavily as performance benchmarks.
Generative creative assembly is bifurcating platform capabilities between those training proprietary diffusion models and those routing prompts through OpenAI or Anthropic APIs. Enterprise advertisers with seasonal volume spikes demand in-house model control for cost predictability. Mid-market buyers accept API dependency to preserve capital for media spend rather than infrastructure.
The FTC's updated endorsement guidelines now explicitly cover synthetic media and AI-generated influencer content. Platforms must embed automated disclosure checks into content workflows before publication. Retail and direct-to-consumer brands face the steepest compliance burden given their reliance on creator partnerships.
Outcome-based compensation models are displacing seat-based SaaS pricing for performance marketing tools. Agencies and brands negotiate contracts tied to incrementally verified conversions rather than impressions served. This shift is most visible in the DTC vertical where CFO scrutiny of marketing ROI has intensified post-2021 capital tightening.
US Digital Marketing Software Market Segmentation
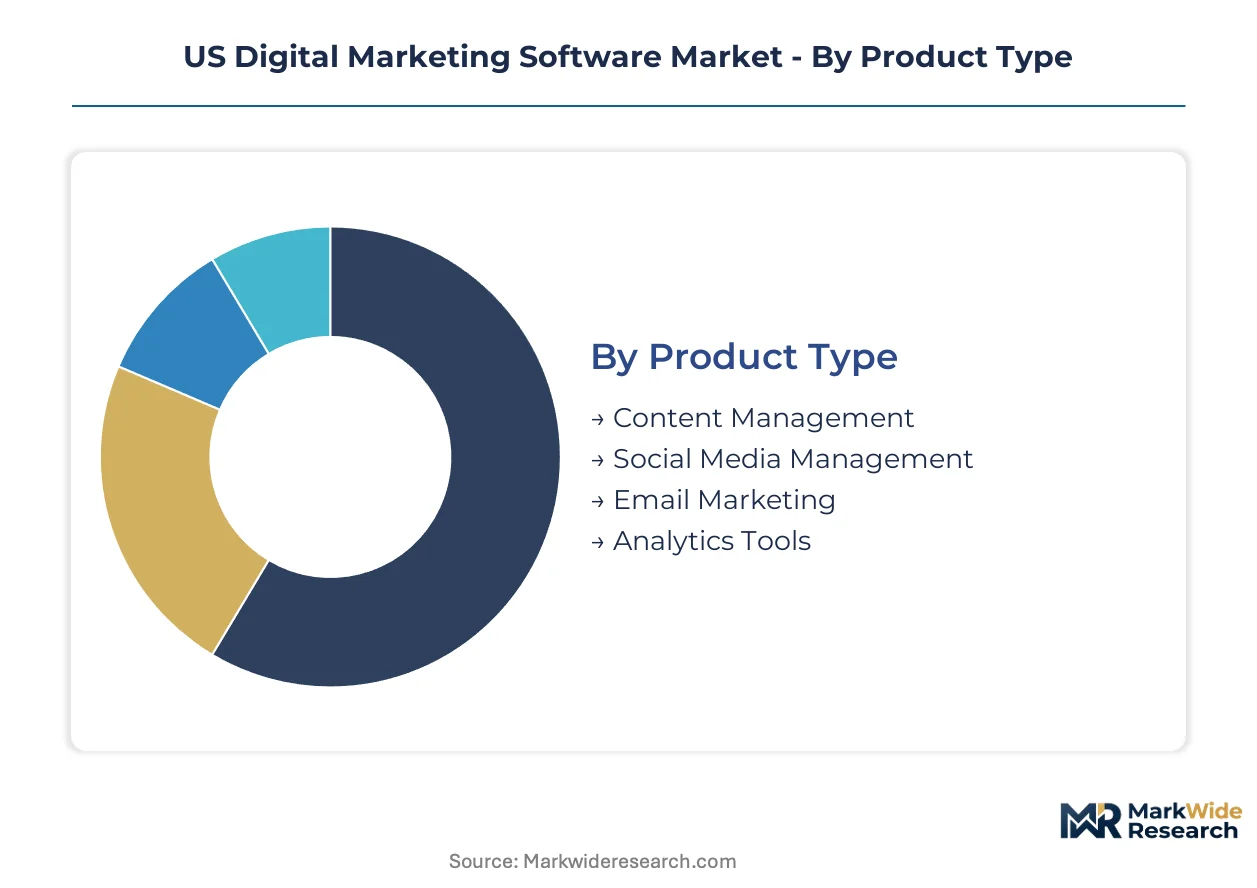
Segmentation reveals how substitution pressures reshape procurement priorities across the US Digital Marketing Software Market. Buyers increasingly trade off best-of-breed depth against stack consolidation, forcing vendors to defend position through integration breadth rather than isolated feature superiority.
Product Type:
Substitution pressure runs strongest through analytics and content management as buyers collapse overlapping point solutions into unified platforms.
- Analytics Tools:Attribution modeling and incrementality measurement capabilities now anchor enterprise RFP requirements. Retail and e-commerce operators in California and Texas prioritize platforms with privacy-compliant cross-channel identity resolution following FTC algorithmic transparency mandates.
- Content Management:Headless CMS architectures with native personalization engines displace legacy web content platforms. Mid-market brands demand Creative Cloud-adjacent workflows that compress creative-to-deployment cycles.
- Social Media Management:Unified inbox and creator workflow tools with automated FTC disclosure checking.
- Email Marketing:Deliverability optimization and first-party data activation for retention-heavy DTC brands.
Analytics Tools anchors the volume base while Analytics Tools gains share at the steepest rate.
Deployment:
Cost tier differentiation separates hyperscaler-dependent vendors from infrastructure-autonomous platforms with pricing predictability.
- Cloud-Based:Elastic compute provisioning supports seasonal campaign spikes without capital-intensive infrastructure commits. Enterprise procurement teams in the Texas corridor favor consumption-based pricing that aligns software spend with media flighting patterns.
- SaaS:Seat-based and outcome-based pricing models compete for agency and mid-market brand preference. CFO scrutiny of marketing ROI intensifies contract negotiations toward incrementally verified conversion metrics.
- Hybrid:Split architectures for healthcare and financial services with segmented data residency requirements.
- On-Premises:Persistent demand from HIPAA-regulated health systems and SEC-registered investment advisors.
Cloud-Based deployment captures the majority of new bookings while Hybrid configurations expand most quickly among compliance-constrained verticals.
User Type:
Application complexity separates resource-constrained buyers from procurement teams with dedicated martech operations functions.
- Enterprises:Multi-brand campaign orchestration with centralized governance and distributed execution rights. Fortune 500 retailers demand CDP-to-activation pipelines with 18-24 month implementation timelines.
- Agencies:Multi-tenant architectures with client isolation and white-label reporting capabilities. Holding companies consolidate vendor relationships to capture volume discounts and reduce stack fragmentation.
- Small Businesses:All-in-one inbound automation with native CMS-to-CRM connectivity and minimal implementation overhead.
- Non-Profits:Grant-funded procurement with donor management integration and volunteer coordination workflows.
Enterprises dominate absolute spending while Small Businesses represent the largest addressable account base.
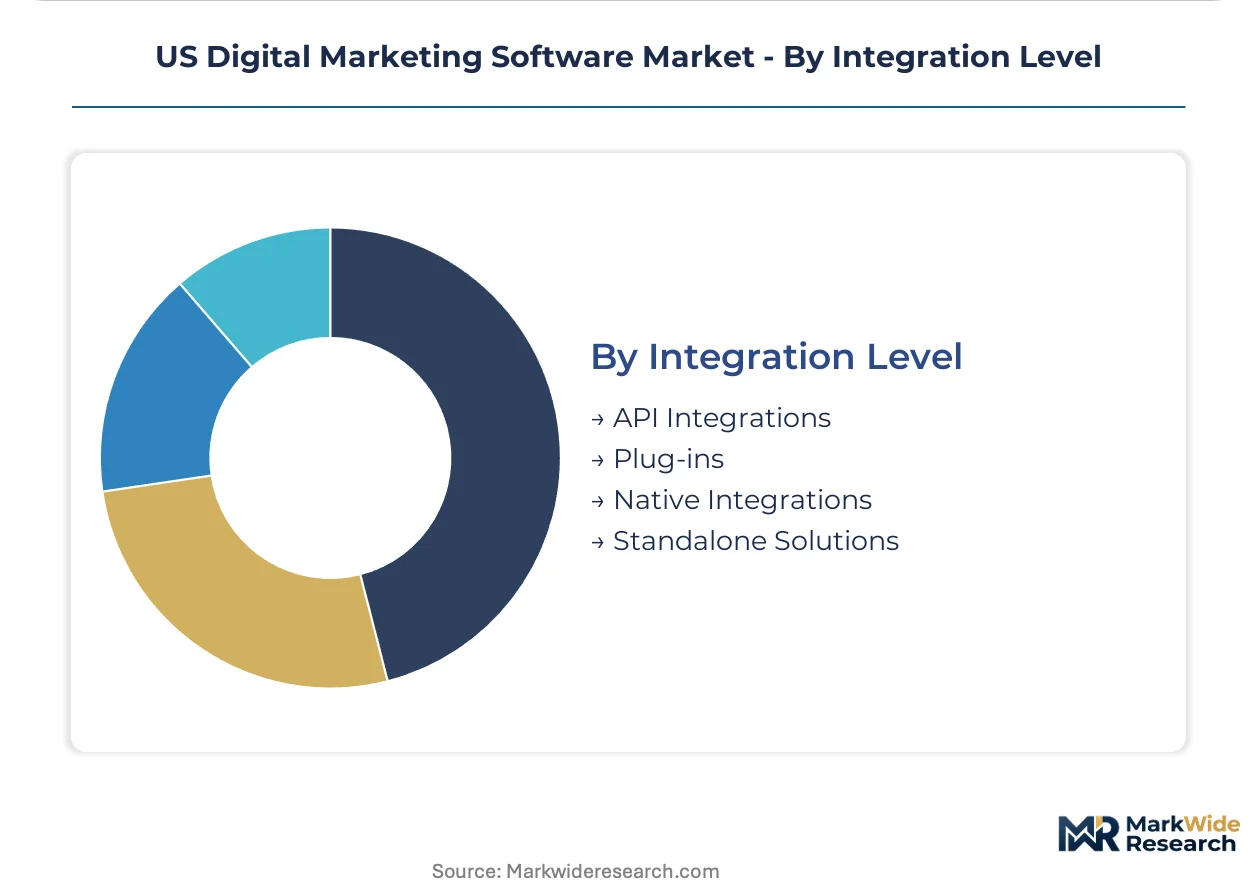
Integration Level:
Customer type maturity determines whether buyers prioritize plug-and-play connectivity or custom API development resources.
- Native Integrations:Pre-built connectors to Salesforce, Adobe, and HubSpot ecosystems reduce middleware costs. Enterprise IT teams in the California technology corridor favor platforms with bi-directional data synchronization that eliminates ETL maintenance.
- API Integrations:Open architecture enabling proprietary workflow construction for technically sophisticated operators. Retail media networks require custom bridges between closed-loop measurement tools and off-platform prospecting systems.
- Plug-ins:Marketplace-extensible platforms for WordPress, Shopify, and WooCommerce merchant bases.
- Standalone Solutions:Point products surviving through vertical specialization or performance pricing models.
Native Integrations command premium pricing while API Integrations climb the fastest as technically mature buyers demand extensibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California technology corridors concentrate platform engineering talent and venture deployment, while Texas enterprise corridors host expanding Fortune 500 headquarters with underdeveloped martech stacks. This geographic consumption differential shapes how vendors allocate sales and implementation resources across the US market.
California
Enterprise adoption of AI-powered campaign orchestration accelerates among retail and e-commerce operators headquartered in the San Francisco-San Jose corridor. The state's Consumer Privacy Act and CPRA successor impose opt-out rights and data minimization obligations that force vendors to engineer consent management as core platform capabilities. Platform engineering talent density in Silicon Valley accelerates feature velocity for locally headquartered vendors including Salesforce and Adobe.
Texas
Austin and Dallas-Fort Worth host expanding Fortune 500 headquarters with underdeveloped martech stacks that shorten sales cycles for vendors with local implementation partners. The state lacks comprehensive privacy legislation equivalent to California's CPRA, creating regulatory arbitrage for compliance-modular architectures. Retail media network operators in the Dallas-Fort Worth metroplex demand closed-loop measurement tools bridging on-site conversion with off-platform prospecting.
New York Metro
Financial services and advertising holding companies in Manhattan and Brooklyn drive demand for on-premises and hybrid deployment options where data residency requirements override cost considerations. The state's SHIELD Act imposes breach notification obligations that reshape customer data management practices for financial services marketers. Madison Avenue agency clusters consolidate vendor relationships to capture volume discounts and reduce stack fragmentation across multi-tenant architectures.
Illinois
Midwest manufacturing and CPG brand headquarters in Chicago generate procurement demand for mid-market inbound automation with native CMS-to-CRM connectivity. The state's Biometric Information Privacy Act creates compliance complexity for facial recognition and voiceprint applications in retail media. Chicago-based professional services firms specialize in legacy CRM integration requiring custom middleware for on-premises Siebel and early Salesforce instances.
Massachusetts
Greater Boston's healthcare and biotechnology concentration drives HIPAA-compliant campaign orchestration requirements that remain underserved by generalist platforms. The state's data protection regulations align with federal healthcare privacy frameworks rather than creating conflicting obligations. Cambridge technology clusters host HubSpot and adjacent marketing automation specialists competing on stack consolidation for resource-constrained teams.
US Digital Marketing Software Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with competitive dynamics determined by proprietary machine learning infrastructure versus API-dependent feature layers. The California technology corridor concentrates platform engineering talent and venture deployment, accelerating feature velocity for locally headquartered vendors. Three strategic archetypes dominate: enterprise CRM-adjacent marketing clouds, creative-integrated campaign execution platforms, and mid-market inbound automation specialists. M&A activity concentrates around analytics and customer data platform capabilities, while strategic partnerships with retail media networks reshape attribution modeling competitive positioning.
Within the enterprise marketing cloud tier, Salesforce leverages its Einstein intelligence layer to sustain pricing power, while Adobe anchors competitive position through Creative Cloud integration extending into campaign execution workflows. HubSpot occupies a distinct mid-market position specializing in inbound automation with native CMS-to-CRM connectivity. These three exemplify how integration breadth rather than isolated feature superiority determines competitive outcomes as buyers trade off best-of-breed depth against stack consolidation.
| Leading Market Players |
|---|
| Salesforce |
| Oracle |
| WebFX |
| IBM |
| SAS Institute |
| HubSpot |
| Marketo |
| Sprinklr |
| Adobe |
| Others |
Cost & Logistics Intelligence
Hyperscaler GPU volume discounts concentrate infrastructure leverage among top-tier vendors, compressing margins for mid-market platforms while anchoring price floors for enterprise AI-powered campaign orchestration tools. This scale dynamic bifurcates vendor economics between those with captive compute capacity and those exposed to spot-market cloud pricing.
Pricing Analysis
Long-term enterprise contracts with consumption-based pricing dominate procurement for Fortune 500 retailers, while seat-based SaaS subscriptions persist among mid-market inbound automation buyers. Three-tier pricing structure across premium, standard, and economy levels differentiates by integration depth and machine learning infrastructure access, with California-headquartered platforms commanding brand premiums. Pricing pressure stems from GPU cost volatility eroding SaaS margins for generative creative tools. Small businesses exhibit highest price sensitivity, prioritizing all-in-one stack consolidation over best-of-breed depth.
Supply Chain Analysis
NVIDIA H100 chip allocation bottlenecks constrain training capacity for proprietary model development, forcing vendors into build-versus-partner decisions on generative AI roadmaps. Cloud infrastructure draws from hyperscaler data centers concentrated in Northern Virginia, Oregon, and Ohio, with backup provisioning from Texas and Arizona facilities. Supply chain risk centers on single-source dependency for specialized AI accelerators. Distribution runs through direct enterprise sales teams, agency channel partners, and self-serve product-led growth motions for small business tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among retail media networks and Fortune 500 holding companies that consolidate vendor relationships to capture volume discounts, fragmenting procurement leverage for standalone point solutions.
For Market Incumbents: Consolidate analytics and customer data platform capabilities through targeted acquisition to defend against API-dependent challengers. Prioritize vertical integration into proprietary machine learning infrastructure to reduce hyperscaler cost exposure. Lock in multi-year enterprise contracts with retail media network operators before compliance-modular architectures commoditize attribution modeling. For New Entrants and Emerging Players: HIPAA-compliant campaign orchestration for healthcare verticals represents the most penetrable white-space segment, with generalist platforms under-serving pharmacy and provider network requirements. Texas enterprise corridors offer shortened sales cycles for vendors with local implementation partners. Lead with outcome-based pricing tied to incrementally verified conversions to differentiate from incumbent seat-based models. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with proprietary machine learning pipelines over API-dependent feature layers, as enterprise buyers prioritize cost predictability for seasonal volume spikes. Long-term viability hinges on CDP-to-activation pipeline ownership. Monitor FTC algorithmic transparency enforcement intensity as the signal indicating whether compliance-modular or unified national architectures capture superior risk-adjusted returns.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Model Development | Captures GPU cost predictability for enterprise advertisers with seasonal volume spikes. |
| CDP Capability Acquisition | Accelerates first-party data infrastructure deployment timelines for Fortune 500 retailers. |
| Healthcare Vertical Certification | Unlocks pharmacy and provider network budgets underserved by generalist platforms. |
| Texas Implementation Partner Network | Shortens sales cycles for expanding Fortune 500 headquarters in Austin and Dallas-Fort Worth. |
| Automated FTC Compliance Embedding | Reduces regulatory risk for retail and DTC brands reliant on creator partnerships. |
Research Approach
A spread of perspectives from platform engineering executives, enterprise marketing operations directors, agency holding company procurement leads, and martech integration specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation drawing from SEC filings, hyperscaler capex disclosures, App Annie mobile intelligence, and FTC enforcement action records. Bottom-up segment sizing triangulated against top-down market reconstruction across deployment models, organization tiers, and vertical adoption patterns.
Segmentation dimensions modeled include product type, deployment architecture, user organization scale, and integration complexity level, with additional granularity on regional adoption patterns within California technology corridors and Texas enterprise corridors. CAGRs were derived through trend extrapolation anchored to disclosed booking growth rates and venture deployment velocity. Forecast inputs incorporated CDP implementation timeline data and retail media network expansion trajectories.
Underlying assumptions cover sustained GPU supply availability, stable state privacy legislative fragmentation, and continued hyperscaler cloud dominance, with deviation risk concentrated in federal preemption debates and algorithmic transparency enforcement intensity. Practitioners should keep alternative scenarios live as FTC disclosure mandate scope and third-party cookie deprecation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Decision Making Software Market
Software & Services
Design Engineering Software Market
Software & Services
Global Construction Management Software Market
Software & Services
Credit Management Software Market
Software & Services
Creative Software Market
Software & Services
Search and Discovery Software Market
Software & Services
Computer Engineering Market
Software & Services
Global Membership Management Software Market
Software & Services
Android Emulator Market
Software & Services
HCS Software and Services Market
Software & Services
Case Management Software (CMS) Market
Software & Services
Telecom Billing Software Market
Software & Services
Software Construction Components Market
Software & Services
Theatrical Distribution Software Market
Software & Services
Mobile Application Development Market
Software & Services
CGI Software Market