
 Global Salesforce CRM Document Generation Software Market | 2026-2036
Global Salesforce CRM Document Generation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Salesforce CRM Document Generation Software Market Foresight
The Salesforce CRM document generation software tier is rebalancing between premium enterprise suites and commodity template tools. Conga leverages deep vertical integration with Salesforce's native architecture to command higher contract values. Nintex sustains competitive pressure through workflow automation breadth that extends beyond document generation. S-Docs anchors the mid-market with API-light deployment that reduces implementation friction for smaller Salesforce orgs.
Salesforce CRM document generation software comprises cloud-native and on-premise applications that extract structured CRM data to auto-populate contracts, proposals, invoices, and compliance records through programmable templates and dynamic field mapping. These systems integrate via REST APIs, Apex triggers, or managed packages to eliminate manual re-entry and enforce version control across distributed sales and legal teams. Cloud-based deployment leads volume due to faster provisioning and lower infrastructure overhead, while contract management captures the largest margin pool as enterprises demand clause libraries, redlining, and e-signature orchestration within a single workflow. Proposal automation represents the fastest structural expansion as configure-price-quote convergence drives real-time document assembly from live product catalogs.
The EU AI Act, GDPR, and SEC disclosure rules are reshaping product requirements by mandating audit trails, data lineage, and explainability in automated document outputs. FDA 21 CFR Part 11 and HIPAA impose additional validation burdens on life sciences and healthcare adopters, creating compliance-based switching costs that favor established vendors with pre-certified architectures. Stakeholders must monitor how evolving cross-border data localization statutes affect multi-tenant cloud architectures and API routing decisions.
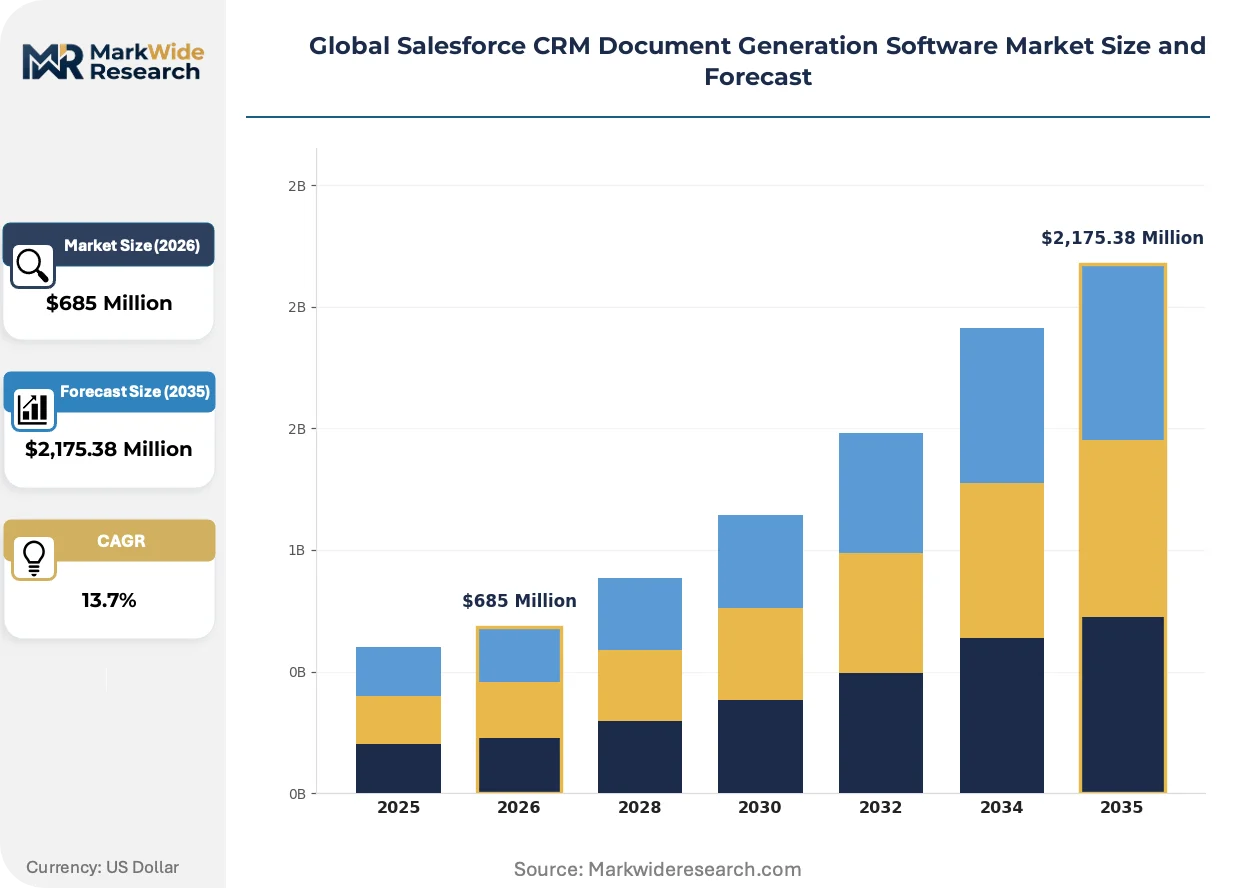
Market Dynamics
The Salesforce CRM document generation market is rebalancing around compliance-driven procurement, where EU AI Act audit mandates and SEC disclosure requirements are forcing buyers to prioritize traceable data lineage over template breadth.
Growth Catalysts
- EU AI Act compliance mandates:Financial services and life sciences firms in Germany and France are accelerating replacement of legacy document systems to satisfy explainability and audit trail requirements for automated contract outputs.
- Configure-price-quote convergence:Manufacturing and technology sectors are demanding real-time document assembly from live product catalogs, compressing sales cycles and reducing quote-to-close friction.
- India's PLI scheme for IT exports:Domestic software vendors are scaling Salesforce-native document automation capabilities to capture enterprise CRM modernization budgets in Mumbai and Bangalore.
Market Restraints
- API rate limiting and data residency costs:Multi-tenant cloud architectures face escalating egress fees and localization requirements that inflate total cost of ownership for cross-border deployments.
- Salesforce platform dependency:Concentration risk in a single CRM ecosystem creates vulnerability to pricing changes, API deprecation schedules, and exclusive partnership shifts by the platform owner.
- Template standardization inertia:Legal and procurement departments in regulated industries resist abandoning clause libraries and redlining workflows embedded in incumbent systems.
Strategic Opportunities
- Healthcare and life sciences vertical expansion:FDA 21 CFR Part 11 and HIPAA validation requirements create compliance-based switching costs that favor vendors with pre-certified architectures in the United States.
- AI-native contract intelligence:Natural language processing and machine learning convergence enables automated clause extraction, risk scoring, and obligation management within document generation workflows.
- Mid-market API-light deployment:Smaller Salesforce orgs in India and Germany are adopting managed-package solutions that reduce implementation friction and accelerate time-to-value.
Industry Challenges
- Apex and Lightning Web Components expertise scarcity:The talent pool for Salesforce-native development remains shallow relative to demand, inflating implementation timelines and professional services costs.
- Cross-border data routing complexity:Evolving localization statutes in the European Union, India, and United States force vendors to rearchitect multi-tenant infrastructure and API endpoint strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Salesforce CRM Document Generation Software Market |
| Market Size in 2026 | $685 Million |
| Market Size in 2035 | $2,175.38 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solution Type: Contract Management, Proposal Automation, Invoice Generation, Report Automation, Compliance Documentation End User: Financial Services, Telecommunications, Manufacturing Firms, Technology Providers, Education Institutions Integration Level: Basic, Advanced, Enterprise, Custom API, Plugin-Based |
| Companies Covered | Conga, Nintex, SpringCM, DealHub, WebMerge, Windward Studios, S-Docs, Docomotion, Documill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Salesforce CRM Document Generation Software Market Shifts & Advancements
Document generation technology is converging with adjacent workflow automation and contract lifecycle management stacks, compressing the addressable market for standalone point solutions.
AI-powered clause intelligence is unifying contract drafting, risk analysis, and compliance verification into single-pass workflows. Large financial institutions in the United States and Germany are piloting these systems for derivatives documentation and M&A closing sets. This convergence is collapsing the traditional separation between document generation and contract analytics, forcing pure-play vendors to expand capability breadth or retreat to template commoditization.
The EU AI Act and GDPR are mandating algorithmic transparency for any automated document containing legally binding terms. Life sciences firms operating under FDA 21 CFR Part 11 must now validate AI model versions as part of their computerized system qualification protocols. European pharmaceutical companies are responding by demanding vendor-provided model cards and data lineage documentation as standard procurement requirements.
Enterprise buyers are consolidating vendor relationships around integrated CRM-native automation suites rather than best-of-breed point tools. Mid-market technology and professional services firms in India and the United States are prioritizing single-vendor solutions that span proposal automation, e-signature orchestration, and post-execution obligation tracking. This preference shift is squeezing standalone document generation vendors into narrower template-tool positioning or forced platform acquisitions.
Global Salesforce CRM Document Generation Software Market Segmentation
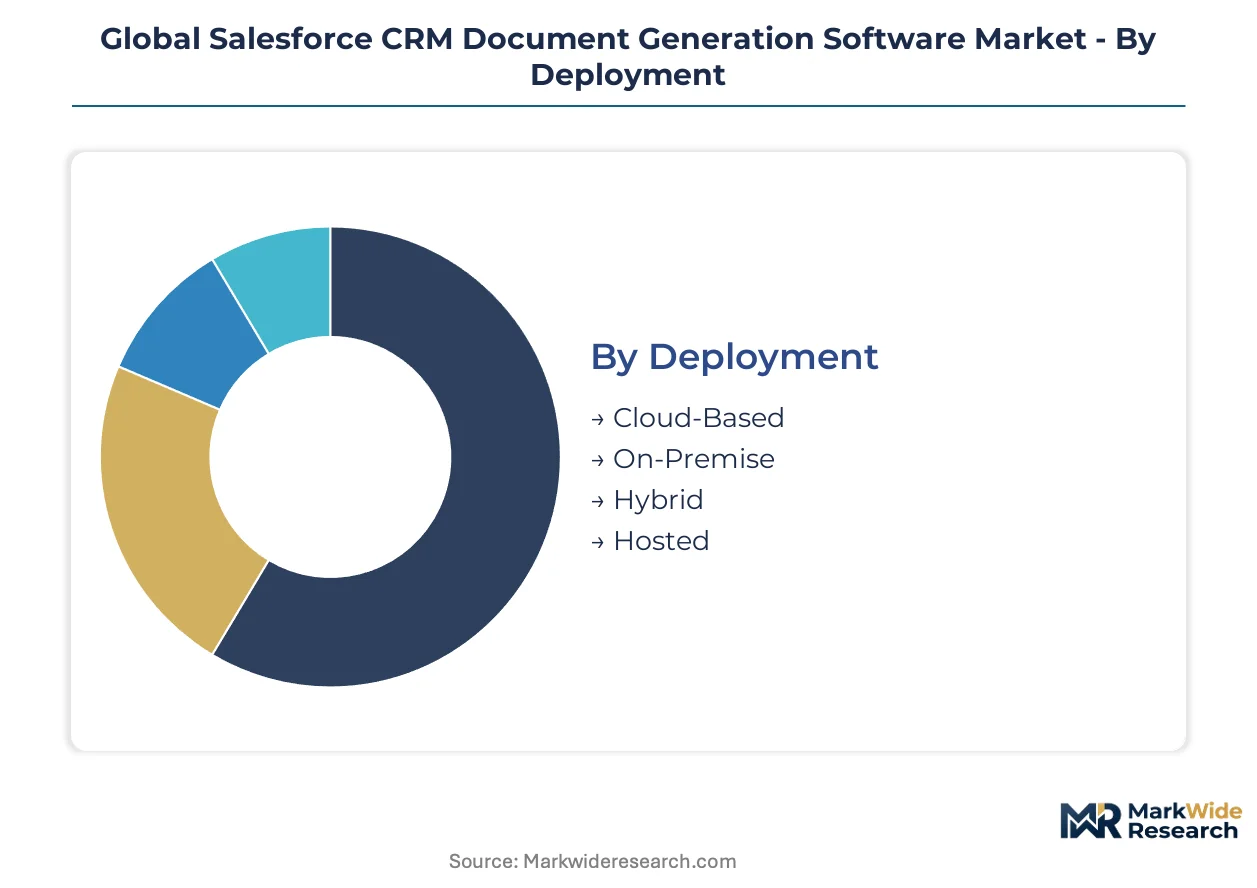
Segmentation in Salesforce CRM document generation software reveals how procurement priorities diverge across infrastructure preferences, workflow complexity, and compliance exposure. Vendors must align product architectures with the capital intensity and integration depth each segment demands.
Deployment:
Capital intensity varies sharply across deployment modes, with self-managed infrastructure demanding the heaviest upfront investment in hardware, security certification, and dedicated DevOps personnel.
- Cloud-Based:Multi-tenant SaaS architectures provision via Salesforce AppExchange or direct API integration, eliminating server procurement. Financial services firms in the United States and Germany concentrate demand here to satisfy SEC disclosure and EU AI Act audit mandates without owning infrastructure.
- On-Premise:Dedicated installations within corporate data centers require substantial capital expenditure for servers, backup systems, and compliance validation. Life sciences organizations under FDA 21 CFR Part 11 in the United States favor this model for direct control over validation documentation and computerized system qualification protocols.
- Hybrid:Split architectures keep sensitive contract data on-premise while routing non-critical workflows through cloud tiers. Appeals to mid-market manufacturers in India balancing PLI scheme export requirements with domestic data localization.
- Hosted:Single-tenant cloud deployments managed by third-party providers offer dedicated instances without internal infrastructure burden. Gaining traction among education institutions with limited IT staffing.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations.
Solution Type:
Margin concentration tracks workflow complexity, with solutions spanning multiple document touchpoints commanding premium pricing against single-purpose tools.
- Contract Management:Clause libraries, redlining workflows, and e-signature orchestration embedded within Salesforce record pages. Large enterprises in Germany and France prioritize these suites to consolidate vendor relationships and satisfy GDPR Article 30 records of processing.
- Proposal Automation:Real-time document assembly from configure-price-quote engines and live product catalogs. Technology providers in India and the United States adopt these systems to compress quote-to-close cycles and reduce sales operations headcount.
- Invoice Generation:Automated billing document creation tied to Salesforce Opportunity and Order objects. Standard offering with limited differentiation.
- Report Automation:Scheduled or triggered generation of compliance, sales, and operational reports. Regulatory filing requirements in the United States drive specialized demand.
- Compliance Documentation:Pre-formatted outputs for HIPAA, FDA, SEC, and EU AI Act submissions. Validation burden creates switching costs favoring established vendors.
Contract Management captures the largest margin pool. Proposal Automation is gaining share fastest.
End User:
Procurement sophistication scales with regulatory exposure, with heavily supervised industries demanding deeper audit trails and pre-certified architectures.
- Financial Services:Banks, insurers, and asset managers require explainable AI outputs for derivatives documentation and M&A closing sets. EU AI Act mandates in Germany and France are accelerating replacement of legacy systems.
- Telecommunications:Subscription billing and service agreement volume drives demand for high-throughput document generation. Indian carriers scaling under PLI scheme export obligations.
- Manufacturing Firms:Configure-price-quote convergence with ERP systems creates complex multi-object document assembly requirements. United States and German industrial exporters lead adoption.
- Technology Providers:Rapid implementation and API flexibility prioritize over compliance depth. Mid-market SaaS vendors in India favor lightweight managed-package solutions.
- Education Institutions:Grant documentation, enrollment agreements, and alumni communications at lower volume and complexity. Price-sensitive procurement patterns.
Financial Services accounts for the deepest implementation spend. Technology Providers are expanding most quickly.
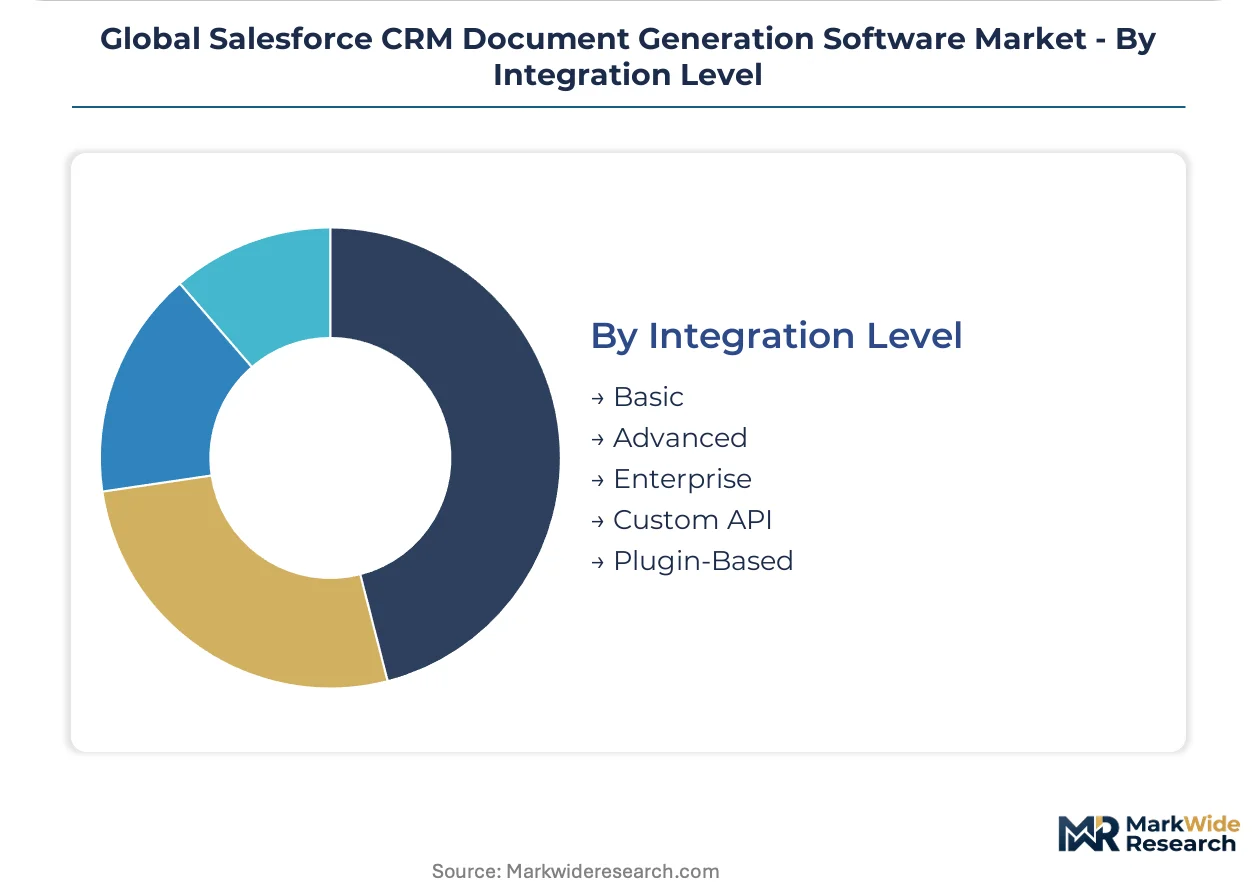
Integration Level:
Technical sophistication required for deployment rises with customization depth, determining whether implementations complete in weeks or quarters.
- Basic:Pre-built managed packages installed via AppExchange with minimal configuration. Appeals to smaller Salesforce orgs in India with limited Apex expertise.
- Advanced:Custom field mapping, Lightning Web Components, and workflow triggers requiring moderate development resources. Standard for mid-market manufacturers in Germany.
- Enterprise:Multi-org architectures, custom objects, and bi-directional sync with external CLM and ERP systems. Financial services firms in the United States demand this tier for system-of-record consolidation.
- Custom API:Direct REST and SOAP integration bypassing managed packages for maximum flexibility. Requires substantial professional services engagement.
- Plugin-Based:Third-party extension frameworks enabling rapid feature addition without core platform modification. Emerging preference among technology providers seeking composable architectures.
Enterprise integrations carry the highest professional services attach rates. Plugin-Based deployments are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States enterprise demand for Salesforce-native document automation outpaces German procurement velocity, while Indian mid-market adoption accelerates fastest among the three major concentration zones.
United States
Financial services firms in New York and Chicago are replacing legacy contract systems to satisfy SEC disclosure mandates for automated documentation. FDA 21 CFR Part 11 validation requirements drive life sciences procurement in Boston and San Francisco. Healthcare providers in the Pacific Northwest prioritize HIPAA-compliant architectures with pre-certified audit trails.
Germany
Automotive and industrial exporters in Stuttgart and Munich demand real-time document assembly from ERP-integrated configure-price-quote engines. EU AI Act explainability requirements reshape procurement criteria for Frankfurt banking consortia. Bavarian manufacturing clusters favor hybrid deployments balancing cloud agility with domestic data localization.
India
Domestic software vendors in Bangalore and Mumbai scale Salesforce-native capabilities to capture PLI scheme export obligations. Technology providers prioritize API-light managed packages reducing implementation timelines. Telecom carriers under TRAI oversight drive high-volume subscription billing document generation in Hyderabad and Chennai.
United Kingdom
London-based asset managers and insurers accelerate compliance documentation automation under FCA regulatory timelines. GDPR Article 30 records of processing requirements reshape legal department procurement priorities. Fintech clusters in Manchester and Edinburgh adopt proposal automation to compress quote-to-close cycles.
France
Parisian banking groups pilot AI-native clause intelligence for derivatives documentation under EU AI Act mandates. Pharmaceutical firms operating under ANSM oversight demand vendor-provided model cards for automated contract outputs. Lyon-based industrial software specialists integrate document generation with legacy ERP architectures.
Global Salesforce CRM Document Generation Software Market Competitive Landscape
Top-tier vendors anchor enterprise compliance suites, while mid-market specialists compete on deployment velocity and template accessibility. The vendor base stratifies across three functional tiers: full-stack contract lifecycle platforms, workflow-integrated document generators, and lightweight template tools. Consolidation pressure favors vendors with pre-certified healthcare and financial services architectures. Dominant competitive moves include strategic partnerships with Salesforce implementation consultancies and geographic expansion into Indian PLI scheme beneficiary zones.
Within the enterprise compliance tier, Conga and Nintex occupy positions reflecting deep Salesforce platform integration and workflow automation breadth respectively. S-Docs anchors the mid-market API-light deployment segment where smaller Salesforce orgs prioritize rapid implementation. SpringCM represents the document-centric workflow archetype with cloud-native infrastructure orientation.
| Leading Market Players |
|---|
| Conga |
| Nintex |
| SpringCM |
| DealHub |
| WebMerge |
| Windward Studios |
| S-Docs |
| Docomotion |
| Documill |
| Others |
Supply & Pricing Matrix
Apex developer scarcity in Bangalore and Hyderabad feeds directly into pricing-tier spreads, with labor-cost differentials between India and Germany creating three-band pricing structures that vendors exploit across enterprise, mid-market, and small-org segments.
Pricing Analysis
Bundled managed-package offerings with implementation services command premiums against unbundled template-only licenses. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with FDA 21 CFR Part 11 and EU AI Act validation tiers carrying substantial markups. Cost compression in the economy tier is intensifying because Indian PLI scheme beneficiaries are flooding mid-market channels with API-light alternatives. Small Salesforce orgs in India exhibit highest price sensitivity; German automotive exporters demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Salesforce platform infrastructure concentrated in United States data centers, creating concentration risk for global deployments. Development talent draws from India, Germany, and the United States, while cloud compute resources rest on AWS, Azure, and Google Cloud infrastructure. Regulatory restriction risk runs through evolving EU data localization mandates and Indian data residency requirements. Distribution runs through Salesforce AppExchange marketplace and direct API integration channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where procurement is shifting toward pre-certified compliance architectures that command premium pricing and resist commoditization pressure.
For Market Incumbents: Cement defensible positioning by acquiring niche compliance specialists with FDA and EU AI Act pre-certifications, and deepen upstream control over Salesforce implementation partner networks to lock channel access against emerging API-light competitors. For New Entrants and Emerging Players: Enter via white-space targets in Indian mid-market manufacturing under PLI scheme coverage and German hybrid deployment segments seeking domestic data localization. Penetrate through vertical-specific template libraries for life sciences and automotive verticals rather than horizontal feature parity. For Investors and Strategic Acquirers: Salesforce implementation consultancies and private equity firms with healthcare vertical expertise are the most active acquirer in this space. Long-term viability favors vendors with validated AI model architectures and multi-tenant cloud footprints across three or more regulatory jurisdictions. Watch FDA 21 CFR Part 11 audit failure rates as inflection indicator for compliance-suite switching costs.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification Investment | Validates algorithmic transparency for Frankfurt banking consortia and Parisian pharmaceutical firms. |
| Hybrid Deployment Architecture Launch | Captures Bavarian manufacturing demand balancing cloud agility with domestic data localization. |
| Strategic Partnership with Salesforce Implementation Consultancies | Locks channel access for mid-market deployments in Bangalore and Mumbai enterprise zones. |
| Acquisition of FDA 21 CFR Part 11 Specialist | Creates switching-cost moats among Boston and San Francisco life sciences clusters. |
| Geographic Expansion into Indian PLI Beneficiary Zones | Positions for domestic software vendor procurement budgets in Hyderabad and Chennai telecom corridors. |
Research Methodology
Direct dialogue with Salesforce platform engineers, IT procurement officers at financial services firms, legal operations directors, and channel integration specialists grounded this analysis. Secondary validation drew from SEC filings, Salesforce AppExchange metrics, EU regulatory disclosure databases, and Indian PLI scheme beneficiary registries. Bottom-up deployment counts and top-down enterprise IT spend estimates were triangulated to cross-check segment sizing.
Market value projections reflect modeled adoption curves across deployment mode, solution type, end-user vertical, and integration complexity tiers throughout the forecast period. CAGRs were derived from regression analysis against CRM modernization spend patterns and compliance mandate implementation timelines. Salesforce org growth rates and API consumption trajectories served as key forecast inputs.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in private vendor pricing disclosures and unreported pilot deployments introduce uncertainty bands around mid-market share estimates. Forecasts reflect documented assumptions regarding EU AI Act enforcement intensity and Salesforce platform API evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
APAC Loyalty Management Market
Customer Relationship Management (CRM)
Loyalty Management Market
Customer Relationship Management (CRM)
Enterprise Feedback Management Market
Customer Relationship Management (CRM)
Ipad CRM Market
Customer Relationship Management (CRM)
Client Onboarding Solutions Market
Customer Relationship Management (CRM)
Contact Centers Speech Applications Market
Customer Relationship Management (CRM)
Global Partner Relationship Management Market
Customer Relationship Management (CRM)
Mobile CRM Market
Customer Relationship Management (CRM)
Cloud Based Contact Center Market
Customer Relationship Management (CRM)
Customer Experience Management Market
Customer Relationship Management (CRM)
Global Saas Customer Relationship Management (CRM) Market
Customer Relationship Management (CRM)
Call Center Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Software Market
Customer Relationship Management (CRM)
Android CRM Software Market
Customer Relationship Management (CRM)
Loyalty Management Solutions Market
Customer Relationship Management (CRM)
Customer Experience Management (CEM) in Telecommunication Market