
 CGI Software Market | 2026-2036
CGI Software Market Size, Share, and Industry Trends Forecast 2026-2036
CGI Software Market Insights
Modular subscription bundling is pivoting how studios evaluate CGI software procurement, with buyers now mixing render engines, simulation tools, and real-time platforms rather than committing to monolithic suites. Autodesk Maya leverages its entrenched position in feature-film pipelines to sustain premium pricing for character animation workflows. Houdini specializes in procedural effects and competes aggressively for high-end visual effects market share against entrenched rivals. Blender occupies a distinctive position as a no-cost entry point, extending its footprint among independent creators and educational institutions worldwide.
Computer-generated imagery software encompasses digital tools for creating, manipulating, and rendering two-dimensional and three-dimensional visual content through polygonal modeling, shader-based material systems, and ray-traced or rasterized output pipelines. These platforms serve industrial and commercial purposes spanning entertainment production, architectural visualization, product design prototyping, and interactive simulation. Public cloud deployment now captures the fastest growth trajectory as studios seek elastic compute for burst rendering workloads without capital-intensive server farms. On-premises installations retain dominance among defense contractors and government agencies with stringent data sovereignty requirements. Hybrid cloud configurations increasingly attract mid-tier production houses balancing confidential asset storage with scalable cloud-based rendering.
FCC content guidelines and MPAA rating standards shape what CGI content reaches broadcast and theatrical distribution, directly influencing software feature development for editorial compliance tools. EMA and national European regulators enforce GDPR-mandated data handling protocols that constrain how cloud-based CGI platforms process creator assets across jurisdictions. ISO 27001 certification has become a de facto procurement gate for enterprise buyers evaluating vendor security postures. Stakeholders must weigh rendering architecture choices against evolving data-localization mandates and the accelerating shift toward real-time, game-engine-derived production methodologies.
Market Dynamics
The transition from offline rendering pipelines to real-time, game-engine-derived workflows is compressing production timelines and forcing vendors to re-architect licensing models around GPU virtualization standards.
Growth Catalysts
- ISO 27001 certification requirements:Enterprise buyers now mandate vendor security postures for cloud-based asset processing, accelerating platform consolidation toward certified providers.
- Media and entertainment studios:Real-time rendering pipelines replace traditional offline workflows, driving demand elasticity for burst compute capacity without capital-intensive server farms.
- Los Angeles production clusters:Concentrated talent pools and infrastructure investment anchor North American demand for high-fidelity character animation tools.
Market Restraints
- GPU supply concentration:Foundry capacity constraints and semiconductor export controls create procurement volatility for rendering hardware dependent on advanced node fabrication.
- GDPR-mandated data localization:Cross-border asset processing faces jurisdictional friction, limiting cloud deployment options for European creators working with US-based studios.
- Proprietary file format lock-in:Decades of accumulated project archives in vendor-specific formats raise switching costs and suppress competitive churn.
Strategic Opportunities
- India educational institutions:Blender's zero-cost entry point has cultivated a generation of trained operators, creating downstream commercial conversion potential for paid toolchains.
- Architectural visualization convergence:Real-time engines originally developed for entertainment now displace static renderers in building design review workflows.
- Hybrid cloud configurations:Mid-tier production houses seek architectures balancing confidential asset storage with elastic cloud-based rendering capacity.
Industry Challenges
- Pipeline integration complexity:Studios struggle to bridge legacy Maya-based character workflows with emerging Unreal Engine real-time environments without fragmenting production data.
- Specialized simulation talent scarcity:Houdini's procedural effects dominance has created a bottleneck of qualified technical directors capable of authoring production-grade VFX.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CGI Software Market |
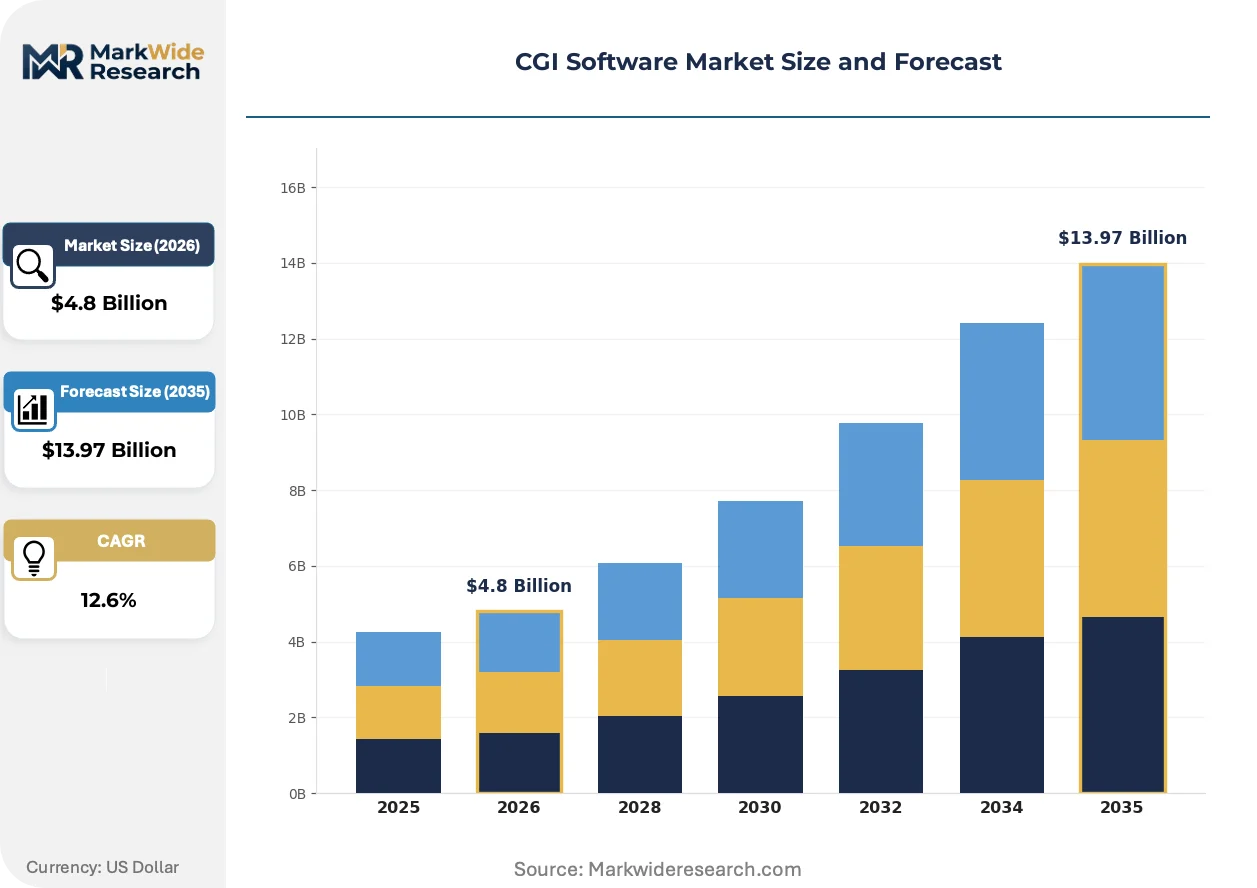
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Retailers, Healthcare Providers, Financial Services, Government Agencies Application Type: Data Analytics, Business Process Management, Customer Relationship Management, Enterprise Resource Planning Service Type: Consulting Services, Implementation Services, Maintenance Services, Training Services |
| Companies Covered | Autodesk Maya, Autodesk 3ds Max, Houdini, Unreal Engine, Unity, Blender, Cinema 4D, Arnold, V-Ray, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CGI Software Market Trends and Innovations
Real-time rendering architectures are compressing the boundary between production and post-production, enabling iterative creative decisions that were previously impossible under offline batch constraints.
Neural radiance fields (NeRF) are integrating volumetric scene reconstruction from sparse photographic capture into previsualization workflows. Automotive and architectural visualization teams adopt these tools for rapid environment prototyping. The technology is integrating photogrammetry pipelines with real-time lighting simulation, collapsing weeks of manual modeling into hours of automated reconstruction.
GDPR-mandated data handling protocols now constrain how cloud-based CGI platforms process creator assets across European jurisdictions. Studios operating multi-national productions must architect geographically segmented storage with jurisdictional access controls. German and French regulators enforce the strictest interpretations, forcing vendors to deploy region-locked infrastructure that increases operational overhead.
Subscription unbundling has fragmented how buyers assemble toolchains, with render engines, simulation modules, and real-time platforms now procured separately rather than as monolithic suites. Independent creators and small studios mix open-source foundations with commercial plugins, while enterprise buyers negotiate enterprise-wide access across previously distinct vendor relationships. This pattern is most visible in the United States, where Los Angeles and Austin production clusters have normalized multi-vendor pipeline architectures.
CGI Software Market Segmentation
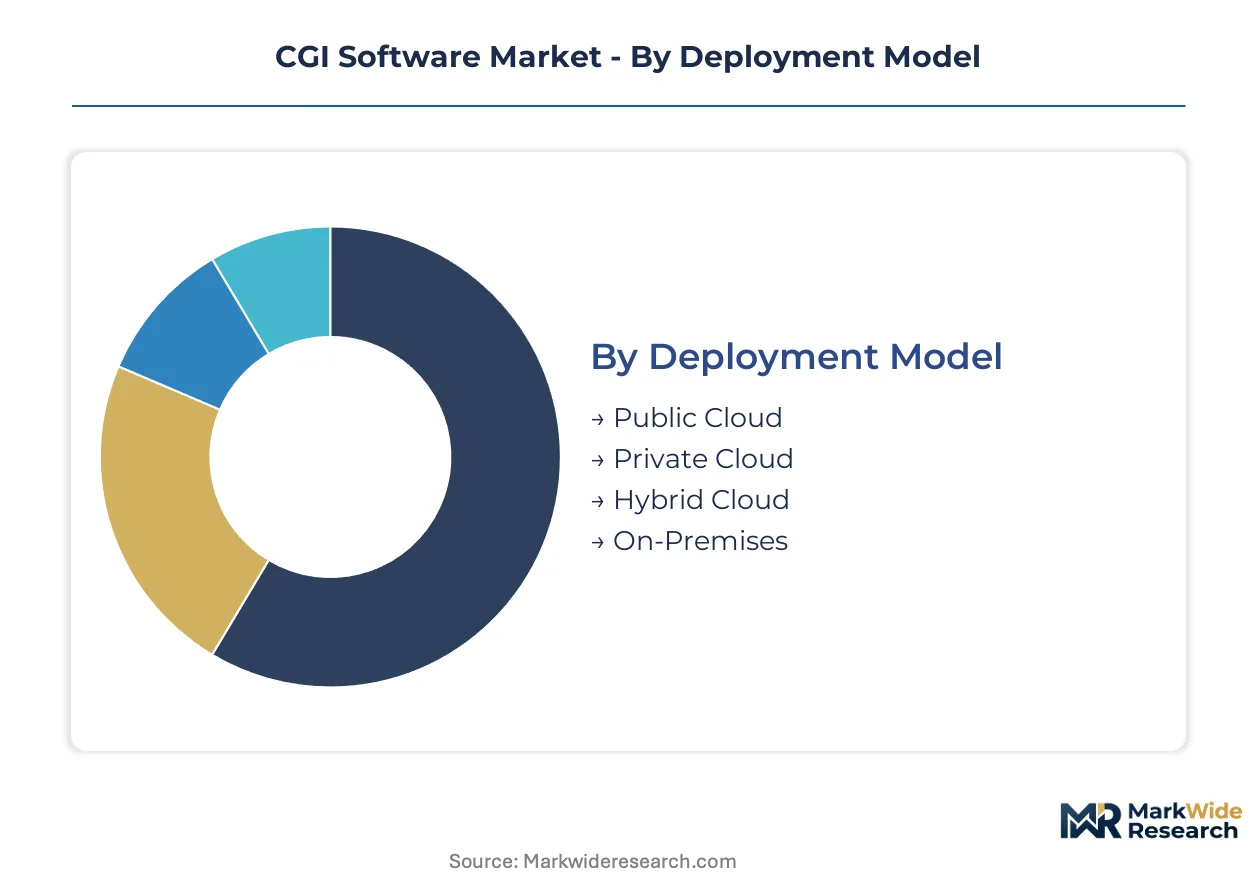
CGI software procurement patterns diverge sharply across deployment architectures and buyer sophistication levels. Certification requirements, data sovereignty mandates, and workflow integration complexity create distinct purchasing behaviors that vendors must navigate separately.
Deployment Model:
ISO 27001 certification governs public cloud and hybrid configurations most stringently, while on-premises installations face distinct compliance burdens around physical access controls and audit trails. EMA data-localization guidance shapes European deployment decisions differently than FCC cloud security frameworks affect US buyers.
- Public Cloud:Elastic compute pools enable burst rendering without capital-intensive server farms. Los Angeles production clusters drive concentrated demand for ISO 27001-certified public infrastructure that scales with project timelines.
- Hybrid Cloud:Mid-tier studios balance confidential asset storage on-premises with cloud-based rendering capacity. German regulators enforce strictest data-localization interpretations, forcing region-locked infrastructure that elevates operational overhead.
- Private Cloud:Dedicated tenant environments satisfy defense contractor security postures with single-occupancy guarantees.
- On-Premises:Government agencies mandate air-gapped installations with physical access logging and domestic hardware provenance.
Leading the category by volume: On-Premises among defense and government buyers. Growing fastest: Public Cloud as real-time pipelines displace offline workflows.
End User:
Buyer procurement sophistication spans from standardized RFP processes in financial services to creative-driven ad-hoc purchasing in entertainment-adjacent retail applications.
- Media and Entertainment Studios:Real-time rendering pipelines compress production timelines and demand GPU-virtualized licensing models. Los Angeles and Austin production clusters anchor North American demand for character animation toolchains.
- Healthcare Providers:HIPAA-compliant asset processing requires encrypted transmission and audit-logged access for patient visualization applications. The sector concentrates procurement in US metropolitan hospital networks with dedicated visualization departments.
- Architectural Visualization Firms:Building design review workflows displace static renderers with real-time engines.
- Government Agencies:Data sovereignty requirements mandate on-premises deployment with domestic supply chain verification.
Architecture and entertainment studios command premium pricing tiers. Healthcare visualization shows steepest expansion trajectory as surgical planning adoption accelerates.
Application Type:
Workflow integration depth determines whether buyers seek standalone tools or embedded modules within broader enterprise platforms.
- Character Animation:Polygonal rigging and motion capture pipelines sustain premium pricing for feature-film workflows. Autodesk Maya entrenches here through decades of accumulated project archives in proprietary formats.
- Procedural Effects Simulation:Houdini dominates fluid dynamics, destruction, and crowd systems through node-based authoring. Talent scarcity constrains production capacity as qualified technical directors command premium compensation.
- Architectural Visualization:Real-time engines displace static ray-traced output for client design reviews.
- Product Design Prototyping:Shader-based material systems enable photorealistic marketing imagery from engineering CAD sources.
Character animation captures largest revenue share. Procedural effects simulation gains share fastest as streaming content volume multiplies VFX shot counts.
Service Type:
Vendor profitability concentrates in recurring maintenance streams versus one-time implementation engagements.
- Implementation Services:Pipeline integration complexity drives substantial professional services revenue as studios bridge legacy Maya workflows with Unreal Engine environments. French system integrators specialize in GDPR-compliant European deployments.
- Training Services:Blender's educational penetration in India institutions cultivates operator pools that downstream convert to commercial toolchains. Autodesk and SideFX compete aggressively for certified training program accreditation.
- Consulting Services:Workflow architecture advisory supports multi-vendor toolchain assembly.
- Maintenance Services:Subscription bundles increasingly embed support rather than price separately.
Implementation services generate highest per-contract value. Training services expand most quickly as talent scarcity intensifies competitive hiring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates the largest consumption volume for CGI software, while production of rendering hardware concentrates in East Asian semiconductor foundries. This asymmetry shapes procurement patterns, with US studios driving demand for cloud-based elastic compute while Taiwan and South Korea supply the underlying GPU infrastructure.
United States
FCC content guidelines and MPAA rating standards directly influence software feature development for editorial compliance tools. Los Angeles production clusters anchor North American demand for high-fidelity character animation pipelines, with Austin emerging as a secondary hub for interactive content and real-time engine development.
Germany
Industrial visualization applications in automotive and manufacturing sustain strong demand for photorealistic rendering capabilities. German regulators enforce strictest GDPR interpretations, forcing vendors to deploy region-locked infrastructure that elevates operational overhead for cloud-based asset processing. Berlin and Munich host concentrated VFX post-production facilities serving European theatrical distribution.
United Kingdom
London's Soho district maintains historical dominance in feature-film visual effects post-production, driving premium-tier software procurement. UK Information Commissioner's Office guidance on international data transfers creates friction for studios collaborating across US-European productions. The British Film Institute certification requirements shape content workflows for domestic theatrical release.
India
Blender's zero-cost penetration across educational institutions has cultivated substantial operator pools with downstream commercial conversion potential. The country's national IT regulator mandates data localization for government-related visualization projects, constraining cloud deployment architectures. Mumbai and Hyderabad production facilities increasingly handle outsourced VFX work for Hollywood studios.
Japan
METI industrial policy supports domestic content creation infrastructure, including real-time rendering adoption for virtual production stages. Japanese animation studios maintain distinctive 2D-3D hybrid workflows that demand specialized software configurations. Tokyo and Osaka metropolitan areas concentrate both production facilities and technology vendor regional headquarters.
CGI Software Market Competitive Landscape
The competitive structure tilts toward diversified platform specialists with entrenched pipeline positions. Autodesk and SideFX maintain strongholds through decades of accumulated project archives in proprietary formats that raise switching costs. Three archetypes dominate: legacy suite vendors defending premium pricing through workflow integration, open-source challengers capturing price-sensitive entry segments, and game-engine platforms leveraging real-time architectures to displace offline renderers. Competitive moves center on GPU-virtualized licensing model innovation and strategic training program accreditation to address talent scarcity.
Within the entrenched-suite tier, Autodesk Maya and Autodesk 3ds Max represent the legacy vendor archetype, anchoring feature-film and broadcast animation pipelines through format lock-in and institutional training relationships. Houdini occupies a specialized position exemplifying the procedural-effects specialist archetype, commanding premium positioning where node-based technical direction differentiates output quality. Blender sits within the open-source disruption archetype, with its zero-cost model extending footprint among independent creators and educational institutions worldwide.
| Leading Market Players |
|---|
| Autodesk Maya |
| Autodesk 3ds Max |
| Houdini |
| Unreal Engine |
| Unity |
| Blender |
| Cinema 4D |
| Arnold |
| V-Ray |
| Others |
Pricing and Supply Chain Analysis
Real-time rendering pipeline migration simultaneously compresses cost economics and concentrates supply power among GPU virtualization-certified vendors. Cloud deployment architectures shift buyer expenditure from capital-intensive server farms toward elastic subscription models, redistributing margin capture across the value chain.
Pricing Analysis
Margin tightening in enterprise tiers reflects ISO 27001 certification overhead and GPU virtualization licensing complexity. Three-tier pricing structure across premium, standard, and economy levels segments by deployment architecture and support entanglement. Independent creators exhibit highest price sensitivity, gravitating toward Blender's zero-cost entry point, while defense contractors absorb premium pricing for air-gapped installations with domestic hardware provenance requirements.
Supply Chain Analysis
Direct-to-studio channels handle hyperscale production house demand, with value-added resellers serving mid-tier architectural visualization firms. Taiwan and South Korea anchor advanced node GPU fabrication, while the United States concentrates cloud infrastructure deployment. Foundry capacity constraints and semiconductor export controls introduce procurement volatility, with rendering hardware supply tethered to East Asian foundry scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 27001 certification requirements erect substantial compliance moats, privileging incumbent vendors with established security postures and forcing capital-constrained challengers toward partnership or acquisition pathways.
For Market Incumbents: Cement format lock-in defenses through expanded certified training programs at Indian educational institutions, neutralizing Blender's operator pipeline threat. Deepen backward integration into GPU virtualization standards development, ensuring licensing model control as real-time pipelines displace offline renderers. For New Entrants and Emerging Players: Capture white-space in hybrid cloud configuration tooling for mid-tier European studios grappling with GDPR-mandated data localization. Architectural visualization convergence presents the most penetrable segment, with building design review workflows seeking real-time engine alternatives to static ray-traced output. For Investors and Strategic Acquirers: Exit pathways concentrate in platform specialists with entrenched pipeline positions and accumulated project archive density. Acquisition targets should demonstrate ISO 27001 certification completion and established relationships with Los Angeles or Austin production clusters. Watch for inflection signals in GPU supply normalization, which would compress rendering hardware scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| GPU Virtualization Licensing Model Innovation | Autodesk and SideFX restructure subscription bundles around elastic compute consumption patterns. |
| ISO 27001 Certification Investment | Cloud vendors deploy region-locked infrastructure satisfying German and French regulator interpretations. |
| Educational Institution Partnership Expansion | Blender's Indian penetration cultivates operator pools with downstream commercial conversion potential. |
| Real-Time Engine Platform Integration | Unreal Engine bridges legacy Maya character workflows with emerging virtual production stages. |
| Procedural Effects Talent Pipeline Development | Houdini competes for technical director scarcity through accredited training program expansion. |
Research Methodology
Independent corroboration across VFX studio technical directors, cloud platform procurement officers, and educational institution program administrators underwrites the qualitative findings. Primary fieldwork encompassed pipeline integration specialists, GPU hardware supply chain managers, and regulatory compliance consultants across the United States, Germany, and India. Secondary validation drew from SEC filings of publicly traded software vendors, hyperscaler capex disclosures, and EMA data-localization guidance documents. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Comparable-period anchoring established historical baseline reference points spanning deployment model transitions and real-time pipeline adoption curves. The analytical framework modeled value trajectories across deployment architecture, end-user sophistication tier, application workflow depth, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion patterns, with specific inputs including GPU foundry capacity forecasts and streaming content volume projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor export control evolution and jurisdictional data-localization enforcement divergence. Base assumptions reflect continued real-time rendering displacement of offline workflows and sustained cloud infrastructure investment concentration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global 360 Degree Feedback Software Market
Software & Services
Systems Administration Management Tools Market
Software & Services
Engineering Software Market
Software & Services
Global Online Expense Management Software Market
Software & Services
SRM Software Market
Software & Services
Global Auto Dealer Software Market
Software & Services
3D Modeling Software Market
Software & Services
Programmable Automation Controller (PAC) Programming Software Market
Software & Services
Talent Acquisition Software Market
Software & Services
Software Construction Components Market
Software & Services
Parks and Playground Inspection Software Market
Software & Services
Global Email Management Software Market
Software & Services
Global Home Inspection Software Market
Software & Services
Legal Software Market
Software & Services
Global Catalog Management Systems Market
Software & Services
United Kingdom HR Payroll Software Market