
 Theatrical Distribution Software Market | 2026-2036
Theatrical Distribution Software Market Size, Share, and Industry Trends Forecast 2026-2036
Theatrical Distribution Software Market Analytics
Cloud-native architecture is realigning the economics of theatrical distribution platforms as on-premise legacy systems face displacement. FilmTrack leverages deep rights-management automation to anchor enterprise accounts across North American cinema circuits. FilmHub competes through filmmaker-direct distribution tools that bypass traditional gatekeepers. Cast & Crew Entertainment Services extends its position by integrating payroll and production finance with distribution workflows.
Theatrical distribution software encompasses platforms that manage film booking, rights clearance, revenue sharing, and exhibition analytics through centralized databases and API-connected theater networks. These systems process DCP (Digital Cinema Package) delivery confirmations, automate VPF (Virtual Print Fee) calculations, and synchronize showtime data across multiplex POS terminals. Rights Management Software dominates margin pools due to complex territorial licensing and residual tracking requirements, while Analytics Tools represents the fastest-growing category as exhibitors demand real-time attendance forecasting and dynamic pricing engines. Cloud-Based deployment leads volume adoption among mid-market cinema chains seeking reduced IT overhead.
The FCC governs broadcast and digital transmission standards affecting theatrical window streaming overlap in the United States. The EU's Digital Services Act and GDPR impose content transparency and data handling obligations on distributors operating across European markets. Theater operators and software vendors must monitor how emerging AI disclosure requirements reshape metadata standards and automated rights-matching protocols.
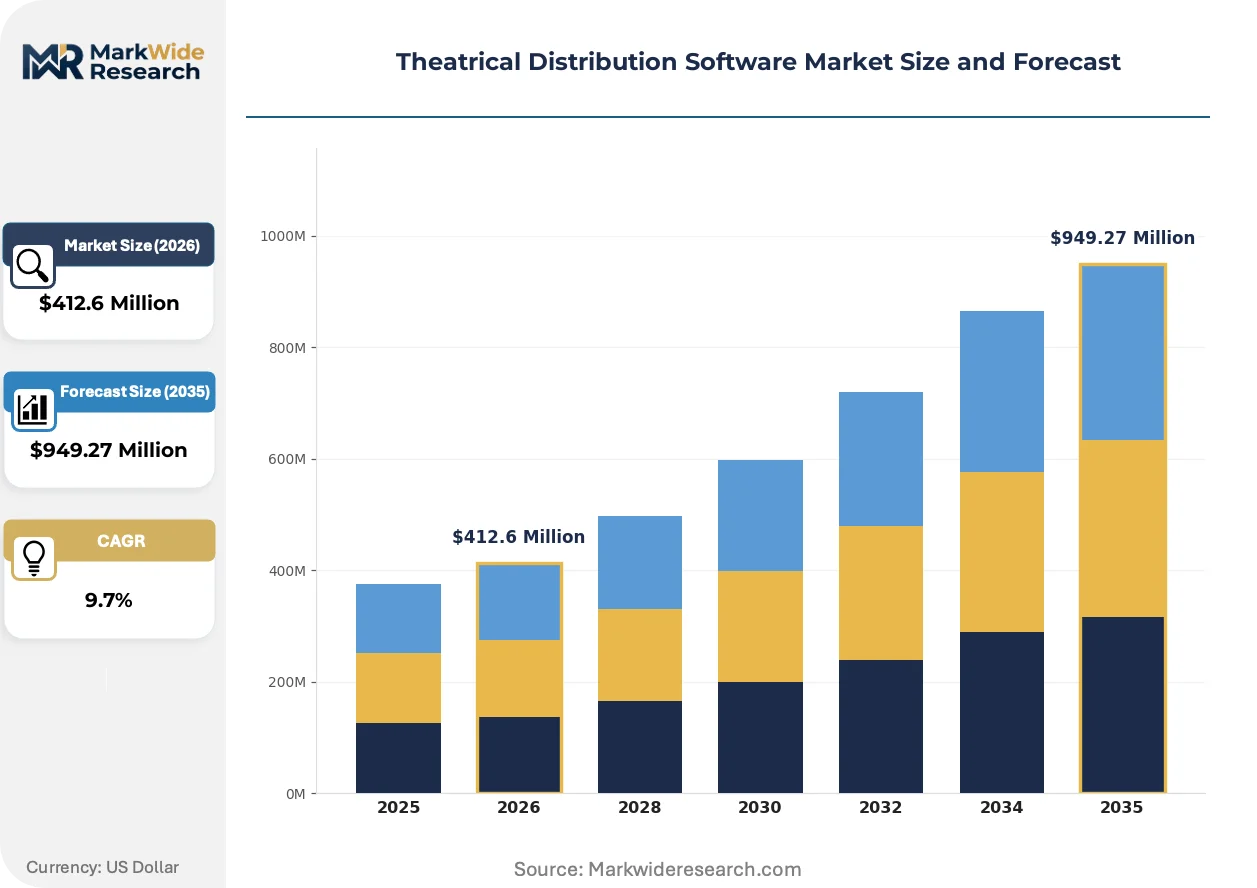
Market Dynamics
Cloud-native booking platforms are displacing on-premise legacy systems across cinema chains, compressing IT overhead while demanding new API standards for theater network synchronization.
Growth Catalysts
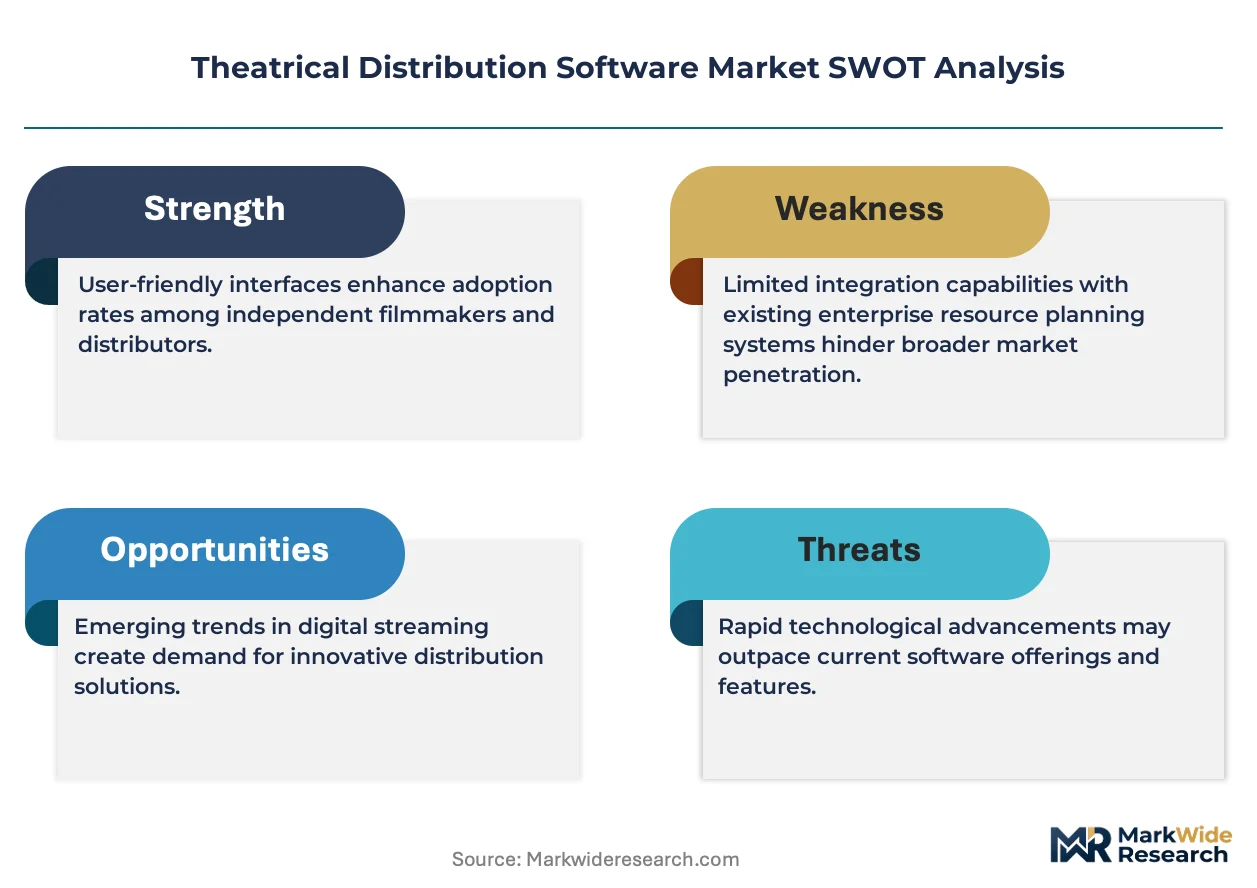
- EU Digital Services Act:Content licensing transparency mandates are forcing distributors to upgrade rights-tracking infrastructure, expanding software addressable market.
- Virtual Print Fee automation:Theater circuits are adopting platforms that calculate VPF splits between distributors and exhibitors, reducing manual reconciliation.
- India multiplex expansion:Tier-2 and Tier-3 cities are building new cinema complexes requiring integrated booking and analytics systems.
Market Restraints
- Legacy system lock-in:Major US theater operators face high switching costs from decades-old mainframe booking databases.
- DCP delivery infrastructure concentration:Satellite and fiber distribution networks for Digital Cinema Packages depend on a limited set of specialized providers.
- GDPR compliance friction:EU data handling requirements add development overhead for analytics tools processing patron behavior data.
Strategic Opportunities
- AI-driven dynamic pricing:Convergence of machine learning and real-time attendance forecasting enables per-show revenue optimization.
- Saudi Arabia cinema buildout:Post-2018 theater liberalization creates greenfield demand for full-stack distribution platforms.
- Residual rights automation:Union and guild payment calculations represent an underpenetrated workflow ripe for software substitution.
Industry Challenges
- Cinema technology talent scarcity:Engineers with expertise in both film distribution workflows and modern cloud architecture command premium compensation.
- API standardization delays:Theater POS terminals from different manufacturers use incompatible data formats, complicating integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Theatrical Distribution Software Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $949.27 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Theatrical Booking System, Rights Management Software, Box Office Management, Analytics Tools Customer Type: Cinema Chains, Independent Theaters, Film Distributors, Streaming Services Deployment: Cloud-Based, On-Premise, Hybrid Solutions, Mobile Platforms End User: Film Producers, Distributors, Theater Operators, Marketers |
| Companies Covered | FilmTrack, FilmHub, FilmChain, RightsTrade, Distrify, Eventive, Cast & Crew Entertainment Services, GCC Production, WriterDuet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Theatrical Distribution Software Market Evolving Landscape
Artificial intelligence and real-time data pipelines are compressing decision cycles in theatrical exhibition, shifting competitive advantage toward platforms with predictive capabilities.
Unified rights-management platforms are unifying previously separate workflows for territorial licensing, residual tracking, and windowing strategy. Mid-market distributors are adopting these systems fastest, seeking to match enterprise-grade automation without dedicated legal operations staff. This unification is compressing the competitive gap between major studios and agile independents.
GDPR and the EU Digital Services Act are imposing granular content transparency and data portability obligations on distributors operating across European markets. Theater operators must now maintain auditable chains of custody for audience measurement data. Analytics tools with built-in privacy-by-design architecture are capturing preference share in Germany, France, and the Netherlands.
Exhibitor procurement is compressing vendor relationships from multi-year enterprise licenses toward modular SaaS subscriptions with usage-based pricing. Theater chains are unbundling after-sales support and self-managing routine configuration. This shift is most visible in the United States, where consolidated circuits like AMC and Regal are insourcing platform administration.
Theatrical Distribution Software Market Segmentation
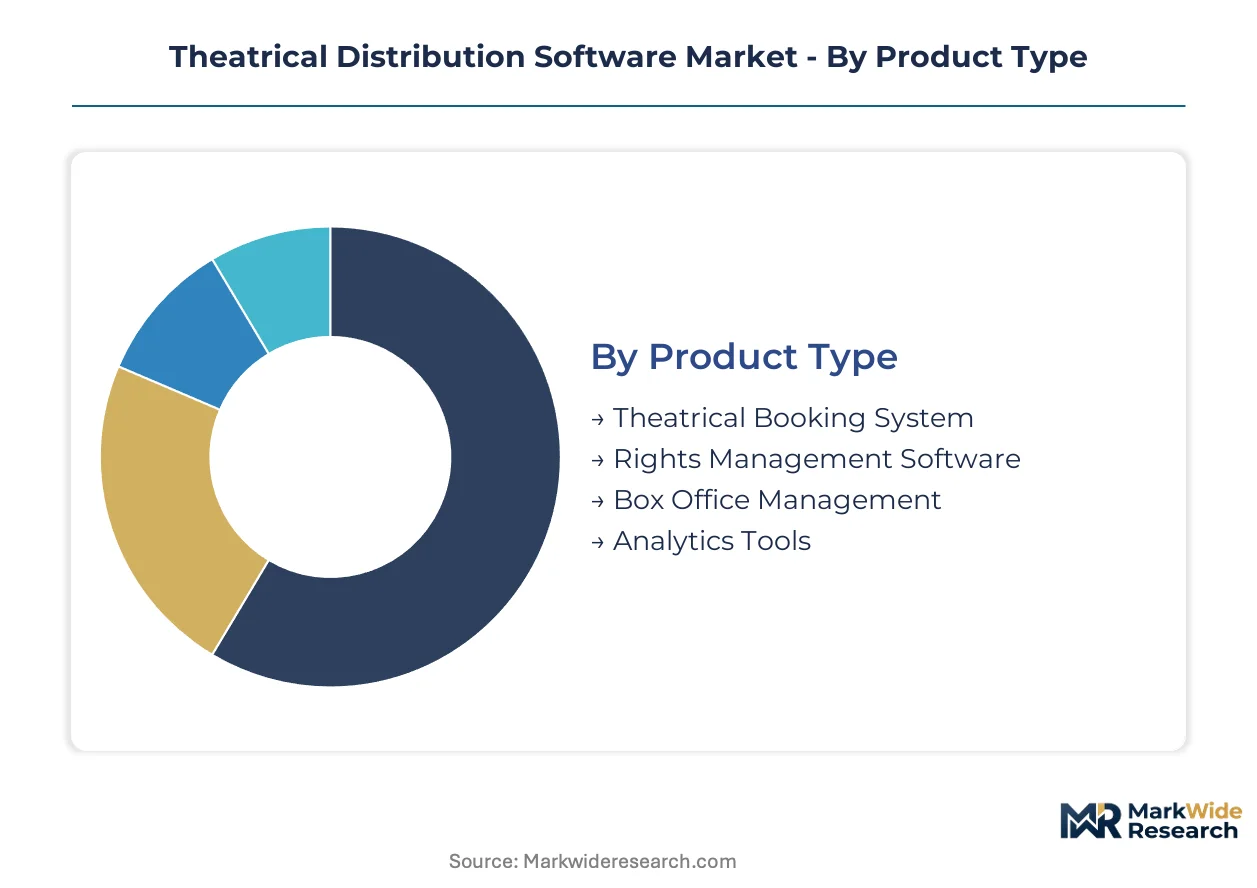
Theatrical distribution software segments reflect divergent capital requirements and workflow complexity across the exhibition value chain. Product architecture, customer scale, and deployment infrastructure each create distinct investment profiles and vendor selection criteria.
Product Type:
Rights Management Software demands the heaviest upfront engineering investment due to multi-territorial licensing logic and residual calculation engines.
- Rights Management Software:Platforms automate territorial licensing, windowing strategy, and guild residual tracking through centralized contract databases. Major studios in the United States deploy these systems to manage thousands of simultaneous licensing agreements across fragmented international markets. Complex residual calculations for union and guild payments drive premium pricing tiers.
- Analytics Tools:Real-time attendance forecasting and dynamic pricing engines process POS terminal feeds and external data signals. Theater operators in Germany and France prioritize these tools to optimize per-screen revenue as admissions fluctuate seasonally. GDPR-compliant privacy architecture adds development overhead but unlocks European market access.
- Theatrical Booking System:Core platforms managing film scheduling, screen allocation, and distributor-exhibitor communication protocols.
- Box Office Management:Revenue reconciliation systems tracking ticket sales, concession integration, and split calculations between venues and distributors.
Rights Management Software absorbs the bulk of installed capacity; Analytics Tools are expanding most quickly.
Customer Type:
Volume concentration varies sharply by customer scale, with consolidated circuits commanding platform customization while independents drive SaaS standardization.
- Cinema Chains:Multi-location operators require enterprise-grade booking synchronization and centralized analytics dashboards. AMC and Regal in the United States negotiate dedicated implementation teams and API customization. Consolidation among US circuits is compressing vendor counts per procurement cycle.
- Film Distributors:Studios and independents need rights-clearance workflows spanning theatrical, streaming, and physical windows. Distributors operating under EU Digital Services Act transparency mandates face upgraded compliance requirements. Automated metadata matching reduces manual legal review hours.
- Independent Theaters:Single-screen and small-chain venues favor modular subscriptions with minimal IT overhead.
- Streaming Services:Day-and-date release strategies require hybrid theatrical-digital rights management infrastructure.
Cinema Chains represent the dominant revenue pool; Streaming Services are climbing the fastest as windowing strategies converge.
Deployment:
Cloud migration economics favor mid-market chains seeking to eliminate data center maintenance while preserving customization flexibility.
- Cloud-Based:SaaS platforms eliminate server hardware capital expenditure and accelerate feature deployment through continuous integration pipelines. Mid-market chains across India and Saudi Arabia adopt these systems to scale rapidly without dedicated IT staff. Subscription pricing aligns costs with screen count fluctuations.
- Hybrid Solutions:Architectures combining cloud analytics with on-premise booking databases address latency-sensitive POS terminal integration. European exhibitors facing GDPR data residency requirements deploy hybrid stacks to keep patron records within jurisdictional boundaries. This approach bridges legacy infrastructure with modern API connectivity.
- On-Premise:Legacy mainframe systems retained by major US operators with decades of historical booking data.
- Mobile Platforms:Manager-facing applications for real-time schedule adjustments and revenue monitoring.
Cloud-Based deployment claims the largest share of new installations; Hybrid Solutions are gaining share fastest among compliance-conscious European operators.
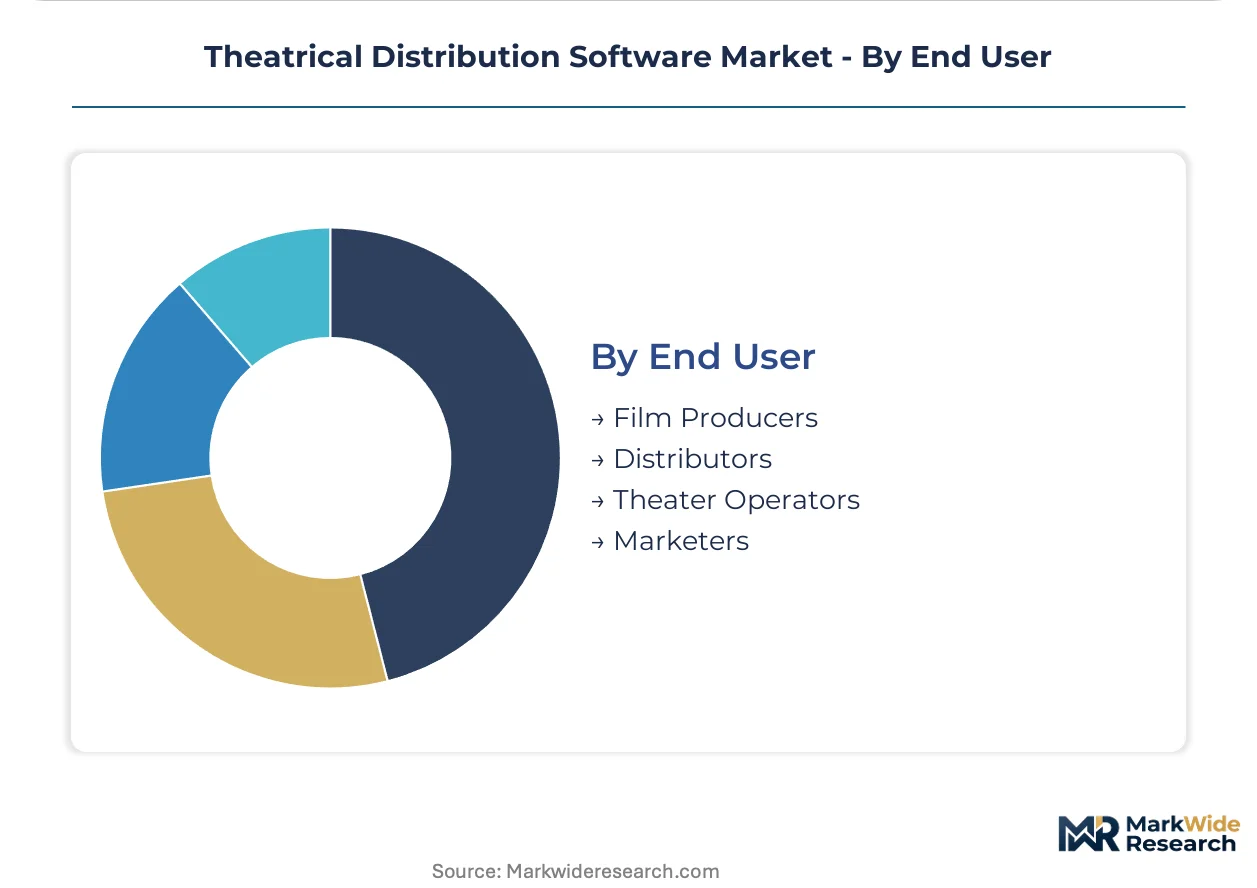
End User:
Workflow integration depth determines platform stickiness, with distributors and theater operators representing the most entrenched user bases.
- Distributors:Rights-holding entities require end-to-end visibility from production delivery through exhibition revenue recognition. Major studios in the United States integrate these platforms with production finance and talent payment systems. Virtual Print Fee automation reduces quarterly reconciliation cycles with exhibitor partners.
- Theater Operators:Exhibition companies prioritize real-time scheduling flexibility and competitive intelligence on rival programming. Multiplex operators in India leverage analytics tools to optimize regional language versus Hollywood content splits per location. Dynamic pricing engines respond to local events and weather patterns.
- Film Producers:Content creators accessing distribution dashboards for release strategy input and revenue tracking.
- Marketers:Campaign teams utilizing attendance forecasts to optimize media spend timing and geographic targeting.
Theater Operators anchor the installed base; Marketers are expanding most quickly as predictive analytics reshape campaign planning cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States cinema circuits anchor software procurement volume as consolidated operators modernize legacy booking infrastructure. Major theater chains in California and Texas drive enterprise platform adoption. European distributors face compliance-driven upgrade cycles under the EU Digital Services Act.
United States
AMC and Regal operate consolidated technology stacks across thousands of screens, demanding API customization and dedicated implementation support. The FCC governs broadcast and digital transmission standards affecting theatrical window streaming overlap. Los Angeles-based distributors integrate rights management with production finance systems for end-to-end workflow visibility.
Germany
Multiplex operators prioritize GDPR-compliant analytics tools to optimize per-screen revenue amid seasonal admission fluctuations. The Digital Services Act imposes granular content transparency obligations on distributors serving German markets. Berlin and Munich host clusters of independent theaters adopting modular SaaS subscriptions with privacy-by-design architecture.
India
Tier-2 and Tier-3 cities are building new cinema complexes requiring integrated booking and analytics systems at scale. The central bank's payment infrastructure standards influence concession and ticketing integration protocols. Mumbai and Bangalore anchor distributor operations serving regional language and Hollywood content splits across expanding multiplex networks.
Saudi Arabia
Post-2018 theater liberalization creates greenfield demand for full-stack distribution platforms without legacy system burden. The General Authority for Media Regulation establishes content licensing frameworks requiring auditable rights-tracking infrastructure. Riyadh and Jeddah concentrate cinema construction activity as operators deploy cloud-native systems from inception.
United Kingdom
Independent distributors adopt unified rights-management platforms to match enterprise-grade automation without dedicated legal operations staff. The Information Commissioner's Office enforces GDPR data handling requirements on patron behavior analytics. London's Soho district clusters film distribution headquarters where automated metadata matching reduces manual legal review hours.
Theatrical Distribution Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise-grade rights management platforms commanding premium positioning against filmmaker-direct distribution tools. The vendor base concentrates around three strategic archetypes: legacy enterprise suites, cloud-native challengers, and filmmaker-centric bypass platforms. Major circuits consolidate vendor relationships through multi-year enterprise licenses while independents drive SaaS standardization. Competitive moves center on API standardization alliances and residual calculation engine development.
Within the enterprise tier, FilmTrack and Cast & Crew Entertainment Services occupy positions anchored to North American cinema circuit procurement cycles. FilmHub exemplifies the filmmaker-direct archetype, representing tools that bypass traditional distribution gatekeepers. These three companies illustrate the market's structural division between consolidated operator infrastructure and independent creator empowerment.
| Leading Market Players |
|---|
| FilmTrack |
| FilmHub |
| FilmChain |
| RightsTrade |
| Distrify |
| Eventive |
| Cast & Crew Entertainment Services |
| GCC Production |
| WriterDuet |
| Others |
Value Network & Pricing Analysis
Cloud architecture engineers with cinema workflow expertise in Los Angeles and London command compensation premiums that compress margin spreads between enterprise and mid-market pricing tiers. Labor scarcity in this specialized talent pool forces vendors to tier pricing aggressively, with premium implementations absorbing these costs while standardized SaaS offerings sacrifice customization depth.
Pricing Analysis
Volume concentrates in standardized SaaS subscriptions while margins pool in enterprise rights-management deployments with dedicated implementation teams. Pricing stratifies across premium, standard, and economy tiers based on customization depth and API integration complexity, with GDPR-compliant privacy architecture adding a certification-grade premium for European markets. Cost compression in the mid-market tier is intensifying because theater chains are unbundling after-sales support and self-managing configuration. Independent theaters and small-chain venues exhibit the highest price sensitivity, while consolidated US circuits like AMC and Regal demonstrate lowest sensitivity due to procurement scale and dedicated vendor relationships.
Supply Chain Analysis
Returns and refurbishment flows for legacy on-premise hardware create reverse-logistics complexity as cinema chains decommission mainframe booking systems. Software development centers in the United States, India, and Germany anchor platform engineering, with specialized DCP delivery infrastructure concentrated among satellite and fiber providers in North America and Western Europe. The supply chain rests on cloud service providers, API middleware vendors, and theater POS terminal manufacturers as critical inputs. Single-source vulnerability in DCP distribution networks poses structural risk for exhibitors dependent on timely digital package delivery. Distribution runs through direct vendor relationships with major cinema chains and channel partnerships with regional system integrators serving independent theaters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Theatrical distribution software sits in a technology-transition phase as cloud-native platforms displace decades-old on-premise booking infrastructure. API-connected theater networks and real-time analytics pipelines are replacing legacy mainframe databases.
For Market Incumbents: Deploy residual calculation engine development to deepen workflow stickiness against filmmaker-direct distribution tools. Incumbents should consolidate API standardization alliances with POS terminal manufacturers to lock in theater network connectivity, while accelerating privacy-by-design architecture investment to capture EU Digital Services Act compliance-driven upgrade cycles before cloud-native challengers establish beachheads. For New Entrants and Emerging Players: The EU Digital Services Act in Europe opens a window for rights-tracking platforms with built-in transparency automation. New entrants should target Saudi Arabia's greenfield cinema buildout with full-stack cloud-native offerings unburdened by legacy migration complexity, and pursue India multiplex expansion in Tier-2 and Tier-3 cities through usage-based SaaS pricing aligned with screen count fluctuations. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid deployment specialists given GDPR data residency requirements driving European theater operator procurement. Long-term viability favors platforms with predictive analytics capabilities and AI-driven dynamic pricing engines. Investors should monitor API standardization progress and theater POS terminal integration velocity as inflection indicators for platform scalability and market penetration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying rights management with production finance systems reduces quarterly reconciliation cycles for major studios. |
| Strategic Partnership | API alliances with POS terminal manufacturers resolve data format incompatibility blocking theater network synchronization. |
| Geographic Expansion | Saudi Arabia greenfield deployment avoids legacy migration costs and captures post-2018 theater liberalization demand. |
| Acquisition of Specialist Firm | Residual calculation engine targets underpenetrated union and guild payment workflows ripe for software substitution. |
| Product Launch | AI-driven dynamic pricing tools enable per-show revenue optimization through real-time attendance forecasting. |
Research Methodology
Independent corroboration across distributor licensing executives, theater chain CTOs, and cinema technology procurement officers underwrites the qualitative findings in this study. Primary interviews with platform engineers, rights-management specialists, and exhibition operations directors were combined with secondary validation from SEC filings, EU regulatory disclosure databases, and theater industry trade association reports. Bottom-up screen-count modeling and top-down market sizing triangulate volume estimates across the analysis window.
Historical reference periods anchored the forecast window to pre-pandemic exhibition patterns and post-recovery technology upgrade cycles. The analytical framework modeled deployment model, customer scale, and regional adoption pattern as core segmentation dimensions, with integration complexity and regulatory compliance architecture as industry-specific forecast inputs. CAGRs were derived from trend extrapolation adjusted for technology substitution rates and capital expenditure cycles in cinema infrastructure.
The model assumes a particular technology adoption path; alternative pathways for cloud-native platform migration would alter the outlook if legacy system lock-in proves more persistent than projected. Forecasts reflect assumptions about API standardization timelines and GDPR enforcement intensity. Practitioners should monitor theater POS terminal integration velocity and AI disclosure requirement developments for early signals of platform competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Chatbot Builder Software Market
Software & Services
Construction Suites Software Market
Software & Services
Software As a Service (Saas) Market
Software & Services
Disk Space Analyzer Software Market
Software & Services
Identity Resolution Software Market
Software & Services
Landscaping Engineering Software Market
Software & Services
Self-Storage Software Market
Software & Services
ELD Compliance Software Market
Software & Services
Social Software As a Collaborative ERP Tool Market
Software & Services
Global Application Release Automation Market
Software & Services
App Uninstall Software Market
Software & Services
Spain HR Payroll Software Market
Software & Services
Global CMDB Software Market
Software & Services
Apache Spark Market
Software & Services
Emotion Recognition and Sentiment Analysis Software Market
Software & Services
Fiber Simulation Software Market