
 Global Decision Making Software Market | 2026-2036
Global Decision Making Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Decision Making Software Market Foresight
Direct enterprise sales channels for decision making software is narrowing as platform vendors consolidate partner ecosystems and prioritize API-first distribution. SAP SE leverages its embedded analytics within ERP workflows to sustain renewal rates among manufacturing clients. IBM anchors its position through specialized prescriptive analytics for financial services compliance. Oracle competes by extending autonomous database features into real-time decision pipelines for energy corporations.
Decision making software comprises algorithmic platforms that process structured and unstructured data through machine learning models, statistical engines, and rule-based systems to generate actionable recommendations or automated choices. These systems typically operate with sub-second inference latency and integrate via REST APIs or native connectors into enterprise resource planning and customer relationship management environments. Cloud-based deployment leads current adoption due to elastic compute scaling for model training workloads, while prescriptive analytics represents the fastest-expanding solution type as organizations seek optimization outputs rather than retrospective reporting. Diagnostic analytics retains mature demand in regulated sectors requiring audit trails for human-reviewable decision logic.
The EU AI Act and GDPR impose conformity assessments and explainability mandates on automated decision systems processing personal data, compelling vendors to embed interpretability modules. The US SEC and FDA maintain separate oversight frameworks for algorithmic trading decisions and clinical diagnostic software respectively, fragmenting compliance architecture across jurisdictions. Stakeholders must evaluate whether platform investments accommodate evolving cross-border algorithmic accountability standards before committing to multi-year deployment roadmaps.
Market Dynamics
Cloud-native inference architectures are compressing deployment timelines for prescriptive analytics, forcing vendors to restructure pricing models around consumption-based metering rather than perpetual licenses.
Growth Catalysts
- EU AI Act Conformity Requirements:Mandates for explainable automated decisions are compelling financial services and healthcare providers to upgrade legacy rule-based systems, expanding the addressable base for interpretable ML platforms.
- Elastic Compute Scaling:Cloud infrastructure providers are reducing training costs for optimization models, enabling mid-market manufacturers to deploy supply chain decision engines previously accessible only to large enterprises.
- FDA Algorithmic Oversight:Clinical diagnostic software regulations are standardizing validation protocols, reducing procurement friction for hospital systems evaluating AI-assisted treatment recommendation tools.
Market Restraints
- GPU Supply Concentration:Taiwan-based foundry capacity constraints for specialized AI accelerators are extending lead times for on-premise deployment of large-scale optimization models.
- Cross-Border Data Localization:China's data security laws and Russia's sovereign internet requirements are fragmenting cloud architectures, raising compliance costs for vendors operating multi-region inference pipelines.
- Interpretability Overhead:Regulatory explainability mandates in the EU and proposed US algorithmic accountability frameworks are adding development cycles that delay product releases.
Strategic Opportunities
- India Manufacturing Digitization:PLI scheme incentives for advanced process control are creating first-mover advantages for prescriptive analytics vendors targeting automotive and electronics clusters in Tamil Nadu and Gujarat.
- Edge Inference Convergence:Integration of lightweight neural networks with industrial IoT sensors is enabling real-time quality control decisions without cloud dependency, opening asset-heavy sectors previously blocked by latency constraints.
- API-First Distribution:Embedded finance and embedded insurance platforms are creating indirect channels for decision engines to reach small business borrowers through banking-as-a-service intermediaries.
Industry Challenges
- ML Operations Talent Scarcity:Shortages of engineers capable of maintaining production inference pipelines at sub-second latency are forcing vendors to absorb training costs or compromise reliability commitments.
- Legacy ERP Integration Complexity:Custom connector development for decades-old manufacturing execution systems consumes implementation resources that vendors struggle to recover under subscription pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Decision Making Software Market |
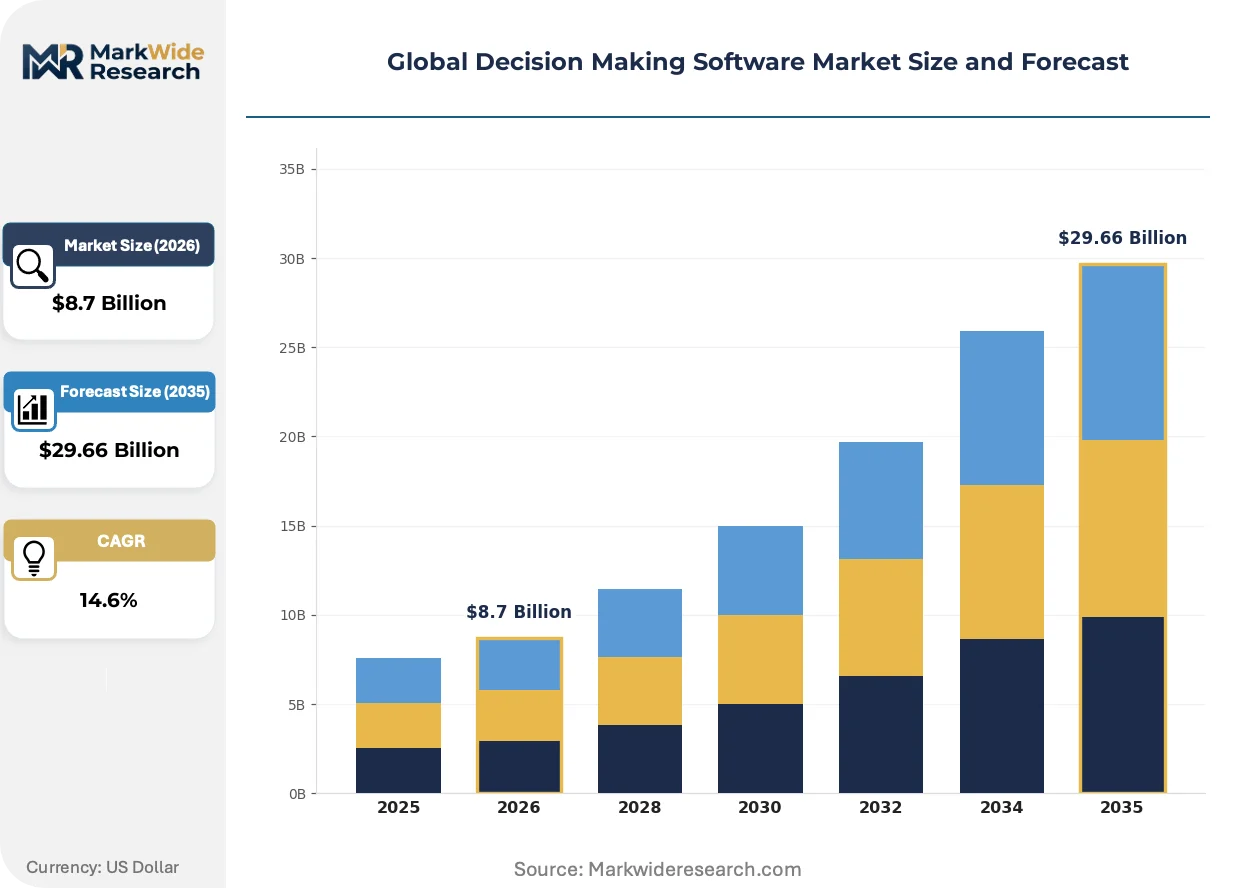
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services Solution Type: Predictive Analytics, Prescriptive Analytics, Descriptive Analytics, Diagnostic Analytics Application: Risk Management, Customer Insights, Supply Chain Optimization, Financial Planning End User: Financial Services, Manufacturing Firms, Telecommunications Providers, Energy Corporations |
| Companies Covered | SAP SE, IBM, FICO, Oracle, TIBCO Software, Microsoft, Google, QLIK TECHNOLOGIES, Information Builders, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Decision Making Software Market Shifts & Advancements
Neuro-symbolic architectures are bridging the gap between statistical pattern recognition and auditable decision logic, reshaping how regulated industries evaluate platform procurement.
Graph neural networks for supply chain optimization are digitizing multi-tier supplier relationship mapping previously managed through spreadsheet-based heuristics. Automotive and aerospace manufacturers in Germany and Japan are piloting these systems for disruption risk quantification. The technology is digitizing procurement workflows by embedding predictive scenarios directly into ERP requisition processes, compressing supplier evaluation cycles from weeks to hours.
The EU AI Act's risk-based classification system is mandating conformity assessments for high-stakes automated decisions in credit, employment, and healthcare. Vendors must now document training data provenance and model performance metrics for notified body review. Financial services institutions in France and the Netherlands are responding by establishing internal algorithmic audit functions ahead of enforcement deadlines.
Buyers are unbundling implementation services from software subscriptions, treating decision engine deployment as discrete professional services engagements. Systems integrators and boutique analytics consultancies are capturing margin previously retained by platform vendors. This pattern is most pronounced in the United States, where enterprise procurement teams with mature data science capabilities prefer to manage model operationalization internally.
Global Decision Making Software Market Segmentation
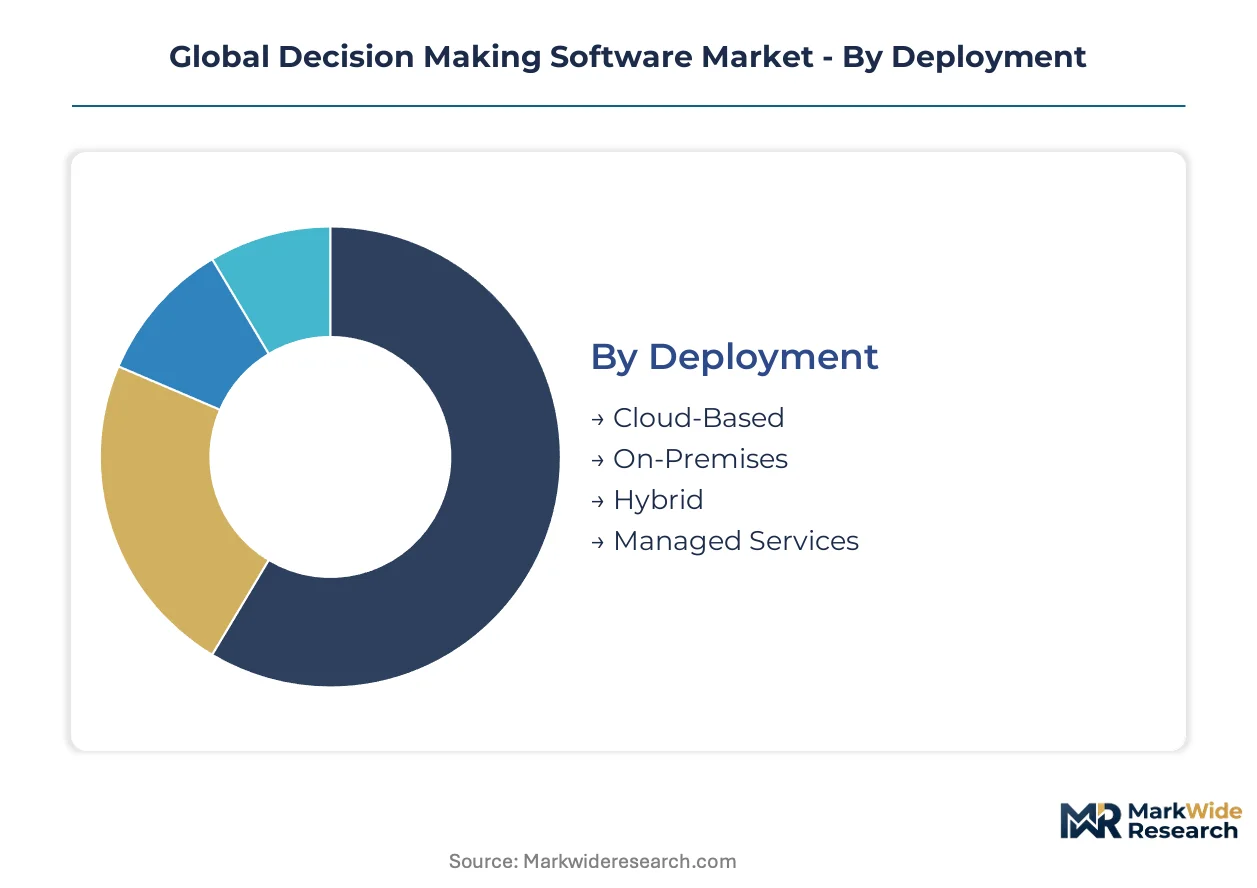
Segmentation in decision making software reveals distinct procurement patterns across deployment architectures, analytical methodologies, and vertical use cases. Buyers prioritize different capability bundles based on regulatory exposure, data sovereignty requirements, and legacy system entanglement.
Deployment:
Use-case spectrum spans from latency-sensitive manufacturing floors to distributed financial services networks with stringent audit requirements.
- Cloud-Based:Elastic compute pools enable training of large optimization models without capital expenditure. Financial services firms in the United States concentrate procurement here for credit risk engines requiring rapid scaling during stress-testing cycles.
- On-Premises:Air-gapped inference environments process sensitive data within facility perimeters. Energy corporations operating critical infrastructure in Germany and Saudi Arabia mandate this architecture for operational technology integration.
- Hybrid:Split workloads train models in cloud environments while executing inference locally. Manufacturing firms with multi-site quality control networks deploy this pattern to balance latency against centralized model governance.
- Managed Services:Third-party operators maintain infrastructure and model operations under service-level agreements. Mid-market enterprises lacking ML operations talent contract these arrangements for supply chain decision engines.
The dominant share belongs to Cloud-Based deployment, while Hybrid architectures are closing the gap fastest as edge inference capabilities mature.
Solution Type:
Cost tier stratification separates retrospective reporting tools from forward-optimization platforms with substantially different implementation economics.
- Prescriptive Analytics:Optimization algorithms generate actionable recommendations rather than probability forecasts. Automotive manufacturers in Japan and Germany deploy these systems for multi-tier supplier network rebalancing during disruption events.
- Predictive Analytics:Statistical models and neural networks forecast future states from historical patterns. Telecommunications providers apply these tools for churn prediction and network capacity planning across subscriber bases.
- Descriptive Analytics:Aggregation engines summarize historical performance through dashboards and standardized reports. Regulated sectors maintain demand for these tools where audit trails require human-reviewable decision logic.
- Diagnostic Analytics:Root-cause analysis modules identify drivers of observed outcomes. Healthcare systems utilize these platforms for clinical variation analysis and treatment pathway optimization.
Prescriptive Analytics commands premium pricing, while Predictive Analytics maintains volume leadership through broader addressable applicability.
Application:
Customer type differentiation separates buyers seeking operational efficiency from those managing regulatory compliance exposure.
- Supply Chain Optimization:Multi-objective algorithms balance inventory costs against service levels across supplier networks. Electronics manufacturers in Tamil Nadu and Gujarat deploy these systems under India's PLI scheme incentives for advanced process control.
- Risk Management:Automated credit assessment and fraud detection engines process structured and unstructured data. Financial services institutions subject to EU AI Act conformity requirements upgrade legacy rule-based systems with interpretable ML modules.
- Customer Insights:Segmentation and propensity models guide personalization and acquisition strategies. Retail banking networks integrate these capabilities into CRM workflows for cross-selling optimization.
- Financial Planning:Scenario modeling tools support capital allocation and budgeting decisions. Energy corporations utilize these platforms for commodity price hedging and infrastructure investment timing.
Supply Chain Optimization attracts the steepest expansion trajectory, while Risk Management retains the largest installed base amid compliance-driven refresh cycles.
End User:
Volume concentration reflects sector-specific data maturity and regulatory pressure for algorithmic accountability.
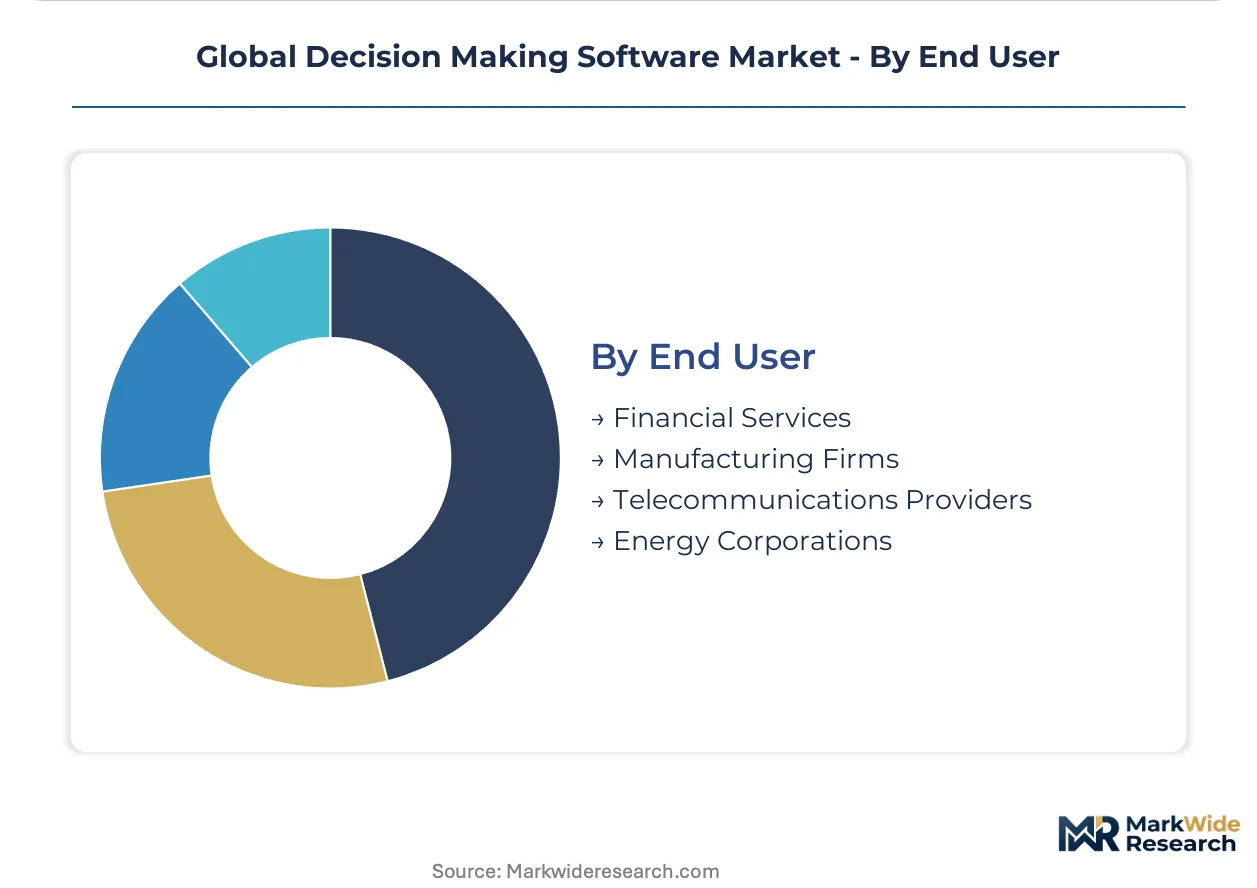
- Financial Services:Banks, insurers, and asset managers deploy decision engines for credit underwriting, algorithmic trading, and claims processing. EU AI Act mandates for explainable automated decisions are compelling system upgrades across French and Dutch institutions.
- Manufacturing Firms:Discrete and process manufacturers apply optimization to production scheduling, quality control, and maintenance planning. Automotive and aerospace clusters in Germany and Japan pilot graph neural networks for supplier disruption risk quantification.
- Energy Corporations:Utilities and oil & gas operators utilize real-time decision pipelines for grid management and asset optimization. Oracle extends autonomous database features into these deployments for operational data integration.
- Telecommunications Providers:Network operators leverage predictive capabilities for capacity planning and predictive maintenance. These firms represent mature adopters with established data infrastructure and internal analytics capabilities.
Financial Services contributes the dominant revenue share, while Manufacturing Firms demonstrate the fastest adoption acceleration as cloud infrastructure democratizes access to optimization tooling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where enterprise procurement teams absorb premium rates for prescriptive analytics, while Indian manufacturing clusters negotiate aggressively under PLI scheme cost ceilings. This asymmetry shapes vendor go-to-market strategies across geographies.
United States
Financial services institutions dominate procurement volumes for credit risk engines and algorithmic trading platforms. The SEC maintains separate oversight frameworks for automated trading decisions, fragmenting compliance architecture. New York Metro and Chicago financial districts house concentrated deployment of real-time decision pipelines for stress-testing cycles.
Germany
Automotive and aerospace manufacturers pilot graph neural networks for multi-tier supplier disruption risk quantification. The EU AI Act mandates conformity assessments for high-stakes automated decisions, compelling system upgrades. Industrial clusters in Bavaria and Baden-Württemberg embed predictive scenarios directly into ERP requisition processes.
India
PLI scheme incentives for advanced process control drive first-mover adoption among automotive and electronics manufacturers. The RBI and SEBI impose algorithmic accountability standards on fintech lending platforms. Tamil Nadu and Gujarat manufacturing corridors deploy supply chain optimization engines previously accessible only to large enterprises.
Japan
Automotive manufacturers apply multi-objective optimization for production scheduling and maintenance planning. METI guidelines shape industrial data governance standards for cross-border model training. Kansai and Chubu industrial regions integrate lightweight neural networks with IoT sensors for real-time quality control.
United Kingdom
Enterprise procurement teams with mature data science capabilities unbundle implementation services from software subscriptions. The Information Commissioner's Office enforces GDPR explainability mandates on automated decision systems. London financial services firms establish internal algorithmic audit functions ahead of enforcement deadlines.
Global Decision Making Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying interpretability modules and optimization engines. The vendor landscape stratifies between ERP-embedded analytics providers and standalone prescriptive analytics firms. Three archetypes dominate: legacy enterprise software houses extending autonomous features, cloud-native optimization specialists, and vertical-focused compliance platforms. Consolidation pressures intensify as API-first distribution forces restructuring of pricing models around consumption-based metering.
Within the ERP-embedded tier, SAP SE leverages manufacturing client renewal rates through workflow-integrated analytics. IBM anchors financial services positioning through specialized prescriptive platforms. Oracle extends autonomous database features into real-time decision pipelines for energy sector deployments.
| Leading Market Players |
|---|
| SAP SE |
| IBM |
| FICO |
| Oracle |
| TIBCO Software |
| Microsoft |
| QLIK TECHNOLOGIES |
| Information Builders |
| Others |
Supply & Pricing Matrix
Asia-Pacific submarine cable routes connecting Singapore, Japan, and the US West Coast carry latency-sensitive inference workloads for financial services clients, with bandwidth costs compressing margins for cloud-native vendors while enabling price differentiation between real-time and batch-processing tiers. This infrastructure geography concentrates supply-side leverage among hyperscale cloud providers who meter compute consumption, forcing mid-tier software vendors to absorb freight-equivalent data transfer costs or surrender pricing power to platform intermediaries.
Pricing Analysis
The customization-premium spread separates API-first consumption metering from perpetual license arrangements, with SaaS-tiered subscriptions dominating procurement for mid-market manufacturers while enterprise financial services firms negotiate project-based engagements for compliance-heavy deployments. Price differentiation rests on explainability module certification levels and vertical integration depth, with EU AI Act conformity assessments commanding substantial premiums. Cost compression in standard analytics tiers is intensifying because GPU supply constraints extend training timelines, while mid-market manufacturers demonstrate highest price sensitivity compared to energy corporations accepting premium rates for air-gapped on-premise architectures.
Supply Chain Analysis
Contract-manufacturing concentration for specialized AI accelerators sits with Taiwan Semiconductor Manufacturing Company and Samsung Foundry, with trailing-edge capacity at GlobalFoundries supplying inference-optimized chips for edge deployments. Geographic supply concentration spans Taiwan, South Korea, and the United States for advanced node production, while India and Vietnam host assembly operations for industrial IoT sensor integration. Raw material dependencies include high-purity silicon wafers, cobalt-containing memory substrates, and rare-earth magnet components for cooling systems. Single-source vulnerability around Taiwan-based foundry capacity represents the dominant structural risk. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales teams, with API-first channels displacing traditional licensing portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as unbundling of implementation services from software subscriptions creates vertical niches for compliance specialists and edge-inference optimizers. The dissolution of integrated platform bundles generates entry points for component vendors targeting specific regulatory or latency requirements.
For Market Incumbents: Pre-empt margin erosion in manufacturing segments by embedding prescriptive analytics deeper into ERP workflows through exclusive connector development for legacy MES systems. Acquire boutique interpretability module developers before EU AI Act enforcement deadlines consolidate demand around certified providers. Threat substitution from open-source optimization engines demands proprietary data pipeline integration to sustain renewal rates.
For New Entrants and Emerging Players: Establish a beachhead in Tamil Nadu and Gujarat automotive clusters by pricing supply chain optimization engines below PLI scheme cost ceilings while offering localized deployment support. Target mid-market manufacturers previously excluded from enterprise-grade tooling through consumption-based API metering. Go-to-market angle: embedded finance intermediaries seeking decision engine white-label partnerships for small business lending workflows.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified enterprise software conglomerates where analytics divisions lack platform-scale resources but retain sticky manufacturing client relationships. Long-term viability centers on regulatory compliance automation rather than raw performance benchmarking. Signal to watch: notified body accreditation timelines for EU AI Act high-risk system certification, which will consolidate vendor viability around demonstrable conformity assessment completion.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Embedded finance intermediaries at banking-as-a-service providers accelerate decision engine distribution to small business borrowers. |
| Acquisition of Specialist Firm | Interpretability module developers with EU notified body relationships command scarcity premiums ahead of conformity assessment deadlines. |
| Strategic Partnership | Hyperscale cloud alliances secure reserved GPU capacity for training large optimization models without capital expenditure burdens. |
| Geographic Expansion | Tamil Nadu and Gujarat manufacturing corridors under India's PLI scheme create first-mover positioning for prescriptive analytics localization. |
| Product Launch | Neuro-symbolic architectures addressing EU AI Act explainability mandates capture compliance-driven refresh cycles in French and Dutch financial institutions. |
Research Methodology
A standing panel of CTOs at mid-market manufacturers, compliance officers at EU-regulated financial institutions, platform engineers at hyperscale cloud providers, and integration specialists at systems integrators provided ongoing calibration against secondary validation from SEC filings, EU AI Act implementation guidance, hyperscaler capex disclosures, and industrial IoT deployment databases. Primary interviews with procurement leads at automotive clusters in Germany and Japan, alongside regulatory affairs directors at French and Dutch banks, supplied demand-side segmentation parameters. Bottom-up triangulation across deployment architecture preferences and top-down reconciliation against aggregate software spending patterns ensured cross-verification.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning deployment model, solution type, vertical application, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves incorporating EU AI Act enforcement phase-ins and PLI scheme incentive timelines. Industry-specific forecast inputs included cloud infrastructure cost trajectories and foundry capacity expansion announcements for AI accelerators.
Stress conditions across GPU supply availability, cross-border data localization enforcement, and algorithmic accountability legislative timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts incorporate documented assumptions regarding regulatory implementation pace and cloud infrastructure cost trajectories. Cross-checking against external benchmarks from enterprise software spending surveys and hyperscaler earnings disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Attendance Tracking Software Market
Software & Services
Global Backup Restore Software Market
Software & Services
Programming Language Market
Software & Services
Embedded Graphical User Interface (GUI) Development Software Market
Software & Services
Global Coworking Space Management Software Market
Software & Services
Global Online Survey Software Market
Software & Services
Shift Planning Software Market
Software & Services
Embedded Software and Tools Market
Software & Services
Global API Management Software Market
Software & Services
Global Customer Communications Management (CCM) Software Market
Software & Services
Global Demand Planning Software Market
Software & Services
Codeless Testing Market
Software & Services
Trading Software Market
Software & Services
Point Cloud Processing Software Market
Software & Services
Production Optimization Software Market
Software & Services
Email Optimization Software Market