
 Telecom Billing Software Market | 2026-2036
Telecom Billing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Billing Software Market Analysis
India's telecom infrastructure expansion is narrowing the operational gap between tier-one operators and emerging digital challengers. Amdocs leverages its deep integration with Indian operators to sustain deployment momentum across convergent billing platforms. Oracle Corporation anchors enterprise-grade postpaid billing systems for carriers navigating complex tariff structures. Ericsson competes aggressively on cloud-native architectures that reduce time-to-market for new service bundles.
Telecom billing software encompasses the systems that rate, charge, invoice, and collect payments for voice, data, and digital services across fixed and mobile networks, typically processing millions of call detail records per hour through real-time charging engines and policy control integration. Its primary commercial purpose is to translate network usage into monetizable revenue streams while ensuring regulatory compliance and customer transparency. Cloud billing deployments are capturing the fastest expansion as operators abandon capital-intensive on-premises installations in favor of elastic SaaS consumption models. Convergent billing platforms now dominate margin pools by unifying prepaid and postpaid revenue streams under single customer views, while managed service providers increasingly outsource their entire billing operations to specialized vendors.
The FCC's evolving stance on broadband labeling and transparent pricing directly shapes billing software requirements for US operators, mandating itemized disclosure of fees and service tiers. TRAI's tariff orders in India enforce strict compliance reporting that forces billing systems to maintain granular audit trails for every rate change. GDPR's data retention and portability rules across Europe add complexity to customer data handling within billing databases. Stakeholders must monitor how open API mandates from regulators accelerate vendor switching and reduce platform lock-in across major telecom markets.
Market Dynamics
Cloud-native billing architectures are compressing deployment timelines from months to weeks, forcing incumbent vendors to dismantle monolithic codebases or lose enterprise accounts to agile challengers. This structural shift rewards modular, API-first platforms that integrate with existing OSS/BSS stacks without forklift upgrades.
Growth Catalysts
- MVNO Outsourcing Surge:Mobile virtual network operators lack capital to build proprietary billing stacks and contract specialized platforms under revenue-share arrangements, expanding addressable market for pure-play vendors.
- FCC Net Neutrality Restoration:Proposed US rules mandate granular usage tracking and transparent service tiering, compelling operators to invest in real-time policy control and billing transparency modules.
- 5G Standalone Core Deployments:Network function virtualization enables dynamic service slicing that requires convergent charging systems capable of rating diverse latency and bandwidth profiles in milliseconds.
Market Restraints
- Cloud Infrastructure Concentration:Hyperscale cloud providers in the United States control critical compute and storage layers, creating vendor lock-in risk for billing software operators dependent on elastic scaling.
- Data Localization Mandates:India's draft data protection framework and similar statutes in Indonesia and Vietnam force redundant infrastructure deployment, inflating operational costs for multinational platform vendors.
- Legacy System Entrenchment:Tier-one carriers in Germany and Japan maintain decades-old COBOL-based billing engines where migration costs exceed replacement benefits, slowing platform refresh cycles.
Strategic Opportunities
- Embedded Finance Integration:Telcos in Brazil and Mexico are unbundling payment services from core connectivity, creating demand for billing platforms with native digital wallet and micro-lending capabilities.
- AI-Driven Revenue Assurance:Machine learning models that detect leakage across interconnect and roaming settlements represent high-margin attach services for platform vendors with proprietary fraud pattern libraries.
- Open API Mandates:Regulatory frameworks in the European Union and United Kingdom accelerate vendor switching by standardizing billing data portability, reducing platform lock-in and expanding competitive tender opportunities.
Industry Challenges
- Convergent Platform Integration:Unifying prepaid and postpaid subscriber data under single customer views requires reconciling incompatible data schemas and real-time charging protocols, extending implementation timelines.
- Specialized Talent Scarcity:Shortage of engineers fluent in both telecommunications charging protocols and modern cloud-native development constrains vendor delivery capacity and inflates compensation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Billing Software Market |
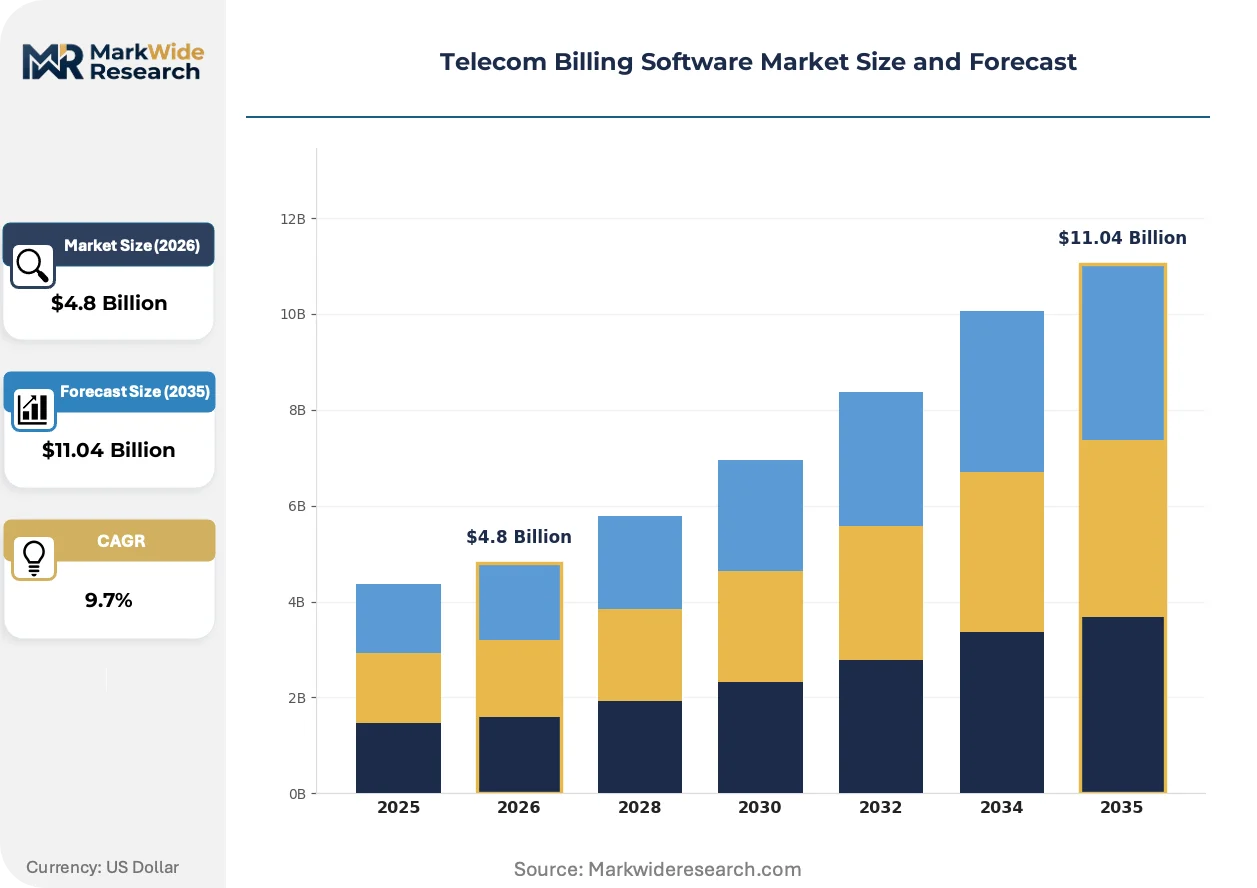
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prepaid Billing, Postpaid Billing, Convergent Billing, Cloud Billing Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Telecom Operators, Resellers, Managed Service Providers, Enterprises Service Type: Consulting, Integration, Support & Maintenance, Managed Services |
| Companies Covered | Amdocs, Oracle Corporation, Ericsson, SAP SE, Huawei Technologies, CSG International, Netcracker Technology, Accenture, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Billing Software Market Emerging Trajectories
Real-time charging engines are displacing batch-processing architectures as operators monetize 5G network slices and IoT connectivity with usage-based pricing granularity. This transformation demands sub-second rating latency and policy enforcement at network edge.
Containerized microservices architectures are migrating from pilot deployments to production-scale billing operations at tier-two operators in South Korea and Australia. These carriers, unburdened by mainframe legacy, deploy fully elastic charging systems that scale compute resources dynamically with traffic spikes. The structural consequence compresses time-to-market for new service bundles from quarters to weeks, pressuring established vendors to modularize monolithic products.
The European Union's Digital Services Act and GDPR retention rules impose strict audit trail requirements on customer data handling within billing databases. Operators must now demonstrate granular consent management and automated data purging workflows, adding compliance layers to platform architecture. German and French carriers allocate significant engineering resources to privacy-by-design billing modules, treating regulatory adherence as competitive differentiation.
Enterprise procurement teams are consolidating vendor relationships and demanding outcome-based pricing models that tie software fees to revenue uplift or cost reduction metrics. This displaces traditional per-subscriber licensing in favor of shared-risk commercial structures. The shift is most visible among digital challenger brands in India and Southeast Asia, where CFOs prioritize cash-flow flexibility over capital ownership of billing assets.
Telecom Billing Software Market Segmentation
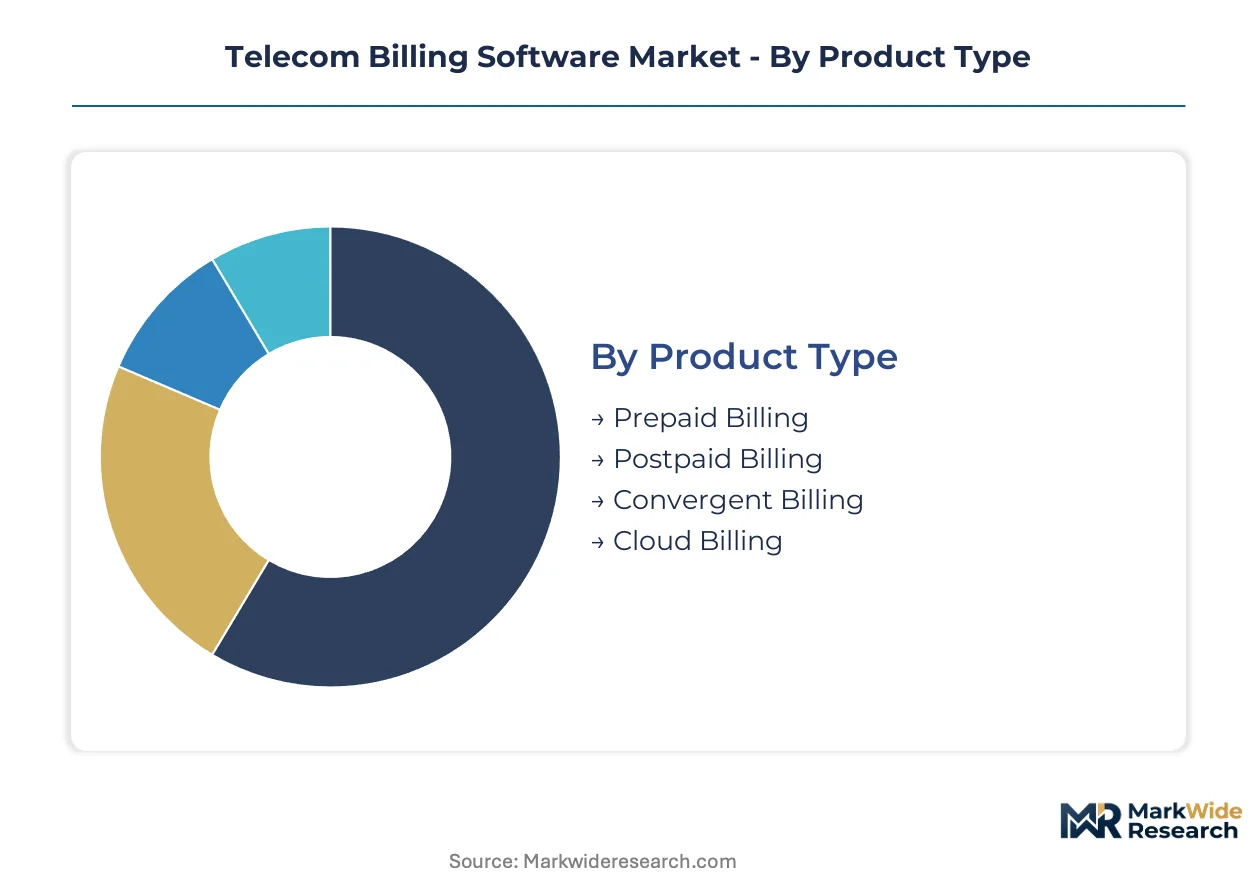
Telecom billing software segments reflect divergent operational priorities across carrier archetypes. Prepaid-heavy markets demand real-time charging precision, while postpaid operators prioritize complex tariff management. Cloud-native challengers favor elastic consumption models that legacy incumbents resist.
Product Type:
Product categories span the use-case spectrum from subscriber acquisition through revenue optimization, with each architecture serving distinct monetization workflows.
- Prepaid Billing:Real-time charging engines deduct balances instantaneously as subscribers consume voice, data, or digital services. Demand concentrates in India and Southeast Asia where Reliance Jio's subscriber acquisition forced legacy operators to modernize prepaid infrastructure rapidly under TRAI tariff compliance pressure.
- Postpaid Billing:Batch-processing architectures aggregate usage over billing cycles, supporting complex tariff hierarchies and credit risk management. German and Japanese tier-one carriers maintain COBOL-based postpaid engines where migration costs exceed replacement benefits, slowing platform refresh cycles.
- Convergent Billing:Unified platforms reconcile prepaid and postpaid subscriber data under single customer views.
- Cloud Billing:Elastic SaaS consumption models replace capital-intensive on-premises installations.
The dominant share belongs to Convergent Billing, while Cloud Billing is closing the gap fastest.
Deployment:
Deployment modes stratify by capital intensity tolerance and regulatory data sovereignty requirements.
- Cloud-Based:Hyperscale infrastructure enables dynamic resource scaling with traffic spikes, compressing deployment timelines from months to weeks. South Korean and Australian tier-two operators deploy containerized microservices architectures unburdened by mainframe legacy.
- SaaS:Outcome-based pricing models tie software fees to revenue uplift metrics, prioritizing cash-flow flexibility. Digital challenger brands in India and Southeast Asia favor shared-risk commercial structures over per-subscriber licensing.
- On-Premises:Capital-intensive installations persist where data localization mandates enforce physical infrastructure control.
- Hybrid:Transitional architectures bridge legacy systems and cloud-native modules.
Cloud-Based deployment captures expanding share, though SaaS exhibits the steepest expansion trajectory among challenger operators.
End User:
End-user categories reflect divergent technical capabilities and outsourcing preferences across the connectivity value chain.
- Telecom Operators:Tier-one carriers demand enterprise-grade platforms with granular policy control and regulatory audit trails. FCC net neutrality restoration proceedings mandate transparent service tiering and usage tracking investments.
- Managed Service Providers:Outsourced billing operations enable specialized focus without proprietary stack development. MVNOs contract platforms under revenue-share arrangements, expanding addressable market for pure-play vendors.
- Resellers:Intermediary entities require lightweight integration with host network billing systems.
- Enterprises:Private network operators seek embedded charging for IoT and campus connectivity deployments.
Telecom Operators retain the dominant share, while Managed Service Providers are gaining share fastest through MVNO outsourcing surge.
Service Type:
Service categories align with implementation complexity and ongoing operational support requirements.
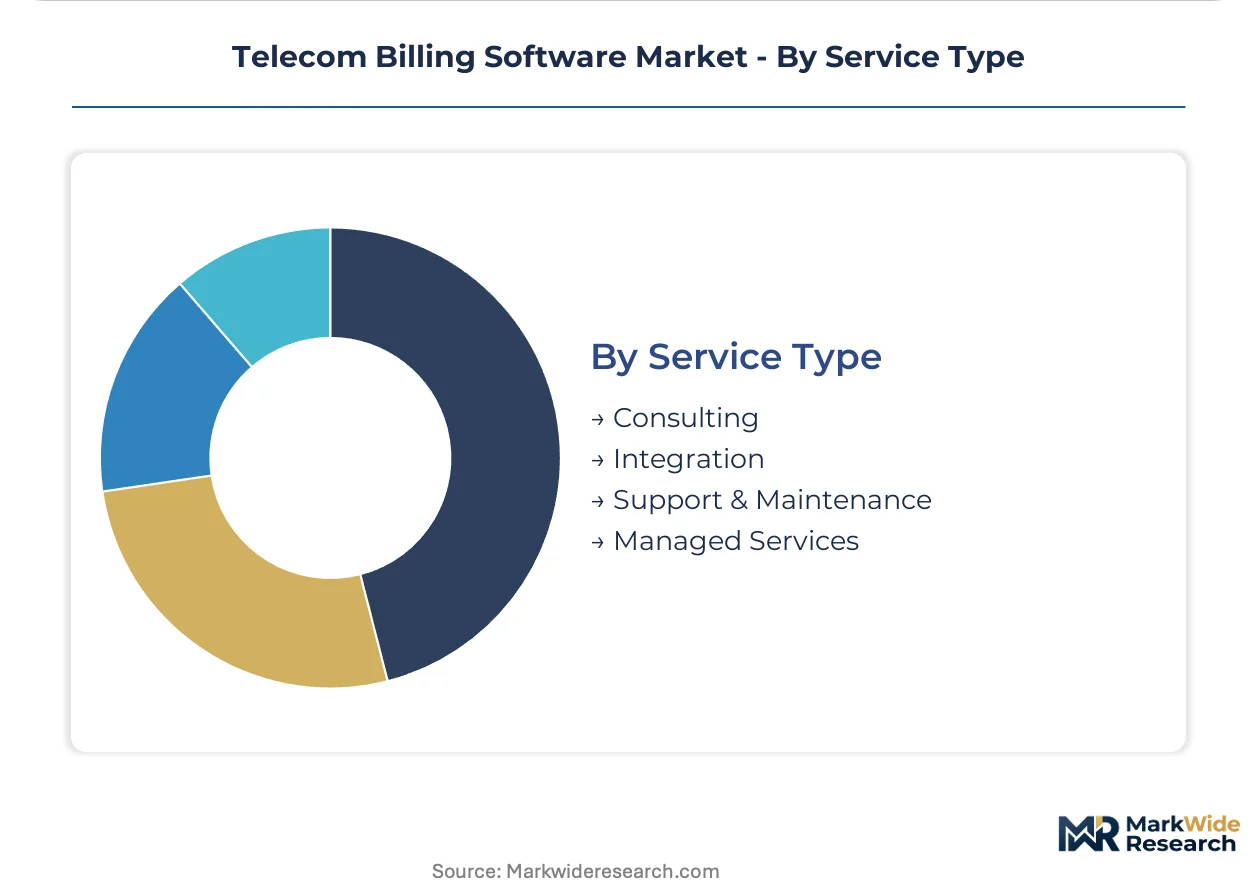
- Integration:Convergent platform deployment requires reconciling incompatible data schemas and real-time charging protocols, extending implementation timelines. Shortage of engineers fluent in both telecommunications charging protocols and cloud-native development constrains vendor delivery capacity.
- Managed Services:Complete billing operation outsourcing transfers operational risk to specialized vendors. Brazil and Mexico telcos unbundle payment services from core connectivity, creating demand for platforms with native digital wallet capabilities.
- Consulting:Advisory services navigate tariff regulation complexity and legacy migration planning.
- Support & Maintenance:Ongoing technical assistance ensures platform stability and regulatory compliance updates.
Integration commands the dominant share, though Managed Services is expanding most quickly as outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TRAI's tariff regulations and Reliance Jio's subscriber expansion anchor the dominant geography, forcing legacy operators across multiple continents to modernize billing infrastructure under convergent platform mandates.
United States
FCC net neutrality restoration proceedings mandate granular usage tracking investments. Transparent broadband labeling rules require itemized fee disclosure modules. Silicon Valley clusters host cloud-native billing startups compressing deployment timelines for tier-two operators.
India
Reliance Jio's subscriber acquisition forced legacy operators to modernize prepaid infrastructure rapidly. TRAI enforces strict compliance reporting with granular audit trails for every rate change. Bangalore and Hyderabad clusters concentrate vendor delivery capacity for convergent platform deployment.
Germany
Tier-one carriers maintain COBOL-based postpaid engines where migration costs exceed replacement benefits. GDPR retention rules impose strict audit trail requirements on customer data handling. Munich and Frankfurt engineering hubs allocate resources to privacy-by-design billing modules.
South Korea
Tier-two operators deploy containerized microservices architectures unburdened by mainframe legacy. 5G standalone core deployments enable dynamic service slicing requiring sub-second rating latency. Seoul metropolitan clusters lead production-scale elastic charging system implementation.
Brazil
Telcos unbundle payment services from core connectivity, creating demand for native digital wallet capabilities. ANVISA and central bank regulations shape embedded finance integration requirements. São Paulo financial technology clusters drive micro-lending capability adoption in billing platforms.
Telecom Billing Software Market Vendor Landscape
Enterprise-grade systems integrators and cloud-native specialists split the market into distinct capability tiers. Incumbent vendors dismantle monolithic codebases to defend enterprise accounts against agile challengers. Two strategic archetypes dominate: legacy platform modernizers and API-first modular specialists. Competitive moves concentrate on strategic partnerships with hyperscale cloud providers and geographic expansion through managed service outsourcing arrangements.
Within the enterprise systems tier, Amdocs leverages deep operator integration across convergent billing platforms. Oracle Corporation anchors postpaid billing systems for carriers navigating complex tariff structures. Ericsson competes on cloud-native architectures reducing time-to-market for new service bundles. These three exemplify the strategic divide between legacy modernization and greenfield elastic deployment.
| Leading Market Players |
|---|
| Amdocs |
| Oracle Corporation |
| Ericsson |
| SAP SE |
| Huawei Technologies |
| CSG International |
| Netcracker Technology |
| Accenture |
| NEC Corporation |
| Others |
Supply Flow & Price Mechanics
The Singapore-Dubai data corridor carries hyperscale cloud infrastructure costs that compress margins for billing software vendors deploying across India and Southeast Asia, while simultaneously enabling tiered service differentiation between latency-sensitive real-time charging modules and batch-processing postpaid systems. This freight-logistics dynamic concentrates pricing power with cloud-native platform vendors who absorb infrastructure volatility through elastic consumption models, forcing legacy on-premises providers into defensive discounting.
Pricing Analysis
Price spreads between North American and Indian deployments exceed threefold for equivalent convergent billing modules, reflecting divergent labor arbitrage and data localization compliance burdens. The dominant pricing structure is outcome-based SaaS tiering, with fees indexed to revenue uplift or transaction volume rather than per-subscriber licensing. Price differentiation hinges on certification level—PCI-DSS and ISO 27001 compliance command substantial premiums—and customization depth for legacy system integration. Pricing pressure stems from hyperscale cloud providers bundling billing adjacent services at marginal cost, eroding standalone platform margins. Digital challenger brands in Southeast Asia exhibit highest price sensitivity, while tier-one carriers in Germany and Japan prioritize operational continuity over cost minimization.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for billing software vendors dependent on semiconductor components and hyperscale cloud infrastructure. Engineering talent concentrates in India, Ireland, and Israel, with Bangalore and Hyderabad clusters supplying convergent platform development capacity. Raw material dependencies span advanced silicon for edge computing nodes, submarine cable capacity for intercontinental data transit, and proprietary fraud-detection algorithm libraries. Single-source vulnerability pervades the hyperscale cloud layer, where Amazon Web Services, Microsoft Azure, and Google Cloud control elastic compute provisioning. Distribution runs through direct enterprise sales teams for tier-one carriers, supplemented by systems integrator partnerships for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Billing software monetization increasingly rests on managed services and revenue assurance attach rates, with AI-driven leakage detection and embedded finance integration expanding faster than core platform licensing. This service-layer acceleration transforms hardware-agnostic software deployment into recurring revenue architectures.
For Market Incumbents: Pre-empt cloud-native challengers by modularizing monolithic codebases into API-first microservices architectures that integrate without forklift upgrades. Defensive consolidation demands acquiring specialized AI revenue assurance vendors to capture high-margin attach services, while simultaneously embedding digital wallet capabilities to counter fintech unbundling in Latin American markets. Capacity expansion in Bangalore and Hyderabad delivery clusters sustains implementation velocity against talent scarcity constraints. For New Entrants and Emerging Players: Underpenetration in Brazilian and Mexican embedded finance integration presents immediate white-space opportunity, where central bank regulations and ANVISA compliance frameworks favor agile specialists over legacy incumbents. MVNO outsourcing surge across Southeast Asia offers second penetration vector, with revenue-share commercial structures reducing customer acquisition friction. Channel partnership with regional systems integrators accelerates credibility establishment without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors API-first modular specialists with demonstrated hyperscale cloud interoperability over legacy platform modernizers encumbered by technical debt. Long-term viability across the projection horizon hinges on recurring revenue mix exceeding seventy percent and vertical-specific fraud pattern libraries. Acquisition target archetype: convergent billing platforms with production-scale 5G standalone core deployments. Signal to monitor: regulatory open API mandates accelerating vendor switching velocity in European and United Kingdom markets.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first microservices architectures compress deployment timelines from months to weeks for tier-two operators. |
| Acquisition of Specialist Firm | AI revenue assurance vendors with proprietary fraud pattern libraries command premium valuations and high-margin attach rates. |
| Strategic Partnership | Hyperscale cloud provider alliances unlock elastic scaling capabilities essential for 5G network slice monetization. |
| Geographic Expansion | Managed service outsourcing arrangements in India and Southeast Asia capture MVNO billing complexity without proprietary stack investment. |
| Product Launch | Native digital wallet and micro-lending modules address unbundled payment service demand from Brazil and Mexico telcos. |
Methodological Framework
Desk research of FCC and TRAI regulatory filings, hyperscaler capex disclosures, and carrier procurement databases preceded structured interviews with CTOs at tier-one operators, billing platform product managers, systems integrator partners, and cloud infrastructure procurement officers. Primary fieldwork validated secondary findings across deployment model preferences, pricing structure evolution, and vendor switching propensity. Bottom-up subscriber volume estimates and top-down IT spending allocations were triangulated against disclosed platform deployment announcements.
Forecast assumptions held 5G standalone core rollout velocity and open API regulatory adoption patterns within observed trajectories, while varying cloud migration speed and MVNO market entry rates across sensitivity scenarios. The analytical framework modeled deployment mode, carrier tier, and service type segmentation dimensions alongside regional regulatory cluster differentiation. CAGRs were derived from subscriber growth projections, average revenue per user compression trends, and platform consolidation velocity across the analysis window. Industry-specific inputs included TRAI tariff order compliance costs and FCC broadband labeling implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive cloud-native investment by Oracle Corporation or accelerated modularization by Amdocs would shift competitive outcomes substantially. Regulatory reversal on net neutrality or data localization mandates represents primary exogenous revision risk. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Recreation Management Software Market
Software & Services
Global UIUX Software Market
Software & Services
Audio and Video Editing Software Market
Software & Services
Desktop Publishing Software Market
Software & Services
IT Professional Services Market
Software & Services
Workshop Management Software Market
Software & Services
Debt Collection Software Market
Software & Services
Plant Design Software Market
Software & Services
US Enterprise Legal Management Software Market
Software & Services
Global Handyman Software Market
Software & Services
Workflow Management Software (WMS) Market
Software & Services
Global Absence and Leave Management Software Market
Software & Services
Global Claims Processing Software Market
Software & Services
Document Capture Software Market
Software & Services
Embedded Operating Systems Market
Software & Services
Model Based Testing Tools Market