
 Creative Software Market | 2026-2036
Creative Software Market Size, Share, and Industry Trends Forecast 2026-2036
Creative Software Market Intelligence
Cloud-native rendering infrastructure is pivoting away from on-premise GPU farms as the dominant cost layer for professional creative workflows. Adobe Inc. leverages its integrated Creative Cloud ecosystem to sustain recurring revenue density across video and design verticals. Canva Pty Ltd. competes through template-first design automation that anchors small-business demand outside traditional agency channels.
Creative software encompasses digital tools that manipulate raster or vector graphics, multi-track audio, non-linear video timelines, and interactive media through GPU-accelerated processing engines and standardized file formats such as ProRes and OpenEXR. Its primary commercial purpose is to compress production cycles from concept to distributable asset across advertising, entertainment, and corporate communications. Video editing and cloud-based deployment command the deepest margin pools as enterprise clients consolidate vendor relationships and demand real-time collaboration protocols. Graphic design remains structurally mature with high penetration among marketing departments, while SaaS delivery is displacing perpetual licenses fastest among mid-market buyers seeking predictable OpEx profiles.
FCC guidelines on broadband infrastructure shape cloud-based creative software accessibility by influencing upload bandwidth thresholds for remote collaboration. EMA and FDA frameworks indirectly govern demand where creative outputs support pharmaceutical advertising and medical device labeling compliance. GDPR and emerging EU AI Act provisions constrain automated content generation tools by mandating provenance disclosure and training data transparency. Stakeholders must monitor how copyright office rulings on AI-generated works recalibrate licensing economics for derivative creative tools.
Market Dynamics
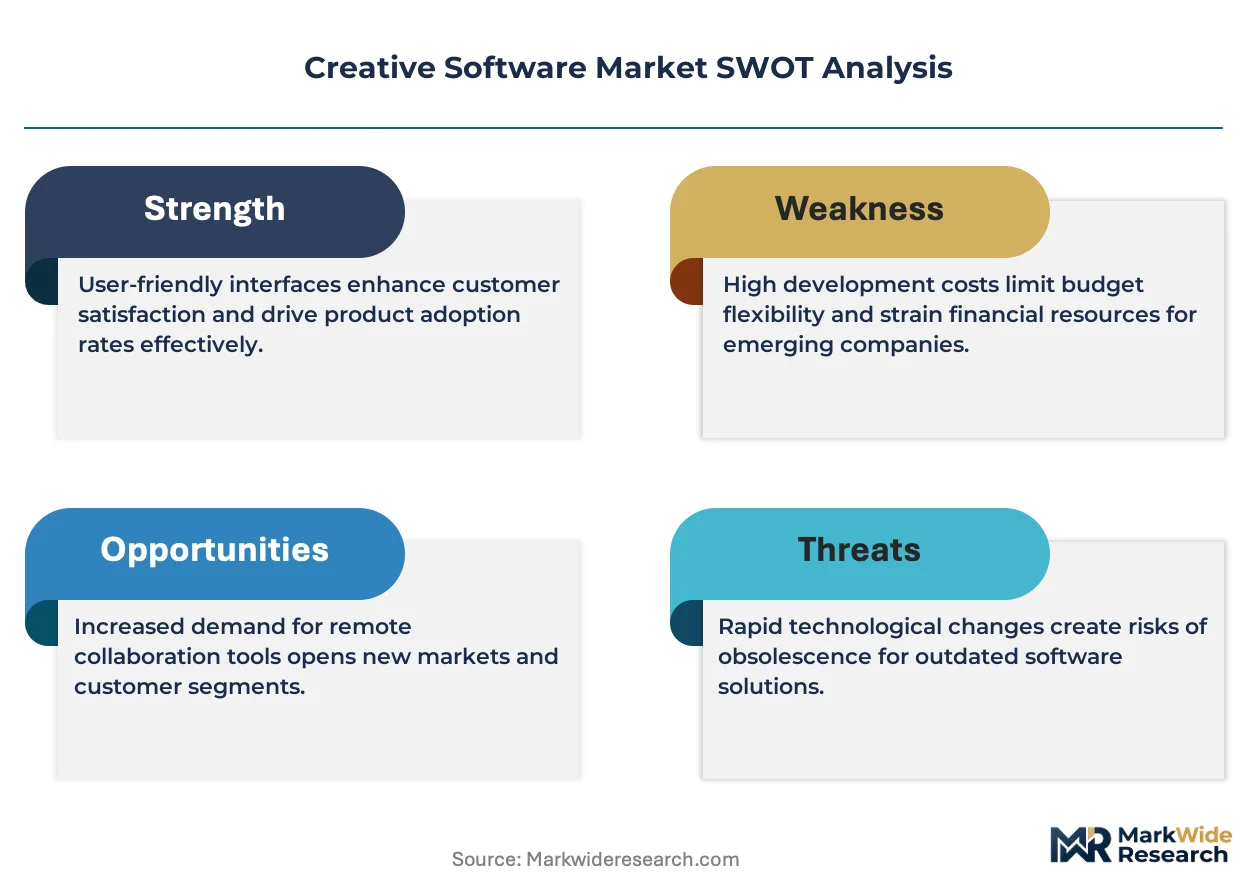
Cloud-based delivery architectures are compressing perpetual license models into subscription revenue streams, forcing vendors to rebuild infrastructure around real-time collaboration protocols and GPU-accelerated rendering pipelines.
Growth Catalysts
- FCC broadband infrastructure guidelines:Rising upload bandwidth thresholds in the United States enable remote creative teams to synchronize large asset libraries without latency degradation.
- Freelance content creator expansion:Individual professionals outside traditional agency structures now represent a scalable addressable base for SaaS creative tools with predictable OpEx profiles.
- GPU-accelerated processing engines:Raster and vector manipulation speeds now match real-time preview demands, collapsing feedback loops between concept and final asset.
Market Restraints
- GDPR training data transparency mandates:Automated content generation tools face provenance disclosure requirements that constrain model training pipelines and increase compliance overhead.
- Cloud rendering cost volatility:GPU farm pricing fluctuates with semiconductor foundry capacity, compressing margins for vendors offering unlimited render credits.
- AI-generated copyright uncertainty:Derivative licensing economics remain unresolved as copyright offices deliberate protection eligibility for machine-created works.
Strategic Opportunities
- EU AI Act compliance tooling:Provenance disclosure mandates create white space for audit-layer software that tracks generative lineage across creative workflows.
- Small-business template automation:Marketing departments outside enterprise procurement channels seek design automation that bypasses traditional agency retainers.
- Medical device labeling creative outputs:FDA framework alignment for pharmaceutical advertising creates specialized demand for compliant asset generation tools.
Industry Challenges
- Real-time collaboration protocol integration:Legacy non-linear video timelines require expensive re-architecture to support frame-accurate multi-user editing.
- Cross-format standardization gaps:ProRes and OpenEXR interoperability remains incomplete across competing cloud-native platforms, fragmenting asset portability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Creative Software Market |
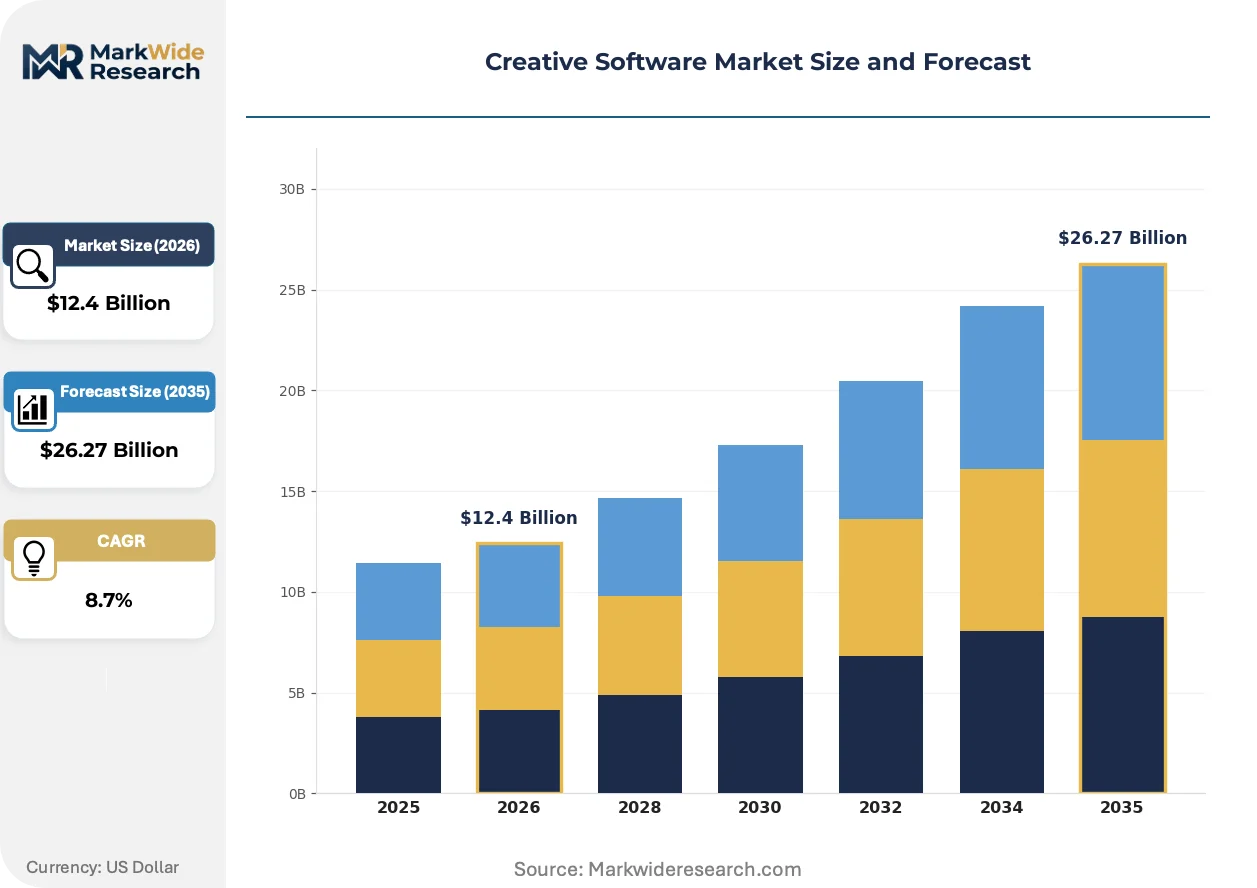
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
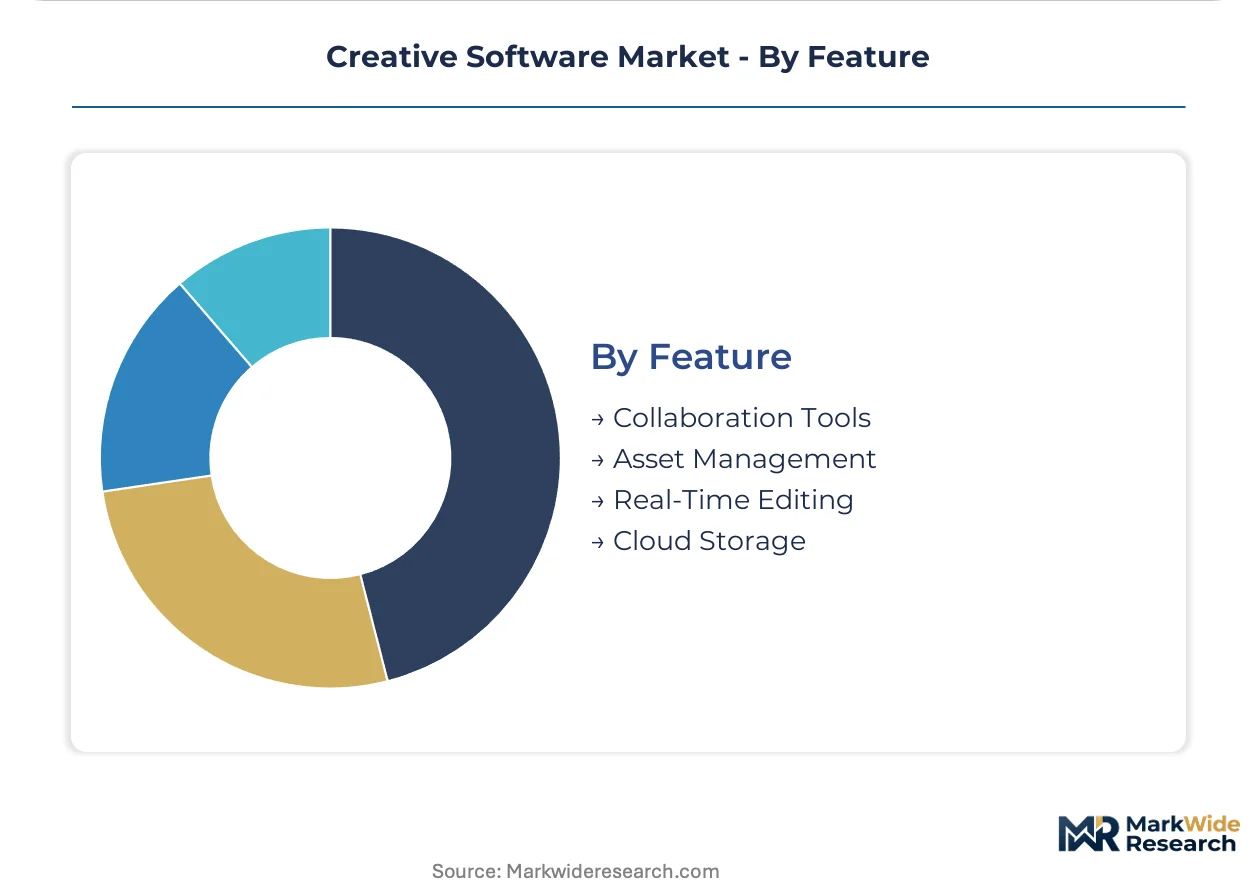
| Segmentation | Product Type: Graphic Design, Video Editing, Digital Publishing, Music Production Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Freelancers, Small Businesses, Large Enterprises, Educational Institutions Feature: Collaboration Tools, Asset Management, Real-Time Editing, Cloud Storage |
| Companies Covered | Adobe Inc., Corel Corporation, Canva Pty Ltd., MAGIX Software GmbH, CyberLink Corp., TechSmith Corporation, Sony Creative Software, Movavi Software Limited, Wondershare Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Creative Software Market Strategic Shifts & Innovations
Generative automation is collapsing production cycles from weeks to hours, while regulatory pressure on algorithmic transparency forces vendors to expose training pipelines. These shifts are reconfiguring competitive moats around data governance rather than feature depth alone.
Neural rendering engines are consolidating texture synthesis and lighting simulation into unified pipelines. Mid-market video production houses adopt these tools fastest, replacing discrete compositing stages with end-to-end generative previews. This compression is consolidating vendor relationships as buyers shed point solutions for integrated suites.
The EU AI Act mandates provenance disclosure for automated content generation tools deployed across member states. Creative software vendors must now embed audit trails that expose training data composition and generation lineage. Pharmaceutical advertising workflows face the steepest compliance burden, as EMA labeling requirements intersect with algorithmic transparency rules.
Subscription fatigue among enterprise procurement departments is compressing vendor consolidation cycles. Marketing departments now bundle creative software procurement with broader MarTech stack decisions, displacing standalone design tool evaluations. This pattern concentrates most visibly in United States creative economy clusters where procurement authority has shifted to centralized IT governance.
Creative Software Market Segmentation
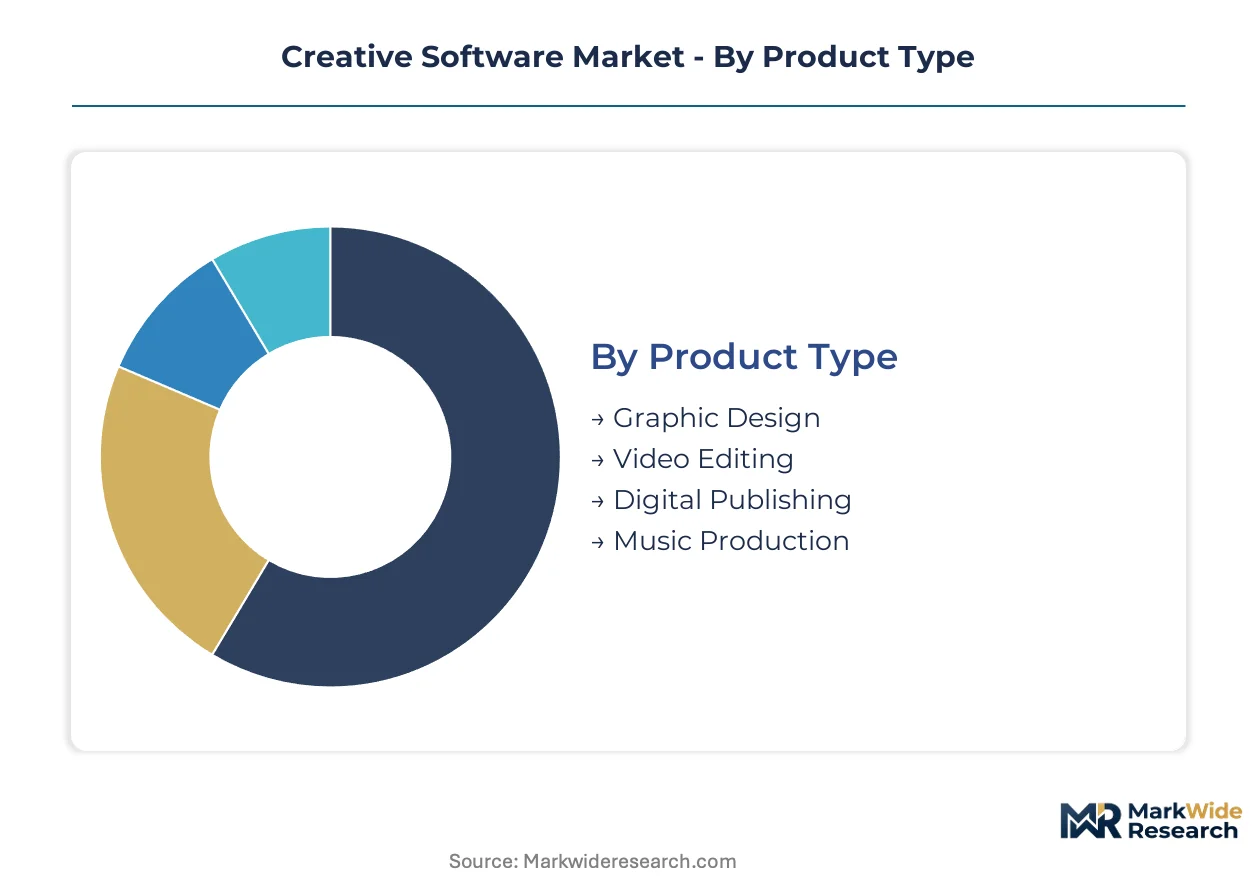
Creative software segmentation reveals how technical specifications, delivery architectures, and user workflows fragment into distinct commercial battlegrounds. Vendors must align product roadmaps with specific deployment constraints and end-user capability thresholds rather than pursuing horizontal dominance.
Product Type:
Raster and vector manipulation engines define the technical core of each product category, with GPU acceleration requirements varying dramatically across output formats.
- Graphic Design:Vector-based illustration and raster composition tools dominate marketing department procurement cycles. United States creative economy clusters concentrate demand for Adobe Illustrator-compatible workflows, though Canva's template automation captures small-business volume outside traditional agency channels. Mature penetration limits expansion to replacement cycles and format migration.
- Video Editing:Non-linear timeline engines with GPU-accelerated preview pipelines command the deepest margin pools. Enterprise clients in Los Angeles and New York production hubs consolidate vendor relationships around real-time collaboration protocols, compressing point-solution providers. Cloud rendering integration determines competitive viability.
- Digital Publishing:Layout automation for multi-channel distribution serves corporate communications and periodical production. EMA-compliant pharmaceutical labeling workflows in Germany and France create specialized demand for audit-traversable asset generation.
- Music Production:Multi-track audio engines with low-latency monitoring target professional studios and independent producers. MIDI protocol standardization limits differentiation, pushing competition toward plugin ecosystem breadth.
Video Editing leads on scale; Graphic Design leads on installed base maturity.
Deployment:
Delivery architecture selection directly shapes vendor infrastructure investments and customer OpEx predictability.
- On-Premise:Perpetual license models persist in high-security environments and legacy facility investments. Defense contractors and classified media production in the United States maintain captive GPU farms despite cloud migration pressure.
- Cloud-Based:Browser-accessible rendering pipelines eliminate local hardware dependencies. Mid-market video houses in United Kingdom and Canada adopt these fastest, trading unlimited render credits for subscription predictability.
- Hybrid:Local preprocessing with cloud finishing balances latency sensitivity and compute elasticity. Post-production facilities in Mumbai and Seoul leverage this architecture for 4K/8K workflows exceeding local GPU capacity.
- SaaS:Subscription-native delivery with automatic feature updates anchors modern procurement. GDPR compliance tooling and provenance disclosure capabilities increasingly determine European Union eligibility.
SaaS dominates new procurement; Hybrid gains share fastest among professional studios.
End User:
Organizational scale dictates collaboration requirements, budget authority, and integration complexity.
- Freelancers:Individual professionals outside agency structures now represent scalable addressable base for tiered subscription tools. FCC broadband infrastructure improvements enable remote asset synchronization from home studios in Austin and Denver.
- Small Businesses:Marketing departments with limited design headcount seek template-first automation. These buyers bypass traditional agency retainers, concentrating demand in United States metropolitan creative clusters.
- Large Enterprises:Centralized IT governance bundles creative software with broader MarTech stack decisions. Procurement authority consolidation in Chicago and San Francisco headquarters compresses vendor evaluation cycles.
- Educational Institutions:Volume licensing for curriculum integration shapes long-term user habit formation. University procurement in California and Massachusetts prioritizes cross-platform compatibility over feature depth.
Large Enterprises lead on contract value; Freelancers lead on expansion trajectory.
Feature:
Functional modules increasingly determine competitive differentiation as core editing capabilities commoditize.
- Collaboration Tools:Frame-accurate multi-user editing protocols require expensive re-architecture of legacy timeline engines. Real-time synchronization demand concentrates among distributed production teams in London and Tokyo.
- Asset Management:Centralized library systems with version control and rights metadata serve enterprise content operations. FDA framework alignment for pharmaceutical advertising creates compliance-driven demand.
- Real-Time Editing:GPU-accelerated preview without render latency collapses feedback loops. Neural rendering engines consolidate texture synthesis and lighting simulation into unified generative pipelines.
- Cloud Storage:Scalable repository integration with automated backup and geographic redundancy. EU AI Act provenance disclosure mandates constrain architecture choices for automated content generation tools.
Collaboration Tools leads on enterprise priority; Real-Time Editing leads on technical momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States creative economy clusters concentrate the deepest demand pools for cloud-native video editing and real-time collaboration tools, with Los Angeles and New York production hubs driving enterprise procurement consolidation.
United States
FCC broadband infrastructure improvements enable remote creative teams in Austin and Denver to synchronize large asset libraries without latency degradation. FDA frameworks govern pharmaceutical advertising workflows, creating specialized demand for compliant asset generation tools. Los Angeles post-production facilities consolidate vendor relationships around GPU-accelerated rendering pipelines.
Germany
EMA-compliant pharmaceutical labeling workflows in Frankfurt and Munich create specialized demand for audit-traversable creative outputs. EU AI Act provenance disclosure mandates constrain automated content generation tools deployed across member states. Berlin-based mid-market video houses adopt browser-accessible rendering pipelines fastest in Europe.
United Kingdom
GDPR training data transparency requirements increase compliance overhead for generative AI features in creative software. London distributed production teams demand frame-accurate multi-user editing protocols for real-time collaboration. Manchester and Bristol marketing departments bundle creative software procurement with broader MarTech stack decisions.
Japan
METI technology standards influence GPU-accelerated processing engine specifications for professional creative workflows. Tokyo animation studios maintain hybrid deployment architectures balancing local preprocessing with cloud finishing for 4K/8K outputs. Osaka-based independent producers drive subscription-native SaaS adoption for predictable OpEx profiles.
India
Bureau of Indian Standards certification requirements shape software localization for domestic creative professionals. Mumbai post-production facilities leverage hybrid architectures for 4K/8K workflows exceeding local GPU capacity. Bangalore freelance content creators represent a scalable addressable base for tiered subscription tools.
Creative Software Market Key Industry Players
Global majors compete with regional champions across delivery architecture and pricing tier segmentation. The vendor base organizes around three tiers: integrated cloud-suite providers, template-first automation specialists, and point-solution rendering engines. Strategic archetypes include ecosystem bundlers, vertical workflow optimizers, and geographic price discounters. Dominant competitive moves encompass SaaS migration investments and generative AI feature integration.
Within the integrated ecosystem tier, Adobe Inc. and Canva Pty Ltd. exemplify divergent approaches to market coverage. Adobe Inc. anchors premium-tier positioning through recurring revenue density across video and design verticals. Canva Pty Ltd. occupies a position in template-first design automation that captures small-business volume outside traditional agency channels. MAGIX Software GmbH represents the regional specialist archetype, sitting within mid-market video editing segments with focused geographic presence.
| Leading Market Players |
|---|
| Adobe Inc. |
| Corel Corporation |
| Canva Pty Ltd. |
| MAGIX Software GmbH |
| CyberLink Corp. |
| TechSmith Corporation |
| Sony Creative Software |
| Movavi Software Limited |
| Wondershare Group |
| Others |
Cost & Logistics Intelligence
EU AI Act provenance disclosure mandates gate qualified supply for premium-tier creative software, as vendors embedding audit-trail infrastructure command pricing power while compliance-lagging competitors face margin compression in mid-market SaaS tiers.
Pricing Analysis
GPU foundry cost pass-through dominates SaaS pricing architecture, with subscription tiers stratifying across enterprise, professional, and freelance levels based on render credit allocation and collaboration protocol depth. Price differentiation rests on real-time rendering throughput and GDPR-compliant data residency certification. Pricing pressure stems from cloud rendering cost volatility linked to semiconductor capacity constraints. Freelance content creators exhibit highest price sensitivity, while Los Angeles and New York production hubs absorb premium tiers for frame-accurate multi-user editing.
Supply Chain Analysis
Reverse-logistics flows for GPU hardware refurbishment and data center equipment redeployment concentrate in Taiwan, South Korea, and the United States, extending compute asset lifecycles for cloud rendering infrastructure. Creative software supply chains draw from NVIDIA and AMD GPU architectures, hyperscaler server farms, and fiber-optic broadband backbones. Single-source vulnerability in advanced semiconductor lithography threatens render pipeline elasticity. Distribution runs through direct SaaS portals and hyperscaler marketplaces, bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Creative software functions as a stable compounder, with recurring subscription revenue density and cloud infrastructure lock-in generating predictable cash flow expansion across the forecast window.
For Market Incumbents: Acquire specialized generative AI engineering teams to neutralize point-solution disruptors threatening video editing margins. Consolidate vendor relationships by embedding real-time collaboration protocols deeper into enterprise MarTech stacks. Defensive priority centers on backward integration into cloud rendering infrastructure to offset GPU farm pricing volatility. For New Entrants and Emerging Players: Launch via template-first automation targeting small-business marketing departments outside traditional agency procurement channels. White-space concentration sits in EU AI Act compliance tooling for pharmaceutical advertising workflows. Go-to-market leverage emerges through browser-accessible rendering pipelines eliminating local hardware dependencies for mid-market video houses. For Investors and Strategic Acquirers: Roll-up economics work for vertical workflow optimizers because enterprise procurement consolidation compresses vendor evaluation cycles toward integrated suites. Five-to-ten-year viability favors SaaS-native platforms with provenance disclosure capabilities over perpetual-license legacy architectures. Monitor FCC broadband infrastructure deployment velocity as inflection indicator for remote creative team expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Feature Integration | Neural rendering engines collapse production cycles from weeks to hours for mid-market video houses. |
| Real-Time Collaboration Protocol Deployment | Frame-accurate multi-user editing anchors enterprise procurement consolidation in Los Angeles and New York. |
| EU AI Act Compliance Layer Development | Provenance disclosure tooling captures pharmaceutical advertising demand in Frankfurt and Munich. |
| Cloud Rendering Infrastructure Expansion | GPU-accelerated pipelines eliminate latency degradation for remote teams in Austin and Denver. |
| Template Automation Platform Launch | Small-business design automation bypasses traditional agency retainers in United States metropolitan clusters. |
Research Approach
Multiple input streams — primary interviews with CTOs and IT procurement officers, secondary validation against hyperscaler capex disclosures and SEC filings, and technical specification audits — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned platform engineers at cloud-native vendors, integration specialists at enterprise MarTech stacks, channel partners distributing SaaS tools, and creative directors at post-production facilities. Secondary sources included App Annie deployment data, hyperscaler infrastructure investment reports, and regulatory filings with the FCC and EU AI Act implementation bodies.
Historical subscription revenue trajectories were cross-referenced against panel input from procurement leaders to model growth across the projection horizon. Segmentation dimensions encompassed deployment architecture, organization scale, creative vertical, integration complexity, and regional adoption pattern. CAGRs were derived from elasticity modeling of SaaS pricing tiers against broadband infrastructure penetration curves and GPU compute cost indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or semiconductor supply disruption scenarios. Practitioners should monitor copyright office rulings on AI-generated works and hyperscaler GPU allocation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Europe CMMS Software Market
Software & Services
Global SAP S-4HANA Application Market
Software & Services
Graphical User Interface (GUI) Design Software Market
Software & Services
Bank Reconciliation Software Market
Software & Services
Business Email Market
Software & Services
Global Press Release Distribution Software Market
Software & Services
Electromagnetic Simulation Software Market
Software & Services
Global Data Mining Software Market
Software & Services
Real-Time Voice Changing Software Market
Software & Services
Global Maintenance Management Software Market
Software & Services
Video Converter Software Market
Software & Services
Human Identification Analysis Software Market
Software & Services
Chromatography Data System (CDS) Software Market
Software & Services
Global Childcare Management Software Market
Software & Services
Airline Route Profitability Software Market
Software & Services
Labor Management Software Market