
 Search and Discovery Software Market | 2026-2036
Search and Discovery Software Market Size, Share, and Industry Trends Forecast 2026-2036
Search and Discovery Software Market Analysis
Modular bundling of AI-powered search with knowledge management suites is shifting procurement patterns across enterprise buyers. Elastic sustains technology leadership in open-source distributed search architectures. Google dominates consumer-to-enterprise search extension through cloud platform integration. Coveo differentiates through vertical specialization in customer-facing discovery applications.
Search and discovery software comprises indexing engines, query processors, relevance algorithms, and analytics layers that ingest structured and unstructured data to return ranked, contextual results with sub-second latency. Its primary commercial purpose is surfacing actionable intelligence from dispersed repositories to accelerate decision workflows. Cloud-based solutions lead deployment preferences as organizations retire on-premise infrastructure, while AI-powered segments capture expanding margin pools through natural language query expansion and automated relevance tuning. Enterprise search applications anchor revenue volume, though e-commerce discovery modules are gaining traction among retail technology stacks.
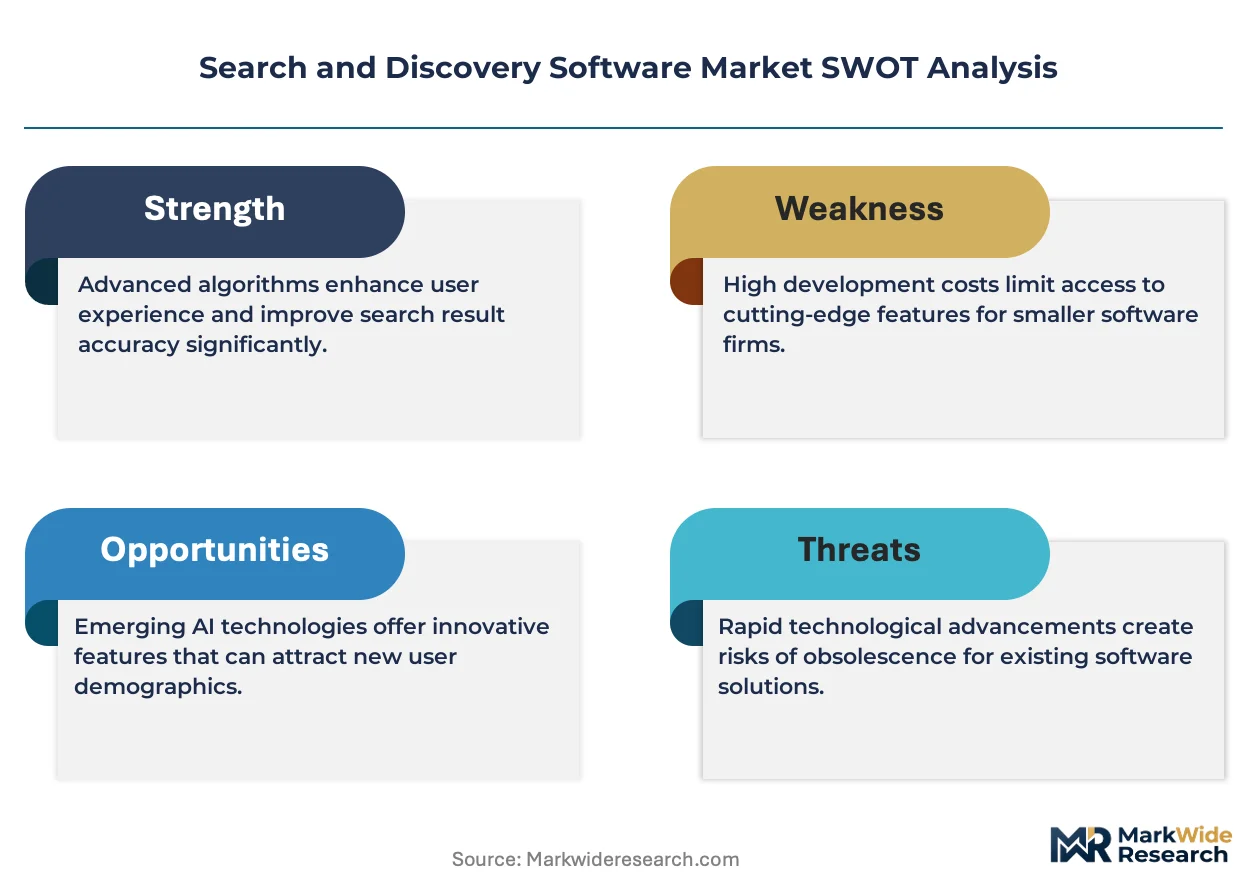
FDA guidelines on software-as-medical-device classification, EU AI Act risk-tiering for automated decision systems, and HIPAA data handling requirements shape product development roadmaps and market access conditions for vendors serving regulated industries. ISO 27001 and SOC 2 Type II certifications function as baseline qualification criteria in procurement evaluations. Stakeholders must monitor how emerging algorithmic accountability frameworks in the European Union and United States recalibrate liability exposure and R&D allocation across the vendor landscape.
Market Dynamics
AI-powered relevance tuning is compressing traditional keyword-index architectures as enterprises demand sub-second contextual retrieval across petabyte-scale unstructured repositories. The EU AI Act's risk-tiering framework is forcing vendors to re-engineer automated decision pipelines before enforcement deadlines.
Growth Catalysts
- Financial Services Modernization:Investment banks and insurance carriers are replacing legacy document management with unified cognitive search to accelerate compliance review cycles.
- GDPR Article 17 Right-to-Erasure:Enterprise demand for indexed data lineage and automated deletion workflows is expanding procurement budgets for governance-integrated search platforms.
- Vector Database Convergence:Embedding-based retrieval architectures are displacing inverted-index systems in customer-facing discovery applications.
Market Restraints
- GPU Compute Cost Volatility:Inference-intensive neural ranking models expose buyers to cloud provider pricing swings that distort total cost of ownership projections.
- Training Data Concentration:High-quality annotated query-document relevance pairs cluster within a narrow set of technology vendors and academic institutions.
- HIPAA Technical Safeguards:Minimum necessary access controls and audit logging requirements extend implementation timelines for healthcare deployments by 40-60%.
Strategic Opportunities
- India Enterprise Digitization:PLI scheme beneficiaries and domestic IT services firms are modernizing knowledge infrastructure with cloud-native search at scale.
- Conversational Interface Convergence:Large language model integration with enterprise retrieval systems is creating new product categories for natural language-to-insight workflows.
- CSRD Mandated Disclosure:European sustainability reporting requirements are generating demand for ESG document intelligence and automated materiality assessment tools.
Industry Challenges
- MLOps Talent Scarcity:Shortage of engineers capable of productionizing neural ranking models at sub-100ms latency is constraining vendor delivery capacity.
- SOC 2 Type II Timeline Compression:Enterprise procurement cycles now require 12-month continuous audit windows before contract execution, elongating sales velocity.
- Legacy ECM Integration Friction:Decades-old content management systems lack API-native architectures, forcing expensive middleware development for unified search indexing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Search and Discovery Software Market |
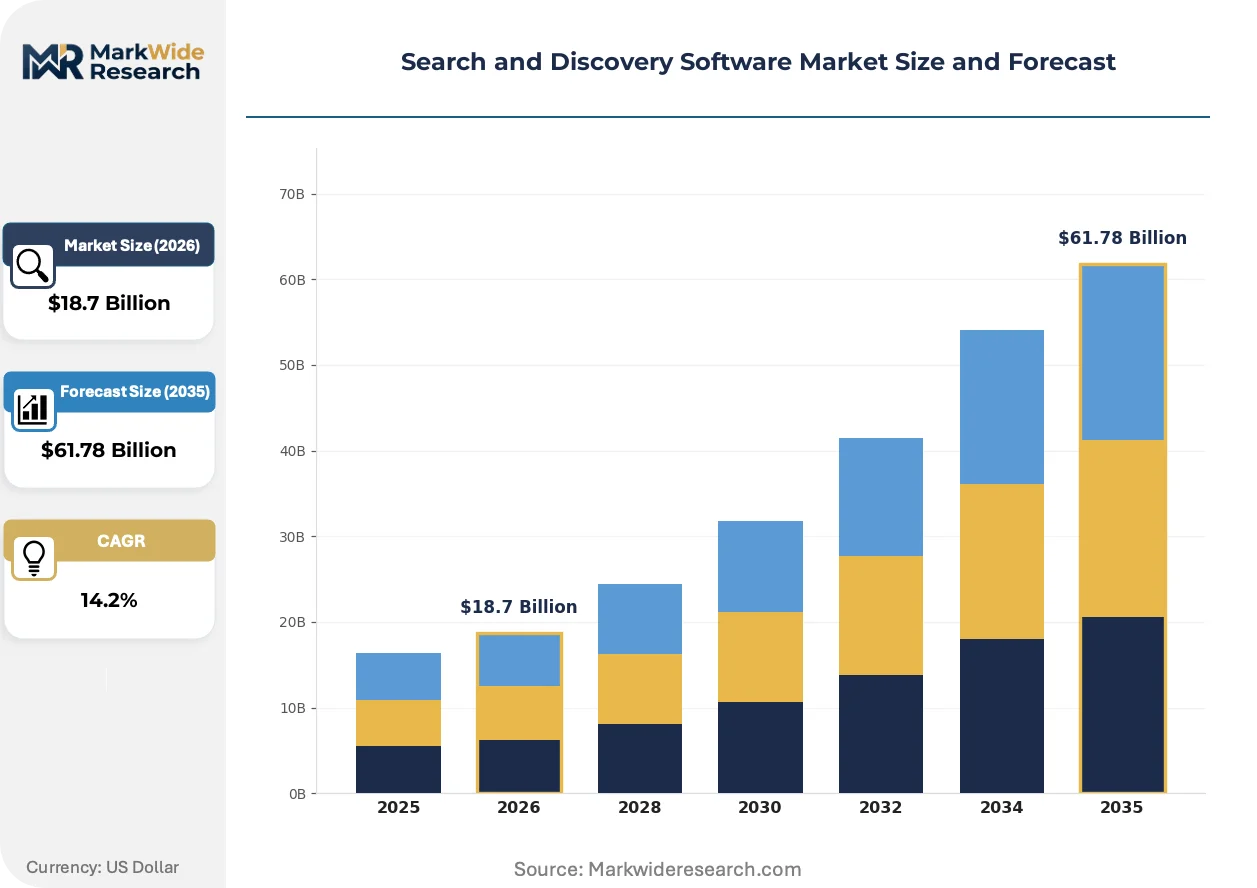
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Cloud-Based, On-Premise, Hybrid, AI-Powered Application: Enterprise Search, E-Commerce, Data Analytics, Knowledge Management End User: SMEs, Large Enterprises, Government, Educational Institutions Deployment Model: Public Cloud, Private Cloud, Multi-Tenant, Single-Tenant |
| Companies Covered | Google, Elastic, GoSearch, Guru, Algolia, Glean, Coveo, AlphaSense, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Search and Discovery Software Market Emerging Trajectories
Neural retrieval architectures are restructuring competitive advantage around latency-optimized inference stacks rather than index scale alone. Vendors are racing to embed automated relevance feedback loops that compress the human-in-the-loop tuning cycle.
Retrieval-augmented generation is electrifying enterprise knowledge workflows by grounding large language model outputs in verifiable source documents. Financial services compliance teams are deploying RAG pipelines for real-time regulatory interpretation at scale. This convergence is compressing the traditional boundaries between search interfaces and decision-support systems.
The EU AI Act's high-risk system classification is forcing vendors serving automated decision markets to implement explainability layers and human oversight mechanisms. Product roadmaps are pivoting toward interpretable ranking signals and audit-ready relevance logs. Healthcare and financial services procurement evaluations now weight algorithmic accountability certifications above raw retrieval accuracy metrics.
Enterprise buyers are consolidating vendor relationships around platform suites that bundle search with adjacent knowledge management capabilities. Standalone search procurement is contracting as CIOs prioritize integrated cognitive infrastructure under single support contracts. This pattern is most visible in United States and Germany, where IT rationalization programs are retiring point solutions in favor of cloud-native platform consolidation.
Search and Discovery Software Market Segmentation
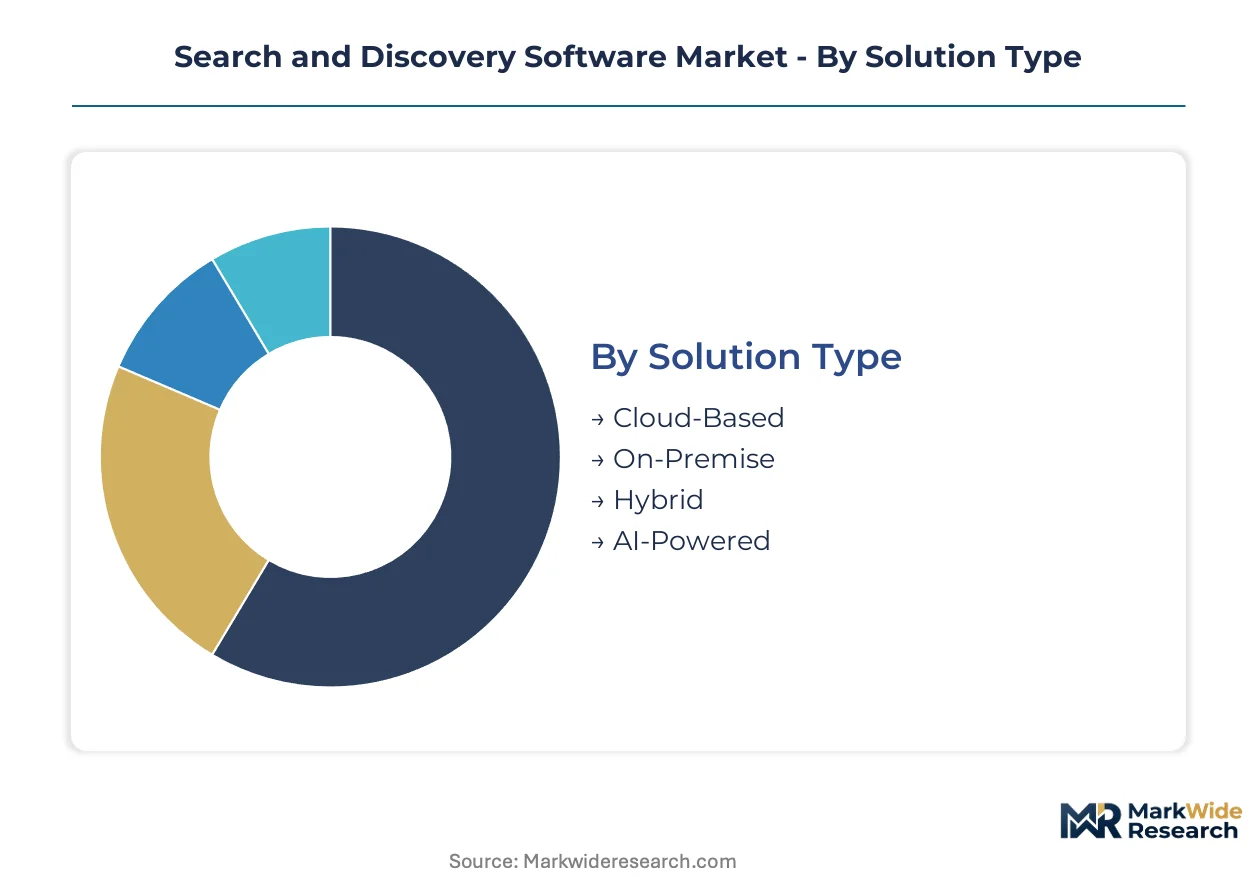
Search and discovery software procurement patterns diverge sharply across infrastructure choices, use cases, and buyer scale. Vendors must architect pricing and packaging around these fault lines to capture margin in a consolidating market.
Solution Type:
Supply concentration in GPU-accelerated inference stacks favors vendors with captive cloud infrastructure over pure software licensors.
- Cloud-Based:Multi-tenant architectures with auto-scaling index clusters dominate procurement among mid-market buyers. Financial services firms in the United States and Germany are retiring on-premise search appliances for consumption-based pricing that aligns cost with query volume volatility.
- AI-Powered:Neural ranking models with embedding-based retrieval and automated relevance tuning command premium pricing. Vector database convergence is displacing inverted-index systems in customer-facing discovery applications across Indian IT services firms and European e-commerce platforms.
- On-Premise:Air-gapped deployments persist in defense and classified government environments with strict data sovereignty requirements.
- Hybrid:Split architectures index sensitive repositories locally while federating queries to cloud analytics layers.
Today's leader: Cloud-Based. Tomorrow's challenger: AI-Powered.
Application:
Margin pools concentrate where search interfaces converge with automated decision workflows rather than standalone information retrieval.
- Enterprise Search:Unified cognitive platforms ingest structured and unstructured repositories to accelerate compliance review cycles. Investment banks and insurance carriers are replacing legacy document management with GDPR-integrated lineage tracking and automated deletion workflows.
- E-Commerce:Real-time personalization engines with visual search and semantic product matching drive conversion optimization. Retail technology stacks in Germany and India are embedding discovery modules that compress the path from query to transaction.
- Knowledge Management:Expertise location and institutional memory preservation tools serve professional services and consulting organizations.
- Data Analytics:Search-driven BI interfaces democratize SQL-free exploration of data warehouse contents.
Enterprise Search captures current procurement volume. E-Commerce is climbing the fastest as digital commerce infrastructure modernizes.
End User:
Buyer sophistication tiers dictate sales motion complexity and implementation support requirements.
- Large Enterprises:Global 2000 organizations demand SOC 2 Type II certification, 12-month continuous audit windows, and dedicated customer success engineering. Procurement cycles elongate as CIOs rationalize point solutions into integrated cognitive infrastructure suites.
- SMEs:Mid-market buyers prioritize rapid deployment templates and pre-configured connectors over customization depth.
- Government:Public sector tenders require FedRAMP or equivalent national security clearances with mandatory onshore data residency.
- Educational Institutions:Universities and research libraries seek open-source compatibility and federated search across disparate campus repositories.
Large Enterprises anchor vendor revenue today. SMEs represent the steepest expansion trajectory as self-service onboarding tools mature.
Deployment Model:
Infrastructure isolation preferences segment buyers by regulatory exposure and data gravity patterns.
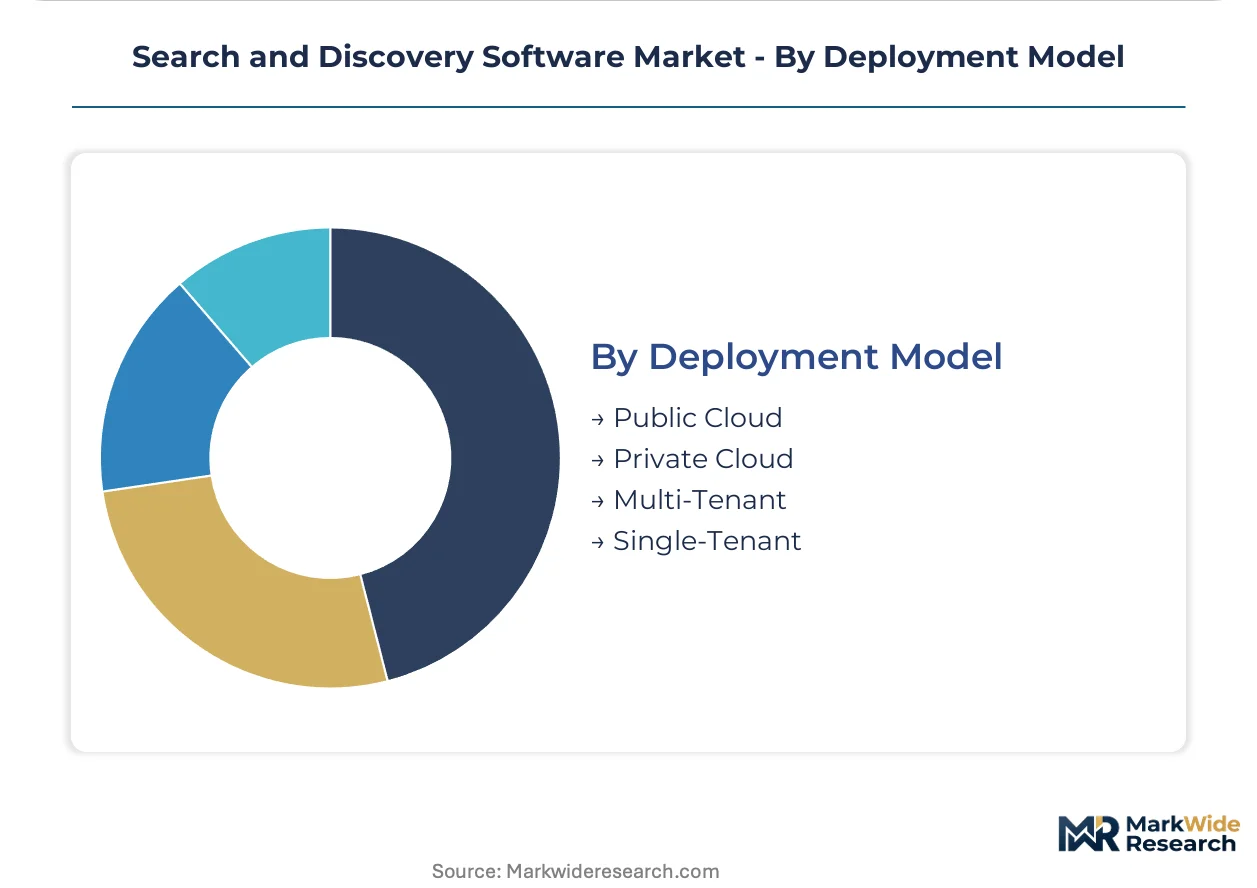
- Public Cloud:Shared infrastructure with provider-managed security patches and automatic version updates. HIPAA-covered entities in the United States and CSRD-reporting European corporations are procuring governance-integrated platforms with automated materiality assessment capabilities.
- Private Cloud:Dedicated virtualized environments within buyer-controlled network perimeters.
- Multi-Tenant:Logical isolation with shared compute resources and tenant-specific encryption key management.
- Single-Tenant:Physically isolated stacks for maximum audit control and custom compliance certification.
Public Cloud dominates new procurement. Private Cloud is gaining share fastest among EU AI Act high-risk system operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise search and discovery software emerged from Silicon Valley's information retrieval laboratories during the 1990s web indexing revolution. The technology stack later migrated to commercial data centers in the United States, Germany, and India as cloud infrastructure matured. Today's procurement patterns reflect this geographic lineage.
United States
Financial services modernization and HIPAA technical safeguard compliance drive enterprise adoption across investment banks and insurance carriers. The SEC's algorithmic trading transparency requirements push vendors toward audit-ready relevance logging. New York and San Francisco clusters host the densest concentration of RAG pipeline deployments for real-time regulatory interpretation.
Germany
CSRD-mandated ESG disclosure and EU AI Act high-risk system classification reshape procurement priorities among DAX-listed manufacturers. The country's national data protection authority enforces GDPR Article 17 deletion workflows with particular rigor. Munich and Frankfurt serve as hubs for governance-integrated search platform implementations.
India
PLI scheme beneficiaries and domestic IT services firms accelerate knowledge infrastructure digitization at scale. RBI guidelines on data localization influence hybrid deployment preferences among banking sector buyers. Bengaluru and Hyderabad clusters exhibit the steepest growth trajectory for vector database convergence in customer-facing applications.
United Kingdom
Financial conduct authority scrutiny of automated decision systems elevates algorithmic accountability in procurement evaluations. The Information Commissioner's Office enforces stringent indexed data lineage requirements. London's fintech corridor concentrates demand for sub-second contextual retrieval across petabyte-scale repositories.
Japan
METI's digital transformation incentives and PMDA software-as-medical-device guidelines shape healthcare sector deployments. Domestic manufacturers prioritize private cloud architectures for intellectual property protection. Tokyo and Osaka metropolitan areas anchor enterprise search modernization among precision engineering conglomerates.
Search and Discovery Software Market Vendor Landscape
Premium-margin players sit above commodity-margin players across inference latency and automated relevance tuning capabilities. The vendor base stratifies into three tiers: cloud-native platform consolidators, vertical specialization specialists, and open-source distribution maintainers. Strategic archetypes include GPU-accelerated inference stack operators, compliance-integrated suite bundlers, and embedding-based retrieval architects. Dominant competitive moves encompass M&A-driven cognitive infrastructure consolidation and strategic partnerships for vector database convergence.
Within the cloud-native platform tier, Google and Microsoft occupy positions as hyperscale infrastructure integrators extending consumer search architectures into enterprise environments. Elastic exemplifies the open-source distribution archetype with its distributed search engine licensing model. Coveo sits within the vertical specialization vector, anchoring customer-facing discovery applications through industry-specific relevance tuning.
| Leading Market Players |
|---|
| Elastic |
| GoSearch |
| Guru |
| Algolia |
| Glean |
| Coveo |
| AlphaSense |
| Microsoft |
| Others |
Supply Flow & Price Mechanics
Vector database convergence and embedding-based retrieval architectures are compressing traditional inverted-index economics while concentrating GPU-accelerated inference capacity among hyperscale cloud operators. This technological pivot simultaneously elevates compute costs as a pricing determinant and tightens vendor dependency on captive infrastructure in the United States, Germany, and India.
Pricing Analysis
Consumption-based SaaS tiers with query-volume scaling dominate procurement among mid-market buyers, while enterprise deployments command fixed-fee platform licensing with dedicated customer success engineering. Price differentiation rests on SOC 2 Type II certification status and sub-100ms latency guarantees for neural ranking models. Cost compression in standard-tier offerings is intensifying because GPU compute pricing volatility distorts total cost of ownership projections for inference-intensive architectures. SMEs exhibit highest price sensitivity, deferring to open-source distributions; large enterprises absorb premium pricing for governance-integrated lineage tracking and automated deletion workflows.
Supply Chain Analysis
ISO 27001 and SOC 2 Type II certification gating concentrates vendor qualification among established cloud-native platform operators with continuous audit capabilities. Supply concentrates in the United States, Germany, and India, where hyperscaler data center expansion feeds GPU-accelerated inference stacks. The supply chain draws from NVIDIA GPU allocations, vector database software licenses, and annotated query-document relevance datasets. Single-source vulnerability around high-quality training data clusters within academic institutions and technology incumbents. Distribution runs through direct enterprise sales teams with 12-month implementation cycles, supplemented by systems integrator partnerships for legacy ECM middleware development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act enforcement timeline compounds procurement urgency among financial services and healthcare buyers, transforming compliance-integrated search platforms from discretionary spend into mandated infrastructure. This regulatory compounding effect creates defensive moats for certified vendors while compressing sales cycles for qualified alternatives.
For Market Incumbents: Hedge against vector database commoditization by deepening backward integration into proprietary embedding architectures and securing exclusive relevance dataset partnerships. Elastic and Google must defend their positions against emerging GPU-accelerated inference specialists by accelerating SOC 2 Type II certification pipelines for mid-market segments. Capacity addition in Indian cloud regions addresses PLI scheme beneficiary demand while reducing latency to Bengaluru and Hyderabad IT services clusters. For New Entrants and Emerging Players: Mid-market SMEs with limited MLOps engineering capacity represent the most penetrable buyer archetype, underserved by complex enterprise platforms requiring dedicated implementation support. White-space targets include conversational interface modules for natural language-to-insight workflows and CSRD-mandated ESG document intelligence tools for European manufacturers. A product-led growth motion with self-service onboarding templates and pre-configured SAP connector libraries bypasses elongated procurement cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among open-source distribution maintainers with established developer communities but undermonetized enterprise pipelines. Long-term viability over the next decade hinges on successful platform bundling with adjacent knowledge management capabilities rather than standalone search licensing. Acquisition target archetypes include vertical specialization specialists with industry-specific relevance tuning in financial services or healthcare. The signal to watch is EU AI Act high-risk system classification expansion beyond automated decision systems into retrieval-augmented generation pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bundling search with knowledge management suites captures IT rationalization budgets in the United States and Germany. |
| Strategic Partnership | Vector database convergence agreements with cloud hyperscalers secure GPU-accelerated inference capacity for sub-100ms latency. |
| Acquisition of Specialist Firm | Vertical relevance tuning expertise in financial services compliance accelerates RAG pipeline deployment for regulatory interpretation. |
| Geographic Expansion | Indian cloud region buildout serves PLI scheme beneficiaries and domestic IT services firms modernizing knowledge infrastructure. |
| Product Launch | Conversational interface modules embedding large language models create new natural language-to-insight workflow categories. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers, platform engineers, and channel partners with secondary validation. SEC filings, hyperscaler capex disclosures, enterprise software vendor 10-K reports, and EU regulatory impact assessments supplied foundational data. Bottom-up triangulation across deployment model, organization size, vertical, and regional adoption patterns converged with top-down market sizing.
Comparable-period anchoring to historical cloud infrastructure spending and enterprise software procurement cycles grounded projections across the analysis window. Segmentation dimensions modeled encompassed solution type, application, end user scale, and deployment model complexity. CAGRs were derived from elasticity-adjusted demand curves incorporating GPU compute pricing volatility and EU AI Act compliance cost pass-through. Neural ranking model productionization timelines and SOC 2 Type II audit completion rates served as industry-specific forecast inputs.
Inputs from vendor financial disclosures and regulatory impact statements were available through the study window; gaps in private company pricing data and unreported contract values introduce uncertainty bands around market share estimates. Forecasts reflect assumptions regarding EU AI Act enforcement rigor and cloud infrastructure expansion trajectories. A model refresh is warranted upon material change in GPU compute pricing regimes or algorithmic accountability framework expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Enterprise Data Observability Software Market
Software & Services
Independent Software Vendors (Isvs) Market
Software & Services
Enterprise Intellectual Property (IP) Management Software Market
Software & Services
Global Application Performance Monitoring (APM) Market
Software & Services
Global Equity Management Software Market
Software & Services
Global Forestry Software Market
Software & Services
Application Server Market
Software & Services
Productivity Management Software Market
Software & Services
Account-Based Advertising Software Market
Software & Services
Know Your Customer Software Market
Software & Services
Global Sales Engagement Platform Market
Software & Services
Europe Yacht Management Software Market
Software & Services
API Testing Market
Software & Services
Microsoft Office 365 Integration Services Market
Software & Services
CAM Software Market
Software & Services
Emotion Recognition and Sentiment Analysis Software Market