
 Android Emulator Market | 2026-2036
Android Emulator Market Size, Share, and Industry Trends Forecast 2026-2036
Android Emulator Market Insights
The EU AI Act is restructuring compliance obligations for emulator platforms processing biometric or behavioral data from European users, forcing vendors to engineer privacy-preserving architectures that raise fixed development costs. BlueStacks leverages its Windows-centric distribution network to sustain market presence across consumer gaming segments. Genymotion anchors its position in enterprise CI/CD pipelines through specialized cloud-based device farm integrations. NoxPlayer competes on modularity, offering scriptable automation layers that appeal to power users in East Asian markets.
An Android emulator is a virtualized computing environment that replicates ARM or x86 mobile processor architectures, GPU rendering pipelines, and sensor subsystems on desktop operating systems, enabling software validation without physical hardware. The technology serves primary commercial purposes spanning application development, quality assurance automation, and mobile game streaming to non-native platforms. Cloud-based deployment models are capturing the fastest expansion as enterprises abandon on-premise device labs for elastic, pay-per-test infrastructure. Developers represent the most entrenched user type, though enterprise procurement of integrated CI/CD emulator solutions is generating the highest per-seat margins. Containerized integration levels are displacing standalone installations among platform engineering teams seeking reproducible build environments.
FDA scrutiny of diagnostic applications running on emulated medical devices is tightening validation documentation requirements for healthcare software vendors. The EU Green Deal's data center efficiency mandates are pressuring cloud emulator providers to disclose carbon intensity metrics tied to virtualized compute workloads. ISO 25010 software quality standards shape how testing tool vendors position reliability and performance benchmarks to enterprise buyers. Stakeholders must weigh regulatory compliance velocity against feature differentiation as the primary axis of competitive investment.
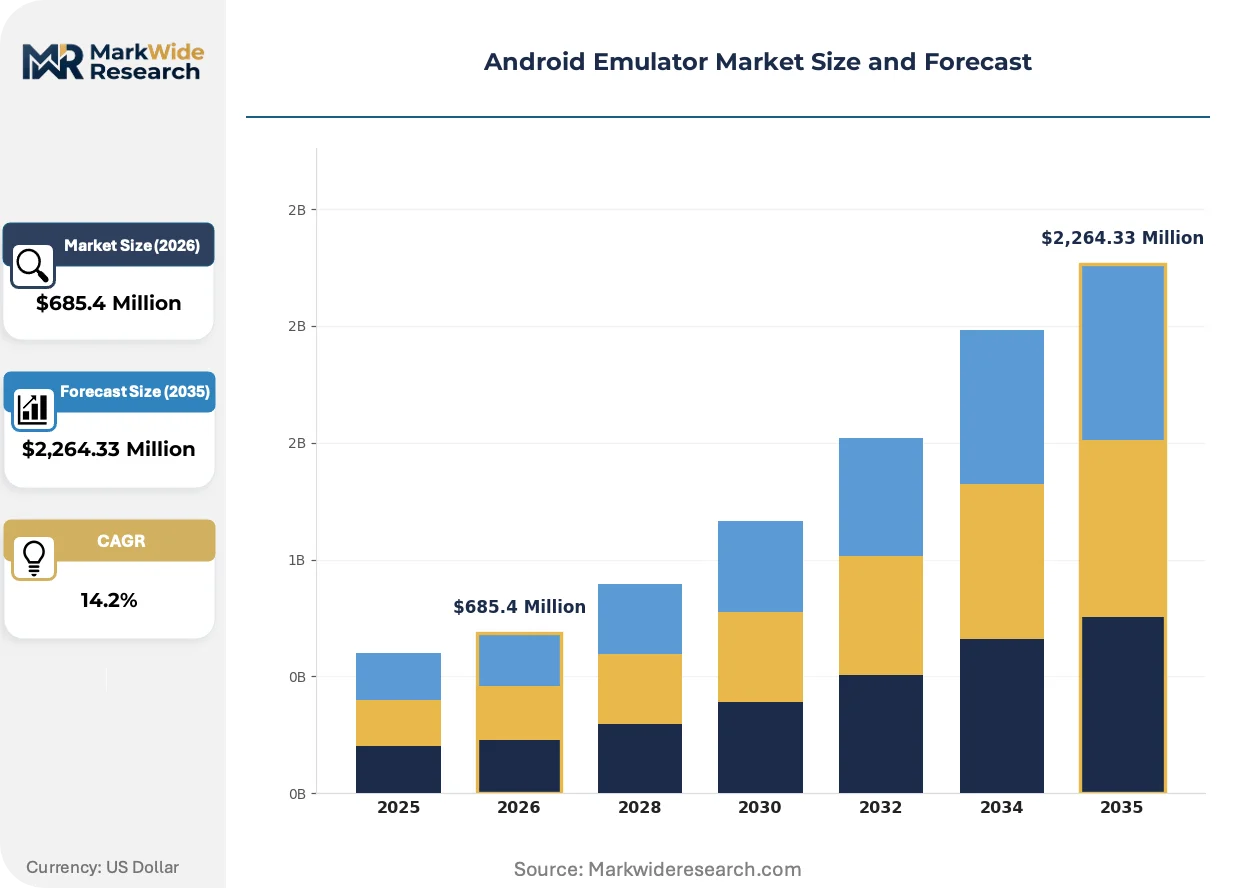
Market Dynamics
Cloud-native virtualization architectures are compressing release cycles and forcing emulator vendors to abandon standalone desktop products for containerized, API-first delivery models that integrate directly into CI/CD pipelines.
Growth Catalysts
- EU AI Act compliance mandates:Biometric and behavioral data processing restrictions are compelling European enterprises to adopt privacy-preserving emulator architectures for testing, expanding addressable demand for compliant tooling.
- Mobile game streaming infrastructure:Cloud gaming platforms require ARM-compatible virtualization layers to render mobile titles on x86 server farms, pulling emulator technology into data center buildouts.
- Container orchestration convergence:Kubernetes-native emulator deployments enable reproducible test environments that platform engineering teams at software firms now specify as procurement requirements.
Market Restraints
- GPU virtualization licensing costs:NVIDIA and AMD per-socket licensing for vGPU technology in cloud emulator farms creates margin pressure that limits price competitiveness against physical device labs.
- FDA validation documentation burdens:Diagnostic application developers face expanded pre-market submission requirements when emulating medical devices, lengthening sales cycles for healthcare-focused emulator vendors.
- ARM architecture licensing fragmentation:Proprietary extensions from Qualcomm, Samsung, and MediaTek force emulator developers to maintain multiple silicon-specific code branches, raising fixed engineering overhead.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Domestic mobile device production incentives are spawning local testing ecosystems where emulator vendors can anchor before hardware supply chains mature.
- EU Green Deal carbon intensity disclosure:Data center efficiency mandates create competitive differentiation for emulator platforms that meter and report per-test carbon footprints to sustainability procurement teams.
- 5G network slicing test automation:Convergence of emulator virtualization with software-defined radio interfaces enables automated validation of carrier-specific network configurations without physical lab infrastructure.
Industry Challenges
- Specialized ARM-to-x86 translation engineering:Deep expertise in binary translation and GPU passthrough virtualization remains concentrated among a small talent pool, constraining vendor scaling velocity.
- ISO 25010 quality standard certification timelines:Enterprise procurement teams increasingly require documented reliability and performance benchmark compliance, extending pre-contract validation periods.
- Legacy on-premise device farm integration:Hybrid deployments combining cloud emulators with residual physical hardware create API compatibility and test result reconciliation complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Android Emulator Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,264.33 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premise, Hybrid, Open Source Operating System: Windows, macOS, Linux, Chrome OS User Type: Developers, Testers, Casual Users, Enterprises Integration Level: Standalone, Integrated, API-Based, Containerized |
| Companies Covered | NoxPlayer, Genymotion, BlueStacks, Android Studio, GameLoop, LDPlayer, MEmu Play, NetEase, MuMu Player, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Android Emulator Market Trends and Innovations
Virtualization technology is converging with cloud orchestration and privacy engineering, producing three distinct vectors of change that vendors must navigate simultaneously.
WebAssembly-based emulator runtimes are electrifying browser-native mobile testing by eliminating local installation requirements. Quality assurance teams at SaaS firms now embed emulated device sessions directly into ticketing workflows. This architecture is compressing the traditional gap between developer-local testing and CI-integrated validation.
GDPR Article 35 data protection impact assessments are reshaping how emulator platforms handle screen recordings and input logs from European users. Vendors must now engineer automated data minimization pipelines that purge biometric artifacts within defined retention windows. Healthcare and fintech application developers face the steepest compliance engineering costs.
Consumption-based pricing for emulator compute minutes is displacing perpetual licensing across enterprise procurement patterns. Platform engineering teams at mid-market software firms now specify pay-per-test contracts that align testing costs with release frequency. This shift is most visible in United States technology hubs where DevOps maturity supports granular usage metering.
Android Emulator Market Segmentation
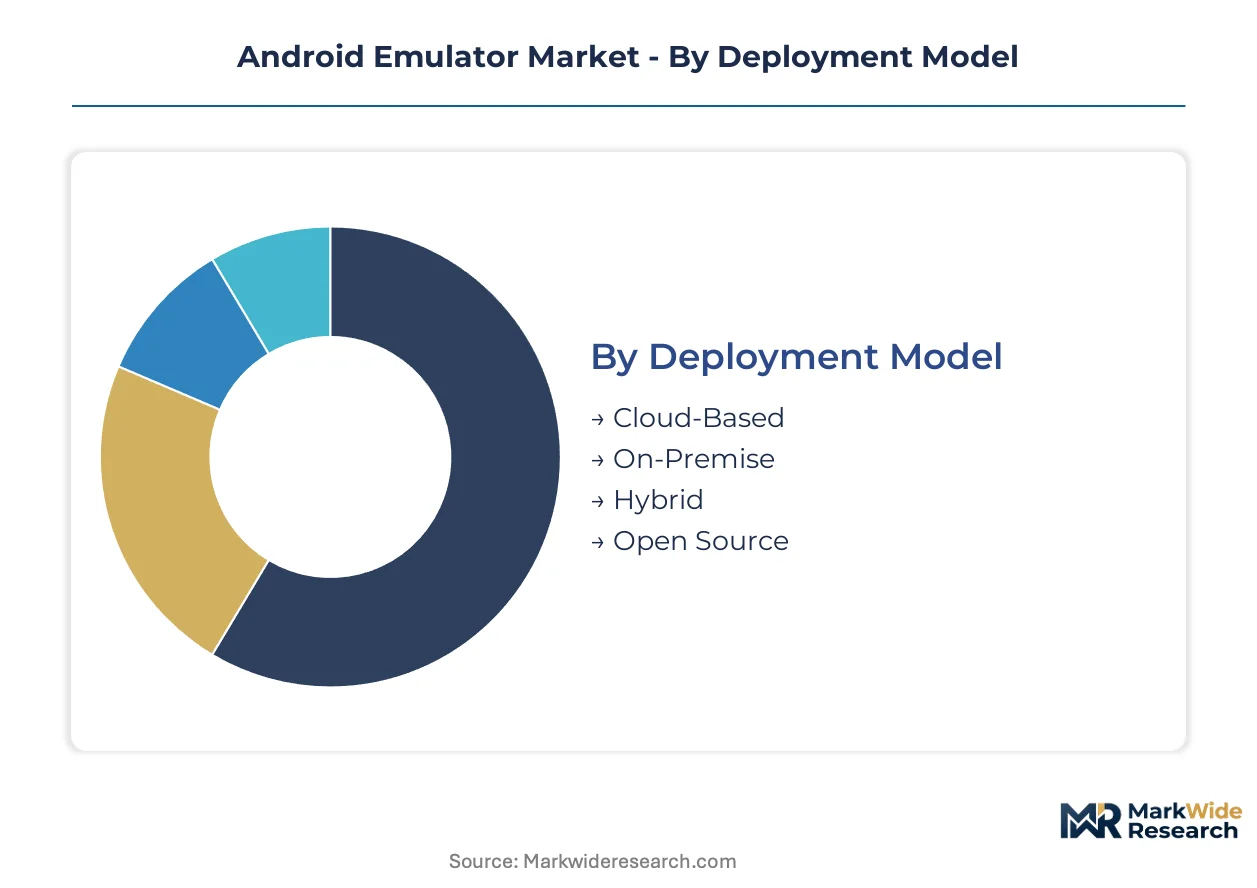
Android emulator procurement patterns diverge sharply across deployment preferences, operating system ecosystems, and integration sophistication. Vendors must architect product lines that span hobbyist price sensitivity to enterprise API requirements without fragmenting engineering resources.
Deployment Model:
Customization intensity varies from fully managed cloud services to self-hosted open-source builds, creating distinct margin profiles and support obligations across the spectrum.
- Cloud-Based:Elastic compute provisioning enables pay-per-test metering that aligns costs with CI/CD release velocity. United States DevOps teams at mid-market SaaS firms now specify cloud-native emulator infrastructure as a procurement baseline.
- On-Premise:Dedicated hardware installations persist in regulated industries requiring air-gapped validation environments. FDA-scrutinized diagnostic application developers maintain on-premise emulator farms to satisfy pre-market submission documentation requirements.
- Hybrid:Mixed deployments balance sensitive workload isolation with burst capacity flexibility. Financial services firms in Frankfurt and Singapore operate hybrid architectures to reconcile GDPR data residency with elastic testing demand.
- Open Source:Community-maintained builds attract cost-constrained developers and academic researchers. Android Studio's emulator components provide a foundation that regional systems integrators in India extend for domestic mobile testing ecosystems.
Leading the category by volume: Cloud-Based. Expanding most quickly: Hybrid.
Operating System:
Host platform distribution reflects enterprise desktop standardization and developer preference clustering across technology hubs.
- Windows:Dominant consumer gaming segment penetration leverages DirectX GPU passthrough and broad hardware compatibility. BlueStacks sustains market presence through Windows-centric distribution networks that reach casual users across North American and European markets.
- macOS:Preferred by iOS-first development studios requiring cross-platform mobile validation. Apple's ARM transition to Apple Silicon has forced emulator vendors to engineer Rosetta-compatible binary translation layers.
- Linux:CI/CD pipeline standard for containerized test orchestration. Google's Android Studio team prioritizes Linux kernel module stability to support cloud emulator farm deployments.
- Chrome OS:Emerging education and lightweight enterprise segment driven by Google's hardware ecosystem expansion. K-12 coding curricula in South Korea and Taiwan deploy Chromebook-native emulators for introductory mobile development instruction.
Highest margin concentration: macOS. Steepest volume climb: Chrome OS.
User Type:
Commercial sophistication ranges from individual hobbyists to procurement-driven enterprise platforms, shaping pricing architecture and feature roadmaps.
- Developers:Local debugging and rapid iteration workflows demand low-latency GPU rendering and sensor simulation fidelity. Individual developers represent the most entrenched user base, though per-seat economics lag enterprise procurement.
- Testers:Quality assurance automation requires scriptable device state management and screenshot capture pipelines. QA teams at SaaS firms embed emulated sessions directly into Jira and ServiceNow ticketing workflows.
- Casual Users:Mobile game streaming on non-native platforms drives consumer emulator adoption. NoxPlayer's modular automation layers capture power users in East Asian gaming markets.
- Enterprises:Integrated CI/CD solutions generate the highest per-seat margins through annual platform contracts. Genymotion anchors enterprise positioning through specialized cloud-based device farm integrations.
Maximum revenue per seat: Enterprises. Gaining share fastest: Testers.
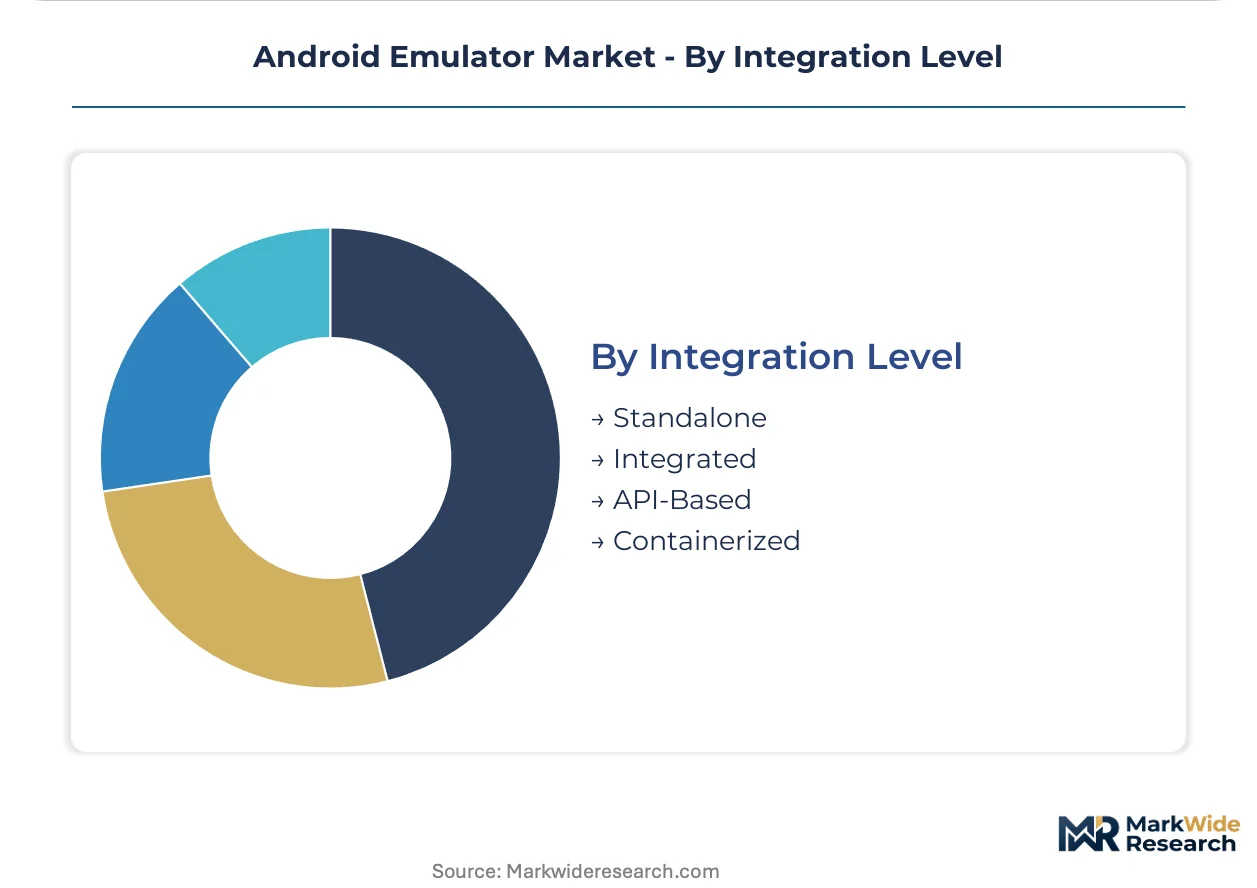
Integration Level:
Technical embedding depth determines vendor stickiness and switching costs across the software delivery lifecycle.
- Standalone:Traditional desktop installations persist among individual developers and small teams. Installation friction and version drift limitations are accelerating migration toward more integrated alternatives.
- Integrated:IDE-native emulator panels compress the gap between local development and validation. Android Studio's emulator architecture refinements compress release cycles for third-party tool vendors dependent on Google's platform.
- API-Based:Headless device control enables test automation frameworks to orchestrate emulator fleets programmatically. Platform engineering teams specify API-first procurement requirements to enable reproducible build environments.
- Containerized:Kubernetes-native deployments are displacing standalone installations among DevOps-mature organizations. Container orchestration convergence enables reproducible test environments that align with GitOps workflows.
Dominant legacy footprint: Standalone. Climbing the fastest: Containerized.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's concentration of DevOps-mature SaaS firms and Seattle's cloud infrastructure headquarters anchor North American emulator demand. India's PLI scheme for electronics manufacturing spawns regional testing ecosystems. Germany's automotive software clusters and China's mobile gaming studios complete the geographic spread.
United States
Enterprise DevOps teams in San Francisco and Seattle drive premium licensing volumes for CI/CD-integrated emulator platforms. FDA scrutiny of diagnostic applications running on emulated medical devices tightens validation documentation requirements for healthcare software vendors. Austin's emerging tech corridor attracts emulator vendors establishing regional sales operations.
China
Shenzhen's hardware manufacturing ecosystem and Shanghai's mobile gaming studios generate concentrated demand for ARM-compatible virtualization. MIIT's data localization requirements push domestic enterprises toward locally-hosted emulator infrastructure. Hangzhou's Alibaba-led cloud computing cluster incubates containerized testing platforms for regional developers.
Germany
Automotive software developers in Stuttgart and Munich require emulator farms for validating infotainment systems across fragmented Android versions. EU Green Deal carbon intensity disclosure mandates pressure cloud emulator providers to meter per-test carbon footprints. Berlin's startup density sustains open-source emulator community contributions.
India
Bengaluru's SaaS export industry and Hyderabad's IT services corridor adopt pay-per-test cloud emulator contracts to align testing costs with release velocity. PLI scheme incentives for domestic mobile device production spawn local testing ecosystems before hardware supply chains mature. Mumbai's fintech application developers face steep GDPR compliance engineering costs for European user data.
South Korea
Seoul's mobile gaming powerhouses and Samsung's device manufacturing operations demand silicon-specific emulator architectures for proprietary ARM extensions. K-12 coding curricula deploy Chromebook-native emulators for introductory mobile development instruction. Busan's logistics technology sector experiments with 5G network slicing test automation through software-defined radio interfaces.
Android Emulator Market Competitive Landscape
United States producers anchor the premium enterprise tier; East Asian specialists hold consumer gaming segments through modular automation layers. The vendor base spans consolidated platform engineering vendors and fragmented regional tool builders. Three archetypes dominate: cloud-native CI/CD integrators, Windows-centric consumer distributors, and open-source IDE-embedded engines. Competitive moves concentrate on Kubernetes-native containerization and API-first delivery models that compress release cycles.
Within the cloud-native tier, Genymotion occupies a position exemplifying enterprise-focused device farm integration, while BlueStacks represents Windows-centric consumer gaming distribution. NoxPlayer anchors the modular automation archetype appealing to power users. These three companies illustrate how geographic origin and architectural specialization stratify competitive positioning across deployment models and user types.
| Leading Market Players |
|---|
| NoxPlayer |
| Genymotion |
| BlueStacks |
| Android Studio |
| GameLoop |
| LDPlayer |
| MEmu Play |
| NetEase |
| MuMu Player |
| Others |
Pricing and Supply Chain Analysis
GPU virtualization licensing fees from NVIDIA and AMD cascade through cloud emulator farm operators into premium SaaS tiers, while containerized deployment tooling compresses mid-market pricing toward open-source alternatives. This cost structure stratifies procurement across enterprise DevOps teams, regional systems integrators, and individual developers.
Pricing Analysis
Short lead-time provisioning commands premium rates in cloud-native emulator contracts, with spot capacity availability driving discounting for flexible scheduling. Consumption-based metering across pay-per-test contracts now dominates enterprise procurement, while per-seat SaaS tiers persist for mid-market software firms. Price differentiation hinges on Kubernetes-native containerization depth and ISO 25010 quality certification status. Pricing pressure stems from AMD's competitive vGPU licensing entry against NVIDIA's established socket-based fees. Individual developers exhibit highest price sensitivity, gravitating toward Android Studio's embedded emulator; enterprise platform engineering teams show lowest sensitivity when CI/CD integration depth justifies annual platform commitments.
Supply Chain Analysis
Freight costs for dedicated server hardware into European and Indian data centers amplify total cost of ownership for on-premise emulator deployments against cloud-native alternatives. Engineering talent concentrates in the United States, Germany, and South Korea, with ARM-to-x86 binary translation expertise remaining scarce. Silicon supply draws from Taiwan's foundry ecosystem, Qualcomm's San Diego design centers, and Samsung's Seoul R&D campuses. Single-source vulnerability sits with NVIDIA's vGPU software stack dominance in cloud rendering pipelines. Distribution runs through hyperscaler marketplaces—AWS, Azure, Google Cloud—rather than traditional enterprise software channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container orchestration convergence is accelerating vendor consolidation as Kubernetes-native capabilities become non-negotiable procurement requirements, forcing standalone desktop emulator vendors toward acquisition or exit.
For Market Incumbents: Lock in enterprise DevOps relationships through API-first CI/CD integrations that embed emulator fleets directly into GitOps workflows. Deepen vertical integration into ARM architecture licensing to reduce Qualcomm and MediaTek royalty exposure. Counter AWS Device Farm and Firebase Test Lab encroachment by emphasizing on-premise air-gapped deployment options for FDA-scrutinized healthcare developers. For New Entrants and Emerging Players: Chrome OS education channel partnerships offer the most penetrable white-space entry, with K-12 coding curricula in South Korea and Taiwan seeking lightweight browser-native emulation. India's PLI scheme spawns regional testing ecosystems before domestic hardware supply chains mature. Pursue WebAssembly-based runtime architectures that eliminate local installation friction for SaaS quality assurance teams embedding emulated sessions into ticketing workflows. For Investors and Strategic Acquirers: Google's Android Studio emulator architecture refinements are the leading indicator that third-party tool vendors face compressed release cycle pressure and margin erosion. Five-to-ten-year viability favors cloud-native CI/CD integrators with established Kubernetes operator ecosystems. Target acquisition profiles emphasize containerized API-first delivery models over legacy standalone desktop installers.| Strategic Initiative | Industry Significance |
|---|---|
| Container-Native Platform Integration | Kubernetes operator certification embeds emulator infrastructure into GitOps workflows at SaaS firms. |
| Privacy-Preserving Architecture Engineering | EU AI Act compliance investments differentiate vendors for European enterprise procurement teams. |
| Carbon Intensity Metering Development | EU Green Deal disclosure mandates create competitive wedge for sustainability-focused platform buyers. |
| Healthcare Validation Documentation | FDA pre-market submission support captures diagnostic application developer spending. |
| WebAssembly Runtime Deployment | Browser-native emulation eliminates installation friction for Jira-embedded QA workflows. |
Research Methodology
Document review covered SEC filings from virtualization technology vendors, hyperscaler capex disclosures, and EU regulatory guidance on AI Act implementation, complemented by interviews with platform engineering directors at mid-market SaaS firms, DevOps tooling procurement officers, and quality assurance automation leads. Secondary validation drew from Android Studio release documentation, Kubernetes ecosystem survey data, and cloud infrastructure spending reports. Bottom-up demand modeling across user type segments triangulated against top-down market sizing from enterprise licensing disclosures.
Segmented outputs across deployment model, operating system ecosystem, integration sophistication, and geographic adoption pattern fed into analytical framework construction across the projection horizon. CAGRs were derived from elasticity modeling against CI/CD pipeline expansion rates and mobile game streaming infrastructure buildouts. Key inputs included container orchestration penetration curves and ARM architecture licensing cost trajectories.
The model holds under sustained DevOps tooling budget expansion and stable hyperscaler pricing; deviation in GPU virtualization licensing terms or EU regulatory enforcement intensity would shift enterprise procurement patterns. Forecasts reflect documented assumptions on Kubernetes adoption velocity and cloud gaming platform infrastructure commitments. Stakeholders should weight assumptions against their own operating context and vertical regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Integration Brokerage Software Market
Software & Services
Tag Management Software Market
Software & Services
Global Club Management Software Market
Software & Services
IT Service Management Tools Market
Software & Services
Machine Translation Software Market
Software & Services
Paraphrasing Tools Market
Software & Services
Application Performance Management (APM) Software Market
Software & Services
Global Polling Software Market
Software & Services
House Cleaning App Market
Software & Services
3D CAD Software Market
Software & Services
Global Product Management and Road Mapping Tool Market
Software & Services
Global Employee Engagement Software Market
Software & Services
Global Spa and Salon Software Market
Software & Services
Codeless Testing Market
Software & Services
Remote Desktop Software Market
Software & Services
RIP Color Management Software Market