
 Global Construction Management Software Market | 2026-2036
Global Construction Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Construction Management Software Market Analysis
Modular unbundling of project management, cost estimation, and scheduling functions is decoupling what buyers once purchased as monolithic suites. Procore leverages its cloud-native architecture to anchor mid-market contractor adoption across North America. Bentley Systems differentiates through deep engineering-grade BIM integration that sustains loyalty among infrastructure designers. Autodesk Construction Cloud competes by extending platform breadth across design-to-build handoffs.
Construction management software coordinates planning, resource allocation, budget tracking, and field communication through centralized digital environments, typically operating via cloud servers with API connectivity to accounting and design systems. Its primary commercial purpose is reducing project overruns by synchronizing schedules, change orders, and subcontractor deliverables in real time. Cloud-based deployment now leads solution preferences among customer types seeking lower upfront capital commitment and faster implementation cycles. Project management modules command the widest installed base, while cost estimation functions represent the fastest-growing solution category as margin pressure intensifies across contractor segments.
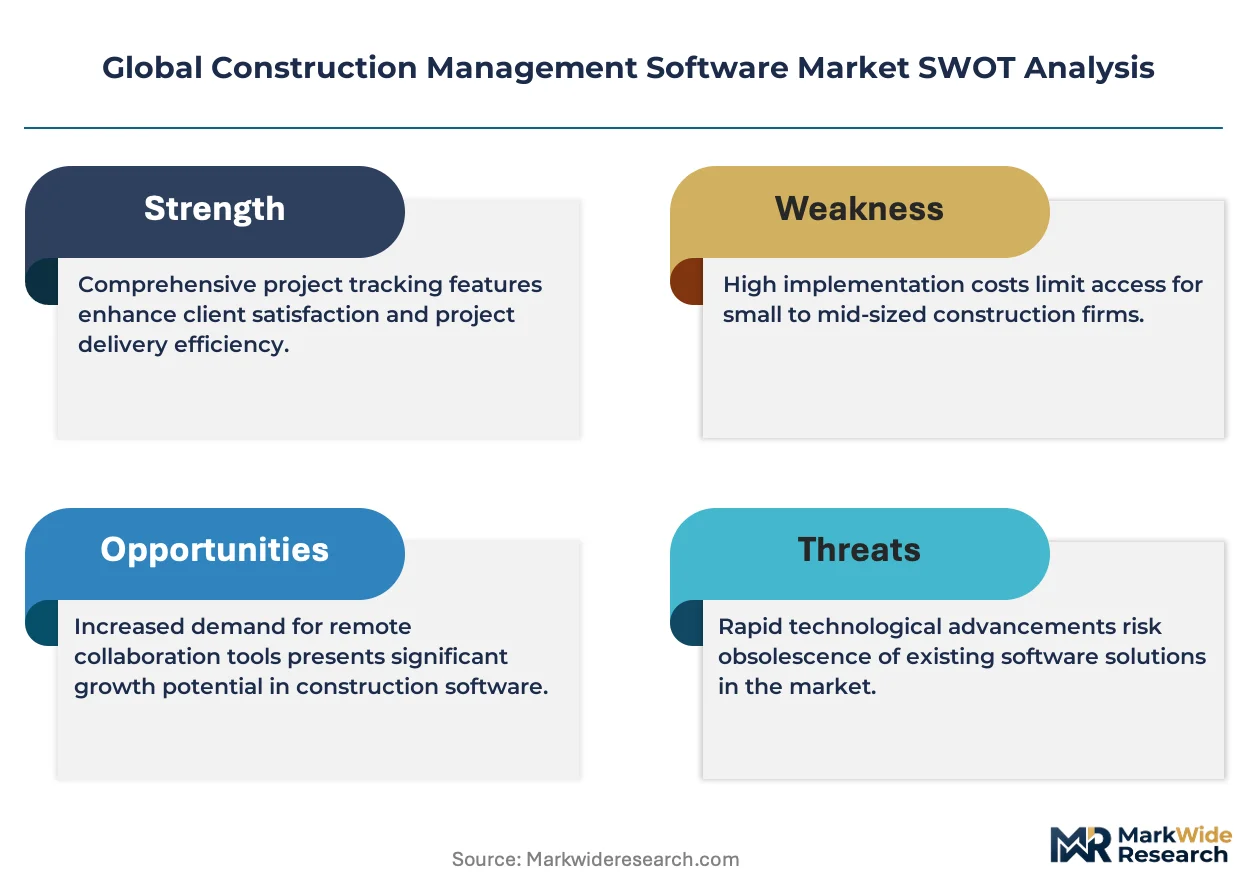
ISO 19650 BIM standards, the EU AI Act, and OSHA digital recordkeeping requirements collectively shape product roadmaps by mandating interoperable data exchange and automated safety documentation. The EU Green Deal's embodied carbon tracking rules are pushing developers toward software with integrated environmental reporting. Buyers should monitor how regulatory divergence between European sustainability mandates and North American safety protocols influences vendor certification investments.
Market Dynamics
Cloud migration mandates and ISO 19650 BIM interoperability standards are forcing replacement cycles across contractor portfolios, decoupling monolithic suites into modular procurement patterns that favor API-native architectures over legacy on-premise installations.
Growth Catalysts
- EU AI Act compliance:Automated safety documentation requirements in European infrastructure projects are accelerating demand for integrated field-to-office platforms that embed machine learning into daily workflows.
- Embodied carbon tracking:The EU Green Deal's environmental reporting rules are pushing developers toward software with built-in lifecycle assessment tools for concrete and steel procurement decisions.
- Australia infrastructure modernization:Federal digitization programs for transportation and utilities are standardizing cloud-based project controls across state-level procurement frameworks.
Market Restraints
- Data sovereignty fragmentation:Divergent national cloud storage requirements between Germany's BSI IT-Grundschutz standards and Australia's data localization laws are complicating multi-country deployments for international contractors.
- Legacy system entrenchment:Decades-old ERP investments in family-owned mid-market construction firms create switching costs that delay SaaS adoption despite superior functionality.
- Skilled implementer scarcity:Shortages of BIM-certified project managers capable of configuring advanced scheduling modules are extending implementation timelines beyond contracted periods.
Strategic Opportunities
- India smart cities initiative:Urban infrastructure digitization programs in Mumbai, Delhi, and Bangalore are creating first-mover advantages for vendors establishing localized cloud partnerships.
- Digital twin convergence:Integration of IoT sensor networks with construction management platforms enables real-time structural health monitoring during and post-construction.
- Subscription unbundling:Modular pricing for standalone cost estimation or safety compliance modules is opening mid-market segments previously priced out of comprehensive suites.
Industry Challenges
- Interoperability certification delays:ISO 19650-2 compliance testing for proprietary file formats is creating bottlenecks as vendors race to validate exchange protocols with competing BIM authoring tools.
- Field connectivity gaps:Remote construction sites in rural Australia and mountainous German regions lack reliable bandwidth for real-time cloud synchronization, forcing hybrid architecture investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Construction Management Software Market |
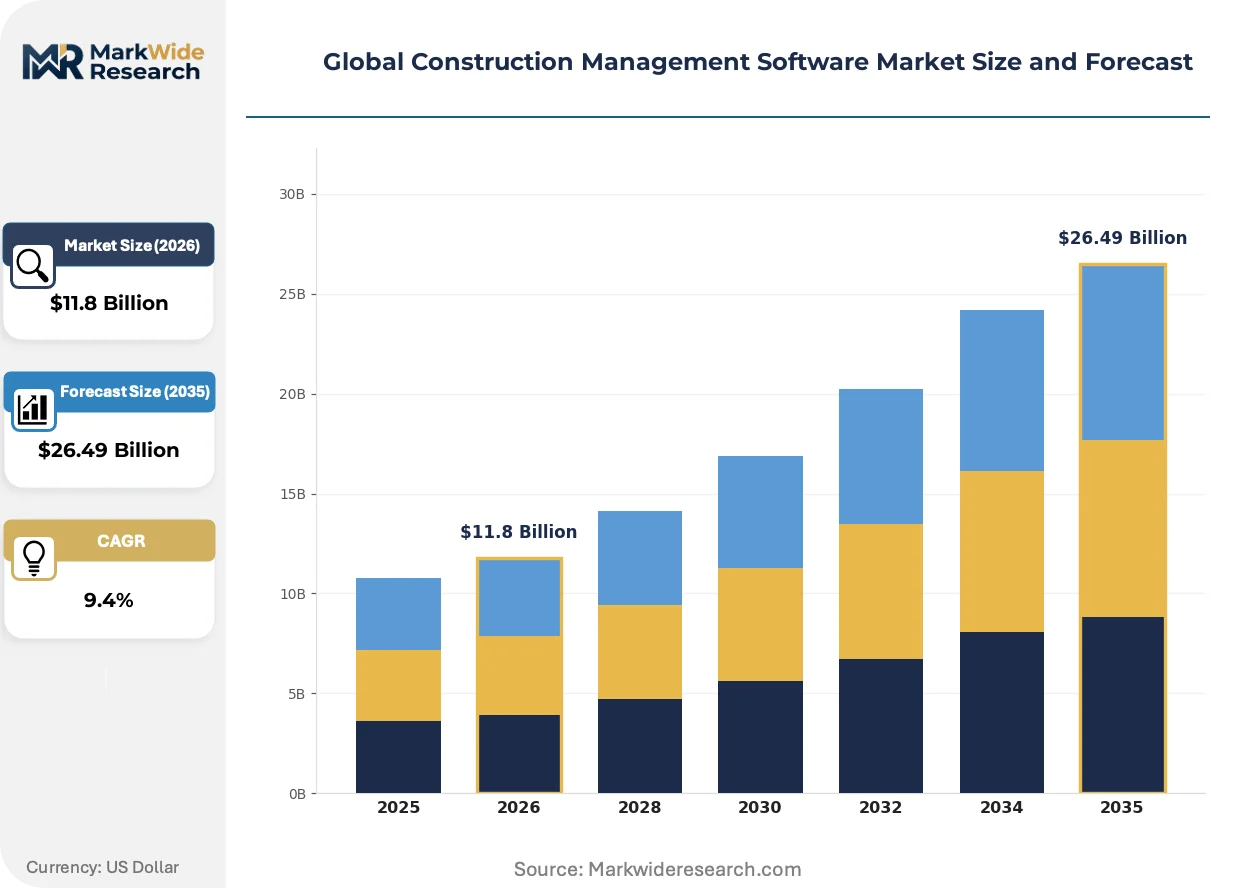
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $26.49 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Contractors, Architects, Engineers, Developers Solution: Project Management, Cost Estimation, Scheduling, Reporting Customer Type: Small Enterprises, Medium Enterprises, Large Enterprises, Others |
| Companies Covered | Buildertrend, Bentley Systems, Procore, PlanGrid, CoConstruct, Autodesk Construction Cloud, Trimble, CMiC, Aconex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Construction Management Software Market Emerging Trajectories
Generative design algorithms and edge computing architectures are compressing the gap between field data capture and executive decision-making, collapsing traditional information hierarchies that separated project managers from real-time site conditions.
Artificial intelligence is rewriting how contractors forecast cost overruns and schedule slippage. Machine learning models trained on historical project data now predict budget deviations six to eight weeks before human analysts detect patterns. Tier-one infrastructure developers in Germany and Australia are deploying these tools across portfolios exceeding fifty concurrent projects. The technology is rewriting competitive differentiation by compressing the advantage window between early adopters and fast followers from years to months.
REACH chemical disclosure requirements and the EU Green Deal's embodied carbon thresholds are mandating material traceability from quarry to installation. Construction software vendors must now integrate supply chain sustainability data directly into procurement modules. German federal transport projects and Dutch commercial developments face the strictest compliance timelines, driving preferential vendor selection toward platforms with pre-certified environmental reporting engines.
Buyer concentration among mega-project developers is consolidating vendor relationships around outcome-guarantee contracts rather than seat-based subscriptions. Saudi Arabia's NEOM and Australia's inland rail program are negotiating performance-linked pricing where software fees scale with measured productivity gains against baseline projections. This restructuring is most visible in Middle Eastern and Asia-Pacific infrastructure markets where sovereign wealth funds directly procure technology stacks for multi-decade developments.
Global Construction Management Software Market Segmentation
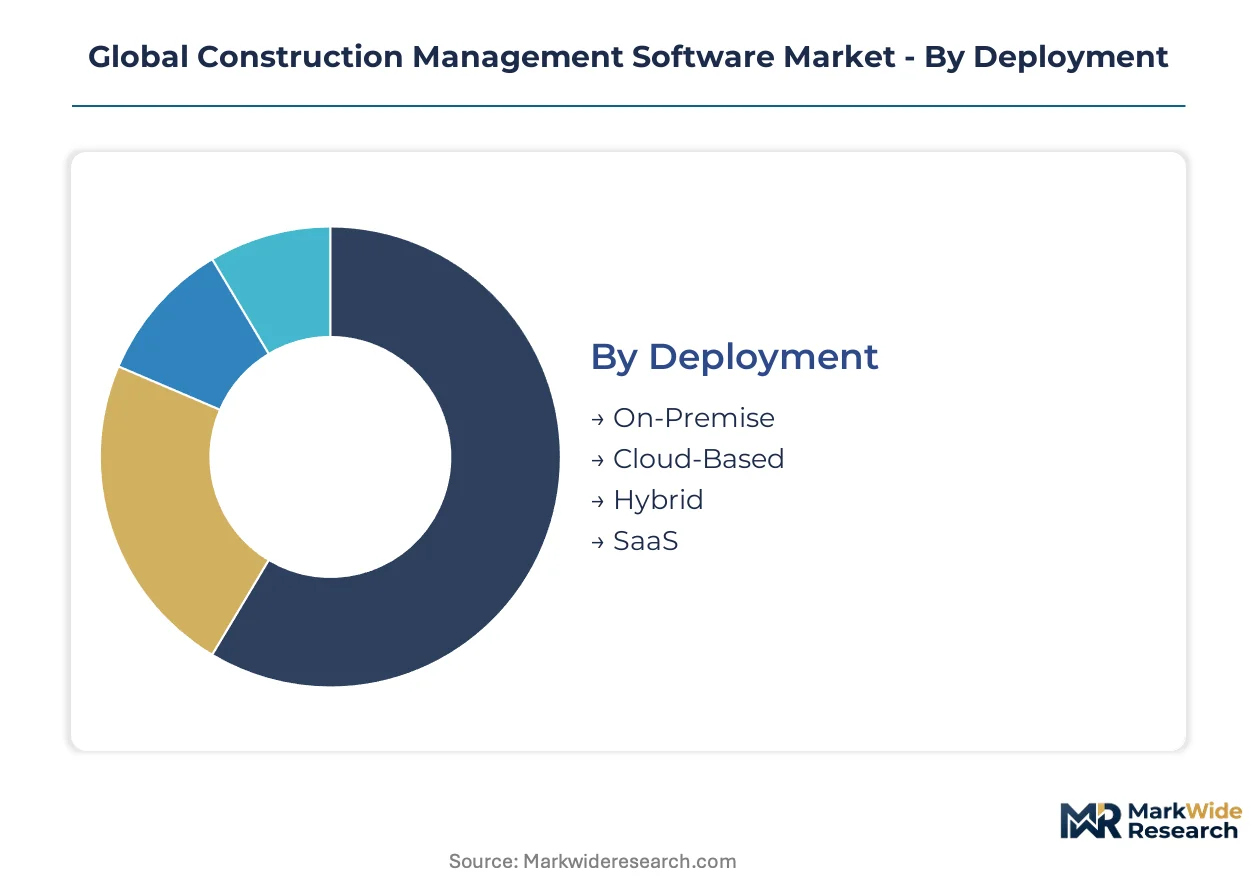
Construction management software procurement decisions hinge on organizational scale, project complexity, and regulatory exposure. Buyers evaluate deployment architectures against data sovereignty requirements, while solution modularity determines how deeply platforms penetrate specific workflows.
Deployment:
IT infrastructure maturity and capital allocation discipline drive deployment selection across contractor portfolios.
- Cloud-Based:Multi-tenant architectures with automatic updates eliminate server maintenance overhead. Demand concentrates among mid-market contractors in Germany and Australia seeking rapid scaling without hardware procurement delays.
- SaaS:Subscription pricing with per-seat or per-project metering lowers entry barriers for specialized trades. US commercial builders favor this model for its alignment with project-based cash flows and minimal upfront commitment.
- On-Premise:Licensed software running on client-owned servers persists in defense and critical infrastructure sectors with strict air-gap requirements.
- Hybrid:Split architectures synchronize sensitive financial data locally while pushing field collaboration tools to cloud nodes, addressing bandwidth constraints in remote Australian and German construction zones.
Volume sits with Cloud-Based deployments; growth tilts toward SaaS as margin pressure intensifies across contractor segments.
End User:
Professional liability exposure and project phase involvement shape feature requirements across stakeholder groups.
- Contractors:Field operations platforms with daily reporting, safety compliance, and subcontractor coordination dominate procurement. German federal transport projects and Australian state infrastructure programs mandate these tools for bid eligibility.
- Engineers:Technical specification management and design change tracking anchor demand. ISO 19650 compliance requirements in EU public works drive specification-heavy purchasing criteria.
- Architects:BIM authoring integration and visualization tools predominate, with EU Green Deal carbon reporting adding environmental performance layers to selection decisions.
- Developers:Portfolio-level dashboards aggregating multiple project financials attract institutional real estate investors in US urban infill and Middle Eastern mega-developments.
Contractors generate the deepest installed base; engineers are expanding most quickly as infrastructure digitization mandates proliferate.
Solution:
Functional specialization determines pricing architecture and implementation complexity for platform vendors.
- Project Management:Centralized document control, RFQ processing, and field-to-office communication hubs form the core of most deployments. Widest penetration across all customer tiers but lowest differentiation among competing vendors.
- Cost Estimation:Material quantity takeoff, labor productivity databases, and bid assembly automation command premium pricing. Australian quantity surveyors and US commercial estimators drive adoption as competitive bidding compresses margins.
- Scheduling:Critical path method engines with resource leveling and delay impact analysis serve complex multi-prime projects. German infrastructure consortiums require these modules for compliance with federal construction timeline regulations.
- Reporting:Executive dashboards and regulatory submission generators consolidate data from operational modules. EU CSRD sustainability disclosure requirements are accelerating demand for automated environmental reporting outputs.
Project Management commands current volume leadership; Cost Estimation exhibits the steepest expansion trajectory as preconstruction workflows digitize.
Customer Type:
Organizational scale dictates implementation approach and support intensity for vendor success teams.
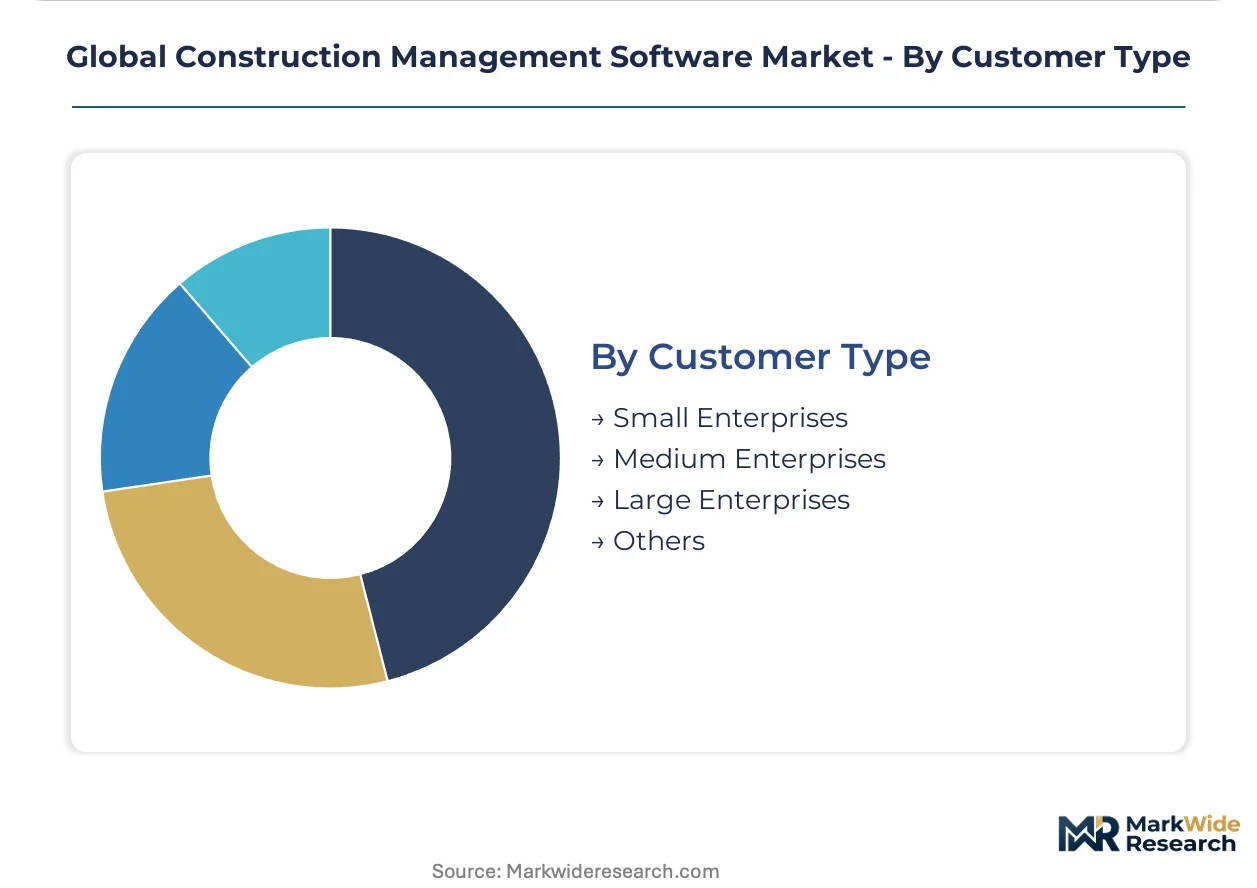
- Large Enterprises:Tier-one contractors and developers operating across multiple geographies require multi-entity consolidation, advanced permissions architecture, and dedicated customer success management. Complex procurement cycles extend sales timelines but generate substantial lifetime value.
- Medium Enterprises:Regional contractors with project portfolios spanning commercial, industrial, and select infrastructure verticals seek configurable platforms without enterprise overhead. Fastest sales cycles and highest expansion revenue potential for vendors with modular pricing.
- Small Enterprises:Specialty trade contractors and single-family residential builders prioritize mobile-first interfaces and simplified onboarding. Price sensitivity limits addressable market for premium solutions without freemium entry points.
- Others:Government agencies, educational institutions, and nonprofit owners with unique procurement and audit requirements represent bespoke implementation challenges.
Large Enterprises anchor current revenue concentration; Medium Enterprises are gaining share fastest as cloud-native platforms democratize access to previously enterprise-grade functionality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in Dubai's DIFC and Saudi Arabia's NEOM special economic zones are concentrating construction software procurement for mega-project digitization mandates.
United States
Federal infrastructure spending and commercial real estate recovery are accelerating cloud platform adoption. OSHA digital recordkeeping requirements now mandate automated safety documentation for federal contractors. Dallas-Fort Worth and Atlanta metropolitan clusters are deploying integrated project controls across multi-billion dollar mixed-use developments.
Germany
Transport infrastructure modernization and industrial facility upgrades are driving BIM-integrated procurement. ISO 19650-2 compliance deadlines for federal construction contracts are forcing legacy system replacements. The Rhine-Ruhr corridor and Bavarian manufacturing zones are standardizing digital twin implementations for factory construction projects.
Australia
Inland rail and renewable energy transmission projects are standardizing cloud-based project controls. Federal digitization mandates for state-level infrastructure procurement require field-to-office platform certification. Sydney and Melbourne construction clusters are embedding machine learning modules into quantity surveying workflows for competitive bidding.
India
Smart cities initiatives in Mumbai, Delhi, and Bangalore are creating localized cloud partnership opportunities. The country's national urban development authority is mandating digital project monitoring for municipal infrastructure tenders. Hyderabad and Pune technology corridors are attracting construction SaaS vendors establishing regional data centers.
Saudi Arabia
NEOM and Red Sea Project developments are negotiating outcome-linked software contracts with productivity guarantees. The kingdom's sovereign wealth fund is directly procuring technology stacks for multi-decade developments. Riyadh and the Eastern Province industrial cities are deploying integrated platforms for gigaproject portfolio management.
Global Construction Management Software Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment architectures and vertical integration strategies. The market structure exhibits tiered concentration with cloud-native platforms gaining share from legacy on-premise installations. Three archetypes dominate: engineering-grade BIM integrators, mid-market SaaS generalists, and construction-specific workflow optimizers. Competitive dynamics center on API ecosystem expansion and modular pricing unbundling rather than pure feature proliferation.
Among North American cloud-native platforms, Procore and Autodesk Construction Cloud occupy positions as archetype anchors for subscription-based field collaboration. Bentley Systems exemplifies the engineering-grade specialist tier with deep infrastructure design integration. Trimble represents the hardware-software convergence archetype, bridging field measurement devices with project management workflows.
| Leading Market Players |
|---|
| Buildertrend |
| Bentley Systems |
| Procore |
| PlanGrid |
| CoConstruct |
| Autodesk Construction Cloud |
| Trimble |
| CMiC |
| Aconex |
| Others |
Supply Flow & Price Mechanics
Captive cloud infrastructure investments by Procore and Autodesk anchor supply positions while enabling subscription pricing power across mid-market contractor segments. This vertical integration into data center operations insulates margin structures from third-party hosting volatility and supports tiered SaaS differentiation.
Pricing Analysis
Short lead-time premiums for rapid implementation contracts command pricing advantages over standard deployment schedules in competitive bid situations. Pricing stratifies across premium, standard, and economy tiers based on module bundling depth and ISO 19650 certification status. Cost compression in the small enterprise tier intensifies as freemium entrants erode entry-level subscription floors. Government contractors exhibit lowest price sensitivity due to outcome-guarantee procurement frameworks, while specialty trade contractors face acute margin pressure.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Australia anchor hub-and-spoke delivery patterns for localized customer success and implementation support. Cloud infrastructure draws from hyperscaler partnerships with AWS, Azure, and Google Cloud Platform, while API integration modules rest on third-party developer ecosystems. Single-source vulnerability concentrates in BIM engine licensing from Autodesk and Bentley Systems. Distribution runs through direct enterprise sales teams supplemented by channel partners serving mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Implementation capacity constraints for BIM-certified project managers prop pricing power across enterprise tiers. Supply scarcity in qualified deployment specialists limits vendor scaling velocity.
For Market Incumbents: Deepen API ecosystem investments to lock in platform stickiness against modular unbundling threats from specialized cost estimation vendors. Pursue backward integration into BIM certification training programs to alleviate implementer scarcity bottlenecks. Prioritize ISO 19650-2 compliance acceleration to capture German federal transport contract mandates ahead of validation backlogs. For New Entrants and Emerging Players: Regional system integrators in India and Saudi Arabia represent the most penetrable channel archetype for cloud-native platforms lacking local presence. Target medium enterprise contractors in Australian state infrastructure programs where digitization mandates create procurement urgency without entrenched incumbent relationships. Lead with standalone safety compliance modules priced below comprehensive suite floors. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified engineering software conglomerates seeking construction vertical penetration. Five-to-ten year viability hinges on API ecosystem density and regulatory certification breadth. Monitor ISO 19650 validation queue lengths as inflection indicators for vendor competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-native architectures capture modular procurement shifts across German and Australian infrastructure mandates. |
| Acquisition of Specialist Firm | Cost estimation pure-plays fill capability gaps in preconstruction workflow coverage. |
| Geographic Expansion | Localized cloud partnerships in India smart cities programs establish first-mover data residency compliance. |
| Strategic Partnership | Hyperscaler alliances secure scalable infrastructure for NEOM-scale mega-project deployments. |
| Product Launch | Embodied carbon tracking modules address EU Green Deal procurement requirements in Dutch and German federal tenders. |
Methodological Framework
Multi-period observation of cloud deployment rates, BIM certification timelines, and modular procurement patterns anchored the trend analysis, supplemented by interviews with construction technology officers, project controls directors, quantity surveyors, and federal procurement officers. Secondary validation drew from SEC software company filings, ISO standards documentation, EU regulatory registers, and Australian infrastructure agency tender databases. Bottom-up project pipeline enumeration triangulated against top-down contractor IT spending surveys.
Segment-weighting approaches modeled deployment architecture, organization scale, solution functional area, and end-user professional role throughout the forecast period. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory mandate acceleration. Forecast inputs incorporated cloud migration mandate compliance deadlines and embodied carbon tracking rule implementation schedules.
Caveats apply where ISO 19650 certification delays, data sovereignty rule changes, or hyperscaler pricing volatility could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Bug Tracking Software Market
Software & Services
Global Accreditation Management Software Market
Software & Services
Cloud Enterprise Application Software Market
Software & Services
Generative Design Software Market
Software & Services
Computer Software Market
Software & Services
Global Inspection Management Software Market
Software & Services
Pure Play Software Testing Market
Software & Services
Software Containers Market
Software & Services
Global Journal App Market
Software & Services
Global Food Traceability Software Market
Software & Services
North America Saas-Based Expense Management Market
Software & Services
Load Balancing Software Market
Software & Services
Media Editing App Market
Software & Services
Automation Test Software Market
Software & Services
Sports Production Software Market
Software & Services
United Kingdom IT Services Market