
 Consumer Facing AI Products Market | 2026-2036
Consumer Facing AI Products Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Facing AI Products Market Insights
Modular subscription bundling is rebalancing how consumers access AI capabilities across virtual assistants, image tools, and recommendation engines. OpenAI leverages tiered API access and ChatGPT Plus packaging to anchor recurring revenue from individual consumers. Google sustains competitive pressure through deep integration of Gemini across Android, Search, and Workspace interfaces. Microsoft dominates enterprise-adjacent consumer segments by embedding Copilot into personal productivity workflows.
Consumer facing AI products encompass software and hardware systems that apply machine learning, natural language processing, and computer vision to deliver personalized, interactive experiences directly to non-enterprise users, typically requiring cloud connectivity, local inference chips, or hybrid architectures with sub-100-millisecond response thresholds. Their primary commercial purpose centers on automating cognitive tasks, reducing decision friction, and generating predictive outputs from behavioral data streams. Virtual assistants and chatbots capture the largest installed base, while edge computing deployments represent the fastest-growing configuration as latency-sensitive applications expand beyond smartphone boundaries. Personalized recommendation engines concentrate margin pools through advertising and commerce commission structures that scale with user engagement depth.
FDA Software as a Medical Device frameworks and EU AI Act risk-classification tiers are tightening validation requirements for health-tracking and diagnostic applications, forcing developers to document algorithmic transparency and clinical efficacy before market entry. The Federal Trade Commission monitors deceptive claims around AI capability, shaping how vendors advertise generative features to consumers. Stakeholders must track evolving conformity assessment pathways across jurisdictions to avoid product delisting and to secure preferred placement on regulated app distribution channels.
Market Dynamics
Generative pretrained transformer architectures are compressing development cycles and collapsing the cost structure of personalized AI delivery, forcing incumbents to reprice subscription tiers and absorb inference cost spikes.
Growth Catalysts
- Edge computing hardware maturation:Dedicated neural processing units in consumer devices enable sub-100-millisecond response thresholds without cloud round-trips, unlocking latency-sensitive applications in automotive and wearable segments.
- FDA Software as a Medical Device guidance:Clarified validation pathways for diagnostic chatbots accelerate clinical deployment timelines for symptom-checking virtual assistants in US healthcare systems.
- Cloud infrastructure density concentration:Hyperscaler datacenter expansion in the United States sustains premium subscription uptake through reduced latency and improved model serving reliability.
Market Restraints
- GPU supply concentration:Foundry capacity for advanced AI accelerators clusters in Taiwan, creating single-point-of-failure exposure for model training and fine-tuning operations.
- EU AI Act risk-classification compliance:Mandatory conformity assessment for emotion recognition and biometric categorization systems extends time-to-market by 12-18 months for affected product categories.
- Energy cost volatility:Datacenter power consumption for large language model inference scales nonlinearly with user query volume, compressing gross margins during electricity price spikes.
Strategic Opportunities
- India consumer digital literacy tailwinds:PLI scheme incentives for electronics manufacturing and expanding 5G penetration create addressable market expansion for vernacular-language virtual assistants.
- Automotive cabin intelligence convergence:Integration of computer vision and natural language processing into in-vehicle infotainment systems opens subscription revenue streams for driver monitoring and predictive maintenance.
- FTC deceptive claims enforcement:Heightened scrutiny of AI capability marketing creates competitive differentiation for vendors with documented algorithmic transparency and validated performance benchmarks.
Industry Challenges
- Multimodal model training expertise scarcity:Synchronous optimization across text, image, and audio modalities requires specialized talent pools concentrated at frontier research labs, constraining product roadmap velocity for mid-tier developers.
- Cross-jurisdiction conformity assessment fragmentation:Divergent documentation requirements between FDA Software as a Medical Device frameworks and EU AI Act technical standards force parallel compliance investments for health-tracking applications.
- On-device inference optimization complexity:Quantization and pruning techniques for transformer compression demand hardware-software co-design capabilities that strain legacy mobile application development teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Facing AI Products Market |
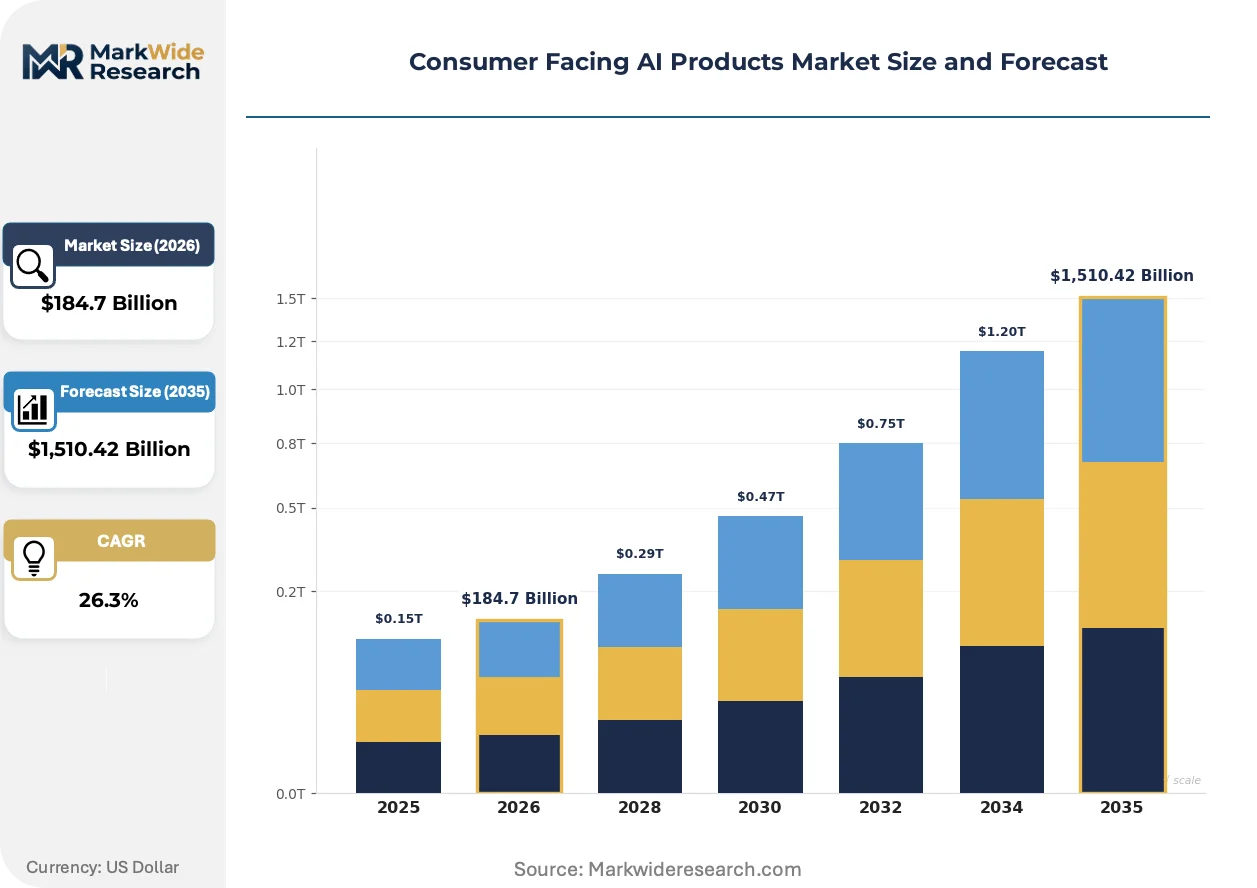
| Market Size in 2026 | $184.7 Billion |
| Market Size in 2035 | $1,510.42 Billion |
| CAGR (2026 – 2036) | 26.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Assistants, Smart Speakers, Chatbots, Image Recognition Tools, Personalized Recommendation Engines Deployment: Cloud-Based, On-Premises, Edge Computing, Hybrid Models Application: Home Automation, Personal Finance Management, Customer Support, E-Learning Platforms, Digital Health Tracking End User: Individual Consumers, Small Business Owners, Students, Senior Citizens, Freelancers |
| Companies Covered | OpenAI, Google, Microsoft, Anthropic, Amazon, Meta, xAI, Perplexity AI, Hugging Face, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Facing AI Products Market Trends and Innovations
Transformer-based architectures are redefining consumer expectations for conversational fluency, compressing the acceptable latency window and collapsing the distinction between cloud and edge intelligence deployment.
Small language model distillation is consolidating the competitive landscape around inference efficiency rather than raw parameter scale. Consumer electronics OEMs are adopting sub-7-billion-parameter variants for smartphone-native assistants, reducing dependency on continuous connectivity. This compression is consolidating margin structures toward hardware-integrated licensing and away from pure software subscriptions.
The EU AI Act's tiered risk classification is reshaping product development roadmaps for biometric and emotion-recognition features. High-risk system designations trigger mandatory third-party auditing and human oversight requirements, diverting engineering resources from capability expansion to compliance documentation. Health and wellness applications face the steepest compliance burden, with several vendors withdrawing planned features from European release schedules.
Subscription fatigue among digital-native consumers is fragmenting payment willingness across micro-transaction and freemium models. Virtual assistant providers are unbundling premium tiers into capability-specific modules—image generation, extended context windows, voice cloning—rather than all-inclusive pricing. This unbundling is most pronounced in the United States, where credit-card-linked recurring payment infrastructure supports granular subscription management.
Consumer Facing AI Products Market Segmentation
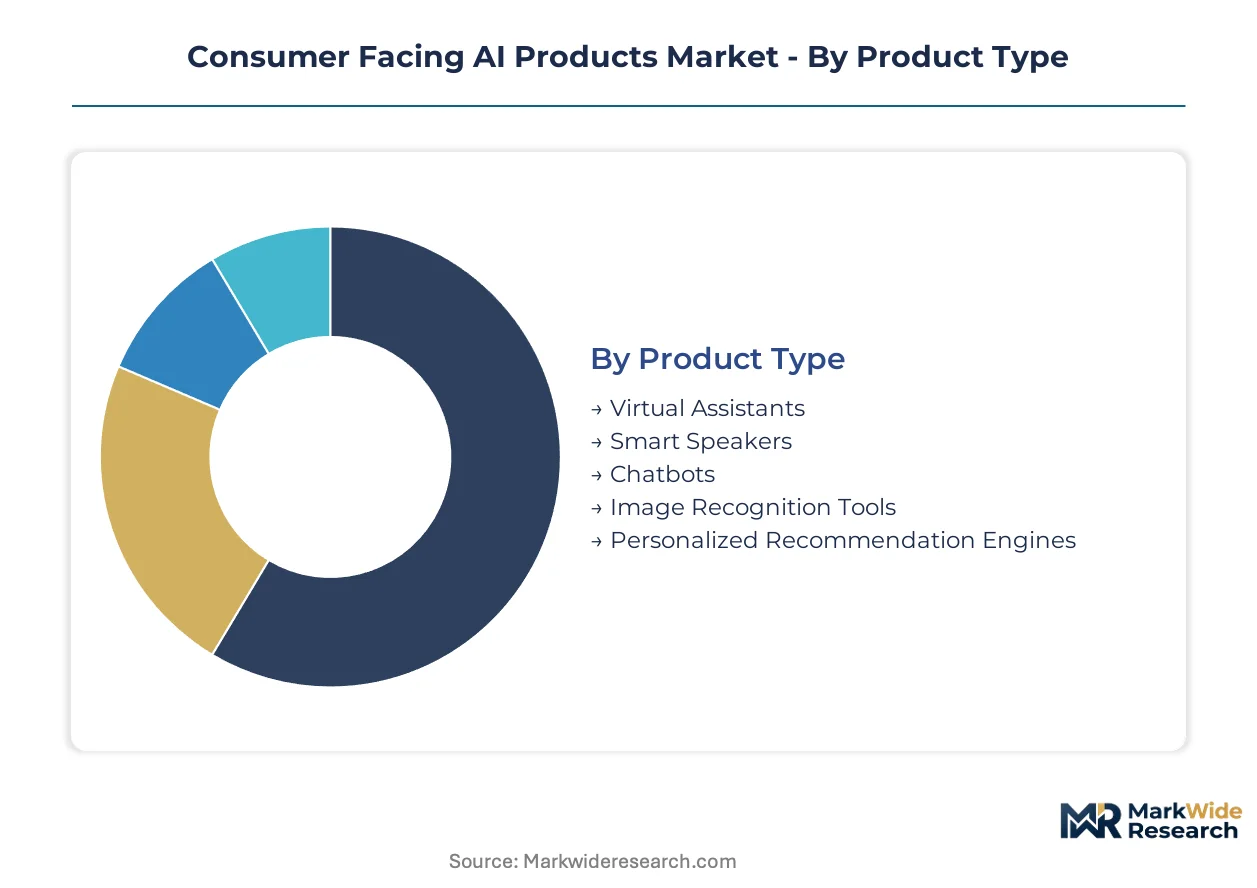
Segmentation reveals how upgrade cycles and replacement dynamics concentrate margin capture across distinct product configurations. Deployment architectures and user maturity levels determine pricing elasticity and retention trajectories for vendors competing in this space.
Product Type:
Replacement cycles vary dramatically across form factors, with hardware-integrated products demanding 2-3 year refresh schedules while software-only offerings iterate continuously without consumer friction.
- Virtual Assistants:Conversational AI systems processing natural language queries through cloud-connected or on-device inference. Demand concentrates in smartphone ecosystems where Apple Siri and Google Assistant ship pre-installed, with subscription conversion highest among United States users seeking productivity automation.
- Smart Speakers:Far-field microphone arrays with embedded wake-word detection and speaker drivers. Replacement cycles extend 4-5 years as hardware durability outpaces capability gains, compressing upgrade revenue for Amazon Echo and Google Nest product lines.
- Chatbots:Text-based conversational interfaces deployed through messaging platforms and standalone applications.
- Image Recognition Tools:Computer vision systems enabling facial authentication, object detection, and visual search functionality.
- Personalized Recommendation Engines:Algorithmic content curation systems predicting user preferences from behavioral signals.
Virtual Assistants sits at the top of the volume ranking, with Chatbots climbing the fastest.
Deployment:
Cost tiering separates premium subscription offerings from ad-supported alternatives, with latency requirements dictating infrastructure investment intensity.
- Cloud-Based:Model inference executed on hyperscaler datacenter infrastructure with continuous connectivity requirements. United States demand concentrates here due to fiber penetration and 5G coverage density sustaining sub-200-millisecond response reliability.
- Edge Computing:Local neural processing unit execution eliminating network round-trips. Automotive cabin intelligence and wearable health monitors drive fastest expansion as FDA Software as a Medical Device guidance clarifies validation pathways for diagnostic applications.
- On-Premises:Dedicated hardware installations within consumer-controlled environments.
- Hybrid Models:Adaptive routing between local and cloud inference based on query complexity and connectivity status.
Cloud-Based dominates current installed base, with Edge Computing gaining share fastest through automotive and health vertical penetration.
Application:
Application maturity correlates directly with consumer payment willingness, with established categories commanding premium pricing while emerging use cases rely on freemium conversion.
- Home Automation:Voice-controlled lighting, climate, and security system orchestration. United States households with existing IoT device investments show highest subscription attachment rates for advanced scene programming and predictive energy optimization.
- Digital Health Tracking:Symptom monitoring, medication adherence, and biometric trend analysis. FDA Software as a Medical Device frameworks accelerate clinical deployment timelines for diagnostic chatbots in US healthcare systems, creating regulated revenue pools unavailable to unvalidated competitors.
- Personal Finance Management:Automated budgeting, expense categorization, and investment recommendation systems.
- Customer Support:Automated resolution of product and service inquiries through conversational interfaces.
- E-Learning Platforms:Adaptive tutoring systems personalizing curriculum pacing and content difficulty.
Home Automation leads volume rankings, with Digital Health Tracking climbing fastest as regulatory clarity unlocks clinical reimbursement pathways.
End User:
Customer type determines feature complexity tolerance and price sensitivity, with professional use cases justifying premium tiers unavailable to casual consumers.
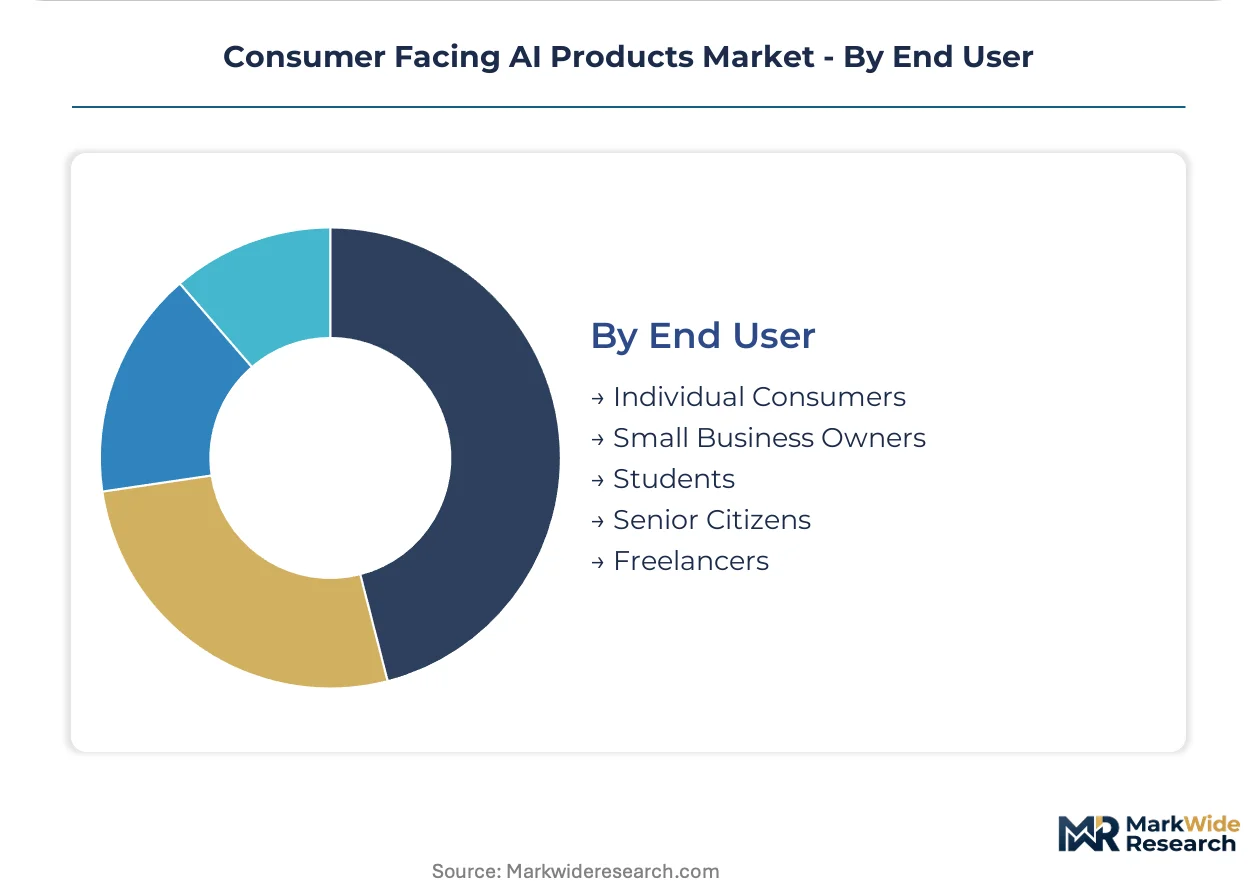
- Individual Consumers:General-purpose users deploying AI products for personal productivity and entertainment. Mass-market pricing prevails here, with subscription fatigue driving unbundling into capability-specific modules across United States credit-card-linked payment infrastructure.
- Small Business Owners:Entrepreneurs leveraging AI for customer communication, content generation, and operational automation. This segment commands 3-4x average revenue per user through business-deductible expense treatment and time-value-of-money justification.
- Students:Learners utilizing AI for research assistance, writing support, and language translation.
- Senior Citizens:Older adults adopting voice-first interfaces for medication reminders, emergency response, and social connection.
- Freelancers:Independent contractors deploying AI for client acquisition, project management, and deliverable production.
Individual Consumers sit at the top of the volume ranking, with Small Business Owners climbing the fastest as operational automation justifies premium subscription attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumer facing AI products industry traces its commercial origins to Silicon Valley's voice assistant deployments in the early 2010s, with hyperscaler infrastructure investments subsequently diffusing development capacity across multiple national technology corridors.
United States
FDA Software as a Medical Device guidance accelerates clinical deployment of diagnostic chatbots across integrated health systems. FTC enforcement actions against deceptive AI capability claims reshape vendor marketing practices nationwide. Seattle and San Francisco Bay Area clusters concentrate engineering talent for transformer architecture optimization and edge inference chip design.
China
MIIT standards for intelligent voice interaction systems mandate interoperability testing for domestic smart speaker deployments. NMPA regulatory pathways for AI-enabled health monitoring create compliance thresholds for wearable diagnostic applications. Shenzhen and Hangzhou manufacturing ecosystems drive cost compression for neural processing unit integration into consumer electronics.
United Kingdom
Information Commissioner's Office guidance on automated decision-making shapes transparency requirements for recommendation engine deployments. MHRA consultation on AI as a Medical Device influences validation protocols for symptom-checking applications. London's King's Cross and Old Street technology corridors host frontier research labs specializing in multimodal model distillation.
Germany
BSI technical guidelines for trustworthy AI establish baseline security requirements for voice-controlled home automation systems. KBA regulatory frameworks for driver monitoring systems accelerate automotive cabin intelligence integration. Munich and Stuttgart automotive engineering clusters drive edge computing specifications for in-vehicle natural language processing.
India
PLI scheme incentives for electronics manufacturing expand domestic assembly capacity for AI-enabled consumer devices. TRAI directives on data localization influence cloud infrastructure investment patterns for virtual assistant services. Bengaluru and Hyderabad technology corridors concentrate engineering talent for vernacular-language model training and optimization.
Consumer Facing AI Products Market Competitive Landscape
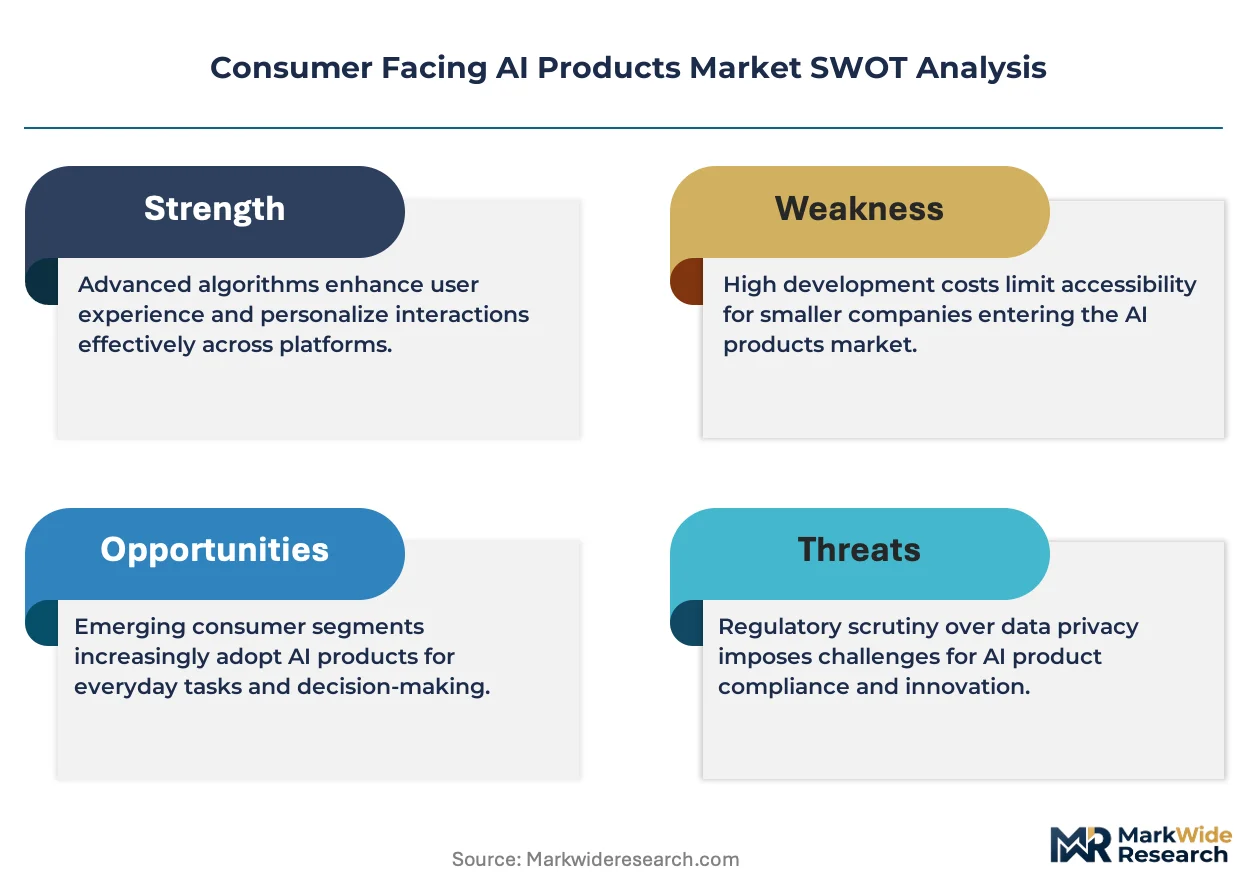
The competitive structure tilts toward hyperscaler-dominated platform consolidation with specialized challengers occupying vertical niches. Three strategic archetypes dominate: full-stack infrastructure operators controlling cloud-edge inference pipelines, application-layer specialists monetizing through subscription unbundling, and open-source ecosystem orchestrators capturing developer mindshare. Dominant competitive moves include strategic partnerships anchoring distribution through pre-installed device integration and technology licensing agreements securing training data access.
Among United States-based platform operators, OpenAI and Google exemplify the full-stack archetype through tiered API access and deep mobile ecosystem integration respectively. Microsoft occupies a hybrid position spanning enterprise-adjacent consumer productivity workflows. Anthropic represents the safety-focused challenger model emphasizing constitutional AI alignment. Amazon leverages smart speaker installed base density for voice commerce conversion. Meta and xAI pursue scale-driven positioning through social graph integration and compute-intensive training clusters. Perplexity AI and Hugging Face anchor the open-source and developer-tooling tier respectively.
| Leading Market Players |
|---|
| OpenAI |
| Microsoft |
| Anthropic |
| Amazon |
| Meta |
| xAI |
| Perplexity AI |
| Hugging Face |
| Others |
Pricing and Supply Chain Analysis
Subscription fatigue among United States digital-native consumers is fragmenting payment willingness and forcing vendors toward capability-specific module unbundling, which compresses average revenue per user while demanding supply chain flexibility for tiered feature delivery.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates consumer-facing AI products, with differentiation driven by FDA Software as a Medical Device certification tier and cloud inference latency guarantees. Price differentiation separates validated diagnostic chatbots from unregulated wellness applications, with the latter facing intensifying cost compression from open-source model competition. Individual consumers exhibit highest price sensitivity, while small business owners absorbing deductible expenses show lowest sensitivity.
Supply Chain Analysis
FDA Software as a Medical Device validation and EU AI Act conformity assessment create dual certification gating that extends supplier qualification timelines. Foundry capacity for advanced AI accelerators concentrates in Taiwan and South Korea, with packaging and testing operations spreading to Malaysia and Vietnam. Raw material dependencies include high-bandwidth memory modules, specialized silicon substrates, and rare earth elements for magnetics. Single-source vulnerability around TSMC's leading-edge node production poses structural risk. Distribution runs through hyperscaler datacenter procurement and OEM pre-installation agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The consumer-facing AI products market has entered late-cycle quality phase as buyers prioritize FDA-validated diagnostic capabilities and sub-100-millisecond edge inference over undifferentiated cloud chatbot subscriptions.
For Market Incumbents: Lock in distribution through Android and iOS pre-installation agreements before open-source alternatives erode channel control. Secure exclusive training data partnerships with United States health systems to defend FDA Software as a Medical Device certification moats. Absorb GPU cost spikes through backward integration into custom silicon design rather than pure foundry dependency. For New Entrants and Emerging Players: Sub-7-billion-parameter small language model distillation offers a technology-first wedge against hyperscaler inference economics. Target automotive cabin intelligence and wearable health monitors in India, where PLI scheme incentives and 5G penetration create white-space expansion for vernacular-language assistants. Pursue hospital system pilot programs as the most penetrable entry path for regulated diagnostic applications. For Investors and Strategic Acquirers: Asymmetric upside sits with edge computing hardware-software co-design specialists possessing FDA validation documentation and automotive Tier 1 supplier relationships. Long-term viability favors acquisition targets with demonstrated on-device inference optimization and multi-jurisdiction compliance portfolios. Watch for inflection in United States healthcare reimbursement codes covering AI-enabled diagnostic chatbots.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Gemini embedding across Android, Search, and Workspace interfaces sustains competitive pressure through ecosystem lock-in. |
| Regulatory Certification | FDA Software as a Medical Device validation unlocks clinical reimbursement pathways unavailable to unvalidated wellness competitors. |
| Edge Hardware Partnership | Neural processing unit co-design with automotive OEMs secures subscription revenue streams for driver monitoring applications. |
| Strategic Partnership | Hyperscaler distribution agreements anchor consumer reach through pre-installed smartphone assistant defaults. |
| Geographic Expansion | Vernacular-language model training for India leverages PLI scheme electronics manufacturing incentives and TRAI data localization compliance. |
Research Methodology
Coverage spans the United States, China, United Kingdom, Germany, and India, with primary inputs from each market combining structured interviews with AI product executives, regulatory affairs specialists at FDA and EU notified bodies, healthcare system procurement managers, and automotive Tier 1 supplier engineering directors. Secondary validation draws from SEC filings of hyperscaler cloud providers, FDA 510(k) submission databases, EU AI Act implementation guidance, and hyperscaler datacenter capex disclosures. Bottom-up unit economics and top-down spending allocation models undergo triangulation against disclosed subscription metrics and installed base estimates.
Rate-of-change decomposition separates volume expansion from pricing trajectory across the analysis window, with segmentation modeling across deployment architecture, application vertical, and end-user archetype. CAGRs derive from fitted adoption curves incorporating cloud infrastructure density, regulatory pathway clarity, and consumer digital literacy indices. Industry-specific forecast inputs include FDA Software as a Medical Device approval velocity and neural processing unit integration rates in smartphone bill of materials.
The model holds under stable regulatory enforcement and continued hyperscaler infrastructure investment; deviation in EU AI Act risk-classification implementation timelines or Taiwan foundry capacity constraints would shift trajectory. A model refresh is warranted upon material change in United States healthcare reimbursement policy for AI-enabled diagnostics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Conversational Systems Market
Artificial Intelligence (AI)
Global AI in Social Media Market
Artificial Intelligence (AI)
Edge AI Market
Artificial Intelligence (AI)
Artificial Intelligence in Business Market
Artificial Intelligence (AI)
United States Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence Oven Market
Artificial Intelligence (AI)
Chatbot Market
Artificial Intelligence (AI)
Brain Computer Interface Market
Artificial Intelligence (AI)
Brain-Computer Interface System Market
Artificial Intelligence (AI)
AI Data Labeling Market
Artificial Intelligence (AI)
AI Code Assistant Market
Artificial Intelligence (AI)
Conversational AI Market
Artificial Intelligence (AI)
Artificial Intelligence in Robots Market
Artificial Intelligence (AI)
Autonomous AI and Autonomous Agents Market
Artificial Intelligence (AI)
Model Validation and Automation Market
Artificial Intelligence (AI)
Automotive Gesture Recognition Market