
 Computer Engineering Market | 2026-2036
Computer Engineering Market Size, Share, and Industry Trends Forecast 2026-2036
Computer Engineering Market Analysis
Subscription-based software-defined hardware is recalibrating how enterprises procure computing infrastructure, shifting capital expenditure toward recurring operational models. NVIDIA leverages its CUDA ecosystem to dominate AI-accelerated datacenter deployments, while Google anchors cloud-native engineering workflows through custom tensor processing units. Microsoft competes by extending Azure's integrated development environments into edge manufacturing floors, blurring boundaries between cloud and local compute.
Computer engineering encompasses the design, integration, and optimization of digital systems spanning microarchitecture, firmware, and system-level software, with specifications typically benchmarked against instruction-per-watt efficiency and thermal design power constraints. The discipline serves industrial automation, telecommunications infrastructure, and intelligent device manufacturing by ensuring reliable signal processing under real-time constraints. Hardware segments sustain margin pools in custom silicon fabrication, while AI-driven technology layers capture expanding value as enterprises embed inference engines directly into network management equipment. Cloud computing application areas lead volume growth, though edge computing deployments for embedded systems in automotive and healthcare settings represent the fastest-expanding frontier for specialized engineering talent.
FDA's software-as-a-medical-device framework and the EU AI Act's risk classification system are tightening validation requirements for computer engineering outputs deployed in healthcare and safety-critical environments, elevating compliance costs for cross-border suppliers. IEEE standards for floating-point arithmetic and system-on-chip interoperability shape baseline design parameters that determine market access for component vendors. China's MIIT cybersecurity review protocols add a third jurisdictional layer that multinational engineering teams must navigate when sourcing or deploying systems across manufacturing bases. Stakeholders must decide whether to maintain parallel compliance architectures or consolidate around the most restrictive standard, a choice that will reshape supplier relationships and R&D allocation without regard to annual planning cycles.
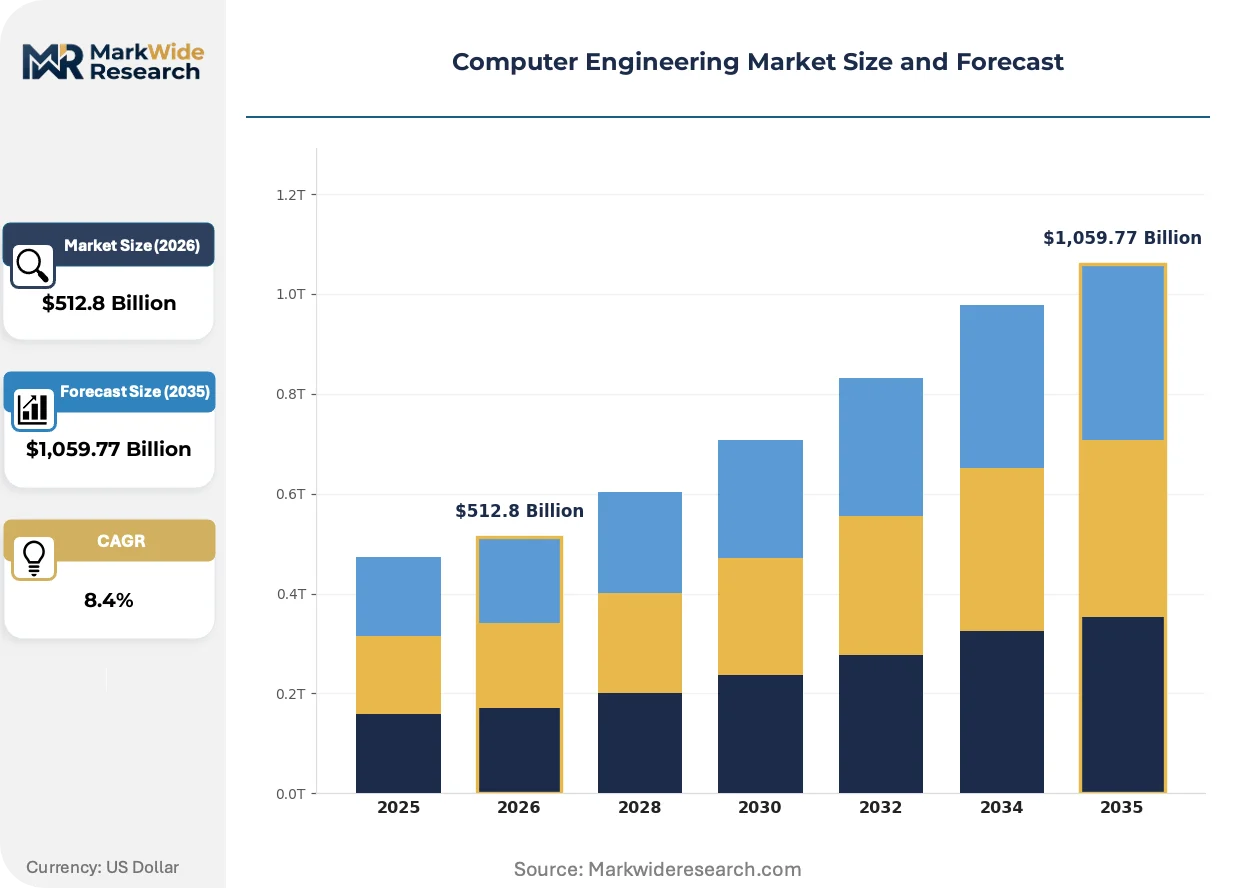
Market Dynamics
Subscription-based software-defined hardware is recalibrating procurement economics across enterprise computing infrastructure, compressing capital expenditure cycles into recurring operational models while forcing established vendors to rearchitect licensing frameworks.
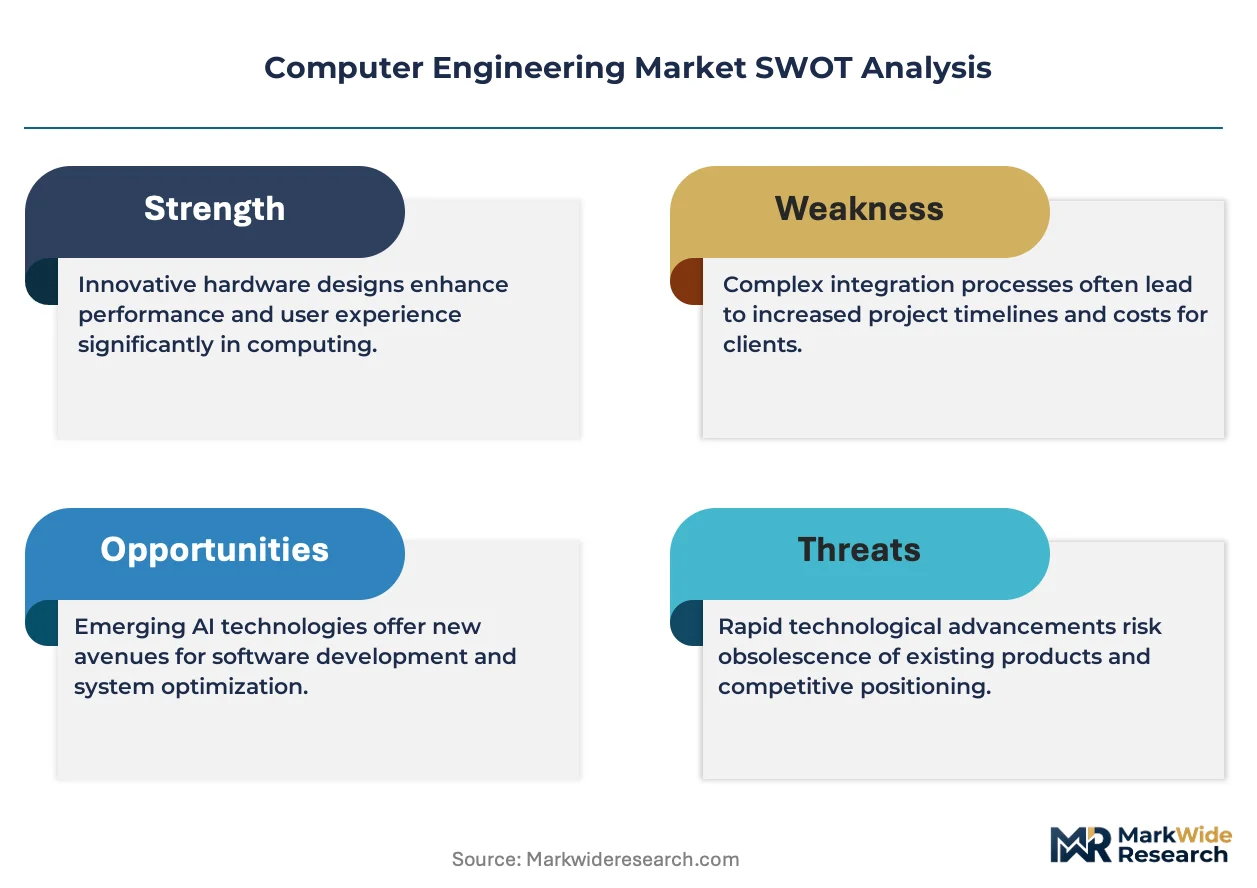
Growth Catalysts
- EU AI Act compliance mandates:Risk classification requirements for embedded systems in medical devices are accelerating validation investments across European healthcare technology procurement pipelines.
- Cloud-native manufacturing workflows:Industrial automation corridors in Germany are driving specialized component orders for integrated hardware-software platforms serving automotive OEM production lines.
- Edge inference engine embedding:AI-driven technology layers are capturing expanding value as enterprises deploy neural processing units directly into network management equipment for real-time signal optimization.
Market Restraints
- Advanced node fabrication concentration:Taiwan-based foundry capacity constraints create supply vulnerability for custom silicon requiring sub-5nm process nodes.
- FDA software-as-a-medical-device validation:Extended premarket submission timelines elevate compliance costs for cross-border suppliers targeting US healthcare deployments.
- Legacy instruction set architecture lock-in:x86 and ARM ecosystem dominance creates switching friction for alternative RISC-V implementations in safety-critical applications.
Strategic Opportunities
- India PLI scheme incentives:Production-linked subsidies for semiconductor assembly and testing are attracting fabrication facility investments targeting domestic electronics manufacturing.
- Chiplets and 3D packaging convergence:Disaggregated die architectures combined with advanced interconnect technologies are enabling cost-optimized heterogeneous integration for mid-volume applications.
- Outcome-based infrastructure contracts:Performance-guaranteed compute provisioning models are penetrating German automotive supplier networks seeking to offload thermal design power optimization risks.
Industry Challenges
- System-on-chip verification engineer scarcity:Specialized talent pools for formal verification and hardware-software co-design remain concentrated in established technology clusters, constraining R&D scaling.
- Multi-jurisdictional certification parallelism:Engineering teams must maintain simultaneous compliance architectures for FDA, EU AI Act, and China's MIIT cybersecurity review protocols without unified standards harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer Engineering Market |
| Market Size in 2026 | $512.8 Billion |
| Market Size in 2035 | $1,059.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Peripherals, Components Technology: AI, Machine Learning, Cloud Computing, Edge Computing Application: Embedded Systems, Data Processing, Network Management, Cybersecurity End User: Education, Healthcare, Manufacturing, Telecommunications |
| Companies Covered | Google, Apple, Microsoft, NVIDIA, IBM, Amazon, Meta, Siemens Healthineers, Salesforce, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer Engineering Market Emerging Trajectories
Hardware abstraction layers are dissolving traditional boundaries between silicon design and software deployment, enabling continuous optimization cycles that compress product development timelines and reshape competitive differentiation.
Chiplets-based modular processor architectures are expanding into high-performance computing and edge AI deployments. Automotive OEMs and cloud infrastructure operators are adopting disaggregated die designs at accelerating cadences to customize compute-memory ratios for specific workloads. This modular approach is expanding into supply chain flexibility by decoupling process node dependencies across functional blocks.
China's MIIT cybersecurity review protocols are mandating source code inspection and data localization for network equipment deployed in critical infrastructure. Multinational engineering teams must establish parallel compliance documentation for hardware-software platforms crossing Chinese manufacturing bases. Medical device and telecommunications segments are responding by segmenting product variants or consolidating around the most restrictive jurisdictional standard.
Enterprise buyers are consolidating vendor relationships around integrated hardware-software-lifecycle service bundles. German industrial automation purchasers are displacing component-centric procurement with long-term compute-performance contracts that transfer obsolescence risk to suppliers. This consolidation pattern is most visible in healthcare and automotive verticals where regulatory validation costs amplify switching penalties.
Computer Engineering Market Segmentation
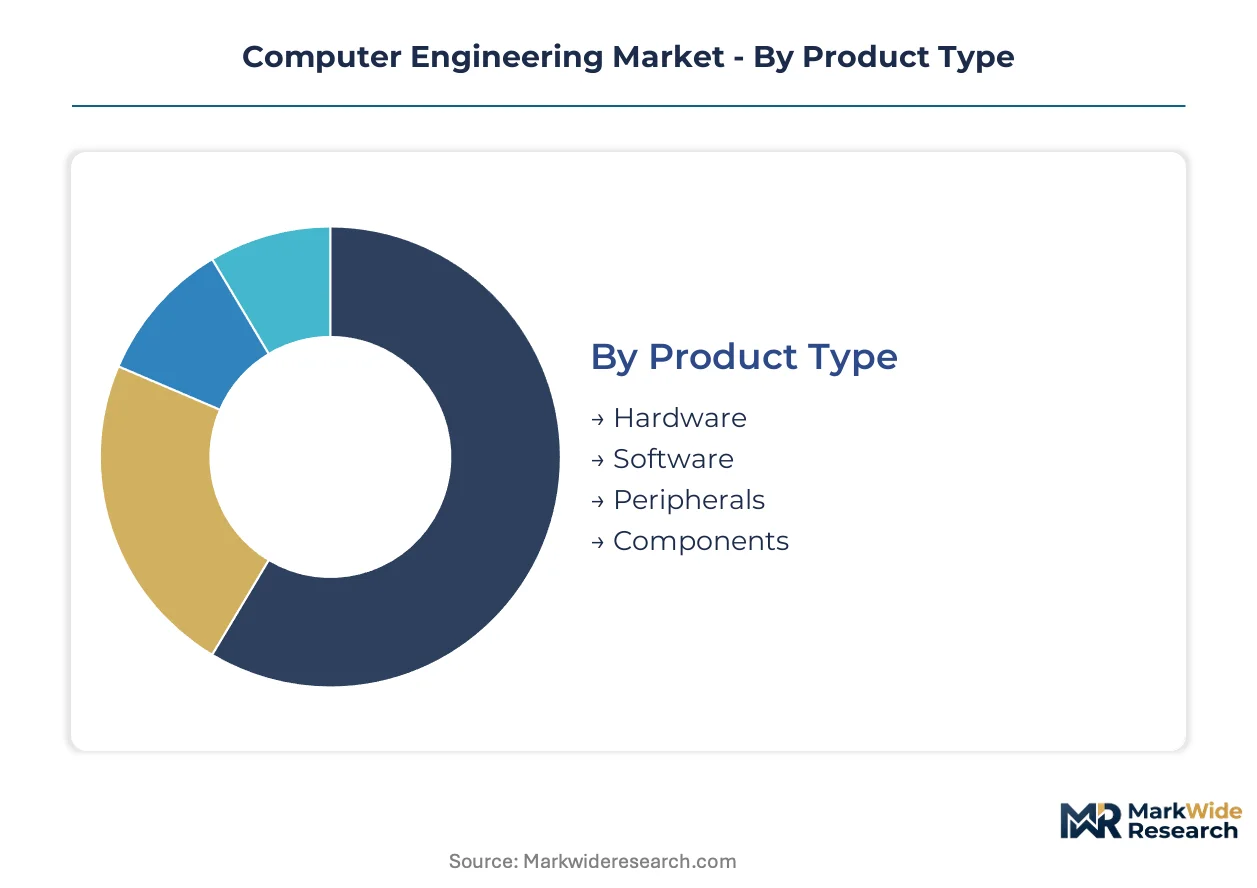
Segmentation in computer engineering reveals how capital allocation and technical specialization concentrate across hardware fabrication, software licensing, and integrated system deployment. Procurement patterns diverge sharply between volume-driven commodity components and custom silicon requiring multi-year validation cycles.
Product Type:
Capital intensity peaks in segments requiring cleanroom fabrication and mask-set development, while software layers monetize through recurring licensing rather than upfront equipment expenditure.
- Hardware:Custom silicon fabrication demands the highest upfront capital commitment, with mask costs for advanced nodes running into millions per design iteration. Demand concentrates in German industrial automation corridors where Siemens Healthineers and automotive OEMs drive specialized component orders for integrated production lines. EU AI Act compliance mandates are reshaping validation requirements for embedded systems deployed in European medical devices.
- Software:Subscription-based delivery models compress capital expenditure into recurring operational outlays, with NVIDIA's CUDA ecosystem dominating AI-accelerated datacenter deployments. Cloud-native engineering workflows from Google and Microsoft anchor procurement decisions in enterprise infrastructure planning.
- Peripherals:Standardized interfaces and mature manufacturing processes reduce entry barriers, though specialized industrial peripherals command premium pricing in safety-critical applications.
- Components:Disaggregated die architectures and chiplet-based designs are enabling cost-optimized heterogeneous integration for mid-volume applications across telecommunications and automotive verticals.
Hardware absorbs the bulk of installed capacity; software is expanding most quickly as enterprises shift procurement toward operational expenditure models.
Technology:
Adoption velocity varies by deployment complexity, with cloud infrastructure representing mature scale and edge inference engines capturing emerging investment priority.
- AI:Neural processing units embedded directly into network management equipment enable real-time signal optimization, with inference engines displacing cloud-only architectures in latency-sensitive applications.
- Machine Learning:Training workloads concentrate in hyperscale datacenters while model compression techniques drive edge deployment feasibility for resource-constrained devices.
- Cloud Computing:Dominant volume segment with established pricing frameworks and vendor consolidation around integrated hardware-software-lifecycle bundles.
- Edge Computing:Fastest-expanding frontier for specialized engineering talent, particularly in automotive and healthcare settings where real-time constraints mandate localized processing.
Cloud computing retains the largest installed base; edge computing climbs the fastest as automotive OEMs and medical device manufacturers localize inference capabilities.
Application:
Regulatory burden intensity determines segment attractiveness, with safety-critical applications commanding premium margins but extended validation timelines.
- Embedded Systems:FDA's software-as-a-medical-device framework and EU AI Act risk classifications tighten validation requirements, elevating compliance costs for cross-border suppliers targeting healthcare deployments.
- Data Processing:Hyperscale operators drive standardization in thermal design power optimization and instruction-per-watt efficiency benchmarking.
- Network Management:China's MIIT cybersecurity review protocols mandate source code inspection and data localization, forcing parallel compliance documentation for multinational engineering teams.
- Cybersecurity:Hardware-software co-design requirements intensify as enterprises embed security primitives at the silicon layer rather than relying solely on software overlays.
Embedded systems carry the heaviest compliance overhead; network management faces the steepest jurisdictional fragmentation as national security protocols multiply.
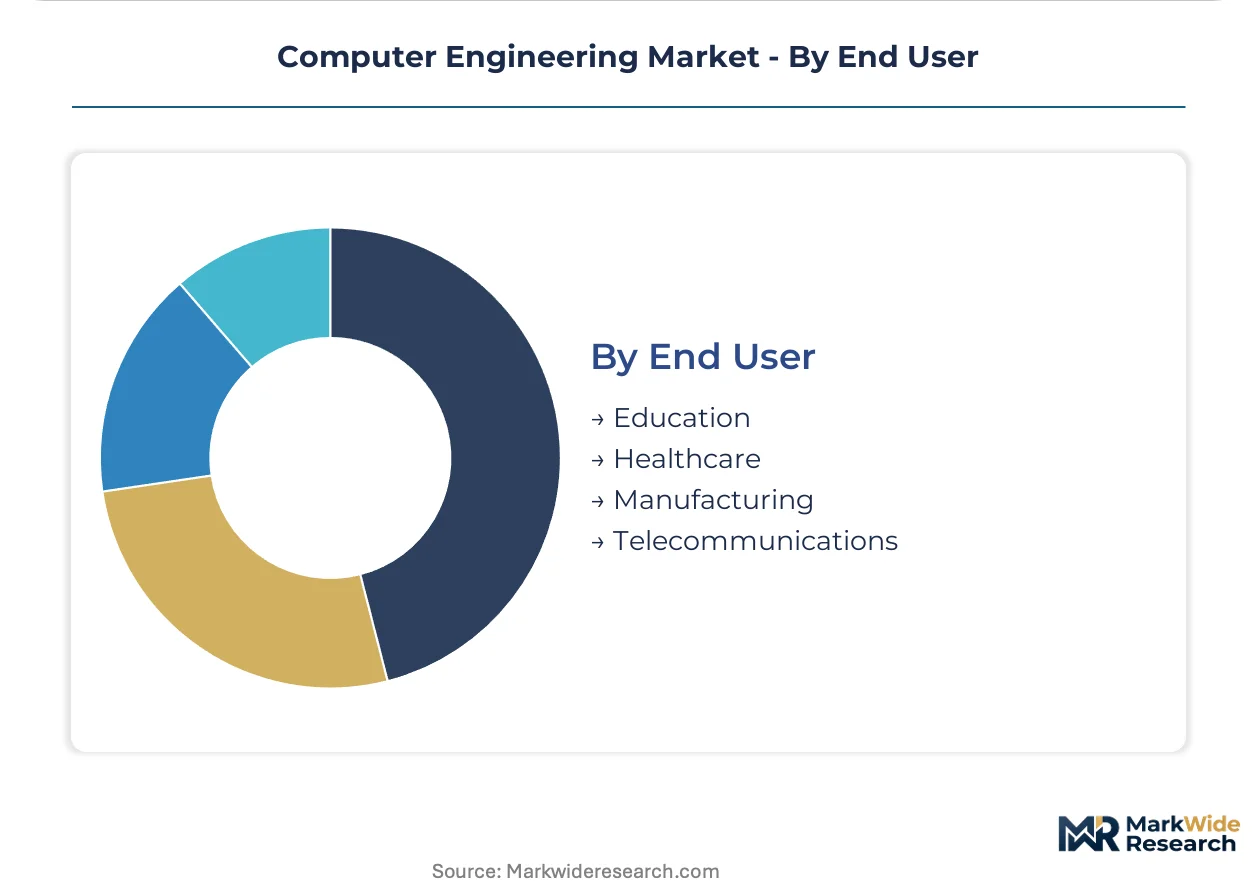
End User:
Procurement sophistication and contract structure vary dramatically across verticals, from outcome-based performance guarantees in manufacturing to grant-funded cycles in education.
- Education:Budget-constrained procurement favors standardized platforms with multi-year support commitments, limiting exposure to leading-edge technologies.
- Healthcare:FDA premarket submission timelines and EU MDR requirements create switching friction that amplifies incumbent vendor advantages in validated system deployments.
- Manufacturing:German automotive supplier networks are pioneering outcome-based infrastructure contracts that transfer thermal design power optimization risks to equipment vendors.
- Telecommunications:Equipment vendor consolidation around integrated lifecycle service bundles displaces component-centric procurement as regulatory validation costs compound.
Manufacturing commands the most sophisticated procurement structures; healthcare presents the highest barriers to competitive entry due to validation pathway complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian fabrication clusters while consumption distributes across German industrial corridors and American healthcare systems. Taiwan-based foundries supply advanced-node silicon to equipment vendors serving latency-sensitive automotive and medical deployments. Regulatory divergence between Washington, Brussels, and Beijing forces parallel compliance architectures that reshape procurement geography.
United States
FDA's software-as-a-medical-device framework and NHTSA automotive safety standards drive specialized engineering validation for healthcare and autonomous systems. The IRA's domestic manufacturing incentives accelerate semiconductor assembly investments in Arizona and Texas. Silicon Valley clusters anchor cloud-native development while Boston's medical device corridor concentrates embedded systems talent.
Germany
Siemens Healthineers and automotive OEMs in Bavaria and Baden-Württemberg generate specialized component demand for integrated production lines. The EU AI Act's risk classification system tightens compliance requirements for medical device embedded systems. The KBA's automotive cybersecurity regulations mandate hardware-software co-validation for network-connected vehicle platforms.
China
MIIT cybersecurity review protocols mandate source code inspection and data localization for network equipment in critical infrastructure. Domestic cloud operators and telecommunications equipment vendors drive volume demand for custom silicon. Yangtze River Delta fabrication clusters serve both export markets and import-substitution programs targeting automotive AI chips.
India
The PLI scheme's production-linked subsidies attract semiconductor assembly and testing investments targeting domestic electronics manufacturing. CDSCO's emerging software-as-a-medical-device guidelines create validation pathway uncertainty for cross-border suppliers. Karnataka and Telangana engineering clusters concentrate firmware development talent for telecommunications and automotive verticals.
Japan
METI's semiconductor revitalization strategy funds domestic advanced packaging and materials science research. PMDA's digital health regulations establish validation frameworks for AI-embedded diagnostic equipment. Tokyo-Osaka industrial corridors sustain precision manufacturing demand for robotics and industrial automation controllers.
Computer Engineering Market Vendor Landscape
Top-tier vendors anchor hyperscale cloud and AI accelerator segments, while mid-tier specialists capture automotive and healthcare niches requiring extended validation cycles. NVIDIA's CUDA ecosystem dominance and Microsoft's Azure integration exemplify platform-centric competitive moats. Strategic moves concentrate on chiplets-based modular architectures and outcome-based infrastructure contracts transferring thermal design risks to vendors.
Within the cloud-native platform tier, Google and Microsoft exemplify integrated hardware-software-lifecycle bundling that displaces component-centric procurement. NVIDIA occupies a position representing AI-accelerated datacenter specialization, its ecosystem leverage creating switching friction for enterprise buyers. These three anchors demonstrate how vertical integration into silicon design and software deployment compresses development timelines and consolidates vendor relationships around performance-guaranteed compute provisioning.
| Leading Market Players |
|---|
| Apple |
| Microsoft |
| NVIDIA |
| IBM |
| Amazon |
| Meta |
| Siemens Healthineers |
| Salesforce |
| Others |
Supply Flow & Price Mechanics
Advanced node mask-set costs cascade through fabrication tiers into subscription-based hardware-software bundles, compressing capital expenditure for German automotive buyers while elevating per-unit pricing for low-volume custom silicon in FDA-validated medical devices.
Pricing Analysis
Margin tightening in custom silicon fabrication reflects Taiwan foundry capacity constraints and escalating EU AI Act validation overhead. Pricing stratifies across premium certified-grade, standard industrial-grade, and economy commercial-grade tiers, with FDA 510(k) pathway costs amplifying differentiation. Cost-down pressure on mid-volume chiplet assemblies accelerates because automotive OEMs consolidate around outcome-based performance contracts. Healthcare procurement committees exhibit lowest price sensitivity due to switching penalties from embedded system validation, while education sector buyers drive hardest bargain on standardized platforms.
Supply Chain Analysis
Regional distribution centers in Singapore, Rotterdam, and Long Beach anchor hub-and-spoke fulfillment patterns for semiconductor components. Supply concentrates in Taiwan for sub-5nm foundry output, South Korea for advanced memory, and China for mature-node logic and assembly. Raw material dependencies span silicon wafers, EUV photoresists, and rare earth elements for magnetics. Single-source vulnerability around Taiwan Strait logistics chokepoints threatens just-in-time delivery for automotive and medical device production lines. Distribution runs through authorized distributor networks serving OEM direct procurement alongside cloud hyperscaler volume contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chiplet-based modular architectures are displacing monolithic system-on-chip designs, compressing development timelines and reshaping competitive differentiation across industrial automation and healthcare verticals.
For Market Incumbents: To counter RISC-V ecosystem encroachment in safety-critical embedded systems, NVIDIA and Microsoft must deepen CUDA and Azure edge runtime moats through backward integration into custom silicon design. Certification investment in EU AI Act high-risk system validation creates switching friction that protects installed base in Siemens Healthineers partnerships. For New Entrants and Emerging Players: Cloud-native developer tooling channels offer lowest customer acquisition cost entry into mid-market manufacturing segments underserved by incumbent platform bundling. White-space targets include India PLI scheme semiconductor assembly facilities and German automotive supplier networks seeking thermal design power outsourcing. Open-source RISC-V core licensing provides go-to-market differentiation against ARM ecosystem lock-in. For Investors and Strategic Acquirers: Distressed-cycle entries favor formal verification engineering boutiques in Israel and Germany with EU AI Act compliance expertise. Long-term viability hinges on 5-10 year automotive software-defined vehicle transition windows. Watch for MIIT cybersecurity review protocol expansion into medical device categories as inflection signal for China market access restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Chiplet Architecture Adoption | Disaggregated die designs enable cost-optimized heterogeneous integration for mid-volume automotive AI workloads. |
| EU AI Act Compliance Investment | High-risk system validation creates regulatory moats protecting incumbent positions in medical device embedded systems. |
| Outcome-Based Infrastructure Contracts | Performance-guaranteed compute provisioning transfers thermal design power optimization risk to equipment vendors in Germany. |
| India PLI Facility Establishment | Production-linked subsidies attract semiconductor assembly investments targeting domestic electronics manufacturing demand. |
| Formal Verification Talent Acquisition | Hardware-software co-design expertise scarcity constrains R&D scaling for safety-critical system development. |
Methodological Framework
Document review covered SEC 10-K filings from hyperscaler cloud operators, EU AI Act implementation guidance, FDA software-as-a-medical-device premarket submission databases, and Taiwan Semiconductor Industry Association trade statistics, complemented by interviews with embedded systems engineering directors, hospital biomedical equipment procurement managers, automotive Tier 1 supplier platform architects, and cloud infrastructure capacity planners. Bottom-up unit economics modeling triangulated against top-down market sizing from foundry capacity disclosures and OEM capital expenditure announcements.
Market value and volume outputs trace from segment-level demand aggregation across hardware fabrication, software licensing, and integrated system deployment categories, spanning the projection horizon through 2035. Segmentation dimensions modeled include product type, technology layer, application vertical, end-user industry, and regional regulatory cluster. CAGRs derive from regression analysis of historical foundry utilization rates, hyperscaler infrastructure investment cycles, and automotive semiconductor content growth trajectories. Industry-specific forecast inputs incorporate EU AI Act compliance cost assumptions and FDA validation timeline distributions.
The model holds under stable Taiwan Strait logistics conditions and sustained cloud infrastructure investment; deviation in foundry capacity allocation or export control expansion would shift supply-side constraints and pricing trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Application Platform As a Service Market
Software & Services
Discount Management Software Market
Software & Services
Non-Profit Donation Software Market
Software & Services
On-Demand Wellness Software Market
Software & Services
Driver and Staff Management Software Market
Software & Services
Compensation Software Market
Software & Services
Global Home Inspection Software Market
Software & Services
Instant Messaging Software Market
Software & Services
Vending Software Market
Software & Services
Asia-Pacific Printing Software Market
Software & Services
Equipment Management Software Market
Software & Services
Global Roofing Software Market
Software & Services
Europe Pharmacy POS Software Market
Software & Services
Trading Software Market
Software & Services
Global ITSM Software Market
Software & Services
Vlog Editing Software Market