
 Software Construction Components Market | 2026-2036
Software Construction Components Market Size, Share, and Industry Trends Forecast 2026-2036
Software Construction Components Market Analytics
Open-source container orchestration is recalibrating cost structures across modular software construction stacks as proprietary middleware loses pricing power. Microsoft Corporation leverages its Azure DevOps ecosystem to anchor enterprise adoption of pre-validated component libraries. Autodesk Inc. specializes in BIM-integrated APIs that dominate architectural and infrastructure workflows. Trimble Inc. competes through field-data capture modules that extend construction software into hardware-augmented environments.
Software construction components encompass reusable code modules, interface protocols, and functional libraries that developers assemble into complete applications, typically distributed through package registries with semantic-versioning constraints and dependency-resolution algorithms. Their primary commercial purpose is to compress development cycles and standardize interoperability across distributed engineering teams. Cloud-based deployment models now capture the fastest expansion as enterprises abandon on-premises maintenance burdens, while hybrid configurations retain margin pools in regulated sectors where data residency requirements persist. Frameworks maintain structural leadership in volume terms, though API segments show the steepest trajectory as microservices architectures proliferate.
The EU AI Act, FDA software-as-medical-device guidance, and Japan's METI data-free-flow-with-trust framework collectively tighten validation requirements for construction components deployed in safety-critical infrastructure. China's MIIT cybersecurity review and GB standards add parallel compliance layers for vendors accessing state-linked projects. Stakeholders must now weigh jurisdiction-specific certification costs against component reusability when architecting multi-market distribution strategies.
Market Dynamics
Cloud-native orchestration platforms are fragmenting procurement patterns across enterprise IT departments, forcing vendors to recalibrate distribution models around container registries and API marketplaces rather than perpetual license structures.
Growth Catalysts
- EU AI Act compliance mandates:Automated building-design systems require pre-validated component libraries, expanding procurement of certified construction toolkits across German industrial software corridors.
- Microservices architecture proliferation:API segments accelerate as distributed engineering teams demand modular interoperability protocols for rapid application assembly.
- Japan METI data-free-flow-with-trust framework:Cross-border component validation standards unlock procurement from Tokyo engineering-technology hubs into broader Asia-Pacific markets.
Market Restraints
- Regulatory friction from China's MIIT cybersecurity review:GB standards impose parallel compliance layers that fragment component reusability for vendors accessing state-linked infrastructure projects.
- Supply concentration in proprietary middleware:Legacy integration platform vendors retain pricing power in regulated sectors where data residency requirements persist.
- Technical limitation of semantic-versioning constraints:Dependency-resolution algorithms create brittle upgrade paths that stall enterprise adoption of bleeding-edge open-source modules.
Strategic Opportunities
- Underpenetrated hybrid deployment configurations:Margin pools persist in US federal and EU defense contracting where on-premises validation remains mandatory for classified infrastructure workflows.
- Technology convergence of BIM-integrated APIs with field-data capture modules:Hardware-augmented construction environments create new component categories bridging software and sensor networks.
- Regulatory tailwind from FDA software-as-medical-device guidance:Safety-critical infrastructure validation requirements expand addressable market for pre-certified component libraries in healthcare-adjacent construction systems.
Industry Challenges
- Certification timeline compression:Jurisdiction-specific validation requirements from EMA, PMDA, and Health Canada force parallel testing tracks that strain R&D resource allocation.
- Integration complexity with legacy CAD systems:Decades-old architectural file formats resist API abstraction, requiring costly adapter development for component interoperability.
- Skill scarcity in DevSecOps:Security-hardened pipeline engineering talent concentrates in hyperscaler hubs, leaving mid-market vendors dependent on contracted specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software Construction Components Market |
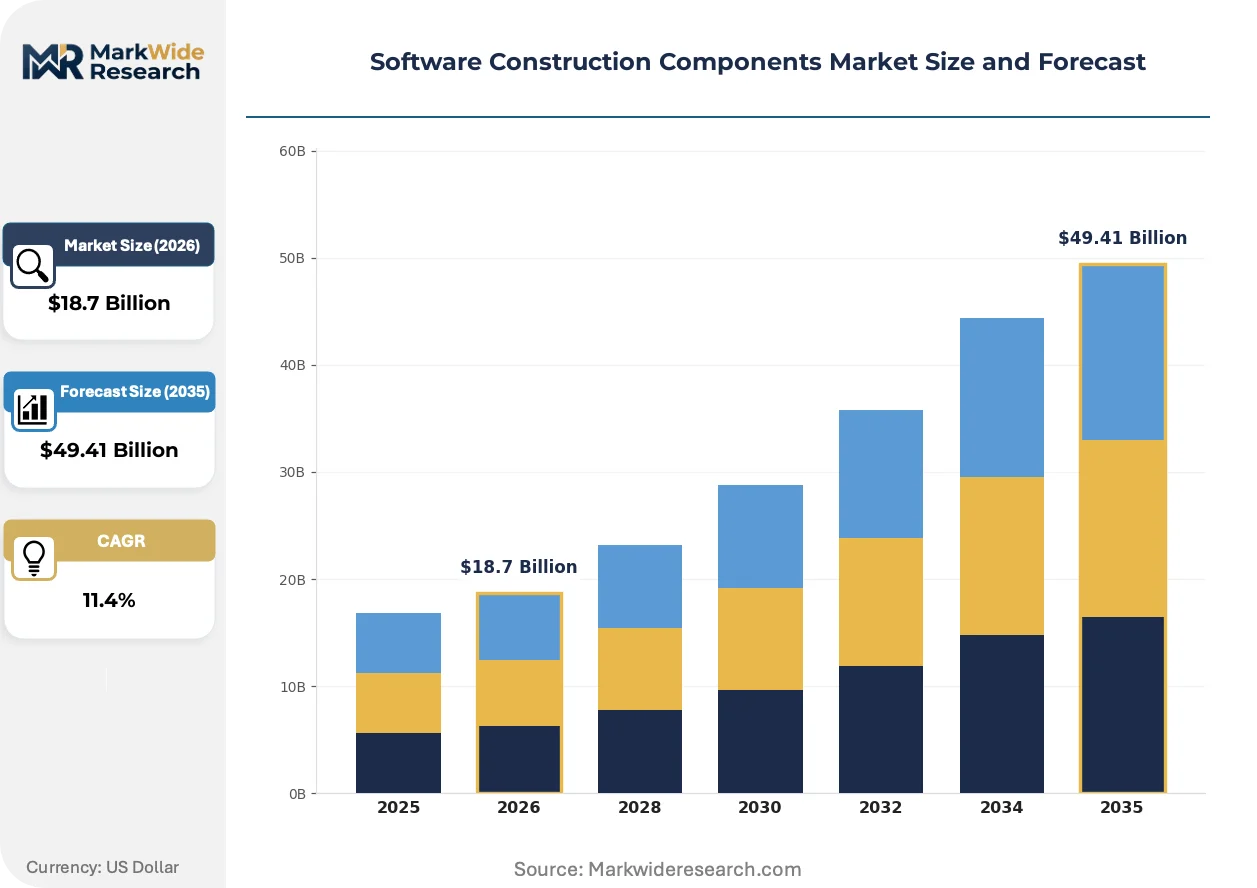
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frameworks, Libraries, APIs, Add-ons Deployment Model: On-Premises, Cloud-Based, Hybrid, Private Cloud End User: Developers, Enterprises, Startups, Educational Institutions Service Type: Support Services, Custom Development, Integration Services, Maintenance |
| Companies Covered | Microsoft Corporation, Google LLC, IBM Corporation, Amazon Web Services, Oracle Corporation, Autodesk Inc., Trimble Inc., Bentley Systems, Sage Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software Construction Components Market Evolving Landscape
Containerized delivery mechanisms are rewriting how construction software components reach engineering teams, compressing traditional sales cycles and flattening channel hierarchies.
WebAssembly runtime modules are overtaking traditional JavaScript-based component architectures for performance-critical rendering pipelines. Industrial design firms in Stuttgart and Detroit adopt these binaries for browser-based BIM visualization, collapsing the latency gap between desktop CAD suites and cloud-native collaboration tools.
REACH substance restrictions and RoHS compliance extensions now govern the hardware-software interface layer, mandating material disclosure in field-data capture devices. Component vendors must embed supply-chain provenance APIs or face exclusion from EU public procurement frameworks, with German municipal infrastructure projects enforcing the strictest verification protocols.
Enterprise buyers now unbundle perpetual licenses in favor of consumption-metered API calls, disrupting traditional software reseller networks. Japanese general contractors pioneered this shift through METI-subsidized digital transformation programs, with US federal agencies now piloting similar structures for civilian infrastructure grants.
Software Construction Components Market Segmentation
Component selection in construction software hinges on interoperability requirements, compliance mandates, and team distribution models. Procurement patterns diverge sharply between safety-critical infrastructure projects and rapid-prototype development environments.
Product Type:
Technical debt tolerance and integration complexity drive buyer preferences across modular code architectures.
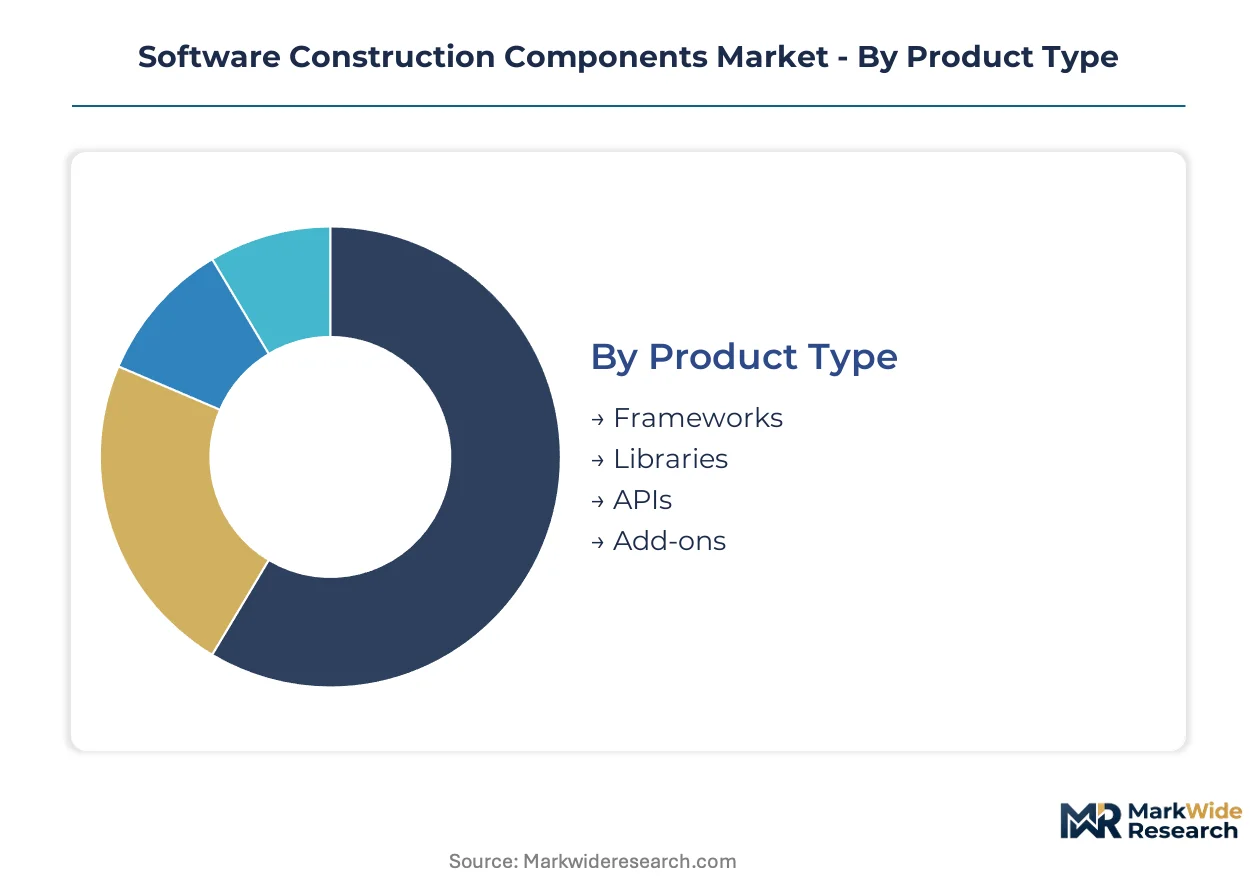
- Frameworks:Structural scaffolding for application assembly, incorporating dependency injection and routing protocols. German industrial software corridors favor pre-validated frameworks that satisfy EU AI Act documentation requirements for automated building-design systems.
- APIs:Interface protocols enabling microservices communication and third-party service integration. Japanese engineering-technology hubs in Tokyo and Osaka deploy these most aggressively for cross-border component validation under METI data-free-flow-with-trust frameworks.
- Libraries:Reusable functional modules distributed through semantic-versioned package registries.
- Add-ons:Extension modules plugging into existing CAD and BIM platforms.
Frameworks lead on scale; APIs lead on momentum.
Deployment Model:
Data residency requirements and maintenance burden trade-offs reshape infrastructure decisions across regulated sectors.
- Cloud-Based:Container-orchestrated delivery through hyperscaler platforms, eliminating on-premises hardware cycles. US federal civilian infrastructure grants now pilot consumption-metered procurement structures for these configurations.
- Hybrid:Split architectures retaining sensitive workloads on-premises while leveraging cloud elasticity for compute-intensive tasks. EU defense contracting and classified infrastructure workflows in Germany mandate this model for validation compliance.
- On-Premises:Fully captive infrastructure satisfying air-gapped security requirements.
- Private Cloud:Single-tenant virtualized environments offering controlled resource pooling.
Cloud-Based deployments capture volume leadership; Hybrid configurations command premium margin pools.
End User:
Budget authority and compliance exposure differentiate procurement behavior across organizational maturity levels.
- Enterprises:Large IT departments with formal vendor governance and multi-year roadmaps. These buyers dominate procurement of certified construction toolkits across German municipal infrastructure projects enforcing REACH substance verification protocols.
- Developers:Individual practitioners and small teams prioritizing rapid integration and community-supported modules. Stuttgart and Detroit industrial design firms adopting WebAssembly runtime modules for browser-based BIM visualization typify this segment.
- Startups:Venture-backed builders favoring open-source foundations and API-first architectures.
- Educational Institutions:Universities and technical colleges training next-generation engineering talent on standardized platforms.
Enterprises anchor revenue concentration; Developers drive technology adoption velocity.
Service Type:
Internal capability gaps determine outsourcing depth for implementation and ongoing operations.
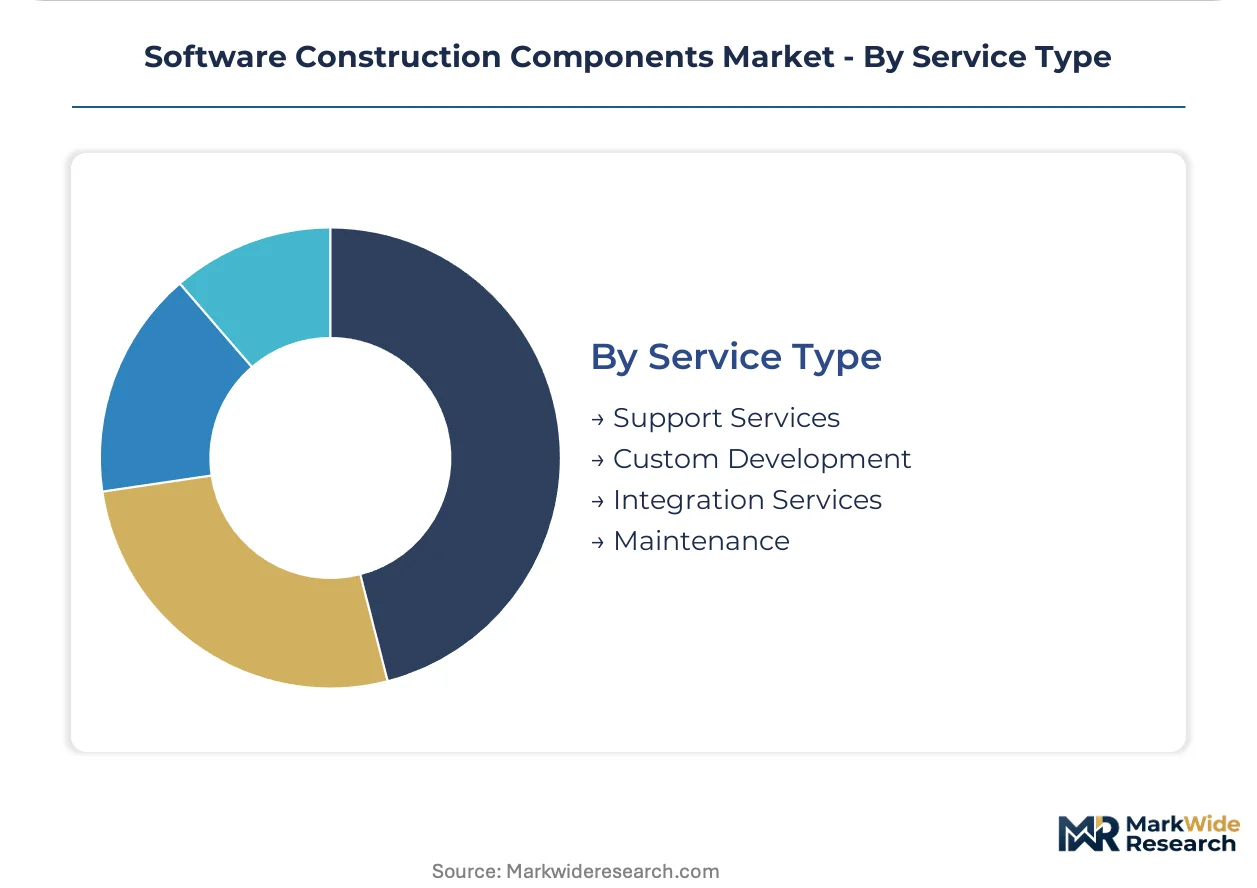
- Integration Services:Adapter development bridging legacy CAD file formats with modern API abstractions. Japan's METI-subsidized digital transformation programs accelerated demand for these services among general contractors unbundling perpetual licenses.
- Custom Development:Bespoke component construction for specialized architectural workflows. US federal agencies and EU infrastructure authorities commission these for safety-critical system validation under FDA software-as-medical-device guidance parallels.
- Support Services:Tiered response agreements ensuring production system continuity.
- Maintenance:Version management and security patching for deployed component libraries.
Integration Services command the steepest expansion trajectory; Custom Development retains the highest contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial software corridor anchors procurement intensity for certified construction toolkits as EU AI Act compliance mandates reshape vendor selection criteria across automated building-design systems.
United States
Enterprise IT departments in the Pacific Northwest and Greater Boston drive cloud-native adoption for federal civilian infrastructure grants piloting consumption-metered procurement. FDA software-as-medical-device guidance tightens validation requirements for safety-critical construction components. Detroit industrial design firms adopt WebAssembly runtime modules for browser-based BIM visualization, collapsing latency gaps between desktop CAD and cloud collaboration.
Germany
Municipal infrastructure projects enforce REACH substance verification protocols for hardware-software interface layers in field-data capture devices. EU AI Act documentation requirements favor pre-validated frameworks from Stuttgart engineering clusters. Baden-Württemberg's industrial software corridor concentrates procurement of certified construction toolkits for automated building-design compliance.
Japan
Tokyo and Osaka engineering-technology hubs deploy API protocols aggressively for cross-border component validation under METI data-free-flow-with-trust frameworks. General contractors pioneered unbundling of perpetual licenses through METI-subsidized digital transformation programs. Nagoya manufacturing ecosystems integrate these modules into hardware-augmented construction environments.
China
MIIT cybersecurity review and GB standards impose parallel compliance layers fragmenting component reusability for state-linked infrastructure projects. Yangtze River Delta software clusters navigate dual carbon goals while supplying modular construction protocols. Beijing-Tianjin-Hebei corridor concentrates procurement of hybrid deployment configurations satisfying data residency requirements.
United Kingdom
London's financial-technology crossover demand pulls API-first architectures into construction-adjacent regulatory technology applications. CSRD disclosure requirements extend to embedded software components in infrastructure supply chains. Southeast England engineering consultancies specialize in adapter development bridging legacy CAD formats with modern API abstractions.
Software Construction Components Market Competitive Landscape
Global majors compete with regional champions across cloud orchestration and compliance certification dimensions, producing a tiered structure where hyperscaler platforms anchor enterprise adoption while specialized vendors capture vertical niches. Three archetypes dominate: platform ecosystems bundling DevOps infrastructure, BIM-integrated specialists serving architectural workflows, and field-data capture vendors bridging software with sensor networks. Competitive moves concentrate on API marketplace expansion and jurisdiction-specific certification acquisition.
Within the platform ecosystem tier, Microsoft Corporation exemplifies cloud-native anchoring through Azure DevOps distribution, while Autodesk Inc. occupies a position representing BIM-integrated specialization for architectural and infrastructure workflows. Amazon Web Services sits within the infrastructure-as-a-service archetype, supplying container orchestration layers that recalibrate cost structures across modular construction stacks. These three entities collectively illustrate how vendor positioning fragments across compliance-heavy regulated sectors and rapid-prototype development environments.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Google LLC |
| IBM Corporation |
| Amazon Web Services |
| Oracle Corporation |
| Autodesk Inc. |
| Trimble Inc. |
| Bentley Systems |
| Sage Group |
| Others |
Value Network & Pricing Analysis
Container registry storage fees and hyperscaler compute unit indices cascade through software construction component supply chains, compressing margins for proprietary middleware vendors while amplifying pricing power for certified open-source distributors serving EU AI Act compliance markets.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers dominates pricing dynamics across the software construction components landscape. Three-tier pricing structure across premium, standard, and economy levels separates pre-validated EU AI Act certified libraries from community-supported modules and bare-metal open-source foundations. Price differentiation hinges on certification grade and after-sales validation support. Cost compression in the economy tier is intensifying because hyperscaler marketplaces commoditize basic container orchestration. Enterprise IT departments exhibit lowest price sensitivity for certified construction toolkits, while individual developers drive aggressive procurement of free-tier API calls.
Supply Chain Analysis
Reverse-logistics flows for deprecated component versions and security-patched legacy modules create secondary distribution channels through specialized registries serving regulated sectors. Component sourcing concentrates in the United States, Germany, and Japan where hyperscaler infrastructure and industrial software corridors anchor production. Raw material dependencies include cloud compute capacity, cryptographic signing infrastructure, and semantic-versioning protocol maintenance. Single-source vulnerability around container registry operators presents structural risk for vendors dependent on centralized distribution. Distribution runs through API marketplaces and hyperscaler-integrated DevOps platforms rather than traditional software reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in software construction components rests on the shift toward consumption-metered API architectures that capture recurring revenue from previously perpetual-license deployments.
For Market Incumbents: Anticipate displacement from WebAssembly runtime modules overtaking JavaScript-based architectures in browser-based BIM visualization. Microsoft Corporation and Autodesk Inc. must deepen certification investments for EU AI Act pre-validated libraries to defend against emerging open-source compliance specialists. Channel control through Azure DevOps and BIM-integrated API ecosystems represents the critical defensive lever.
For New Entrants and Emerging Players: FDA software-as-medical-device guidance in the United States opens a window for specialized component vendors targeting healthcare-adjacent construction systems with pre-certified validation documentation. White-space targets include hybrid deployment configurations for US federal classified infrastructure and field-data capture modules bridging software with REACH-compliant sensor hardware. Go-to-market execution should prioritize consumption-metered procurement structures piloted through civilian infrastructure grants.
For Investors and Strategic Acquirers: Asymmetric upside sits with DevSecOps pipeline specialists possessing security-hardened engineering talent concentrated in hyperscaler hubs. Long-term viability over the next decade favors vendors with jurisdiction-specific certification moats rather than undifferentiated open-source aggregators. Watch for inflection when MIIT cybersecurity review enforcement intensifies fragmentation of component reusability for China-accessing vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure DevOps ecosystem anchoring anchors enterprise adoption of pre-validated component libraries across German industrial corridors. |
| Certification Investment | EU AI Act compliance documentation expands addressable market for automated building-design system vendors in Stuttgart engineering clusters. |
| Acquisition of Specialist Firm | Field-data capture module vendors bridging software with sensor networks command premium positioning in hardware-augmented construction. |
| Geographic Expansion | Tokyo and Osaka engineering-technology hubs unlock cross-border component validation under METI data-free-flow-with-trust frameworks. |
| Strategic Partnership | Integration services alliances with Japanese general contractors accelerate unbundling of perpetual licenses through subsidized digital transformation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers, platform engineers, and integration specialists alongside secondary validation through SEC filings, hyperscaler capex disclosures, container registry adoption metrics, and EU regulatory documentation databases. Bottom-up component deployment tracking and top-down enterprise IT spend analysis were triangulated to anchor market sizing.
Comparable-period anchoring to historical cloud-native adoption curves and compliance-driven procurement cycles shaped the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical application, integration complexity, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to validated baseline estimates, incorporating API call volume trajectories and certified component library penetration rates as industry-specific inputs.
Revisions become necessary when MIIT cybersecurity review enforcement intensifies, FDA software-as-medical-device guidance expands scope, or hyperscaler pricing structures shift materially. Forecasts reflect documented assumptions about regulatory timeline adherence and enterprise cloud migration velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Combat Management Systems Software Market
Software & Services
Parks and Playground Inspection Software Market
Software & Services
Geomechanics Software and Service Market
Software & Services
Global Guidewire Market
Software & Services
Global Professional Service Automation (PSA) Software Market
Software & Services
Classified Platform Market
Software & Services
Global Photogrammetry Software Market
Software & Services
Sales Intelligence Software Market
Software & Services
Scanning and Migration Software Market
Software & Services
Lawn Care Software Market
Software & Services
Digital Illustration App Market
Software & Services
Lease Accounting Software Market
Software & Services
Embedded Operating Systems Market
Software & Services
Vehicle Embedded Software Market
Software & Services
Global Catalog Management Software Market
Software & Services
Acoustic Simulation Software Market