
 Latin America E-Commerce Logistics Market | 2026-2036
Latin America E-Commerce Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America E-Commerce Logistics Market Foresight
Apparel and consumer electronics retail is consolidating as the dominant end-use vertical across Latin American e-commerce logistics networks. Mercado Libre leverages its proprietary fulfillment infrastructure to control last-mile density in São Paulo and Mexico City corridors. FedEx Corporation anchors cross-border express volumes through Miami hub operations serving Andean and Southern Cone markets. Loggi competes aggressively on same-day urban delivery in Brazilian metropolitan zones.
Latin America e-commerce logistics encompasses the integrated movement, storage, and fulfillment of online retail orders across warehousing, intercity freight, and terminal distribution nodes, typically operating with inventory turnover targets of 15-30 days for fashion and electronics categories. Its primary commercial purpose is collapsing delivery times between digital checkout and physical receipt while minimizing cost per package in markets with fragmented addressing systems and variable road quality. Last mile delivery and express delivery modes now capture disproportionate investment as margin pools concentrate in speed-tiered service differentiation. Warehousing automation and AI logistics are displacing manual sortation and static route planning across major fulfillment centers.
Brazil's ANTT freight regulations, Mexico's SAT customs protocols, and Colombia's transport ministry last-mile safety standards collectively shape carrier licensing, cross-border clearance speed, and vehicle fleet specifications. These frameworks determine market access thresholds and operational cost structures for both domestic platforms and international integrators. Stakeholders must monitor how pending fintech-logistics convergence rules and emissions standards for urban delivery fleets reshape capital allocation across the region's fulfillment networks.
Market Dynamics
PIX instant-payment adoption in Brazil and SAT customs modernization in Mexico are collapsing settlement-to-delivery cycles, forcing carriers to compress warehouse-to-door timelines from 72 hours toward same-day thresholds.
Growth Catalysts
- Urban density corridors:São Paulo and Mexico City metropolitan zones generate sufficient order volume to justify micro-fulfillment node placement within 10 kilometers of 60% of online buyers.
- ANTT freight deregulation:Brazil's 2023 regulatory relaxation on intercity trucking permits asset-light carriers to scale fleet capacity without legacy concession requirements.
- Apparel inventory velocity:Fashion retailers now demand 15-day warehouse turnover, pulling investment toward automated sortation and dynamic slotting systems.
Market Restraints
- Fuel cost volatility:Diesel price swings across Brazil and Mexico directly compress last-mile margins, with no viable electric fleet substitution at commercial scale before 2028.
- Address database fragmentation:Colombia's informal street naming and unmapped favela zones force manual geocoding, adding 12-18% to delivery cost per package.
- Cross-border duty complexity:SAT's variable classification protocols for consumer electronics create clearance delays that undermine express service guarantees.
Strategic Opportunities
- Colombia's secondary cities:Medellín and Cali e-commerce penetration lags São Paulo by 40 percentage points, offering first-mover density advantages for fulfillment network buildout.
- Fintech-logistics convergence:Embedded credit at checkout is integrating with delivery confirmation, enabling cash-on-digital substitution in underbanked segments.
- Reverse logistics monetization:Apparel retailers are piloting instant refund-at-pickup services, converting returns handling from cost center to customer retention tool.
Industry Challenges
- WMS-TMS integration gaps:Legacy warehouse management systems lack API compatibility with modern transport optimization platforms, forcing expensive middleware development.
- Certification bottlenecks:Colombia's transport ministry last-mile safety standards require vehicle retrofit timelines that outpace available conversion shop capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America E-Commerce Logistics Market |
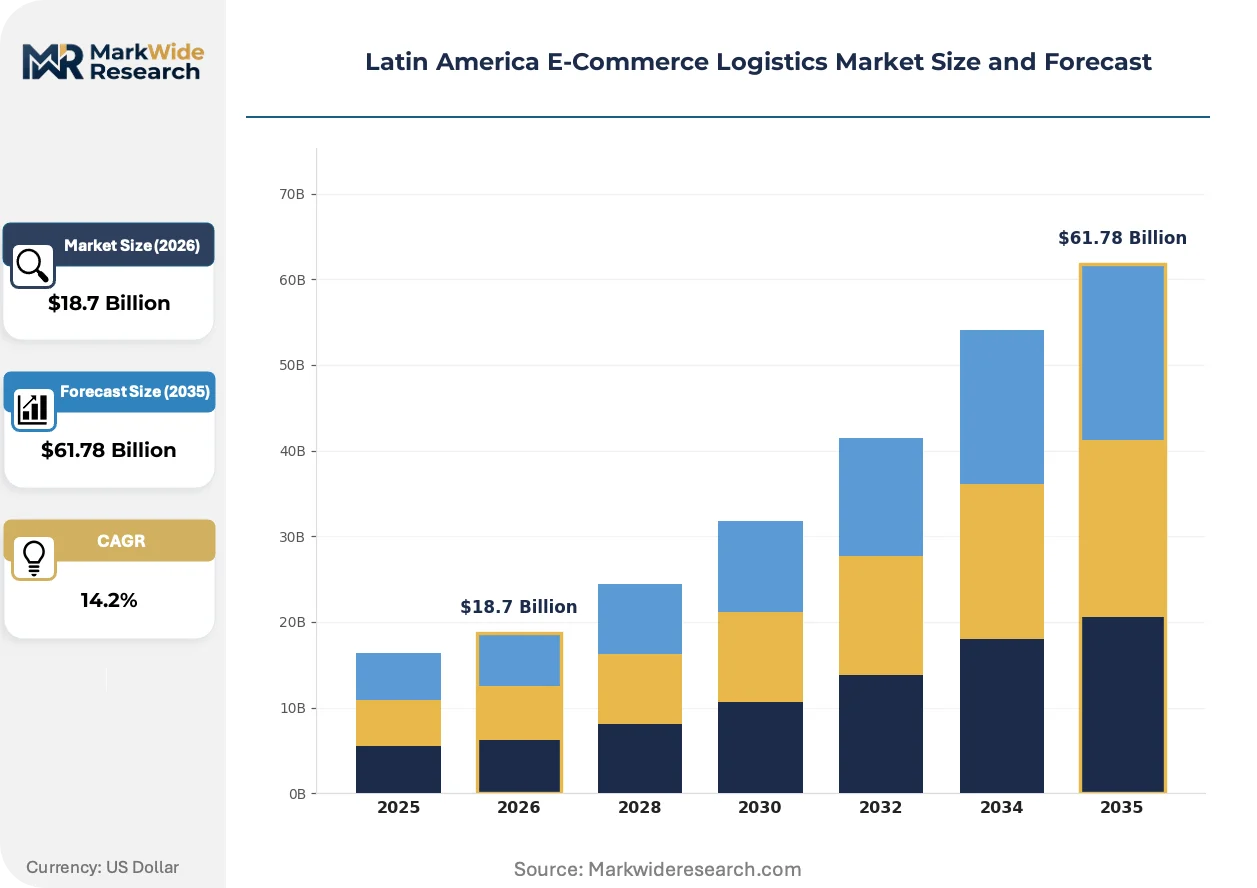
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Last Mile Delivery, Warehousing, Fulfillment Centers, Freight Transportation Customer Type: B2B, B2C, C2C, Retailers Delivery Mode: Standard Shipping, Express Delivery, Same-Day Delivery, Click & Collect Technology: Automation, AI Logistics, IoT Tracking, Cloud Solutions |
| Companies Covered | Mercado Libre, DHL Express, FedEx Corporation, UPS, Correios, DB Schenker, Kuehne + Nagel, Loggi, CEVA Logistics, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America E-Commerce Logistics Market Shifts & Advancements
Warehousing automation and AI-driven route optimization are compressing fulfillment economics while regulatory pressure on urban emissions forces fleet reconfiguration. Three developments are restructuring competitive positioning.
Automated sortation systems are integrating vision-guided robotics with dynamic batch-picking algorithms in São Paulo and Mexico City fulfillment centers. Apparel and electronics retailers are deploying these configurations to achieve 400+ units per labor hour. The technology is integrating previously siloed inbound receiving and outbound shipping workflows, collapsing facility footprint requirements by 30%.
Brazil's ANTT is tightening emissions standards for urban delivery fleets operating in metropolitan congestion zones. The regulation mandates Euro VI-equivalent engines or electric alternatives for new vehicle registrations from 2026. Last-mile carriers serving São Paulo's central business district are accelerating compressed natural gas and battery-electric pilot programs to maintain operating licenses.
Buyer expectations for delivery speed are compressing switching thresholds, with same-day availability now table stakes for electronics purchases in major metros. Marketplace platforms are displacing pure retail logistics contracts by offering integrated fulfillment-as-a-service. This shift concentrates most visibly in Mexico City, where Mercado Libre's proprietary network sets the competitive baseline for all other carriers.
Latin America E-Commerce Logistics Market Segmentation
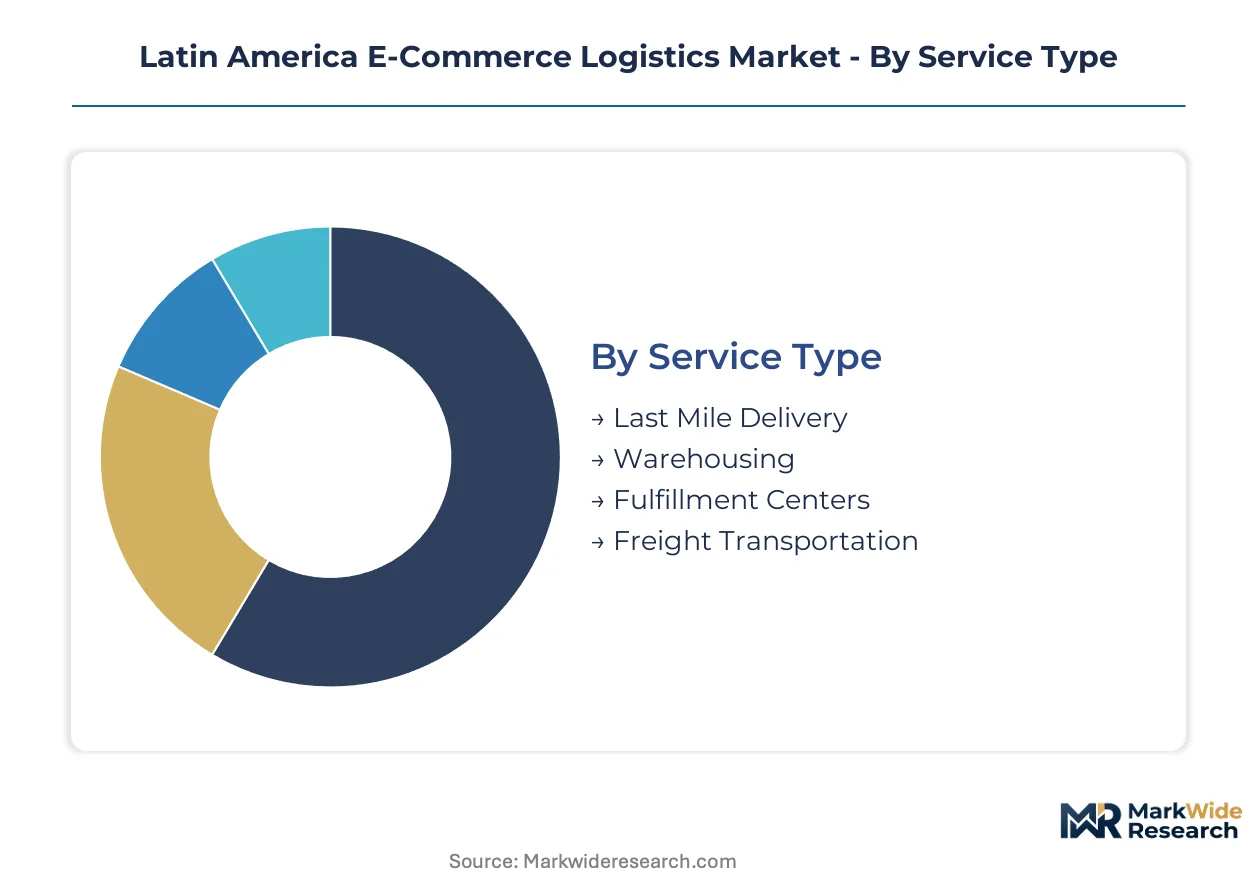
Segmentation reveals where capital deployment concentrates and which service tiers command pricing power in Latin American e-commerce logistics. Understanding these divides helps identify which infrastructure investments align with buyer willingness to pay for speed and reliability.
Service Type:
Capital intensity varies sharply across service types, with fixed-asset requirements determining competitive moats and margin structures.
- Last Mile Delivery:Dense urban routing networks require fleet assets, driver pools, and micro-fulfillment nodes positioned within 10 kilometers of demand clusters. São Paulo and Mexico City corridors absorb the majority of regional investment as carriers compete on same-day coverage density.
- Warehousing:Automated sortation systems and dynamic slotting configurations demand upfront outlays of $15-25 million per major facility. Apparel retailers with 15-day inventory turnover targets are pulling automation adoption fastest in Brazilian distribution zones.
- Fulfillment Centers:Integrated receiving, storage, and shipping operations serving marketplace platforms.
- Freight Transportation:Intercity line-haul capacity connecting coastal ports to interior consumption centers.
Most installed capacity flows through Last Mile Delivery. Expansion is steepest in Warehousing.
Customer Type:
Volume concentration and contract structures diverge significantly across buyer categories, shaping carrier sales organization design.
- Retailers:Large-format merchants with dedicated fulfillment contracts negotiate multi-year rate agreements and demand SLA-backed performance guarantees. Brazilian apparel and electronics verticals generate the densest order flows for contracted capacity.
- B2C:Individual consumers purchasing through marketplace platforms, where delivery speed expectations compress switching thresholds toward same-day availability in major metros.
- B2B:Corporate procurement channels with scheduled delivery windows and palletized freight requirements.
- C2C:Peer-to-peer parcel flows through informal selling channels with minimal service standardization.
Contract value concentrates with Retailers. Volume growth is climbing the fastest in B2C.
Delivery Mode:
Speed-tier differentiation creates distinct operational footprints and cost structures that segment carrier capabilities.
- Express Delivery:Time-definite service guarantees requiring dedicated air freight capacity and priority sortation lanes. Cross-border flows through Miami hub operations anchor this segment's economics for Andean and Southern Cone markets.
- Same-Day Delivery:Urban micro-fulfillment networks with inventory positioning inside metropolitan cores. São Paulo and Mexico City density corridors justify the capital intensity as electronics purchases now demand immediate availability.
- Standard Shipping:Deferred ground-based delivery with consolidated sortation and flexible routing.
- Click & Collect:Locker and pickup point networks reducing failed delivery attempts in addressing-challenged zones.
Premium pricing power sits with Express Delivery. Infrastructure buildout is gaining share fastest in Same-Day Delivery.
Technology:
Technology adoption separates carriers with scalable unit economics from those trapped in manual cost structures.
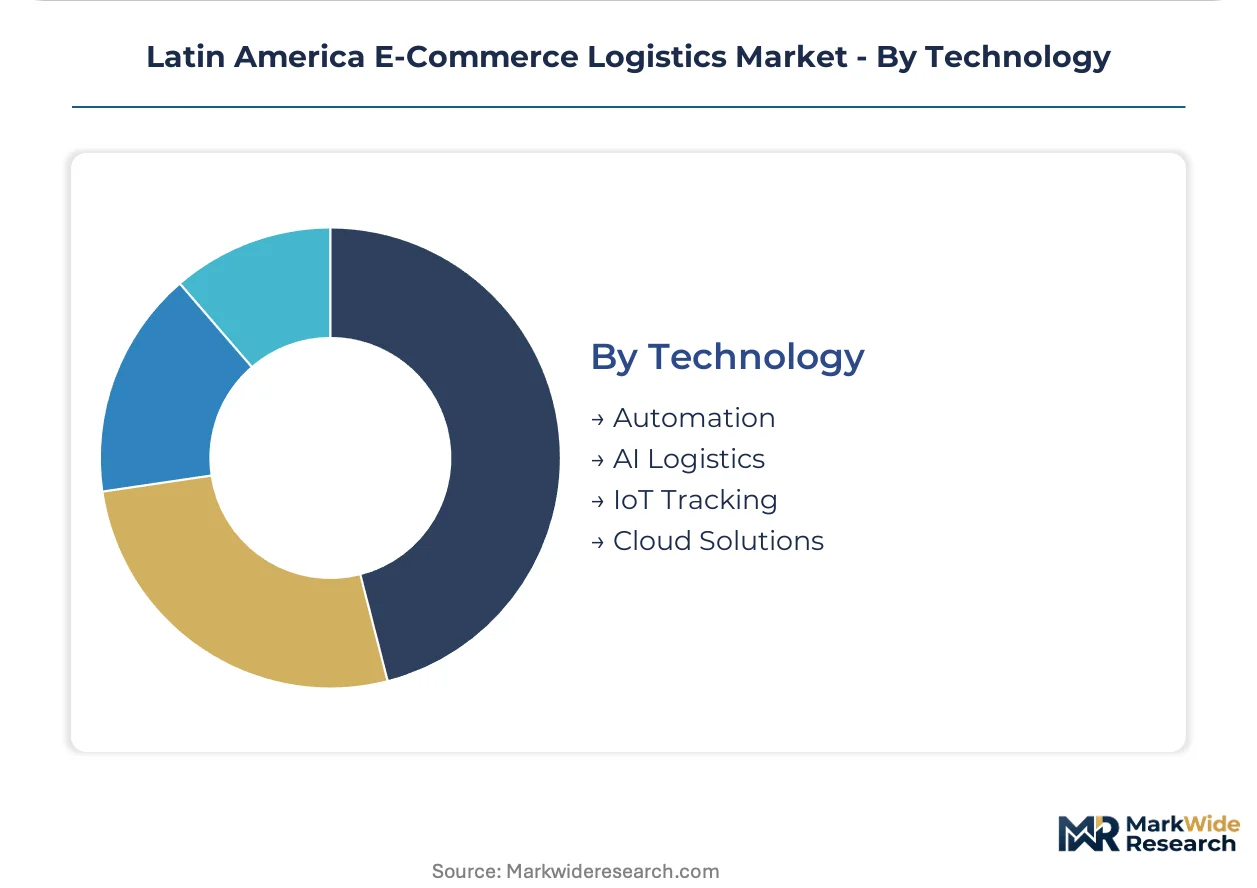
- Automation:Vision-guided robotics and dynamic batch-picking systems achieving 400+ units per labor hour in São Paulo fulfillment centers. These configurations collapse facility footprints by 30% while meeting apparel inventory velocity requirements.
- AI Logistics:Predictive demand positioning and dynamic route optimization compressing warehouse-to-door timelines from 72 hours toward same-day thresholds in Brazilian and Mexican corridors.
- IoT Tracking:Real-time parcel visibility reducing customer service inquiries and failed delivery rates.
- Cloud Solutions:API-based integration platforms connecting warehouse management to transport optimization systems.
Operational scale advantages flow through Automation. Deployment velocity is expanding most quickly in AI Logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage around customs modernization and fintech integration is redirecting fulfillment investment toward markets with compressed clearance timelines. Brazil's PIX-enabled settlement velocity and Mexico's SAT digitization programs create compliance-cost gaps that attract cross-border logistics capacity. ANTT freight deregulation further tilts intercity trucking economics toward asset-light Brazilian operators.
Brazil
PIX instant-payment adoption and ANTT's 2023 freight deregulation are collapsing settlement-to-delivery cycles for apparel and electronics retailers. São Paulo's metropolitan corridor anchors the densest micro-fulfillment network placement, with carriers positioning inventory within 10 kilometers of 60% of online buyers to meet same-day thresholds.
Mexico
SAT customs modernization and embedded credit integration at checkout are accelerating cross-border parcel flows through Laredo-Nuevo Laredo corridors. Mexico City's urban density justifies automated sortation investments as marketplace platforms set speed baselines that compress competitor margins.
Colombia
Transport ministry last-mile safety standards and unmapped addressing challenges in informal urban zones are forcing manual geocoding investments. Medellín and Cali lag São Paulo e-commerce penetration by 40 percentage points, offering first-mover density advantages for fulfillment network buildout.
Chile
Santiago's concentrated metropolitan demand and streamlined customs protocols for consumer electronics are attracting express carrier hub operations. The country's narrow geography enables efficient intercity line-haul economics that support speed-tiered service differentiation.
Argentina
Currency volatility and import restriction cycles are fragmenting fulfillment network stability, yet Buenos Aires maintains sufficient order density to justify automated warehouse configurations. Local carriers are piloting dynamic slotting systems to offset labor cost pressures in a constrained capital environment.
Latin America E-Commerce Logistics Market Competitive Landscape
Capacity expansion dominates the current landscape as carriers race to densify last-mile networks before regulatory deadlines tighten. The market exhibits tiered concentration: integrated marketplace platforms with captive fulfillment infrastructure sit atop, followed by global express integrators with Miami hub advantages, then regional specialists competing on urban same-day density. Three archetypes define competitive positioning: proprietary network operators, cross-border express specialists, and asset-light urban delivery platforms. M&A activity and fleet electrification partnerships represent the dominant competitive moves as carriers secure operating licenses under tightening emissions standards.
Among integrated marketplace platforms, Mercado Libre exemplifies the proprietary network archetype through its fulfillment-as-a-service positioning. FedEx Corporation and DHL Express anchor the cross-border express tier with Miami hub operations serving Andean and Southern Cone markets. Loggi occupies the asset-light urban specialist position, competing aggressively on same-day density in Brazilian metropolitan zones.
| Leading Market Players |
|---|
| Mercado Libre |
| DHL Express |
| FedEx Corporation |
| UPS |
| Correios |
| DB Schenker |
| Kuehne + Nagel |
| Loggi |
| CEVA Logistics |
| Others |
Supply & Pricing Matrix
Same-day delivery expectations from São Paulo and Mexico City electronics buyers are forcing carriers to position inventory within 10 kilometers of demand clusters, compressing fulfillment economics and reshaping how pricing power flows through network density tiers.
Pricing Analysis
Retailer markup layers dominate final-mile pricing as marketplace platforms extract 15-25% fulfillment commissions on consumer electronics flows. Three-tier pricing structure across premium, standard, and economy levels stratifies around delivery speed guarantees and inventory positioning depth. Price differentiation hinges on urban density coverage and automated sortation certification tiers. Pricing pressure stems from diesel cost volatility eroding last-mile margins in Brazilian metropolitan zones. B2C individual consumers exhibit highest price sensitivity, while large-format apparel retailers with multi-year contracts demonstrate lowest elasticity due to SLA-backed performance requirements.
Supply Chain Analysis
Freight cost differentials between Brazilian intercity corridors and Mexican cross-border lanes are redirecting fulfillment investment toward markets with compressed clearance timelines. Supply concentrates in Brazil, Mexico, and Colombia, with São Paulo and Mexico City anchoring automated sortation capacity. Raw material dependencies center on diesel fuel, compressed natural gas conversion kits, and battery-electric vehicle components. Single-source vulnerability runs through Miami hub operations serving Andean markets. Distribution runs through proprietary marketplace networks, cross-border express integrators, and asset-light urban specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America e-commerce logistics functions as a geographic-arbitrage play where ANTT freight deregulation in Brazil creates 20-30% operating cost advantages against Mexican carriers facing SAT customs complexity.
For Market Incumbents: To counter same-day delivery speed thresholds set by Mercado Libre's proprietary network, legacy carriers must densify micro-fulfillment placement within São Paulo's 10-kilometer coverage zones and accelerate fleet electrification to maintain ANTT operating licenses under tightening emissions standards. For New Entrants and Emerging Players: The 40-percentage-point e-commerce penetration gap between Medellín and São Paulo offers first-mover density advantages for fulfillment network buildout. Target Colombia's secondary cities with embedded credit integration at checkout, converting cash-on-digital substitution into customer acquisition in underbanked segments. For Investors and Strategic Acquirers: Asymmetric upside sits with asset-light urban delivery platforms possessing API-native technology stacks and compressed natural gas fleet conversion capabilities. Over the coming decade, acquisition focus should center on carriers with automated sortation certifications and reverse logistics monetization pilots. Watch for fintech-logistics convergence rules as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Network Densification | Positions inventory within 10 kilometers of 60% of São Paulo online buyers to meet same-day thresholds. |
| Fleet Electrification Partnership | Secures ANTT operating licenses through Euro VI-equivalent engine or battery-electric pilot programs. |
| Embedded Credit Integration | Links checkout financing with delivery confirmation to displace cash-on-digital in underbanked segments. |
| Reverse Logistics Monetization | Converts apparel returns handling from cost center to customer retention tool through instant refund-at-pickup. |
| Cross-Border Customs Automation | Accelerates SAT clearance timelines to compress settlement-to-delivery cycles for electronics flows. |
Research Methodology
Bottom-up parcel volume modeling reconciled against top-down carrier capacity tracking forms the analytical core of this study. Primary interviews with fulfillment center operations directors, last-mile fleet managers, marketplace platform logistics leads, and customs brokerage specialists combined with secondary validation from ANTT regulatory filings, SAT customs protocols, and trade flow databases. Cross-referencing of bottom-up demand signals against top-down infrastructure investment disclosures enabled triangulation of market sizing.
Historical trendline analysis of inventory turnover compression and delivery speed tier evolution informed projection frameworks across the analysis window. Segmentation dimensions modeled include service type, customer archetype, delivery mode, and technology adoption tier. CAGRs derived from elasticity modeling of PIX payment velocity and urban density corridor expansion. Forecast inputs incorporated apparel retailer 15-day turnover requirements and emissions standard compliance timelines.
Caveats apply where fuel cost volatility, currency fluctuation in Argentina, or fintech-logistics regulatory shifts could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Asia-Pacific E-Commerce Logistics Market
E-Commerce Solutions
Slovenia E-Commerce Market
E-Commerce Solutions
IT Consumer Electronics E-Commerce Market
E-Commerce Solutions
M-Commerce Market
E-Commerce Solutions
United States Same-Day Delivery Market
E-Commerce Solutions
Omnichannel Commerce Software Market
E-Commerce Solutions
Lithuania E-Commerce Market
E-Commerce Solutions
Multi-Channel E-Commerce Software Market
E-Commerce Solutions
Automotive E-Commerce Market
E-Commerce Solutions
China Ecommerce Logistics Market
E-Commerce Solutions
United Kingdom E-Commerce Logistics Market
E-Commerce Solutions
T-Commerce Market
E-Commerce Solutions
North America B2B E-Commerce Market
E-Commerce Solutions
Chile E-Commerce Market
E-Commerce Solutions
Serbia E-Commerce Market
E-Commerce Solutions
Nigeria Alcohol E-Commerce Market