
 AI Powered Software Testing Tool Market | 2026-2036
AI Powered Software Testing Tool Market Size, Share, and Industry Trends Forecast 2026-2036
AI Powered Software Testing Tool Market Insights
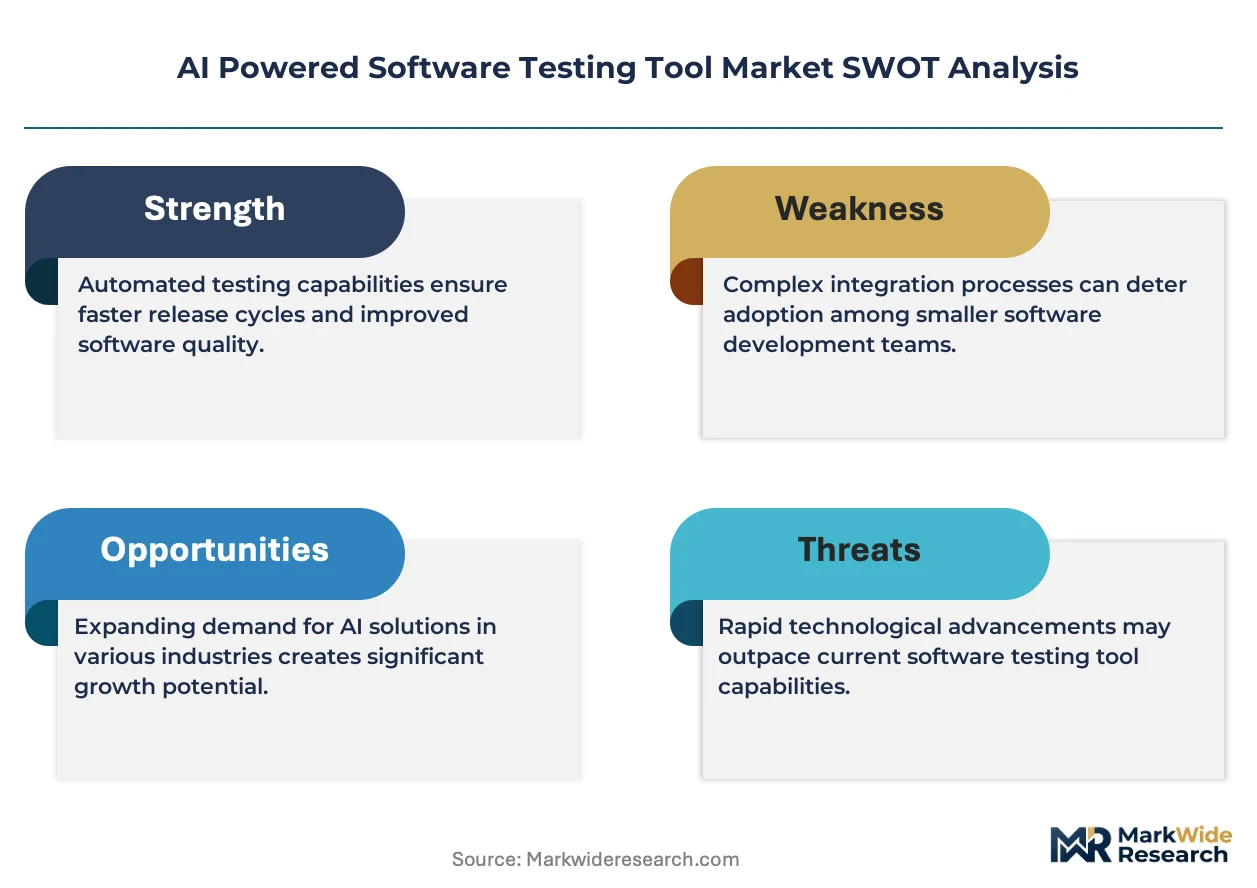
India is narrowing its talent-cost advantage as domestic AI engineering wages rise and automation commoditizes routine test scripting. Tricentis leverages its Vienna engineering base to sustain platform breadth across enterprise DevOps pipelines. SmartBear Software anchors its position through API testing specialization and channel density among mid-market software vendors.
AI powered software testing tools employ machine learning models to autonomously generate test cases, predict defect locations, and self-heal test scripts when application interfaces change, typically processing DOM structures, API payloads, and visual renderings through neural classification or reinforcement learning pipelines. These systems primarily reduce manual test maintenance burden and accelerate continuous integration feedback loops in software delivery organizations. Cloud-based deployment dominates solution type economics due to elastic compute scaling for parallel test execution, while functional testing retains the largest solution type revenue pool as organizations retrofit legacy test suites with autonomous generation capabilities. Security testing represents the fastest-expanding solution type segment as shift-left mandates embed vulnerability scanning earlier in development cycles.
FDA software validation guidelines for medical device systems, EU AI Act risk classification requirements for automated decision tools, and SEC cybersecurity disclosure rules for public software vendors collectively elevate compliance-driven demand for auditable, explainable test automation platforms. ISO/IEC 25010 quality standards and IEEE 29119 test process specifications further shape product certification requirements across regulated industries. Stakeholders must evaluate whether their current toolchains can generate the traceability documentation regulators now require for AI-assisted quality assurance workflows.
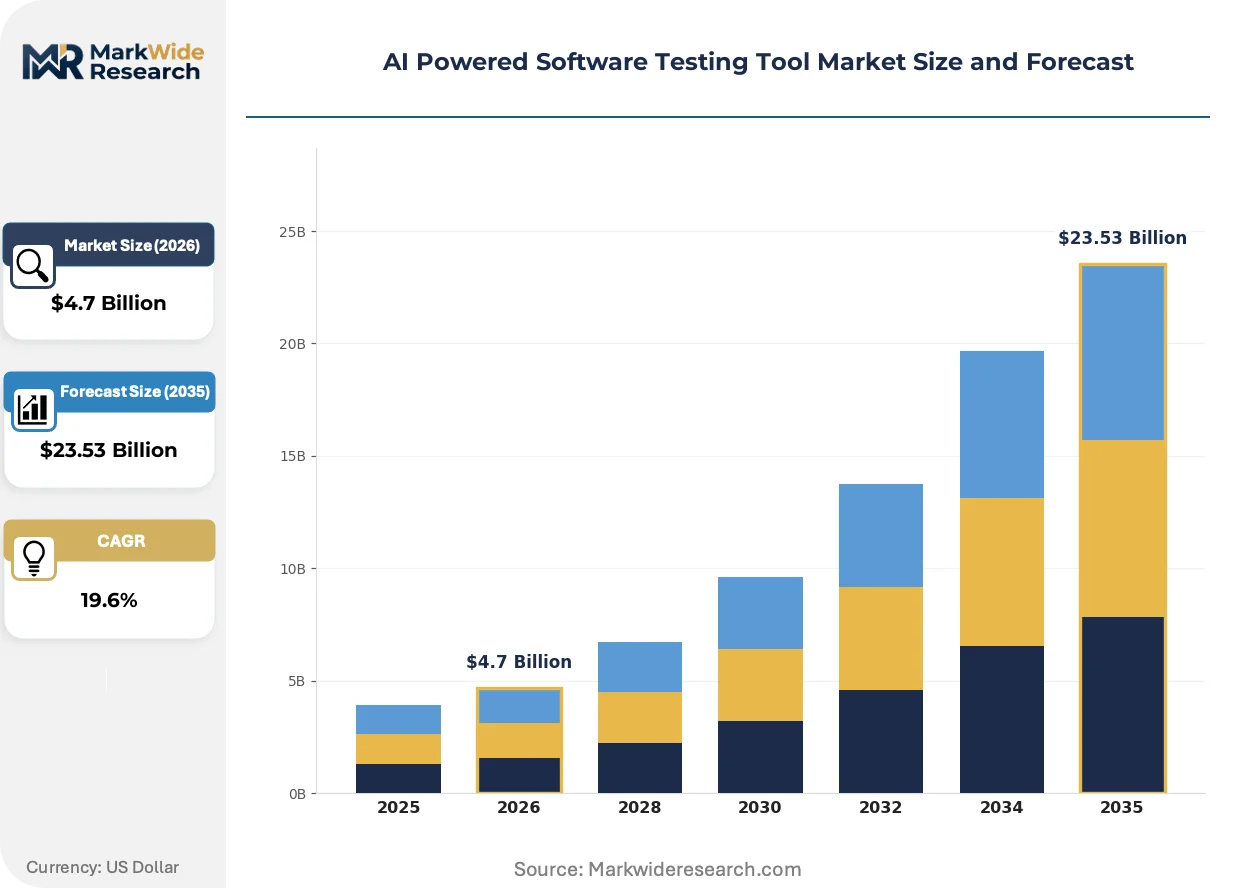
Market Dynamics
EU AI Act risk classification mandates are compressing procurement timelines for auditable test automation platforms, forcing vendors to retrofit explainability features into neural pipelines ahead of enforcement deadlines.
Growth Catalysts
- Shift-left security mandates:SEC cybersecurity disclosure rules for public software vendors embed vulnerability scanning earlier in development cycles, expanding demand for autonomous security test generation.
- India:Domestic AI engineering talent pools support offshore test automation delivery for North American and European financial services firms seeking 24-hour development cycles.
- Reinforcement learning pipelines:Self-healing test scripts reduce maintenance burden for continuous integration environments, accelerating enterprise DevOps adoption.
Market Restraints
- GPU compute cost volatility:Elastic cloud scaling for parallel test execution exposes buyers to fluctuating infrastructure costs, particularly for visual rendering and neural classification workloads.
- Vendor concentration in Silicon Valley:Platform engineering talent clusters in San Francisco Bay Area and Seattle metro corridors, creating geographic supply risk for enterprise procurement teams.
- EU AI Act compliance friction:High-risk system documentation requirements delay vendor certification timelines, particularly for medical device test automation under FDA software validation guidelines.
Strategic Opportunities
- Mid-market software vendors:API testing specialization addresses underserved segments between enterprise DevOps pipelines and open-source alternatives, creating channel density opportunities.
- ISO/IEC 25010 certification:Quality standard compliance opens regulated industry procurement processes in healthcare, automotive, and financial services verticals.
- Neural classification and computer vision convergence:Visual rendering analysis combined with DOM structure processing enables cross-platform mobile application testing at reduced script maintenance cost.
Industry Challenges
- Test automation engineer scarcity:Machine learning operations and neural pipeline tuning skills command premium wages in Vienna, Berlin, and Bangalore engineering markets.
- Legacy test suite migration complexity:Retrofitting existing Selenium-based frameworks with autonomous generation capabilities requires substantial script refactoring and validation effort.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Powered Software Testing Tool Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $23.53 Billion |
| CAGR (2026 – 2036) | 19.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS, Private Cloud Solution Type: Functional Testing, Performance Testing, Security Testing, Regression Testing, Usability Testing Application: Web Applications, Mobile Applications, Enterprise Applications, Embedded Systems, API Testing End User Industry: IT Services, Telecommunications, Banking, Insurance, E-Commerce |
| Companies Covered | Tricentis, SmartBear Software, Keysight Technologies, Sauce Labs, BrowserStack, Applitools, LambdaTest, mabl, Functionize, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Powered Software Testing Tool Market Trends and Innovations
Neural test generation architectures are converging with explainability frameworks to satisfy algorithmic accountability requirements across multiple regulatory jurisdictions.
Reinforcement learning-based test case generation is hybridizing with symbolic execution methods to improve coverage metrics for complex conditional logic in financial trading systems. Large European banks deploy these hybrid architectures to satisfy internal model risk management standards while compressing regression test cycles. The approach enables autonomous exploration of edge cases that pure neural methods miss, reducing manual test design effort by capturing explicit path constraints.
EU AI Act automated decision system classifications extend to quality assurance tools used in medical device software validation, triggering documentation requirements for test generation algorithms. FDA software validation guidelines for SaMD (Software as a Medical Device) increasingly reference ISO/IEC 25010 quality characteristics, creating harmonized compliance burdens across Atlantic markets. Medical device manufacturers in Germany and Switzerland accelerate procurement of auditable test platforms to preempt regulatory scrutiny.
Enterprise buyers now unbundle test automation procurement from broader DevOps platform commitments, favoring specialized vendors for security and API testing functions. Mid-market software vendors in New York financial technology corridors lead this fragmentation, selecting best-of-breed tools over integrated suites. The pattern concentrates in organizations with mature continuous integration practices that can orchestrate heterogeneous toolchains without vendor lock-in.
AI Powered Software Testing Tool Market Segmentation
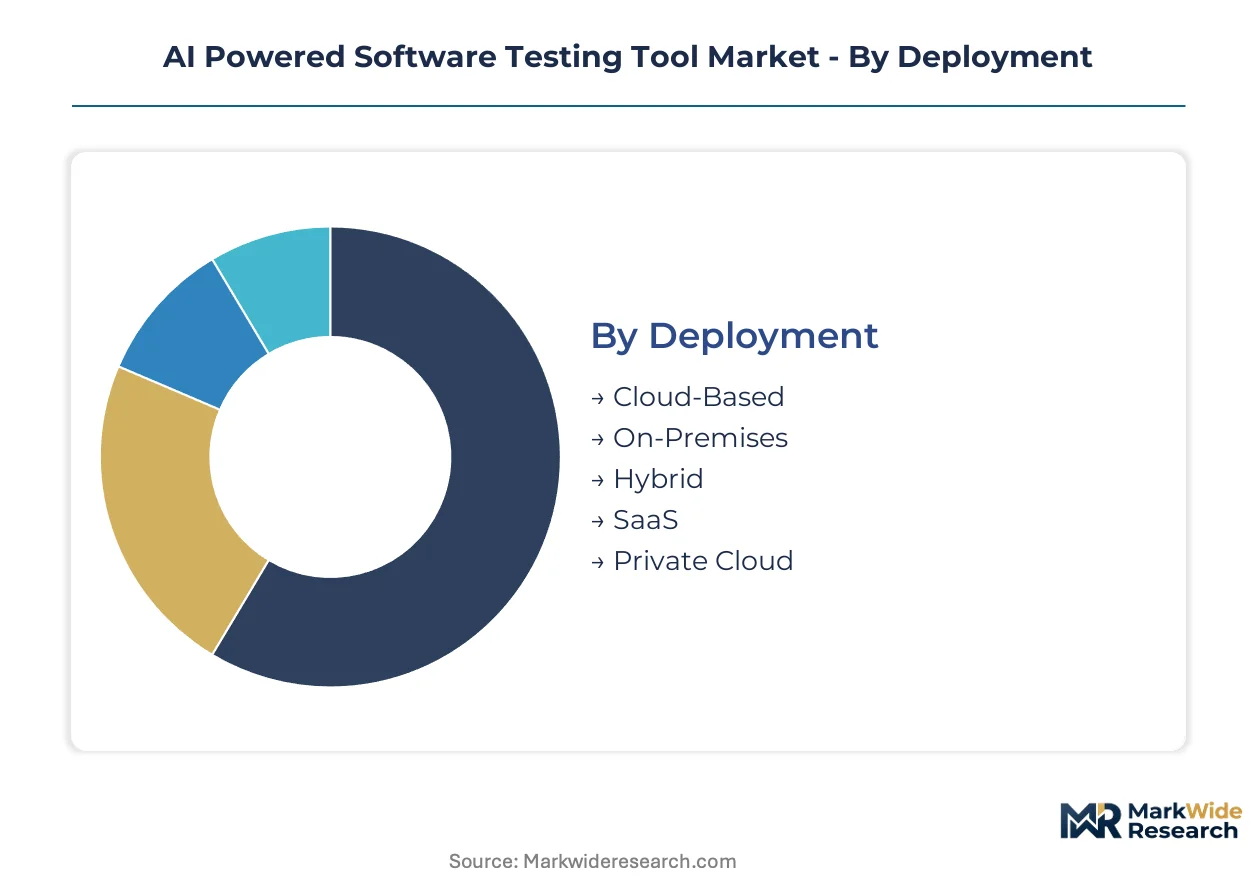
Segmentation reveals how AI testing tools align with distinct operational constraints across deployment architectures, solution types, and industry verticals. Procurement patterns diverge sharply between regulated financial services and agile software vendors, forcing vendors to modularize platform capabilities.
Deployment:
Mature cloud configurations dominate transaction volume, while emerging hybrid architectures address sovereignty-sensitive workloads.
- Cloud-Based:Elastic compute scaling supports parallel test execution for continuous integration pipelines. Demand concentrates among Silicon Valley enterprise software clusters seeking rapid provisioning without capital expenditure.
- SaaS:Subscription delivery models reduce procurement friction for mid-market vendors with limited DevOps engineering resources. New York financial technology corridors favor this model for rapid vendor switching capability.
- On-Premises:Air-gapped installations serve defense contractors and classified government systems with strict data residency mandates.
- Hybrid:Split architectures allow sensitive test data to remain on-premises while leveraging cloud burst capacity for peak regression cycles.
- Private Cloud:Dedicated infrastructure deployments satisfy EU AI Act data localization requirements for high-risk automated decision systems.
Cloud-Based handles the majority of throughput; Security Testing is the fastest mover on share.
Solution Type:
Cost tier stratification separates commodity functional testing from premium security and performance capabilities.
- Functional Testing:Autonomous test case generation from DOM structures and API specifications. Banking sector procurement in London and Frankfurt drives retrofit demand for legacy Selenium frameworks.
- Security Testing:Neural classification of vulnerability patterns embedded within shift-left development cycles. SEC cybersecurity disclosure rules accelerate adoption among publicly traded software vendors.
- Performance Testing:Load simulation and latency profiling for high-frequency trading platforms and streaming media applications.
- Regression Testing:Self-healing scripts reduce maintenance burden for enterprise applications with frequent UI updates.
- Usability Testing:Computer vision analysis of visual renderings combined with behavioral interaction tracking.
Functional Testing retains the largest revenue pool; Security Testing is expanding most quickly.
Application:
Customer type differentiation separates enterprise legacy modernization from native mobile and API-first development.
- Web Applications:Cross-browser compatibility testing through visual rendering comparison and DOM structure validation. E-Commerce platforms in Berlin and Amsterdam prioritize checkout flow automation.
- API Testing:Contract validation and payload fuzzing for microservices architectures. SmartBear Software anchors market position through channel density among mid-market software vendors.
- Mobile Applications:Cross-platform testing across iOS and Android with device farm integration for fragmentation coverage.
- Enterprise Applications:SAP and Oracle module testing with specialized handling for complex business logic workflows.
- Embedded Systems:Hardware-in-the-loop validation for automotive ECUs and medical device firmware under FDA software validation guidelines.
Web Applications processes the highest test volume; API Testing is climbing the fastest.
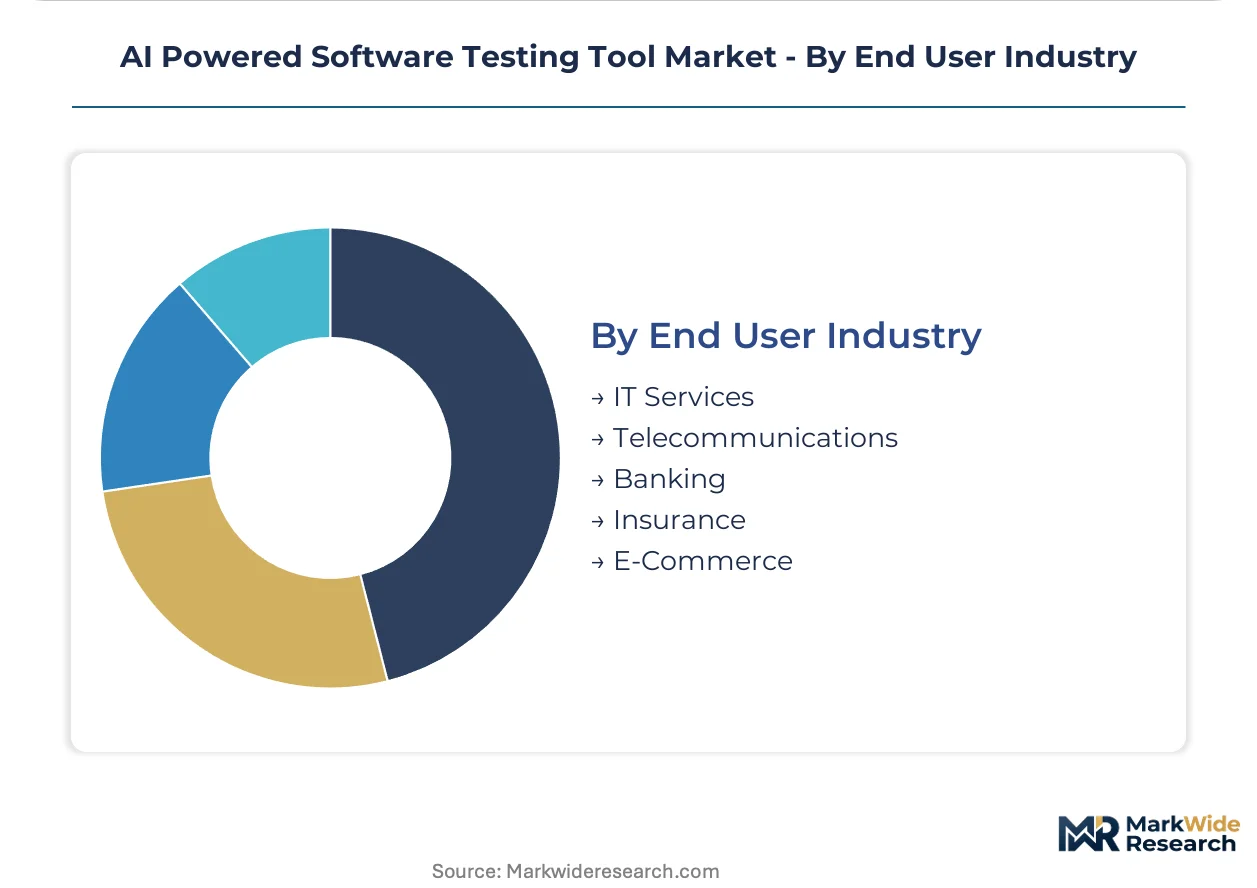
End User Industry:
Margin structure varies dramatically between regulated financial services and commoditized IT outsourcing.
- Banking:Autonomous test generation for digital banking applications with strict audit trail requirements. EU AI Act compliance friction extends procurement timelines for algorithmic accountability documentation.
- Insurance:Legacy policy administration system modernization with self-healing scripts for COBOL-to-cloud migrations.
- IT Services:Offshore delivery models leverage Bangalore and Hyderabad engineering pools for 24-hour test cycles.
- Telecommunications:5G network function virtualization testing with massive scale simulation requirements.
- E-Commerce:Rapid release cycle compression through parallel execution across global fulfillment platform updates.
Banking commands premium pricing; E-Commerce is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform engineering talent clusters disproportionately in the San Francisco Bay Area and Seattle metro corridors, creating geographic supply risk for enterprise procurement teams seeking alternative sourcing. Demand patterns diverge sharply between regulated financial services hubs and agile software development clusters.
United States
SEC cybersecurity disclosure rules for public software vendors accelerate autonomous security test generation procurement in New York financial technology corridors. Silicon Valley enterprise software clusters dominate cloud-based deployment adoption for elastic compute scaling. FDA software validation guidelines for medical device systems elevate compliance-driven demand in Boston and Minneapolis healthcare technology hubs.
Germany
EU AI Act risk classification mandates compress procurement timelines for auditable test automation platforms across Frankfurt banking centers. Large European banks deploy hybrid reinforcement learning architectures to satisfy internal model risk management standards. Medical device manufacturers in Munich and Stuttgart accelerate procurement of auditable test platforms to preempt regulatory scrutiny under harmonized Atlantic compliance frameworks.
India
Domestic AI engineering talent pools in Bangalore and Hyderabad support offshore test automation delivery for North American financial services firms seeking 24-hour development cycles. Rising domestic AI engineering wages narrow the historical talent-cost advantage as automation commoditizes routine test scripting. IT services exporters in Chennai and Pune retrofit legacy Selenium frameworks with autonomous generation capabilities for European banking clients.
United Kingdom
London banking sector procurement drives retrofit demand for legacy test frameworks with autonomous generation capabilities. Lloyd's of London insurance technology modernization programs deploy self-healing scripts for COBOL-to-cloud policy administration migrations. Fintech clusters in Manchester and Edinburgh favor SaaS delivery models for rapid vendor switching capability without long-term platform commitments.
Japan
METI industrial digitization programs embed AI-assisted quality assurance into automotive and electronics manufacturing supply chains. Tokyo-based enterprise software vendors prioritize API testing specialization for microservices architectures serving domestic industrial conglomerates. Osaka and Nagoya engineering centers concentrate performance testing expertise for high-frequency trading platform simulation requirements.
AI Powered Software Testing Tool Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in functional niches. The vendor base separates between consolidated enterprise DevOps pipeline providers and fragmented best-of-breed tool vendors. Three archetypes dominate: Vienna-based platform breadth sustainers, API testing channel density builders, and visual rendering computer vision convergers. Competitive moves concentrate on strategic partnerships for heterogeneous toolchain orchestration and geographic expansion into mid-market software vendor segments.
Among the named players, Tricentis exemplifies the platform breadth archetype through its Vienna engineering base sustaining cross-pipeline capabilities. SmartBear Software occupies a position representing API testing specialization and channel density concentration among mid-market software vendors. Applitools and LambdaTest sit within the visual rendering and cross-platform mobile testing convergence tier, anchoring computer vision-based approaches to reduced script maintenance.
| Leading Market Players |
|---|
| Tricentis |
| SmartBear Software |
| Keysight Technologies |
| Sauce Labs |
| BrowserStack |
| Applitools |
| LambdaTest |
| mabl |
| Functionize |
| Others |
Pricing and Supply Chain Analysis
GPU undercapacity in cloud compute regions is forcing testing tool vendors toward hybrid deployment architectures that split price-sensitive workloads between reserved on-premises capacity and burst cloud scaling, compressing margins on pure-SaaS offerings while inflating premiums for sovereign-cloud alternatives.
Pricing Analysis
EU AI Act compliance documentation dictates the pricing tier structure across the AI powered software testing tool market, separating premium-certified platforms with full audit trails from standard-tier offerings lacking explainability features. Three-tier pricing structure across premium, standard, and economy levels reflects ISO/IEC 25010 certification status, with FDA-validated medical device tiers commanding substantial premiums over uncertified alternatives. Cost compression in the standard tier is intensifying because GPU compute volatility exposes buyers to elastic infrastructure pricing, while mid-market software vendors exhibit the highest price sensitivity due to limited DevOps engineering budgets.
Supply Chain Analysis
Neural training infrastructure and specialized AI engineering talent feed the upstream cost structure of AI powered software testing platforms. Taiwan and South Korea supply advanced GPU silicon, while India and Germany provide pipeline engineering expertise for test generation algorithms. Single-source vulnerability concentrates in NVIDIA's dominance of training-grade accelerators, with distribution running through hyperscaler marketplaces and direct enterprise sales channels serving regulated financial services and healthcare verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in mid-market API testing niches as enterprise buyers unbundle procurement from integrated DevOps suites, creating white-space for specialized vendors between open-source alternatives and platform breadth providers.
For Market Incumbents: Entrench platform position through backward integration into explainability frameworks that satisfy EU AI Act documentation requirements ahead of enforcement deadlines, while adding Vienna and Berlin engineering capacity to defend against talent scarcity in neural pipeline tuning. Channel control through strategic partnerships with hyperscaler marketplaces represents the critical defensive lever against emerging visual rendering specialists. For New Entrants and Emerging Players: Japanese industrial digitization programs represent the most penetrable geographic underpenetration, with METI-funded automotive and electronics supply chains seeking AI-assisted quality assurance without incumbent platform lock-in. Target Osaka and Nagoya engineering centers with computer vision-based mobile testing specialization, leveraging device farm partnerships as the primary go-to-market angle against established cross-platform vendors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among API testing specialists with channel density among mid-market software vendors, indicating superior long-term viability through the projection horizon. Acquisition targets should exhibit ISO/IEC 25010 certification progress and existing penetration of New York fintech corridors. The signal to watch is SEC cybersecurity disclosure rule enforcement intensity, which accelerates autonomous security test generation procurement among publicly traded software vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Explainability framework embedding satisfies EU AI Act risk classification mandates for high-risk automated decision systems. |
| Strategic Partnership | Hyperscaler marketplace distribution expands reach into Silicon Valley enterprise software clusters seeking rapid provisioning. |
| Acquisition of Specialist Firm | Computer vision capabilities from visual rendering vendors compress cross-platform mobile testing script maintenance costs. |
| Geographic Expansion | Vienna and Berlin engineering bases sustain neural pipeline breadth against Bangalore wage inflation. |
| Product Launch | Self-healing script architectures reduce maintenance burden for continuous integration environments in financial services. |
Research Methodology
Desk research of SEC cybersecurity disclosure filings, FDA software validation guidelines, and EU AI Act regulatory texts preceded structured interviews with CTOs, DevOps platform engineers, IT procurement officers, and channel integration specialists across financial services and healthcare verticals. Secondary validation drew from hyperscaler capex disclosures, ISO/IEC standards documentation, and IEEE test process specifications. Bottom-up segment sizing triangulated against top-down market construction across deployment models, solution types, and end-user industries.
Assumptions held regulatory enforcement timelines and GPU compute cost volatility within observed patterns while varying enterprise DevOps maturity and mid-market unbundling propensity. The analytical framework modeled deployment architecture, organization size, vertical regulatory intensity, integration complexity, and regional adoption pattern across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with aggregate market expansion, incorporating neural classification adoption curves and shift-left security mandate penetration as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by visual rendering specialists or hyperscaler-native testing platforms would shift outcomes beyond modeled ranges. Cross-checking against FDA software validation guideline updates and EU AI Act implementing act releases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Public Financial Management Software Market
Software & Services
Ecommerce Inventory Management Software Market
Software & Services
Global Proposal Management Software Market
Software & Services
Staffing Agency Software Market
Software & Services
Multiphysics Software Market
Software & Services
US Content Services Platform Market
Software & Services
Enterprise Software Market
Software & Services
North America Deck Design Software Market
Software & Services
Global Coworking Space Management Software Market
Software & Services
Structured Data Management Software Market
Software & Services
Lead-To-Account Matching and Routing Software Market
Software & Services
Telecom Billing Software Market
Software & Services
France HR Payroll Software Market
Software & Services
Laboratory Management Software Market
Software & Services
Stone Analysis Software Market
Software & Services
Global Travel and Expense Management Software Market