
 Credit Management Software Market | 2026-2036
Credit Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Credit Management Software Market Analysis
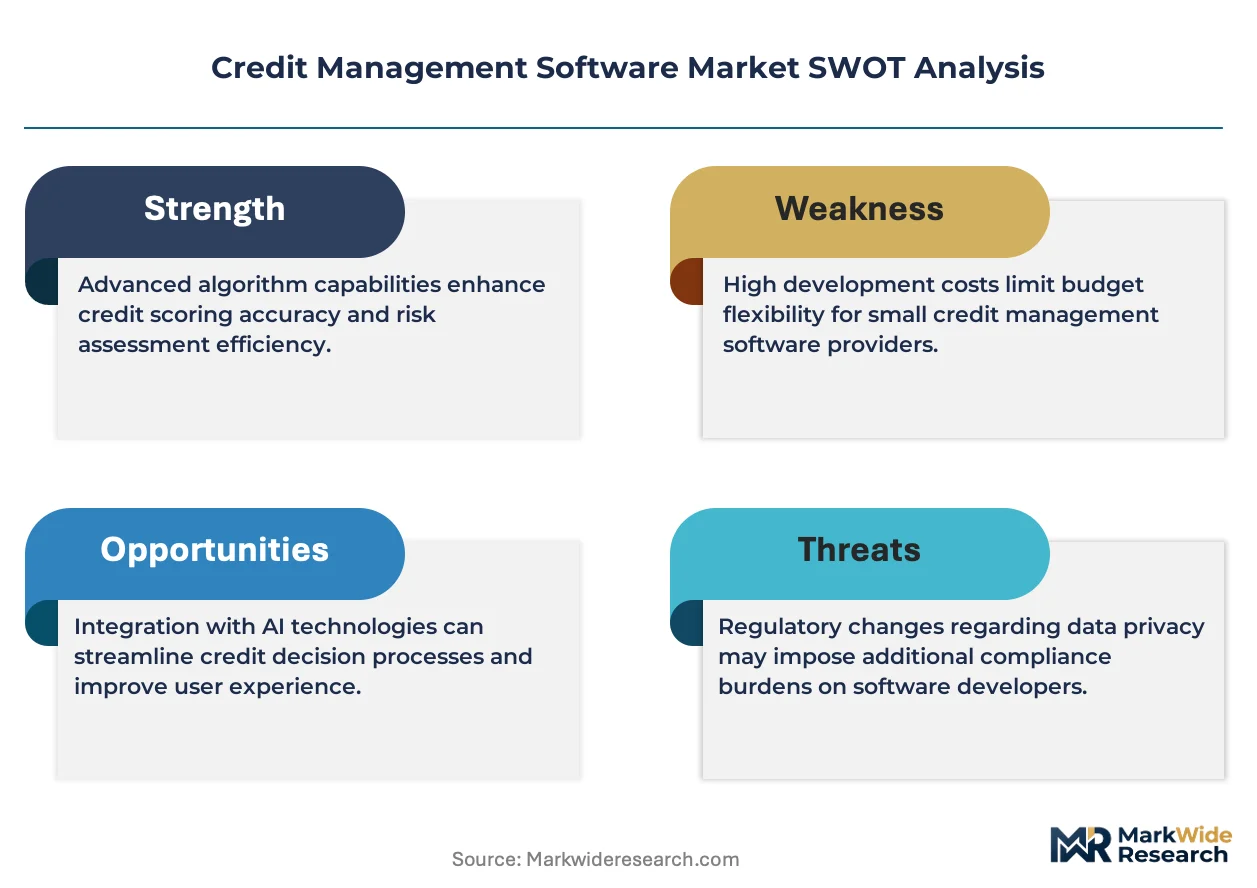
Project finance for software-as-a-service receivables platforms is narrowing the competitive field to vendors with balance-sheet capacity or banking partnerships. HighRadius leverages its treasury management heritage to anchor enterprise-grade working capital solutions. ACTICO sustains dominance in rules-based decisioning for European cooperative banks. Experian competes through embedded credit data layers that extend traditional bureau scoring into real-time monitoring.
Credit management software orchestrates the automated evaluation, tracking, and collection of trade receivables through configurable workflows integrating ERP ledgers, payment gateways, and risk scoring engines. The technology employs machine learning models trained on historical repayment patterns to flag delinquency probability before invoice due dates, primarily serving CFO offices and credit departments seeking to reduce days sales outstanding while minimizing bad-debt provisions. Cloud-based deployment captures the fastest expansion as financial institutions retire mainframe installations, though on-premises solutions still occupy regulated jurisdictions with data sovereignty constraints. Invoice management and risk assessment solutions concentrate the deepest margin pools because they require continuous regulatory recalibration and proprietary data feeds that resist commoditization.
FDA oversight of software-as-medical-device credit tools used in healthcare patient financing shapes validation requirements for algorithmic risk models in the United States. The EU AI Act's prohibited-practice list and conformity assessment obligations for credit-scoring automation force vendors serving European financial institutions to maintain auditable decision trails. GDPR data-retention limits complicate longitudinal default prediction datasets across EU member states. Stakeholders must monitor whether central bank digital currency settlement rails will displace traditional payment processing integrations in credit workflows.
Market Dynamics
Cloud migration among mid-market banks is compressing deployment cycles from eighteen months to under ninety days, forcing vendors to re-architect onboarding workflows around API-first integration rather than custom implementation.
Growth Catalysts
- EU AI Act Conformity Obligations:Automated credit-scoring systems in European financial institutions now require auditable decision trails, creating mandatory upgrade cycles for legacy platforms.
- Sparkassen-Finanzgruppe Modernization:Germany's cooperative banking sector is retiring mainframe credit infrastructure, generating concentrated demand for cloud-native replacement systems.
- Machine Learning Delinquency Prediction:Pre-due-date risk flagging trained on historical repayment patterns is reducing days sales outstanding for CFO offices managing trade receivables.
Market Restraints
- Data Sovereignty Constraints:On-premises solutions retain dominance in jurisdictions with strict cross-border data transfer prohibitions, fragmenting vendor addressable market.
- GDPR Retention Limits:Longitudinal default prediction datasets face truncation across EU member states, degrading model accuracy for pan-European credit portfolios.
- Mainframe Legacy Entrenchment:Regulated banks in Switzerland and Austria maintain COBOL-based credit cores, extending replacement timelines and diluting near-term revenue visibility.
Strategic Opportunities
- Central Bank Digital Currency Settlement Rails:Pilot programs in Frankfurt and Paris are testing programmable payment triggers that could displace traditional gateway integrations.
- Healthcare Patient Financing:FDA validation pathways for software-as-medical-device credit tools create a regulated entry point into US hospital revenue cycle management.
- Explainable Scoring Modules:Vendors embedding interpretable AI layers capture premium positioning as EU supervisors intensify scrutiny of black-box lending algorithms.
Industry Challenges
- API Integration Complexity:ERP ledger synchronization across SAP, Oracle, and Microsoft Dynamics environments consumes implementation resources and extends customer time-to-value.
- Model Governance Talent Scarcity:Credit departments lack personnel capable of validating machine learning outputs against regulatory fairness standards, creating adoption bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Credit Management Software Market |
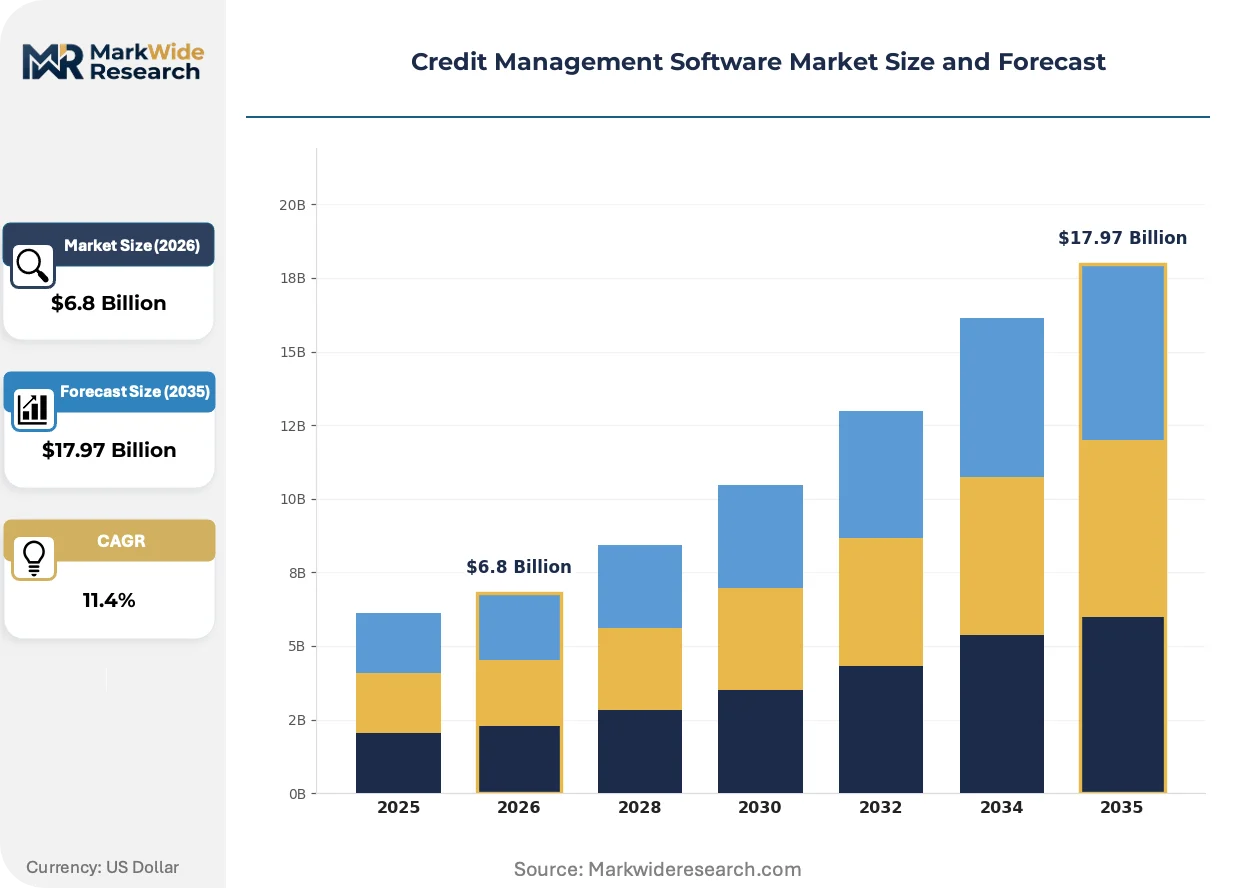
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services End User: SMEs, Large Enterprises, Financial Institutions, Collection Agencies Solution: Invoice Management, Risk Assessment, Payment Processing, Reporting Tools Integration Level: API Integration, Third-Party Integrations, Custom Integrations, Standalone Solutions |
| Companies Covered | Pega, ACTICO, HighRadius, Resolve Pay, HES FinTech, Gaviti, Experian, Daylit, Esker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Credit Management Software Market Emerging Trajectories
Real-time data orchestration is collapsing the latency between invoice generation and risk assessment, compressing the traditional batch-processing paradigm into continuous monitoring architectures.
Embedded credit data layers are rendering obsolete the quarterly bureau pull model that dominated commercial underwriting for three decades. Mid-market manufacturers adopting API-connected scoring engines now refresh risk profiles daily rather than at renewal. This velocity is compressing bad-debt provision volatility and shifting competitive advantage toward platforms with proprietary payment-gateway data feeds.
The EU AI Act's prohibited-practice list and high-risk system classification are mandating conformity assessments for automated credit decisions across European member states. Vendors must now maintain technical documentation, human oversight protocols, and post-market monitoring systems that mirror medical device quality management. German Sparkassen and French mutual banks are prioritizing vendors with existing CE-marking competencies in adjacent financial software categories.
Subscription pricing for credit management capabilities is displacing perpetual license models among CFO offices seeking to align software costs with receivables volume. Annual recurring revenue structures now dominate new bookings in the United Kingdom and Nordic markets, compressing upfront implementation fees into spread recognition over contract terms. This shift favors vendors with balance-sheet capacity to absorb elongated cash conversion cycles.
Credit Management Software Market Segmentation
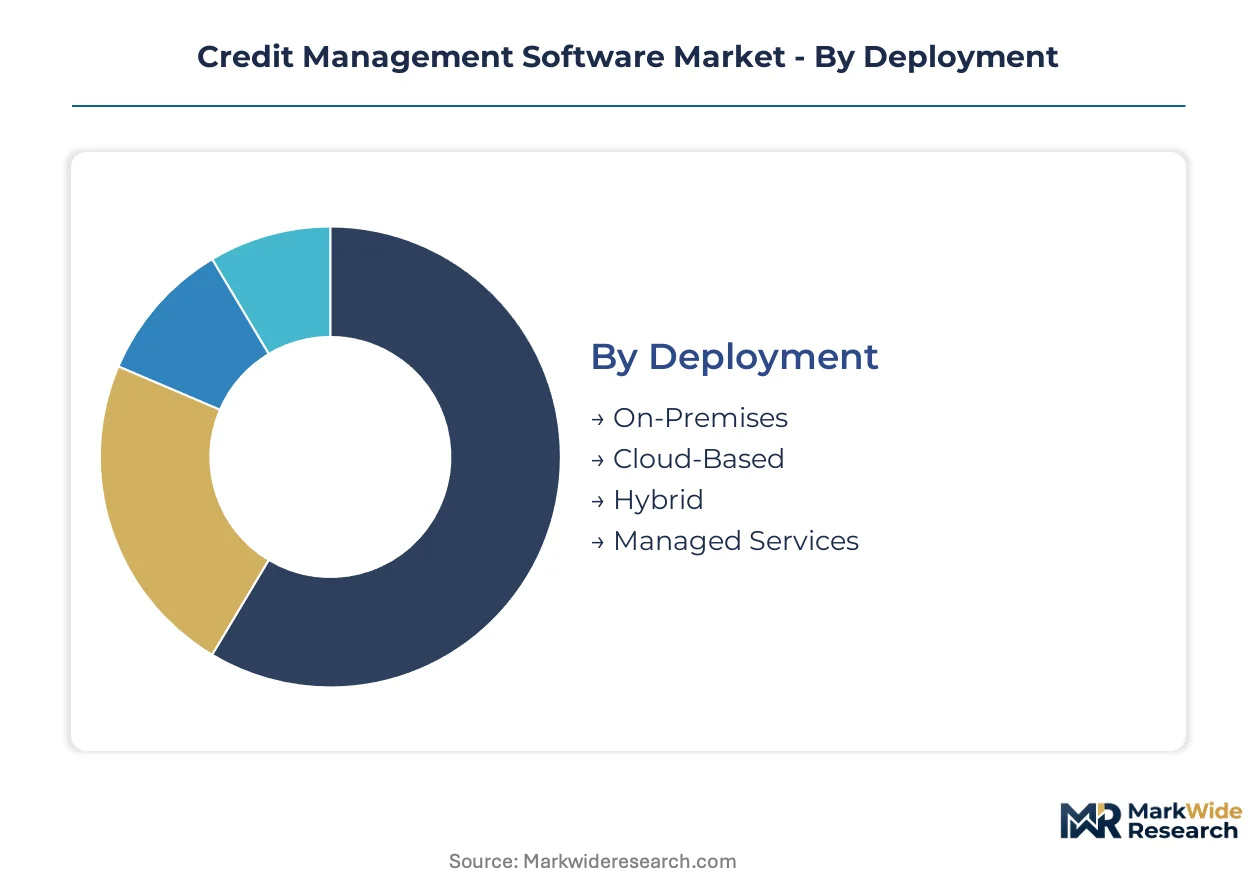
Credit management software vendors architect go-to-market strategies around deployment economics, buyer sophistication, and integration complexity. Segment boundaries determine pricing architecture, sales cycle length, and R&D allocation across the product lifecycle.
Deployment:
Mature on-premises installations coexist with emerging cloud-native architectures across regulated and unregulated jurisdictions respectively.
- Cloud-Based:Multi-tenant SaaS architectures with elastic compute scaling serve CFO offices seeking ninety-day deployment cycles. German Sparkassen and French mutual banks drive concentrated demand as EU AI Act conformity obligations force legacy system replacement.
- On-Premises:Single-tenant installations with localized data residency satisfy Swiss and Austrian banking regulators. COBOL-core entrenchment extends replacement timelines while preserving maintenance revenue streams for incumbent vendors.
- Hybrid:Split architectures route sensitive scoring workloads on-premises while pushing reporting to cloud tiers. German cooperative banks pilot these configurations during phased mainframe migrations.
- Managed Services:Vendor-operated private cloud deployments absorb operational burden for mid-market manufacturers lacking IT security personnel. Subscription pricing aligns costs with receivables volume fluctuations.
On-Premises retains volume leadership; Cloud-Based holds the steepest expansion curve.
End User:
Customer type segmentation maps directly to contract value distribution and solution complexity requirements.
- Financial Institutions:Universal banks and cooperative networks require real-time risk scoring with auditable decision trails. EU AI Act high-risk system classifications mandate conformity assessments that elevate procurement scrutiny.
- Large Enterprises:Multinational manufacturers with SAP-Oracle ERP heterogeneity demand API-first integration architectures. Daily risk profile refresh rates replace quarterly bureau pulls.
- SMEs:Mid-market CFO offices prioritize subscription pricing over perpetual licenses. Annual recurring revenue structures now dominate UK and Nordic bookings.
- Collection Agencies:Specialized recovery firms consume workflow automation with compliance logging. GDPR retention limits constrain longitudinal default prediction dataset construction.
Financial Institutions command the highest contract values; SMEs are expanding most quickly.
Solution:
Functional modules differentiate by margin durability and regulatory recalibration frequency.
- Risk Assessment:Machine learning models trained on historical repayment patterns flag delinquency probability before invoice due dates. Continuous regulatory recalibration and proprietary data feeds resist commoditization.
- Invoice Management:Automated receivables tracking with ERP ledger synchronization reduces days sales outstanding. API complexity across SAP, Oracle, and Microsoft Dynamics environments extends implementation timelines.
- Payment Processing:Gateway integrations with programmable settlement triggers face potential displacement from central bank digital currency pilots in Frankfurt and Paris.
- Reporting Tools:Dashboard visualization with drill-down audit trails satisfies EU supervisor scrutiny of black-box lending algorithms.
Risk Assessment captures premium pricing; Invoice Management holds the broadest installed base.
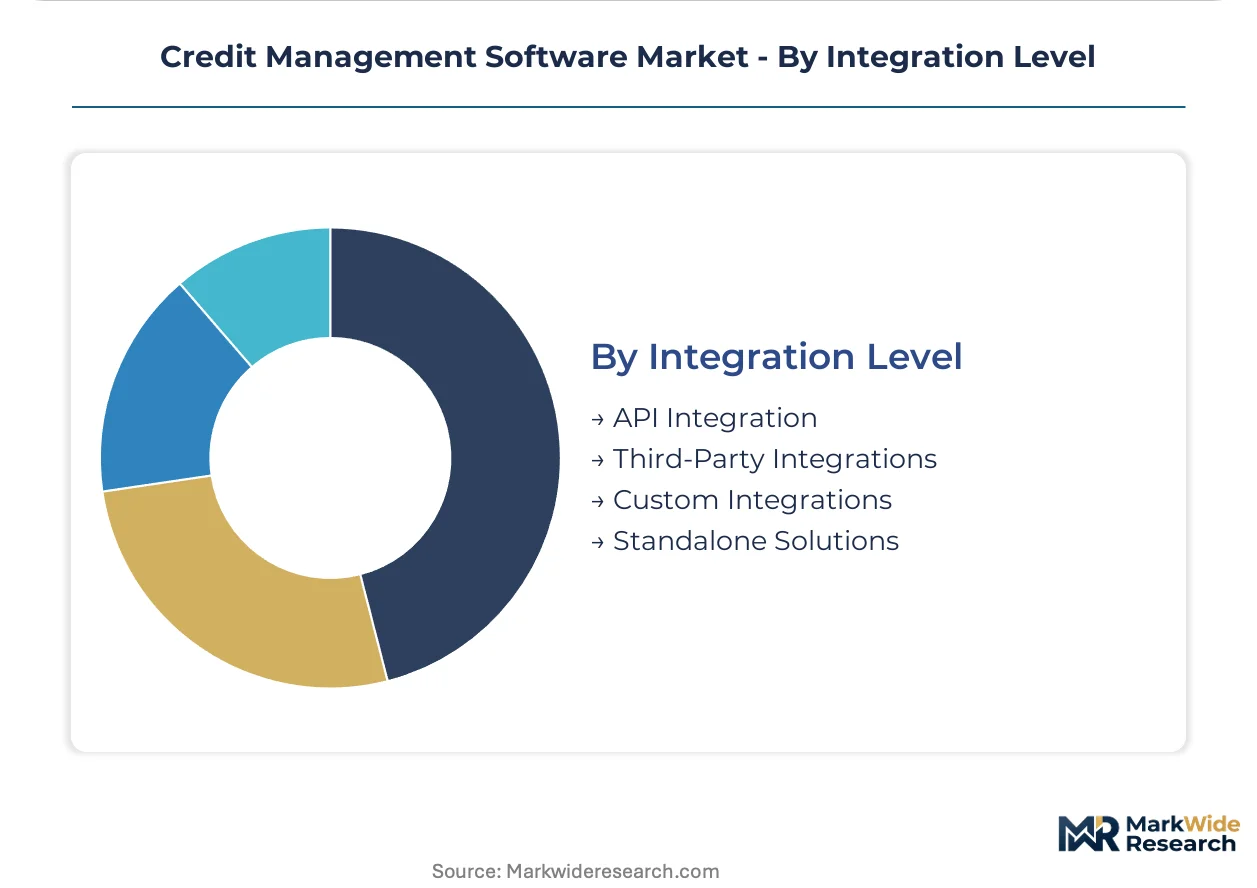
Integration Level:
Technical architecture choices determine customer time-to-value and vendor implementation resource intensity.
- API Integration:RESTful endpoints with standardized authentication enable rapid ERP connectivity. Cloud migration among mid-market banks compresses deployment cycles from eighteen months to under ninety days.
- Third-Party Integrations:Pre-built connectors to payment gateways and credit bureaus reduce custom development. Embedded credit data layers extend traditional bureau scoring into real-time monitoring.
- Custom Integrations:Bespoke middleware for legacy mainframe environments preserves COBOL-core functionality. Swiss and Austrian regulated banks maintain these configurations despite elongated replacement timelines.
- Standalone Solutions:Self-contained platforms with manual data import serve collection agencies and smaller manufacturers lacking IT integration capacity.
API Integration is gaining share fastest; Custom Integrations retain entrenched positions in legacy-dependent jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act's conformity obligations for automated credit decisions are accelerating modernization cycles across European financial institutions. Cloud migration mandates from national regulators are compressing deployment timelines from multi-year mainframe replacements to ninety-day SaaS implementations. Demand concentrates in cooperative banking networks and mid-market manufacturers seeking receivables automation.
Germany
Sparkassen-Finanzgruppe cooperatives are retiring COBOL-based credit infrastructure at scale, generating concentrated demand for cloud-native replacement systems. BaFin supervision requires auditable decision trails for algorithmic scoring models under EU AI Act high-risk system classifications. Frankfurt's fintech cluster hosts pilot programs for central bank digital currency settlement rails that could reshape payment processing integrations.
United States
Healthcare patient financing platforms are driving FDA validation requirements for software-as-medical-device credit tools in hospital revenue cycle management. The Federal Reserve's real-time payment infrastructure expansion is enabling daily risk profile refreshes that displace quarterly bureau pulls. Silicon Valley vendors anchor embedded credit data layers extending traditional scoring into continuous monitoring architectures.
United Kingdom
CFO offices at mid-market manufacturers are displacing perpetual licenses with subscription pricing structures that align software costs to receivables volume. The Financial Conduct Authority's consumer duty obligations intensify scrutiny of algorithmic fairness in automated lending decisions. London's financial services cluster concentrates demand for API-first integration architectures connecting ERP heterogeneity to real-time scoring engines.
France
Mutual banks are prioritizing vendors with CE-marking competencies in adjacent financial software categories to satisfy EU AI Act conformity assessment obligations. GDPR data-retention limits complicate longitudinal default prediction dataset construction for pan-European credit portfolios. Paris hosts pilot programs testing programmable payment triggers through central bank digital currency rails that may displace traditional gateway integrations.
Switzerland
FINMA-regulated institutions maintain on-premises installations with localized data residency satisfying strict cross-border transfer prohibitions. COBOL-core entrenchment extends replacement timelines while preserving maintenance revenue streams for incumbent vendors serving legacy-dependent jurisdictions. Zurich's private banking cluster sustains demand for single-tenant architectures with human oversight protocols mandated by supervisor scrutiny of black-box algorithms.
Credit Management Software Market Vendor Landscape
On the supply side, the industry is consolidating around vendors with balance-sheet capacity to absorb elongated cash conversion cycles from subscription pricing models. Tiered competitive positioning separates enterprise-grade platforms with treasury management heritage from specialists in rules-based decisioning and embedded credit data layers. Dominant competitive moves include API-first re-architecture of onboarding workflows and strategic partnerships anchoring working capital solutions.
Within the enterprise platform tier, HighRadius leverages its treasury management heritage while ACTICO sustains positioning in rules-based decisioning for European cooperative banks. Experian competes through embedded credit data layers extending traditional bureau scoring into real-time monitoring. These three exemplify distinct archetypes: working capital solution providers, regulatory compliance specialists, and data-integrated scoring platforms.
| Leading Market Players |
|---|
| Pega |
| ACTICO |
| HighRadius |
| Resolve Pay |
| HES FinTech |
| Gaviti |
| Experian |
| Daylit |
| Esker |
| Others |
Supply Flow & Price Mechanics
Undercapacity in explainable AI engineering talent across Germany and France is compressing vendor margins while elevating pricing power for certified solution providers. Cloud-native deployment capacity constraints in EU-regulated jurisdictions force buyers toward longer implementation queues or premium-tier managed service arrangements.
Pricing Analysis
Certification level under EU AI Act high-risk system classifications creates the primary spread between premium and standard tiers. Subscription pricing for SaaS receivables platforms now dominates UK and Nordic markets, displacing perpetual licenses. Cost compression in mid-market segments is intensifying because Sparkassen-Finanzgruppe cooperatives demand bundled compliance modules. SMEs exhibit highest price sensitivity; financial institutions with BaFin supervision requirements show lowest.
Supply Chain Analysis
Tariff exposure between US and EU cloud infrastructure providers dominates supply chain risk planning for vendors serving cross-border credit portfolios. Engineering talent concentrates in Germany, United Kingdom, and United States. Proprietary machine learning model development draws from academic partnerships, open-source frameworks, and payment-gateway data feeds. Single-source vulnerability in API-first integration specialists extends implementation timelines. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward cooperative banking networks consolidating procurement decisions across Sparkassen-Finanzgruppe and French mutual federations. Fragmentation among mid-market manufacturers is narrowing as CFO offices centralize vendor selection through shared service centers.
For Market Incumbents: Pre-empt displacement by embedded finance platforms through backward integration into proprietary payment-gateway data feeds. Anchor working capital solutions with treasury management heritage to defend against fintech entrants. Invest in CE-marking competencies for adjacent financial software categories before EU AI Act conformity assessments harden procurement criteria. For New Entrants and Emerging Players: Mid-market manufacturers in the United Kingdom and Nordic markets represent the most penetrable entry point given subscription pricing acceptance and compressed deployment cycle expectations. Healthcare patient financing platforms in the United States offer regulated entry through FDA validation pathways for software-as-medical-device credit tools. Lead with API-first architectures that synchronize SAP-Oracle ERP heterogeneity without custom implementation. For Investors and Strategic Acquirers: Capital is best deployed toward vendors with balance-sheet capacity to absorb elongated cash conversion cycles from subscription pricing models and existing banking partnerships anchoring enterprise-grade deployments. Long-term viability hinges on explainable scoring module differentiation as EU supervisors intensify scrutiny of black-box lending algorithms. Watch central bank digital currency pilot expansion in Frankfurt and Paris as inflection signal for payment processing integration displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first re-architecture compresses deployment cycles from eighteen months to ninety days for mid-market banks. |
| Strategic Partnership | Banking partnerships anchor working capital solutions against pure-play fintech competition. |
| Acquisition of Specialist Firm | CE-marking competencies in adjacent financial software accelerate EU AI Act conformity assessment readiness. |
| Geographic Expansion | Frankfurt and Paris CBDC pilots open programmable settlement trigger opportunities displacing traditional gateways. |
| Product Launch | Explainable scoring modules capture premium positioning under EU supervisor scrutiny of algorithmic decisions. |
Methodological Framework
The analysis maps cloud deployment models, on-premises legacy migrations, and hybrid architectures, each validated through credit department heads, CFO office procurement leads, ERP integration specialists, and regulatory compliance officers. Primary fieldwork combined structured interviews with secondary validation against SEC filings, BaFin supervision disclosures, EU AI Act technical documentation requirements, and cloud infrastructure capex reports. Bottom-up segment sizing triangulated against top-down macroeconomic anchors.
Assumptions held fixed include EU AI Act implementation timelines and GDPR data-retention limits across member states; variables tested included central bank digital currency settlement adoption rates and healthcare patient financing regulatory pathways. The projection horizon spans deployment model transitions, end-user sophistication tiers, solution module bundling patterns, and integration complexity levels across regional adoption clusters. CAGRs derived from segment-level build-ups incorporating receivables volume elasticity and software-as-a-service pricing penetration curves.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories, cross-border data transfer policy, or cooperative banking consolidation pace would shift the trajectory. Forecasts reflect documented assumptions subject to revision from regulatory technology mandates or machine learning governance standard evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Screen and Video Capture Software Market
Software & Services
Asia-Pacific Saas-Based SCM Market
Software & Services
Global Data Warehouse Software Market
Software & Services
Poultry Farm Management Software Market
Software & Services
Cloud-Based ERP Software Market
Software & Services
User Feedback Software Market
Software & Services
Course Authoring Software Market
Software & Services
Machine Translation Software Market
Software & Services
Quick Service Restaurants (QSR) IT Market
Software & Services
Global Absence Management Software Market
Software & Services
Customer Self-Service Software Market
Software & Services
Predictive Dialer Software Market
Software & Services
PCB Design Software Market
Software & Services
Global Business Card Software Market
Software & Services
School Timetable Software Market
Software & Services
Global Accreditation Management Software Market