
 Case Management Software (CMS) Market | 2026-2036
Case Management Software (CMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Case Management Software (CMS) Market Outlook
HIPAA is expanding the cost-of-entry calculus for vendors serving U.S. healthcare clients, forcing encryption, audit trails, and access controls into baseline product architecture. IBM leverages enterprise-grade security certifications to sustain dominance in government and large health system contracts. Clio anchors the legal vertical with practice-specific workflow tools, while Salesforce competes across multiple end-user segments through platform extensibility and native CRM integration.
Case Management Software constitutes digital infrastructure for organizing, tracking, and resolving complex workflows across regulated industries, typically incorporating document management, task automation, role-based access controls, and configurable reporting dashboards. Cloud-Based deployment leads product type adoption as organizations retire on-premises data centers, while SaaS models capture the fastest expansion in deployment models by converting capital expenditure into predictable operational spending. Legal Firms represent a mature end-user segment with established vendor relationships, whereas Healthcare Providers concentrate near-term demand growth as clinical case complexity rises.
FDA oversight of software-as-medical-device functionality intersects with HIPAA privacy and security rules to create dual compliance burdens for healthcare-focused CMS vendors in the United States. The EU AI Act and GDPR impose additional algorithmic transparency and data residency requirements for vendors serving European government agencies and insurers. Stakeholders must evaluate whether their current architectures can absorb emerging interoperability mandates without wholesale platform replacement.
Market Dynamics
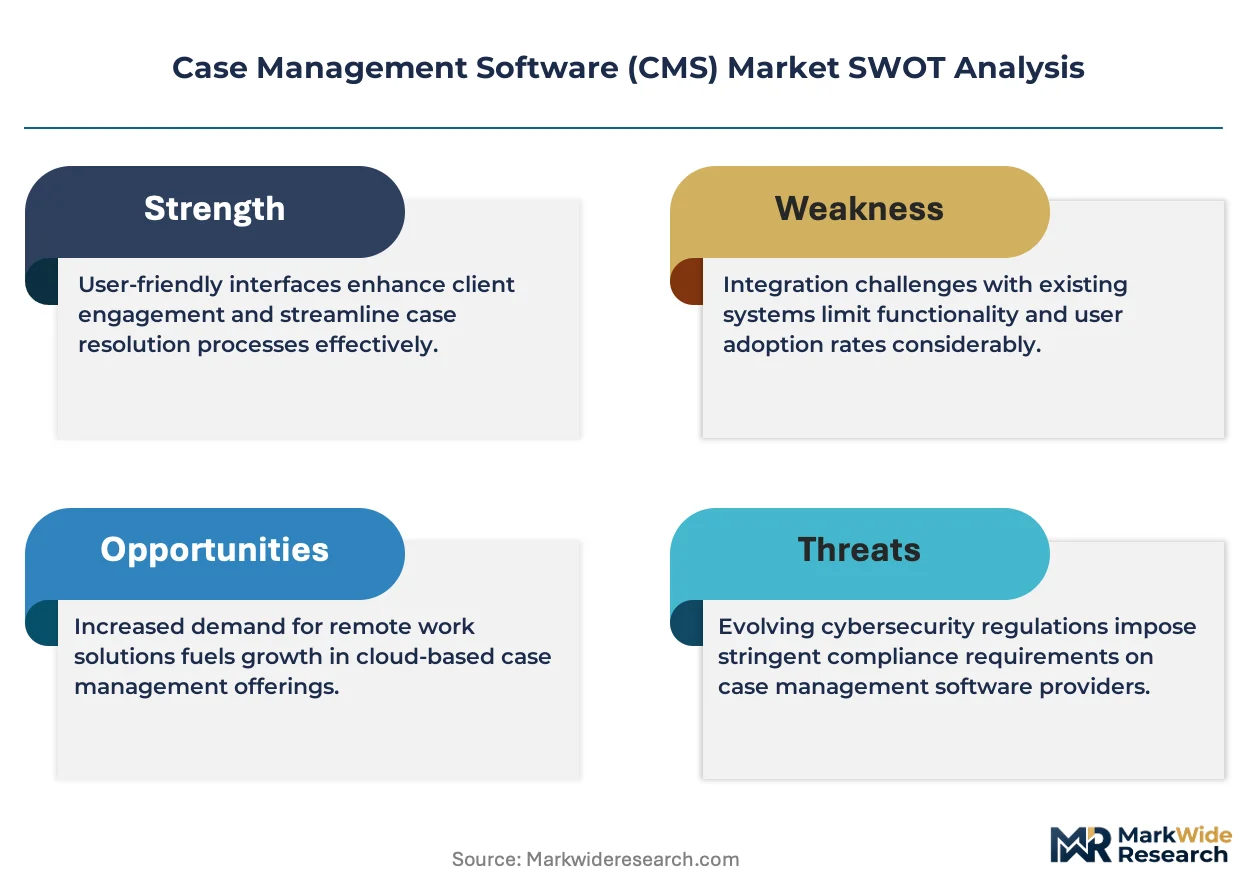
HIPAA compliance mandates and cloud migration imperatives are forcing healthcare providers to retire legacy on-premises systems, compressing procurement cycles and elevating security architecture to a primary vendor selection criterion.
Growth Catalysts
- Cloud Migration:Healthcare providers are accelerating SaaS adoption to eliminate capital-intensive data center maintenance and enable remote clinical access.
- HIPAA Security Rule:Encryption and audit trail requirements are expanding addressable market for compliant vendors serving U.S. health systems.
- Clinical Workflow Complexity:Rising patient acuity and care coordination demands are driving specialized case management automation in hospital networks.
Market Restraints
- Compliance Cost Burden:Dual FDA software-as-medical-device and HIPAA obligations impose redundant validation cycles on healthcare-focused vendors.
- Data Residency Requirements:EU GDPR restrictions on cross-border data flows fragment cloud infrastructure economics for multinational deployments.
- Legacy System Entrenchment:Deep integration with existing EHR architectures creates switching friction that prolongs sales cycles.
Strategic Opportunities
- EU AI Act Alignment:Algorithmic transparency mandates create first-mover advantage for vendors building explainable automation into clinical decision support.
- Behavioral Health Integration:Unmet demand for coordinated mental health and substance abuse case management represents an underserved application segment.
- India Digital Health Mission:National health stack infrastructure investments are opening public-sector procurement channels for interoperable case management platforms.
Industry Challenges
- Interoperability Talent Scarcity:Shortage of engineers with HL7 FHIR and SMART on FHIR expertise constrains product development velocity.
- Certification Timeline Compression:FDA 510(k) clearance processes for clinical decision support features extend time-to-revenue for innovative modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Case Management Software (CMS) Market |
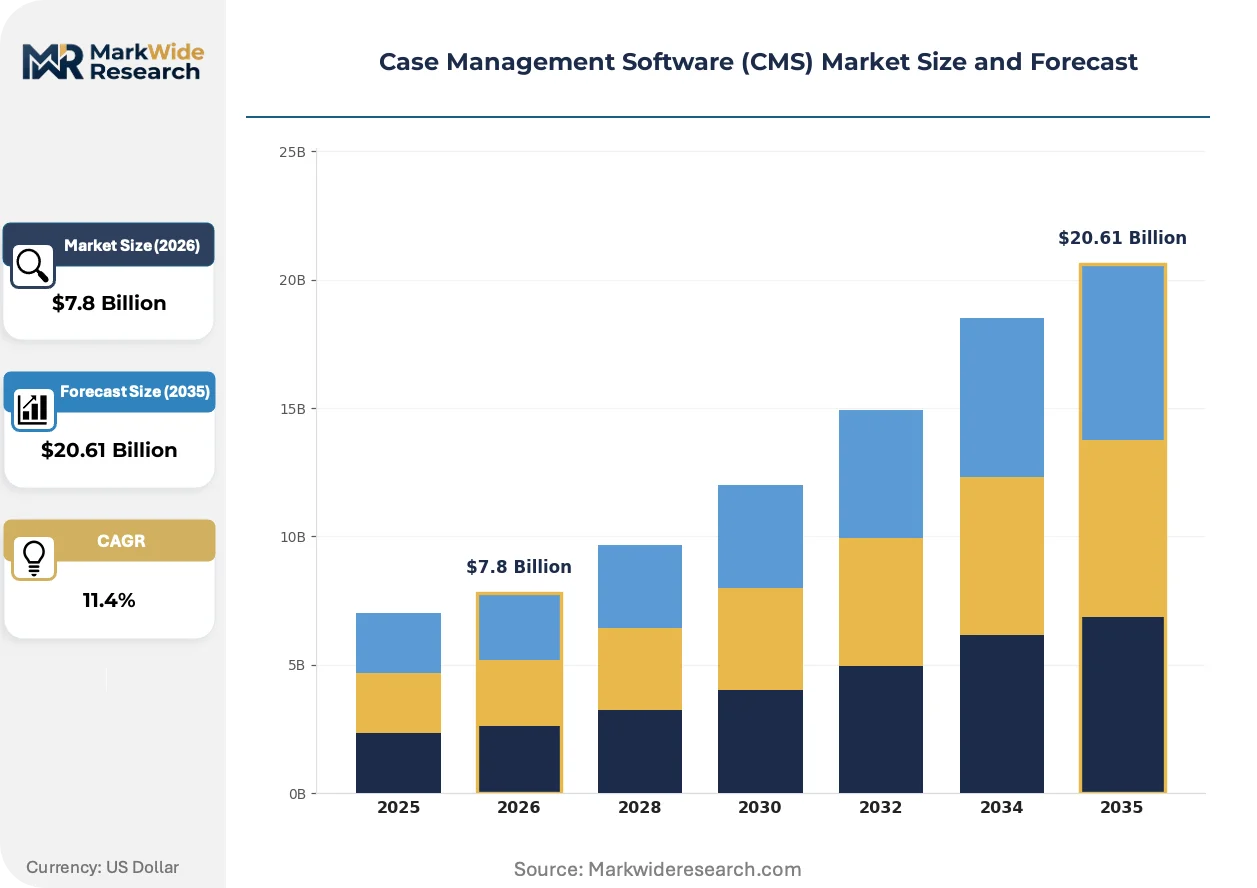
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Mobile End User: Healthcare Providers, Government Agencies, Legal Firms, Insurance Companies Deployment Model: Public Cloud, Private Cloud, SaaS, Self-Hosted Integration Level: API Integration, Third-Party Integration, Custom Integration, Out-of-the-Box Solutions |
| Companies Covered | IBM, Athena Software, AbacusLaw, Smokeball, CosmoLex, Rocket Matter, Actionstep, Clio, Salesforce, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Case Management Software (CMS) Market Strategic Shifts
Artificial intelligence integration and modular API architectures are redefining how case management platforms embed into existing clinical workflows, shifting competitive advantage from feature breadth to interoperability depth.
Blockchain-based audit logging is decentralizing consent management and data provenance tracking across multi-party care teams. Academic medical centers in the United States are piloting distributed ledger implementations for clinical trial case management. This architecture is decentralizing trust assumptions that previously required centralized vendor control over patient records.
The EU AI Act's risk-based classification system is imposing documentation and human oversight obligations on case management tools with diagnostic or triage automation. Vendors must now maintain technical files and conformity assessments for algorithms previously deployed without regulatory visibility. Healthcare providers in Germany and France are demanding vendor-supplied algorithmic impact assessments before procurement approval.
Subscription-based pricing with usage-tier scaling is displacing perpetual license models in mid-market legal and insurance segments. Buyers now expect API call volumes and user seats to adjust dynamically without renegotiation. This preference is most visible among United Kingdom professional services firms consolidating multiple practice management tools into unified platforms.
Case Management Software (CMS) Market Segmentation
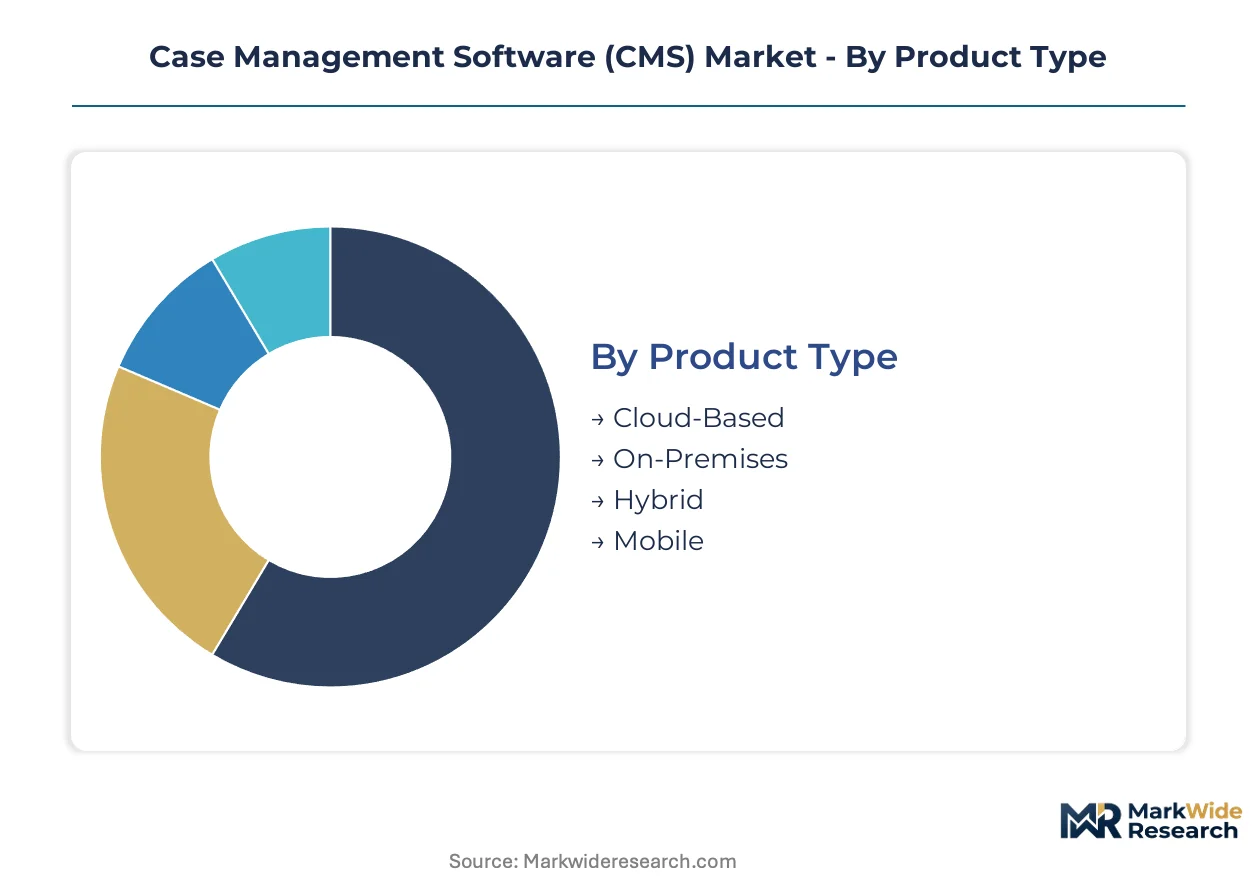
Case Management Software architectures diverge sharply between standalone platforms and embedded workflow layers. Procurement patterns in regulated industries favor deep integration over feature breadth, reshaping how vendors position across deployment and product categories.
Product Type:
Integration depth separates cloud-native architectures from legacy infrastructure—standalone deployments demand heavier customization, while embedded systems ride existing EHR or CRM stacks.
- Cloud-Based:Multi-tenant architectures with automatic patching and elastic compute scaling. Hospital networks in the United States are retiring on-premises data centers to satisfy HIPAA Security Rule audit trail mandates without capital expenditure cycles.
- On-Premises:Single-tenant installations with full data sovereignty and air-gapped security boundaries. Defense contractors and certain European government agencies specify these for classified case workflows where cloud residency is prohibited.
- Hybrid:Split architectures keeping sensitive records on-premises while routing collaborative features through cloud gateways.
- Mobile:Native iOS and Android applications with offline synchronization and biometric authentication for field case workers.
Cloud-Based leads volumes today; Mobile is gaining share fastest.
End User:
Cost tier stratification dominates procurement—enterprise health systems fund comprehensive platforms while mid-market legal practices prioritize seat-based SaaS economics.
- Healthcare Providers:Integrated clinical, financial, and operational case workflows spanning admission through discharge. Academic medical centers in the United States demand HL7 FHIR interoperability and FDA 510(k) clearance for diagnostic modules.
- Legal Firms:Matter-centric docketing, conflict checking, and trust accounting with jurisdiction-specific compliance templates. AmLaw 200 firms in New York and London drive premium pricing for AI-powered document analysis.
- Government Agencies:Citizen service portals with strict accessibility and records retention requirements.
- Insurance Companies:Claims adjudication workflows with fraud detection integration and reinsurance reporting.
Healthcare Providers anchor revenue concentration; Legal Firms show the steepest expansion trajectory.
Deployment Model:
Application criticality determines infrastructure control—clinical decision support demands private tenancy, while administrative case tracking accepts public cloud economics.
- SaaS:Fully managed subscriptions with zero infrastructure ownership and continuous feature delivery. United Kingdom professional services firms consolidate fragmented tools into unified SaaS platforms with API-tier pricing.
- Private Cloud:Dedicated single-tenant environments with custom security boundaries and guaranteed resource allocation. German insurers specify these for GDPR data residency compliance.
- Public Cloud:Shared infrastructure with consumption-based pricing and rapid provisioning for non-sensitive workloads.
- Self-Hosted:Complete operational control including hardware procurement, patching schedules, and disaster recovery orchestration.
SaaS dominates new procurement; Private Cloud is climbing the fastest among regulated industries.
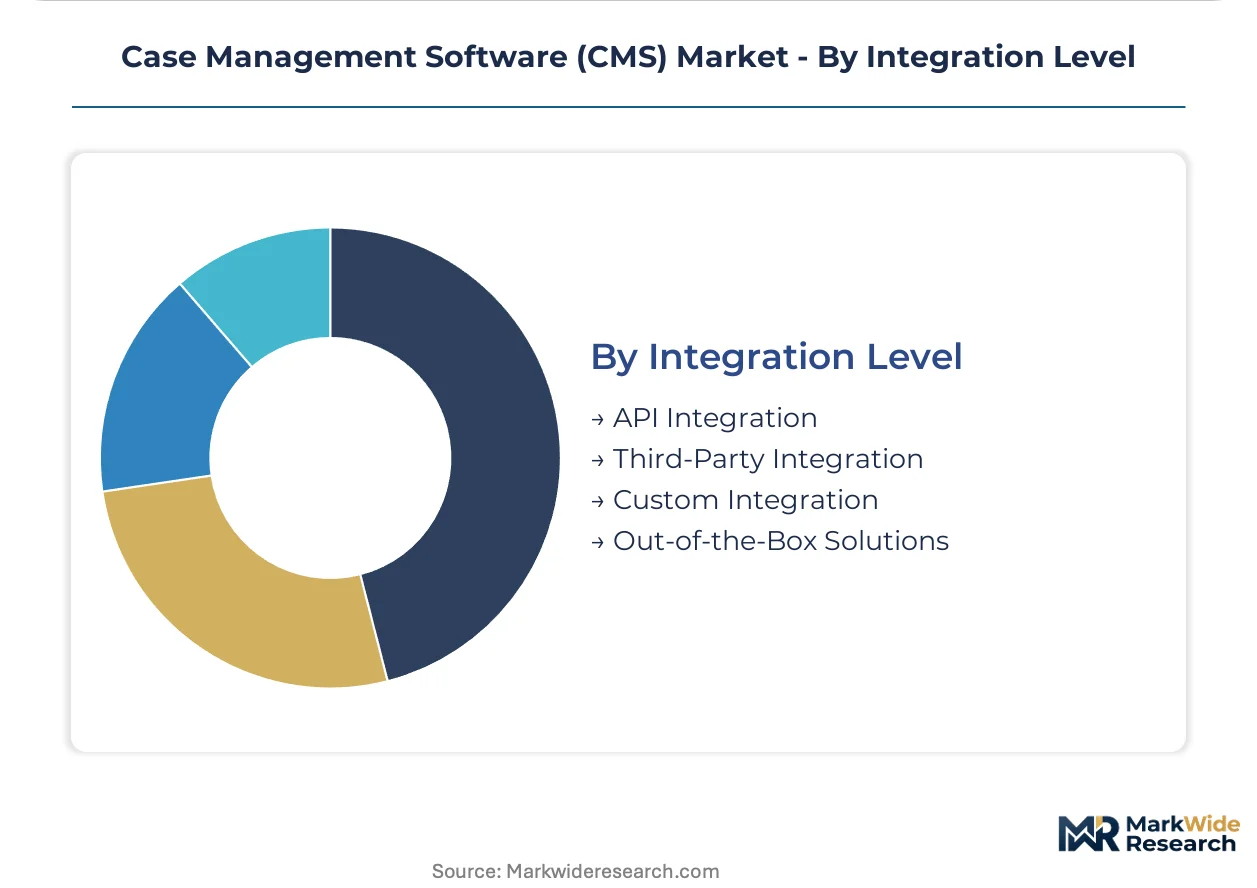
Integration Level:
Customer technical maturity separates buyers seeking turnkey activation from those demanding programmable extensibility.
- API Integration:RESTful and GraphQL endpoints enabling custom workflow orchestration and data exchange. Health systems with mature IT organizations in the United States prioritize SMART on FHIR APIs for EHR connectivity.
- Out-of-the-Box Solutions:Pre-configured templates with minimal setup and standardized workflows for rapid deployment. Small law practices and municipal courts select these to avoid integration engineering costs.
- Third-Party Integration:Native connectors to Salesforce, Microsoft 365, or specialized vertical applications.
- Custom Integration:Bespoke development for legacy mainframe or proprietary internal systems.
API Integration leads adoption among enterprise buyers; Out-of-the-Box Solutions are expanding most quickly in the mid-market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineering talent clusters in the United States, India, and Germany anchor geographic demand concentration for case management platforms. Cloud infrastructure investments and regulatory compliance mandates reshape procurement priorities across these markets.
United States
Hospital network consolidation drives enterprise-scale deployments across academic medical centers and integrated delivery networks. HIPAA Security Rule enforcement compels encryption and audit trail investments, while FDA software-as-medical-device oversight extends validation timelines for clinical modules. The Boston-Cambridge corridor hosts pilot programs for blockchain-based audit logging in clinical trial case management.
Germany
GDPR data residency requirements and the EU AI Act's risk-based classification system elevate procurement scrutiny for algorithmic decision support. German insurers specify private cloud deployments with guaranteed resource allocation for claims adjudication workflows. The Rhine-Ruhr metropolitan region concentrates health IT procurement activity among statutory sickness funds.
United Kingdom
Professional services firms in London consolidate fragmented practice management tools into unified SaaS platforms with API-tier pricing. The NHS Long Term Plan accelerates interoperability investments across regional integrated care systems. Manchester and Birmingham health systems pilot SMART on FHIR integrations for cross-organizational case coordination.
India
The Digital Health Mission opens public-sector procurement channels for interoperable case management platforms at state and district levels. CDSCO medical device regulations intersect with data localization requirements for cloud-hosted clinical workflows. Bengaluru and Hyderabad host development centers supplying HL7 FHIR integration expertise to North American and European vendors.
Japan
METI digital transformation incentives accelerate SaaS migration among mid-market legal practices and regional insurers. PMDA software regulations impose documentation burdens comparable to FDA pathways for clinical decision support modules. The Tokyo-Osaka corridor concentrates demand for mobile-native case management among field-based insurance adjusters and legal investigators.
Case Management Software (CMS) Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across deployment and integration tiers. Market structure shows moderate consolidation at the enterprise health system level alongside fragmentation in legal vertical SaaS. Three archetypes dominate: platform extensibility players, vertical workflow specialists, and security-certification incumbents. M&A activity concentrates on API-first interoperability assets, while geographic expansion targets India and Southeast Asia for engineering talent acquisition.
Within the security-certification tier, IBM leverages enterprise-grade credentials to sustain position in government and large health system contracts. Clio anchors the legal vertical archetype with practice-specific workflow tools. Salesforce occupies the platform extensibility position, competing across multiple end-user segments through native CRM integration and modular API architectures.
| Leading Market Players |
|---|
| IBM |
| Athena Software |
| AbacusLaw |
| Smokeball |
| CosmoLex |
| Rocket Matter |
| Actionstep |
| Clio |
| Salesforce |
| Others |
Value Chain & Pricing Dynamics
Cloud-native SaaS architectures are compressing infrastructure economics while redistributing value capture toward compliance-certified vendors, concentrating procurement power among health systems and legal enterprises that bundle security validation into vendor selection. This production-method transition simultaneously collapses on-premises maintenance costs and elevates certification premiums as pricing differentiators.
Pricing Analysis
Bundled security-audit services now command substantial premiums over unbundled software licenses, with HIPAA-compliant SaaS tiers separating from standard offerings through encryption guarantees and audit-trail automation. Price differentiation rests on certification depth and integration complexity, with enterprise health systems showing lowest sensitivity due to bundled risk-transfer economics while mid-market legal practices face acute cost compression from seat-based subscription scaling. Pricing pressure stems from hyperscaler infrastructure commoditization, though compliance-validated modules resist erosion through regulatory stickiness.
Supply Chain Analysis
Certification and qualification gating concentrates vendor viability among those holding FedRAMP, ISO 27001, and HIPAA Business Associate Agreement credentials, filtering development capacity toward the United States, Germany, and India. Engineering talent draws from Bengaluru, Hyderabad, and Boston-Cambridge clusters, with cloud infrastructure sourcing from hyperscaler regions in Northern Virginia, Frankfurt, and Mumbai. Single-source vulnerability runs through AWS and Azure dominance in healthcare-compliant hosting, while distribution feeds through direct enterprise sales and channel partners serving mid-market legal segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where engineering talent cost differentials between India and the United States enable margin expansion for vendors maintaining HIPAA-validated delivery centers in South Asia.
For Market Incumbents: Deploy certification moats to lock out emerging cloud-native competitors, accelerating FedRAMP and EU AI Act conformity assessments before regulatory timelines compress. Deepen SMART on FHIR engineering benches in Bengaluru to defend against interoperability talent scarcity threatening product velocity.
For New Entrants and Emerging Players: Enter via behavioral health case management workflows, where coordination gaps between mental health and primary care systems create white-space demand unmet by established EHR-embedded platforms. Target state-level procurement channels under India's Digital Health Mission as the most penetrable public-sector entry point.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market legal SaaS vendors lacking healthcare compliance infrastructure, presenting acquisition targets for platform extension. Watch FDA 510(k) clearance timelines for clinical decision support modules as the signal indicating whether innovation premiums or regulatory burdens will dominate returns across the analysis window.
| Strategic Initiative | Industry Significance |
|---|---|
| HIPAA Compliance Certification | FedRAMP authorization opens federal health system procurement channels previously blocked to uncertified vendors. |
| SMART on FHIR Integration | Native EHR connectivity satisfies interoperability mandates from CMS and NHS England simultaneously. |
| EU AI Act Conformity Assessment | Algorithmic documentation requirements create first-mover advantage for explainable clinical automation. |
| Behavioral Health Module Launch | Substance abuse and mental health coordination gaps represent underserved application segments with unconsolidated demand. |
| India Development Center Expansion | Bengaluru and Hyderabad engineering clusters supply HL7 FHIR expertise at cost structures enabling margin defense. |
Study Parameters
Coverage spans the United States, Germany, United Kingdom, India, and Japan, with primary inputs from each market combining interviews with hospital CIOs, legal practice managing partners, health IT procurement officers, and cloud platform engineers. Secondary validation draws from FDA 510(k) filings, NHS procurement databases, CDSCO medical device registrations, and hyperscaler compliance disclosure documents. Bottom-up demand modeling triangulates against top-down market sizing across deployment models and vertical segments.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon, with segmentation modeling spanning cloud deployment architecture, end-user vertical, integration complexity tier, and regional regulatory cluster. CAGRs derive from logistic adoption curves fitted to health system modernization cycles and legal SaaS migration patterns, with forecast inputs incorporating HIPAA enforcement intensity and EU AI Act implementation timelines.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in real-time SaaS pricing transparency introduce uncertainty bands around mid-market segment sizing. Forecasts reflect assumptions about regulatory timeline adherence and cloud infrastructure cost trajectories. A model refresh is warranted upon material change in FDA software-as-medical-device enforcement posture or EU AI Act risk-classification rulings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Application Server Market
Software & Services
Global Professional Service Automation (PSA) Software Market
Software & Services
Global Brand Management Software Market
Software & Services
Global Pharmaceutical Manufacturing Software Market
Software & Services
Global Big Data Software Market
Software & Services
Global Electronic Lab Notebook (ELN) Market
Software & Services
Category Management Software Market
Software & Services
Train Reservation Software Market
Software & Services
Global Pre-Employment Testing Software Market
Software & Services
Global Charity Accounting Software Market
Software & Services
Global Data Discovery Software Market
Software & Services
Global Digital Adoption Platform Software Market
Software & Services
Online Lottery Software Market
Software & Services
Subscription Management Software Market
Software & Services
Video Communications Software Market
Software & Services
Automated Testing Software Market