
 HCS Software and Services Market | 2026-2036
HCS Software and Services Market Size, Share, and Industry Trends Forecast 2026-2036
HCS Software and Services Market Outlook
Modular deployment packaging is repositioning buyer choice in the HCS Software and Services Market, as laboratories shift from monolithic enterprise licenses to component-based subscriptions that separate imaging acquisition from analytics modules. PerkinElmer leverages its instrumentation heritage to anchor bundled hardware-software contracts in North American academic centers. Thermo Fisher Scientific competes through cloud-native architecture that decouples data storage from analytical compute. Danaher Corporation extends its life sciences portfolio into workflow automation software that integrates with existing cell-analysis hardware.
High-content screening software and services encompass computational platforms, image-analysis algorithms, and professional services that process multi-parametric cellular data from automated microscopy systems, typically quantifying hundreds of morphological features per cell across thousands of compounds. These systems serve pharmaceutical discovery and toxicology screening by transforming fluorescence and bright-field images into statistically robust phenotypic profiles. Cloud-based deployment is capturing the fastest expansion as biopharma customers prioritize elastic compute for sporadic large-scale screens, while on-premises installations retain dominance in regulated environments where data residency requirements constrain off-premise migration. Support and maintenance services command durable margin pools due to the specialized expertise required for GxP-validated system upkeep.
FDA 21 CFR Part 11 shapes software validation requirements for electronic records in drug discovery workflows, while EMA's GxP data-integrity guidelines extend similar obligations across European contract research organizations. ISO 13485 quality-management standards govern service providers supporting medical-device-adjacent screening applications. Stakeholders must monitor evolving AI-validation frameworks from both FDA and EMA as machine-learning models increasingly drive primary screening decisions without human-intermediate review.
Market Dynamics
Modular deployment packaging is fragmenting buyer decision-making across pharmaceutical and academic laboratories, as component-based subscriptions separate imaging acquisition from analytics modules and erode traditional bundled contract structures.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records validation requirements in United States drug discovery workflows are accelerating software investment cycles and expanding professional services demand.
- Cloud-native architecture:Biopharma customers prioritize elastic compute infrastructure for sporadic large-scale screens, displacing fixed-capacity on-premises installations.
- Germany:University medical centers are consolidating high-content screening infrastructure, creating concentrated demand for integrated workflow automation.
Market Restraints
- Data residency constraints:European EMA GxP data-integrity guidelines restrict off-premise cloud migration for regulated toxicology screening environments.
- Specialized talent scarcity:GxP-validated system upkeep requires rare expertise in fluorescence microscopy and statistical phenotyping, inflating support service costs.
- Legacy hardware lock-in:Existing cell-analysis instrumentation from prior capital cycles limits software vendor switching flexibility in academic centers.
Strategic Opportunities
- AI-validation frameworks:Emerging FDA and EMA guidance on machine-learning model review creates first-mover advantage for vendors with pre-validated algorithmic screening tools.
- Contract research organizations:European CROs face expanded GxP obligations under EMA guidelines, driving demand for outsourced compliance and validation services.
- Workflow convergence:Integration between automated microscopy and laboratory information management systems opens cross-selling paths in North American biopharma.
Industry Challenges
- Multi-parametric data integration:Harmonizing morphological feature extraction across heterogeneous fluorescence and bright-field image formats strains bioinformatics pipelines.
- Validation timeline compression:ISO 13485 quality-management certification for medical-device-adjacent screening applications extends go-to-market cycles for new software releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HCS Software and Services Market |
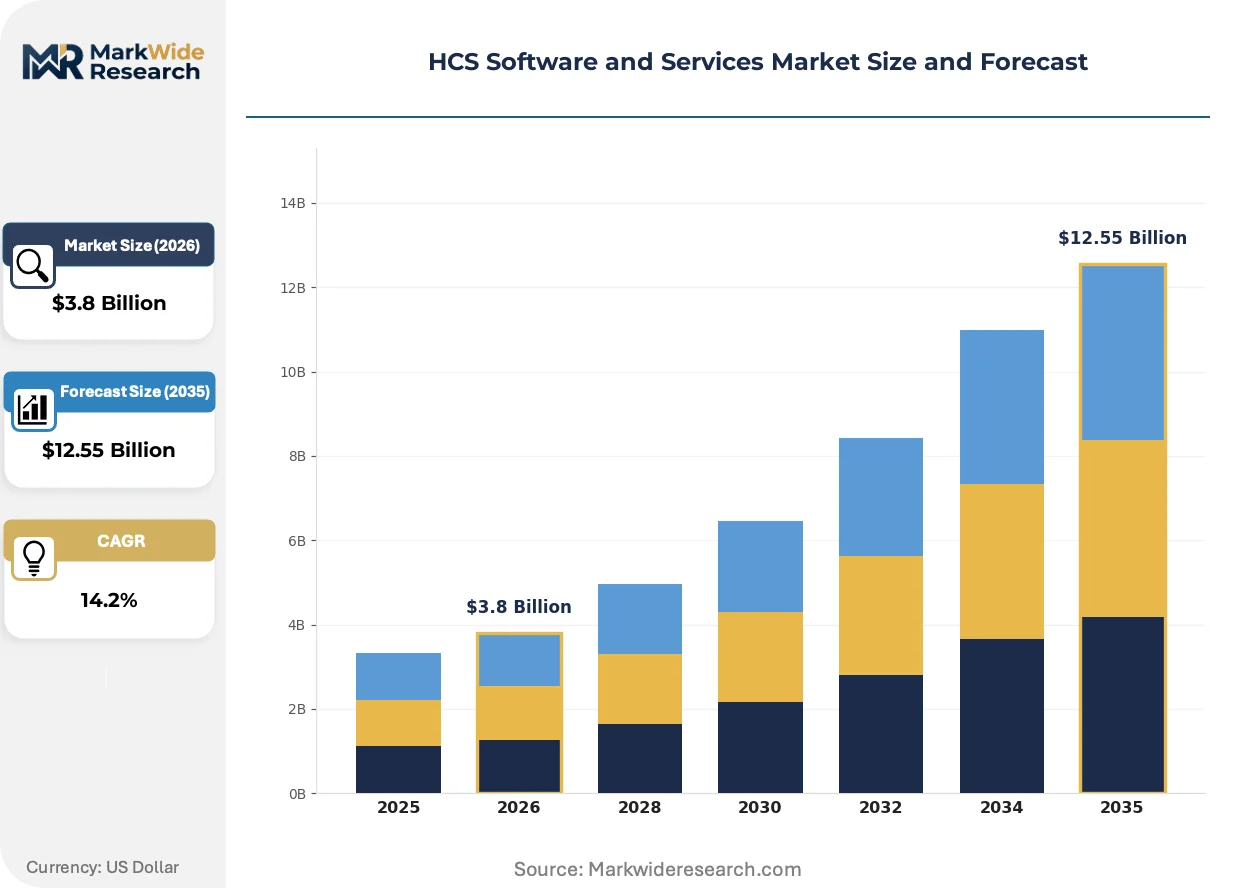
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Implementation, Support, Maintenance Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Services End User: Hospitals, Clinics, Diagnostic Labs, Healthcare Providers Application: Patient Management, Analytics, Telehealth, Workflow Optimization |
| Companies Covered | PerkinElmer, Olympus Corporation, Thermo Fisher Scientific, Tecan Group Ltd, Sysmex Corporation, Danaher Corporation, GE Healthcare, Thorlabs Inc, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HCS Software and Services Market Strategic Shifts
Computational platforms for cellular image analysis are undergoing architectural transformation, with algorithmic sophistication and deployment flexibility now determining competitive differentiation more than raw processing throughput.
Deep-learning phenotypic profiling is consolidating disparate image-analysis workflows into unified neural architectures that simultaneously quantify hundreds of morphological features per cell. Mid-tier pharmaceutical discovery groups are adopting these platforms at accelerating pace, bypassing traditional sequential algorithm development. The technology is consolidating vendor competitive positions around pre-trained model libraries rather than customizable feature engineering tools.
EMA's expanding GxP data-integrity guidelines are imposing electronic audit-trail requirements on European contract research organizations running outsourced toxicology screens. This regulatory pressure is fragmenting software procurement between validated on-premises installations and emerging compliant cloud configurations. Small-molecule discovery teams in Germany and Switzerland are responding by bifurcating infrastructure between elastic compute for early screening and fixed-capacity systems for regulatory submission.
Academic procurement committees are unbundling hardware-software contracts that historically locked imaging acquisition and analytics into single-vendor relationships. Biopharma purchasing functions are replacing these with modular subscriptions that separate data storage from analytical compute licensing. This behavioral shift is most visible in United States university medical centers, where federal grant flexibility enables faster contract restructuring than corporate capital-budget cycles permit.
HCS Software and Services Market Segmentation
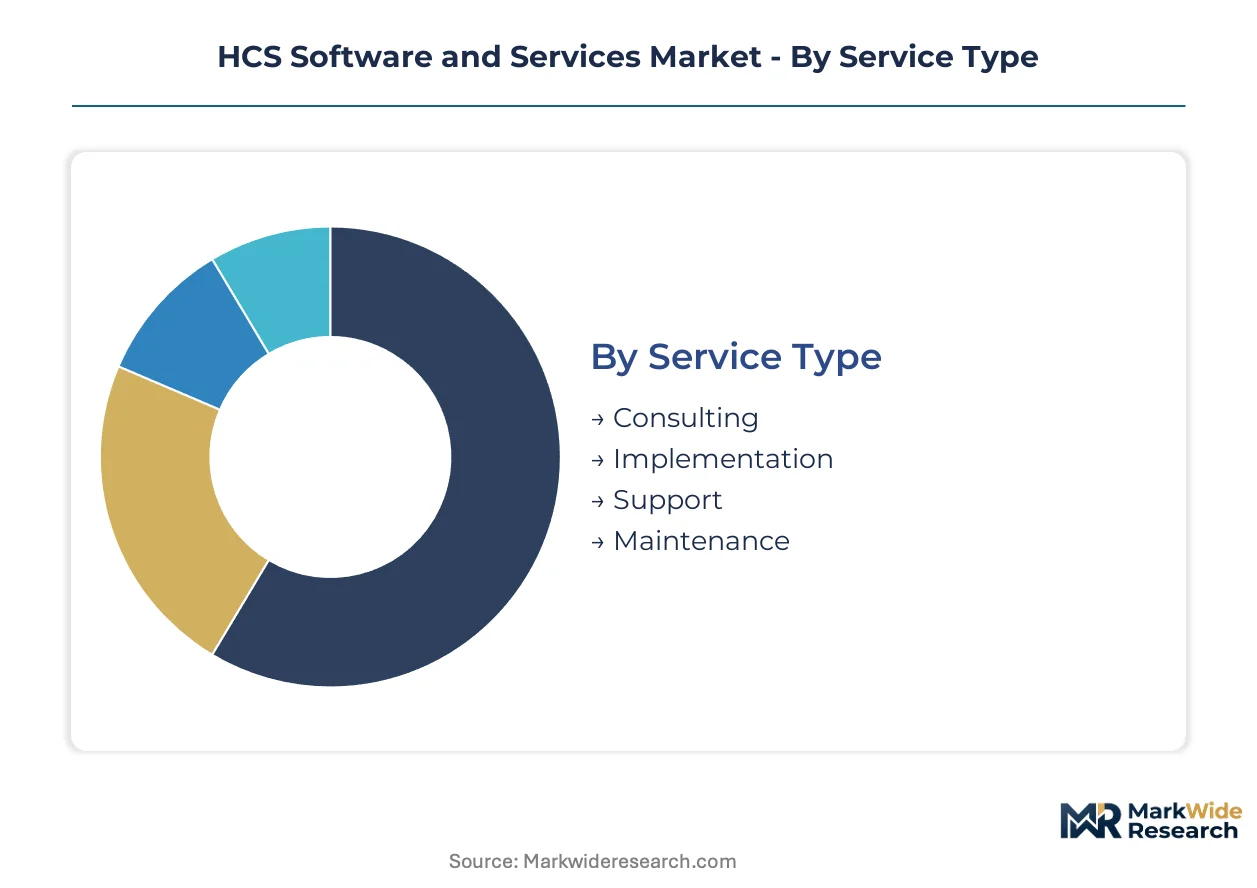
HCS software and services segmentation reveals divergent margin profiles across deployment models and service types. Cloud-native architectures command premium pricing while support services generate recurring revenue pools. Understanding these splits enables targeted resource allocation for vendors navigating modular procurement trends.
Service Type:
Implementation and consulting services capture upfront project value, while maintenance contracts deliver multi-year annuity streams with superior retention economics.
- Consulting:Strategic advisory engagements span workflow design, regulatory pathway mapping, and vendor selection for high-content screening infrastructure. Demand concentrates in German university medical centers consolidating multi-site imaging platforms under unified governance frameworks.
- Implementation:System integration services deploy computational platforms, configure image-analysis pipelines, and establish data architectures. Pharmaceutical discovery groups in the United States prioritize rapid deployment to meet compressed FDA 21 CFR Part 11 validation timelines.
- Support:Technical assistance for fluorescence microscopy calibration, algorithm troubleshooting, and compute resource optimization.
- Maintenance:GxP-validated system upkeep requiring specialized expertise in statistical phenotyping and electronic audit-trail management.
Today's leader: Maintenance. Tomorrow's challenger: Implementation.
Deployment Model:
Elastic infrastructure preferences split procurement between sporadic screening workloads and continuous regulatory operations.
- Cloud-Based:Scalable compute environments enable burst capacity for large-scale compound screens without fixed capital commitment. Biopharma customers prioritize this model for early-stage discovery, though EMA GxP data-integrity guidelines constrain adoption in regulated toxicology environments.
- On-Premises:Dedicated installations within facility data centers satisfy data residency requirements and enable direct hardware control. Diagnostic labs in regulated jurisdictions retain this model for FDA submission-grade screening workflows.
- Hybrid:Bifurcated architectures separate elastic cloud compute for exploratory screening from fixed on-premises systems for regulatory documentation.
- Managed Services:Outsourced infrastructure operation where vendors assume responsibility for compliance, security, and capacity scaling.
Volume dominance: On-Premises. Steepest expansion trajectory: Cloud-Based.
End User:
Capital availability and procurement flexibility distinguish institutional buyers across the healthcare and research spectrum.
- Diagnostic Labs:High-throughput screening operations processing thousands of compounds with automated microscopy systems. Cloud-based analytics platforms are expanding fastest here as labs modernize legacy infrastructure.
- Hospitals:Clinical research divisions conducting patient-derived cell analysis for precision medicine applications.
- Clinics:Smaller-scale operations with limited IT infrastructure and constrained capital budgets.
- Healthcare Providers:Integrated delivery networks consolidating research functions across multiple sites.
Primary revenue source: Diagnostic Labs. Emerging growth vector: Hospitals.
Application:
Functional use cases align software investment with specific operational pain points in cellular analysis workflows.
- Analytics:Computational platforms transforming multi-parametric cellular images into statistically robust phenotypic profiles. Deep-learning architectures now consolidate morphological feature extraction into unified neural networks.
- Workflow Optimization:Integration between automated microscopy and laboratory information management systems, opening cross-selling paths in North American biopharma procurement.
- Patient Management:Sample tracking and chain-of-custody documentation for clinical trial specimens.
- Telehealth:Remote consultation capabilities for distributed research teams reviewing screening results.
Core investment focus: Analytics. Adjacent expansion opportunity: Workflow Optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The HCS software and services industry traces its commercial origins to United States academic medical centers that pioneered automated microscopy for pharmaceutical discovery in the early 2000s. German university hospitals subsequently scaled centralized screening infrastructure throughout the 2010s. Today, demand concentrates in four national markets where regulatory frameworks and research funding patterns diverge sharply.
United States
FDA 21 CFR Part 11 compliance mandates are accelerating validation investments across biopharma discovery groups. The regulation's electronic records requirements force software vendors to maintain specialized professional services teams for audit-trail implementation. Boston and San Diego anchor the densest clusters of contract research organizations running validated screening workflows.
Germany
University medical centers in Heidelberg, Munich, and Berlin are consolidating fragmented high-content screening infrastructure under unified governance frameworks. EMA GxP data-integrity guidelines impose electronic audit-trail obligations that favor on-premises installations over cloud migration. The country's federal research funding structure enables faster capital procurement than corporate budget cycles permit elsewhere.
Switzerland
Swissmedic oversight of medical-device-adjacent screening applications extends ISO 13485 quality-management requirements to software service providers. Basel's pharmaceutical research corridor generates concentrated demand for workflow automation integrating automated microscopy with laboratory information management systems. The country's dual-language regulatory environment creates specialized localization requirements for validation documentation.
United Kingdom
London and Cambridge academic consortia are unbundling historical hardware-software contracts into modular subscriptions separating imaging acquisition from analytics modules. MHRA alignment with EMA post-Brexit maintains GxP data-integrity obligations while introducing independent AI-validation framework development. Research councils' flexible grant structures enable faster procurement restructuring than pharmaceutical corporate headquarters.
Japan
PMDA's evolving guidance on machine-learning model review is creating first-mover advantage opportunities for vendors with pre-validated algorithmic screening tools. Tokyo and Osaka pharmaceutical discovery groups are bifurcating infrastructure between elastic cloud compute for early screening and fixed-capacity systems for regulatory submission. METI funding programs for precision medicine infrastructure are accelerating hospital adoption of patient-derived cell analysis platforms.
HCS Software and Services Market Competitive Environment
The competitive structure tilts toward instrumentation-anchored conglomerates with bundled hardware-software contracts. Three to five diversified life sciences groups control premium-tier positioning through existing microscopy installed bases. Mid-tier specialists compete on cloud-native architecture and modular subscription flexibility. Consolidation pressure is intensifying as biopharma procurement functions demand vendor consolidation for compliance accountability.
Within the instrumentation-heritage tier, PerkinElmer and Thermo Fisher Scientific occupy positions exemplifying divergent architectural strategies. PerkinElmer leverages its microscopy legacy to anchor bundled contracts in North American academic centers. Thermo Fisher Scientific represents the cloud-native vector decoupling data storage from analytical compute. Danaher Corporation sits within the workflow automation archetype extending life sciences portfolios into software integrating with existing cell-analysis hardware.
| Leading Market Players |
|---|
| PerkinElmer |
| Olympus Corporation |
| Thermo Fisher Scientific |
| Tecan Group Ltd |
| Sysmex Corporation |
| Danaher Corporation |
| GE Healthcare |
| Thorlabs Inc |
| Bio-Rad Laboratories |
| Others |
Value Chain & Pricing Dynamics
Biopharma procurement committees unbundling historical hardware-software contracts into modular subscriptions are forcing vendors to restructure cost bases and pricing architectures around component-level value capture rather than bundled enterprise licensing.
Pricing Analysis
Subscription-based SaaS tiers anchored to compute consumption and validation grade stratify vendor offerings across premium GxP-validated, standard research-grade, and economy exploratory tiers. Price differentiation rests on FDA 21 CFR Part 11 certification level and elastic cloud capacity allocation. Cost compression in the standard tier is intensifying because mid-tier pharmaceutical discovery groups are consolidating vendor relationships. Academic centers exhibit highest price sensitivity; regulated toxicology CROs demonstrate lowest sensitivity due to compliance switching costs.
Supply Chain Analysis
FDA and EMA software validation requirements gate vendor participation, concentrating qualified supply among instrumentation-heritage conglomerates with pre-established regulatory documentation capabilities. Development and delivery centers in the United States, Germany, and Switzerland anchor the qualified vendor base. Algorithm development draws from specialized bioinformatics talent pools, cloud infrastructure partnerships, and fluorescence microscopy hardware ecosystems. Single-source vulnerability concentrates in GxP-validated professional services expertise. Distribution runs through direct enterprise sales teams supplemented by specialized life sciences channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in HCS software and services rests on cloud-native architecture reducing infrastructure delivery costs and biopharma buyers accepting premium pricing for pre-validated AI screening tools.
For Market Incumbents: Deepen vertical integration into professional services capabilities to capture GxP validation annuity streams and defend against cloud-native specialists eroding the analytics tier. Fortify position through ISO 13485 certification investments for medical-device-adjacent screening applications. Lock in academic centers with instrumentation trade-in programs that increase switching costs. For New Entrants and Emerging Players: Cloud service providers represent the most viable channel partnership vector for bypassing direct sales infrastructure requirements. White-space opportunity concentrates in European CRO compliance outsourcing and mid-tier pharmaceutical hybrid deployment configurations. Penetrate through API-first architectures enabling integration with existing laboratory information management systems without hardware displacement. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native specialists possessing pre-trained deep-learning model libraries and GxP validation frameworks. Long-term viability favors vendors with recurring revenue concentration above sixty percent and demonstrated FDA 21 CFR Part 11 audit success. Monitor EMA AI-validation guidance publication as inflection signal for algorithmic screening tool premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies imaging acquisition with analytics modules for biopharma workflow consolidation. |
| Strategic Partnership | Cloud infrastructure alliances enable elastic compute scaling for sporadic large-scale screens. |
| Acquisition of Specialist Firm | Captures GxP-validated professional services expertise and regulatory documentation capabilities. |
| Geographic Expansion | Targets German university medical centers consolidating high-content screening infrastructure. |
| Product Launch | Pre-validated AI phenotypic profiling tools command premium pricing under emerging FDA guidance. |
Study Parameters
Bottom-up biopharma procurement modeling reconciled against top-down cloud infrastructure deployment tracking forms the analytical core of this study. Primary interviews with drug discovery executives, regulatory affairs leads, GPO contracts managers, and fluorescence microscopy specialists combined with secondary validation against FDA 21 CFR Part 11 guidance documents, EMA GxP data-integrity guidelines, ISO 13485 certification databases, and SEC filings from publicly traded life sciences conglomerates. Triangulation between demand-side spending patterns and supply-side capacity announcements ensures consistency across estimation layers.
Historical trendline analysis of software licensing transitions from perpetual to subscription models informs projection architecture across deployment model, end-user organization type, application function, and regional regulatory cluster dimensions. CAGRs derive from curve-fitting against validated adoption inflection points in comparable life sciences software categories. Forecast inputs incorporate biopharma R&D expenditure patterns, cloud hyperscaler healthcare vertical growth disclosures, and academic research funding allocations from NIH and federal German sources.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA AI-validation framework publication timing and FDA enforcement posture on machine-learning model review. Assumptions reflect current regulatory trajectory and biopharma procurement behavioral patterns. A model refresh is warranted upon material change in GxP cloud compliance guidance or major biopharma vendor consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Federal Government Software Market
Software & Services
Japan HR Payroll Software Market
Software & Services
Client Virtualization Software Market
Software & Services
Global AR Game Engine Software Market
Software & Services
Creative Software Market
Software & Services
Enterprise Backup and Recovery Software Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
HPC Software Market
Software & Services
Warranty Management Software Market
Software & Services
Performing Arts Software Market
Software & Services
Video Communications Software Market
Software & Services
Collaborative Office Software Market
Software & Services
Global User Interface Service Market
Software & Services
House Cleaning App Market
Software & Services
Global Integration Software Market
Software & Services
Global Florist Software Market