
 Latin America Autonomous Mobile Robot Market | 2026-2036
Latin America Autonomous Mobile Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Autonomous Mobile Robot Market Analytics
Warehouse automation is broadening the addressable market for autonomous mobile robots across Latin America. Geek+ leverages its product specialization in robotic sorting systems to serve third-party logistics providers. ABB anchors its regional presence through localized engineering support and established industrial channels. KUKA AG competes on manufacturing scale, drawing on its European production base to supply Latin American assembly plants.
Autonomous mobile robots are self-navigating vehicles equipped with LiDAR, computer vision, and sensor fusion that transport materials without fixed infrastructure or human drivers. These systems operate through simultaneous localization and mapping algorithms, achieving positional accuracy within centimeters for repetitive material handling tasks. Healthcare robots represent the fastest-growing product category as hospitals in Mexico and Colombia deploy automated delivery for pharmaceuticals and linens. Indoor deployment dominates current installations, though hybrid indoor-outdoor configurations are gaining traction among large-format retail distributors seeking unified fleet management.
Brazil's ANATEL spectrum policies and Mexico's federal labor safety standards shape certification requirements for connected robotics platforms. Argentina's national industrial technology institute promotes local assembly through import substitution frameworks, affecting supply chain configuration for foreign vendors. Stakeholders must weigh regulatory fragmentation against the operational gains from cross-border fleet standardization as the technology matures.
Market Dynamics
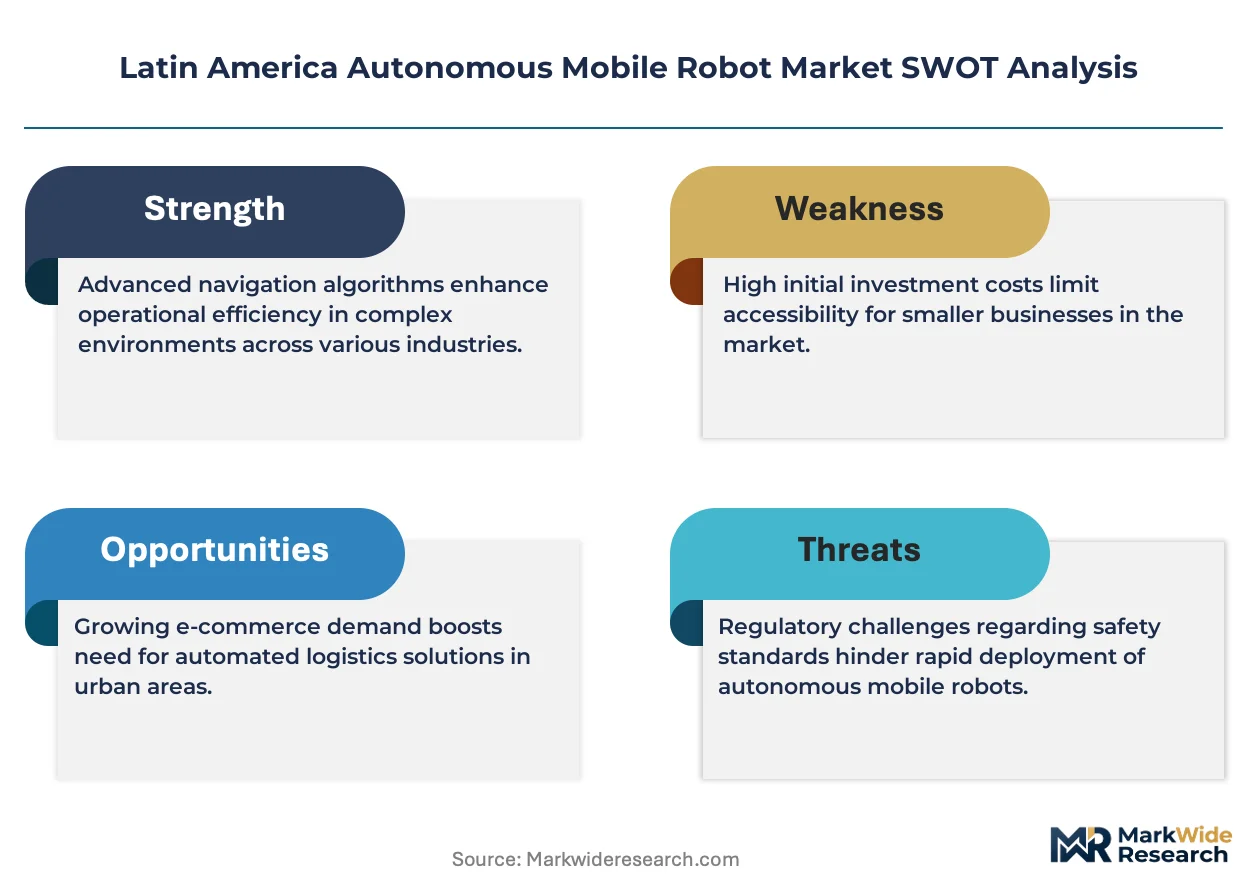
Spectrum allocation decisions by Brazil's ANATEL are compressing deployment timelines for connected robotics fleets, while warehouse automation mandates from e-commerce platforms are pulling capital into autonomous material handling systems across the São Paulo industrial corridor.
Growth Catalysts
- ANATEL Industrial IoT Spectrum:Expanded frequency bands enable real-time fleet coordination without proprietary radio infrastructure. Third-party logistics providers in Brazil's Southeast region are retrofitting fulfillment centers with connected AMR fleets.
- Pharmaceutical Intralogistics:Hospitals in Mexico and Colombia deploy autonomous delivery systems for medication and linen transport. Healthcare facilities cite labor safety standards and infection control protocols as adoption drivers.
- LiDAR-Sensor Fusion Convergence:Cost declines in solid-state LiDAR arrays are enabling centimeter-grade navigation without magnetic tape or QR-code infrastructure. Distribution centers are eliminating fixed-path guided vehicles.
Market Restraints
- Import Duty Structure:Argentina's national industrial technology institute maintains local assembly requirements through import substitution frameworks. Foreign vendors face 35% effective cost penalties for fully-imported units versus locally-assembled alternatives.
- Technical Talent Scarcity:Simultaneous localization and mapping algorithm specialists remain concentrated in São Paulo and Mexico City. Regional deployment projects stall during commissioning phases due to integrator availability constraints.
- Li-ion Battery Supply Concentration:Cell production for mobile robot power systems concentrates in East Asian manufacturing hubs. Latin American assemblers absorb 60-90 day lead time volatility for core energy storage components.
Strategic Opportunities
- Colombian Healthcare Corridor:Bogotá's hospital network modernization program creates first-mover positioning for pharmaceutical delivery automation. Public health infrastructure spending targets logistics efficiency improvements.
- Hybrid Indoor-Outdoor Fleets:Large-format retail distributors seek unified management platforms spanning warehouse and yard operations. Sensor fusion advances enable navigation across lighting condition boundaries without infrastructure handoffs.
- Mexico Federal Labor Safety Standards:Updated occupational safety frameworks explicitly recognize autonomous systems as compliant alternatives for hazardous material transport. Manufacturers can substitute robot capital for personal protective equipment and injury liability exposure.
Industry Challenges
- SLAM Algorithm Commissioning:Facility-specific mapping and localization calibration requires specialized field engineers. Deployment timelines extend 4-8 weeks beyond hardware installation for complex multi-floor operations.
- Warehouse Management System Integration:Legacy enterprise resource planning platforms in Brazilian distribution centers lack native AMR fleet APIs. Middleware development consumes 15-25% of total project implementation budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Autonomous Mobile Robot Market |
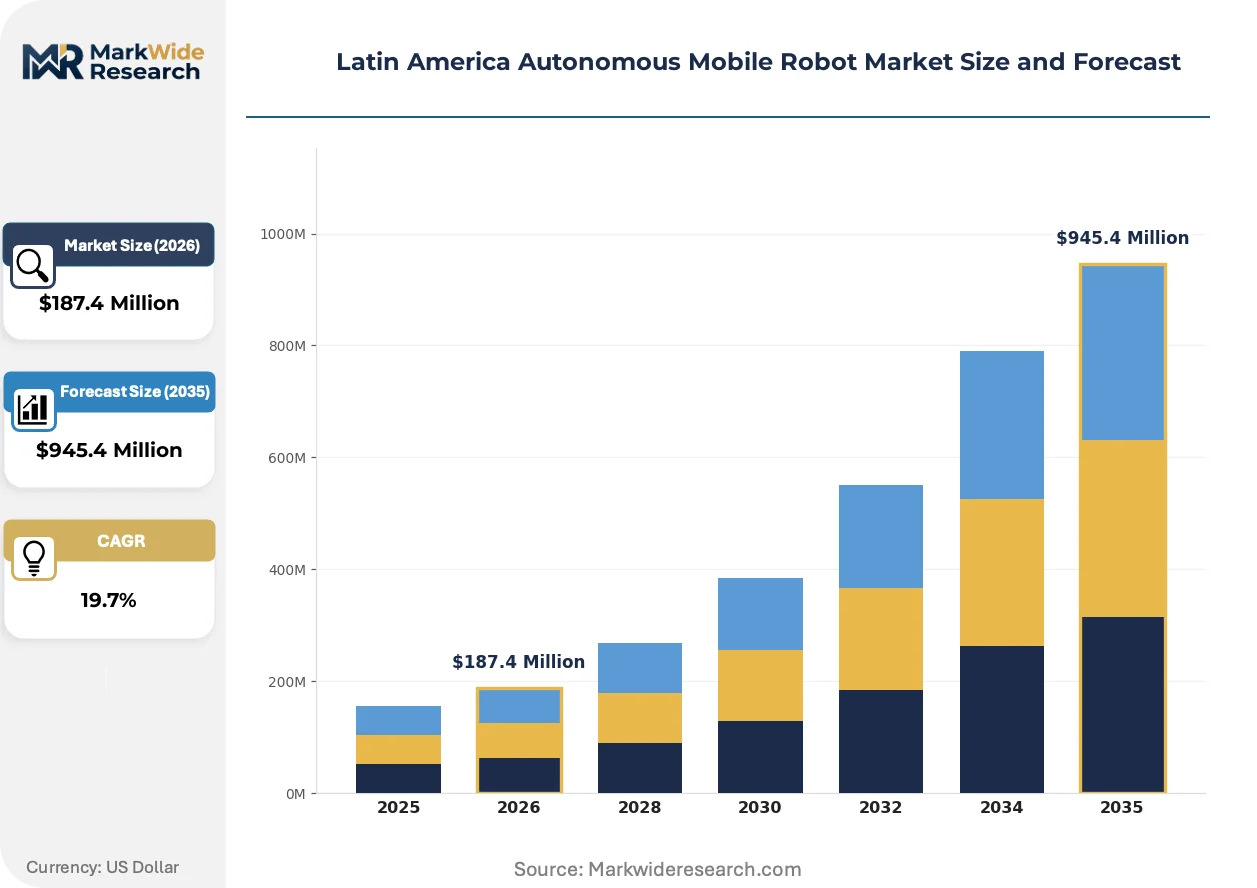
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $945.4 Million |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Delivery Robots, Surveillance Robots, Automated Floor Cleaning Robots, Healthcare Robots End User: Retail, Logistics, Healthcare Facilities, Manufacturing Technology: LiDAR, Computer Vision, Sensor Fusion, Artificial Intelligence Deployment: Indoor, Outdoor, Hybrid, Remote Locations |
| Companies Covered | Mobile Industrial Robots, Geek+, ABB, Locus Robotics, Fetch Robotics, KUKA AG, Amazon Robotics, Fanuc Corporation, Omron Corporation, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Autonomous Mobile Robot Market Evolving Landscape
Computer vision architectures are displacing laser-based navigation as the primary localization modality, while regulatory clarity on industrial IoT spectrum is enabling cross-border fleet standardization that was previously blocked by connectivity fragmentation.
Vision-based simultaneous localization and mapping is electrifying competitive positioning among mid-tier robotics vendors. Solid-state camera arrays with embedded edge computing eliminate mechanical LiDAR components and reduce unit manufacturing costs by 40-60%. Brazilian third-party logistics providers are adopting vision-primary systems for high-velocity e-commerce sortation. The technology is electrifying price competition in the sub-100 kg payload segment previously dominated by established guided vehicle suppliers.
Brazil's ANATEL has finalized dedicated spectrum blocks for industrial IoT applications in the 902-928 MHz and 2.4 GHz bands. Manufacturing facilities can now deploy standardized radio modules without site-specific licensing delays. The policy shift compresses deployment timelines from 90-120 days to 14-21 days for connected AMR fleets. Mexico's federal communications regulator is evaluating similar unlicensed spectrum frameworks for manufacturing corridors in Querétaro and Nuevo León.
Third-party logistics providers are unbundling after-sales service contracts from initial equipment procurement. Large distributors now negotiate separate multi-year fleet management agreements covering predictive maintenance, software updates, and spare parts logistics. The model shifts capital risk to robotics-as-a-service providers while converting vendor relationships into recurring revenue streams. São Paulo-based fulfillment operators pioneered this structure and are now exporting the contracting template to regional distribution networks in Chile and Peru.
Latin America Autonomous Mobile Robot Market Segmentation
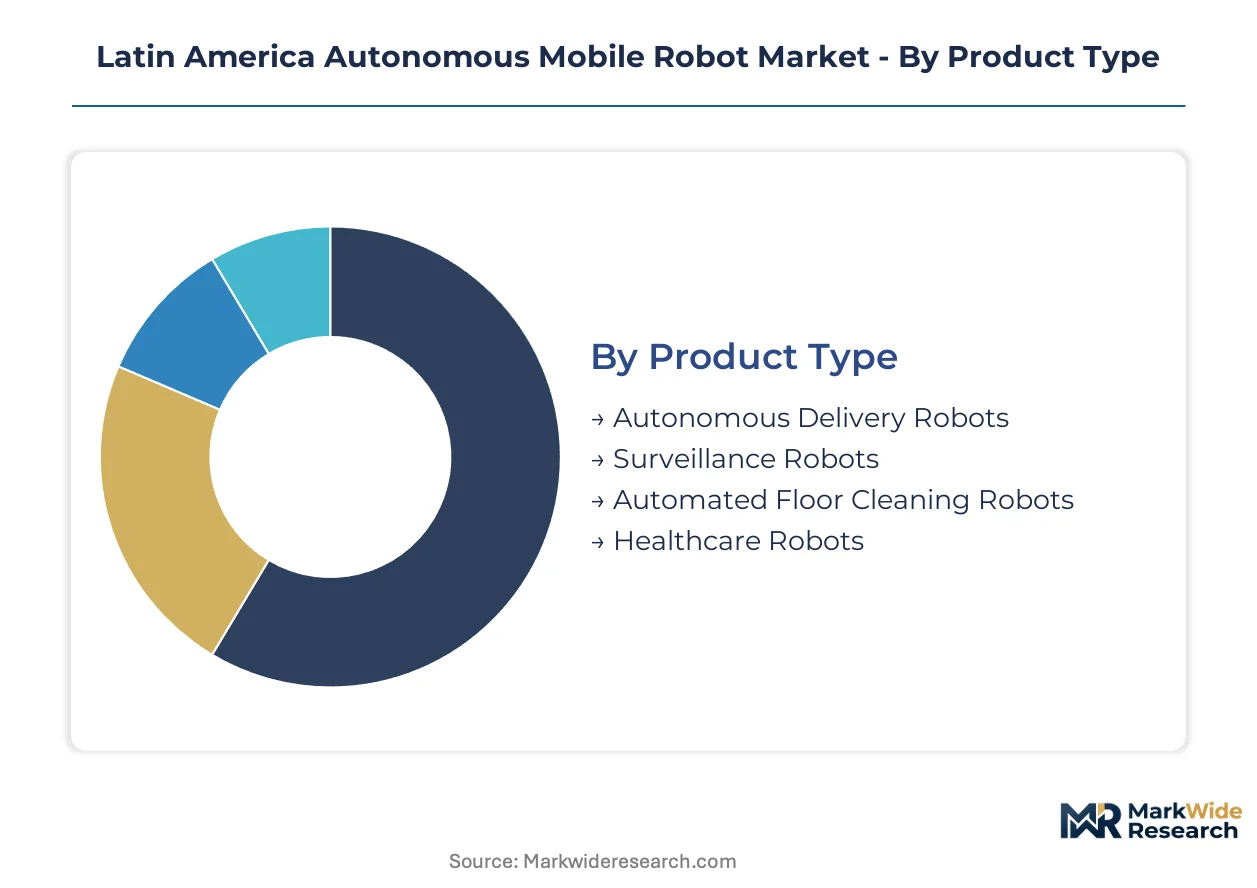
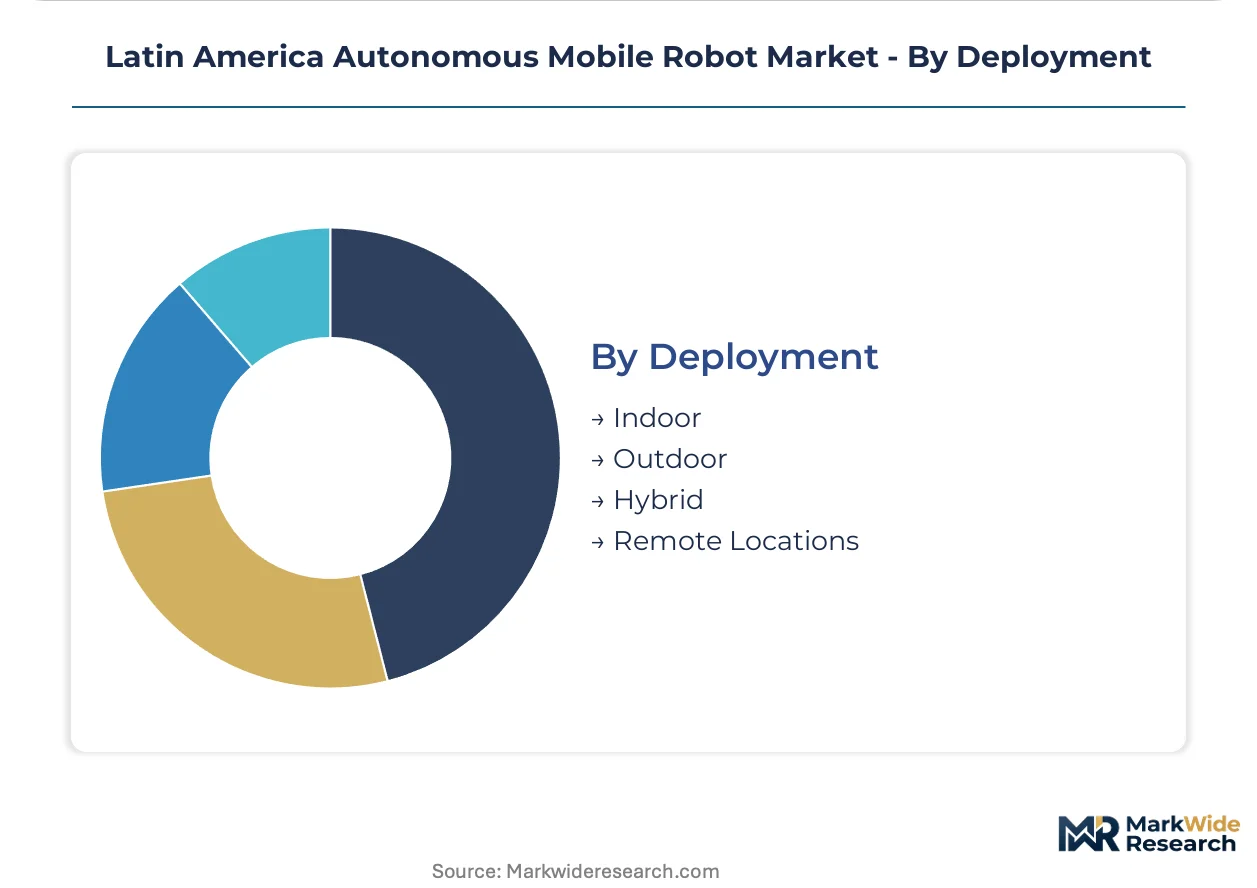
Segmentation reveals how capital allocation priorities diverge across Latin America's emerging automation infrastructure. Facility operators balance proven indoor systems against experimental hybrid configurations as connectivity and labor economics reshape procurement criteria.
Product Type:
Upgrade cycles accelerate as legacy guided vehicles reach end-of-life and warehouse operators evaluate autonomous alternatives against refurbishment costs.
- Autonomous Delivery Robots:These units transport payloads up to 500 kg across warehouse zones using SLAM-based navigation without magnetic tape guidance. São Paulo's third-party logistics corridors concentrate procurement as e-commerce fulfillment operators replace manual cart systems with coordinated robot fleets.
- Healthcare Robots:Hospital-grade units incorporate sealed chassis and HEPA filtration for pharmaceutical and linen transport in clinical environments. Mexico City's public hospital network and Bogotá's healthcare modernization program drive placement volume as infection control protocols harden.
- Surveillance Robots:Mobile security platforms patrol perimeters and interior spaces with thermal imaging and anomaly detection capabilities.
- Automated Floor Cleaning Robots:Industrial scrubbers and sweepers operate autonomously in retail and logistics environments with scheduled route optimization.
Volume placements concentrate in Autonomous Delivery Robots; the faster expansion belongs to Healthcare Robots.
End User:
Cost tier stratification separates high-velocity fulfillment operations from capital-constrained manufacturing floors.
- Logistics:Third-party distribution centers and e-commerce fulfillment hubs deploy coordinated AMR fleets for sortation and transport tasks. Brazil's Southeast region anchors regional demand as Mercado Libre and Amazon expand warehouse footprints.
- Healthcare Facilities:Hospitals and clinics automate internal logistics for medication, specimen, and linen delivery. ANVISA medical device regulations and federal labor safety standards in Mexico shape certification requirements for clinical deployments.
- Retail:Large-format distributors deploy robots for inventory scanning and shelf replenishment in store backrooms.
- Manufacturing:Assembly plants utilize AMRs for work-in-progress transport between production cells.
Logistics commands the dominant share of current installations; Healthcare Facilities are climbing the fastest as hospital infrastructure spending accelerates.
Technology:
Application requirements dictate sensor modality selection as facility operators trade off navigation precision against infrastructure modification costs.
- Sensor Fusion:Multi-modal systems combine LiDAR, camera arrays, and inertial measurement units for robust localization across lighting conditions. Hybrid indoor-outdoor deployments in Brazilian retail distribution networks favor this architecture for unified fleet management.
- Computer Vision:Camera-primary navigation leverages embedded edge computing and deep learning for feature-based localization. Vision systems gain share in cost-sensitive segments as solid-state camera costs decline relative to mechanical LiDAR.
- LiDAR:Laser-based ranging provides centimeter-grade accuracy for high-density warehouse operations with dynamic obstacle environments.
- Artificial Intelligence:Machine learning layers optimize path planning, fleet coordination, and predictive maintenance across robot populations.
Sensor Fusion dominates premium deployments; Computer Vision is gaining share fastest in mid-market segments.
Deployment:
Geography of installation determines connectivity architecture and environmental hardening requirements.
- Indoor:Controlled-environment deployments in warehouses and hospitals utilize Wi-Fi and industrial IoT spectrum for fleet coordination. ANATEL's expanded 902-928 MHz allocation enables real-time connectivity without proprietary radio infrastructure in Brazilian facilities.
- Hybrid:Unified platforms span warehouse interiors and adjacent yard operations without infrastructure handoffs. Large-format retail distributors in Mexico's Nuevo León corridor pilot these configurations for seamless inbound-to-storage workflows.
- Outdoor:Weather-hardened units operate in logistics yards and industrial campuses with GPS augmentation and robust localization.
- Remote Locations:Satellite-connected or offline-capable systems serve mining operations and energy facilities in isolated geographies.
Indoor environments anchor current volume; Hybrid configurations show the steepest expansion trajectory as distribution networks unify yard and warehouse operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone incentives and São Paulo state R&D tax credits concentrate AMR assembly and software development in Brazil's Southeast industrial corridor.
Brazil
Mercado Libre and Amazon fulfillment expansion drives warehouse robot procurement across the São Paulo industrial corridor. ANATEL's 902-928 MHz and 2.4 GHz spectrum allocation eliminates 90-120 day licensing delays for connected fleets. Campinas and Sorocaba host third-party logistics clusters where operators retrofit distribution centers with coordinated AMR systems.
Mexico
Automotive assembly plants in Querétaro and Nuevo León deploy work-in-progress transport robots between production cells. Federal labor safety standards explicitly recognize autonomous systems as compliant alternatives for hazardous material handling. Mexico City Metro hospitals accelerate pharmaceutical delivery automation as infection control protocols harden.
Colombia
Bogotá's public hospital network modernization program targets logistics efficiency improvements through automated linen and medication transport. The national health ministry infrastructure spending framework prioritizes clinical automation. Medellín's pharmaceutical distribution corridor pilots healthcare robot fleets for regional supply chain integration.
Argentina
Import substitution frameworks through the national industrial technology institute impose 35% effective cost penalties on fully-imported units versus locally-assembled alternatives. Buenos Aires province assembly plants absorb 60-90 day Li-ion battery lead time volatility from East Asian suppliers. Córdoba's automotive parts distributors evaluate AMR retrofit economics against guided vehicle refurbishment.
Chile
Large-format retail distributors in Santiago seek unified fleet management platforms spanning warehouse and yard operations. Customs modernization programs accelerate cross-border component transit for regional AMR assemblers. Valparaíso port logistics operators pilot hybrid indoor-outdoor configurations for seamless inbound-to-storage workflows.
Latin America Autonomous Mobile Robot Market Competitive Landscape
Top-tier vendors anchor premium-tier deployments with localized engineering support, while mid-market specialists compete on vision-primary system costs. The vendor base stratifies across three tiers: established industrial automation conglomerates with regional service networks, robotics-native specialists with product-focused portfolios, and emerging vision-technology challengers with edge-computing architectures. Dominant competitive moves include strategic partnerships with third-party logistics providers and portfolio diversification into healthcare-specific chassis designs.
Within the industrial automation tier, ABB and KUKA AG exemplify scale-driven positioning through established distribution channels and captive service infrastructure. Geek+ occupies a specialist position among robotics-native vendors with product concentration in sorting and fulfillment applications. Mobile Industrial Robots anchors the mid-market penetration strategy with compact platform designs targeting retrofit-friendly warehouse environments.
| Leading Market Players |
|---|
| Mobile Industrial Robots |
| Geek+ |
| ABB |
| Locus Robotics |
| Fetch Robotics |
| KUKA AG |
| Amazon Robotics |
| Fanuc Corporation |
| Omron Corporation |
| Others |
Value Network & Pricing Analysis
E-commerce fulfillment operators in Brazil's São Paulo corridor now mandate 14-21 day deployment timelines for connected AMR fleets, forcing vendors to absorb inventory carrying costs or sacrifice margin for spot availability. This procurement compression reshapes how suppliers configure regional stock positions and price access to technical commissioning resources.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent deployments from planned rollouts, with premium tiers capturing buyers facing ANATEL-mandated connectivity deadlines. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales bundling intensity. Cost compression in the economy tier intensifies as vision-primary systems displace mechanical LiDAR configurations. Third-party logistics providers exhibit highest price sensitivity; healthcare facilities with infection-control mandates show lowest.
Supply Chain Analysis
Warehouse-distribution layer configuration centers on East Asian cell production hubs feeding Latin American assembly plants through Valparaíso and Santos port corridors. Solid-state LiDAR arrays, embedded edge-computing modules, and Li-ion battery cells draw from China, South Korea, and Japan manufacturing concentrations. Single-source vulnerability in battery cell supply creates 60-90 day exposure windows for regional assemblers. Distribution runs through São Paulo-based third-party logistics clusters serving Mercado Libre and Amazon fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANATEL's spectrum certification requirements and Mexico's federal labor safety standards erect compliance moats that favor incumbents with established regulatory affairs infrastructure and localized engineering presence.
For Market Incumbents: Extend service contract unbundling pioneered in São Paulo to Chilean and Peruvian distribution networks, converting equipment sales into recurring fleet management revenue streams. Deepen backward integration into vision-primary system manufacturing to defend margin position against emerging edge-computing challengers. Prioritize certification investment for ANVISA medical device pathways in healthcare robotics. For New Entrants and Emerging Players: Enter via Bogotá's hospital network modernization program, where public health infrastructure spending outpaces established vendor coverage. Colombia's pharmaceutical delivery automation segment offers lowest competitive density among major Latin American metros. Pursue robotics-as-a-service contracting templates to bypass capital-constrained procurement committees. For Investors and Strategic Acquirers: The window for entry favors mid-market vision-technology specialists with edge-computing architectures and established ANATEL certification records. Long-term viability hinges on cross-border fleet standardization capabilities as industrial IoT spectrum harmonization progresses. Monitor Mexico's federal communications regulator evaluation of unlicensed spectrum frameworks for manufacturing corridors as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics-as-a-Service Contracting | Unbundled fleet management agreements shift capital risk from São Paulo logistics operators to vendors. |
| Vision-Primary System Development | Solid-state camera arrays with embedded edge computing reduce unit manufacturing costs for Brazilian e-commerce sortation. |
| ANATEL Spectrum Certification | Pre-certified radio modules compress deployment timelines from proprietary infrastructure dependencies. |
| Healthcare Chassis Specialization | Sealed HEPA-filtered designs meet ANVISA requirements for Mexico City and Bogotá hospital deployments. |
| Hybrid Fleet Management Platforms | Unified indoor-outdoor navigation enables seamless warehouse-yard workflows for Nuevo León retail distributors. |
Research Methodology
Trade databases, ANATEL regulatory filings, and hospital procurement records formed the secondary backbone for demand quantification and policy trajectory assessment. Primary interviews with warehouse operations directors, biomedical engineering managers at Mexico City Metro hospitals, third-party logistics procurement leads, and robotics system integrators in Campinas and Sorocaba validated deployment timelines and commissioning constraints. Bottom-up installation tracking across São Paulo, Querétaro, and Bogotá industrial corridors triangulated against top-down e-commerce fulfillment capex disclosures.
Bottom-up modeling aggregated facility-level robot deployment data by payload tier, sensor modality, and end-use vertical across the projection horizon. Segmentation dimensions included product type, deployment environment, technology architecture, and geographic regulatory cluster. CAGRs derived from logistic curve penetration modeling calibrated to historical guided vehicle replacement cycles and connectivity infrastructure buildout rates. Forecast inputs incorporated LiDAR cost decline trajectories and ANATEL spectrum allocation implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Argentina import substitution policy shifts and East Asian battery supply disruptions. Outputs reflect documented assumptions regarding e-commerce fulfillment expansion trajectories and industrial IoT spectrum harmonization progress. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Metal Fabrication Robots Market
Robotics and Automation
Smart Sweeper Market
Robotics and Automation
Global Robotics Market
Robotics and Automation
Commercial Security Robots Market
Robotics and Automation
South America Agricultural Robots and Mechatronics Market
Robotics and Automation
Middle East and Africa Medical Robots Market
Robotics and Automation
Thailand Cloud Robotics Market
Robotics and Automation
US Cloud Robotics Market
Robotics and Automation
Robotics End of Arm Tooling Market
Robotics and Automation
Cordless Router Market
Robotics and Automation
Asrs and Ruos Market
Robotics and Automation
Robotic Air Purifier Market
Robotics and Automation
Global All Terrain Robots Market
Robotics and Automation
Singapore Cloud Robotics Market
Robotics and Automation
Medical Robots Market
Robotics and Automation
Robot As a Service Market