
 Egg Donation Market | 2026-2036
Egg Donation Market Size, Share, and Industry Trends Forecast 2026-2036
Egg Donation Market Analysis
Spain is reshaping competitive dynamics in reproductive services through its high-volume donor recruitment infrastructure and permissive anonymity laws. Shady Grove Fertility leverages its multi-site network across the United States to sustain high-throughput egg banking operations. California Cryobank differentiates through integrated cryopreservation logistics and stringent donor screening protocols that extend quality assurance across distribution channels.
Egg donation involves the retrieval of oocytes from a screened donor, followed by fertilization via in vitro fertilization and transfer to a recipient uterus, with cryopreservation enabling storage at minus 196 degrees Celsius for deferred use. The procedure serves intended parents who cannot produce viable eggs due to age-related ovarian decline, genetic conditions, or iatrogenic infertility from oncologic treatment. Anonymous donors occupy the largest share of the donor profile segment, while fresh donation commands premium pricing due to synchronization complexity and higher live birth rates per transfer. Frozen donation grows fastest among service types because it eliminates cycle coordination costs and expands geographic access for fertility centers sourcing from centralized egg banks.
The FDA regulates donor screening and infectious disease testing in the United States, while the EMA and national tissue authorities enforce the EU Tissues and Cells Directives across European member states. HIPAA compliance requirements shape data handling for donor-recipient matching platforms, and medical ethics frameworks govern compensation caps that directly affect donor supply elasticity. Stakeholders must monitor evolving statutory definitions of donor anonymity and commercial compensation limits, as legislative shifts in major supply countries could abruptly reconfigure sourcing strategies and cross-border patient flows.
Market Dynamics
The egg donation market operates under asymmetric regulatory geography where supply concentrates in permissive jurisdictions while demand originates from restrictive ones, creating cross-border patient flows that reshape competitive positioning among fertility centers and egg banks.
Growth Catalysts
- EU Tissues and Cells Directives:Harmonized quality standards across member states enable accredited Spanish and Czech clinics to serve patients from Germany, Italy, and France where donor anonymity is restricted or banned.
- Cryopreservation technology:Vitrification protocols achieving survival rates above 90% for thawed oocytes allow centralized egg banking to replace fresh-cycle coordination, compressing logistics costs and expanding inventory depth.
- Oncofertility preservation:Pre-chemotherapy egg freezing for cancer patients creates a secondary donor pool when patients later elect not to use stored gametes, broadening supply elasticity in the United States.
Market Restraints
- Donor compensation caps:UK Human Fertilisation and Embryology Authority limits reimbursement to 750 pounds per cycle, constraining donor recruitment relative to uncompensated jurisdictions and creating supply bottlenecks for NHS-funded patients.
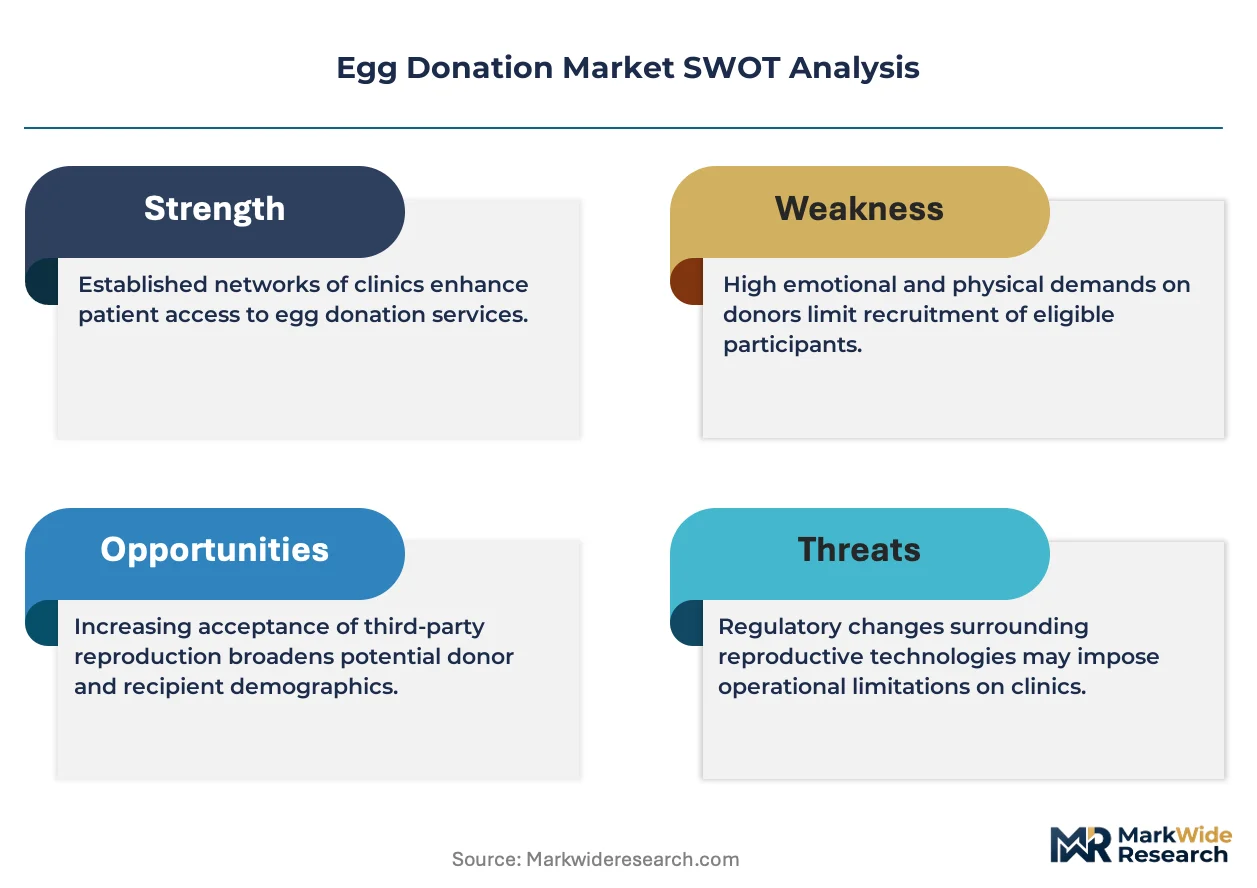
- Fresh-cycle synchronization costs:Recipient-donor menstrual alignment requires 4-6 weeks of hormonal coordination, producing cancellation rates near 15% when donor response falls outside clinical windows.
- Genetic screening complexity:Expanded carrier testing panels detecting 250+ recessive conditions extend donor disqualification rates, narrowing eligible pools and elongating wait times for rare ethnic phenotypes.
Strategic Opportunities
- Ukraine and Georgia:Eastern European jurisdictions with permissive frameworks and lower operational costs attract intended parents from Western Europe and Israel seeking price-sensitive alternatives to Spanish clinics.
- Direct-to-consumer matching platforms:Online donor databases bypass traditional clinic intermediaries, enabling intended parents to filter by education, phenotype, and genetic markers before selecting a fertility center for transfer.
- Preimplantation genetic testing integration:Combining donor egg IVF with PGT-A screening addresses aneuploidy concerns in recipients over 40, creating premium service tiers that command higher clinic fees per cycle.
Industry Challenges
- Reproductive endocrinologist scarcity:Fellowship-trained specialists concentrate in urban academic centers, limiting expansion capacity for satellite clinics in secondary US markets and extending patient travel burdens.
- Cross-border liability fragmentation:Intended parents pursuing treatment in Spain or Greece face jurisdictional ambiguity over parental rights, citizenship transmission, and malpractice recourse when complications arise post-transfer.
- Legacy electronic health record interoperability:Clinic-specific donor databases lack standardized data exchange protocols, forcing manual re-entry of screening results when patients switch providers or pursue backup cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg Donation Market |
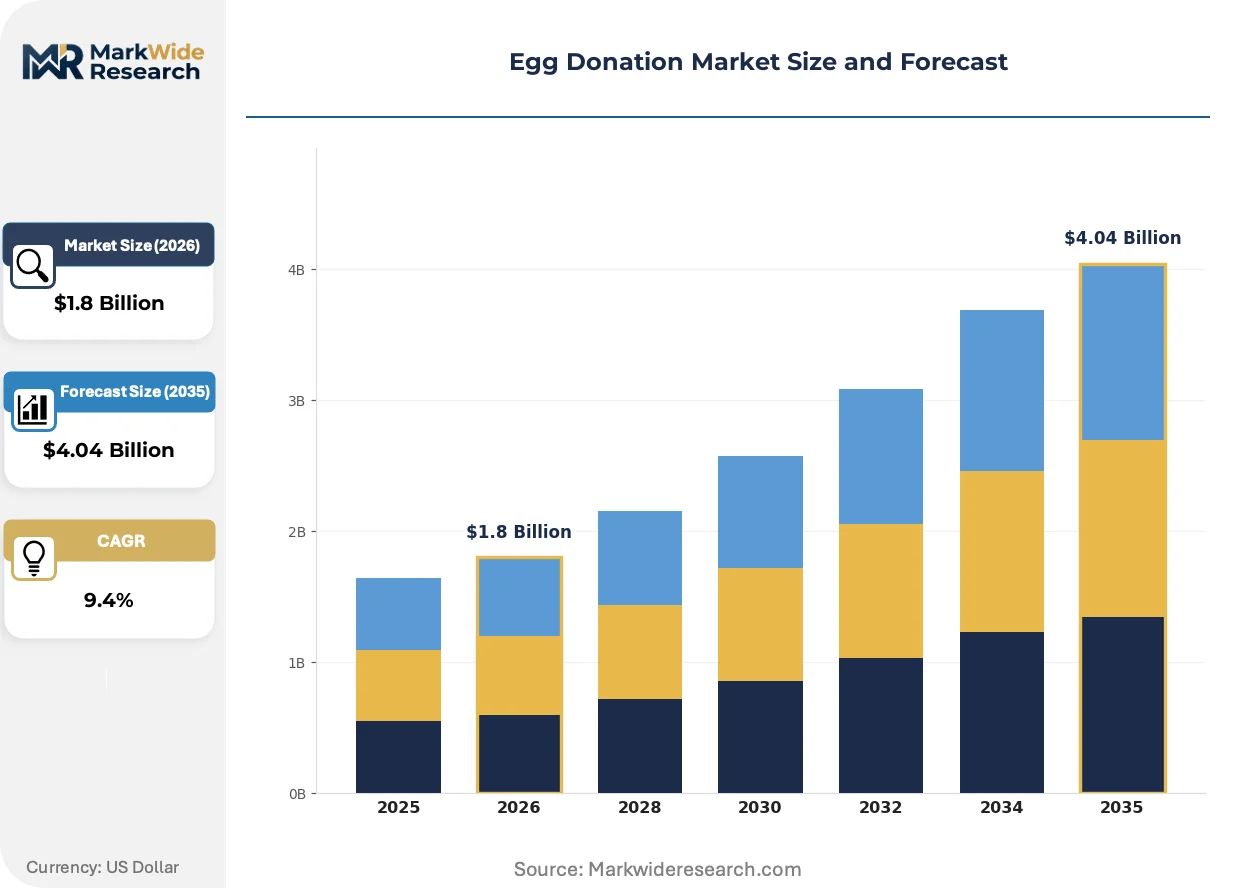
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Client Type: Intended Parents, Single Mothers, LGBTQ+ Couples, Fertility Centers Donor Profile: Anonymous Donors, Known Donors, Gestational Carriers, Egg Freezing Donors Service Type: Fresh Donation, Frozen Donation, Egg Banking, IVF Support Legal Framework: Contractual Agreements, Donor Compensation, Parental Rights, Medical Ethics |
| Companies Covered | Reproductive Medicine Associates of New Jersey, Shady Grove Fertility, California Cryobank, Fairfax EggBank, Donor Egg Bank USA, CCRM Fertility, Hatch Fertility, MyEggBank, Cryos International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg Donation Market Emerging Trajectories
Reproductive medicine is experiencing a platform shift where digital infrastructure and algorithmic matching compress information asymmetries between donors, clinics, and intended parents. Three developments are restructuring how gametes are sourced, screened, and transferred.
Artificial intelligence donor matching is digitizing the historically intuition-driven selection process. Fertility centers and independent platforms deploy machine learning models that weight phenotypic, educational, and genetic criteria against recipient preferences. The technology is digitizing what was previously a coordinator-mediated search, reducing match timelines from weeks to hours while expanding the effective addressable donor pool beyond geographic proximity.
The EU Tissues and Cells Directives are tightening traceability requirements for cross-border gamete movement. Member state regulators now mandate standardized coding systems linking donor identity to all derivative embryos, complicating logistics for multi-country clinic networks. Spanish and Cypriot banks serving northern European patients are responding by investing in dedicated compliance infrastructure and restricted-access biometric donor registries.
Intended parents are fragmenting their procurement across multiple egg banks to mitigate single-source risk. Rather than committing to one clinic's inventory, buyers now secure backup donor profiles from separate jurisdictions before initiating stimulation. This behavioral shift is most visible among US patients over 42, where cycle cancellation costs exceed 15,000 dollars and genetic screening delays threaten age-related fertility windows.
Egg Donation Market Segmentation
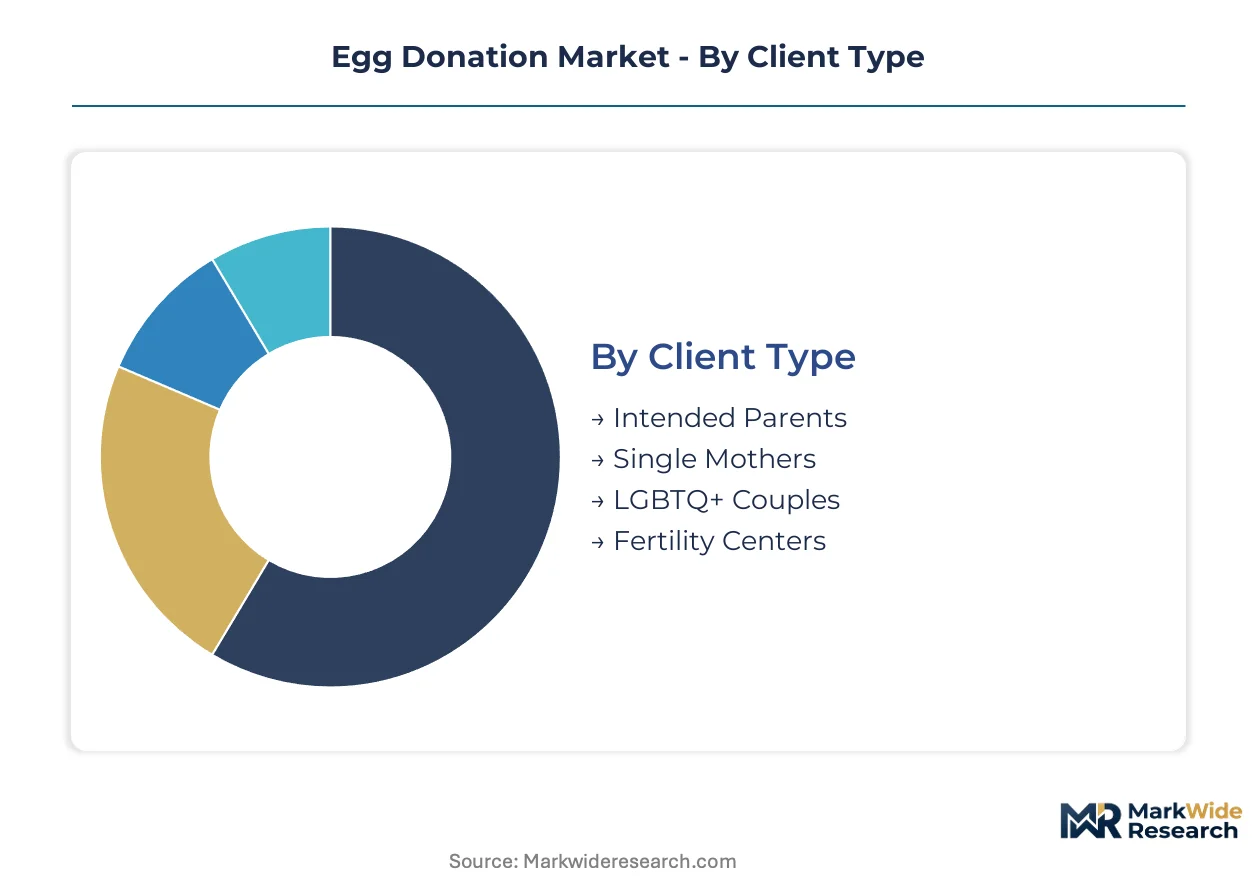
Egg donation segmentation reveals how service delivery models, donor relationships, and legal architectures create distinct commercial tiers. Each category shapes procurement costs, regulatory exposure, and patient matching complexity for fertility centers and intended parents.
Client Type:
After-sales service intensity varies sharply across client categories, with fertility centers demanding inventory guarantees and intended parents requiring cycle coordination support.
- Fertility Centers:High-volume procurement clients operating multi-site networks. These centers negotiate bulk pricing for frozen oocyte lots and require 24-hour logistics support for thaw protocols. Spain's centralized egg banks serve German and Italian centers facing domestic donor shortages.
- Intended Parents:Direct-pay individuals or couples purchasing discrete cycles without institutional intermediation. California and New York jurisdictions concentrate demand due to permissive commercial frameworks and proximity to specialized reproductive endocrinology practices.
- LGBTQ+ Couples:Dual-intended-parent arrangements requiring legal clarity on second-parent adoption alongside gamete procurement. Demand clusters in Massachusetts, Illinois, and other states with established parental presumption statutes.
- Single Mothers:Solo intended parents prioritizing donor phenotype matching and genetic screening transparency over cost minimization. This segment shows highest willingness-to-pay for expanded carrier testing panels.
By volume, fertility centers lead procurement. By growth pace, LGBTQ+ couples are expanding most quickly as legal recognition spreads across US states and European jurisdictions.
Donor Profile:
Margin structures diverge based on donor identification protocols and recruitment channel economics.
- Anonymous Donors:Identity-protected contributors recruited through agency networks or clinic databases. These donors command premium compensation in Spain and Cyprus where anonymity statutes remain intact, while UK and Netherlands restrictions compress available supply.
- Known Donors:Personally identified contributors, often friends or relatives of intended parents. Legal frameworks in France and Germany heavily restrict this category, pushing cross-border flows toward Belgium and Greece.
- Egg Freezing Donors:Cancer patients or fertility preservation clients who later elect to donate unused oocytes. US oncofertility programs in Boston and Houston generate this supply through pre-chemotherapy counseling protocols.
- Gestational Carriers:Surrogate arrangements combining gamete donation with uterine hosting, requiring dual legal infrastructure. California and Ukraine concentrate this complex service tier due to established case law and contractual enforceability.
Anonymous donors dominate transaction volume. Known donors are gaining share fastest where legislative shifts threaten anonymity protections.
Service Type:
Supply concentration patterns map directly to cryopreservation capability and cycle coordination infrastructure.
- Frozen Donation:Vitrified oocytes stored in liquid nitrogen at minus 196 degrees Celsius, enabling immediate availability without menstrual synchronization. Centralized US egg banks in California and Texas leverage this format to serve dispersed fertility centers.
- Fresh Donation:Retrieved oocytes fertilized within hours of aspiration, requiring precise donor-recipient hormonal alignment. Live birth rates per transfer remain marginally higher, justifying 30-40% price premiums in Spanish and Czech clinics.
- Egg Banking:Inventory warehousing for deferred personal use or future anonymous allocation. This model requires substantial capital deployment for cryogenic storage infrastructure and regulatory compliance across multiple jurisdictions.
- IVF Support:Ancillary services including hormonal monitoring, embryo culture, and transfer procedures bundled with gamete provision. Revenue accrues to fertility centers rather than donor agencies or egg banks.
Frozen donation leads by volume. Egg banking shows the steepest expansion trajectory as vitrification survival rates exceed 90% and geographic sourcing constraints dissolve.
Legal Framework:
Regulatory maturity determines market access and operational risk exposure for cross-border service providers.
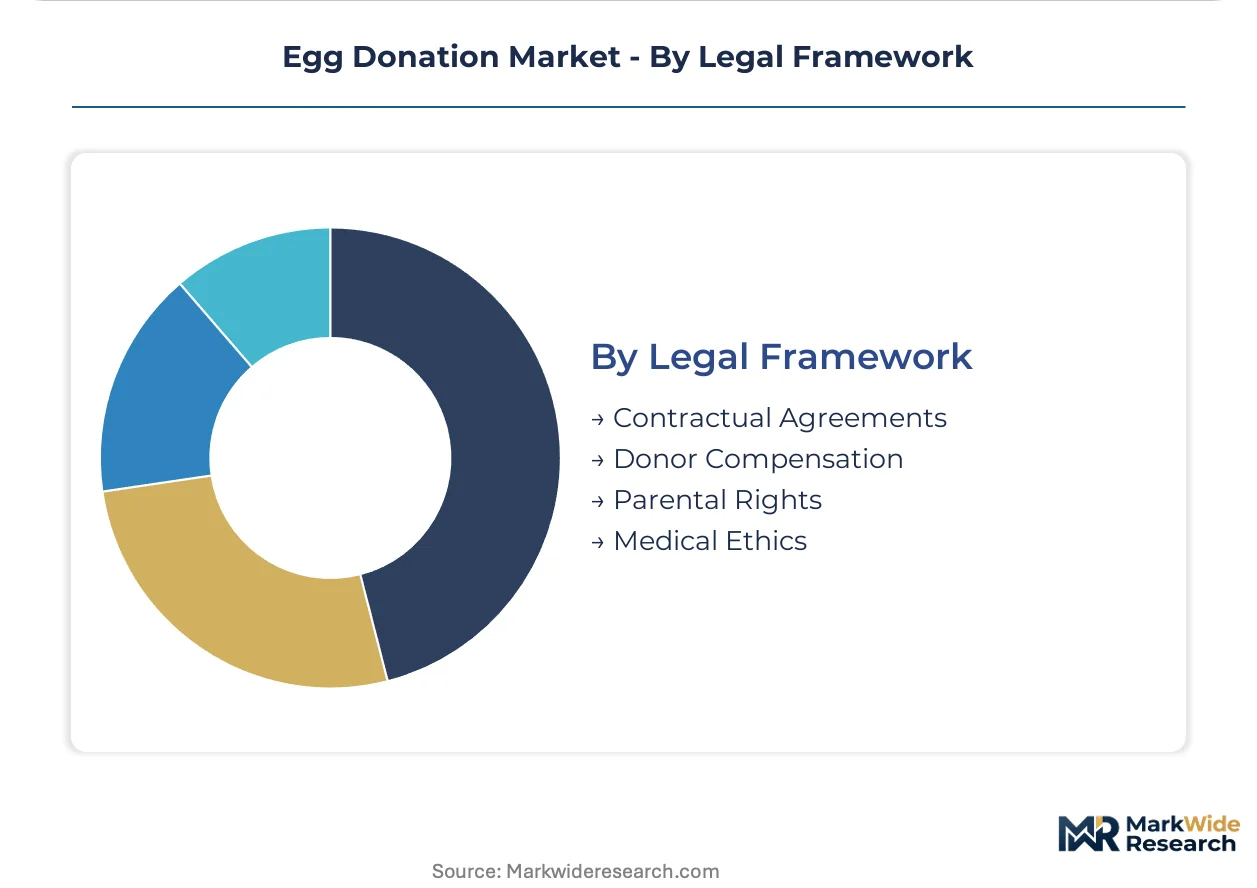
- Donor Compensation:Commercial payment structures ranging from expense reimbursement to performance-based fees. UK HFEA caps reimbursement at 750 pounds, while Spain permits market-rate compensation that attracts Northern European patients.
- Contractual Agreements:Binding documents governing gamete transfer, parental rights relinquishment, and liability allocation. Greek and Ukrainian legal systems offer template contracts with judicial precedents reducing enforcement uncertainty.
- Parental Rights:Statutory frameworks determining legal motherhood at birth versus genetic motherhood. Israel and some US states recognize intended parents immediately, while others require adoption proceedings.
- Medical Ethics:Professional guidelines from national fertility societies and international bodies limiting donor offspring numbers and mandating counseling protocols. These standards shape clinic accreditation and insurance coverage eligibility.
Contractual agreements anchor commercial volume. Donor compensation frameworks are climbing the fastest as jurisdictions liberalize payment rules to address supply shortages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EMA anchors European regulatory harmonization through the EU Tissues and Cells Directives, enabling accredited clinics in permissive jurisdictions to serve cross-border demand from restrictive member states.
United States
FDA donor screening protocols and HIPAA compliance requirements shape operational standards for fertility centers and egg banks. State-level compensation permissiveness in California and New York sustains donor supply elasticity. Multi-site networks in Texas and the Mid-Atlantic concentrate cryogenic storage infrastructure for national distribution.
Spain
Anonymous donation statutes and market-rate compensation frameworks attract Northern European patients facing domestic supply constraints. The national tissue authority enforces traceability standards aligned with EU directives. Barcelona and Madrid clinics operate high-volume donor recruitment infrastructure serving German, Italian, and French intended parents.
United Kingdom
The Human Fertilisation and Embryology Authority caps donor reimbursement at 750 pounds per cycle, compressing domestic supply relative to uncompensated jurisdictions. NHS funding limitations create wait-time bottlenecks for publicly funded patients. London fertility centers increasingly refer patients to Spanish and Cypriot clinics for timely access.
Czech Republic
Permissive anonymity protections and lower operational costs position Prague and Brno clinics as price-sensitive alternatives to Spanish providers. National tissue regulators implement EU directive traceability requirements. The country's centralized egg banks serve Austrian and German patients restricted by domestic donor identification mandates.
Ukraine
Liberal commercial frameworks and reduced cost structures attract intended parents from Western Europe and Israel seeking alternatives to established Spanish clinics. Template contractual agreements with judicial precedents reduce enforcement uncertainty. Kyiv clinics have expanded cryopreservation capacity to support cross-border patient flows.
Egg Donation Market Vendor Landscape
Capability concentration sits with specialized fertility networks operating multi-site retrieval and banking infrastructure; scale advantage sits with centralized egg banks leveraging vitrification logistics to serve dispersed clinic clients. The market structures around three archetypes: integrated fertility networks with captive donor pools, independent egg banks supplying third-party clinics, and direct-to-consumer matching platforms bypassing traditional intermediaries. Consolidation pressures favor entities controlling both donor recruitment and cryogenic distribution. Dominant competitive moves include geographic expansion into underserved secondary markets and technology licensing for vitrification protocols.
Among US-based integrated networks, Shady Grove Fertility and CCRM Fertility exemplify the multi-site fertility center archetype combining retrieval, banking, and transfer services under unified clinical governance. California Cryobank occupies a position within the specialized cryopreservation tier, representing the centralized egg bank model that supplies third-party fertility centers with vitrified inventory. These three entities anchor distinct competitive vectors: clinical integration, cryogenic logistics, and national distribution scale.
| Leading Market Players |
|---|
| Reproductive Medicine Associates of New Jersey |
| Shady Grove Fertility |
| California Cryobank |
| Fairfax EggBank |
| Donor Egg Bank USA |
| CCRM Fertility |
| Hatch Fertility |
| MyEggBank |
| Cryos International |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Spanish donor recruitment infrastructure determines both pricing tier spreads and supply chain shape, as clinics in Germany and Italy face 12-18 month wait times that compress margins while channeling patient flows toward cross-border providers with captive donor pools.
Pricing Analysis
Geographic price spreads between Spanish clinics and UK providers exceed threefold for equivalent donor profiles, with Barcelona and Madrid facilities commanding premiums for immediate-cycle availability while NHS-funded British patients queue under compensation-capped supply constraints. Three-tier pricing structure across premium, standard, and economy levels segments by genetic screening depth and donor phenotype specificity, with expanded carrier testing panels adding substantial cost. Pricing pressure stems from Ukrainian and Georgian entrants undercutting established Spanish rates by 30-40 percent for comparable anonymity protections. Fertility centers exhibit lowest price sensitivity due to bulk procurement power, while single mothers by choice show highest willingness-to-pay for phenotype-matched profiles.
Supply Chain Analysis
Extended payment terms from fertility centers to egg banks now stretch 90-120 days as inventory financing burdens shift upstream toward cryogenic storage operators. Supply concentrates in Spain, the Czech Republic, and Ukraine as donor recruitment hubs, with vitrification technology enabling distribution to satellite clinics across Northern Europe. Raw material dependencies include liquid nitrogen for cryogenic preservation, hormonal stimulation pharmaceuticals, and specialized transport containers maintaining chain-of-custody documentation. Single-source vulnerability runs through Spanish tissue authority accreditation as the gateway to EU-wide patient access. Distribution runs through centralized egg banks serving dispersed fertility center networks rather than direct-to-patient fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, as accreditation under EU Tissues and Cells Directives creates years-long compliance barriers that protect incumbent positions against unlicensed competitors.
For Market Incumbents: Pre-empt donor pool fragmentation by securing exclusive recruitment agreements with Spanish and Czech agencies before legislative shifts toward identification mandates erode anonymity-based supply advantages. Expand cryogenic storage capacity in Texas and California to capture domestic US demand as state-level compensation permissiveness sustains donor supply elasticity against federal restriction threats. For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer matching platforms, where algorithmic donor-recipient pairing bypasses traditional clinic intermediaries and captures margin from information-asymmetric search processes. Target LGBTQ+ couples in Massachusetts and Illinois as the fastest-expanding client segment with unmet demand for legal-clarity bundled services. Deploy preimplantation genetic testing integration as the primary go-to-market wedge against commodity egg banking providers. For Investors and Strategic Acquirers: EU anonymity statute revisions reshape the acquisition landscape toward vertically integrated fertility networks with captive donor recruitment and cryogenic distribution capabilities. Long-term viability favors entities controlling both Spanish-sourced donor pools and US multi-site transfer infrastructure across the projection horizon. Monitor UK Human Fertilisation and Embryology Authority compensation cap adjustments as the critical signal for supply elasticity inflection and cross-border patient flow redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Donor Recruitment Infrastructure Expansion | Spanish tissue authority accreditation secures EU-wide patient access under harmonized quality standards. |
| Vitrification Technology Licensing | Proprietary cryopreservation protocols differentiate centralized egg banks serving dispersed fertility centers. |
| Direct-to-Consumer Platform Development | Algorithmic matching compresses donor-recipient search timelines from weeks to hours. |
| Preimplantation Genetic Testing Integration | PGT-A screening addresses aneuploidy concerns in recipients over 40, commanding premium clinic fees. |
| Cross-Border Compliance Infrastructure | Biometric donor registries satisfy EU Tissues and Cells Directives traceability mandates for multi-country networks. |
Methodological Framework
Cross-validation between reproductive endocrinology practice administrators and egg bank operations directors anchors the qualitative findings, with secondary validation against FDA tissue establishment registration databases and EU member state tissue authority inspection reports. Primary interviews encompassed fertility center procurement managers, donor agency recruitment coordinators, reproductive endocrinologists, and intended parent advocacy organization representatives. Secondary sources included the Human Fertilisation and Embryology Authority annual statistics, Spanish national tissue authority compliance bulletins, and ASRM practice committee guidelines. Bottom-up donor cycle volume estimates from clinic-level reporting triangulate against top-down national fertility registry aggregates.
Calibration against historical cross-border patient flow data and cryopreservation adoption curves informs the analytical framework across the projection horizon. Segmentation dimensions modeled encompass service type, donor profile, client category, and legal framework jurisdiction. CAGRs derive from logistic diffusion curves fitted to vitrification technology penetration rates and donor anonymity statute elasticity estimates. Forecast inputs include reproductive endocrinologist fellowship graduation rates and EU directive implementation variance across member state tissue authorities.
Stress conditions across donor compensation cap adjustments, vitrification survival rate thresholds, and cross-border liability ruling precedents were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory stability and technology adoption trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
In Vitro Fertilization (IVF) Market
Reproductive Health
IVF Services Market
Reproductive Health
Assisted Reproductive Technology (ART) Market
Reproductive Health
Global Cervical Dysplasia Market
Reproductive Health
Europe in Vitro Fertilization (IVF) Market
Reproductive Health
Cryopreservation for in-Vitro Fertilization (IVF) Market
Reproductive Health
Donor Egg IVF (in-Vitro Fertilization) Market
Reproductive Health
Fertility Services Market
Reproductive Health
Cervical Dysplasia Treatment Market
Reproductive Health
Vaginal Exam Specula Market
Reproductive Health
Germany in Vitro Fertilization (IVF) Market
Reproductive Health
US Sexual and Reproductive Health Clinics Market
Reproductive Health
Contraceptives Market
Reproductive Health
Pregnancy Care Products Market
Reproductive Health
Intrauterine Insemination (IUI) Treatment Market
Reproductive Health
Surrogacy Market