
 Global Umbilical Cord Blood Banking Market | 2026-2036
Global Umbilical Cord Blood Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Global Umbilical Cord Blood Banking Market Foresight
Asset-light leasing models for cryogenic storage infrastructure is reconfiguring competitive dynamics, allowing smaller entrants to bypass capital-intensive facility buildouts. Cryo-Cell International leverages its established laboratory network to sustain geographic reach across North American markets. Global Cord Blood Corporation anchors its position through dominant operational scale within China's regulated biobanking sector. FamiCord Group differentiates via specialized processing capabilities across European collection networks.
Umbilical cord blood banking encompasses the procurement, cryopreservation, and long-term storage of hematopoietic stem cells derived from placental tissue at minus 196 degrees Celsius in liquid nitrogen systems, serving therapeutic transplantation and regenerative medicine applications. Processing and storage services command the deepest margin pools due to recurring annual fees and technical complexity barriers. Regenerative medicine applications represent the fastest-expanding category as clinical trials advance beyond traditional oncology indications. Direct enrollment channels are displacing hospital referrals in select markets as digital consumer acquisition tools mature.
The U.S. FDA regulates cord blood units as human cells and tissue products under Section 361 criteria, while the EU's EMA framework through the ATMP classification shapes market access pathways for advanced therapeutic applications. China's NMPA biobanking standards and India's CDSCO tissue banking guidelines create divergent compliance requirements for multinational operators. Stakeholders must monitor evolving regenerative medicine reimbursement decisions across Medicare, national health systems, and private insurers to align service portfolio investments with viable revenue streams.
Market Dynamics
Asset-light leasing models for cryogenic infrastructure are compressing barriers to entry, enabling smaller operators to contest established players without capital-intensive facility investments. This structural shift accelerates competitive fragmentation across North American and European markets.
Growth Catalysts
- Hematopoietic Stem Cell Transplantation Programs:Hospital adoption of cord blood-derived therapies for oncology and blood disorder treatments sustains service demand. Clinical protocol standardization at transplant centers reinforces procurement volumes.
- FDA Section 361 Framework:The U.S. regulatory pathway for human cells and tissue products provides operational clarity, reducing compliance uncertainty for domestic operators. This framework enables faster market entry relative to pharmaceutical-grade licensing.
- Private Banking Preference in China:Expectant parents in tier-one cities demonstrate willingness-to-pay for family-directed biobanking services. NMPA biobanking standards create compliance infrastructure that legitimizes the sector.
Market Restraints
- Liquid Nitrogen Supply Concentration:Industrial gas supply chains concentrate among three multinational suppliers, exposing operators to input cost volatility and regional shortage risk.
- Technical Shelf-Life Limitations:Cryopreserved unit viability degrades after 20-25 years, constraining long-term revenue recognition and requiring periodic reinvestment in collection infrastructure.
- EMA ATMP Classification Friction:Advanced therapy medicinal product pathways impose clinical trial burdens that delay regenerative medicine commercialization, compressing near-term margin expansion.
Strategic Opportunities
- India's Underpenetrated Private Sector:CDSCO tissue banking guidelines establish compliance baselines while market penetration remains below 5% of addressable births. First-mover positioning in Mumbai, Delhi, and Bangalore clusters offers scale advantages.
- Regenerative Medicine Applications:Neurological and metabolic disorder trials expand addressable indications beyond oncology. Early-stage pipeline assets target Parkinson's disease and type 1 diabetes interventions.
- Digital Direct Enrollment Channels:Consumer acquisition platforms displace hospital referral dependencies, reducing customer acquisition costs and enabling geographic expansion without clinical partnerships.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:Specialized biobank operations require cross-trained personnel in cryopreservation protocols and quality management systems. Recruitment competition from pharmaceutical cold chain operators intensifies wage pressure.
- Multi-Jurisdiction Certification Complexity:Operators serving multinational client bases must maintain simultaneous compliance with FDA, EMA, and NMPA standards. Audit synchronization creates administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Umbilical Cord Blood Banking Market |
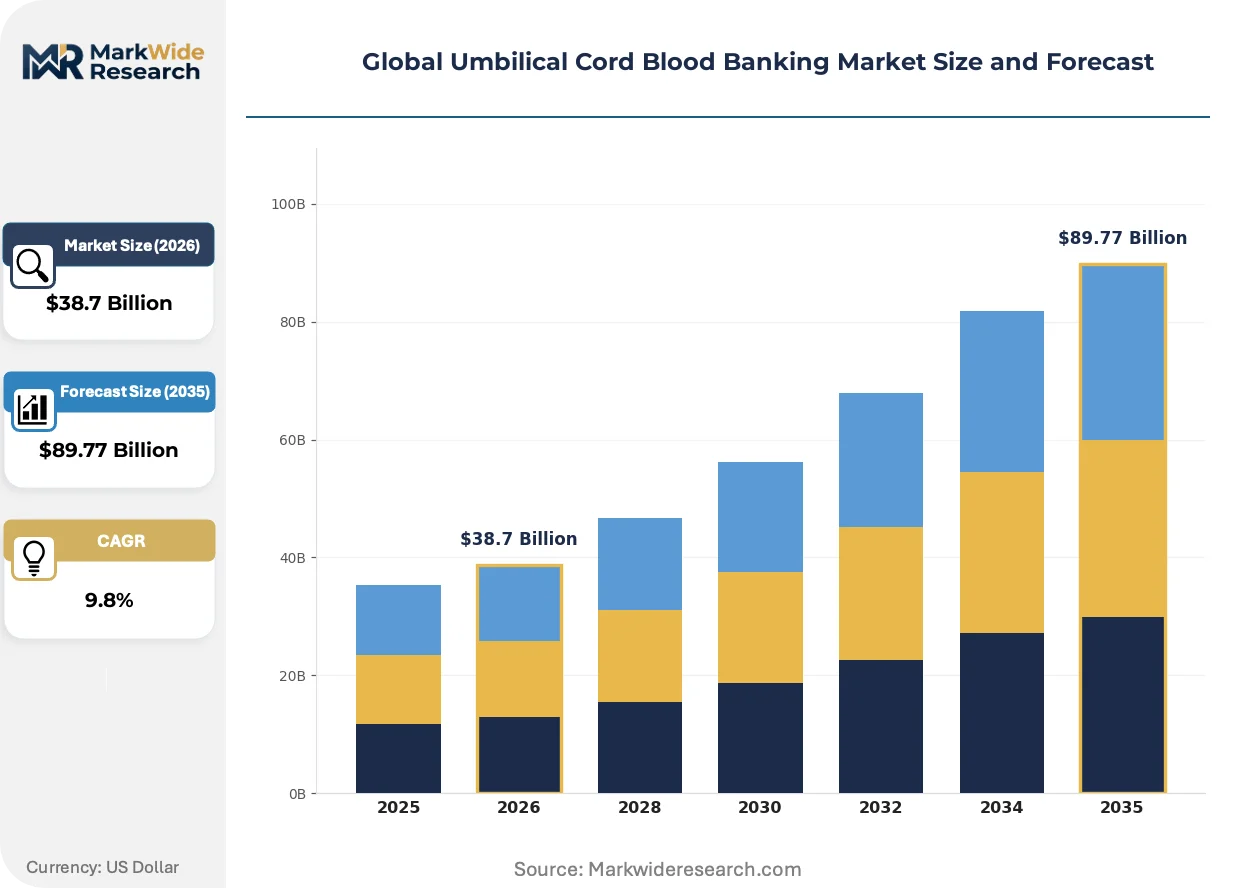
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $89.77 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Processing, Storage, Testing, Transportation Application: Hematopoietic Stem Cell Transplantation, Immune Disorders Treatment, Genetic Disorder Therapy, Regenerative Medicine, Research End User: Hospitals, Research Institutions, Fertility Clinics, Biotechnology Firms, Diagnostic Centers Distribution Channel: Direct Enrollment, Hospitals & Clinics, Online Platforms, Third-Party Providers |
| Companies Covered | Cord Blood Registry (CBR), Cryo-Cell International, ViaCord, Global Cord Blood Corporation, LifeCell International, FamiCord Group, Cordlife Group, StemCyte, Americord Registry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Umbilical Cord Blood Banking Market Shifts & Advancements
Automated processing systems and regulatory harmonization efforts are compressing operational costs while expanding therapeutic applicability beyond traditional transplantation markets.
Automated cell separation platforms integrate robotics with closed-system processing to reduce human error rates in hematopoietic stem cell isolation. Mid-scale biobanks in Germany and the United Kingdom deploy these systems to achieve AABB accreditation without proportional headcount expansion. Manual processing workflows are rendering obsolete in jurisdictions where labor cost inflation exceeds equipment depreciation schedules.
EMA's ATMP classification framework establishes centralized marketing authorization pathways for cord blood-derived advanced therapies. This regulatory architecture enables cross-border service standardization across EU member states while imposing Good Manufacturing Practice requirements that favor capitalized operators. German and French biobanks invest in quality management system upgrades to secure manufacturing authorizations ahead of regenerative medicine commercialization.
Expectant parents increasingly evaluate biobank options through direct digital channels rather than obstetrician referrals. Consumer review platforms and subscription-based pricing models disrupt traditional hospital-centric distribution in the United States and Australia. This channel migration concentrates marketing expenditure on search engine optimization and telehealth consultation infrastructure rather than clinical liaison programs.
Global Umbilical Cord Blood Banking Market Segmentation
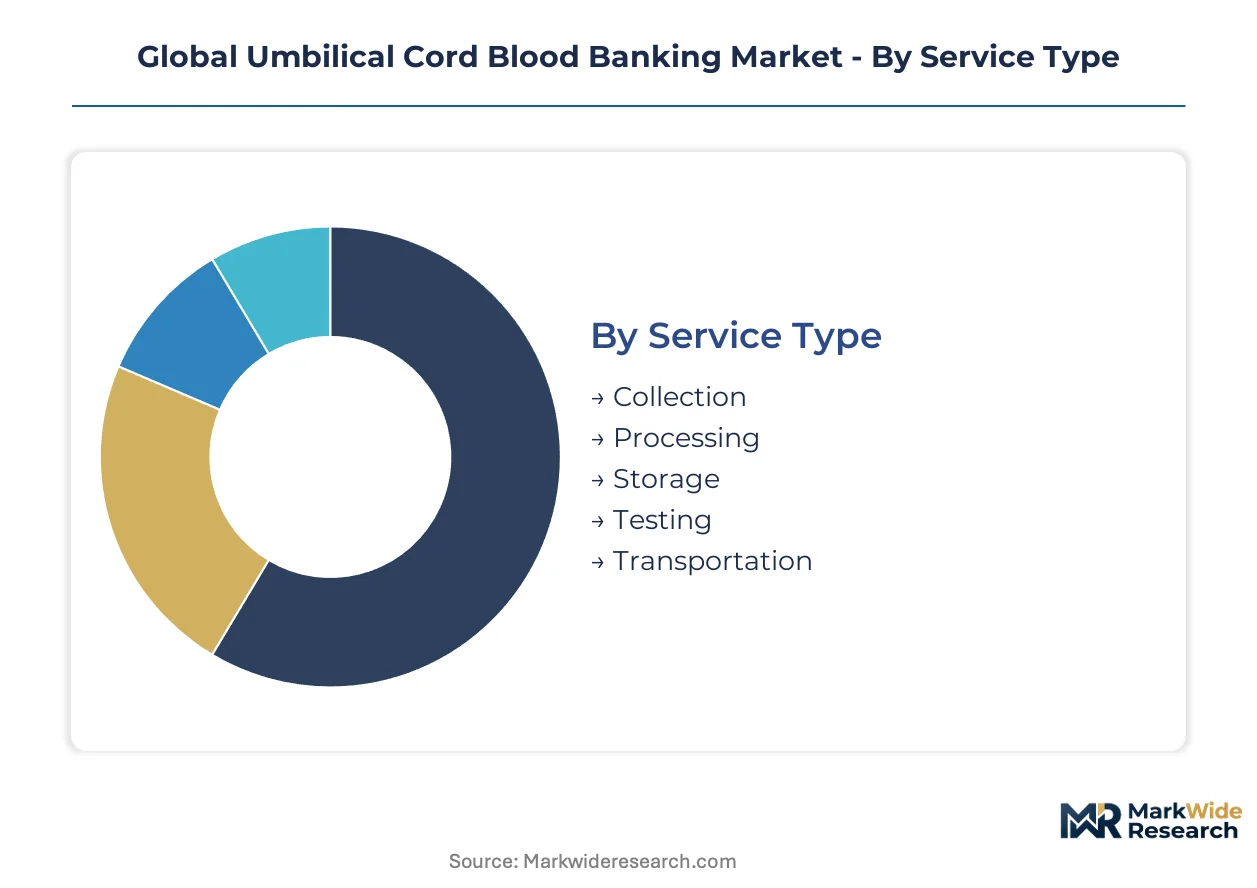
Service configuration across the umbilical cord blood banking sector determines recurring revenue durability and capital intensity requirements. Segment-specific operational models create divergent margin profiles and customer retention mechanics.
Service Type:
After-sales service intensity varies dramatically across the service spectrum, with cryogenic storage commanding perpetual monitoring obligations and annual renewal interactions.
- Storage:Liquid nitrogen systems maintain hematopoietic stem cells at minus 196 degrees Celsius through vapor-phase or liquid-phase containment. Demand concentrates among private banking clients in the United States, China, and India where multi-decade contracts generate predictable recurring revenue streams.
- Processing:Automated cell separation platforms isolate mononuclear fractions through density gradient centrifugation and volume reduction protocols. Hospital transplant programs in Germany and the United Kingdom drive specification requirements for AABB-accredited processing workflows.
- Collection:Obstetric collection kits require sterile procurement materials and temperature-controlled logistics chains.
- Testing:Infectious disease screening and HLA typing services verify unit viability and compatibility.
- Transportation:Cryogenic shipping containers maintain cold chain integrity during inter-facility transfers.
Storage holds the largest share; momentum sits with Processing as automation investments accelerate.
Application:
Application segmentation traces therapeutic maturity, with established oncology protocols subsidizing experimental regenerative medicine development.
- Hematopoietic Stem Cell Transplantation:Cord blood units replace bone marrow grafts for leukemia and lymphoma interventions through reduced graft-versus-host disease risk. Transplant centers at Johns Hopkins and Peking Union Medical College Hospital anchor procurement volumes through standardized clinical protocols.
- Regenerative Medicine:Neurological and metabolic disorder trials target Parkinson's disease and type 1 diabetes through immunomodulatory and tissue repair mechanisms. Early-phase studies at Duke University and Shenzhen-based biotech clusters expand addressable indications beyond oncology.
- Immune Disorders Treatment:Severe combined immunodeficiency and Wiskott-Aldrich syndrome protocols utilize cord blood-derived hematopoietic reconstitution.
- Genetic Disorder Therapy:Hurler syndrome and Krabbe disease interventions leverage enzyme replacement compatibility through early transplantation windows.
- Research:Academic institutions utilize banked units for stem cell biology and immunology investigations.
Hematopoietic Stem Cell Transplantation dominates current utilization; Regenerative Medicine is climbing the fastest as pipeline assets advance through clinical trials.
End User:
End user configuration shapes facility certification requirements and sales cycle complexity across institutional procurement processes.
- Hospitals:Transplant centers and maternity wards generate dual demand streams for allogeneic public banking and autologous private services. Tertiary medical centers in Mumbai, Delhi, and Bangalore clusters within India's underpenetrated market offer first-mover scale advantages.
- Research Institutions:Academic medical centers and government laboratories procure units through grant-funded mechanisms with extended payment cycles.
- Fertility Clinics:Assisted reproduction facilities bundle banking services with prenatal care packages.
- Biotechnology Firms:Cell therapy developers source research-grade and clinical-grade units for manufacturing process development.
- Diagnostic Centers:Independent laboratories perform HLA matching and infectious disease screening as outsourced service providers.
Hospitals command the deepest volume concentration; biotechnology firms are expanding most quickly as cell therapy manufacturing scales.
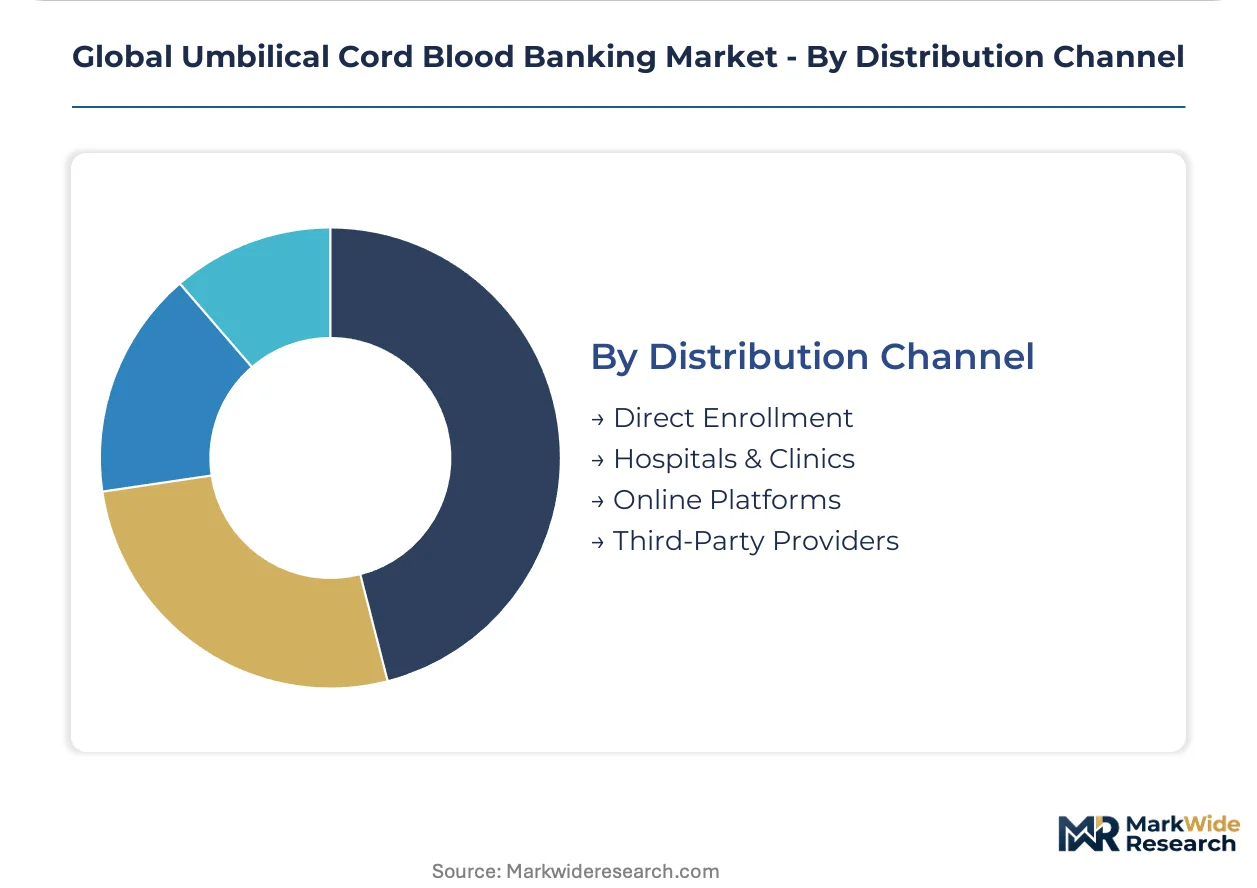
Distribution Channel:
Channel structure determines customer acquisition economics and geographic reach without clinical partnership dependencies.
- Direct Enrollment:Digital platforms and telehealth consultations enable expectant parent acquisition independent of obstetrician referrals. Consumer review aggregation and subscription pricing models disrupt traditional hospital-centric distribution in the United States and Australia.
- Hospitals & Clinics:Obstetric department partnerships embed banking decisions within standard prenatal care workflows through physician recommendation networks.
- Online Platforms:E-commerce marketplaces and comparison engines aggregate biobank options through search-optimized consumer journeys.
- Third-Party Providers:Insurance brokers and employee benefit administrators bundle banking services with supplemental health coverage.
Hospitals & Clinics retains the largest transaction volume; Direct Enrollment is gaining share fastest as digital consumer acquisition tools mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The umbilical cord blood banking sector exhibits pronounced geographic asymmetry in service penetration. The United States and China generate substantial domestic demand while maintaining limited cross-border service flows. India represents a net importer of processing technologies and cryogenic infrastructure components.
United States
Hospital transplant programs at Johns Hopkins and Duke University sustain procurement volumes for hematopoietic stem cell therapies. FDA Section 361 framework provides operational clarity for human cells and tissue products, reducing compliance uncertainty relative to pharmaceutical-grade pathways. California and Texas clusters concentrate private banking enrollment through direct-to-consumer digital platforms.
China
Tier-one city expectant parents demonstrate willingness-to-pay for family-directed biobanking services in Beijing and Shanghai. NMPA biobanking standards establish compliance infrastructure that legitimizes sector operations. Shenzhen-based biotech clusters advance regenerative medicine trials targeting neurological applications beyond traditional oncology.
India
Mumbai, Delhi, and Bangalore maternity wards generate underpenetrated demand with market penetration below 5% of addressable births. CDSCO tissue banking guidelines create compliance baselines for private sector operators. Maharashtra and Karnataka states attract first-mover biobank investments seeking scale advantages in high-birth-volume corridors.
Germany
AABB-accredited processing workflows at mid-scale biobanks serve hospital transplant programs across Bavaria and North Rhine-Westphalia. EMA ATMP classification imposes Good Manufacturing Practice requirements favoring capitalized operators. Frankfurt and Munich clusters invest in quality management system upgrades ahead of regenerative medicine commercialization.
United Kingdom
Automated cell separation platforms deploy across German and UK biobanks to achieve accreditation without proportional headcount expansion. NHS procurement frameworks shape public banking economics while private operators compete through digital enrollment channels. London and Cambridge academic medical centers anchor research-grade unit demand for immunology investigations.
Global Umbilical Cord Blood Banking Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in cryogenic infrastructure and processing automation. The vendor base stratifies across three tiers: multinational operators with laboratory networks, regional specialists with geographic concentration, and asset-light entrants leasing storage capacity. Strategic archetypes include scale-driven incumbents, technology-forward processors, and digital-native direct enrollment platforms. Competitive moves concentrate on M&A for laboratory network expansion and strategic partnerships for regenerative medicine pipeline access.
Within the scale-driven tier, Global Cord Blood Corporation and Cryo-Cell International occupy positions reflecting divergent geographic anchoring. FamiCord Group exemplifies the European specialist archetype with processing capabilities across collection networks. Cord Blood Registry and ViaCord represent the North American platform model with established consumer acquisition infrastructure. These operators illustrate how regulatory compliance investments and cryogenic asset configuration determine competitive positioning across distinct national frameworks.
| Leading Market Players |
|---|
| Cord Blood Registry (CBR) |
| Cryo-Cell International |
| ViaCord |
| Global Cord Blood Corporation |
| LifeCell International |
| FamiCord Group |
| Cordlife Group |
| StemCyte |
| Americord Registry |
| Others |
Supply & Pricing Matrix
Underutilized cryogenic storage capacity in North American metropolitan clusters is compressing lease rates for liquid nitrogen infrastructure and forcing asset-light entrants to compete on annual storage fees rather than service differentiation. This surplus drives incumbent operators toward bundled processing-and-storage contracts to defend margin pools.
Pricing Analysis
Expectant parents in tier-one cities anchor subscription-based pricing structures for multi-decade storage contracts. Three-tier pricing structure across premium, standard, and economy levels separates AABB-accredited units from standard-processed and research-grade inventories. Cost compression in economy tiers is intensifying because automated processing platforms reduce labor overhead. Price sensitivity concentrates among first-time parents in underpenetrated Indian markets, while repeat-birth households in the United States demonstrate lower elasticity.
Supply Chain Analysis
Industrial liquid nitrogen production draws from concentrated air-separation facilities in the United States, Germany, and China. Cryogenic storage vessels, automated cell separation platforms, and temperature-controlled logistics containers constitute critical input dependencies. Single-source vulnerability in specialty alloy procurement for dewar manufacturing exposes operators to extended lead times. Distribution runs through hospital partnerships in established markets and direct-to-consumer digital channels in emerging geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regenerative medicine pipeline advancement represents a high-growth disruption as FDA Section 361 pathways expand toward ATMP-classified indications, creating dual-revenue potential beyond transplantation services.
For Market Incumbents: Pre-empt asset-light competitors by securing exclusive obstetric partnerships in Mumbai and Bangalore corridors where CDSCO compliance infrastructure remains sparse. Accelerate AABB accreditation investments to differentiate automated processing capabilities against manual workflows. Defend storage revenue through long-term contract lock-in before digital enrollment platforms mature.
For New Entrants and Emerging Players: India's underpenetrated private sector below 5% of addressable births represents the most penetrable entry point for regional laboratory networks. Shenzhen-based biotech clusters offer partnership pathways for regenerative medicine pipeline access. Direct enrollment via telehealth consultation infrastructure bypasses hospital referral dependencies entirely.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among operators with established liquid nitrogen storage infrastructure and multi-decade contract backlogs. Five-to-ten-year viability hinges on regenerative medicine commercialization timelines. Acquisition targets should demonstrate simultaneous FDA, EMA, and NMPA certification readiness. Monitor EMA ATMP manufacturing authorization decisions as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | Simultaneous FDA, EMA, and NMPA compliance unlocks multinational client bases without audit duplication. |
| Automated Processing Platform Deployment | Robotics integration at German and UK biobanks achieves AABB accreditation without proportional headcount expansion. |
| Direct Enrollment Channel Development | Telehealth infrastructure in California and Texas clusters displaces obstetrician referral dependencies. |
| Regenerative Medicine Pipeline Partnership | Early-stage trial access at Duke University and Shenzhen biotech clusters expands addressable indications. |
| Geographic Laboratory Network Expansion | Mumbai, Delhi, and Bangalore facility investments capture first-mover advantages in underpenetrated Indian corridors. |
Research Methodology
Initial hypotheses were tested against primary input from cord blood bank operations directors, transplant center procurement managers, regulatory affairs specialists at biobank operators, and expectant parent focus groups and refined through secondary validation. FDA 510(k) filings, EMA ATMP designation records, CDSCO tissue banking registration databases, and NMPA biobank facility inspection reports anchored quantitative baselines. Bottom-up service volume estimates triangulated against top-down healthcare expenditure allocations across the analysis window.
Demand-supply balance modeling incorporated hematopoietic stem cell transplantation program expansion rates, liquid nitrogen infrastructure capacity utilization, and regenerative medicine clinical trial enrollment trajectories. Segmentation dimensions spanned service type, application category, end-user institution, and distribution channel. CAGRs were derived from logistic growth curve fitting to historical procurement volumes. Cryogenic storage contract renewal rates and automated processing adoption curves served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement policy, industrial gas pricing volatility, or cross-border biobank regulatory harmonization would shift the trajectory. Forecasts embed assumptions regarding EMA ATMP pathway maturation and FDA Section 361 enforcement continuity. Cross-checking against hospital transplant center procurement databases and national birth registry projections is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Concierge Medicine Market
Healthcare Services
Vaccine Transport Carrier Market
Healthcare Services
Global Sperm Bank Market
Healthcare Services
Healthcare Physician Staffing Market
Healthcare Services
US Primary Care Physicians Market
Healthcare Services
Medical Peer & External Physician Review Services Market
Healthcare Services
Global Retirement Home Services Market
Healthcare Services
Medical Social Working Services Market
Healthcare Services
Assisted Living Market
Healthcare Services
Surgical Fluid Disposal Market
Healthcare Services
Medical Billing Outsourcing Market
Healthcare Services
India Senior Living Market
Healthcare Services
Global Cord Blood Banking Services Market
Healthcare Services
Global Geriatric Care Services Market
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
Biopharmaceutical Third Party Logistics (3PL) Market