
 Cerebral Spinal Fluid (CSF) Management Market | 2026-2036
Cerebral Spinal Fluid (CSF) Management Market Size, Share, and Industry Trends Forecast 2026-2036
Cerebral Spinal Fluid (CSF) Management Market Intelligence
The direct sales channel to individual hospitals is tilting towards consolidated purchasing through large hospital networks and Group Purchasing Organizations. Medtronic leverages its extensive portfolio and global reach in the neurosurgery space. Integra LifeSciences Corporation differentiates through its focus on specialized neurosurgical and regenerative technology products. B. Braun Melsungen AG sustains a strong position through its established distribution channels, particularly within Germany and other European countries.
Cerebral Spinal Fluid (CSF) management encompasses medical devices used to regulate CSF flow and pressure, such as shunts incorporating silicone catheters and programmable valves. Their primary purpose is to treat conditions like hydrocephalus by redirecting excess CSF to alleviate intracranial pressure. CSF shunts constitute the largest product segment, while external drainage systems are critical for acute management. Hospitals perform the majority of procedures, but specialty centers are an increasingly important end-user for complex cases.
Regulatory bodies like the FDA in the United States, the EMA in Europe, and China's NMPA mandate rigorous clinical trials and post-market surveillance for CSF management devices. These regulations ensure patient safety and device efficacy but also create significant hurdles for new market entrants. The next strategic decision for manufacturers involves navigating reimbursement landscapes while investing in advanced technologies like MRI-compatible shunts.
Market Dynamics
The central dynamic shaping the market is the tension between stringent regulatory frameworks, like the EU's MDR, and the clinical demand for more sophisticated, patient-specific devices such as programmable valves and MRI-safe shunts for treating hydrocephalus.
Growth Catalysts
- Programmable Valve Technology:The development of non-invasive, externally adjustable shunt valves allows for personalized pressure settings post-surgery, reducing the need for revision procedures and improving patient outcomes in specialty hydrocephalus centers.
- Aging Global Demographics:A rising incidence of Normal Pressure Hydrocephalus (NPH) in elderly populations, particularly in developed nations like Japan and Germany, is expanding the patient base requiring CSF management interventions.
- Healthcare Infrastructure Expansion:Government and private investment in neurosurgical capabilities within emerging economies is improving access to diagnosis and treatment, creating new demand for CSF shunts and drainage systems.
Market Restraints
- Strict Regulatory Hurdles:Regulations such as the EU's MDR and the FDA's premarket approval process impose lengthy and costly clinical validation requirements, creating significant barriers to entry for new device manufacturers.
- High Procedure Costs:The total cost of care, including the device, implantation surgery, and post-operative management, can be prohibitive, with reimbursement policies varying significantly across different national healthcare systems.
- Shunt-Related Complications:Persistent risks of device failure, infection, and blockages associated with CSF shunts necessitate revision surgeries, which adds to healthcare costs and impacts patient quality of life.
Strategic Opportunities
- Sensor Integration and Telemetry:Incorporating micro-sensors into shunts to enable real-time, remote monitoring of intracranial pressure presents a major opportunity for proactive patient management and data-driven clinical decisions.
- Underpenetrated Markets:There is significant untapped demand in countries like Brazil and India, where growing middle-class populations and improving healthcare access are creating new markets for advanced neurosurgical devices.
- Antimicrobial Catheter Coatings:Developing and commercializing catheters with novel antimicrobial or anti-biofilm properties to reduce the high rate of shunt-associated infections offers a clear path for product differentiation.
Industry Challenges
- Specialized Surgical Training:The effective implantation and management of advanced programmable shunts require specialized neurosurgical expertise, creating a skills gap that can limit adoption in regions with fewer trained specialists.
- Post-Market Surveillance Demands:Meeting the intensified post-market surveillance and data collection mandates from regulators like the FDA and EMA requires significant, ongoing investment in clinical follow-up and reporting systems.
- Interoperability of Systems:A lack of standardization among different manufacturers' shunt programmers and diagnostic tools creates challenges for clinicians in hospitals that use devices from multiple vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cerebral Spinal Fluid (CSF) Management Market |
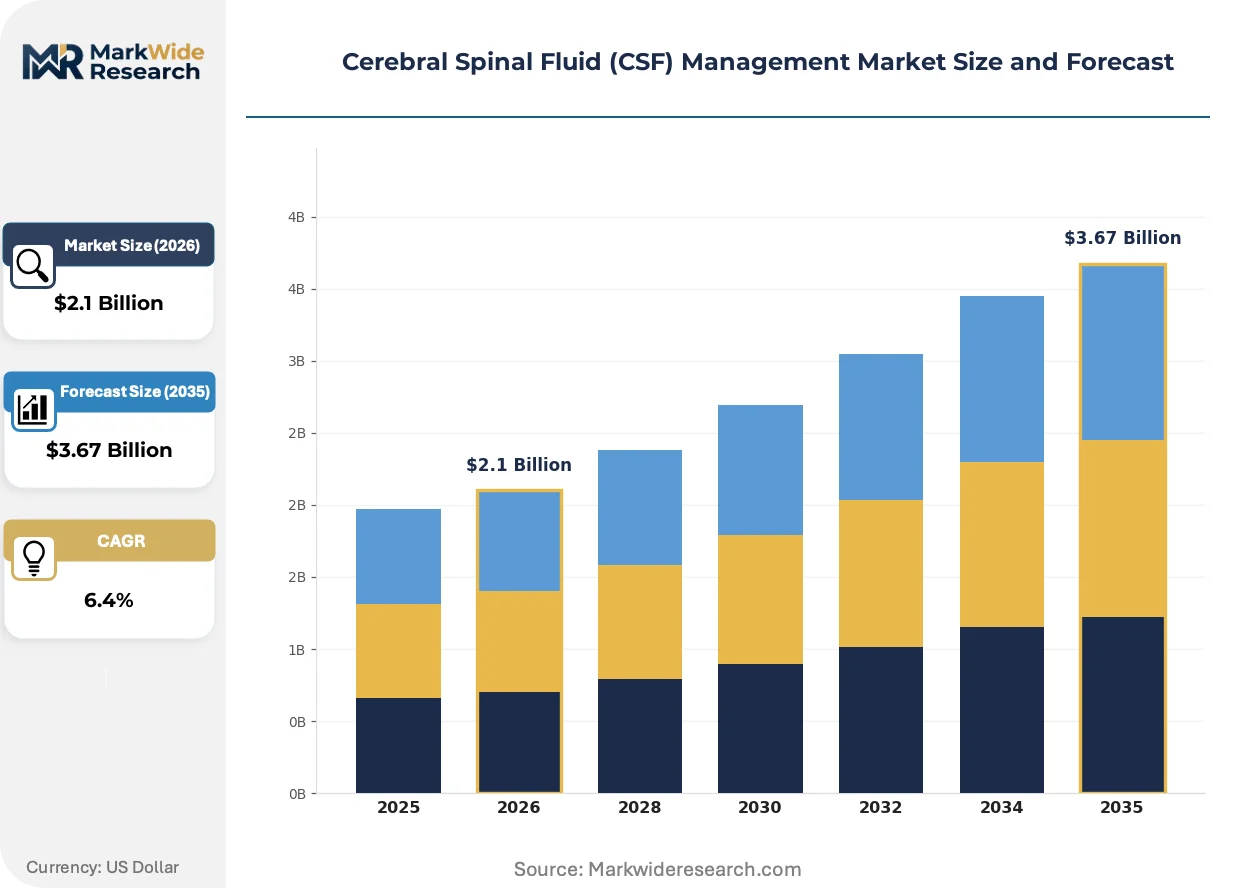
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CSF Shunts, Manometers, Drainage Systems, Collection Containers End User: Hospitals, Clinics, Specialty Centers, Research Facilities Delivery Mode: Invasive Techniques, Non-Invasive Techniques, Remote Monitoring, Preoperative Assessment Application: Diagnostics, Therapeutics, Research, Emergency Care |
| Companies Covered | Medtronic, B. Braun Melsungen AG, Integra LifeSciences Corporation, Spiegelberg GmbH & Co. KG, Sophysa, Natus Medical Incorporated, BeckerSmith Medical, CHRISTOPH MIETHKE GMBH & CO. KG, CereVasc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cerebral Spinal Fluid (CSF) Management Market Strategic Shifts & Innovations
Technological advancement is focused on creating smarter, more durable devices that reduce long-term patient complications. This innovation push is occurring within an environment of heightened regulatory scrutiny, compelling manufacturers to provide robust clinical evidence for both new and existing products.
Advanced programmable shunt valves allow neurosurgeons to adjust pressure settings non-invasively using an external magnetic device. Adoption is accelerating within specialized pediatric and adult hydrocephalus centers that manage complex cases. This technology is rendering obsolete older fixed-pressure shunt designs, which often necessitated invasive surgical revisions to alter CSF drainage levels and address over- or under-drainage complications.
The European Union's Medical Device Regulation (MDR) has significantly increased the burden of proof for device safety and efficacy. Its implementation is forcing manufacturers to conduct new clinical studies and enhance post-market surveillance even for long-established products to maintain market access. CSF shunt and catheter manufacturers are particularly affected, needing to re-certify their entire portfolios under the more stringent CE marking requirements.
Consolidated purchasing by large hospital networks and Group Purchasing Organizations (GPOs) is altering traditional sales models. This trend disrupts the direct-to-surgeon relationship that historically drove device selection, shifting power to administrators who prioritize cost-effectiveness and supplier standardization. The shift is most visible in the United States and Germany, favoring large manufacturers with broad portfolios capable of securing network-wide contracts.
Cerebral Spinal Fluid (CSF) Management Market Segmentation
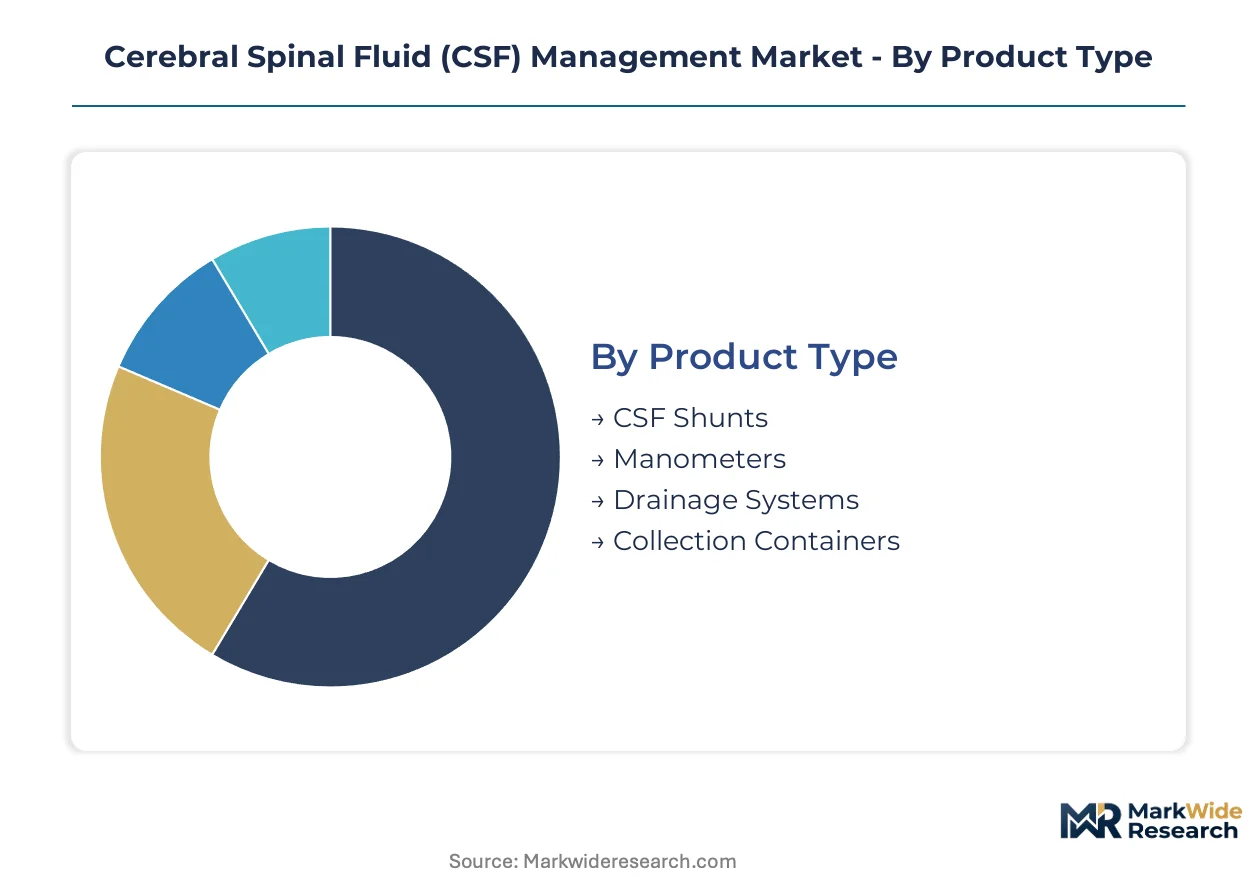
Understanding the segmentation within the Cerebral Spinal Fluid (CSF) management market clarifies where demand concentrates and how specific product attributes drive adoption. This detailed breakdown helps manufacturers align product development with clinical needs and end-user preferences across diverse healthcare environments.
Product Type:
The after-sales service intensity of CSF management devices significantly influences product type selection and long-term patient care. Maintenance requirements and the potential for revision surgeries impact the overall cost-effectiveness of each solution.
- CSF Shunts:These medical devices, primarily silicone catheters with programmable valves, regulate CSF flow and pressure to treat hydrocephalus. Demand concentrates in advanced neurosurgical centers in Germany and the United States, driven by the need for personalized pressure management and reduced revision surgeries.
- Manometers:These devices precisely measure CSF pressure, crucial for diagnosis and post-surgical monitoring of conditions like idiopathic intracranial hypertension.
- Drainage Systems:External ventricular and lumbar drainage systems manage acute intracranial pressure by diverting CSF temporarily. Hospitals, particularly in urban areas with high trauma incidence, drive demand for these critical devices in emergency and post-operative care.
- Collection Containers:Sterile containers gather CSF from shunts or drainage systems for diagnostic analysis, ensuring proper sample integrity.
By volume, CSF Shunts lead. By growth pace, Drainage Systems are ahead.
End User:
Customer type preferences dictate procurement strategies and the integration of advanced CSF management technologies across healthcare settings. Each end-user segment has distinct requirements for device complexity, training, and cost structures.
- Hospitals:General hospitals perform the majority of CSF management procedures, particularly for acute hydrocephalus and emergency interventions. Procurement patterns in the United States and Germany increasingly favor consolidated purchasing through large networks, impacting supplier selection.
- Clinics:Outpatient clinics primarily handle follow-up care and routine monitoring for patients with implanted CSF management devices.
- Specialty Centers:Dedicated hydrocephalus and neurosurgical centers manage complex and pediatric cases, often adopting advanced programmable shunt technologies. These centers in Japan and the EU prioritize devices that improve long-term patient outcomes and reduce revision rates.
- Research Facilities:These institutions utilize CSF management tools for studies on neurological disorders and device innovation, driving demand for specialized experimental setups.
The largest customer segment remains Hospitals, while Specialty Centers exhibit strong expansion.
Delivery Mode:
Application-specific requirements drive the development and adoption of various delivery modes, from surgical interventions to remote monitoring solutions. The choice of delivery mode impacts patient comfort, recovery time, and long-term management strategies.
- Invasive Techniques:These involve surgical implantation of devices like CSF shunts and external drainage systems to directly manage intracranial pressure. Procedures are critical for hydrocephalus treatment in countries with advanced neurosurgical infrastructure, including the United States.
- Non-Invasive Techniques:This category includes external programming of shunt valves and diagnostic imaging, minimizing patient discomfort and revision surgeries. Adoption is rising in pediatric hydrocephalus centers that seek to optimize patient care and reduce intervention frequency.
- Remote Monitoring:Emerging technologies integrate sensors into shunts for real-time, off-site intracranial pressure data, enabling proactive patient management.
- Preoperative Assessment:Diagnostic imaging and physiological evaluations determine the necessity and type of CSF management intervention before surgery.
The dominant method is Invasive Techniques, with Non-Invasive Techniques showing considerable promise.
Application:
The maturity level of different application areas shapes investment priorities and technological advancements within the CSF management sector. Each application addresses specific clinical needs, influencing device design and market demand.
- Diagnostics:This segment involves identifying conditions requiring CSF management through imaging and pressure measurement techniques.
- Therapeutics:This application focuses on treating conditions like hydrocephalus by redirecting or draining excess CSF to alleviate intracranial pressure. Programmable shunt valves are central to therapeutic interventions, particularly in developed markets like Germany and Japan, which face aging populations.
- Research:Investigating new device designs, materials, and treatment protocols for CSF-related neurological disorders falls under this application.
- Emergency Care:Rapid intervention for acute hydrocephalus or intracranial hemorrhage requires prompt CSF drainage to prevent severe neurological damage. Hospitals in regions with robust trauma centers, such as the United States, drive demand for external drainage systems in these critical situations.
While Therapeutics constitutes the primary application, Emergency Care is an area gaining momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced neurosurgical infrastructure across key global regions underwrites their significant roles in the Cerebral Spinal Fluid (CSF) management market. Robust hospital networks and specialty centers drive demand for sophisticated devices. These regions also possess stringent regulatory bodies ensuring device safety and efficacy.
United States
The United States market is driven by a high incidence of acute hydrocephalus and extensive adoption of advanced programmable shunt technologies. The FDA's stringent premarket approval process ensures device efficacy and safety for patients. Major medical device clusters, such as those in Boston, foster innovation in CSF management solutions.
Germany
Germany's market reflects an aging population, leading to a rising incidence of Normal Pressure Hydrocephalus requiring CSF management interventions. The EU's Medical Device Regulation (MDR) significantly influences product development and market access for new devices. Bavaria, a prominent medical technology hub, sees strong adoption of specialized neurosurgical products.
Japan
Japan's elderly population contributes to an expanding patient base for Normal Pressure Hydrocephalus, driving demand for CSF management devices. The PMDA mandates rigorous clinical trials and post-market surveillance for new device approvals. Advanced medical research facilities in Tokyo prioritize devices improving long-term patient outcomes and reducing revision rates.
India
India presents significant untapped demand, propelled by improving healthcare access and a growing middle class seeking advanced medical solutions. The CDSCO regulates medical device imports and manufacturing, ensuring product quality and safety standards. Bangalore's growing medical technology sector is attracting investment in neurosurgical device development.
Brazil
Brazil's expanding neurosurgical infrastructure and increasing diagnosis rates are creating new demand for CSF shunts and drainage systems. ANVISA oversees medical device registration and post-market vigilance, ensuring product safety within the country. São Paulo's prominent healthcare facilities are at the forefront of adopting advanced neurosurgical devices.
Cerebral Spinal Fluid (CSF) Management Market Key Industry Players
On the supply side, the industry is characterized by a mix of established global players and specialized innovators. Consolidation efforts are visible as larger entities seek to expand their neurosurgical portfolios. Key strategic archetypes include diversified medical device giants, specialized neurosurgical technology firms, and regional manufacturers with strong distribution networks. Companies are pursuing both portfolio diversification and strategic partnerships to strengthen their market presence.
Diversified medical technology companies like Medtronic leverage extensive portfolios and global reach within the neurosurgery space, often securing broad network contracts. Integra LifeSciences Corporation, for example, exemplifies a specialized firm focusing on advanced neurosurgical and regenerative technology products, differentiating through innovation. German-based B. Braun Melsungen AG sustains a strong position through established distribution channels, particularly across European countries, maintaining a significant regional footprint. These entities collectively shape the competitive dynamics through continuous product innovation and strategic market access initiatives, addressing diverse clinical needs.
| Leading Market Players |
|---|
| Medtronic |
| B. Braun Melsungen AG |
| Integra LifeSciences Corporation |
| Spiegelberg GmbH & Co. KG |
| Sophysa |
| Natus Medical Incorporated |
| BeckerSmith Medical |
| CHRISTOPH MIETHKE GMBH & CO. KG |
| CereVasc |
| Others |
Cost & Logistics Intelligence
Bavaria's robust medical technology hub, with its specialized manufacturing capabilities for CSF devices, influences pricing power across European markets. Its concentrated production capacity impacts the cost structures for advanced neurosurgical devices.
Pricing Analysis
Premium-mid-economy pricing differentiation characterizes the CSF management market, driven by device complexity and after-sales service bundles. Device quality, particularly MRI-compatibility and programmable features, commands higher prices. Consolidated purchasing by large hospital networks and GPOs in the United States and Germany exerts downward pricing pressure. Specialty centers, focused on patient outcomes, exhibit lower price sensitivity compared to general hospitals.
Supply Chain Analysis
The supply chain for CSF management devices draws heavily from specialized silicone and precision metal component manufacturers. Geographic supply concentrates in Germany, the United States, and Japan, which possess advanced medical device manufacturing ecosystems. Single-source vulnerability for highly specialized programmable valve components presents a structural risk. Distribution runs through direct sales channels to hospitals, increasingly shifting towards consolidated purchasing by Group Purchasing Organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cerebral Spinal Fluid (CSF) management market represents a high-growth disruption, driven by advanced programmable valve technology and stringent regulatory shifts like the EU MDR. These forces compel manufacturers to innovate while ensuring robust clinical evidence.
For Market Incumbents: Pre-empt emerging threats from specialized innovators by investing heavily in sensor integration and antimicrobial catheter coatings. Deepen portfolio diversification to offer comprehensive solutions that meet evolving regulatory demands, particularly under the EU MDR. Leverage existing global reach and established distribution channels to secure network-wide contracts with large hospital systems. Form strategic partnerships to address specialized surgical training gaps in emerging economies. For New Entrants and Emerging Players: Establish a beachhead in underpenetrated markets like India and Brazil by offering cost-effective, high-quality CSF shunts. Focus on niche technologies such as advanced antimicrobial catheter coatings or specialized MRI-compatible shunts. Target specialty centers that prioritize innovation and improved patient outcomes. Develop robust clinical evidence from the outset to navigate stringent regulatory hurdles effectively. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among firms providing advanced, long-term implantable solutions for chronic hydrocephalus, given the aging global demographics. Target specialized neurosurgical technology firms with strong intellectual property in programmable valves or sensor integration. These entities offer sustained growth potential. Watch for accelerated adoption rates of MRI-compatible shunts and regulatory approvals for novel antimicrobial devices as key inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Recertification | Ensures continued market access in the European Union under stringent MDR requirements for CSF shunt manufacturers. |
| Hospital Network Integration | Secures preferred supplier status and volume contracts with large purchasing organizations in the United States and Germany. |
| Sensor Integration R&D | Enables remote monitoring of intracranial pressure, improving proactive patient management and reducing revision surgeries. |
| Antimicrobial Catheter Development | Addresses shunt-related infection risks, a critical complication impacting patient quality of life and healthcare costs. |
| Emerging Market Entry | Captures untapped demand in countries like India and Brazil, expanding the patient base for advanced neurosurgical devices. |
Research Approach
A standing panel of neurosurgeons, biomedical engineers, and hospital procurement managers provided ongoing calibration for market sizing and forecast validation. This primary input was triangulated with extensive secondary research from FDA filings, EMA submissions, and clinical trial registries. The analysis integrated both bottom-up and top-down approaches to ensure robust data integrity.
The forecast framework employed scenario bracketing, projecting market trajectories across the analysis window based on various growth assumptions. Segmentation dimensions modeled included product type, end user, delivery mode, application, and regional regulatory clusters. Compound Annual Growth Rates were derived through regression analysis, validated by expert consensus. Key inputs included hydrocephalus incidence rates and neurosurgical procedure volumes.
Stress conditions across regulatory shifts and technological breakthroughs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding clinical adoption and reimbursement stability. Cross-checking against national health statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Neurological Biomarkers Market
Neurology
Brain Aneurysm Treatment Market
Neurology
Mild Cognitive Impairment Market
Neurology
United Kingdom Neurology Devices Market
Neurology
Chile Neurology Devices Market
Neurology
Optic Neuropathy Management Market
Neurology
US Optic Neuritis Market
Neurology
Demyelinating Diseases Therapeutics Market
Neurology
Central Nervous System Lymphoma Treatment Market
Neurology
Cognitive Neuroscience Market
Neurology
Moyamoya Disease Market
Neurology
Cervical Dystonia Treatment Market
Neurology
Global Acoustic Neuroma Market
Neurology
Peripheral Neuritis Treatment Market
Neurology
3D Neuroscience Market
Neurology
Global Sciatica Treatment Market