
 Healthcare Revenue Cycle Management (RCM) Outsourcing Market | 2026-2036
Healthcare Revenue Cycle Management (RCM) Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Revenue Cycle Management (RCM) Outsourcing Market Foresight
Certified medical coder shortages across the United States are redrawing competitive boundaries in healthcare revenue cycle outsourcing. Optum leverages its integrated payer-provider data infrastructure to anchor large health system contracts. R1 RCM specializes in end-to-end hospital revenue partnerships, while Ensemble Health Partners competes through technology-enabled operational transformation at academic medical centers.
Healthcare Revenue Cycle Management outsourcing encompasses the delegation of financial administrative processes—from patient registration and charge capture through claims submission, payment posting, and denial management—to third-party vendors operating under HIPAA and institutional compliance frameworks. The practice eliminates fixed labor costs while accelerating cash conversion through specialized expertise in payer contract negotiation and regulatory coding updates. Cloud-based delivery models represent the fastest-expanding architecture as hospitals prioritize elastic capacity and remote workforce enablement. Billing services occupy the largest service-type revenue pool, though artificial intelligence-augmented coding verification is emerging as the highest-margin technology layer.
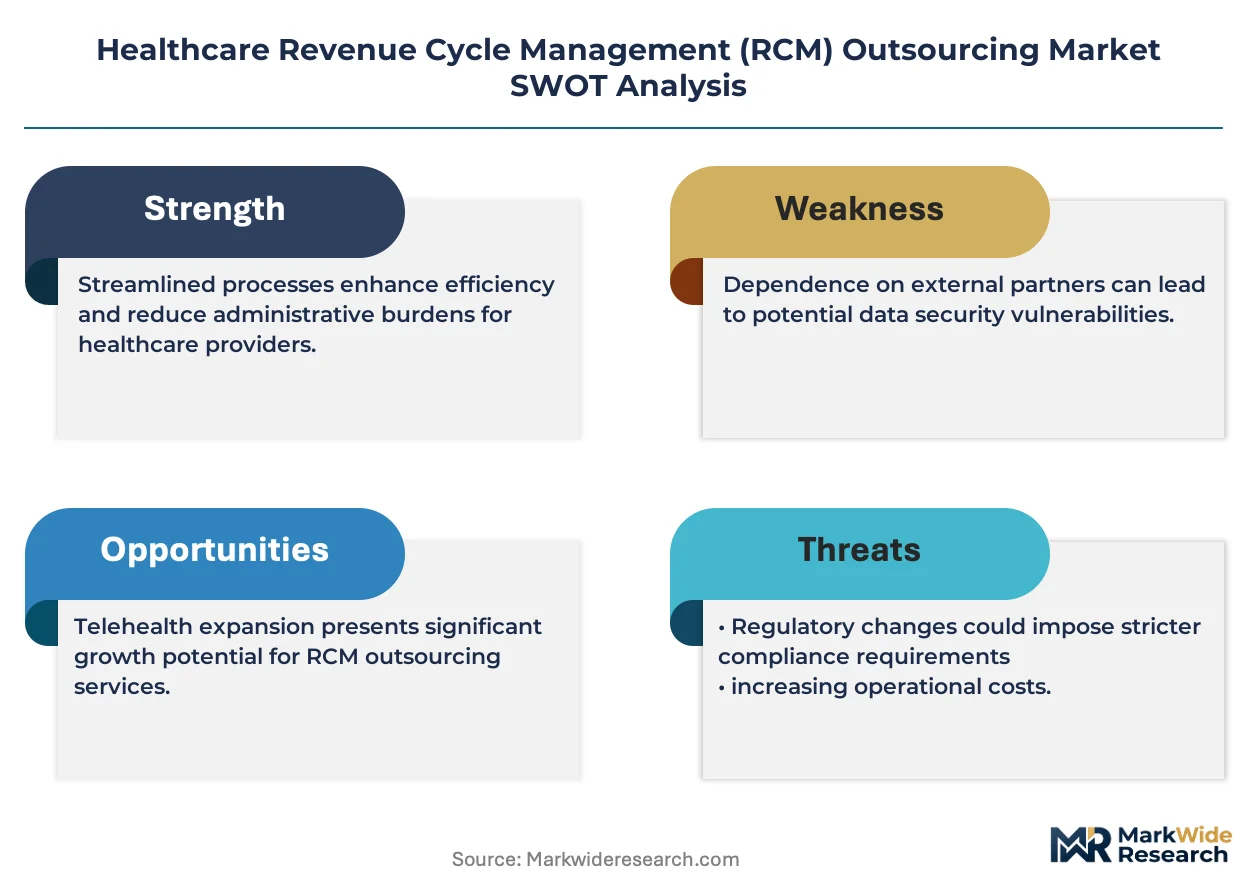
FDA oversight of clinical data integrity, HIPAA privacy mandates, and CMS reimbursement rulemaking collectively determine vendor qualification standards and contract renewal rates in this sector. State-level Medicaid expansion decisions and commercial payer consolidation further fragment standardization efforts across operating territories. Stakeholders must monitor evolving federal surprise billing regulations and their downstream impact on claims dispute workflows.
Market Dynamics
Cloud-native revenue cycle platforms are compressing deployment timelines from months to weeks, forcing incumbent vendors to rearchitect legacy infrastructure or cede mid-market hospital contracts to agile competitors.
Growth Catalysts
- ICD-10-CM complexity:Annual coding updates now exceed 70,000 billable codes, overwhelming in-house billing departments at community hospitals and driving delegation to certified coding specialists.
- United States labor scarcity:AAPC-certified medical coder vacancies exceed 35,000 positions nationally, creating permanent capacity constraints that institutionalize outsourcing relationships.
- Prior authorization automation:AI-enabled eligibility verification reduces denial rates by intercepting coverage gaps before claim submission, converting cost centers into performance-based vendor economics.
Market Restraints
- Data localization mandates:HIPAA business associate agreements impose geographic processing restrictions that fragment vendor scale economies across state boundaries.
- Legacy system integration:Epic and Cerner EHR architectures require custom API development, extending implementation cycles and inflating upfront professional services costs.
- Payer consolidation:Dominant commercial insurers in concentrated metropolitan markets standardize reimbursement rules, eroding vendor differentiation through contract negotiation expertise.
Strategic Opportunities
- Rural health clinic penetration:Critical Access Hospitals in the Upper Midwest and Mountain West operate with minimal billing infrastructure, presenting turnkey outsourcing conversion potential.
- Surprise billing compliance:The No Surprises Act creates federally mandated dispute resolution workflows that specialized vendors can productize as subscription compliance modules.
- Telehealth coding specialization:CMS modifier requirements for virtual visits diverge from in-person protocols, opening niche expertise markets for modality-specific revenue cycle management.
Industry Challenges
- Cybersecurity credentialing:HITRUST certification timelines stretch 14-18 months, delaying vendor onboarding for health systems with zero-trust infrastructure mandates.
- Interoperability fragmentation:FHIR API implementation varies across EHR versions, forcing vendors to maintain multiple integration codebases for identical clinical workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Revenue Cycle Management (RCM) Outsourcing Market |
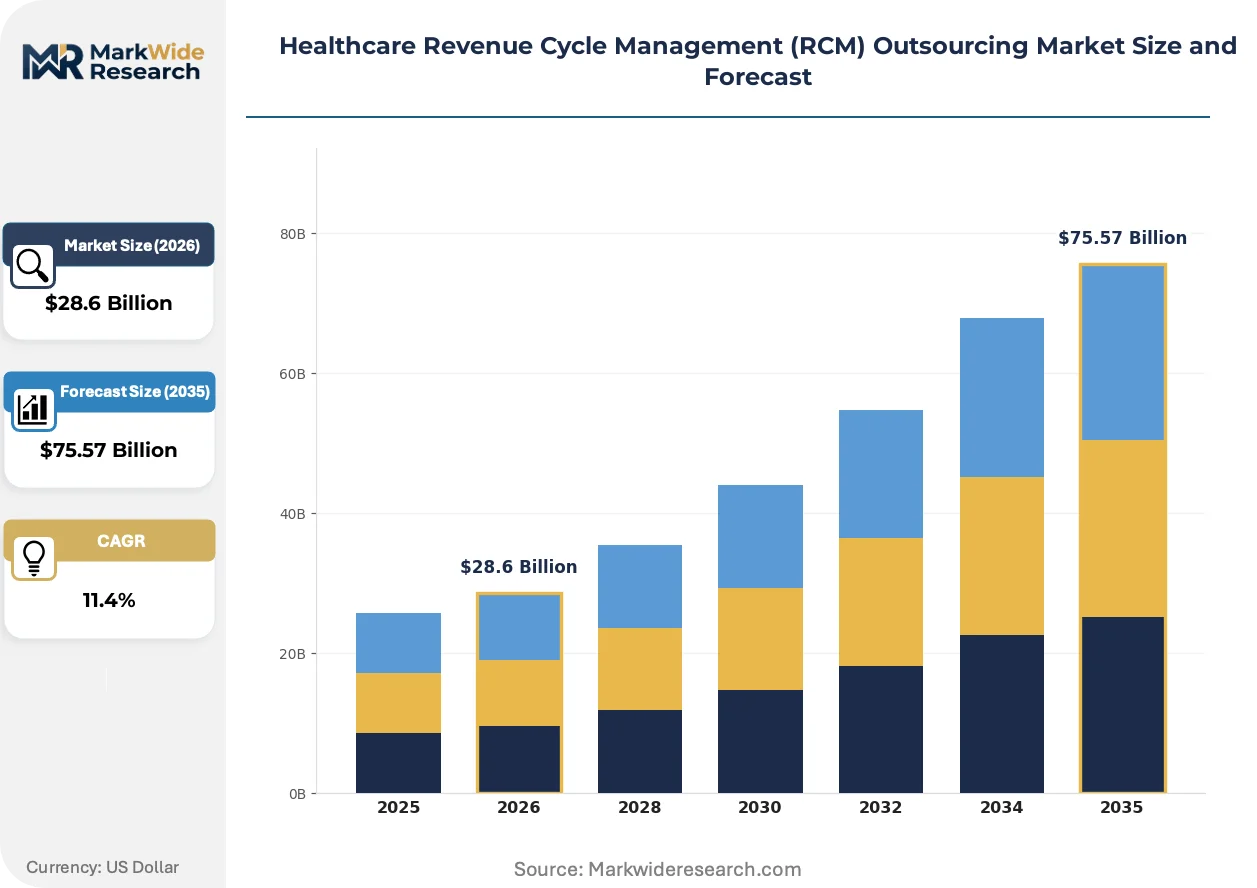
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Billing Services, Coding Services, Accounts Receivable Management, Payment Processing Client Type: Hospitals, Physician Practices, Ambulatory Surgery Centers, Diagnostic Laboratories Delivery Model: On-premise, Cloud-based, Hybrid, Offshore Technology: Artificial Intelligence, Machine Learning, Data Analytics, Blockchain |
| Companies Covered | Optum, R1 RCM, Conifer Health Solutions, Ensemble Health Partners, McKesson Corporation, Oracle, Cognizant, Guidehouse, Parallon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Revenue Cycle Management (RCM) Outsourcing Market Shifts & Advancements
Artificial intelligence is rewriting the economics of claims processing by automating coding verification and denial prediction, compressing the revenue cycle from weeks to days while reducing human error rates.
Machine learning models trained on historical denial patterns are displacing rules-based claim scrubbers in hospital billing departments. Large health systems in Texas and Florida are deploying these tools across emergency department and surgical service lines. The technology is displacing overnight offshore coding shifts as primary denial prevention infrastructure.
CMS reimbursement rulemaking now mandates machine-readable file formats for price transparency compliance. Hospital systems must publish negotiated rates with 300 shoppable services, creating data engineering burdens that vendors address through automated extraction pipelines. Academic medical centers with complex payer mixes face the steepest compliance costs and are outsourcing disclosure infrastructure buildout.
Health system procurement teams are consolidating vendor relationships from point-solution contracts to comprehensive revenue cycle partnerships. Single-source accountability for cash conversion performance is replacing fragmented billing-coding-collections vendor stacks. This concentration is most pronounced in multi-hospital systems across the Southeast and Pacific Northwest where CFOs prioritize working capital metrics over functional specialization.
Healthcare Revenue Cycle Management (RCM) Outsourcing Market Segmentation
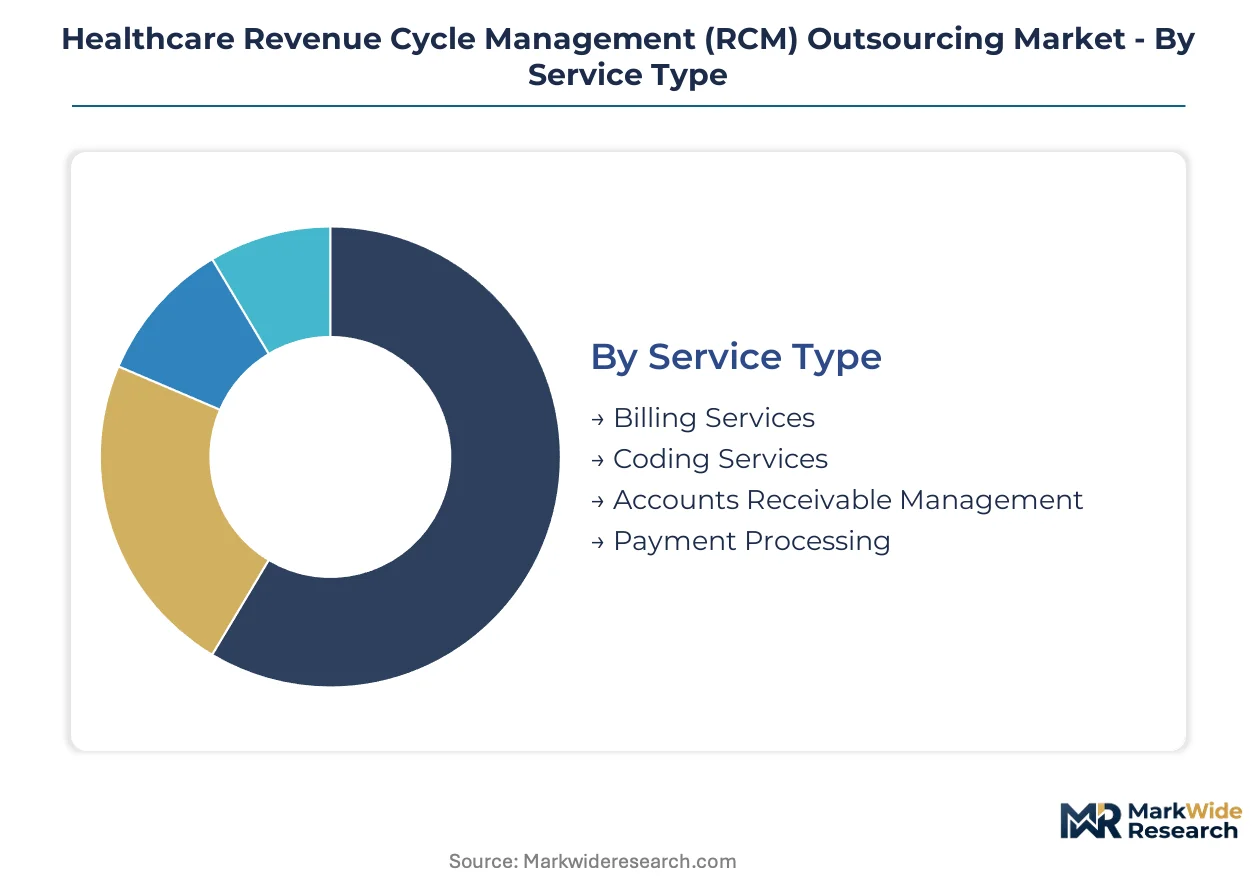
RCM outsourcing segmentation reveals divergent margin profiles across service modalities and infrastructure investments. Cloud-native architectures and AI-augmented coding command premium pricing while legacy billing services face commoditization pressure.
Service Type:
Billing Services anchor domestic revenue concentration. Coding Services and AR Management increasingly leverage offshore delivery corridors.
- Billing Services:End-to-end claim submission, payment posting, and patient statement management form the foundational revenue layer. Community hospitals in Texas and Florida outsource entire billing departments to eliminate fixed labor overhead.
- Coding Services:Certified specialists translate clinical documentation into ICD-10-CM and CPT reimbursement codes with compliance precision. Academic medical centers with complex surgical volumes delegate specialty coding to external AAPC-certified teams.
- Accounts Receivable Management:Denial appeals, aged receivable recovery, and payer follow-up workflows.
- Payment Processing:Patient financial clearance, point-of-service collections, and payment plan administration.
Billing Services commands the established base. The steepest expansion runs through Coding Services.
Client Type:
Hospital systems generate the largest contract values. Physician practices and ambulatory settings drive volume aggregation through multi-site rollups.
- Hospitals:Inpatient and outpatient revenue cycle complexity justifies comprehensive outsourcing partnerships spanning registration through collections. IDNs with 10+ facilities consolidate vendor relationships under single-source accountability structures.
- Physician Practices:Multi-specialty groups with 50+ providers lack economies of scale for in-house billing infrastructure. Private equity-backed practice aggregators standardize RCM platforms across acquired clinics.
- Ambulatory Surgery Centers:High-volume, low-complexity procedural billing with rapid turnaround requirements.
- Diagnostic Laboratories:High-claim-volume, low-dollar-amount testing reimbursement with prior authorization intensity.
Hospitals command the established base. Physician practices show the steepest expansion trajectory.
Delivery Model:
Cost tier stratification separates capital-intensive on-premise deployments from variable-cost cloud consumption.
- On-premise:Legacy infrastructure requiring dedicated server hardware and IT maintenance staff. Large health systems with Epic-hosted environments retain on-premise RCM modules for data sovereignty compliance.
- Cloud-based:Elastic capacity provisioning with subscription economics and remote workforce enablement. Rural health clinics adopt cloud-native platforms to bypass capital expenditure barriers.
- Hybrid:Sensitive data remains on-premise while analytics and reporting shift to cloud infrastructure.
- Offshore:Labor arbitrage through India and Philippines delivery centers with HIPAA business associate agreements.
On-premise deployments retain the established base. Cloud-based delivery gains share fastest.
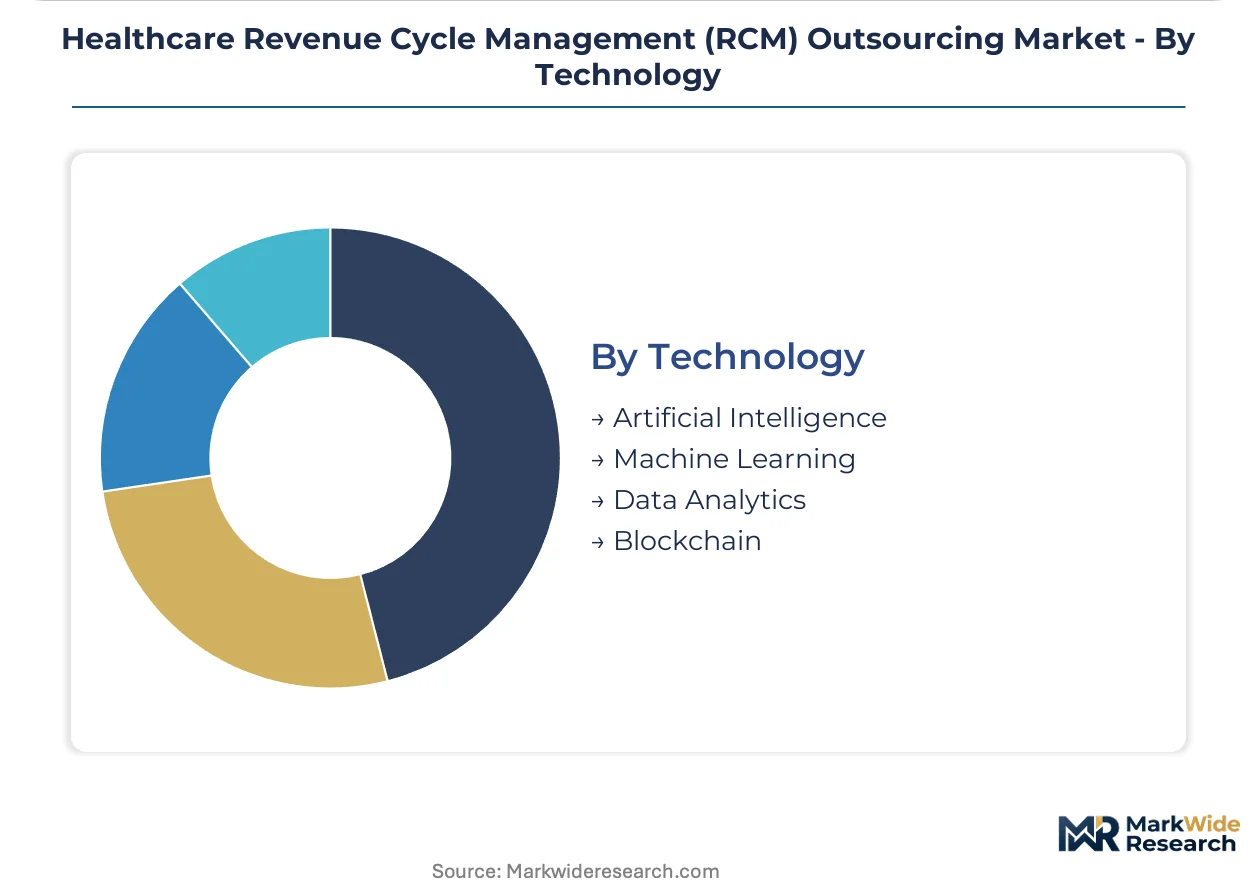
Technology:
Application maturity varies sharply—predictive analytics deploys at scale while blockchain remains experimental.
- Artificial Intelligence:Natural language processing extracts clinical concepts from unstructured physician notes for automated coding suggestions. Emergency department documentation at Level I trauma centers deploys AI coding assistants.
- Machine Learning:Historical denial pattern recognition predicts claim rejection probability before submission. Surgical service lines in California health systems use ML models to preempt coverage verification failures.
- Data Analytics:Payer mix optimization, revenue leakage detection, and performance benchmarking dashboards.
- Blockchain:Distributed ledger pilots for prior authorization transparency and smart contract-based payment reconciliation.
Data Analytics commands the established base. Artificial Intelligence shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems command premium outsourcing rates while Canadian facilities operate under tighter provincial budget constraints. This pricing-power asymmetry reflects divergent reimbursement models and labor market conditions across North American borders.
United States
Hospital consolidation in Texas and Florida creates multi-billion-dollar contract opportunities for end-to-end revenue cycle partners. HIPAA business associate agreements impose strict geographic processing restrictions that fragment vendor scale economies across state lines. The Dallas-Fort Worth metroplex anchors the nation's largest concentration of RCM outsourcing headquarters.
Canada
Provincial health authorities in Ontario and British Columbia delegate billing operations to contain administrative overhead within single-payer frameworks. Health Canada regulates medical device and pharmaceutical reimbursement coding through the Medical Devices Bureau. Toronto's health technology corridor hosts emerging RCM platforms serving cross-border provider networks.
United Kingdom
NHS Trusts in England outsource revenue cycle functions to private sector specialists amid persistent workforce shortages. The Care Quality Commission audits vendor compliance with data protection standards for patient financial records. London's digital health cluster attracts cloud-native RCM providers targeting European expansion.
Germany
University hospitals in Bavaria and North Rhine-Westphalia seek external coding expertise to manage Diagnosis-Related Group complexity. The Federal Joint Committee (G-BA) determines reimbursement catalogs that vendors must navigate for claims acceptance. Berlin-Brandenburg's health IT ecosystem incubates specialized revenue cycle automation ventures.
India
Offshore delivery centers in Bangalore and Hyderabad process medical coding for United States health systems under HIPAA-compliant business associate agreements. The Ministry of Health and Family Welfare promotes healthcare IT exports through specialized economic zones. Hyderabad's Genome Valley corridor concentrates certified medical coder training institutes serving international clients.
Healthcare Revenue Cycle Management (RCM) Outsourcing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the revenue cycle outsourcing spectrum. The market structures around three distinct tiers: integrated payer-provider platforms, pure-play hospital revenue specialists, and offshore labor arbitrage operators. Strategic differentiation runs through AI-augmented coding capabilities, end-to-end accountability structures, and geographic delivery model selection. Consolidation pressures favor vendors with capital reserves for Epic and Cerner integration investments.
Within the integrated platform tier, Optum leverages UnitedHealth Group's payer data infrastructure to anchor large health system contracts. R1 RCM occupies the pure-play hospital specialist position through long-term operating partnerships. Ensemble Health Partners represents the technology-enabled transformation archetype targeting academic medical centers with complex payer mixes.
| Leading Market Players |
|---|
| Optum |
| R1 RCM |
| Conifer Health Solutions |
| Ensemble Health Partners |
| McKesson Corporation |
| Oracle |
| Cognizant |
| Guidehouse |
| Parallon |
| Others |
Supply & Pricing Matrix
HITRUST certification timelines stretch 14-18 months and simultaneously gate vendor qualification and stratify pricing tiers across the revenue cycle outsourcing landscape. This regulatory barrier separates premium-configured partnerships from commoditized billing services.
Pricing Analysis
Configured-to-order pricing commands substantial premiums over standard SaaS-tiered subscription models in this market. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by AI-augmented coding capability, HITRUST certification status, and end-to-end accountability scope. Cost compression in legacy billing services is intensifying because cloud-native entrants displace on-premise incumbents with elastic capacity economics. Critical Access Hospitals in rural geographies exhibit highest price sensitivity, while academic medical centers with complex payer mixes prioritize performance-based vendor economics over unit cost.
Supply Chain Analysis
India and the Philippines anchor offshore medical coding delivery, while the United States concentrates cloud-native platform development and Epic-Cerner integration expertise. The supply chain draws from certified coder training institutes in Hyderabad's Genome Valley, HIPAA-compliant data centers in Bangalore, and domestic implementation specialists in the Dallas-Fort Worth metroplex. Single-source vulnerability runs through concentrated Philippines delivery corridors exposed to typhoon disruption and geopolitical friction. Distribution runs through health system procurement committees, GPO contracts, and direct vendor-to-IDN partnerships with multi-hospital accountability structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as FHIR API standardization and cloud-native architectures collapse switching costs between revenue cycle vendors. This interoperability inflection rewards ecosystem orchestrators over point-solution specialists.
For Market Incumbents: Shield large health system contracts through accelerated AI coding assistant deployment and captive Epic integration certification programs. Cloud-native entrants with elastic workforce models threaten legacy billing service margins. Vertical integration into offshore delivery through acquisition of Philippines-based coding institutes preserves labor arbitrage advantages. For New Entrants and Emerging Players: Anchor in rural health clinic white space across the Upper Midwest and Mountain West, where minimal billing infrastructure and capital expenditure constraints favor turnkey cloud-native conversion. Critical Access Hospitals represent the most penetrable segment. Lead with subscription-based surprise billing compliance modules to bypass entrenched incumbent relationships. For Investors and Strategic Acquirers: CMS reimbursement rulemaking on machine-readable price transparency reshapes the acquisition landscape toward vendors with automated extraction pipeline capabilities. Long-term viability favors platforms combining AI-augmented coding with end-to-end cash conversion accountability. Monitor health system procurement consolidation from fragmented vendor stacks to single-source partnerships as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Augmented Coding Platform Launch | Machine learning models trained on historical denial patterns displace overnight offshore shifts at Texas and Florida health systems. |
| Epic Integration Certification Investment | Custom API development capability unlocks multi-billion-dollar IDN contracts in consolidated hospital markets. |
| Surprise Billing Compliance Module Development | No Surprises Act dispute resolution workflows convert regulatory mandate into recurring subscription revenue. |
| Offshore Delivery Center Acquisition | Philippines and India coding capacity secures labor arbitrage against domestic AAPC-certified coder scarcity. |
| Cloud-Native Infrastructure Migration | Elastic capacity provisioning collapses deployment timelines from months to weeks for mid-market hospital contracts. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital CFOs, revenue cycle directors, AAPC-certified coding specialists, and health system procurement managers; and secondary validation through CMS Medicare reimbursement databases, hospital GPO contract filings, HITRUST certification registries, and SEC disclosures from publicly traded RCM vendors. Bottom-up service-type demand modeling and top-down health system expenditure analysis were triangulated against cloud deployment metrics and AI adoption indicators.
Across the modeling period, forecasts incorporated segmentation dimensions spanning service type, client category, delivery architecture, and technology layer, with particular weighting applied to cloud-native platform adoption curves and certified coder supply constraints. CAGRs were derived from elasticity-adjusted demand projections and vendor capacity expansion signals. FHIR API implementation variance and payer consolidation patterns served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable HIPAA business associate agreement enforcement and continued cloud infrastructure cost decline; material deviation in federal surprise billing regulation or Epic-Cerner merger integration outcomes would warrant model refresh. Recalibration cycles align with material shifts in CMS reimbursement rulemaking and health system consolidation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
US Healthcare Third-Party Logistics Market
Healthcare Services
Audiology Services Market
Healthcare Services
Long Term Care Market
Healthcare Services
Global Funeral Homes and Funeral Services Market
Healthcare Services
Healthcare Staffing Market
Healthcare Services
Western Europe Medical Recruitment Market
Healthcare Services
US Primary Care Physicians Market
Healthcare Services
North America Healthcare Cold Chain Logistics Market
Healthcare Services
Specialty Pharma Home Delivery and Patient Support Logistics Market
Healthcare Services
Contract Research Organization (CRO) Services Market
Healthcare Services
Global Urgent Care Center Market
Healthcare Services
Funeral and Cremation Services Market
Healthcare Services
Ambulatory Healthcare Service Market
Healthcare Services
Inhaled and Intranasal Products Contract Service Providers Market
Healthcare Services
Medical Second Opinion Market
Healthcare Services
Healthcare Transportation Services Market