
 Medical Waste Disposal Services Market | 2026-2036
Medical Waste Disposal Services Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Waste Disposal Services Market Insights
Modular service bundling is shifting buyer choice as healthcare facilities seek integrated waste management rather than point solutions. Stericycle, Inc. leverages its national collection network to anchor comprehensive programs across acute care networks. Clean Harbors, Inc. competes through specialized hazardous waste capabilities that extend into pharmaceutical destruction. Daniels Sharpsmart Inc. differentiates via reusable container systems that reduce sharps waste volume at the source.
Medical waste disposal services encompass the collection, transport, treatment, and final disposition of potentially infectious or hazardous materials generated by healthcare activities, with autoclaving applying steam at 121°C under 15 psi pressure to sterilize microbiological waste before landfill placement. The primary commercial purpose centers on preventing disease transmission while ensuring regulatory compliance throughout the waste lifecycle. Autoclaving dominates service type volume due to lower capital requirements and broader regulatory acceptance, while chemical treatment occupies niche applications for pharmaceutical residues where thermal methods risk air emissions. Biohazardous waste leads waste type demand from hospital surgical and patient care operations, with sharps containers representing the most standardized collection infrastructure across end user sites.
The US EPA enforces cradle-to-grave tracking under RCRA subtitle C for hazardous pharmaceutical waste, while OSHA mandates engineering controls and worker training for bloodborne pathogen exposure, collectively elevating compliance spending as a permanent cost layer. State-level regulations in California, New York, and Texas impose treatment facility permitting and manifest documentation requirements that create barriers to unlicensed market entry. Stakeholders must monitor evolving EPA pharmaceutical waste rulemakings and state-level hazardous waste designations that could reclassify substantial waste volumes and redirect treatment capacity investments.
Market Dynamics
Stringent cradle-to-grave tracking mandates under EPA's RCRA subtitle C are forcing healthcare facilities to consolidate vendor relationships and invest in integrated waste management platforms rather than fragmented point solutions.
Growth Catalysts
- OSHA Bloodborne Pathogen Standard:Mandatory engineering controls and worker training protocols drive recurring compliance service contracts across acute care networks.
- Hospital surgical volume:Rising procedure counts in tertiary care centers generate sustained biohazardous waste streams requiring specialized collection infrastructure.
- California hazardous waste designation:State-level pharmaceutical waste reclassifications expand treatable volumes and extend service provider capture rates.
Market Restraints
- Treatment facility permitting:State-level licensing requirements in Texas and New York create geographic supply concentration and limit new entrant capacity.
- Autoclave energy intensity:Steam sterilization at 121°C under 15 psi pressure demands substantial natural gas inputs vulnerable to commodity price volatility.
- Chemical treatment substitution:Pharmaceutical residue destruction via chemical methods competes with thermal approaches where air emission controls add cost layers.
Strategic Opportunities
- Rural health clinic penetration:Underserved ambulatory surgical centers in secondary US markets lack dedicated medical waste infrastructure and present greenfield contract potential.
- Reusable container systems:Sharps waste volume reduction at the source through durable collection hardware creates differentiation against disposable alternatives.
- EPA pharmaceutical waste rulemaking:Pending hazardous designation expansions for controlled substances could redirect substantial waste volumes toward specialized treatment capacity.
Industry Challenges
- DOT hazardous materials certification:Driver training and vehicle placarding requirements for regulated medical waste transport extend hiring timelines and inflate labor costs.
- Legacy manifest documentation:Paper-based tracking systems in smaller healthcare facilities resist integration with electronic cradle-to-grave platforms, forcing dual-system maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Waste Disposal Services Market |
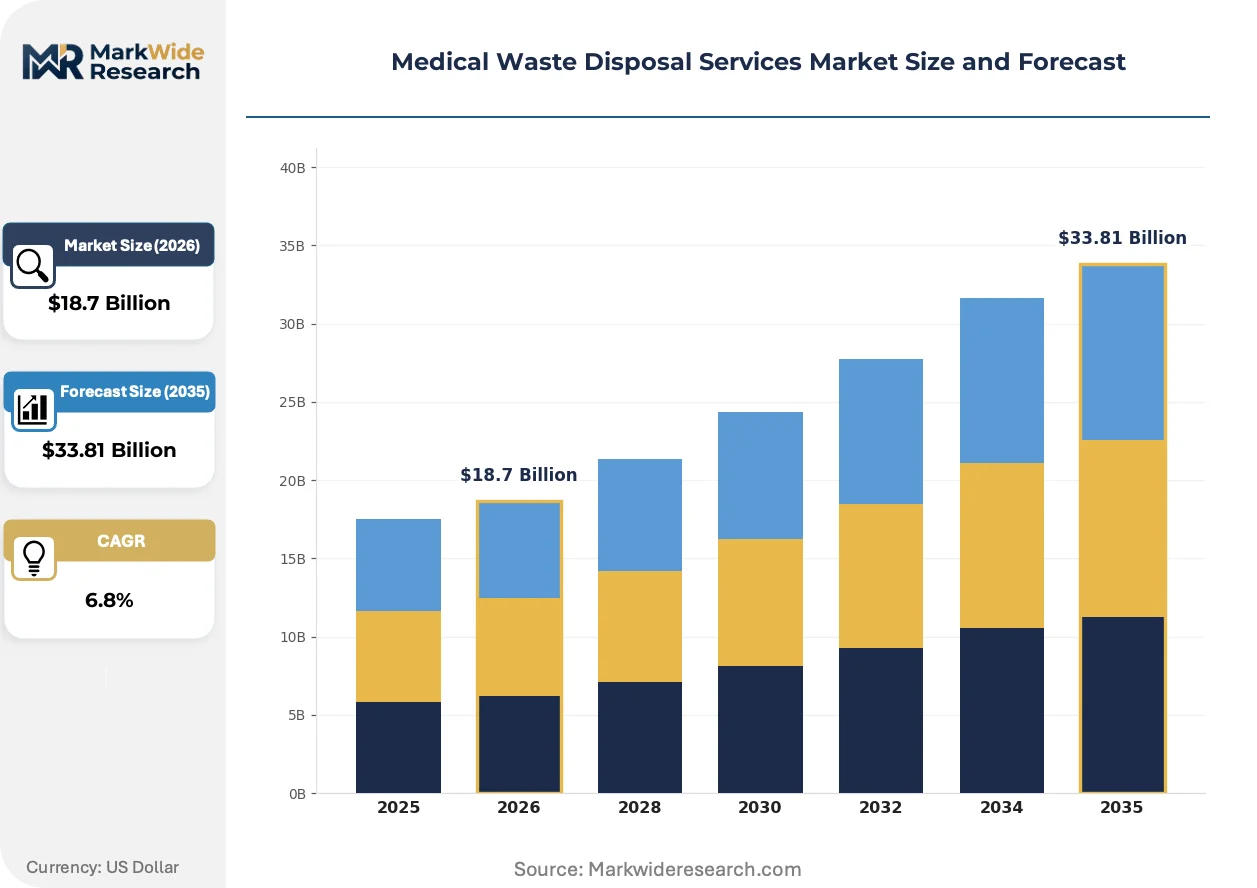
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Incineration, Autoclaving, Chemical Treatment, Landfill End User: Hospitals, Clinics, Laboratories, Dental Practices Waste Type: Biohazardous, Sharps, Pharmaceuticals, Pathological Compliance Level: Regulatory, Non-Regulatory, State-Level, International |
| Companies Covered | Stericycle, Inc., Clean Harbors, Inc., Veolia Environnement S.A., Waste Management, Inc., Republic Services, Inc., REMONDIS SE & Co. KG, Suez Environnement, Daniels Sharpsmart Inc., Triumvirate Environmental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Waste Disposal Services Market Trends and Innovations
Active transformation in medical waste management centers on container reuse, regulatory digitization, and buyer consolidation around full-service platforms rather than transactional collection relationships.
Microwave treatment technology is expanding into hospital on-site sterilization applications. Large health systems in the United States are piloting these units to reduce transportation costs and liability exposure. The technology is expanding into markets previously dominated by autoclaving by offering comparable microbiological kill rates with smaller physical footprints.
The EPA's pending pharmaceutical waste rulemakings under RCRA are tightening hazardous designation criteria for discarded medications. Healthcare facilities must segregate larger waste volumes into separate treatment streams. Hospital pharmacies and long-term care operators are responding by pre-sorting at the point of generation, creating demand for specialized collection containers and staff training modules.
Integrated service bundling now dominates purchasing decisions among multi-site health networks. Buyers are consolidating vendor relationships to capture volume discounts and unified compliance reporting. This pattern is most visible in the United States, where acute care networks with dozens of affiliated sites negotiate enterprise-wide contracts replacing site-by-site arrangements.
Medical Waste Disposal Services Market Segmentation
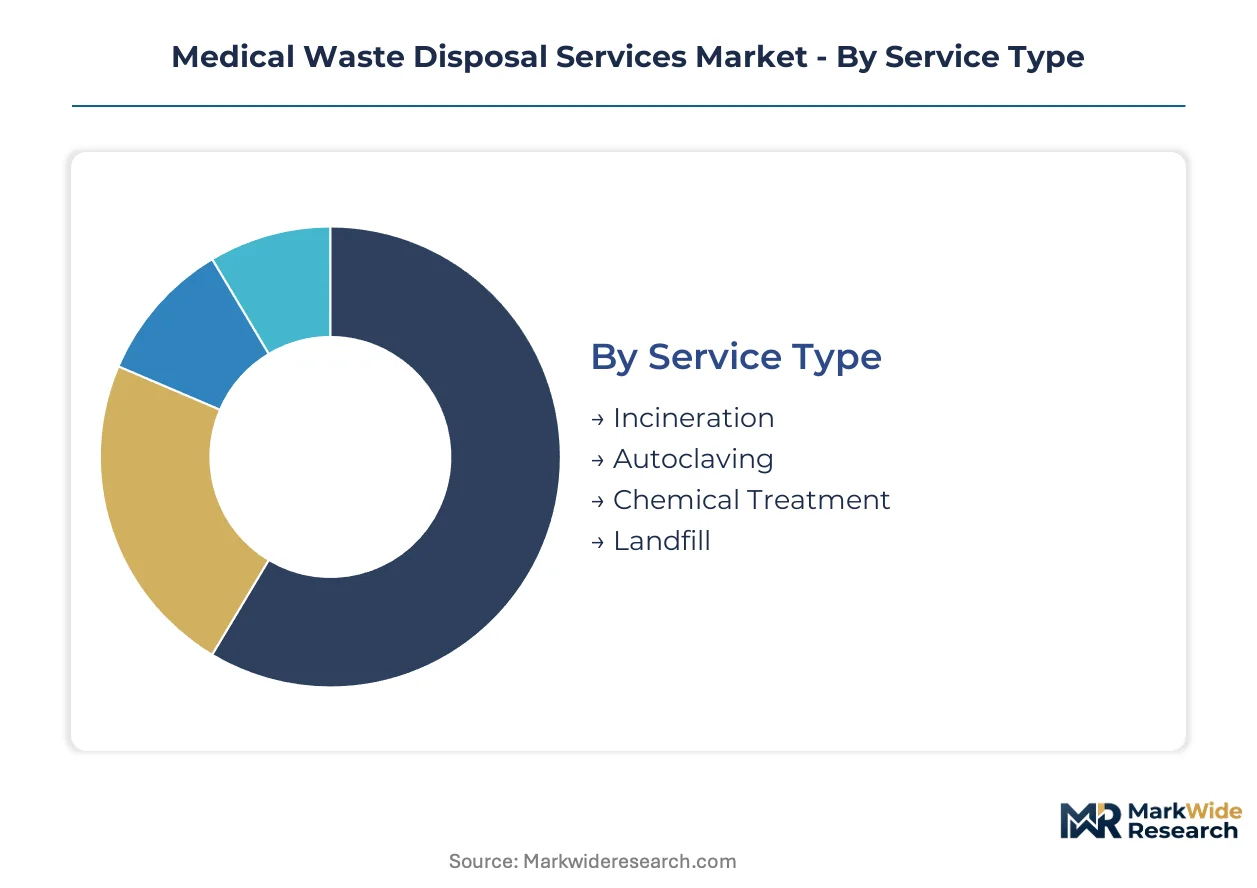
Service configuration in medical waste disposal hinges on treatment technology selection, end-user operational scale, and regulatory jurisdiction complexity. Segment boundaries shift as health systems consolidate purchasing and EPA rulemakings reclassify waste streams.
Service Type:
Capital intensity varies dramatically across treatment modalities, with thermal infrastructure demanding the heaviest upfront investment while chemical systems offer lower barriers to entry.
- Autoclaving:Steam sterilization at 121°C under 15 psi pressure dominates installed base due to moderate capital requirements and broad EPA acceptance for microbiological waste. Hospital networks in Texas and California concentrate procurement here, driven by OSHA bloodborne pathogen compliance mandates and natural gas price sensitivity.
- Incineration:High-temperature combustion units require substantial permitting and air quality control investments, limiting deployment to specialized hazardous waste facilities. Demand concentrates in pharmaceutical destruction applications where California's hazardous waste designation rules apply.
- Chemical Treatment:Neutralization and oxidation systems occupy niche positions for pharmaceutical residues and chemotherapeutic waste where thermal methods risk emissions violations.
- Landfill:Final disposition for treated residues operates through permitted municipal and hazardous waste facilities, with state-level manifest documentation requirements governing acceptance criteria.
Most installed capacity flows through Autoclaving. Expansion is steepest in Chemical Treatment as pharmaceutical waste reclassifications accelerate.
End User:
Procurement sophistication and contract scale separate institutional buyers from fragmented practice-level purchasing.
- Hospitals:Acute care networks generate the highest waste volumes per site and negotiate enterprise-wide service agreements spanning collection through treatment. Tertiary centers in the United States drive demand for integrated platforms with unified compliance reporting.
- Clinics:Ambulatory surgical centers and specialty practices represent dispersed, lower-volume accounts often served through route-density optimization rather than dedicated infrastructure.
- Laboratories:Research and diagnostic facilities produce concentrated chemical and biological waste streams requiring specialized handling protocols beyond standard biohazardous categories.
- Dental Practices:Small-scale generators with predictable sharps and amalgam waste profiles, frequently served through retail-style container programs rather than comprehensive service contracts.
Revenue concentration sits with Hospitals. Contract growth is climbing fastest in Clinics as rural health networks expand.
Waste Type:
Physical characteristics and infectious risk level determine collection infrastructure and treatment pathway selection.
- Biohazardous:Infectious materials from patient care and laboratory operations constitute the core volume driver, requiring color-coded bag systems and documented chain-of-custody protocols.
- Sharps:Needles, scalpels, and lancets demand puncture-resistant container engineering with OSHA-mandated engineering controls at point of generation.
- Pharmaceuticals:Discarded medications face escalating RCRA subtitle C scrutiny, with EPA rulemakings expanding hazardous designation criteria and forcing segregation into specialized treatment streams.
- Pathological:Human tissues and anatomical waste require incineration or alkaline hydrolysis under state-level medical waste regulations, with limited treatment facility availability constraining geographic service coverage.
Volume leadership belongs to Biohazardous waste. Regulatory pressure is intensifying fastest around Pharmaceuticals.
Compliance Level:
Documentation and oversight requirements stratify service pricing and vendor qualification thresholds.
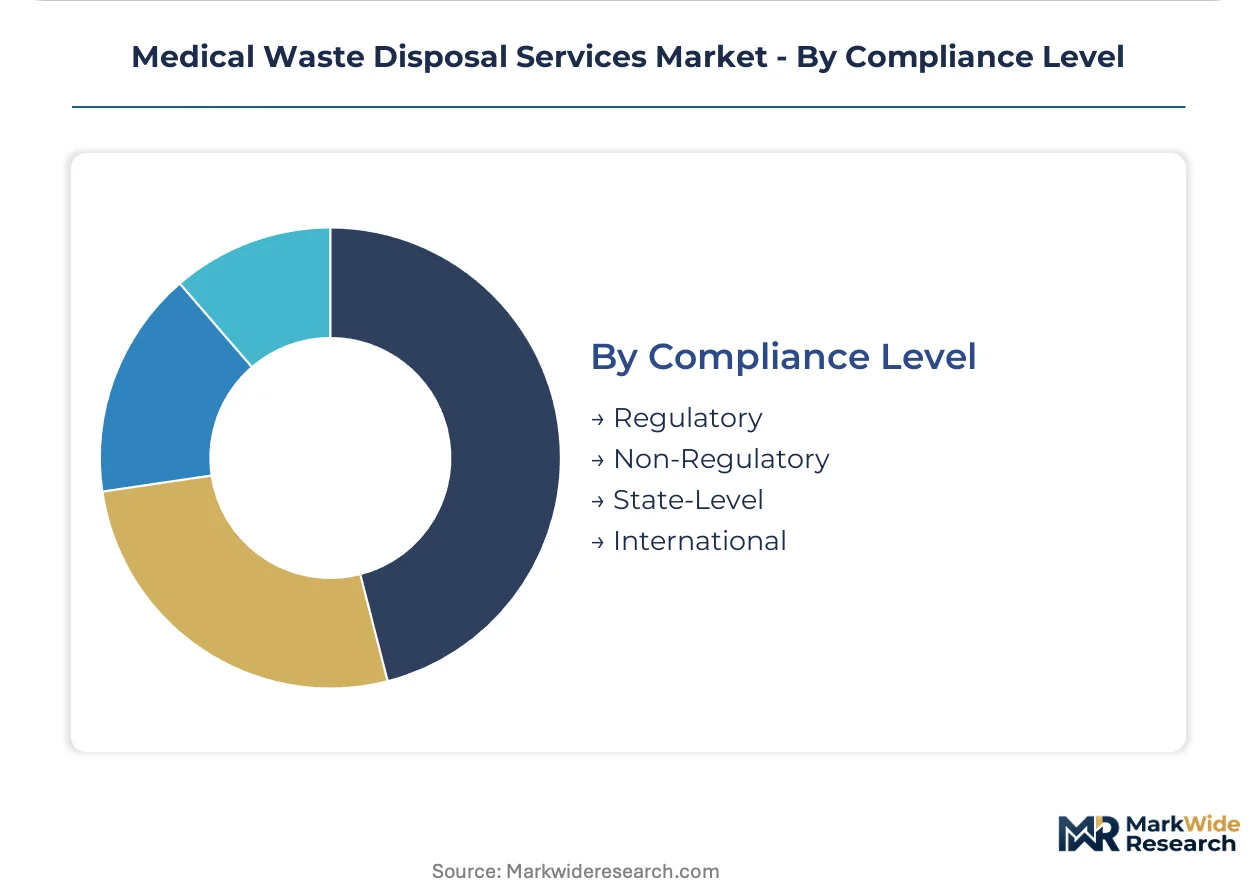
- Regulatory:Federal EPA and OSHA mandates establish baseline cradle-to-grave tracking, worker training, and treatment standards applicable across all fifty states.
- State-Level:California, New York, and Texas impose facility permitting, manifest documentation, and waste characterization rules that create geographic regulatory patchwork.
- International:Cross-border shipment protocols and WHO guidance apply to limited waste categories, primarily relevant for research institutions with multinational operations.
- Non-Regulatory:Voluntary sustainability certifications and corporate environmental policies drive premium service tiers without legal enforcement.
Service complexity centers on State-Level requirements. Documentation digitization is advancing most quickly in Regulatory-tier accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern medical waste disposal industry traces its regulatory foundations to the United States, where EPA RCRA subtitle C and OSHA bloodborne pathogen standards established cradle-to-grave accountability frameworks that later diffused to other jurisdictions. These protocols now govern service architecture across major healthcare markets worldwide.
United States
Hospital surgical volume and acute care network consolidation drive service demand concentration. EPA RCRA subtitle C mandates force healthcare facilities into integrated vendor relationships with unified compliance reporting. Texas and California host the densest treatment facility permitting clusters, with Houston and Los Angeles metropolitan areas anchoring autoclaving capacity expansion.
Germany
Precision manufacturing in medical devices and pharmaceutical production generates specialized chemical waste streams requiring specialized handling. ECHA REACH regulations govern hazardous waste characterization and cross-border shipment protocols. The Rhine-Ruhr industrial corridor concentrates incineration infrastructure serving Benelux export markets.
Japan
Aging demographics and hospital bed density sustain biohazardous waste generation per capita above regional averages. METI circular economy directives promote microwave treatment technology adoption for on-site sterilization. The Kanto region around Tokyo anchors national collection network optimization.
United Kingdom
NHS procurement consolidation shifts purchasing toward enterprise-wide service agreements replacing fragmented site-level contracts. Environment Agency hazardous waste regulations align with EU legacy frameworks post-Brexit. Greater Manchester and West Midlands health clusters pilot reusable container system deployment.
India
Rapid hospital infrastructure expansion in tier-2 cities outpaces dedicated medical waste treatment capacity installation. CPCB biomedical waste management rules mandate color-coded segregation and documented chain-of-custody. Maharashtra and Karnataka states concentrate private sector service provider penetration around Mumbai and Bangalore healthcare corridors.
Medical Waste Disposal Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance documentation sophistication and treatment technology breadth. The vendor base stratifies into three tiers: national integrated platforms commanding enterprise health system contracts, regional specialists optimizing route density in secondary markets, and technology-focused disruptors commercializing reusable hardware or on-site sterilization equipment. Consolidation through acquisition of permitted treatment assets and long-term exclusive service agreements with acute care networks represent the dominant competitive vectors.
Among North American service providers, Stericycle, Inc. and Clean Harbors, Inc. exemplify contrasting archetypes within the integrated platform tier. Stericycle anchors the reusable container system segment through Daniels Sharpsmart Inc., while Clean Harbors extends hazardous waste capabilities into pharmaceutical destruction niches. European-based Veolia Environnement S.A. and REMONDIS SE & Co. KG occupy positions emphasizing municipal and industrial waste synergies that transfer to healthcare verticals.
| Leading Market Players |
|---|
| Stericycle, Inc. |
| Clean Harbors, Inc. |
| Veolia Environnement S.A. |
| Waste Management, Inc. |
| Republic Services, Inc. |
| REMONDIS SE & Co. KG |
| Suez Environnement |
| Daniels Sharpsmart Inc. |
| Triumvirate Environmental |
| Others |
Pricing and Supply Chain Analysis
California's hazardous waste designation for pharmaceutical residues gates both qualified treatment capacity and premium-tier pricing access, as facilities lacking specialized permitting cannot serve regulated generators and command compliance-grade rate cards. Buyers in Texas and New York face corresponding supply concentration effects where permitted autoclave and incineration infrastructure anchors regional pricing bands.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates enterprise health systems from mid-tier clinics and small dental practices. Price differentiation rests on EPA RCRA subtitle C documentation sophistication and OSHA bloodborne pathogen certification depth. Cost compression in the standard tier is intensifying because autoclave natural gas inputs face commodity volatility. Rural ambulatory surgical centers exhibit highest price sensitivity; tertiary acute care networks with enterprise contracts show least.
Supply Chain Analysis
Reverse-logistics flows for reusable sharps containers create dedicated collection circuits distinct from single-use disposal streams, with Daniels Sharpsmart Inc. operating closed-loop container refurbishment networks. Geographic supply concentrates in the United States, Germany, and Japan where EPA, ECHA REACH, and METI regulations respectively anchor treatment infrastructure. Raw material dependencies span medical-grade polypropylene for containers, natural gas for autoclave steam generation, and specialized alkaline hydrolysis chemicals for pathological waste. Single-source vulnerability runs through permitted incineration capacity for pharmaceutical destruction. Distribution runs through route-optimized collection fleets serving multi-site health networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: California's stricter pharmaceutical waste reclassifications impose compliance cost burdens that Texas-based competitors can undercut through lighter regulatory overhead, creating margin capture opportunities for strategically positioned operators.
For Market Incumbents: Lock in exclusive long-term service agreements with consolidating acute care networks before EPA pharmaceutical rulemakings expand hazardous designation criteria. Acquire permitted treatment assets in California and New York to defend against regional specialists exploiting route-density advantages. Autoclave energy intensity represents the core margin pressure point; backward integration into natural gas hedging or on-site microwave sterilization technology offers defensive leverage.
For New Entrants and Emerging Players: Enter via rural health clinic penetration in secondary US markets where incumbent route density remains thin and compliance documentation demands are rising. Target ambulatory surgical centers in Texas and Florida as the most penetrable segment given surgical volume growth and lighter state-level permitting barriers. Lead with reusable container system hardware sales to establish footprint before expanding into full-service contracts.
For Investors and Strategic Acquirers: Roll-up economics work for regional permitted-treatment specialists because state-level licensing creates natural geographic moats and fragmented ownership structures resist organic scale. The five-to-ten year viability window favors platforms consolidating Texas and California treatment capacity. Acquisition target archetype: family-owned autoclave operators with EPA RCRA subtitle C permits and established hospital relationships. Monitor EPA pharmaceutical waste rulemaking progress as the critical inflection signal for hazardous designation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Container System Deployment | Daniels Sharpsmart Inc. demonstrates volume reduction at point of generation cuts transport costs. |
| On-Site Microwave Sterilization Pilot | US health systems reduce liability exposure and DOT hazardous materials transport dependencies. |
| Enterprise-Wide Service Consolidation | Multi-site acute care networks capture unified compliance reporting under single vendor relationships. |
| Pharmaceutical Waste Segregation Infrastructure | Hospital pharmacies pre-sort at generation point to meet EPA RCRA subtitle C pending rulemakings. |
| Permitted Treatment Asset Acquisition | California and Texas licensing barriers create defensive moats against unlicensed market entry. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, biomedical engineers, GPO contracts managers, and EPA compliance officers with secondary validation against OSHA enforcement data, EPA RCRA filing databases, state-level manifest documentation systems, and hospital procurement databases. Bottom-up service provider capacity modeling and top-down healthcare waste generation estimates were cross-checked for triangulation.
Historical reference periods anchored the projection horizon through treatment capacity installation trends and regulatory implementation timelines across the modeling period. Segmentation dimensions modeled include service type, end user scale, waste type physical characteristics, and state-level regulatory jurisdiction complexity. CAGRs were derived from installed base expansion rates and surgical procedure volume trajectories, with natural gas price sensitivity and EPA rulemaking probability weighted as scenario inputs.
The model holds under steady regulatory enforcement intensity and hospital consolidation continuity; deviation in EPA pharmaceutical waste designation timing or state-level permitting moratoria would shift capacity investment schedules and vendor capture rates. Practitioners should monitor EPA Federal Register notices and California DTSC rulemaking dockets for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Packaging and Labeling (Healthcare) Services Market
Healthcare Services
Global Infusion Pharmacy Management Market
Healthcare Services
Hair Restoration Services Market
Healthcare Services
UK Pharmaceutical Logistics Market
Healthcare Services
Global Funeral Homes and Funeral Services Market
Healthcare Services
Healthcare Third-Party Logistics Market
Healthcare Services
US Biopharmaceutical Third-Party Logistics Market
Healthcare Services
US Hospice Care Market
Healthcare Services
Global Operating Room Management Market
Healthcare Services
Retail Clinics Market
Healthcare Services
Hospital Workforce Management Market
Healthcare Services
Metabolomics Services Market
Healthcare Services
Tissue Banking Market
Healthcare Services
Australia Senior Living Market
Healthcare Services
Global Hospice Care Market
Healthcare Services
Private Healthcare Market