
 Clinical Perinatal Software Market | 2026-2036
Clinical Perinatal Software Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Perinatal Software Market Intelligence
The entry of specialized AI-driven diagnostic firms is restructuring the competitive landscape for perinatal software. GE HealthCare leverages its extensive hospital network to bundle software with its fetal monitoring hardware. In contrast, Epic Systems integrates perinatal modules within its broader Electronic Health Record ecosystem. Niche vendors like PeriGen, Inc. specialize in advanced analytics for labor and delivery risk assessment.
Clinical perinatal software comprises integrated digital platforms for managing patient data throughout the pregnancy, labor, and postpartum periods. These systems process real-time data from fetal monitors, such as heart rate variability and uterine activity, to support clinical decision-making. While on-premise systems remain common in large hospitals, cloud-based SaaS platforms are gaining share due to lower upfront costs. Fetal monitoring and maternal health management modules generate the majority of application-based revenue.
Software vendors must comply with medical device regulations, such as the FDA's requirements in the United States and the EU's Medical Device Regulation (MDR). Data privacy laws, including HIPAA and GDPR, impose strict controls on the handling and storage of sensitive patient health information. Future platform development will center on achieving seamless interoperability between disparate hospital IT systems and incorporating predictive analytics.
Market Dynamics
The imperative for data interoperability between disparate hospital IT systems is the central force shaping the clinical perinatal software market. This pressure stems from regulatory mandates for patient data access and clinical demands for a unified view of maternal and fetal health.
Growth Catalysts
- Regulatory Compliance Mandates:Data privacy laws, including HIPAA in the United States and GDPR in Europe, compel healthcare providers to adopt secure, auditable software systems for managing sensitive patient information, driving investment in modern platforms.
- AI in Clinical Decision Support:The integration of artificial intelligence and machine learning algorithms to analyze real-time fetal monitoring data for early risk detection is a significant technological driver, especially in high-risk obstetrics.
- Expansion of Specialized Care Centers:A rising number of standalone birth centers and specialist perinatal clinics are adopting integrated software to improve care coordination and compete with larger hospitals, creating a new customer segment.
Market Restraints
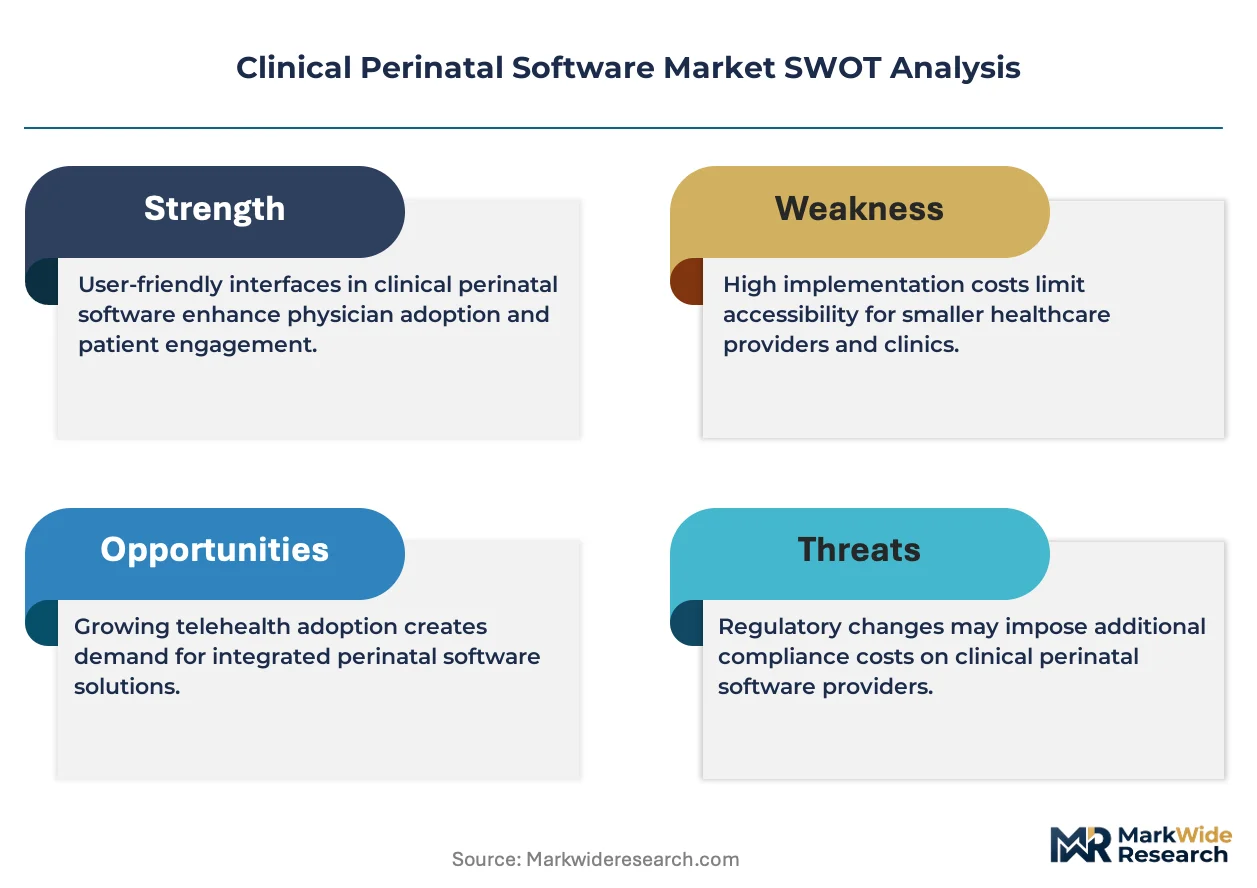
- High Implementation Costs:The significant upfront investment and ongoing maintenance expenses for comprehensive on-premise software systems remain a substantial barrier for smaller hospitals and clinics with limited IT budgets.
- Legacy System Interoperability:Achieving seamless data exchange between new perinatal software and existing, often proprietary, hospital EHR systems and fetal monitoring hardware presents a major technical and financial hurdle for many institutions.
- Stringent Regulatory Pathways:Software with diagnostic capabilities is subject to lengthy and complex approval processes by bodies like the FDA and under the EU's Medical Device Regulation, delaying market entry for new innovations.
Strategic Opportunities
- Postpartum Care Modules:There is a significant opportunity to develop and integrate specialized software modules focused on postpartum care, including remote monitoring for complications and maternal mental health screening and support.
- Predictive Analytics for Genomics:The convergence of perinatal data with maternal and neonatal genomic information opens a new frontier for developing highly personalized risk assessment tools and targeted intervention strategies.
- Telehealth Integration:Expanding software capabilities to fully integrate with telehealth platforms can support remote prenatal consultations and postpartum follow-ups, particularly in rural or underserved areas in countries like Australia and Canada.
Industry Challenges
- Data Standardization:A lack of universal standards for data formats from different fetal monitor manufacturers creates significant integration complexity and challenges the reliability of cross-platform data analysis.
- Clinical Workflow Disruption:Implementing new software often requires substantial changes to established clinical workflows in labor and delivery units, leading to resistance from staff and requiring extensive training and change management.
- Cybersecurity Vulnerabilities:The increasing connectivity of clinical systems makes them prime targets for cyberattacks, requiring vendors and hospitals to make continuous, costly investments in security infrastructure to protect patient data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Perinatal Software Market |
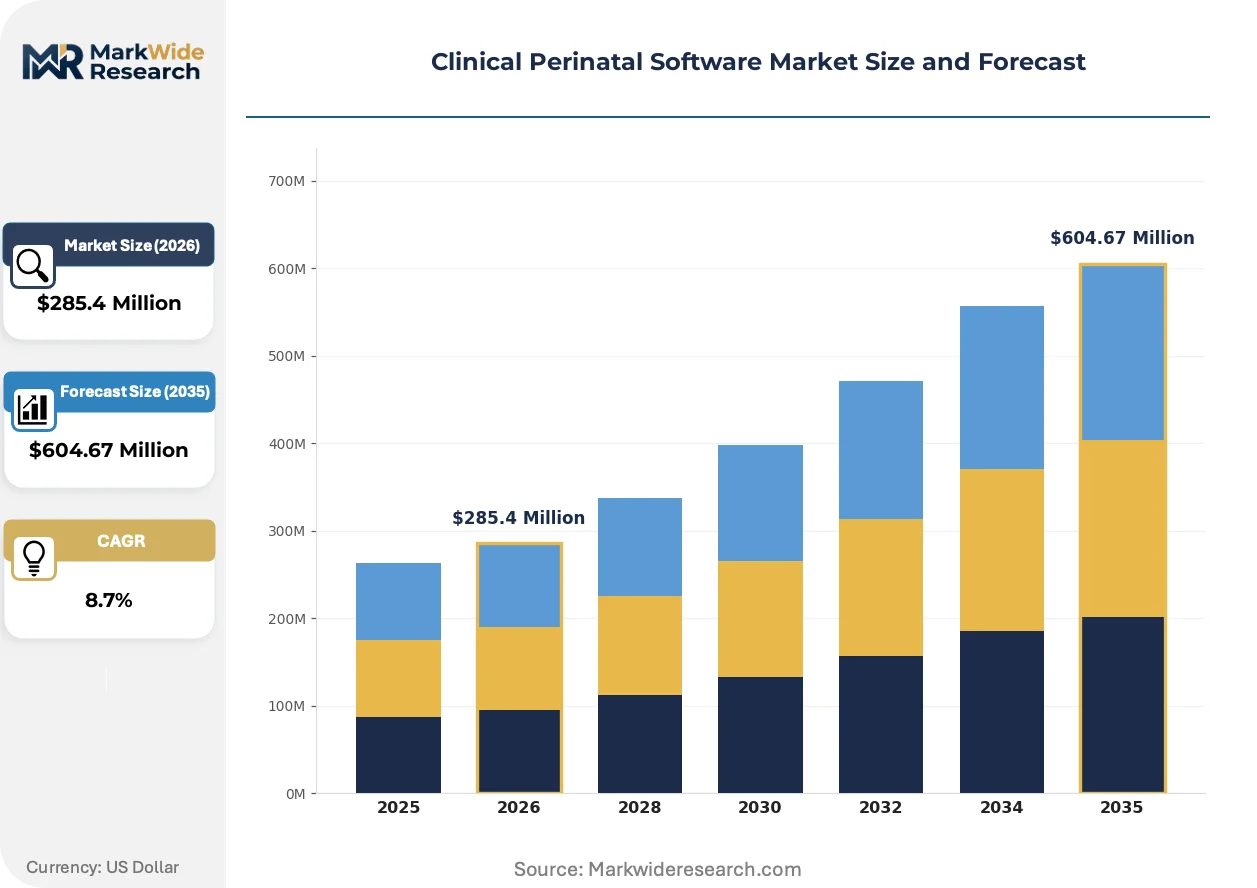
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Risk Assessment Tools, Electronic Health Records, Patient Monitoring Systems, Data Analytics Platforms Application: Fetal Monitoring, Maternal Health Management, Neonatal Care, Prenatal Diagnosis End User: Specialist Clinics, Birth Centers, Diagnostic Laboratories, Research Institutes Deployment: Cloud-Based Solutions, On-Premise Systems, Hybrid Models, SaaS Platforms |
| Companies Covered | Clinical Computer Systems, Inc., Trium Analysis Online GmbH, GE HealthCare, Ascom Holding AG, Hill-Rom Holdings Inc., Koninklijke Philips N.V., Epic Systems, Sonio, PeriGen, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Perinatal Software Market Strategic Shifts & Innovations
The market's evolution is defined by the transition from passive data repositories to active, intelligent systems that provide predictive insights for clinical intervention. This shift is powered by advancements in analytics and a greater emphasis on integrated care pathways across the perinatal period.
AI-powered analytical engines provide real-time interpretation of complex data streams, such as fetal heart rate variability and uterine contraction patterns. Adoption of these tools is accelerating within large, high-volume maternity hospitals in the United States and Germany seeking to improve patient safety. This advanced analytical capability is converging with the broader Electronic Health Record ecosystem, enabling a more holistic and longitudinal view of patient health.
The European Union’s Medical Device Regulation (MDR) establishes a more rigorous regulatory framework for software classified as a medical device. This policy increases the burden of proof for clinical efficacy and demands robust post-market surveillance from vendors. Software platforms that offer diagnostic predictions or risk scoring are most affected, prompting vendors to invest more heavily in clinical validation to maintain market access in EU member states.
A clear preference for subscription-based Software-as-a-Service (SaaS) models is altering procurement patterns. This model displaces the traditional high-capital, on-premise license purchase, making advanced software more accessible to mid-sized hospitals and independent birth centers. The trend is most advanced in North America and the United Kingdom, where cloud infrastructure is mature and healthcare providers prioritize operational expenditure over large capital outlays.
Clinical Perinatal Software Market Segmentation
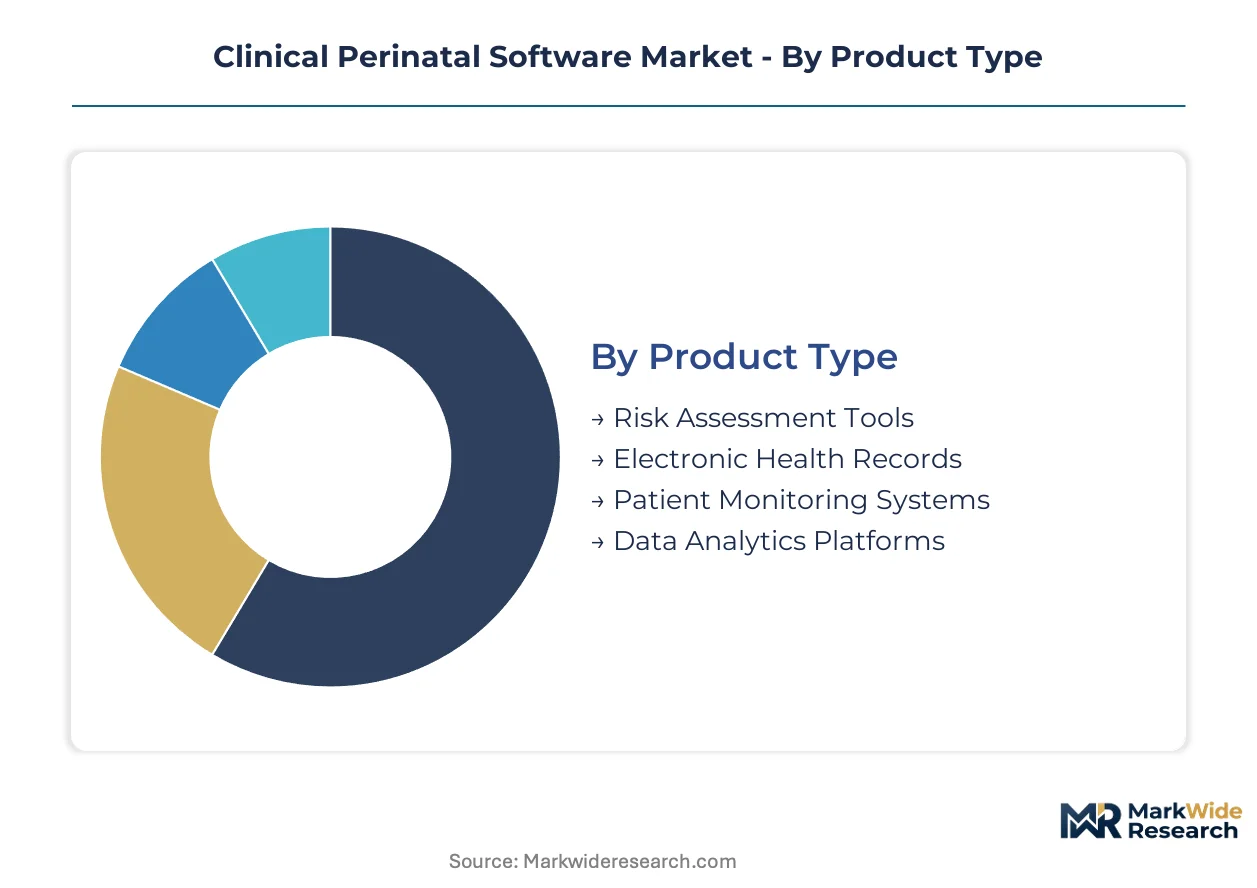
Clinical perinatal software segmentation highlights the diverse functional requirements across healthcare settings. Understanding these categories reveals where technological innovation is concentrating and how different user groups prioritize features. This granular view clarifies market opportunities for specialized solutions.
Product Type:
The product type segmentation reveals a clear distinction between core data management functionalities and advanced analytical capabilities that command premium pricing.
- Risk Assessment Tools:These software modules utilize AI and machine learning algorithms to analyze real-time fetal monitoring data and maternal health indicators, identifying potential complications early. Demand for these sophisticated tools is particularly strong in high-volume maternity hospitals in Germany, where patient safety protocols are stringent.
- Patient Monitoring Systems:These platforms integrate data from various medical devices, including fetal heart rate monitors and uterine activity sensors, providing clinicians with a consolidated view of patient status. Adoption is high in specialist clinics and birth centers seeking comprehensive, real-time oversight of labor and delivery.
- Electronic Health Records:Perinatal modules within broader EHR systems manage patient histories, appointment scheduling, and clinical documentation for pregnancy and postpartum care.
- Data Analytics Platforms:These systems process large datasets to identify trends, support research, and optimize resource allocation within perinatal care departments.
Today's leader: Patient Monitoring Systems. Tomorrow's challenger: Risk Assessment Tools.
Application:
Application segmentation illustrates how clinical perinatal software addresses distinct phases of maternal and fetal care, from initial pregnancy through neonatal support.
- Fetal Monitoring:This application involves the continuous tracking and interpretation of fetal heart rate, uterine contractions, and other vital signs during pregnancy and labor. Large hospitals in the United States prioritize these modules to enhance real-time decision support for obstetricians.
- Maternal Health Management:These applications encompass comprehensive care for the mother, including prenatal check-ups, medication management, and postpartum recovery tracking. Demand for these integrated platforms is expanding in Canada to support remote consultations and follow-ups in underserved regions.
- Prenatal Diagnosis:Software in this category aids in interpreting diagnostic tests and screenings, helping identify potential fetal abnormalities early in pregnancy.
- Neonatal Care:These modules manage data for newborns, including vital signs, feeding schedules, and developmental milestones, often integrating with hospital NICU systems.
Fetal monitoring applications currently account for the largest revenue share, while maternal health management is gaining share fastest.
End User:
The end-user segmentation highlights the varying operational scales and specific clinical requirements driving software adoption across different healthcare providers.
- Specialist Clinics:These facilities, often focusing on high-risk pregnancies or specific perinatal conditions, require highly specialized software for detailed patient management and advanced diagnostic integration. Investment is significant in urban centers of Japan, where specialized care is highly valued.
- Birth Centers:Standalone birth centers adopt software to manage patient flow, coordinate care, and ensure regulatory compliance in a more intimate, non-hospital setting. These centers in the United Kingdom increasingly favor cloud-based solutions for their lower operational overhead.
- Diagnostic Laboratories:These laboratories utilize perinatal software for managing test orders, processing results, and integrating genetic screening data for expectant parents.
- Research Institutes:Academic and medical research institutions leverage perinatal software for data collection, analysis, and clinical trial management related to maternal and child health.
Specialist clinics represent the primary revenue source, with birth centers showing a steep expansion trajectory.
Deployment:
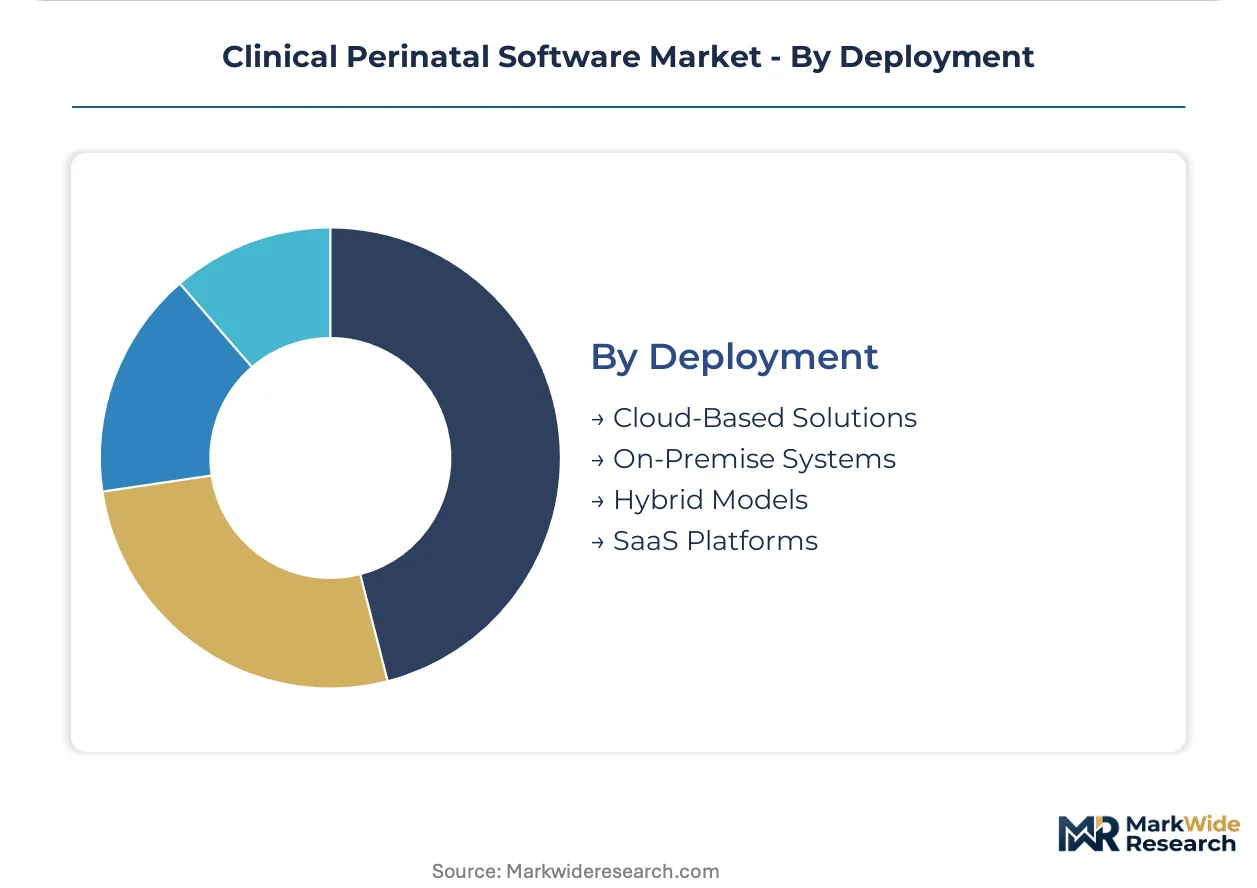
Deployment type segmentation reflects the infrastructure preferences of healthcare providers, balancing initial investment against long-term operational flexibility.
- Cloud-Based Solutions:These Software-as-a-Service (SaaS) platforms offer remote accessibility, automatic updates, and reduced upfront capital expenditure, appealing to smaller clinics and new birth centers. Adoption is particularly pronounced in North America due to mature cloud infrastructure and operational efficiency mandates.
- On-Premise Systems:Hosted directly on a healthcare institution's servers, these systems provide maximum control over data security and customization, favored by large hospital networks. Major hospitals in France continue to invest in on-premise solutions for their robust integration with existing legacy IT infrastructure.
- Hybrid Models:These models combine elements of both cloud and on-premise solutions, allowing healthcare providers to store sensitive data locally while leveraging cloud services for scalability.
- SaaS Platforms:SaaS platforms, a subset of cloud-based solutions, deliver perinatal software as a subscription service, minimizing IT management burdens for end-users.
On-premise systems retain a significant user base, but cloud-based solutions are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The varied regulatory landscapes across global healthcare markets influence where clinical perinatal software development and deployment concentrate. Stricter compliance mandates, such as the EU's Medical Device Regulation, necessitate significant investment, potentially shifting vendor focus to regions with clearer pathways or higher demand for compliant solutions. Vendors must navigate these diverse requirements for market entry and sustained growth.
United States
Demand for advanced perinatal software in the United States stems from large hospital networks seeking improved patient safety and data integration. HIPAA regulations compel providers to adopt secure systems for sensitive health information, driving investment. Major medical technology hubs like Boston and Silicon Valley see significant development in AI-driven diagnostic tools for obstetrics.
Germany
Germany's market for clinical perinatal software prioritizes risk assessment tools and stringent patient safety protocols in high-volume maternity hospitals. The EU's Medical Device Regulation (MDR) imposes rigorous clinical validation requirements on software classified as medical devices. Healthcare clusters in cities like Munich are actively adopting advanced analytical engines for real-time fetal monitoring interpretation.
Japan
Specialized clinics in Japan drive demand for highly detailed patient management and advanced diagnostic integration within perinatal care. PMDA regulations ensure software solutions meet high standards for medical device approval and data accuracy. Urban centers, particularly Tokyo, are hubs for specialized perinatal care, integrating sophisticated software for patient histories.
United Kingdom
The United Kingdom shows a strong preference for cloud-based SaaS perinatal software platforms, especially among independent birth centers. Data privacy laws like GDPR mandate secure and auditable systems, influencing procurement patterns. London and other major cities are seeing increased adoption of cloud infrastructure, prioritizing operational expenditure over large capital outlays for new systems.
Canada
Canada's demand for integrated maternal health management software is expanding to support remote prenatal consultations and postpartum follow-ups. Health Canada's regulatory framework guides the approval of medical devices, including perinatal software, ensuring patient safety. Telehealth integration is particularly crucial in underserved rural areas across provinces like Ontario and British Columbia.
Clinical Perinatal Software Market Key Industry Players
Established producers occupy the standard tier, offering comprehensive perinatal software solutions; emerging entrants pursue specialized AI-driven diagnostic functionalities. The market structure exhibits a tiered consolidation, with large healthcare technology conglomerates alongside niche analytics providers. Strategic archetypes include integrated EHR providers, specialized fetal monitoring software developers, and AI-focused risk assessment firms. Dominant competitive moves include strategic partnerships to enhance interoperability and portfolio diversification into new care modules.
Within the integrated solutions tier, GE HealthCare exemplifies a major provider leveraging an extensive hospital network to bundle software with its fetal monitoring hardware. Epic Systems, a prominent Electronic Health Record vendor, occupies a position integrating comprehensive perinatal modules within its broader healthcare IT ecosystem. Niche vendors like PeriGen, Inc. represent specialized analytics providers, focusing on advanced risk assessment functionalities tailored for labor and delivery units. These different approaches highlight the varied strategies for market penetration and value capture within the clinical perinatal software domain.
| Leading Market Players |
|---|
| Clinical Computer Systems, Inc. |
| Trium Analysis Online GmbH |
| GE HealthCare |
| Ascom Holding AG |
| Hill-Rom Holdings Inc. |
| Koninklijke Philips N.V. |
| Epic Systems |
| Sonio |
| PeriGen, Inc. |
| Others |
Cost & Logistics Intelligence
Healthcare providers' increasing preference for cloud-based SaaS models alters software delivery and pricing structures by shifting costs from capital expenditure to operational expenditure. This demand-side pressure necessitates flexible vendor offerings.
Pricing Analysis
Direct-to-customer software subscriptions often incorporate tiered pricing based on functionality and user volume. The dominant pricing model is subscription-based Software-as-a-Service, offering flexibility and continuous updates. Price differentiation stems from the level of customization required for integration and the extent of post-implementation support services. Pricing softness affects entry-level solutions due to increased competition from niche AI-driven firms, with smaller birth centers exhibiting higher price sensitivity.
Supply Chain Analysis
Direct sales teams and value-added resellers form the primary distribution channels for clinical perinatal software. Geographic development concentrates in the United States, Germany, and the United Kingdom, reflecting innovation hubs for medical technology. The supply chain relies heavily on skilled software developers and robust cloud infrastructure services for SaaS delivery. Data privacy regulatory fragmentation across regions, such as HIPAA and GDPR, presents a significant structural risk for multi-national vendors, complicating software integration with existing hospital IT systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The clinical perinatal software market offers geographic-arbitrage opportunities due to varying regulatory stringencies. For instance, the EU's MDR imposes higher clinical validation costs compared to less stringent frameworks in some emerging markets.
For Market Incumbents:Extend existing hospital network relationships by bundling advanced perinatal software with fetal monitoring hardware, mitigating the threat from niche AI-driven diagnostic firms. Deeply integrate perinatal modules within broader EHR ecosystems to create sticky, comprehensive solutions. Invest significantly in R&D for predictive analytics to maintain a technological edge. Focus on achieving seamless interoperability with diverse hospital IT systems to counter legacy system challenges.
For New Entrants and Emerging Players:Independent software integrators represent a key channel for new entrants to target underserved segments like standalone birth centers. Develop specialized postpartum care modules or integrate telehealth capabilities to address unmet needs in maternal health management. Offer cloud-based SaaS solutions with lower upfront costs to appeal to institutions with limited IT budgets. Focus on niche AI-driven diagnostic tools for early risk detection in high-risk obstetrics.
For Investors and Strategic Acquirers:Asymmetric upside sits with specialized analytics providers offering advanced AI-driven risk assessment tools, promising high growth over the next decade. Acquire firms with proven clinical validation under rigorous regulations like the EU's MDR. Target companies demonstrating strong data interoperability capabilities with existing EHR systems. A signal to watch for inflection is increased regulatory clarity and streamlined approval pathways for AI-based diagnostic software.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deepen modules within broader EHR systems for comprehensive patient views. |
| AI Diagnostic Development | Accelerate AI/ML algorithm development for real-time fetal monitoring interpretation. |
| Telehealth Capability Expansion | Integrate remote monitoring and virtual consultation features for maternal health. |
| SaaS Model Transition | Prioritize subscription-based cloud solutions for accessibility and operational efficiency. |
| Regulatory Compliance Investment | Strengthen clinical validation processes for medical device software in EU markets. |
Research Approach
Multiple input streams — primary interviews, secondary research, and market intelligence databases — were reconciled for a robust data foundation. Primary research involved discussions with obstetricians, hospital IT procurement managers, perinatal software developers, and regulatory compliance officers. Secondary validation drew from medical device regulatory filings, healthcare IT journals, and national health statistics. This approach utilized both bottom-up market sizing and top-down validation.
Historical data trends were cross-referenced against expert panel input to project market trajectories across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end user, deployment, and regional adoption patterns. Compound annual growth rates were derived through regression analysis, validated via expert consensus. Key forecast inputs included healthcare expenditure growth and global birth rate trends.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving regulatory changes and technological breakthroughs. Projections reflect current market assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Healthcare AIDC Market
Healthcare IT
Healthcare Credentialing Software Market
Healthcare IT
US Practice Management Systems Market
Healthcare IT
Pharmaceutical Quality Management Systems Market
Healthcare IT
Technology Spending on Revenue Cycle Management Market
Healthcare IT
Global Telepharmacy Market
Healthcare IT
Global Pharmaceutical Quality Management Software Market
Healthcare IT
Healthcare Technology Management Market
Healthcare IT
Asia-Pacific Dental Practice Management Software Market
Healthcare IT
Aged Care Software Market
Healthcare IT
Global Dermatology EMR Software Market
Healthcare IT
Asia Pacific Healthcare IT Market
Healthcare IT
IP-Based Nurse Call System Market
Healthcare IT
Chiropractic Software Market
Healthcare IT
Global IT Spending in Healthcare Market
Healthcare IT
Pharma Management Software Market