
 Global Healthcare Contract Development and Manufacturing Organization Market | 2026-2036
Global Healthcare Contract Development and Manufacturing Organization Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Contract Development and Manufacturing Organization Market Foresight
CGMP-plus specification tiers is rotating demand toward facilities capable of integrated biologics manufacturing. Lonza Group leverages its Swiss-based biologics network to anchor high-value antibody-drug conjugate production. Thermo Fisher Scientific sustains scale advantages across viral vector and plasmid manufacturing platforms. Samsung Biologics dominates capacity expansion in mammalian cell culture with purpose-built facilities in Songdo.
A healthcare contract development and manufacturing organization provides outsourced pharmaceutical development and production services encompassing formulation, analytical validation, clinical supply, and commercial-scale biologics manufacturing under quality-assured protocols. The primary purpose centers on enabling drug innovators to access specialized manufacturing infrastructure without capital-intensive facility ownership. Biopharmaceutical Manufacturing commands the largest value pool as complex protein therapies require dedicated single-use bioreactor trains and stringent contamination controls. Oncology as a therapy area absorbs disproportionate CDMO investment as antibody and cell therapy pipelines multiply. Cell Culture technology leads capital deployment decisions given its centrality to monoclonal antibody and recombinant protein output.
FDA enforces current Good Manufacturing Practice through facility inspections and process validation requirements that determine market access for US-bound drug products. EMA's Good Manufacturing Practice framework and the EU's Falsified Medicines Directive shape cross-border supply chain compliance obligations for European market participation. China's NMPA accelerates domestic biologics oversight through revised drug administration laws that elevate manufacturing quality benchmarks. Stakeholders must weigh regulatory divergence against consolidation economics when selecting multi-jurisdictional manufacturing partners.
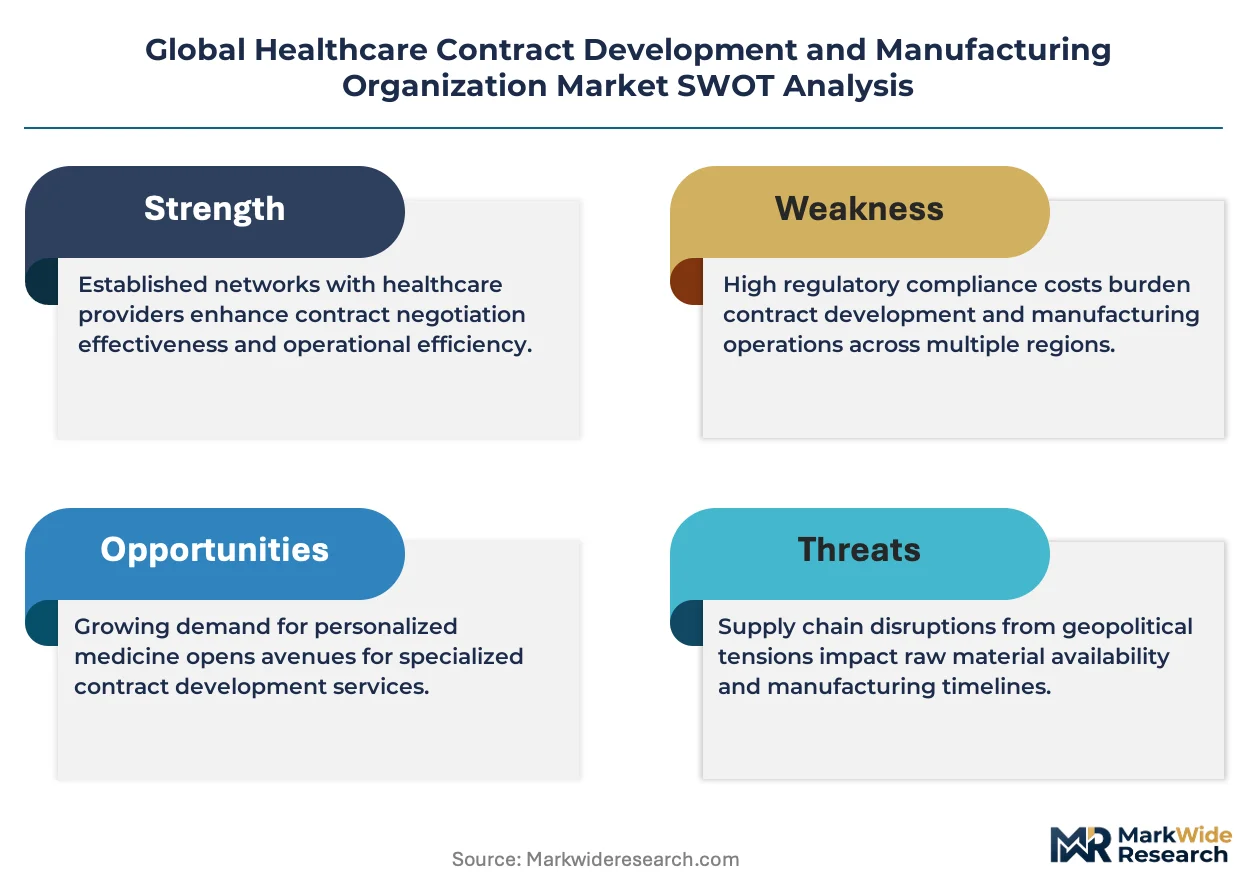
Market Dynamics
Single-use bioreactor technology is collapsing the economic threshold for commercial-scale biologics production, enabling virtual biotech firms to bypass fixed-asset ownership entirely and contract manufacturing capacity on demand.
Growth Catalysts
- FDA Process Validation Guidance:The agency's enhanced emphasis on continued process verification pushes drug sponsors toward CDMOs with established quality management systems and documented validation protocols.
- Antibody-Drug Conjugate Pipelines:Oncology developers require specialized conjugation facilities combining biologics fermentation with cytotoxic small-molecule handling, a capability set concentrated among outsourced providers.
- Songdo Biologics Cluster:Purpose-built manufacturing parks in South Korea attract multinational sponsors seeking mammalian cell culture capacity with integrated analytical and fill-finish services.
Market Restraints
- Stainless Steel Asset Stranding:Legacy fixed-tank facilities face utilization pressure as single-use systems reduce batch changeover time and cross-contamination risk.
- Chinese Heparin Supply Concentration:Raw material dependence on specific geographic sources for critical cell culture media components creates supply vulnerability.
- EMA Annex 1 Revision:Updated sterile manufacturing guidance imposes costly facility upgrades for contamination control strategy compliance across European-serving plants.
Strategic Opportunities
- Cell and Gene Therapy Viral Vectors:AAV and lentiviral production capacity remains structurally constrained, commanding premium pricing for qualified manufacturing slots.
- India CDSCO Manufacturing Linked Incentive:Domestic biologics production subsidies attract investment in biosimilar contract manufacturing infrastructure.
- Continuous Manufacturing Convergence:Integration of perfusion cell culture with continuous chromatography promises productivity gains for high-volume monoclonal antibodies.
Industry Challenges
- Qualified Personnel Scarcity:Cell culture process engineers with CGMP biologics experience command compensation premiums that compress CDMO margin structures.
- Multi-Product Facility Scheduling:Campaign changeover complexity increases operational risk as sponsors demand shorter lead times for clinical supply.
- Technology Transfer Timelines:Process knowledge documentation gaps between innovator and contract site extend validation phases and delay commercial revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Contract Development and Manufacturing Organization Market |
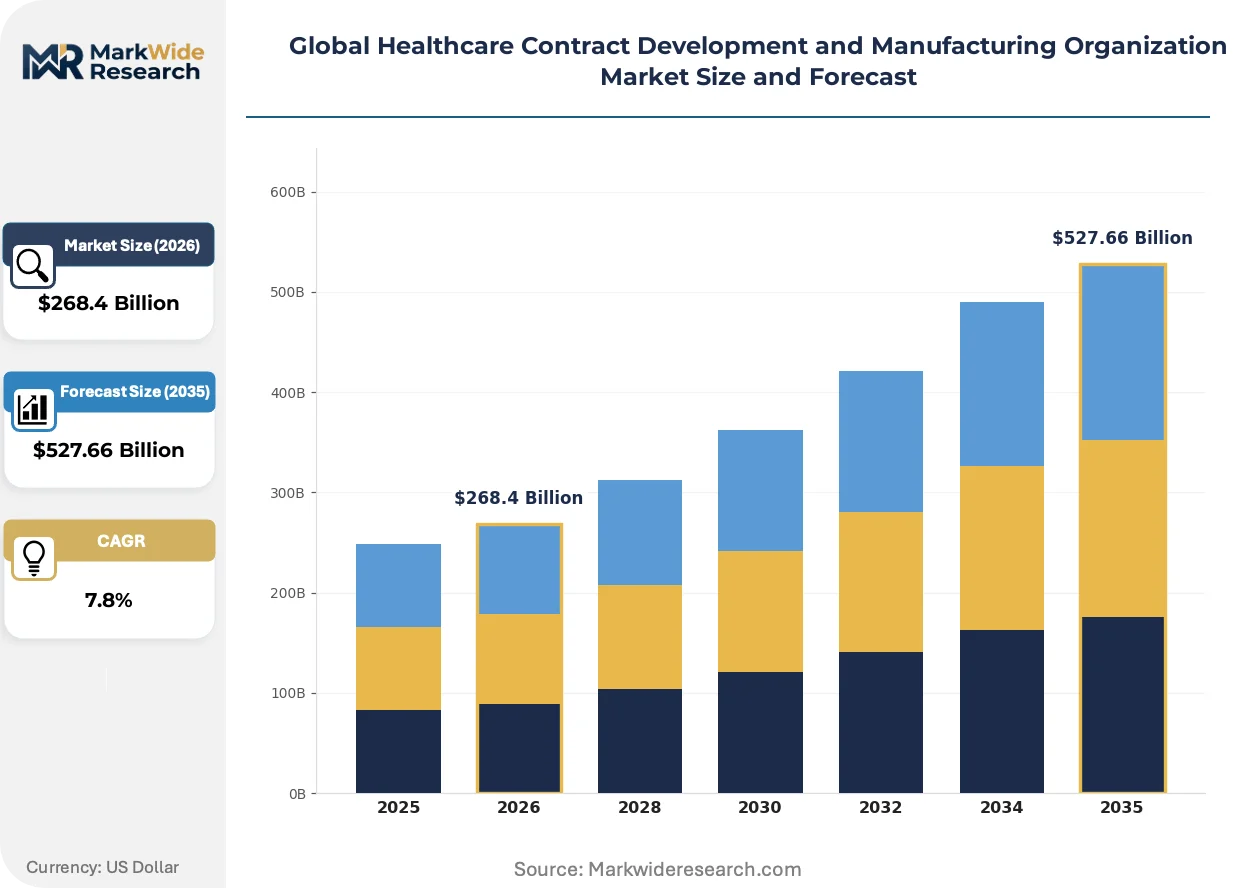
| Market Size in 2026 | $268.4 Billion |
| Market Size in 2035 | $527.66 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Formulation Development, Analytical Testing, Clinical Trial Supply, Chemistry Manufacturing Control, Regulatory Support, Biopharmaceutical Manufacturing Therapy Area: Oncology, Cardiovascular, Neurology, Infectious Diseases, Endocrinology, Autoimmune Disorders End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Diagnostic Developers Technology: Cell Culture, Microbial Fermentation, Synthetic Chemistry, High Throughput Screening, Bioconjugation |
| Companies Covered | Lonza Group, Thermo Fisher Scientific, Catalent, Samsung Biologics, WuXi Biologics, Boehringer Ingelheim, Patheon Pharma Services, Cambrex, Siegfried, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Contract Development and Manufacturing Organization Market Shifts & Advancements
Modular facility architectures and closed-system processing are compressing the capital-intensity of biologics manufacturing while expanding the geographic footprint of qualified production capacity.
Single-use bioreactor assemblies with integrated perfusion control systems are supplanting stainless steel vessels in new facility designs. Mid-size biotech sponsors now specify disposable trains for Phase III and commercial supply, eliminating cleaning validation burdens. This shift is compressing facility construction timelines from thirty-six to eighteen months.
EMA's revised Annex 1 on sterile manufacturing mandates enhanced barrier technology and environmental monitoring for fill-finish operations. CDMOs serving European markets must retrofit isolator lines and implement real-time particle detection. High-value injectable biologics manufacturers face the steepest compliance investment requirements.
Sponsor quality audits now precede formal request-for-proposal processes, reversing traditional procurement sequencing. Virtual biotech firms engage contract manufacturers for technical due diligence before molecule IND filing, embedding partnership selection into early-stage financing milestones. This pattern is most pronounced among Boston and San Francisco headquartered drug developers.
Global Healthcare Contract Development and Manufacturing Organization Market Segmentation
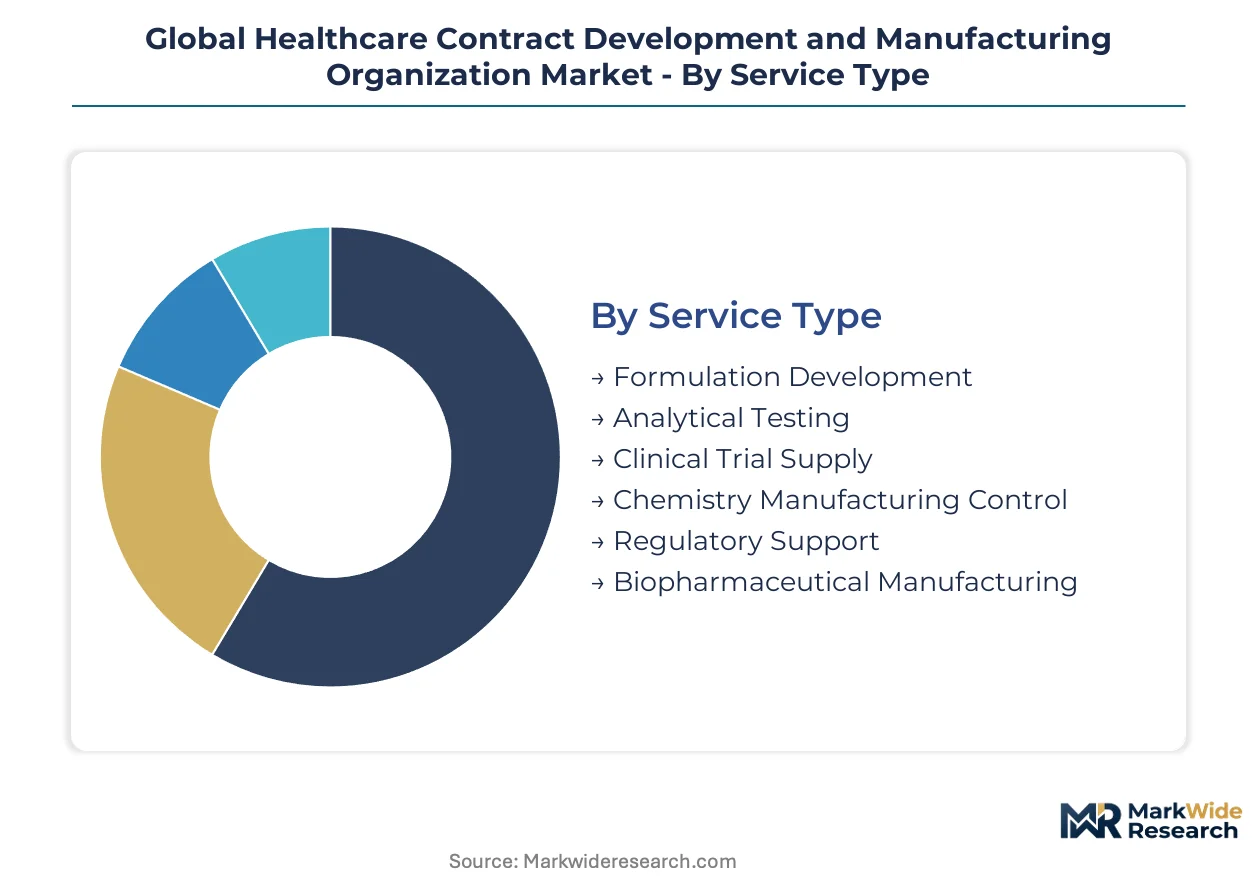
Segmentation reveals how CDMOs allocate capital across divergent technical capabilities and regulatory risk profiles. Service complexity and therapy modality dictate facility investment priorities and margin structures across the contract manufacturing landscape.
Service Type:
Biopharmaceutical Manufacturing faces acute substitution pressure from single-use technology platforms that collapse the economic case for stainless steel infrastructure. Formulation Development and Analytical Testing compete with in-house capabilities at large pharmaceutical sponsors.
- Biopharmaceutical Manufacturing:Mammalian cell culture and microbial fermentation at commercial scale require dedicated single-use bioreactor trains and stringent contamination controls. Demand concentrates in Switzerland and South Korea where purpose-built facilities serve global antibody and recombinant protein pipelines.
- Analytical Testing:Method development, stability studies, and release testing under CGMP protocols demand specialized instrumentation and documented validation packages. Biotechnology firms in Boston and San Francisco outsource these capabilities to accelerate IND timelines.
- Formulation Development:Preclinical and early-phase dosage form design including lyophilization and complex parenteral formulations.
- Clinical Trial Supply:Packaging, labeling, and distribution of investigational products with temperature-controlled logistics.
- Chemistry Manufacturing Control:Process chemistry optimization and scale-up for small-molecule APIs and intermediates.
- Regulatory Support:CMC documentation, FDA filing preparation, and agency response management.
Biopharmaceutical Manufacturing anchors the volume base while Regulatory Support gains share at the steepest rate as sponsors navigate divergent FDA, EMA, and NMPA submission requirements.
Therapy Area:
Cost tier differentiation separates oncology programs commanding premium pricing from commoditized cardiovascular manufacturing. High-complexity biologics drive facility specialization and capacity allocation decisions.
- Oncology:Antibody-drug conjugates, bispecific antibodies, and cell therapies require conjugation chemistry and viral vector production capabilities. Investment concentrates in CDMOs with cytotoxic handling licenses and isolator-based fill-finish lines.
- Cardiovascular:Established monoclonal antibodies and recombinant proteins face biosimilar competition and pricing pressure. Manufacturing specifications emphasize high-volume output and cost efficiency over technical novelty.
- Neurology:Blood-brain barrier penetration technologies and CNS-targeted delivery systems.
- Infectious Diseases:Vaccine bulk manufacturing and pandemic response capacity.
- Endocrinology:Peptide hormones and long-acting injectable formulations.
- Autoimmune Disorders:Established TNF inhibitors and emerging cytokine-targeting biologics.
Oncology commands the highest capacity premiums while Infectious Diseases shows the steepest expansion trajectory following pandemic-era government stockpiling programs.
End User:
Customer type determines contract structure, with virtual biotechnology firms demanding fully integrated services and large pharmaceutical companies cherry-picking specific capabilities.
- Biotechnology Firms:Venture-backed drug developers without manufacturing infrastructure outsource entire value chains from cell line development through commercial supply. These sponsors prioritize speed and regulatory documentation over unit cost.
- Pharmaceutical Companies:Established manufacturers use CDMOs for capacity overflow, geographic expansion, and specialized modalities outside core expertise. Procurement emphasizes audit-ready quality systems and multi-site redundancy.
- Research Institutions:Academic medical centers and nonprofit developers with limited manufacturing scale.
- Diagnostic Developers:Companion diagnostic and biomarker assay manufacturers requiring GMP reagent production.
Pharmaceutical Companies provide the most stable revenue base while Biotechnology Firms expand most quickly as capital flows into virtual drug development models.
Technology:
Supply concentration in Cell Culture expertise creates bottlenecks that reshape competitive positioning across the manufacturing value chain. Platform selection locks sponsors into specific CDMO partnerships for program duration.
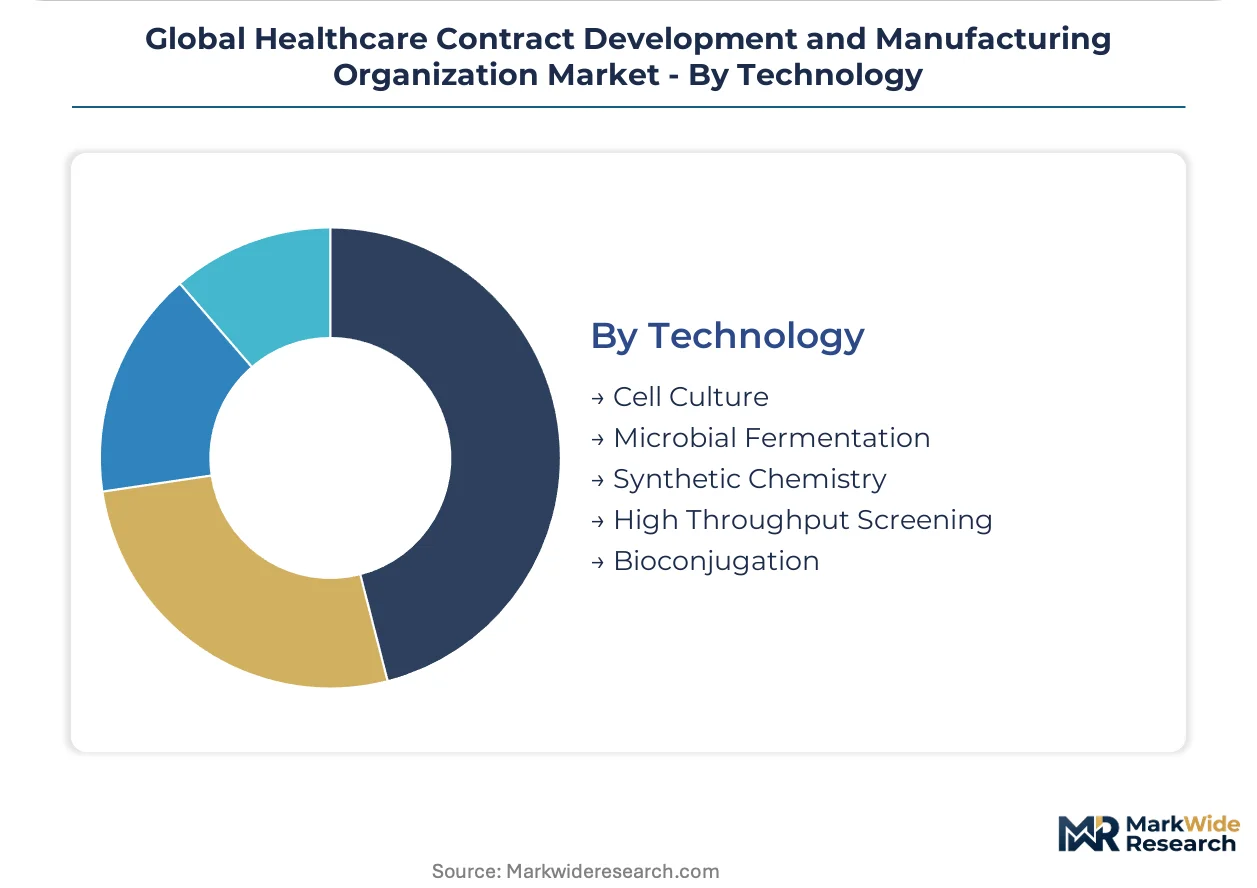
- Cell Culture:Mammalian expression systems for monoclonal antibodies and recombinant proteins dominate commercial biologics output. Perfusion bioreactor technology and continuous processing are displacing fed-batch methods for high-titer production.
- Bioconjugation:Covalent linkage of cytotoxic payloads to antibodies demands specialized containment facilities and handling protocols. Qualified capacity remains structurally constrained, commanding premium pricing and long-term contracting.
- Microbial Fermentation:Bacterial and yeast systems for insulin, growth factors, and smaller therapeutic proteins.
- Synthetic Chemistry:Small-molecule API synthesis and route optimization for oral drug products.
- High Throughput Screening:Automated assay platforms for process development and quality attribute monitoring.
Cell Culture anchors the volume base while Bioconjugation climbs the fastest as antibody-drug conjugate pipelines multiply and qualified manufacturing slots remain scarce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDMO capacity clusters in three national jurisdictions where regulatory stringency and infrastructure investment converge. Switzerland, the United States, and South Korea host purpose-built biologics manufacturing parks that serve multinational drug sponsors seeking mammalian cell culture and viral vector production capabilities.
Switzerland
Basel and Visp anchor high-value antibody-drug conjugate manufacturing for oncology pipelines. Swissmedic enforces stringent GMP standards that qualify facilities for simultaneous FDA and EMA submissions. Lonza Group operates integrated biologics networks across the Basel region, combining microbial fermentation with cytotoxic conjugation suites.
United States
Greater Boston and San Francisco Bay Area biotech clusters outsource entire manufacturing value chains to CDMO partners. FDA process validation guidance pushes sponsors toward contract manufacturers with documented continued process verification protocols. Thermo Fisher Scientific maintains viral vector and plasmid production platforms across Massachusetts and California facilities.
South Korea
Songdo International Business District concentrates mammalian cell culture capacity with integrated analytical and fill-finish services. MFDS accelerates domestic biologics oversight through revised drug administration laws that elevate manufacturing quality benchmarks. Samsung Biologics dominates capacity expansion with purpose-built single-use bioreactor trains in Incheon.
Germany
Bavaria and North Rhine-Westphalia host established pharmaceutical manufacturers expanding into contract services for biologics overflow. EMA Annex 1 revision imposes costly facility upgrades for contamination control strategy compliance across German-serving plants. Boehringer Ingelheim leverages Ingelheim-based infrastructure for mammalian cell culture and bioconjugation capabilities.
China
Yangtze River Delta biologics parks attract multinational sponsors seeking cost-competitive mammalian cell culture capacity. NMPA accelerates domestic biologics oversight through revised drug administration laws that elevate manufacturing quality benchmarks. WuXi Biologics anchors integrated discovery-to-manufacturing services across Shanghai and Wuxi facilities.
Global Healthcare Contract Development and Manufacturing Organization Market Competitive Landscape
Concentration sits with diversified life science conglomerates and specialized biologics pure-plays. The vendor base stratifies across three tiers: global diversified players with multi-modality platforms, regional specialists with deep cell culture expertise, and emerging challengers in viral vector and cell therapy manufacturing. Strategic moves center on capacity expansion in mammalian cell culture and selective M&A to acquire bioconjugation capabilities.
Among Swiss-based integrated players, Lonza Group exemplifies the high-value manufacturing archetype with dedicated antibody-drug conjugate infrastructure. Thermo Fisher Scientific represents the diversified conglomerate model spanning analytical services through commercial biologics production. Samsung Biologics anchors the scale-driven Asian specialist tier with purpose-built mammalian cell culture capacity in Songdo.
| Leading Market Players |
|---|
| Lonza Group |
| Thermo Fisher Scientific |
| Catalent |
| Samsung Biologics |
| WuXi Biologics |
| Boehringer Ingelheim |
| Patheon Pharma Services |
| Cambrex |
| Siegfried |
| Others |
Supply & Pricing Matrix
Single-use bioreactor assemblies displacing stainless steel infrastructure simultaneously redraw supply geography toward South Korea and Switzerland while collapsing the capital barrier that once protected incumbent pricing power. This substitution dynamic compresses facility construction timelines from thirty-six to eighteen months, enabling virtual biotech sponsors to negotiate manufacturing slots across multiple qualified sites rather than accepting captive pricing from asset-heavy providers.
Pricing Analysis
FDA process validation guidance dictates the pricing tier structure across the contract manufacturing landscape, separating CDMOs with documented continued process verification protocols from facilities requiring costly remediation. Three-tier pricing structure across premium, standard, and economy levels reflects facility certification grade and volume commitment scale, with oncology antibody-drug conjugate manufacturing commanding the steepest premiums. Cost compression in mammalian cell culture capacity is intensifying because Samsung Biologics and WuXi Biologics are expanding purpose-built single-use trains. Virtual biotechnology firms in Boston and San Francisco demonstrate the least price sensitivity, prioritizing speed-to-IND and regulatory documentation over unit manufacturing cost.
Supply Chain Analysis
Extended lead times for qualified single-use bioreactor assemblies and cell culture media components are forcing sponsors to secure multi-year supply agreements eighteen to twenty-four months ahead of clinical manufacturing campaigns. Manufacturing capacity concentrates in Switzerland, the United States, and South Korea, with raw material dependencies drawing from Chinese heparin suppliers and German specialty chemical producers for critical cell culture additives. Single-source vulnerability sits with geographic concentration of cytotoxic payload manufacturing for antibody-drug conjugates. Distribution runs through temperature-controlled logistics networks anchored by purpose-built biologics parks in Basel, Songdo, and Greater Boston.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent CDMOs face substitution pressure from modular facility architectures and closed-system processing technologies that enable new entrants to bypass legacy capital requirements. The threat of virtual biotech sponsors building captive manufacturing through single-use platforms demands defensive repositioning.
For Market Incumbents: Fortify bioconjugation capabilities through selective capacity addition in Switzerland or South Korea, where cytotoxic handling licenses create defendable moats. Secure backward integration into cell culture media production to reduce Chinese heparin supply concentration. EMA Annex 1 revision mandates isolator line investments that favor scaled players with balance sheet capacity.
For New Entrants and Emerging Players: Lead with viral vector manufacturing for cell and gene therapy applications, where AAV and lentiviral production capacity remains structurally constrained and commands premium pricing. Target the Songdo biologics cluster for mammalian cell culture partnerships with Korean domestic sponsors seeking MFDS-qualified export capacity. Position around continuous manufacturing convergence, integrating perfusion cell culture with continuous chromatography for productivity differentiation.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized biologics pure-plays with differentiated modality expertise over diversified conglomerates. Long-term viability across the projection horizon hinges on regulatory certification depth rather than geographic cost arbitrage alone. Watch for FDA warning letter issuance rates as an inflection indicator for quality system differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Purpose-built single-use bioreactor trains in Songdo anchor Samsung Biologics capacity leadership. |
| Regulatory Approval Pathway | Swissmedic GMP standards qualify Lonza facilities for simultaneous FDA and EMA submissions. |
| Backward Integration | Captive cell culture media production insulates against Chinese heparin supply concentration. |
| Technology Licensing | Perfusion bioreactor control systems license from specialized vendors accelerates facility commissioning. |
| Joint Venture | Partnerships between Boston virtual biotech firms and CDMOs embed manufacturing selection into Series B milestones. |
Research Methodology
Operator-level perspectives from cell culture process engineers, regulatory affairs leads at CDMOs, biotech CMC executives, and hospital pharmacy procurement managers anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 483 inspection databases, EMA GMP certificates, ClinicalTrials.gov manufacturing location disclosures, and MFDS biologics approval records. Bottom-up capacity modeling across single-use bioreactor installations triangulated against top-down sponsor outsourcing spend estimates.
Sensitivity analysis tested forecast outputs against variable assumptions for mammalian cell culture capacity utilization, antibody-drug conjugate pipeline progression, and regulatory inspection failure rates across the analysis window. Segmentation dimensions modeled encompassed service type complexity tiers, therapy area cost structures, end-user contract archetypes, and technology platform selection. CAGRs derived from capacity expansion announcements, sponsor pipeline disclosures, and historical outsourcing penetration trends. Industry-specific inputs included bioreactor productivity curves and batch failure probability distributions.
Underlying assumptions cover continued single-use technology adoption, stable FDA and EMA regulatory stringency, and sustained venture capital flow into virtual biotech models, with deviation risk concentrated in Chinese raw material export restrictions and qualified personnel scarcity. Revision becomes warranted when EMA Annex 1 compliance cost estimates or viral vector manufacturing yield improvements cross thresholds that reshape facility investment economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
US Primary Care Physicians Market
Healthcare Services
US Biopharmaceutical Third-Party Logistics Market
Healthcare Services
Per Diem Nurse Staffing Market
Healthcare Services
Global Cath Lab Services Market
Healthcare Services
Healthcare CMO Market
Healthcare Services
US Concierge Medicine Market
Healthcare Services
South Korea Healthcare Cold Chain Logistics Market
Healthcare Services
Western Europe Medical Recruitment Market
Healthcare Services
In-Home Senior Care Franchises Market
Healthcare Services
United States Senior Living Market
Healthcare Services
Biopharmaceutical Third Party Logistics (3PL) Market
Healthcare Services
Healthcare Third-Party Logistics Market
Healthcare Services
Healthcare Cold Chain Logistics Market
Healthcare Services
Metabolomics Services Market
Healthcare Services
Hair Restoration Services Market
Healthcare Services
Medical Case Management Services Market