
 Power Boiler Market | 2026-2036
Power Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Power Boiler Market Outlook
Long-term service agreements for boiler maintenance and digital performance monitoring is pivoting vendor-customer relationships toward recurring revenue models. Babcock & Wilcox Enterprises leverages its aftermarket parts network to sustain renewal rates across North American utility fleets. Mitsubishi Heavy Industries anchors its position through proprietary supercritical steam cycle technology. Siemens AG competes on integrated digital twin platforms that optimize combustion efficiency and reduce unplanned outages.
A power boiler is a pressure vessel system designed to convert water into steam through thermal energy transfer, operating at temperatures exceeding 540°C and pressures above 24 MPa in supercritical configurations to drive turbine generators for electricity production. Water-tube designs dominate utility-scale installations where higher pressures and outputs are required, while biomass fuel types are gaining traction as utilities seek to co-fire or fully convert from coal to meet decarbonization targets. The power generation end user segment remains the primary demand anchor, though chemical and food processing applications provide specialized opportunities for smaller-capacity industrial units.
The EPA enforces Maximum Achievable Control Technology standards that mandate emissions reductions from fossil fuel-fired boilers, while the EU Industrial Emissions Directive imposes best available technique requirements on large combustion plants. ISO 16528 provides international safety and performance benchmarks for boiler construction and operation. Stakeholders must monitor evolving carbon border mechanisms and technology-neutral capacity auctions that will determine whether supercritical upgrades or fuel switching delivers superior returns on existing asset bases.
Market Dynamics
The transition from subcritical to supercritical and ultra-supercritical steam cycles is compressing plant footprints while demanding precision metallurgy and advanced control systems, fundamentally restructuring vendor capability requirements and procurement evaluation criteria across utility fleets.
Growth Catalysts
- India's Ultra-Supercritical Tender Pipeline:NTPC and state generation companies are soliciting bids for high-efficiency coal units that cut CO2 intensity per megawatt-hour, creating sustained order backlogs for domestic and international boiler fabricators.
- EU Industrial Emissions Directive Retrofit Mandates:Best available technique requirements for large combustion plants are compelling utilities across Germany, Poland, and the Czech Republic to upgrade existing subcritical assets or face forced retirement.
- Southeast Asia Baseload Expansion:Power generation utilities in Vietnam, Indonesia, and the Philippines are adding supercritical capacity to displace aging oil-fired peaking plants and stabilize grid frequency against renewable intermittency.
Market Restraints
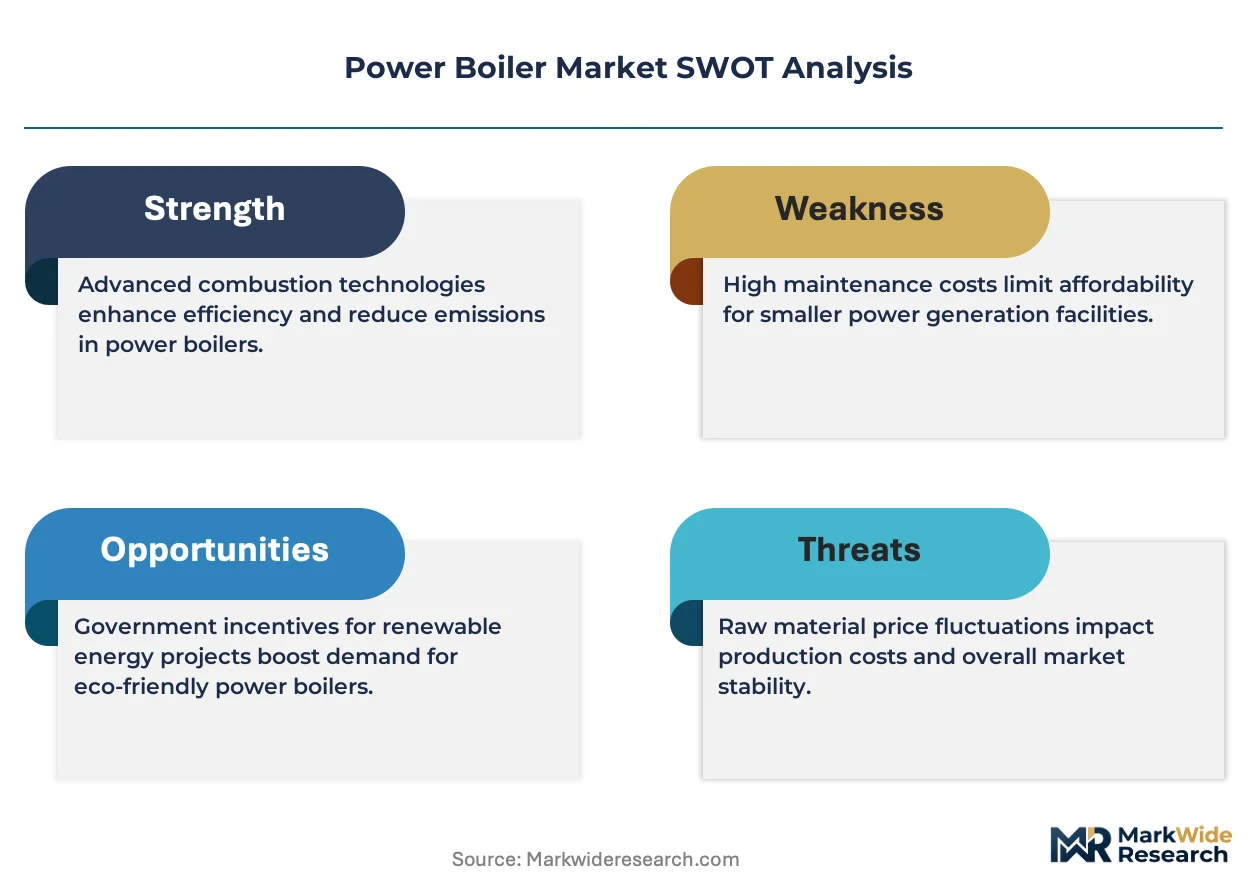
- Specialized Alloy Supply Concentration:High-nickel superalloys for supercritical water walls and headers depend on a narrow supplier base concentrated in Japan and Germany, exposing project timelines to raw material bottlenecks.
- EPA Maximum Achievable Control Technology Compliance Costs:Retrofitting existing coal-fired units with selective catalytic reduction and fabric filters imposes capital burdens that erode residual asset life economics for mid-sized utilities.
- Biomass Co-Firing Technical Limits:Corrosion from alkali chlorides in agricultural residues restricts co-firing ratios in existing pulverized coal boilers without comprehensive furnace redesign and materials replacement.
Strategic Opportunities
- Digital Twin Integration:Real-time combustion optimization and predictive maintenance platforms are automating performance monitoring, enabling vendors to capture recurring revenue through long-term service agreements rather than one-time equipment sales.
- India's National Clean Air Programme:Emission reduction targets for thermal power plants are accelerating demand for flue gas desulfurization retrofits and efficiency upgrades that extend boiler operational life.
- Hydrogen-Ready Boiler Development:Burner and combustion system modifications capable of firing hydrogen-natural gas blends are positioning early movers for carbon-neutral heat and power applications in European industrial clusters.
Industry Challenges
- Welding and NDT Specialist Shortages:Supercritical pressure vessel fabrication demands certified welders and ultrasonic inspection technicians that outstrip current training pipeline output in North America and Western Europe.
- ISO 16528 Certification Timeline Compression:Third-party verification of design calculations, material traceability, and pressure testing for export markets extends project schedules by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Boiler Market |
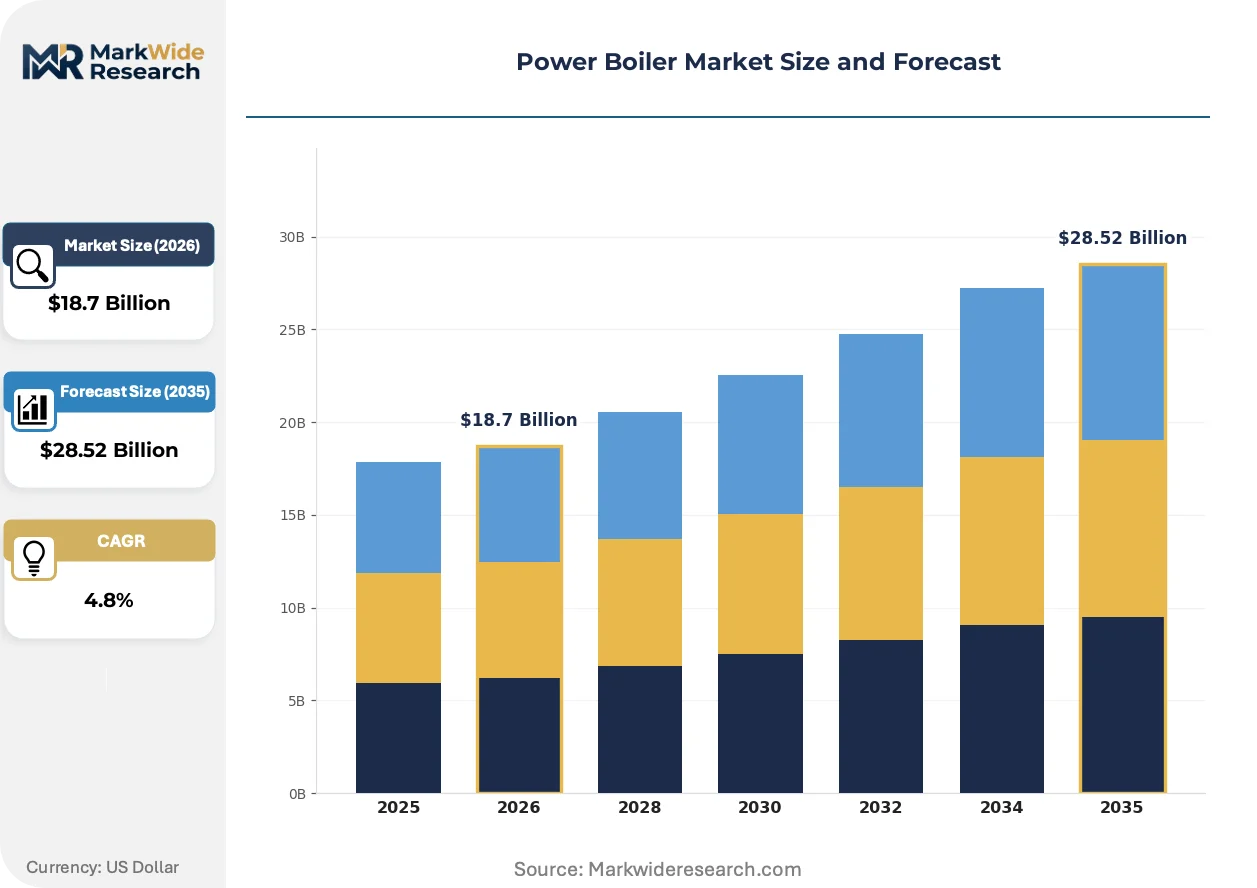
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-Tube, Water-Tube, Supercritical, Natural Circulation Fuel Type: Natural Gas, Coal, Biomass, Oil End User: Power Generation, Manufacturing, Chemical, Food Processing Installation Type: Onshore, Offshore, Modular, Fixed |
| Companies Covered | General Electric Company, Babcock & Wilcox Enterprises, Inc., Mitsubishi Heavy Industries, Ltd., Siemens AG, Doosan Corporation, Dongfang Electric Corporation, IHI Corporation, Bharat Heavy Electricals Limited, Andritz Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Boiler Market Strategic Shifts
Intelligent combustion control, advanced materials science, and evolving procurement architectures are compressing operational margins and reshaping how utilities evaluate total cost of ownership across boiler lifecycles.
Advanced sensor arrays coupled with machine learning algorithms are automating real-time stoichiometric adjustment and sootblowing optimization in supercritical units. Large independent power producers in Texas and the UK are deploying these systems to reduce heat rate penalties and minimize forced outage frequency. The technology is automating what previously required continuous operator intervention, compressing staffing models and shifting value capture toward software-enabled service providers.
The EU F-Gas Regulation phase-down of hydrofluorocarbons is accelerating adoption of ammonia and CO2-based heat pump integration for feedwater preheating in combined heat and power configurations. Industrial operators in Germany and the Netherlands are retrofitting auxiliary systems to comply with refrigerant restrictions while recovering low-grade waste heat. Cogeneration facilities serving district heating networks in Scandinavia face the most compressed compliance timelines and are driving supplier innovation in closed-loop thermal management.
Long-term availability guarantees are displacing traditional equipment-only procurement across Southeast Asian utility tenders. State generation companies in Vietnam and Indonesia now require fifteen to twenty-year parts and service commitments bundled with initial supply contracts. This restructuring concentrates vendor selection criteria on aftermarket network density and spare parts inventory depth rather than upfront capital cost alone.
Power Boiler Market Segmentation
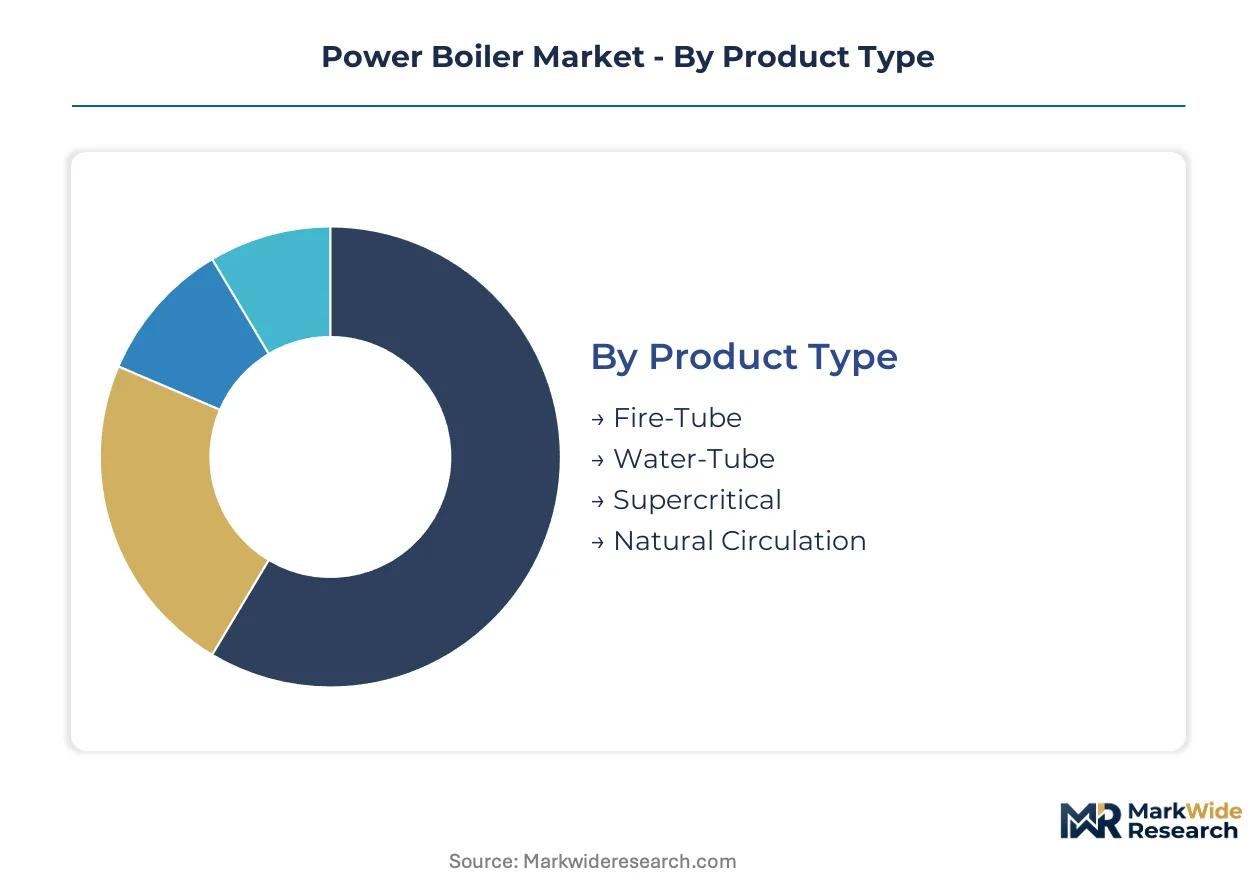
Power boiler procurement decisions hinge on pressure ratings, fuel compatibility, and emissions compliance—variables that segment the market into technically distinct categories with divergent certification burdens and supplier qualification requirements. Understanding these divisions clarifies where capital concentrates and which technology pathways utilities prioritize under tightening environmental mandates.
Product Type:
ISO 16528 certification applies universally, yet supercritical and ultra-supercritical designs trigger additional ASME Section I and EN 12952 compliance reviews due to elevated pressure boundaries and specialized alloy specifications.
- Water-Tube:High-pressure designs circulate water through tubes heated externally by combustion gases, enabling steam pressures above 24 MPa required by supercritical cycles. Demand concentrates in Indian utility tenders where NTPC specifies water-tube architectures for new ultra-supercritical installations to maximize thermal efficiency and reduce CO2 intensity per megawatt-hour.
- Supercritical:Operating above water's critical point eliminates distinct liquid-vapor phase separation, boosting thermal efficiency to 45% or higher. Southeast Asian baseload expansion in Vietnam and Indonesia drives procurement, with state gencos requiring integrated digital control systems and fifteen-year service commitments to manage metallurgical stress and thermal cycling fatigue.
- Fire-Tube:Lower-pressure designs route combustion gases through tubes immersed in water, suited for industrial steam loads below 20 bar. Chemical plants in Germany and food processors in the Netherlands specify these for saturated steam applications where supercritical pressures are unnecessary.
- Natural Circulation:Density differentials between heated and unheated water columns drive flow without pumps, simplifying maintenance but limiting pressure capability. Aging subcritical coal fleets in Poland and the Czech Republic retain these designs, though EU Industrial Emissions Directive retrofit mandates are accelerating replacement timelines.
Water-tube sits at the top of the volume ranking, with supercritical climbing the fastest.
Fuel Type:
Emissions intensity and fuel availability reshape procurement economics, with regulatory pressure forcing utilities to weigh conversion costs against carbon border exposure and technology-neutral capacity auction eligibility.
- Coal:Pulverized coal combustion dominates existing installed base, particularly across Germany, Poland, and India where domestic reserves or import infrastructure anchor fuel security. EPA Maximum Achievable Control Technology and EU Best Available Technique requirements are compelling selective catalytic reduction retrofits and flue gas desulfurization additions that extend operational life where residual asset economics permit.
- Natural Gas:Combined cycle configurations achieve lower capital cost and faster ramp rates than coal, positioning gas-fired boilers for grid balancing roles against renewable intermittency. Texas independent power producers and UK unregulated generators are deploying these for frequency stabilization, leveraging domestic shale or North Sea supply.
- Biomass:Agricultural residues and forestry waste enable partial or full coal displacement, though alkali chloride corrosion constrains co-firing ratios in existing pulverized coal furnaces without comprehensive water wall replacement. Scandinavian district heating networks and Dutch industrial clusters are driving demand for purpose-built biomass grate designs.
- Oil:Distillate and residual fuel oils retain niche roles in peaking plants and island grids lacking pipeline gas access. Aging oil-fired units in the Philippines and Indonesia face displacement by supercritical coal as baseload requirements harden.
Coal retains the largest installed footprint, though natural gas is gaining share fastest where pipeline infrastructure exists.
End User:
Scale requirements and steam quality specifications divide the market between utility-scale electricity production and process-industrial thermal loads with divergent pressure, purity, and reliability demands.
- Power Generation:Centralized electricity production requires supercritical steam conditions, emissions controls, and grid-synchronized output. Indian state gencos and Southeast Asian independent power producers anchor procurement volume, with tender structures increasingly bundling long-term service agreements and digital performance monitoring.
- Chemical:Process steam for cracking, distillation, and reaction vessels demands precise pressure and temperature control, often with redundancy requirements for continuous operations. German chemical parks and US Gulf Coast petrochemical complexes specify these for captive power and thermal integration.
- Manufacturing:General industrial steam loads span textile, paper, and primary metals applications with moderate pressure requirements. These installations concentrate in regions with district heating network access or cogeneration incentives.
- Food Processing:Sanitary steam specifications and batch operational patterns favor smaller-capacity fire-tube or low-pressure water-tube designs. Dutch and Danish food processors prioritize these for pasteurization and sterilization duties.
Power generation commands the dominant revenue share, with chemical processing expanding most quickly on reshoring and feedstock cost volatility.
Installation Type:
Site constraints and construction logistics determine whether boilers ship as field-erected components or pre-assembled modular packages, with implications for project timeline, labor requirements, and quality assurance.
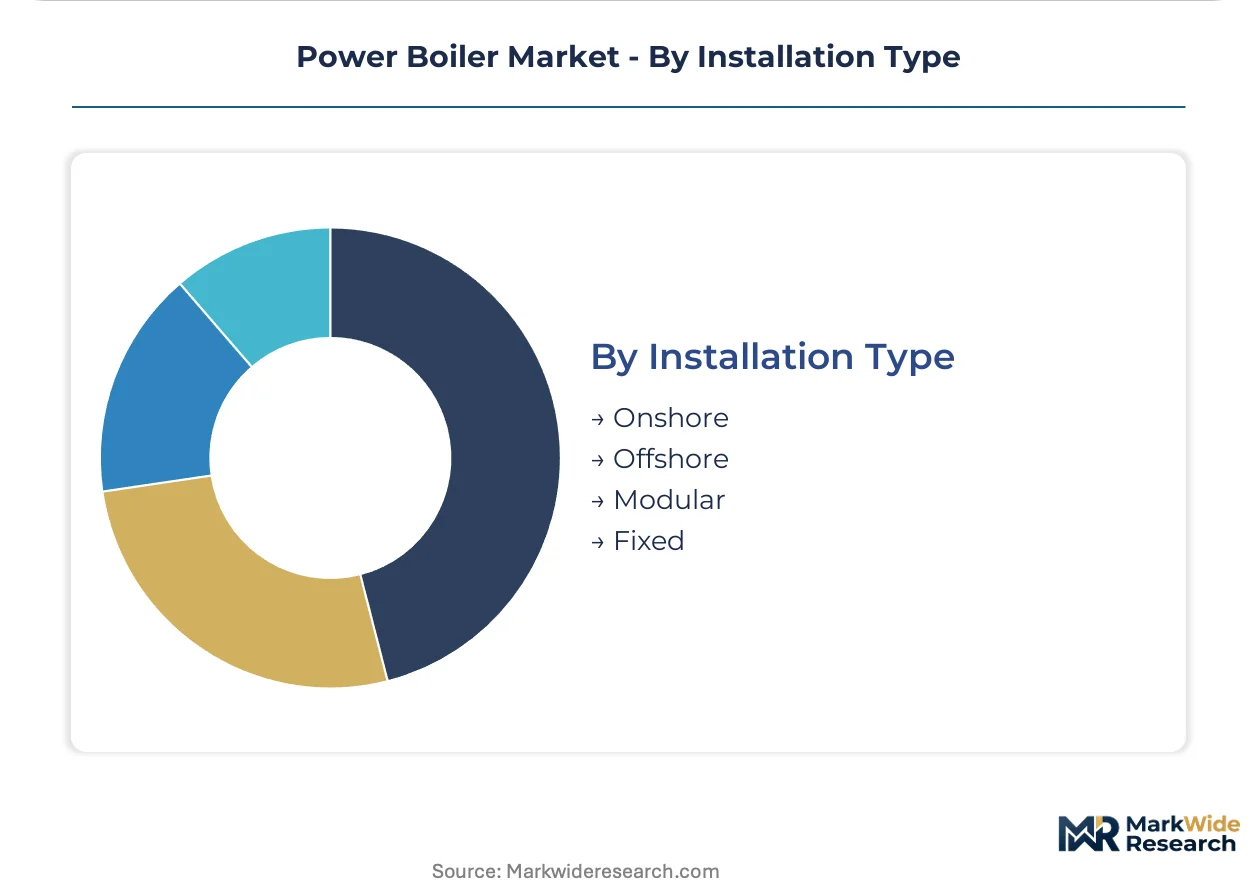
- Onshore:Conventional field construction at permanent utility or industrial sites enables maximum unit scale and customization. Indian ultra-supercritical tenders and German retrofit projects follow this model, with extended ISO 16528 certification timelines for third-party design verification and pressure testing.
- Modular:Shop-fabricated modules reduce field welding and accelerate commissioning, trading some customization for schedule certainty. Southeast Asian utilities in Vietnam and Indonesia are specifying these for remote sites with limited skilled labor availability.
- Fixed:Permanent foundations and integrated civil works anchor large utility installations with forty-year design lives. These dominate coal and gas-fired baseload procurement.
- Offshore:Platform-mounted boilers serve oil and gas production facilities with space-weight constraints and marine environmental exposure. North Sea and Gulf of Mexico installations require specialized corrosion protection and compact footprints.
Onshore fixed installations lead by unit scale, with modular approaches climbing fastest where construction labor shortages compress project schedules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India tenders more ultra-supercritical capacity than Germany retrofits, yet both markets reshape vendor order books through divergent regulatory pathways. Southeast Asian utilities add baseload units as European operators face forced retirement deadlines. Procurement patterns fragment across emissions compliance timelines and fuel security priorities.
India
NTPC and state generation companies tender supercritical and ultra-supercritical installations to cut CO2 intensity per megawatt-hour. The Central Electricity Authority mandates emission norms for thermal power plants that accelerate flue gas desulfurization retrofits. Fabricators cluster around manufacturing hubs in Maharashtra and Gujarat where domestic boiler component supply chains deepen.
Germany
Utilities retrofit aging subcritical coal fleets or retire units ahead of EU Industrial Emissions Directive deadlines. The country's national climate protection program forces best available technique upgrades across large combustion plants. Industrial clusters in North Rhine-Westphalia concentrate engineering expertise for selective catalytic reduction and efficiency optimization projects.
United States
Independent power producers in Texas deploy gas-fired combined cycle boilers for grid balancing against renewable intermittency. EPA Maximum Achievable Control Technology standards impose selective catalytic reduction and fabric filter retrofits on existing coal units. Equipment suppliers concentrate aftermarket service networks around legacy utility fleets in the Midwest and Southeast.
Vietnam
State generation companies add supercritical coal capacity to displace aging oil-fired peaking plants and stabilize grid frequency. Power development plans prioritize baseload expansion to meet industrial demand growth in the Red River Delta and Mekong Delta regions. Tender structures now bundle fifteen-year parts and service commitments with initial equipment supply.
Poland
Utilities confront EU Industrial Emissions Directive retrofit mandates for natural circulation subcritical boilers or face accelerated retirement. The country's national energy security priorities sustain coal-fired generation despite tightening environmental standards. Upper Silesian industrial districts concentrate the largest remaining fleet of aging units requiring metallurgical assessment and control system upgrades.
Power Boiler Market Competitive Environment
Top-tier vendors anchor utility-scale procurement, while mid-tier fabricators compete on regional aftermarket density and modular delivery speed. Market structure tilts toward consolidated supercritical technology holders with integrated digital platforms. Three archetypes dominate: full-cycle engineering conglomerates with proprietary steam cycle IP, specialized boiler fabricators with deep alloy welding capabilities, and aftermarket service networks capturing recurring revenue through long-term availability guarantees. Competitive moves concentrate on strategic partnerships for hydrogen-ready combustion development and geographic expansion into India's tender pipeline.
Within the full-cycle engineering tier, General Electric Company and Siemens AG exemplify integrated platform strategies that bundle digital twin monitoring with equipment supply. Mitsubishi Heavy Industries, Ltd. occupies a position anchored in supercritical steam cycle technology specialization. These three represent divergent pathways for capturing value as procurement shifts from capital sales toward outcome-based service agreements.
| Leading Market Players |
|---|
| General Electric Company |
| Babcock & Wilcox Enterprises, Inc. |
| Mitsubishi Heavy Industries, Ltd. |
| Siemens AG |
| Doosan Corporation |
| Dongfang Electric Corporation |
| IHI Corporation |
| Bharat Heavy Electricals Limited |
| Andritz Group |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed fabricators in India and China anchor supply capacity for supercritical pressure vessels, compressing price discipline among private-equity-rolled-up European specialists who must defend aftermarket service margins against bundled long-term availability guarantees.
Pricing Analysis
Capacity additions in India are reshaping price floors for water-tube supercritical units as domestic fabricators leverage localized alloy sourcing and reduced import duties under the PLI scheme. Project-based pricing dominates utility tenders, with differentiation driven by ISO 16528 certification tier and bundled fifteen-year service commitments. Cost compression in standard-efficiency subcritical retrofits is intensifying because EPA and EU Industrial Emissions Directive compliance burdens erode residual asset economics. Municipal utilities and mid-sized independent power producers exhibit highest price sensitivity, while national oil companies and state gencos prioritize metallurgical guarantees over capital cost.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale tender demand across Indian and Southeast Asian markets, with EPC contractors managing field erection and commissioning logistics. High-nickel superalloy supply concentrates in Japan and Germany, while pressure vessel fabrication draws from China, India, and South Korea. Raw material dependencies rest on nickel-chromium-molybdenum alloys, specialized welding consumables, and digital control system hardware. Single-source vulnerability for supercritical water wall tubing exposes project timelines to raw material bottlenecks. Distribution runs through OEM-direct procurement for utility-scale units and regional fabricator networks for industrial fire-tube applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in power boiler supply hinges on aftermarket service capture and hydrogen-ready combustion system premiums, with efficiency upgrade cycles and digital twin bundling shifting value toward recurring revenue architectures.
For Market Incumbents: Anticipate displacement pressure from modular fabricators in Southeast Asia by deepening vertical integration into supercritical alloy welding capabilities and certifying hydrogen-ready burner designs ahead of EU industrial cluster demand. Defend service contract renewal rates through predictive maintenance platform deployment and spare parts inventory positioning near Indian and Vietnamese utility fleets. For New Entrants and Emerging Players: Enter via biomass grate boiler specialization for Scandinavian district heating networks, where agricultural residue co-firing mandates outstrip incumbent capacity. Target Poland and Czech Republic retrofit markets where EU Industrial Emissions Directive deadlines force subcritical replacement decisions ahead of domestic fabricator expansion. Lead with modular delivery speed and compressed ISO 16528 certification timelines as the primary go-to-market angle. For Investors and Strategic Acquirers: Engineering conglomerates with captive power project pipelines are the most active acquirer in this space, seeking supercritical IP and digital twin capabilities to bundle with EPC offerings. Acquisition targets should display certified welding specialist workforces and established aftermarket parts networks. Watch hydrogen-ready boiler demonstration project announcements in German and Dutch industrial clusters as the signal indicating technology transition inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Supply | Japanese and German mills dominate high-nickel alloy supply, creating bottleneck exposure for project timelines. |
| Long-term Service Agreement Bundling | Vietnamese and Indonesian state gencos now mandate fifteen-year parts commitments with initial equipment tenders. |
| Hydrogen-Ready Combustion Development | EU industrial clusters in North Rhine-Westphalia and Rotterdam Harbor drive burner modification demand. |
| Digital Twin Platform Integration | Texas independent power producers deploy real-time combustion optimization to reduce heat rate penalties. |
| Modular Fabrication Capacity Expansion | Remote Southeast Asian sites with limited skilled labor accelerate shop-fabricated module adoption. |
Study Parameters
Direct dialogue with utility planning officers, EPC project developers, boiler maintenance directors, and aftermarket service heads informed primary intelligence, cross-referenced against Central Electricity Authority tender databases, EPA enforcement and compliance records, EU Industrial Emissions Directive implementation reports, and ISO certification registries. Bottom-up unit deployment tracking across Indian state gencos and Southeast Asian independent power producers was triangulated against top-down capacity addition forecasts from national power development plans.
Segment-level outputs across the analysis window reflect modeled deployment trajectories by pressure rating architecture, fuel conversion pathway, and end-user scale tier. CAGRs were derived from regression analysis of historical tender awards and announced retrofit commitments, with inputs including metallurgical stress cycling assumptions, emissions compliance timeline rigidity, and digital control system adoption curves.
Inputs from utility procurement databases and EPC contractor project pipelines were available through the study window; gaps in privately held maintenance cost data and unannounced hydrogen-ready pilot programs introduce uncertainty bands around aftermarket revenue projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Reformer Unit Market
Boilers
Superheater Market
Boilers
Gas Condensing Boiler Market
Boilers
Industrial Boiler MRO Market
Boilers
Germany Combined Heat and Power Market
Boilers
Global Domestic Boilers Market
Boilers
Industrial Biomass Boiler Market
Boilers
US Commercial Boiler Market
Boilers
US Industrial Boiler Market
Boilers
Coal-Saving Combustion-Supporting Agent Market
Boilers
Global Package Boilers Market
Boilers
North America Industrial Boiler Market
Boilers
Power Plant Boiler Market
Boilers
Fossil Fuel Fired Water Heaters Market
Boilers
Industrial and Residential Heating Market
Boilers
Boiler System Market