
 Steam Boiler for Thermal Power Plant and Oil Refinery Market | 2026-2036
Steam Boiler for Thermal Power Plant and Oil Refinery Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Boiler for Thermal Power Plant and Oil Refinery Market Insights
EPA emission standards for industrial boilers is realigning the cost-of-entry calculus for North American and European suppliers. Babcock & Wilcox leverages its century-long fabrication heritage to dominate supercritical and ultra-supercritical installations. Mitsubishi Heavy Industries anchors its position through integrated turbine-boiler packages for Asian utility tenders. Siemens competes on digital plant controls and predictive maintenance platforms that extend equipment life cycles.
Steam boilers for thermal power plants and oil refineries are pressurized vessels that convert feedwater into superheated steam through combustion or heat recovery, typically operating at pressures exceeding 150 bar and temperatures above 540°C to drive steam turbines or process heat exchangers. Water-tube configurations command the premium segment due to higher pressure tolerance and faster steam ramp rates demanded by combined-cycle plants. Heat recovery technology is displacing conventional combustion in refinery settings where waste heat streams from catalytic crackers and coker units offer secondary energy capture. Modular boiler systems are gaining traction in petrochemical clusters requiring phased capacity additions without extended outage windows.
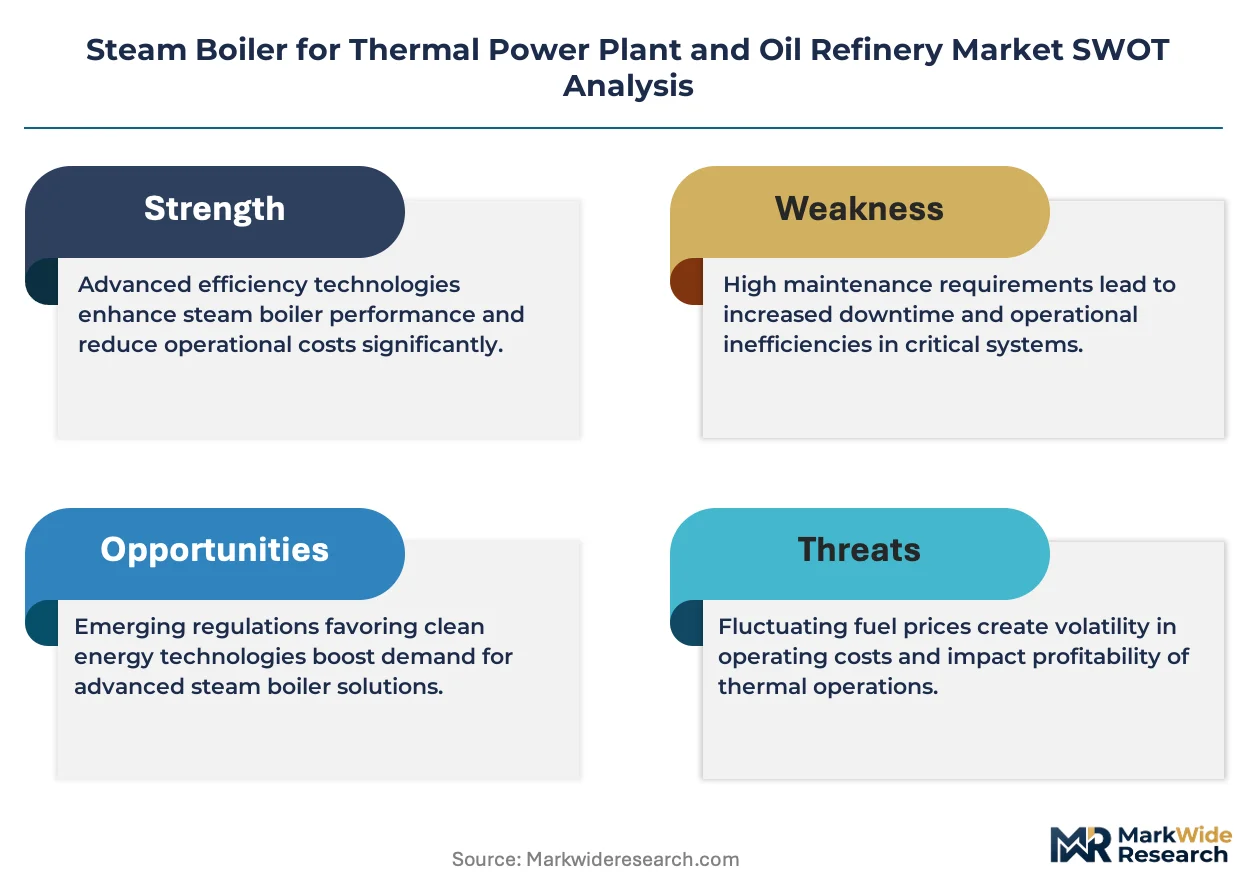
EPA standards in the United States, the EU Green Deal's Industrial Emissions Directive, and India's CEA boiler efficiency mandates collectively tighten allowable NOx and particulate thresholds. These frameworks force retrofit investments in flue-gas desulfurization and selective catalytic reduction systems, altering total cost-of-ownership calculations for plant operators. Stakeholders must weigh fuel-switching timelines against carbon border adjustment mechanisms that threaten export-competitive refinery margins.
Market Dynamics
Supercritical and ultra-supercritical steam cycles are compressing the addressable market for subcritical boiler fabricators as utilities prioritize thermal efficiency gains over upfront capital savings. This technology migration is redrawing competitive boundaries between established OEMs and emerging Asian suppliers.
Growth Catalysts
- India's CEA boiler efficiency mandates:NTPC and state gencos are retiring subcritical units ahead of schedule, triggering replacement tenders exceeding 10 GW annually.
- Refinery waste heat recovery:Catalytic cracker off-gas streams in Gulf Coast petrochemical clusters now feed heat recovery steam generators for captive power.
- Southeast Asia grid baseload expansion:Vietnam and Indonesia are adding supercritical coal blocks to stabilize renewable intermittency.
Market Restraints
- Specialized alloy supply concentration:Superheater tubing in grades T91 and T92 relies on Japanese and German metallurgical suppliers with 18-month order backlogs.
- EPA MATS compliance deadlines:US utilities face compressed retrofit windows for mercury and air toxics controls, diverting capex from new builds.
- Gas turbine combined-cycle substitution:Grid operators in Bangladesh and Pakistan are favoring 60% efficient gas blocks over 40% efficient coal steam cycles.
Strategic Opportunities
- Modular boiler skids for petrochemical clusters:Saudi Aramco's Jafurah gas expansion is procuring phased HRSG additions without master outage.
- EU Green Deal Industrial Emissions Directive:The tightening BAT standards create retrofit demand for flue-gas treatment integration in Polish and German lignite plants.
- Digital twin convergence with predictive maintenance:Boiler OEMs are bundling AI-driven tube leak detection to extend pressure part life cycles.
Industry Challenges
- Welding inspector certification bottlenecks:ASME Section IX qualified welders for high-pressure tube joints command 40% wage premiums in tight labor markets.
- Legacy DCS integration complexity:Brownfield turbine-boiler control upgrades require protocol bridging between 1990s-era distributed control systems and modern IoT architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Boiler for Thermal Power Plant and Oil Refinery Market |
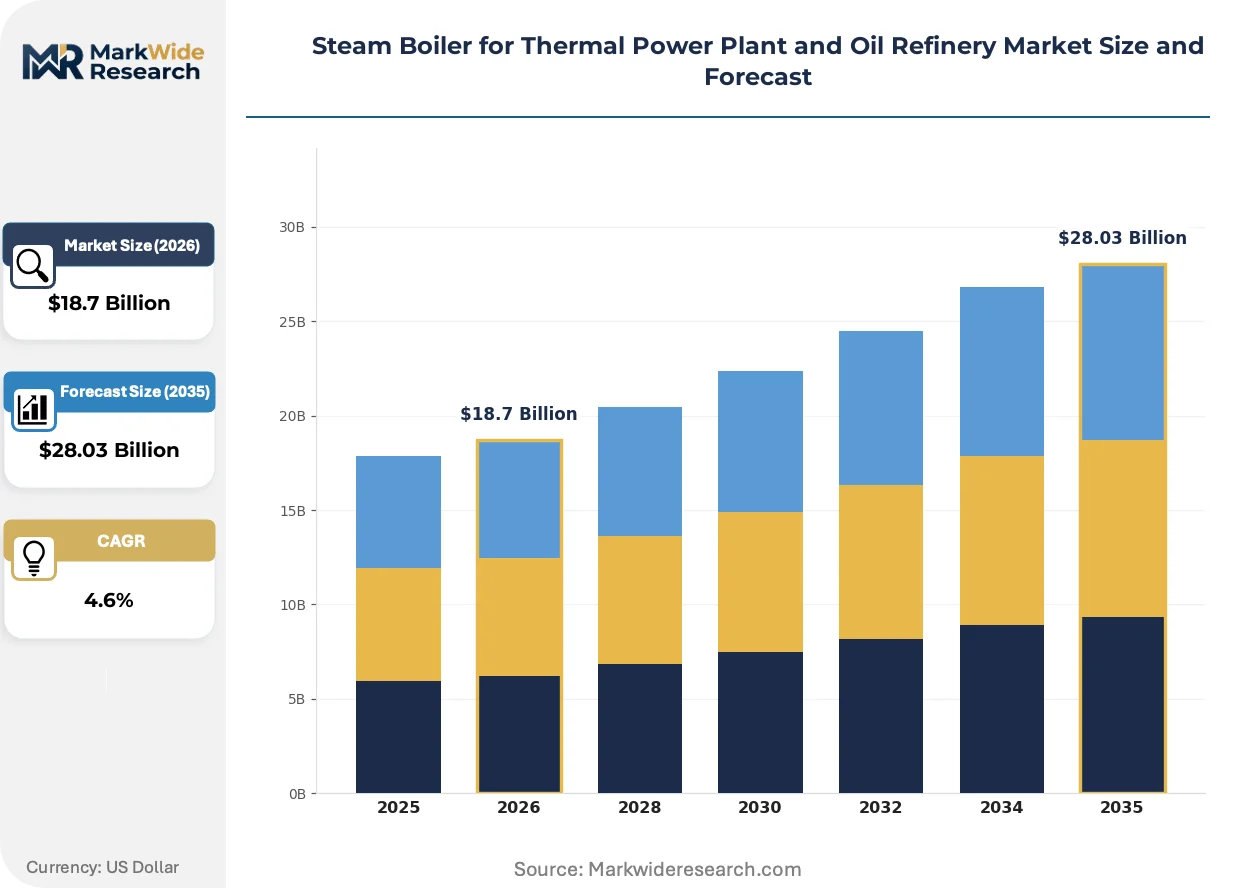
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-Tube Boiler, Water-Tube Boiler, Electric Boiler, Modular Boiler Technology: Combustion Technology, Heat Recovery, Fluidized Bed, Biomass-fired End User: Power Generation, Oil Processing, Petrochemical, Chemical Manufacturing Fuel Type: Natural Gas, Coal, Biomass, Diesel |
| Companies Covered | Babcock & Wilcox, Alfa Laval, Viessmann Manufacturing Company, Forbes Marshall, Clayton Industries, Fulton Boiler Works, Siemens, Mitsubishi Heavy Industries, Thermax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Boiler for Thermal Power Plant and Oil Refinery Market Trends and Innovations
Digitalization of boiler lifecycle management is compressing maintenance intervals and reshaping supplier-customer relationships around uptime guarantees rather than equipment sales alone.
Ultra-supercritical steam conditions at 300 bar and 620°C are consolidating the premium boiler segment around water-tube architectures with advanced nickel superalloy tubing. Chinese utilities under MIIT efficiency directives are driving the fastest adoption curves. This thermal boundary extension is consolidating the supplier base by disqualifying fabricators lacking ASME Section I certification for advanced materials.
The EU Green Deal's Industrial Emissions Directive is tightening Best Available Techniques for NOx and SOx from large combustion plants. Refinery operators in Rotterdam and Antwerp are pre-investing in selective catalytic reduction retrofits ahead of 2025 compliance deadlines. German lignite generators are responding with biomass co-firing modifications to stay within emission budgets.
Performance-based service contracts are displacing traditional spare parts procurement in Asian utility fleets. Long-term agreements covering tube replacement and pressure part inspections now dominate tenders from Indonesian state-owned power developers. This shift is most visible in Java-Bali grid expansion projects where availability guarantees determine vendor selection.
Steam Boiler for Thermal Power Plant and Oil Refinery Market Segmentation
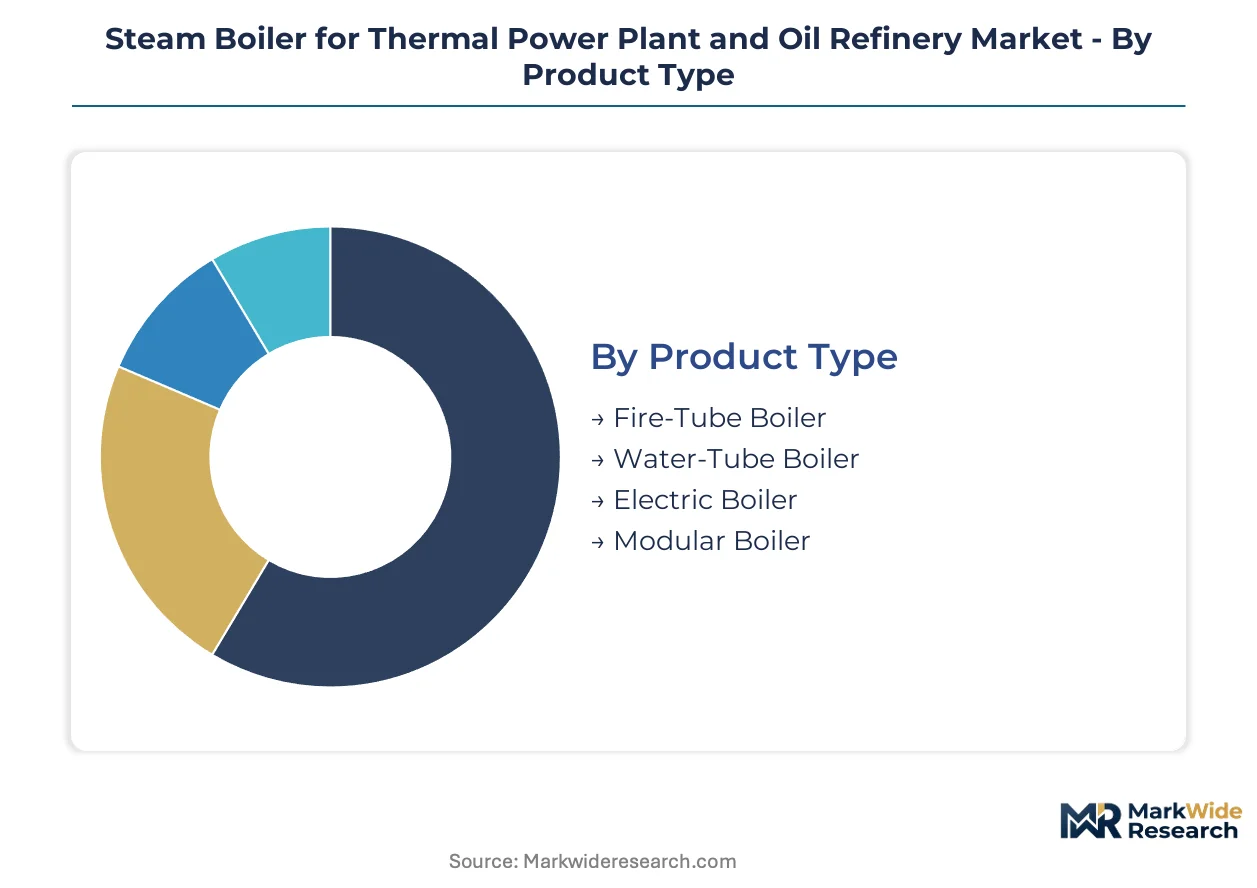
Steam boiler procurement decisions hinge on pressure ratings, thermal efficiency targets, and integration complexity with existing plant infrastructure. Segment boundaries blur where combined-cycle configurations demand hybrid heat recovery and combustion systems.
Product Type:
Volume deployment concentrates in standardized configurations for baseload coal plants, while premium fabrication serves ultra-supercritical installations requiring advanced metallurgy.
- Water-Tube Boiler:High-pressure water circulates through vertical tubes while combustion gases flow externally, enabling steam conditions exceeding 250 bar and 600°C. Demand concentrates in China's MIIT-mandated efficiency upgrades and India's NTPC supercritical tenders where thermal efficiency targets exceed 42%. Alloy supply bottlenecks for T91/T92 superheater tubing constrain deployment timelines.
- Fire-Tube Boiler:Combustion gases pass through submerged tubes surrounded by pressurized water, limiting operating pressure to approximately 20 bar. Refinery process heat applications in Gulf Coast petrochemical clusters favor this configuration for saturated steam supply to distillation units. Lower capital cost and simplified maintenance protocols drive selection.
- Electric Boiler:Resistive or electrode heating eliminates combustion emissions entirely, serving European refineries under EU Green Deal carbon budgets. Grid-connected installations in Rotterdam and Antwerp clusters displace gas-fired units where carbon border adjustments threaten export margins.
- Modular Boiler:Factory-assembled skid-mounted units enable phased capacity additions without extended master outages. Saudi Aramco's Jafurah gas expansion procures these for captive power without disrupting existing refinery operations.
Mature deployment sits with Fire-Tube Boiler. Newer deployment is concentrated in Modular Boiler.
Technology:
Margin structures diverge sharply between commodity combustion systems and integrated heat recovery configurations capturing waste streams.
- Heat Recovery:Catalytic cracker off-gas and coker unit exhaust feed heat recovery steam generators, displacing standalone combustion in refinery settings. Gulf Coast petrochemical clusters now mandate HRSG integration for new cracker units. Steam output quality determines turbine-generator coupling feasibility.
- Combustion Technology:Pulverized coal and gas-fired burners dominate baseload power generation where grid stability requirements override efficiency optimization. Southeast Asian utilities in Vietnam and Indonesia specify supercritical coal blocks with low-NOx burners to manage renewable intermittency.
- Fluidized Bed:Circulating fluidized bed combustion enables lower-grade coal utilization with in-situ sulfur capture, serving Indian state gencos with high-ash domestic fuel. CEA efficiency mandates accelerate retrofit demand.
- Biomass-fired:German lignite generators deploy co-firing modifications to comply with EU Industrial Emissions Directive emission budgets. Feedstock logistics constrain scaling beyond 10-20% thermal substitution.
Established capacity relies on Combustion Technology. Fastest capacity additions track with Heat Recovery.
End User:
Customer procurement patterns separate long-cycle utility tenders from process-industry spot purchases driven by turnaround schedules.
- Power Generation:Grid-connected thermal plants specify ultra-supercritical cycles with 300 bar and 620°C steam conditions under Chinese MIIT directives. Availability guarantees and 25-year service contracts dominate vendor selection criteria in Indonesian state-owned tenders.
- Oil Processing:Refinery steam demand splits between process heat for distillation and captive power for internal consumption. Complexity rises where coker and cracker off-gas streams enable heat recovery integration rather than flaring.
- Petrochemical:Ethylene crackers and aromatics complexes require high-pressure steam for turbine drives and process heating. Phased expansion strategies in Saudi Arabia favor modular HRSG configurations.
- Chemical Manufacturing:Fertilizer and specialty chemical plants prioritize steam reliability over peak efficiency, often retaining subcritical boilers beyond technical obsolescence. EPA MATS compliance deadlines force retrofit investments over replacement.
Installed base concentrates in Power Generation. Greenfield investment tilts toward Oil Processing.
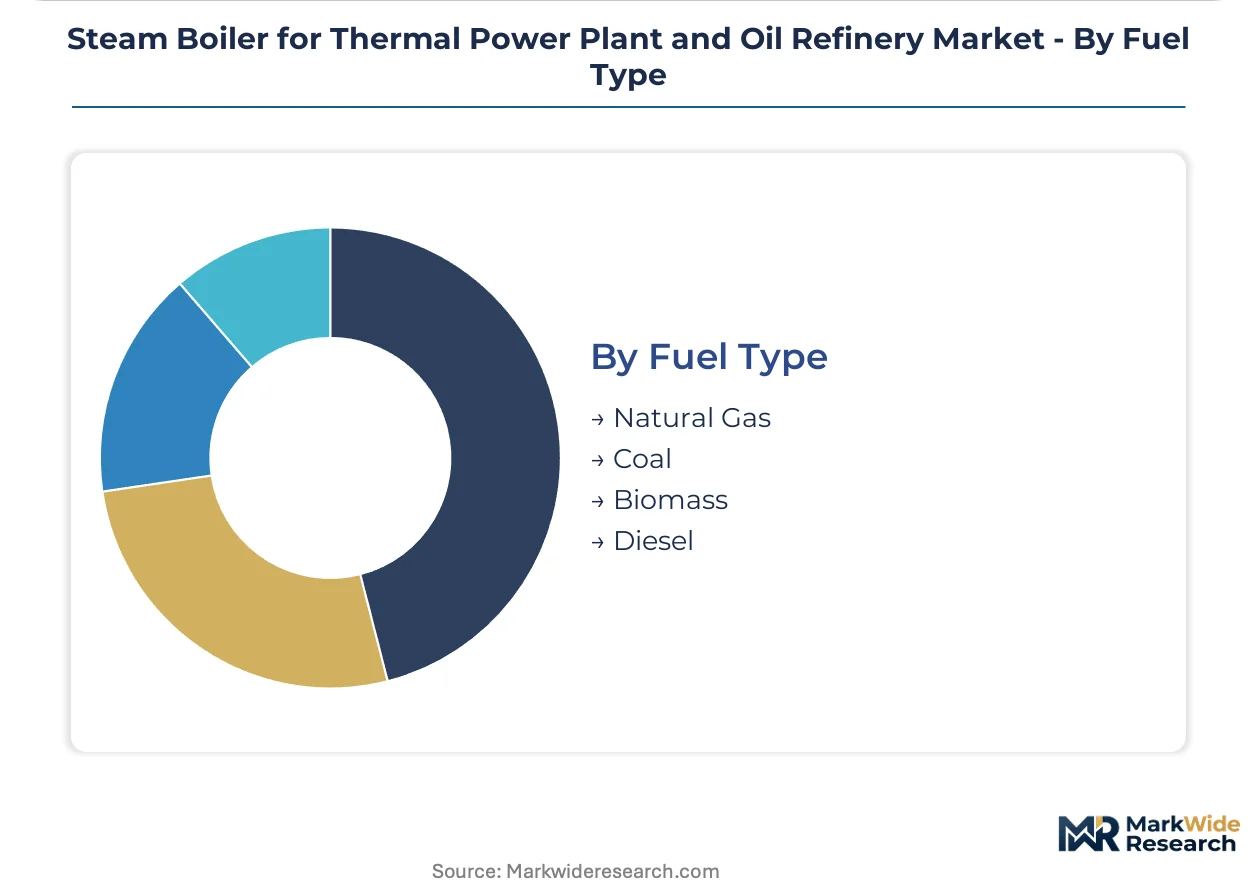
Fuel Type:
Supply security considerations and carbon pricing mechanisms are reordering fuel hierarchy across geographies.
- Natural Gas:Combined-cycle gas turbines at 60% efficiency displace 40% efficient coal steam cycles in Bangladesh and Pakistan grid planning. Pipeline infrastructure constraints limit deployment in Southeast Asian archipelago geographies.
- Coal:Domestic reserves anchor procurement in India and Indonesia despite efficiency penalties. Supercritical and ultra-supercritical upgrades compress the addressable market for subcritical fabricators.
- Biomass:Agricultural residue and energy crop combustion serves distributed industrial heat demand where grid extension is uneconomic. Fuel supply seasonality requires storage and handling investments.
- Diesel:Emergency and peaking applications in islanded grids and remote refinery locations where gas infrastructure is absent. High operating cost limits baseload deployment.
Conventional dominance rests with Coal. Transition momentum gathers behind Natural Gas.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and China concentrate procurement volumes for supercritical boiler installations as grid baseload expansion accelerates across Asia. Refinery operators in the Middle East and Gulf Coast United States are driving heat recovery steam generator demand. European utilities face retrofit deadlines under tightening emission frameworks.
China
MIIT efficiency directives mandate ultra-supercritical cycles at 300 bar and 620°C steam conditions for new coal blocks. Provincial grid operators in Shandong and Jiangsu provinces tender 10 GW annually of replacement capacity. Yangtze River Delta manufacturing clusters supply advanced nickel superalloy tubing for domestic boiler fabricators.
India
NTPC and state gencos retire subcritical units ahead of CEA-mandated schedules, triggering replacement tenders exceeding 10 GW annually. Domestic coal reserves anchor procurement despite efficiency penalties. Gujarat and Maharashtra industrial corridors concentrate refinery and petrochemical steam demand from Reliance Industries complexes.
United States
EPA MATS compliance deadlines compress retrofit windows for mercury and air toxics controls across utility fleets. Gulf Coast petrochemical clusters in Texas and Louisiana mandate heat recovery steam generator integration for new catalytic cracker units. Pipeline infrastructure constraints limit gas-fired boiler deployment in Permian Basin isolation.
Germany
EU Green Deal Industrial Emissions Directive tightens BAT standards for NOx and SOx from lignite combustion plants. RWE and LEAG pre-invest in selective catalytic reduction retrofits ahead of 2025 compliance deadlines. Rhineland and Lusatia lignite basins deploy biomass co-firing modifications to remain within emission budgets.
Saudi Arabia
Saudi Aramco's Jafurah gas expansion procures modular heat recovery steam generators for phased capacity additions without master outage windows. SABIC petrochemical complexes in Jubail Industrial City drive high-pressure steam demand for ethylene cracker turbine drives. Domestic gas reserves anchor captive power generation economics against grid import alternatives.
Steam Boiler for Thermal Power Plant and Oil Refinery Market Competitive Landscape
Japanese and German metallurgical suppliers anchor the premium alloy tier; Chinese fabricators hold volume positions in standardized subcritical configurations. The supplier base concentrates around ASME Section I certified fabricators capable of advanced materials welding. Three archetypes dominate: integrated turbine-boiler packagers, specialized heat recovery system builders, and digital controls platform vendors. Competitive moves center on technology licensing partnerships and backward integration into superheater tubing supply.
Among established boiler fabricators, Babcock & Wilcox and Mitsubishi Heavy Industries exemplify the integrated systems tier, while Siemens occupies a position in digital plant controls and predictive maintenance platforms. These companies represent divergent strategic positioning around fabrication heritage versus software-enabled service models. Their geographic footprints reflect century-long utility relationships in North American and Asian markets respectively.
| Leading Market Players |
|---|
| Babcock & Wilcox |
| Alfa Laval |
| Viessmann Manufacturing Company |
| Forbes Marshall |
| Clayton Industries |
| Fulton Boiler Works |
| Siemens |
| Mitsubishi Heavy Industries |
| Thermax |
| Others |
Pricing and Supply Chain Analysis
Backward integration into superheater tubing supply anchors both cost position and pricing power for ASME Section I certified fabricators serving ultra-supercritical installations. Japanese and German metallurgical suppliers command 18-month order backlogs for T91 and T92 grades, forcing boiler OEMs to absorb alloy premiums or pass through to utility buyers under long-term service contracts.
Pricing Analysis
Volume deployment concentrates in standardized subcritical configurations where Chinese fabricators compete on capital cost, while premium margins accrue to ultra-supercritical water-tube systems requiring advanced nickel superalloy certification. Price differentiation hinges on ASME Section I welding credentials and bundled predictive maintenance platforms. Cost compression in the subcritical tier is intensifying as Indian state gencos consolidate procurement around NTPC tender formats. Refinery operators show least price sensitivity where heat recovery integration eliminates flaring penalties.
Supply Chain Analysis
Superheater tubing supply rests on Japanese and German specialty steel producers with concentrated capacity for creep-resistant grades. Raw material flows draw from Indonesian nickel ore, Australian coking coal, and Chinese rare earth processing for advanced alloys. Single-source vulnerability concentrates in T91/T92 metallurgical supply where qualified welders for high-pressure tube joints command 40% wage premiums. Distribution runs through EPC contractors and direct utility procurement channels with 25-year service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around fabricators with captive alloy supply and ASME certification depth as EPA MATS deadlines and EU Green Deal retrofit windows force subcritical specialists into exit or acquisition.
For Market Incumbents: Extend pressure-part service contract coverage to capture 25-year revenue streams from Indonesian and Vietnamese state-owned utilities. Deepen backward integration into superheater tubing supply to offset Japanese and German metallurgical bottlenecks. Digital twin bundling with predictive maintenance platforms defends margin position against Chinese cost competition in standardized configurations. For New Entrants and Emerging Players: The mid-tier pricing gap between premium ultra-supercritical systems and economy subcritical units offers white-space entry through modular HRSG skids for Saudi Aramco-style phased expansions. Target refinery waste heat recovery segments where combustion displacement creates new demand without competing head-to-head with established utility relationships. Lead with AI-driven tube leak detection as a differentiated service layer rather than equipment-only positioning. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated turbine-boiler packagers seeking ASME Section I certification depth. Five-to-ten year viability favors fabricators with demonstrated ultra-supercritical installation records and captive alloy sourcing relationships. Watch for CEA-mandated retirement acceleration in India's subcritical fleet as the inflection signal for replacement tender volume spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superheater Tubing | Captive T91/T92 supply insulates margin pressure from Japanese and German metallurgical bottlenecks. |
| Digital Twin Platform Development | AI-driven tube leak detection extends pressure part life cycles and locks in 25-year service contracts. |
| Modular HRSG Capacity Expansion | Factory-skid configurations capture Saudi Aramco Jafurah-style phased additions without master outages. |
| ASME Section I Certification Investment | Advanced materials welding credentials qualify fabricators for 300 bar ultra-supercritical tenders. |
| Selective Catalytic Reduction Retrofit Bundling | Flue-gas treatment integration addresses EU Green Deal BAT deadlines for German lignite operators. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving utility planning officers, EPC contractors, refinery maintenance directors, and aftermarket service heads. EPA MATS compliance databases, CEA boiler efficiency mandates, EU ETS transaction records, and MIIT equipment standards provided segmentation benchmarks. Bottom-up project pipelines and top-down fuel consumption models were triangulated for volume validation.
Segment-level modeling tracked water-tube versus fire-tube configurations, supercritical versus subcritical technology tiers, and power generation versus oil processing end-use splits across the projection horizon. CAGRs were derived from replacement cycle analysis and greenfield capacity announcements rather than macroeconomic extrapolation. Alloy supply lead times, welder certification backlogs, and digital service attach rates informed margin trajectory assumptions.
Inputs from NTPC tender disclosures, Saudi Aramco procurement bulletins, and MIIT equipment directives were available through the study window; gaps in privately held EPC contract terms introduce uncertainty bands around project timing. Forecasts reflect documented assumptions regarding CEA retirement schedules and EU Green Deal enforcement intensity. A small set of triggers—carbon border adjustment activation, nickel export restriction, and ASME welding inspector strike activity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Superheater Market
Boilers
North America and Europe Electric Boilers Market
Boilers
North America Industrial Boiler Market
Boilers
Middle East and Africa Power Plant Boiler Market
Boilers
Coal-Saving Combustion-Supporting Agent Market
Boilers
Europe Residential Boiler Market
Boilers
Boiler Control Market
Boilers
Circulating Fluidized Bed Boilers Market
Boilers
Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market
Boilers
Global Marine Boilers Market
Boilers
Brazil Combined Heat and Power Market
Boilers
Boiler System Market
Boilers
Space Heating Boilers Market
Boilers
Watertube Boilers Market
Boilers
Industrial and Residential Heating Market
Boilers
US Industrial Boiler Market