
 Industrial and Residential Heating Market | 2026-2036
Industrial and Residential Heating Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial and Residential Heating Market Analysis
Data center thermal management is recalibrating procurement patterns across the industrial heating value chain. Daikin Industries Ltd. leverages its refrigerant technology leadership to capture premium installations in hyperscale facilities. Carrier Global Corporation anchors its position through backward integration into compressor manufacturing. NIBE specializes in ground-source systems for decentralized European residential developments.
Industrial and residential heating encompasses the generation, distribution, and control of thermal energy for space conditioning, process heat, and hot water supply, operating across temperature ranges from low-grade radiant warmth to high-pressure steam above 150°C for manufacturing processes. The primary purpose centers on maintaining occupant comfort, protecting infrastructure from freezing, and enabling chemical reactions, material drying, and food processing operations. Heat pumps represent the fastest-expanding fuel source substitution category as electricity displaces hydrocarbons in decarbonization roadmaps. Boilers retain dominant installed base share but face margin compression in regions with aggressive building performance standards. Furnaces occupy mature replacement cycles in North American residential housing stock with limited growth upside.
The US EPA regulates stationary source emissions under the Clean Air Act while the EU Ecodesign Directive mandates minimum efficiency thresholds for space and water heaters sold across member states. Germany's Federal Motor Transport Authority enforces building energy codes that accelerate heat pump deployment timelines. Stakeholders must monitor how the EU AI Act shapes automated building management system compliance requirements and liability frameworks.
Market Dynamics
The EU F-Gas Regulation's phasedown of fluorinated greenhouse gases is forcing boiler retrofits across German manufacturing corridors while simultaneously accelerating heat pump deployment timelines in Nordic residential clusters. This regulatory compression is reshaping equipment procurement patterns across both industrial process heat and domestic space conditioning segments.
Growth Catalysts
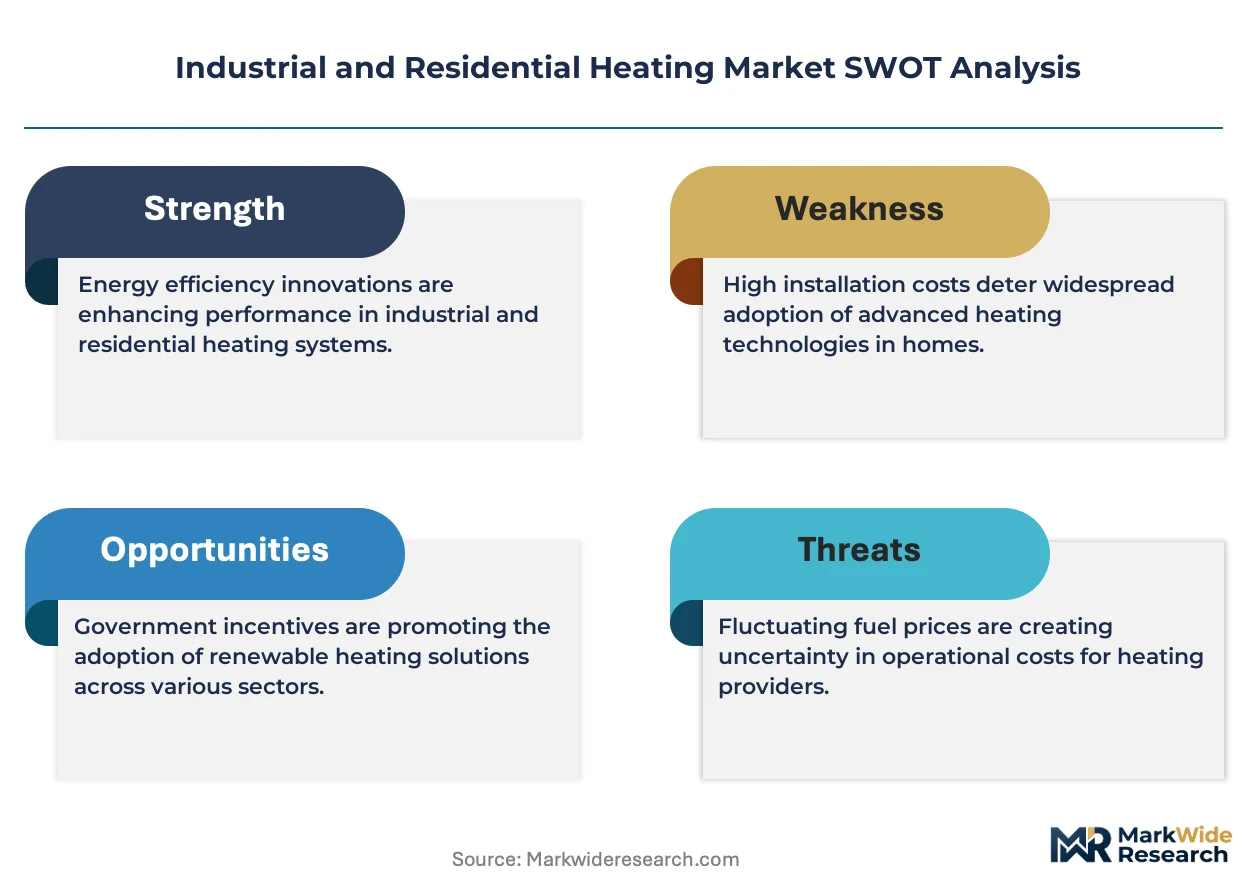
- EU Ecodesign Directive:Minimum efficiency thresholds for space and water heaters sold across member states are pulling high-performance heat pump installations into mainstream replacement cycles.
- Data center thermal management:Hyperscale facilities are recalibrating procurement volumes for industrial-grade chillers and heat rejection equipment as server density intensifies.
- Ground-source deployment:Decentralized European residential developments are adopting closed-loop geothermal systems as electricity displaces hydrocarbons in national decarbonization roadmaps.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger manufacturing faces margin compression from base metal price swings that resist long-term contracting.
- Compressor supply concentration:Scroll and screw compressor fabrication clusters in East Asian manufacturing hubs create single-source vulnerability for European OEMs.
- Low-temperature performance limits:Air-source heat pumps face technical barriers below minus 20°C that retain fossil boiler demand in continental climate zones.
Strategic Opportunities
- Industrial waste heat recovery:District heating networks in Denmark and Sweden are integrating data center exhaust into municipal supply loops.
- Refrigerant technology convergence:Natural refrigerant adoption is intersecting with variable-speed compressor controls to unlock subcritical CO2 systems for commercial refrigeration.
- Automated building management:The EU AI Act is creating compliance-driven demand for fault-detection algorithms in multi-zone commercial installations.
Industry Challenges
- Refrigerant handling certification:F-Gas quota reductions are compressing technician training timelines while expanding compliance documentation burdens.
- Legacy hydronic integration:Low-flow temperature optimization requires pipework redesign in 1970s housing stock that resists invasive retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial and Residential Heating Market |
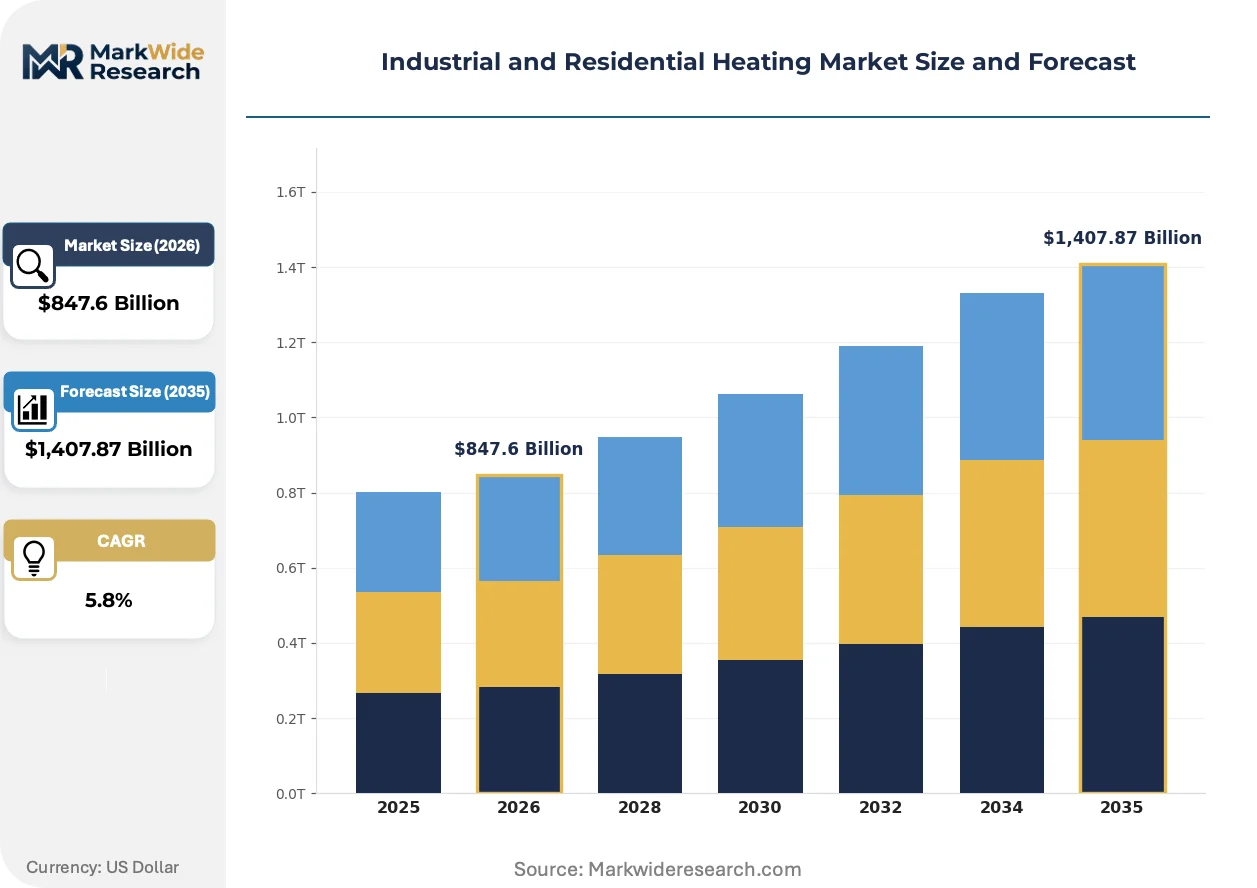
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $1,407.87 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boilers, Heat Pumps, Furnaces, Radiators Installation Type: Centralized, Decentralized, Modular, Hybrid Fuel Source: Natural Gas, Propane, Electricity, Wood End User: Manufacturing Facilities, Residential Homes, Commercial Buildings, Warehouses |
| Companies Covered | Carrier Global Corporation, Lennox International Inc., Trane Technologies plc, Daikin Industries Ltd., Johnson Controls International plc, Robert Bosch GmbH, Mitsubishi Electric Corporation, Rheem Manufacturing Company, NIBE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial and Residential Heating Market Emerging Trajectories
Electrification of thermal energy is compressing traditional equipment replacement cycles while digitalization of building systems is unbundling hardware from control-layer procurement. These forces are converging to reshape how heat is generated, distributed, and monetized across both residential and industrial settings.
CO2 transcritical heat pump systems are expanding into commercial refrigeration and space heating applications simultaneously. Supermarket chains in Northern Europe are adopting these units for combined cooling and heating duty. The technology is expanding into district energy networks as a dual-temperature source that displaces separate boiler and chiller installations.
The EU F-Gas Regulation mandates stepped reductions in hydrofluorocarbon availability through 2030. This policy is accelerating refrigerant transition roadmaps for equipment manufacturers with legacy product lines. Commercial cold chain operators are most affected, responding with accelerated natural refrigerant pilot programs and service technician retraining investments.
Energy-as-a-service contracting is displacing capital purchase models in multi-tenant commercial buildings. Facility managers are transferring performance risk to equipment financiers who retain ownership and optimize runtime efficiency. Germany and the Netherlands show the strongest contract penetration where building energy codes create compliance-driven upgrade urgency.
Industrial and Residential Heating Market Segmentation
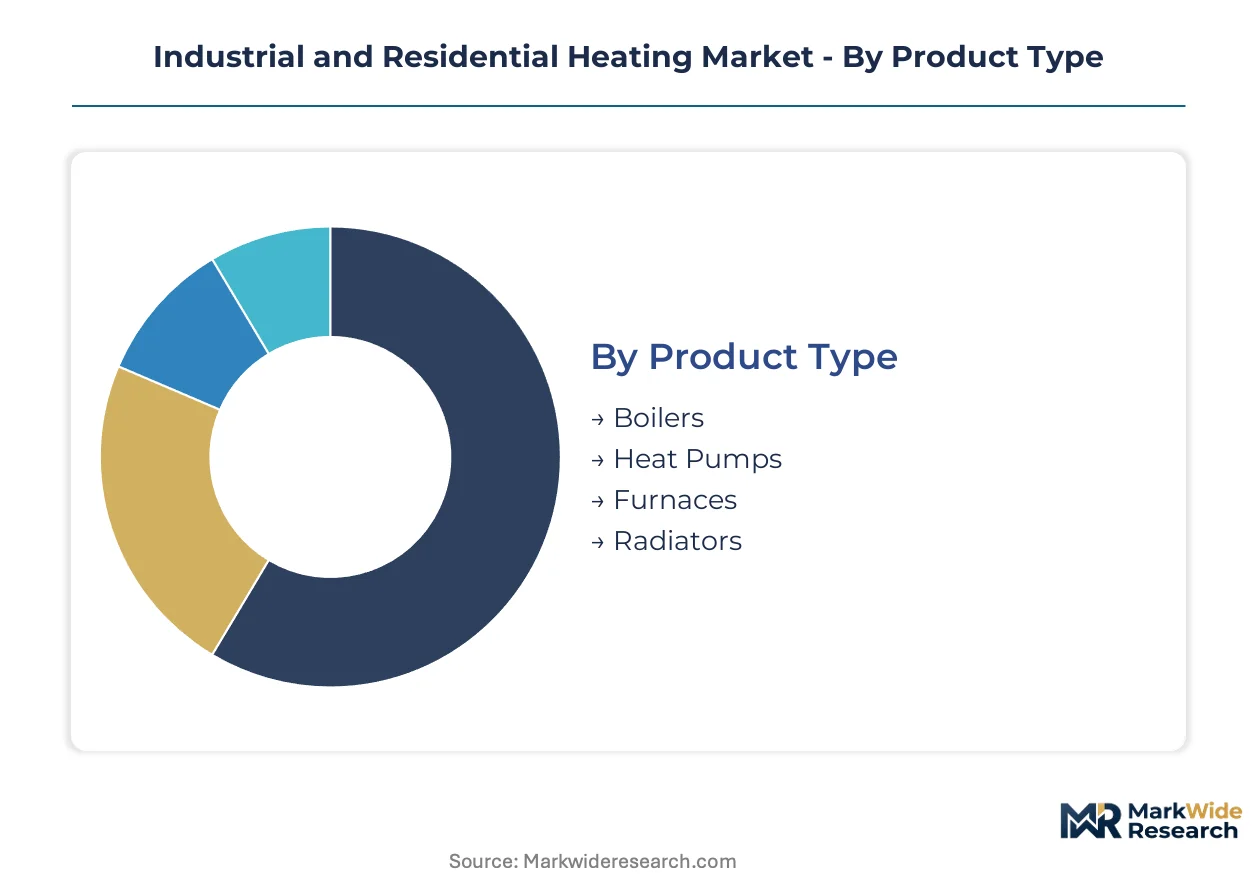
Thermal energy procurement patterns diverge sharply across equipment categories, installation architectures, and fuel inputs. Segment boundaries are blurring as electrification roadmaps and refrigerant phase-downs force hybrid configurations that defy traditional classification.
Product Type:
Manufacturing concentration for heat exchangers and compressors concentrates procurement leverage among three equipment categories.
- Boilers:Pressurized vessels generate steam or hot water through combustion or electric resistance, operating across 50°C to 250°C temperature ranges. German manufacturing corridors are accelerating retrofits as the EU F-Gas Regulation compresses fluorinated gas availability. Legacy installed base dominance creates replacement cycle visibility but margin pressure from efficiency mandates.
- Heat Pumps:Refrigerant-cycle systems transfer thermal energy from ambient sources to deliver space conditioning and water heating. Nordic residential clusters are absorbing the steepest deployment volumes as electricity displaces hydrocarbons in national decarbonization frameworks. Variable-speed compressor integration and natural refrigerant adoption are unlocking subcritical CO2 configurations for commercial applications.
- Furnaces:Forced-air combustion systems dominate North American residential heating infrastructure with mature replacement cycles. Limited growth upside persists where building stock age and fuel switching incentives reshape upgrade timing.
- Radiators:Convective and radiant heat emitters distribute thermal energy in hydronic and steam systems. European district heating networks in Denmark and Sweden are integrating low-temperature variants for data center waste heat recovery.
Boilers absorb the bulk of installed capacity; heat pumps are expanding most quickly.
Installation Type:
Capital intensity and performance risk allocation vary systematically across system scale configurations.
- Centralized:Single-source thermal generation serves multiple zones through distribution networks, common in commercial campuses and district heating. Energy-as-a-service contracting is concentrating ownership among specialized financiers in Germany and the Netherlands.
- Decentralized:Point-source equipment serves individual buildings or zones without distribution infrastructure. NIBE is capturing ground-source deployments across European residential developments through closed-loop geothermal specialization.
- Modular:Scalable unit configurations allow capacity additions matching demand growth. Data center thermal management is recalibrating procurement volumes as server density intensifies chiller redundancy requirements.
- Hybrid:Combined fossil and electric systems optimize operating costs across temperature ranges and electricity price periods. The EU Ecodesign Directive is pulling these configurations into mainstream replacement cycles through minimum efficiency thresholds.
Centralized systems retain the largest capital deployment; modular configurations are climbing the fastest as hyperscale facilities expand.
Fuel Source:
Decarbonization roadmaps are compressing hydrocarbon demand timelines while electricity procurement reshapes utility load profiles.
- Natural Gas:Pipeline-delivered methane dominates process heat and space conditioning in regions with established distribution infrastructure. The US EPA Clean Air Act stationary source regulations are accelerating emission control investments in manufacturing corridors.
- Propane:Liquefied petroleum gas serves off-grid locations and mobile applications where pipeline access is uneconomical. Rural residential clusters in continental climate zones retain demand where air-source heat pumps face minus 20°C performance barriers.
- Electricity:Grid-delivered power drives resistance heating and heat pump cycles with zero point-of-use emissions. Nordic residential markets are absorbing the steepest substitution volumes as building energy codes accelerate deployment timelines.
- Wood:Biomass combustion in pellet and chip configurations serves decentralized heating in forest-rich geographies. Austrian and Finnish residential markets maintain installed base share through carbon-neutral fuel accounting.
Natural gas retains dominant consumption volume; electricity is gaining share fastest as heat pump deployment accelerates.
End User:
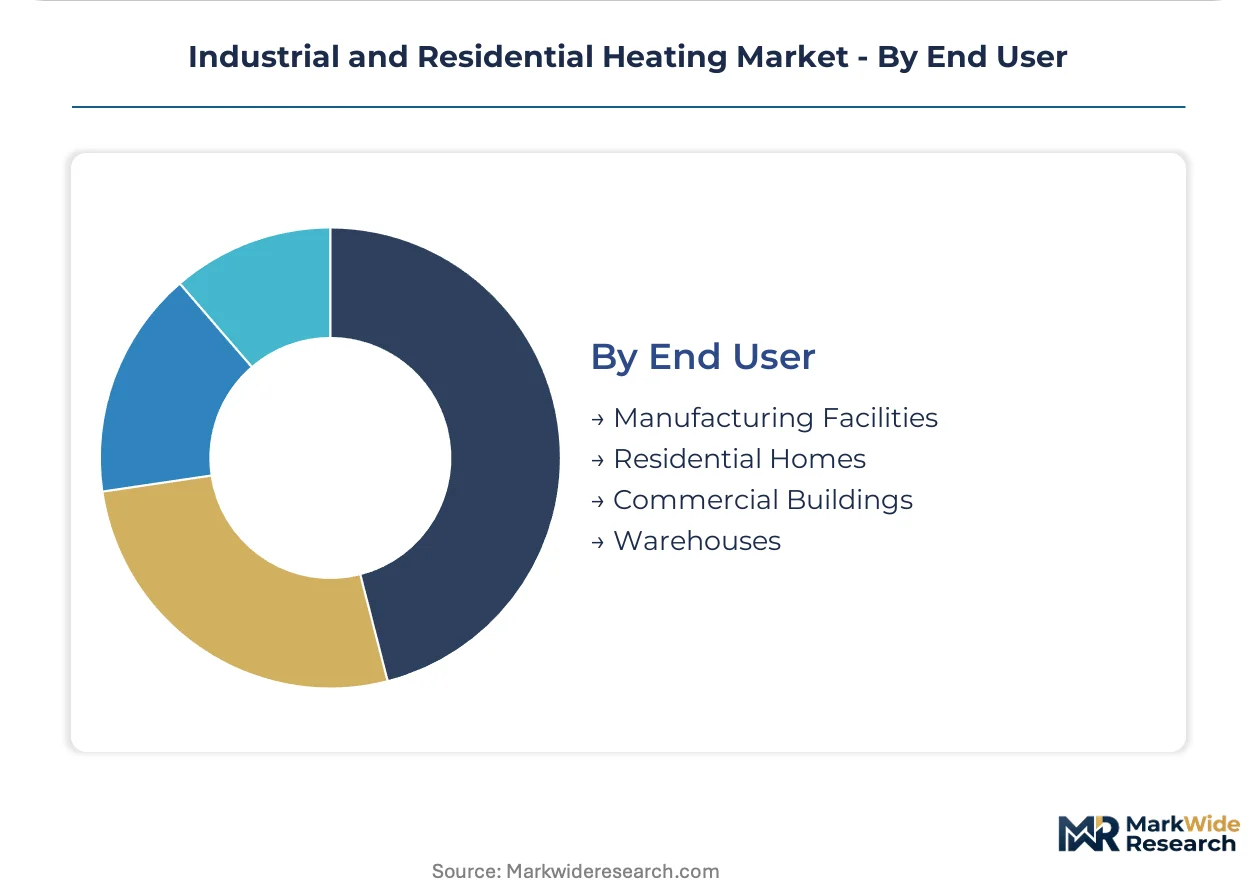
Operating temperature requirements and duty cycle patterns segment procurement behavior across facility types.
- Manufacturing Facilities:Process heat applications demand high-pressure steam above 150°C for chemical reactions, material drying, and food processing. German boiler retrofits are concentrating equipment procurement as F-Gas quotas compress refrigerant availability.
- Residential Homes:Space conditioning and domestic hot water supply operate at low-grade temperature ranges prioritizing efficiency over output intensity. Nordic clusters are leading heat pump penetration as electricity displaces hydrocarbons in national roadmaps.
- Commercial Buildings:Multi-tenant facilities balance comfort delivery with energy cost allocation across lease structures. The EU AI Act is creating compliance-driven demand for fault-detection algorithms in automated building management systems.
- Warehouses:Large-volume structures with intermittent occupancy patterns prioritize freeze protection and rapid recovery capacity. Low-temperature radiant systems are displacing forced-air configurations in automated logistics facilities.
Manufacturing facilities absorb the bulk of high-temperature capacity; residential homes are expanding most quickly as building codes tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates heat pump manufacturing capacity while Nordic markets absorb deployment volumes. The United States retains furnace-dominated replacement cycles. China scales compressor fabrication for export markets. Italy and Poland emerge as installation growth corridors.
United States
Residential furnace replacement cycles dominate equipment procurement in Midwest and Southeast housing stock. The US EPA Clean Air Act stationary source regulations accelerate emission control investments in manufacturing corridors. Texas and Ohio industrial clusters are retrofitting process heat systems ahead of tightening state-level building codes.
Germany
Federal Motor Transport Authority enforcement of building energy codes compresses heat pump deployment timelines across residential developments. The EU F-Gas Regulation phases down fluorinated greenhouse gases through 2030, forcing boiler retrofits. Manufacturing facilities in Bavaria and North Rhine-Westphalia are accelerating equipment procurement ahead of refrigerant quota reductions.
Sweden
Ground-source heat pump penetration reaches saturation in single-family housing clusters around Stockholm and Gothenburg. National decarbonization roadmaps mandate electricity substitution for hydrocarbon heating. District heating networks in Malmö are integrating data center exhaust into municipal supply loops.
China
Scroll and screw compressor fabrication concentrates procurement leverage for European OEMs dependent on East Asian supply. Dual carbon goals under MIIT guidance accelerate domestic heat pump deployment in northern provinces. Yangtze River Delta manufacturing hubs are scaling variable-speed compressor output for export markets.
Italy
Hybrid heating configurations gain traction in Alpine climate zones where air-source performance degrades below minus 20°C. EU Ecodesign Directive minimum efficiency thresholds pull high-performance installations into mainstream replacement cycles. Lombardy and Veneto industrial zones are retrofitting process steam systems ahead of refrigerant transition deadlines.
Industrial and Residential Heating Market Vendor Landscape
Top-tier vendors anchor premium heat pump and chiller segments, while mid-tier fabricators compete on installation density and service network coverage. The vendor base stratifies across refrigerant technology leadership, compressor manufacturing control, and ground-source specialization vectors. Strategic archetypes include full-system integrators, component specialists, and energy-as-a-service financiers. Competitive moves concentrate on backward integration into compressor manufacturing and natural refrigerant transition roadmaps.
Among diversified industrial conglomerates, Carrier Global Corporation and Daikin Industries Ltd. occupy positions exemplifying refrigerant-cycle technology depth. NIBE represents the ground-source specialization archetype. Robert Bosch GmbH anchors the European premium residential tier through captive distribution networks. These three named entities illustrate how competitive positioning stratifies across technology control, geographic focus, and vertical scope.
| Leading Market Players |
|---|
| Carrier Global Corporation |
| Lennox International Inc. |
| Trane Technologies plc |
| Daikin Industries Ltd. |
| Johnson Controls International plc |
| Robert Bosch GmbH |
| Mitsubishi Electric Corporation |
| Rheem Manufacturing Company |
| NIBE |
| Others |
Supply Flow & Price Mechanics
Copper and aluminum futures volatility cascades through heat exchanger fabrication costs into tiered equipment pricing across European and North American markets. Base metal price swings compress margins for mid-tier boiler manufacturers while premium heat pump vendors pass through material costs via performance-linked contract structures.
Pricing Analysis
Margin tightening in standard-efficiency equipment reflects EU Ecodesign Directive compliance investments and refrigerant transition costs. Three-tier pricing structure across premium, standard, and economy levels separates variable-speed compressor systems from fixed-speed units and basic resistance heating. Cost-down pressure on economy-tier boilers accelerates because Nordic building codes pull demand toward heat pump substitutes. Residential retrofit buyers exhibit highest price sensitivity; data center operators prioritize thermal reliability over capital cost.
Supply Chain Analysis
Remanufactured compressor flows from European service depots extend equipment lifecycles while reducing raw material draw from primary fabrication. Scroll and screw compressor production concentrates in China, South Korea, and Japan, creating procurement leverage for OEMs dependent on East Asian supply. Heat exchanger manufacturing rests on copper tube and aluminum fin dependencies vulnerable to LME price volatility. Single-source vulnerability persists where German and Italian OEMs lack captive compressor capacity. Distribution runs through authorized dealer networks for residential equipment and direct EPC relationships for industrial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation constructs a cost-of-compliance moat that favors incumbent refrigerant technology leaders over capital-constrained challengers. Quota enforcement accelerates technician certification requirements that smaller installers cannot absorb.
For Market Incumbents: Deepen backward integration into compressor manufacturing to offset East Asian supply concentration. Secure natural refrigerant IP positions ahead of hydrofluorocarbon phase-down deadlines. Defend against emerging energy-as-a-service financiers by captive ownership of installation and maintenance channels. For New Entrants and Emerging Players: Enter via modular data center thermal management contracts where hyperscale procurement recalibrates vendor qualification thresholds. Target Italian and Polish installation corridors where EU Ecodesign Directive compliance creates replacement urgency. Lead with CO2 transcritical system expertise to bypass legacy refrigerant infrastructure requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor ground-source specialists with closed-loop geothermal project pipelines in Sweden and Germany. Long-term viability hinges on electricity grid decarbonization pace and building code enforcement consistency. Monitor F-Gas quota auction prices as inflection indicator for equipment manufacturer margin compression severity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Carrier Global Corporation's captive supply reduces East Asian dependency for European OEM procurement. |
| Natural Refrigerant Transition Program | Daikin Industries Ltd. leverages CO2 transcritical expertise to capture premium commercial refrigeration retrofits. |
| Energy-as-a-Service Contract Expansion | German and Dutch financiers transfer performance risk while retaining equipment ownership and optimization rights. |
| Ground-Source Deployment Specialization | NIBE captures decentralized European residential developments through closed-loop geothermal system integration. |
| Data Center Thermal Management Partnership | Hyperscale facilities recalibrate procurement volumes as server density intensifies chiller redundancy requirements. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with HVAC plant managers, OEM procurement leads, distribution channel partners, and aftermarket service heads combined with secondary validation from EU Ecodesign Directive implementation reports, EPA Clean Air Act enforcement databases, and F-Gas quota auction records. Bottom-up equipment shipment analysis triangulated against top-down energy consumption projections.
Granularity-level modeling deployed equipment category, installation architecture, fuel source substitution, and end-use temperature requirements as segmentation dimensions. CAGRs derived from replacement cycle analysis and regulatory compliance timeline alignment across the analysis window. Forecast inputs incorporated copper and aluminum price trajectory assumptions alongside electricity grid carbon intensity roadmaps.
Revisions become necessary when F-Gas quota enforcement accelerates, building code adoption diverges across member states, or compressor supply disruptions materialize. Practitioners should monitor EU AI Act compliance documentation requirements and natural refrigerant technician certification bottlenecks for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Space Heating Boilers Market
Boilers
US Commercial Boiler Market
Boilers
Fire Tube Industrial Boiler Market
Boilers
North America Industrial Boiler Market
Boilers
Watertube Boilers Market
Boilers
Boiler Combustion Chamber Market
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market
Boilers
US Boiler Market
Boilers
Circulating Fluidized Bed Boilers Market
Boilers
Residential Boiler Market
Boilers
Feed Water Heater for Power Plants Market
Boilers
Biomass Boiler Market
Boilers
Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market
Boilers
Steam Boiler Market
Boilers
Coal-Saving Combustion-Supporting Agent Market
Boilers
Reformer Unit Market