
 US Cold Drawn Seamless Steel Pipes Market | 2026-2036
US Cold Drawn Seamless Steel Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
US Cold Drawn Seamless Steel Pipes Market Intelligence
A divergence in capital investment for advanced cold drawing and finishing capabilities is bifurcating the market. Integrated giants like U. S. Steel Tubular Products Inc. leverage economies of scale in high-volume production. In contrast, specialists such as Michigan Seamless Tube, LLC differentiate through custom alloys and tight tolerances for aerospace and defense applications. ArcelorMittal North America Holdings LLC sustains its position with a powerful distribution network across the US.
Cold drawn seamless steel pipes are manufactured by pulling a pre-hollowed steel shell through a die and over a mandrel at ambient temperature. This process refines the grain structure, improves surface finish, and increases tensile strength, making them ideal for high-pressure fluid conveyance. Oil Country Tubular Goods (OCTG) for the energy sector constitute a major product segment by volume. However, significant growth is observed in mechanical pipes for automotive manufacturing applications, where precision is paramount.
Product integrity is governed by standards from organizations like the American Petroleum Institute (API) for energy applications. Federal agencies also exert influence, with EPA regulations controlling emissions from steel production and OSHA rules mandating worker safety. A producer's strategic choice between investing in specialized, high-margin capabilities and optimizing for high-volume, standard-grade production will dictate future market positioning.
Market Dynamics
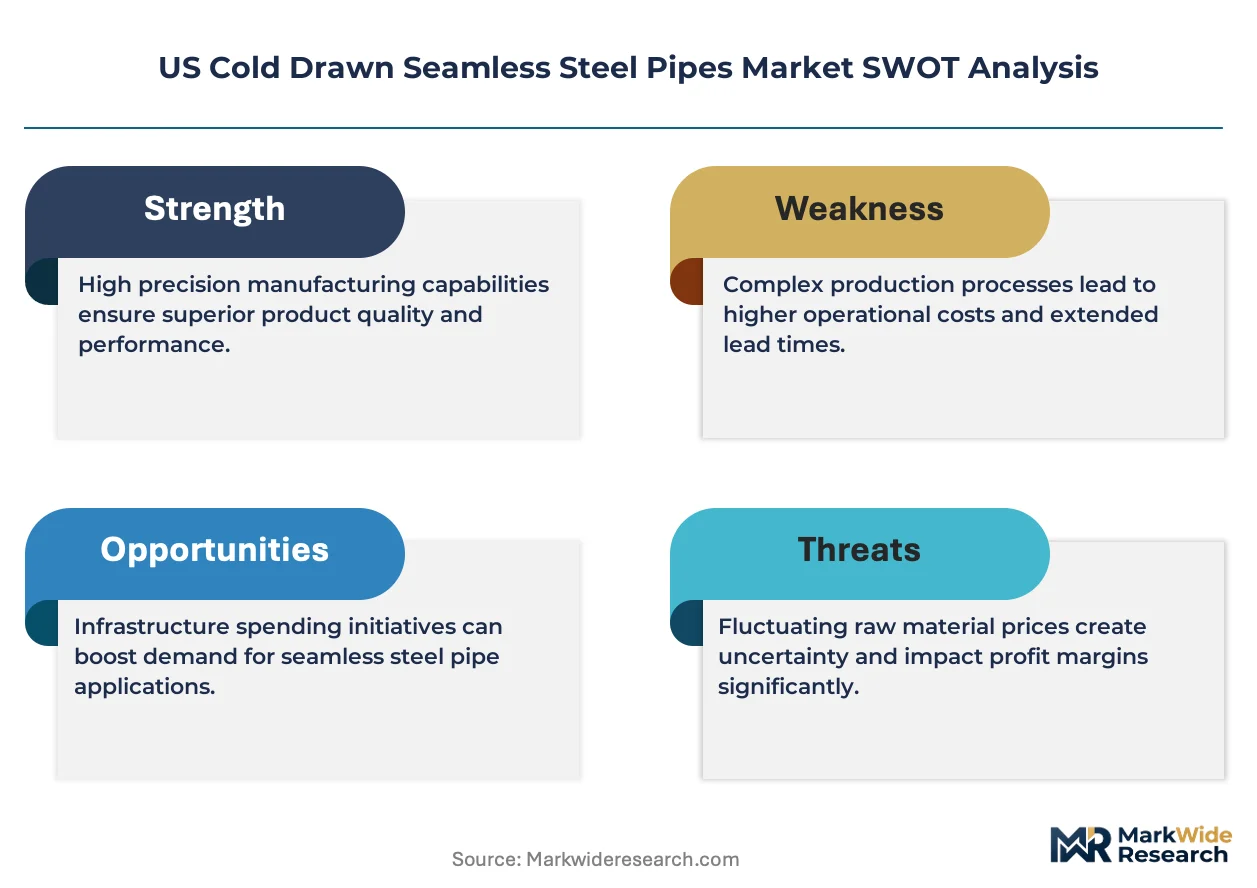
The strategic imperative to align production with domestic content requirements, heavily influenced by the Inflation Reduction Act, is the central force shaping the US market. This policy is compelling producers to re-evaluate capital investment priorities between high-volume commodity grades and specialized, high-margin products.
Growth Catalysts
- Inflation Reduction Act (IRA):This legislation provides significant tax credits and incentives for projects utilizing domestically sourced industrial materials, directly benefiting US-based steel pipe manufacturers serving the energy and automotive sectors.
- Automotive Lightweighting:The transition to electric vehicles necessitates the use of high-strength, lightweight steel pipes in chassis and structural components to offset battery weight, creating new demand for precision mechanical tubing.
- Gulf Coast Infrastructure:Sustained investment in oil and gas exploration, production, and LNG export facilities along the US Gulf Coast drives consistent demand for Oil Country Tubular Goods (OCTG) and line pipes.
Market Restraints
- Input Cost Volatility:Unpredictable price fluctuations in essential raw materials, particularly high-grade steel scrap and alloying elements like chromium and molybdenum, compress producer margins and complicate long-term contract pricing.
- Substitution from Composites:In certain non-critical, low-pressure applications, particularly in the automotive and industrial sectors, advanced polymer and composite pipes present a viable, corrosion-resistant alternative to steel.
- High Capital Intensity:The substantial upfront investment required for cold drawing benches, annealing furnaces, and advanced finishing equipment creates a high barrier to entry, concentrating the market among established players.
Strategic Opportunities
- Hydrogen Infrastructure:The development of a national hydrogen economy presents an opportunity for pipes designed for high-pressure hydrogen transport and storage, requiring specialized materials resistant to hydrogen embrittlement.
- Carbon Capture & Sequestration (CCS):Emerging CCS projects require extensive networks of seamless pipes capable of safely transporting supercritical CO2 from industrial sources to geological storage sites, opening a new application segment.
- Modernization of Water Systems:Federal funding allocated to upgrading aging municipal water infrastructure creates demand for durable, long-lasting seamless steel pipes, particularly for large-diameter transmission lines.
Industry Challenges
- Workforce Skill Gaps:A persistent shortage of qualified metallurgists, NDT inspectors, and skilled machine operators capable of managing modern, computer-controlled cold drawing equipment hampers productivity and quality control efforts.
- Certification Lead Times:The lengthy and rigorous process for obtaining or renewing certifications, such as those from the American Petroleum Institute (API), can delay market entry for new products and create production bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cold Drawn Seamless Steel Pipes Market |
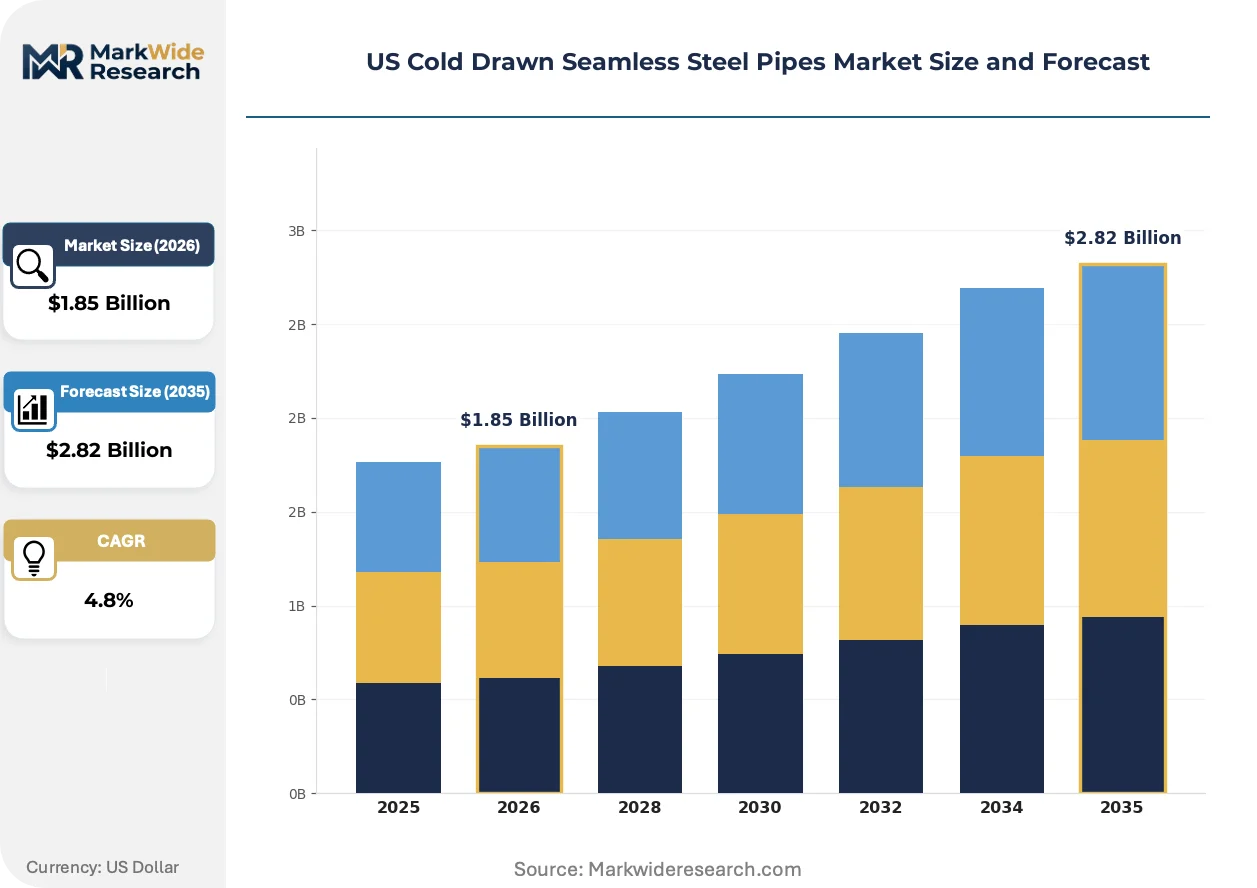
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Pipes, Structural Pipes, Oil Country Tubular Goods, Boiler Tubes, Others Technology: Cold Drawing, Hot Rolling, Forging, Extrusion, Threading Application: Oil & Gas Exploration, Chemical Processing, Power Generation, Automotive Manufacturing, Aerospace Engineering End User: Energy Producers, Petrochemical Plants, Power Plants, Vehicle Manufacturers, Aircraft Builders |
| Companies Covered | U. S. Steel Tubular Products Inc., ArcelorMittal North America Holdings LLC, Chicago Tube and Iron Company, American Piping Products Inc., Michigan Seamless Tube, LLC, Penn Stainless Products, Inc., U.S. Metals, Inc., Industrial Tube and Steel Corporation, Bison Stainless Tube, LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cold Drawn Seamless Steel Pipes Market Strategic Shifts & Innovations
Technological advancements in material science and process control are converging with policy-driven supply chain realignments. This dynamic compels producers to innovate beyond traditional manufacturing, focusing on product integrity, application-specific performance, and emissions reduction to maintain a competitive edge.
Advanced non-destructive testing (NDT) technologies, such as phased array ultrasonic testing, provide comprehensive internal and external flaw detection in real-time. Aerospace and energy sector clients increasingly mandate these advanced inspection protocols. The implementation of automated NDT is displacing older, slower manual inspection methods, improving throughput and enabling 100% inspection for critical applications.
The Environmental Protection Agency (EPA) continues to tighten air emission standards for steel production under the Clean Air Act. These regulations mandate reduced output of particulate matter and hazardous air pollutants, forcing investment in superior fume capture systems and cleaner furnace technologies. Mills located in non-attainment zones face the most stringent compliance burdens, influencing decisions on facility upgrades and expansions.
A clear shift in purchasing behavior is evident as large end-users in the energy sector prioritize total cost of ownership over initial price. This involves specifying pipes with enhanced corrosion resistance or higher tensile strength to extend asset life and reduce maintenance cycles. This preference is most visible in procurement for deepwater offshore projects and unconventional gas fields.
US Cold Drawn Seamless Steel Pipes Market Segmentation
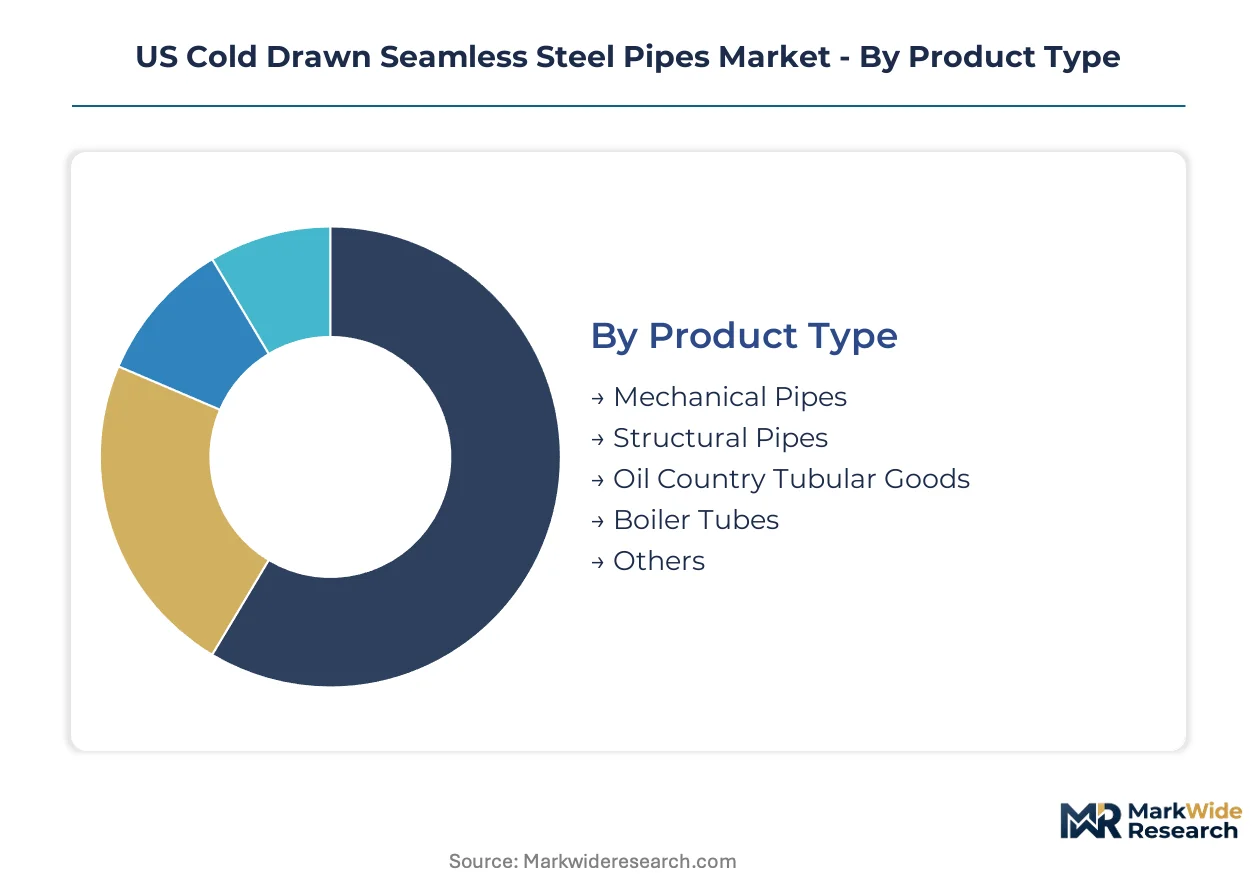
The US cold drawn seamless steel pipes market differentiates across distinct product forms, manufacturing processes, end-use applications, and customer types. Understanding these segments reveals specific demand drivers and supply chain dynamics influencing material specifications and procurement patterns. Market stratification reflects varying performance requirements, from high-pressure energy applications to precision automotive components.
Product Type:
Margin pools within product types are concentrated in specialized, high-performance offerings that meet stringent industry standards and application-specific demands. These premium segments command higher pricing due to their complex manufacturing and critical performance characteristics.
- Oil Country Tubular Goods:These pipes are designed for demanding upstream oil and gas operations, including drilling, casing, and tubing. Demand is concentrated in the US Gulf Coast states, driven by extensive investment in new well development and LNG export infrastructure.
- Mechanical Pipes:Precision-engineered for structural and fluid conveyance applications in machinery, hydraulics, and automotive systems. Automotive manufacturing in the Midwest is driving significant demand for these pipes, requiring tight tolerances for lightweight electric vehicle components.
- Structural Pipes:Used in construction and heavy equipment for their load-bearing capabilities.
- Boiler Tubes:Designed for high temperatures and pressures in heat exchangers and power generation systems.
- Others:Includes specialized pipes for niche industrial applications and custom projects.
Oil Country Tubular Goods holds installed capacity. Mechanical Pipes rotate up share rankings.
Technology:
Supply concentration in manufacturing technologies reflects the capital intensity required for advanced cold drawing and finishing capabilities. Proprietary process controls and specialized equipment define the competitive landscape for producers in this segment.
- Cold Drawing:This core process involves pulling steel through a die at ambient temperatures, enhancing dimensional accuracy, surface finish, and mechanical properties. US producers leverage advanced cold drawing benches to meet precision requirements for automotive and aerospace sectors.
- Threading:A post-processing step that creates screw threads on pipe ends, essential for joining pipes in high-pressure applications like Oil Country Tubular Goods. This process requires specialized machinery and strict quality control for secure connections in oil and gas infrastructure.
- Hot Rolling:Produces seamless pipes at elevated temperatures, for larger diameters or less stringent finish.
- Forging:Shapes metal using compressive forces, suitable for complex pipe geometries or high-strength components.
- Extrusion:Forces metal through a die to create continuous profiles, for specialized alloys.
Cold drawing technology underpins precision output. Threading capabilities gain share fastest.
Application:
Volume dynamics across applications are driven by large-scale infrastructure projects and evolving industrial manufacturing needs. Each application segment demands specific pipe properties, influencing material selection and production volumes for manufacturers.
- Oil & Gas Exploration:Pipes are critical for drilling, casing, and transporting hydrocarbons under high pressure and corrosive conditions. Sustained investment in US shale plays and offshore projects drives consistent demand for robust seamless steel pipes.
- Automotive Manufacturing:Utilizes precision seamless pipes for chassis, hydraulic systems, and structural components requiring high strength-to-weight ratios. The shift towards electric vehicles in the US necessitates lightweighting, accelerating demand for advanced steel alloys.
- Chemical Processing:Requires corrosion-resistant pipes for transporting aggressive chemicals in industrial plants.
- Power Generation:Employs high-temperature and high-pressure pipes in boilers and steam lines for electricity.
- Aerospace Engineering:Demands ultra-high strength, lightweight pipes for hydraulic lines and structural elements in aircraft.
Oil & Gas Exploration remains foundational. Automotive Manufacturing shows steepest expansion.
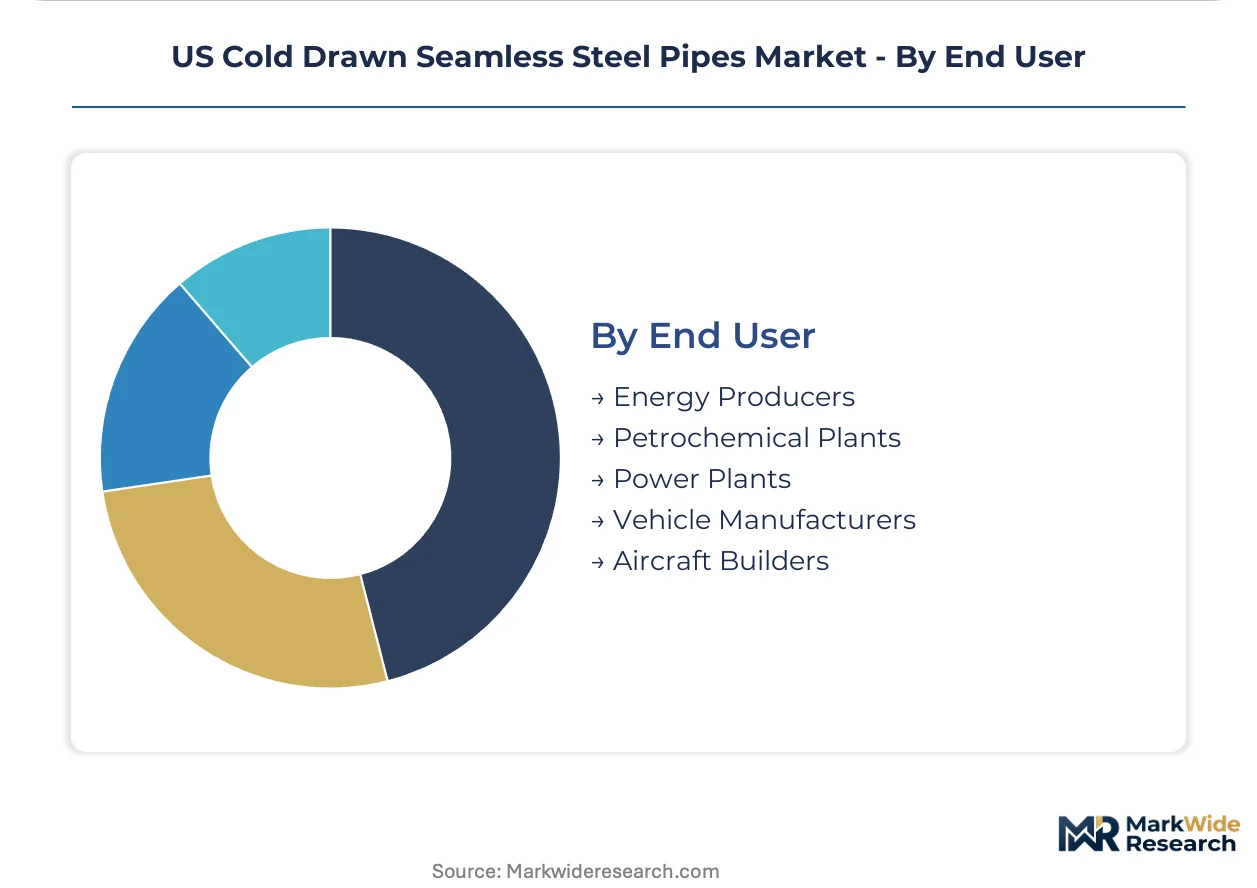
End User:
Customer type segmentation highlights distinct procurement behaviors and technical requirements from major industrial consumers. Direct relationships with these end-users are crucial for producers to align product development with specific industry needs and regulatory compliance.
- Energy Producers:These companies operate in upstream, midstream, and downstream sectors, requiring specialized pipes for exploration, transportation, and processing of oil and natural gas. Their purchasing decisions are heavily influenced by API standards and project-specific material specifications for Gulf Coast operations.
- Vehicle Manufacturers:Integrate seamless steel pipes into various vehicle components, prioritizing precision, lightweighting, and material strength. US automotive giants are increasingly demanding pipes optimized for electric vehicle platforms, impacting supplier specifications.
- Petrochemical Plants:Utilize seamless pipes for conveying corrosive fluids, demanding high chemical resistance.
- Power Plants:Procure pipes for extreme temperatures and pressures in boilers and steam systems.
- Aircraft Builders:Require highly specialized, certified pipes for critical aerospace applications.
Energy Producers constitute a significant end-user base. Vehicle Manufacturers climb fastest in demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for standard-grade pipes remains concentrated in regions with high-volume demand like the Gulf Coast, while specialized products command premium pricing in precision manufacturing hubs. This dynamic creates distinct regional market characteristics across the United States. Demand drivers and regulatory frameworks vary significantly by geographic area.
Gulf Coast States
Extensive oil and gas exploration, coupled with LNG export infrastructure projects, drives consistent demand for Oil Country Tubular Goods. The Inflation Reduction Act (IRA) incentives bolster domestic sourcing for these critical materials. Houston, Texas, remains a central hub for new well development and pipeline construction activities.
Midwest
Automotive manufacturing, particularly the shift towards electric vehicle components, generates significant demand for precision mechanical tubing. EPA air emission standards influence steel production processes, necessitating investment in cleaner technologies. Detroit, Michigan, focuses on lightweighting initiatives for advanced EV platforms.
Northeast
Modernization of aging municipal water systems and general industrial applications underpin demand for durable seamless steel pipes. OSHA rules mandate rigorous worker safety in steel production facilities, impacting operational costs. Pittsburgh, Pennsylvania, continues to invest in advanced finishing capabilities for specialized industrial uses.
California
Aerospace engineering and high-tech manufacturing require ultra-high strength, lightweight pipes for critical applications. State-level environmental policies shape manufacturing practices, pushing for sustainable production methods. Los Angeles, California, supports specialized pipe demand for defense and commercial aerospace sectors.
US Cold Drawn Seamless Steel Pipes Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the US cold drawn seamless steel pipes market. The market exhibits a tiered structure, with integrated steel producers focusing on economies of scale for high-volume standard grades. Specialized fabricators differentiate through custom alloys and tight tolerances for niche, high-performance applications such as aerospace and defense. Capacity expansion and strategic partnerships are dominant competitive moves shaping the industry's evolution.
Integrated giants like U. S. Steel Tubular Products Inc. exemplify scale-driven production, leveraging extensive infrastructure for high-volume output across various industrial sectors. ArcelorMittal North America Holdings LLC sustains its market position through a powerful distribution network spanning diverse end-user industries across the US. Michigan Seamless Tube, LLC occupies a specialized tier, focusing on custom alloys and tight tolerances to meet stringent requirements for aerospace and defense applications.
| Leading Market Players |
|---|
| U. S. Steel Tubular Products Inc. |
| ArcelorMittal North America Holdings LLC |
| Chicago Tube and Iron Company |
| American Piping Products Inc. |
| Michigan Seamless Tube, LLC |
| Penn Stainless Products, Inc. |
| U.S. Metals, Inc. |
| Industrial Tube and Steel Corporation |
| Bison Stainless Tube, LLC |
Cost & Logistics Intelligence
Project-based procurement for large infrastructure projects locks in both material supply access and price visibility for US cold drawn seamless steel pipes. This structure enables long-term planning for complex energy and automotive initiatives.
Pricing Analysis
Customization-premium pricing differentiates specialized seamless pipes from standard-grade offerings in the US market. The dominant pricing model is contract-based long-term offtake for major industrial buyers. Price differentiation stems from precision tolerances and specific alloy compositions. Pricing softness reflects input cost volatility in raw materials like chromium and molybdenum. Vehicle manufacturers exhibit higher price sensitivity for high-volume components, while aerospace engineering prioritizes performance over cost.
Supply Chain Analysis
The United States anchors cold drawn seamless steel pipe production, with significant output from Gulf Coast states for energy and the Midwest for automotive. The supply chain draws from high-grade steel scrap and essential alloying elements such as molybdenum. Single-source vulnerability for specialized components presents a structural risk for certain applications. Distribution runs through established networks of industrial distributors and direct supply agreements with large end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US cold drawn seamless steel pipes market is defined by a scarcity of advanced finishing capabilities for high-precision applications. This gap necessitates strategic investments in specialized equipment and skilled personnel.
For Market Incumbents:Compound existing scale advantages by expanding high-volume standard-grade production in Gulf Coast facilities. Invest in advanced NDT certification to counter threats from substitute materials and ensure product integrity. Strengthen distribution networks to maintain market access and reduce customer churn. Pursue R&D in hydrogen-resistant alloys to capture future infrastructure demand.
For New Entrants and Emerging Players:Niche service gaps in custom alloy development for aerospace and defense applications present a significant white space. Target the Midwest automotive manufacturing sector with precision mechanical tubing optimized for electric vehicle lightweighting. A go-to-market angle focused on rapid prototyping and specialized material certification can attract high-value clients.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among specialized manufacturers serving critical infrastructure and defense sectors. Long-term viability rests on securing intellectual property in advanced materials and process control over the next 5-10 years. Acquisition targets should be mid-sized specialists with proprietary cold drawing techniques or unique certification portfolios. A signal to watch is legislative changes favoring domestic sourcing for strategic materials.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expand cold drawing bench capacity to meet rising demand from automotive manufacturing. |
| Certification Investment | Secure API certification for new product lines targeting Gulf Coast oil and gas projects. |
| R&D in Advanced Materials | Develop specialized alloys resistant to hydrogen embrittlement for emerging hydrogen infrastructure. |
| Strategic Partnership | Form alliances with NDT technology providers to implement automated inspection protocols. |
| Workforce Development Program | Address skill gaps by investing in training programs for metallurgists and skilled machine operators. |
Research Approach
Initial hypotheses were tested against primary input from metallurgists, NDT inspectors, automotive procurement leads, and energy project managers. This involved combining direct interviews with secondary validation from industry reports. Bottom-up data aggregation and top-down market sizing provided a triangulated view. Secondary sources included API standards, EPA regulations, OSHA rules, and major steel producer SEC filings.
Variance decomposition isolated key growth drivers and restraints across the analysis window, allowing for granular market projections. The framework modeled market evolution across product type, technology, application, end user, and regional demand. Compound annual growth rates were derived by integrating historical trends with future projections. Industry-specific inputs included automotive lightweighting trends and oil & gas investment cycles.
Material uncertainties — input cost volatility, IRA policy changes, and technological substitution — sit outside the modeled envelope. Forecasts reflect assumptions based on current market conditions and anticipated regulatory trajectories. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market
Pipes and Tubes
Steel Pipe Market
Pipes and Tubes
Industrial Draft Tube Crystallizer Market
Pipes and Tubes
GCC CPVC Pipes Market
Pipes and Tubes
Glass Reinforced Epoxy (GRE) Pipes Market
Pipes and Tubes
PVC Pipes and Fittings Market
Pipes and Tubes
Piping System and Piping Spools Market
Pipes and Tubes
Global Polypropylene Pipes Market
Pipes and Tubes
Gas Pipe Fittings Market
Pipes and Tubes
Global Titanium Tube Market
Pipes and Tubes
Stainless Steel Plumbing Pipes Market
Pipes and Tubes
Industrial Blast Hoses Market
Pipes and Tubes
Tapping Sleeves Market
Pipes and Tubes
Europe PVC Pipes Market
Pipes and Tubes
Water and Wastewater Pipe Market
Pipes and Tubes
Gathering Pipeline Market