
 High Performance Coatings Market | 2026-2036
High Performance Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Coatings Market Outlook
Specialty chemical producers in Germany's industrial corridor is consolidating waterborne polyurethane capacity to serve automotive OEMs. PPG Industries Inc. leverages its aerospace qualification portfolio across North American and European airframe programs. Akzo Nobel NV anchors marine coating supply through controlled distribution at major European shipyards. BASF SE sustains R&D intensity in epoxy formulations for wind-tower protection.
High performance coatings are engineered systems delivering thermal stability, chemical resistance, and mechanical durability under extreme operating conditions, typically formulated with fluoropolymers, ceramic fillers, or advanced resin matrices cured through controlled thermal or radiation processes. Their primary purpose is extending asset life cycles in environments where standard coatings degrade within months. Epoxy chemistry dominates heavy-industrial maintenance for its adhesion to blasted steel, while waterborne technology captures the fastest expansion as environmental compliance tightens across manufacturing jurisdictions. Powder coatings occupy a mature margin pool in appliance and architectural metal finishing where transfer efficiency and VOC elimination carry regulatory weight.
REACH restrictions on volatile organic compounds and EPA emissions standards under the Clean Air Act are restructuring formulation priorities across solventborne portfolios. ECHA substance-of-very-high-concern listings are forcing reformulation of legacy chromate pretreatments in aerospace primers. Stakeholders must monitor regulatory divergence between EU hazard-classification schemes and OSHA permissible exposure limits when allocating product-development resources across manufacturing footprints.
Market Dynamics
The solventborne-to-waterborne transition is compressing legacy formulation margins while concentrating supply among producers with captive resin synthesis capabilities. REACH substance restrictions and EPA emissions standards are forcing simultaneous reformulation across multiple industrial coating categories.
Growth Catalysts
- Aerospace thermal-barrier specifications:OEMs in Germany and France are qualifying ceramic-filled polyurethane systems for next-generation turbine components. Airframe programs in Toulouse and Hamburg are driving dual-cure process adoption.
- EU Green Deal industrial mandates:The European Commission's carbon-border adjustment mechanism is accelerating low-VOC coating procurement across automotive assembly plants in Stuttgart and Wolfsburg.
- Wind-tower epoxy demand:Offshore installations in the North Sea and Baltic are specifying extended-life primer systems. German and Danish operators are consolidating supplier lists around proven field performance data.
Market Restraints
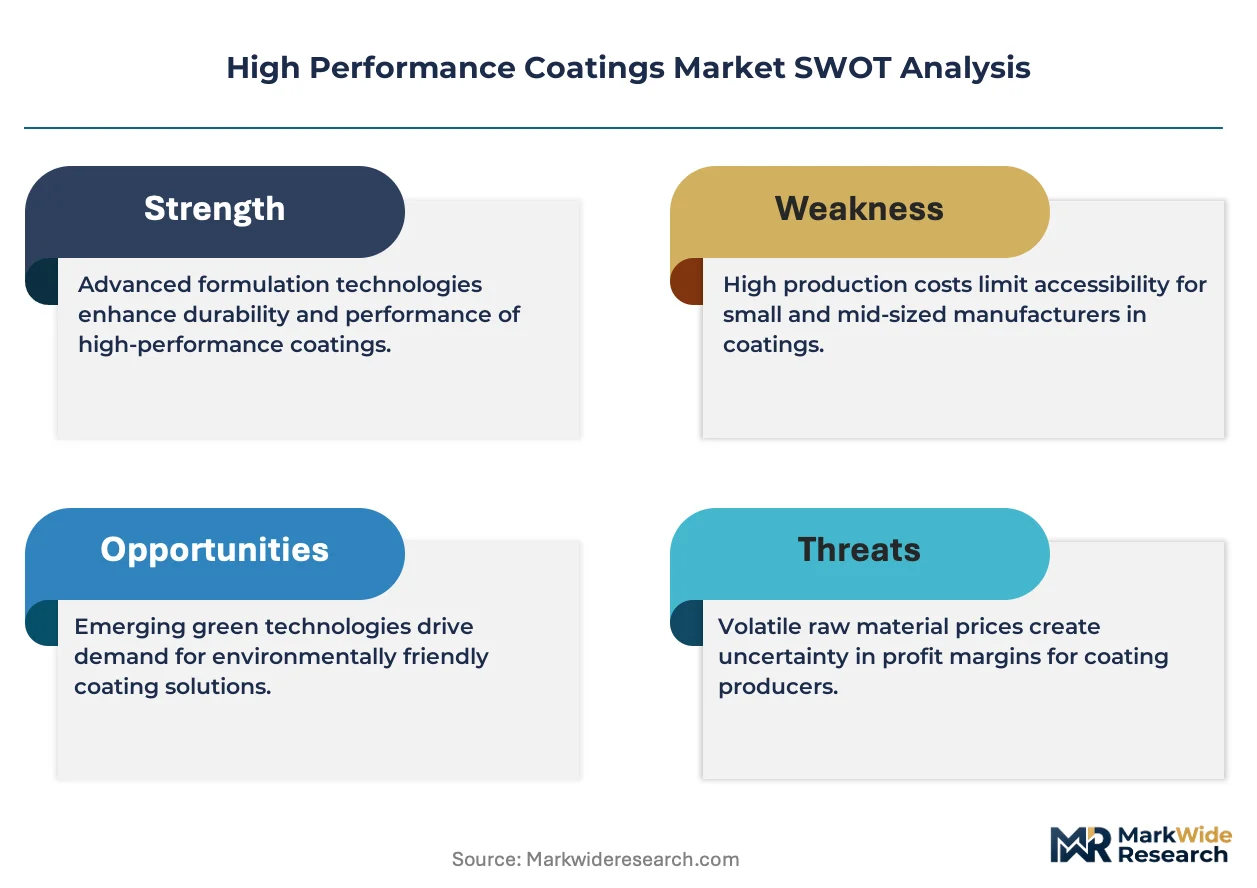
- Fluoropolymer feedstock concentration:PTFE and PVDF resin supply concentrates among three integrated chemical producers. Disruptions at any single facility cascade through aerospace and chemical-processing coating supply chains.
- Chromate pretreatment phase-out:ECHA's SVHC listings have eliminated hexavalent chromium conversion coatings from aerospace primers. Alternative trivalent and cerium-based systems require longer qualification cycles with airframe OEMs.
- Ceramic filler cost volatility:High-purity alumina and zirconia prices fluctuate with energy costs in Chinese and Norwegian smelting operations. Coating producers lack pricing power to pass through raw material spikes.
Strategic Opportunities
- India industrial corridor penetration:Automotive and white-goods manufacturing clusters in Pune and Chennai are upgrading from commodity enamels to polyurethane and powder systems. Domestic producers lack formulation depth in high-temperature segments.
- UV-cure convergence with robotics:Automated spray cells at German automotive suppliers are integrating UV-LED curing arrays. This eliminates thermal oven bottlenecks and reduces energy intensity per coated unit.
- Marine coating specification tightening:IMO antifouling restrictions and EU port-state controls are displacing copper-based systems. Silicone foul-release coatings are gaining trial slots at Korean and Japanese shipyards.
Industry Challenges
- Formulation chemist scarcity:Waterborne polyurethane expertise concentrates among specialists with 15-plus years of industrial experience. Technical universities in Germany and the Netherlands have reduced polymer chemistry program enrollment.
- Multijurisdictional certification timelines:Aerospace primers require simultaneous FAA, EASA, and CAAC qualification. Each regulator maintains distinct testing protocols and documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Performance Coatings Market |
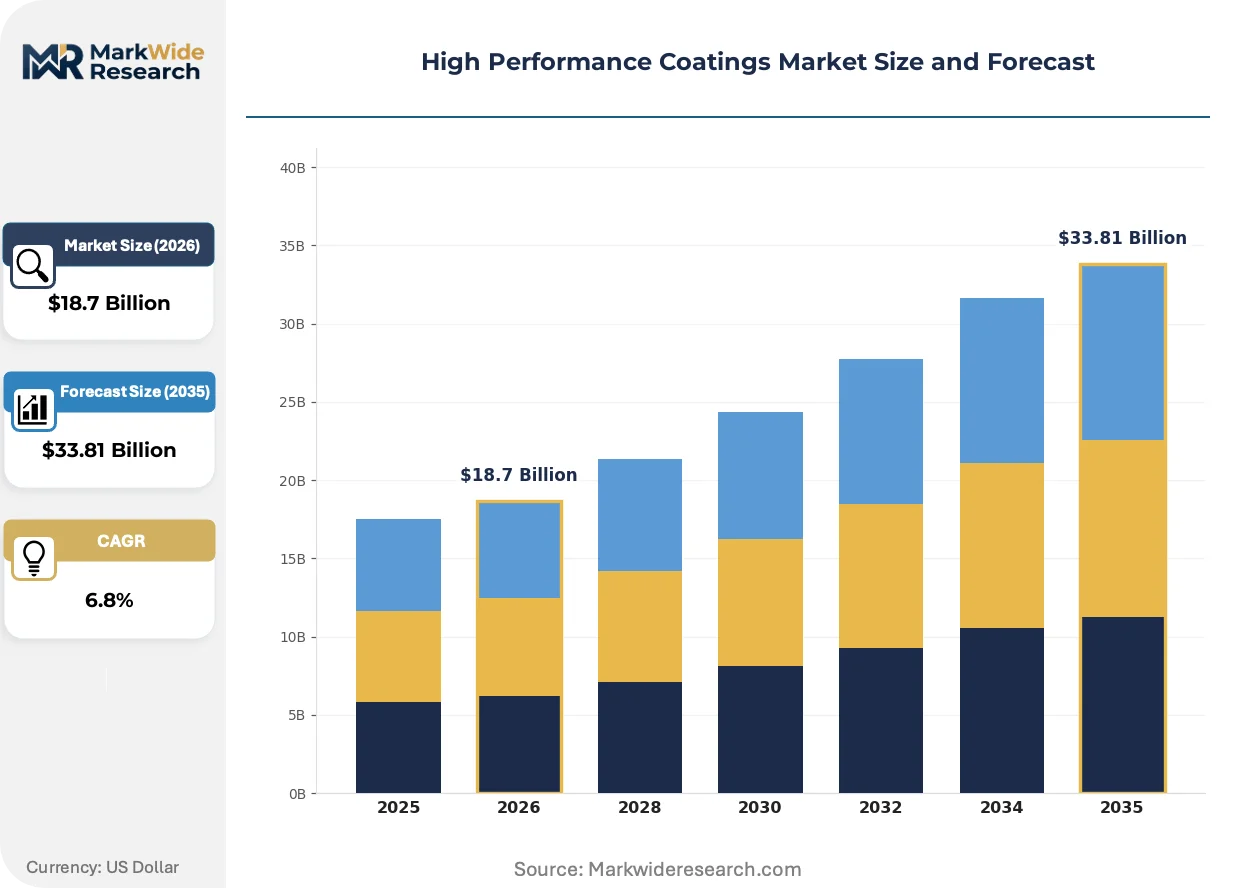
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Alkyd Application: Aerospace, Automotive, Marine, Construction End User: Manufacturers, Contractors, OEMs, Repair Shops Technology: Waterborne, Solventborne, Powder Coatings, UV Curable |
| Companies Covered | PPG Industries Inc., Akzo Nobel NV, The Sherwin-Williams Company, BASF SE, Axalta Coating Systems LLC, Hempel Group, Jotun, Nippon Paint Holdings Co., Ltd., Daikin Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Coatings Market Strategic Shifts
Digital formulation platforms and closed-loop manufacturing controls are compressing development cycles while tightening batch consistency. These capabilities separate integrated producers from toll-compounders.
Self-healing polymer networks incorporating microencapsulated repair agents are automating damage recovery in automotive clearcoats and aerospace leading-edge protection. German premium OEMs are specifying laboratory-validated systems for 2027 model-year programs. This technology is automating quality assurance by reducing field failure rates and warranty claim frequency.
REACH authorization requirements for diisocyanates are restricting polyurethane spray application across European maintenance yards. Training certification mandates under ECHA's restriction entry are extending contractor onboarding timelines. Marine and industrial maintenance segments in Hamburg and Rotterdam are consolidating around qualified applicator networks with documented compliance records.
Asset-owner procurement teams are unbundling coating supply from application services. German wind-farm operators and chemical processors are separating material specification from contractor selection. This shift is most visible in the Rhine-Ruhr industrial corridor, where facility engineers now mandate third-party coating inspection and performance bonding independent of applicator relationships.
High Performance Coatings Market Segmentation
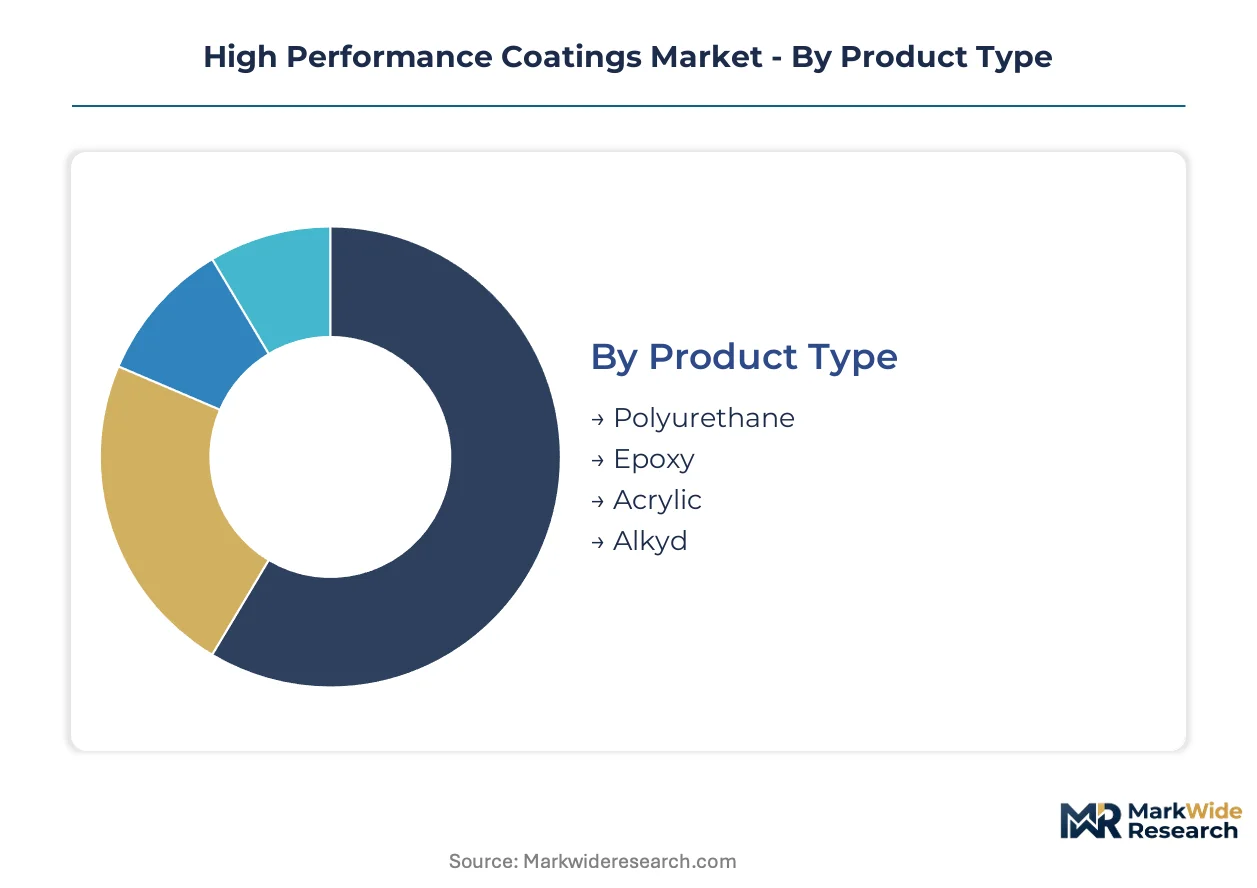
High performance coatings serve asset owners with divergent risk tolerances and regulatory exposures. Segmentation reveals where formulation investments concentrate and which buyer archetypes command premium pricing.
Product Type:
Buyers in this category separate by corrosion severity, thermal exposure, and substrate preparation budgets.
- Polyurethane:Two-component systems combining isocyanate crosslinkers with polyol resins deliver exceptional abrasion resistance and UV stability. Demand concentrates in German automotive OEM clearcoats and aerospace exterior finishes, where ECHA diisocyanate restrictions are extending contractor qualification timelines.
- Epoxy:Amine-cured bisphenol formulations provide superior adhesion to blasted steel and chemical resistance. Offshore wind towers in the North Sea and Baltic specify extended-life epoxy primers, with Danish and German operators consolidating supplier lists around proven field performance data.
- Acrylic:Thermoplastic and thermoset variants balance cost with exterior durability for architectural metal finishing.
- Alkyd:Oil-modified polyester resins serve maintenance markets where solventborne application persists despite VOC pressures.
Volume sits with epoxy in heavy industrial maintenance; growth tilts toward polyurethane as waterborne automotive specifications tighten.
Application:
End-use environments dictate cure chemistry, film thickness requirements, and certification burdens.
- Aerospace:Thermal-barrier and corrosion-resistant systems protect turbine components and airframes under extreme thermal cycling. OEMs in Toulouse and Hamburg are qualifying ceramic-filled polyurethane systems, with dual-cure process adoption accelerating across next-generation airframe programs.
- Automotive:Clearcoats and basecoats must balance appearance retention with regulatory compliance. Stuttgart and Wolfsburg assembly plants are accelerating low-VOC coating procurement under EU carbon-border adjustment mechanisms.
- Marine:Antifouling and protective systems face IMO restrictions displacing copper-based formulations. Korean and Japanese shipyards are trialing silicone foul-release coatings under tightening port-state controls.
- Construction:Structural steel protection combines with architectural metal finishing across infrastructure and commercial projects.
Revenue concentrates in aerospace qualification-driven sales; expansion accelerates most quickly in marine as regulatory deadlines approach.
End User:
Procurement sophistication varies sharply between specification writers and applicator contractors.
- Manufacturers:In-house coating operations at automotive and appliance producers demand consistent batch quality and regulatory documentation. German white-goods manufacturers are upgrading from commodity enamels to polyurethane and powder systems.
- OEMs:Original equipment manufacturers write performance specifications that cascade through supply chains. Airframe OEMs maintain distinct FAA, EASA, and CAAC qualification protocols.
- Contractors:Third-party applicators face ECHA training mandates for diisocyanate handling. Hamburg and Rotterdam maintenance yards are consolidating around qualified networks with documented compliance records.
- Repair Shops:Smaller-scale operations prioritize material availability and simplified application over maximum performance.
Specification authority rests with OEMs; profit pool expansion favors manufacturers integrating coating operations.
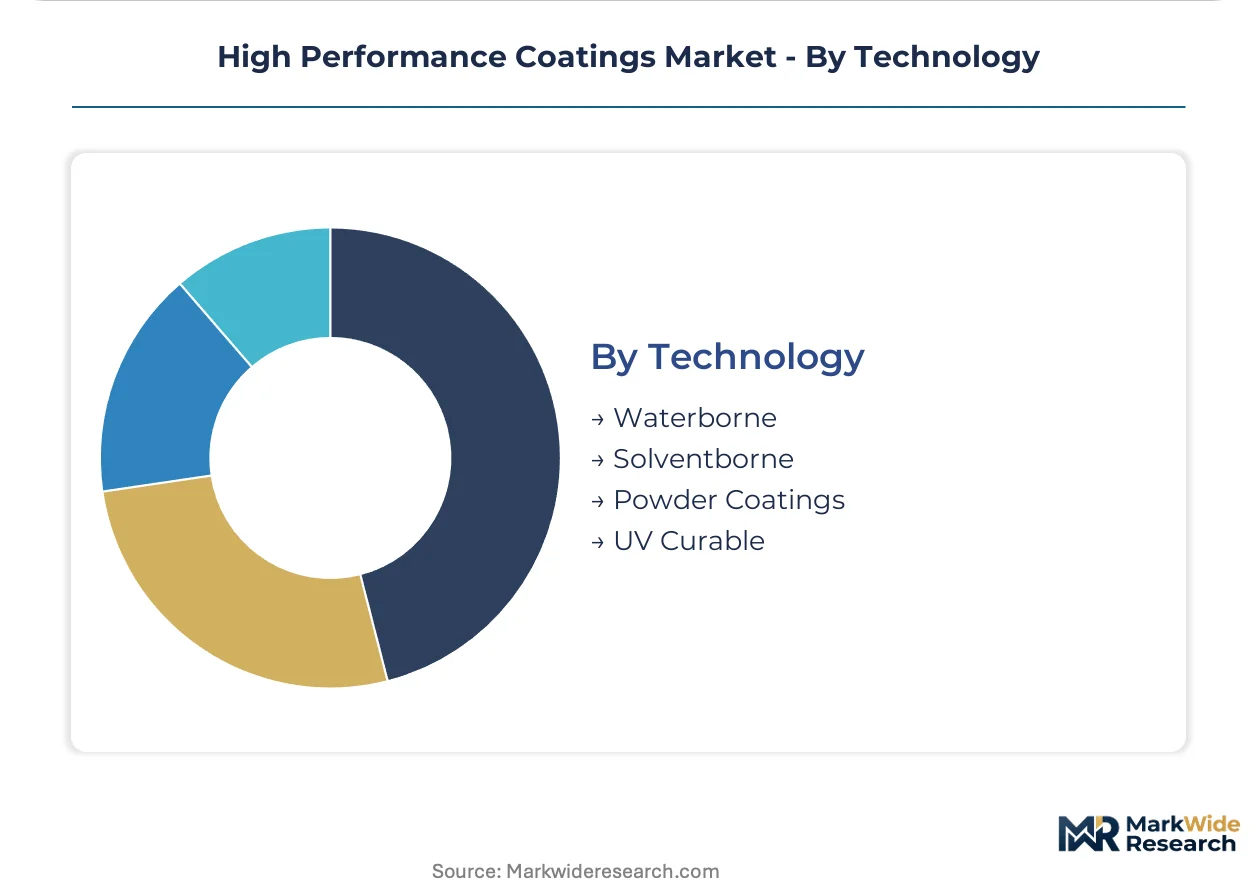
Technology:
Environmental compliance timelines and capital intensity divide adoption patterns across user types.
- Waterborne:Polyurethane and acrylic dispersions replace solventborne systems where VOC limits tighten. REACH and EU Green Deal mandates are accelerating conversion across European automotive assembly plants.
- Solventborne:Legacy formulations persist in aerospace and marine where performance specifications resist reformulation. Margin compression is concentrating supply among producers with captive resin synthesis capabilities.
- Powder Coatings:Thermoset powders eliminate VOC emissions and achieve high transfer efficiency in appliance and architectural metal finishing.
- UV Curable:Rapid cure through LED arrays eliminates thermal oven bottlenecks. German automotive suppliers are integrating UV-LED curing arrays into automated spray cells, reducing energy intensity per coated unit.
Installed base remains solventborne; technology transition gains share fastest in waterborne polyurethane as regulatory deadlines harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluoropolymer resin production concentrates in Chinese and Norwegian smelting corridors, anchoring feedstock supply for aerospace and chemical-processing coating formulations across three continents.
United States
Aerospace OEMs in Seattle and Charleston drive thermal-barrier coating procurement for next-generation turbine programs. EPA emissions standards under the Clean Air Act compress solventborne formulation margins. Automated spray cells in Michigan automotive plants integrate UV-LED curing arrays to eliminate thermal oven bottlenecks.
Germany
Automotive assembly plants in Stuttgart and Wolfsburg accelerate low-VOC coating procurement under EU carbon-border adjustment mechanisms. REACH substance restrictions force simultaneous reformulation across industrial coating categories. The Rhine-Ruhr industrial corridor concentrates waterborne polyurethane capacity serving white-goods manufacturers upgrading from commodity enamels.
China
Wind-tower installations in the Yangtze River Delta and Shandong Peninsula specify extended-life epoxy primer systems for offshore deployment. MEE environmental compliance timelines tighten VOC limits across manufacturing jurisdictions. Domestic producers in Jiangsu and Zhejiang lack formulation depth in high-temperature ceramic-filled segments.
Japan
Marine coating specifications at Korean and Japanese shipyards displace copper-based systems under IMO antifouling restrictions. METI industrial standards accelerate silicone foul-release coating trials. Osaka-based chemical processors consolidate supplier lists around proven field performance data for chemical-resistant tank linings.
India
Automotive and appliance manufacturing clusters in Pune and Chennai upgrade from commodity enamels to polyurethane and powder systems. BIS certification requirements extend product qualification timelines for imported formulations. Domestic producers lack captive resin synthesis capabilities for waterborne automotive clearcoats.
High Performance Coatings Market Competitive Environment
Global majors compete with regional champions across formulation qualification depth and captive resin synthesis capabilities. The vendor base separates into integrated chemical conglomerates with aerospace certification portfolios, specialized marine coating suppliers with controlled distribution at major shipyards, and regional formulators serving maintenance markets. Three archetypes dominate: scale-driven resin producers, qualification-heavy aerospace specialists, and application-integrated marine suppliers. Competitive moves concentrate on backward integration into fluoropolymer feedstocks and geographic expansion into Indian industrial corridors.
Among diversified chemical conglomerates, PPG Industries Inc. and BASF SE exemplify the integrated archetype combining captive resin production with aerospace and automotive qualification portfolios. Akzo Nobel NV anchors the marine-specialist position through controlled distribution networks. These three entities represent distinct competitive vectors—scale-driven synthesis, qualification-heavy OEM relationships, and application-integrated supply—rather than direct substitution competitors.
| Leading Market Players |
|---|
| PPG Industries Inc. |
| Akzo Nobel NV |
| The Sherwin-Williams Company |
| BASF SE |
| Axalta Coating Systems LLC |
| Hempel Group |
| Jotun |
| Nippon Paint Holdings Co., Ltd. |
| Daikin Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon-border adjustment mechanisms gate qualified supply for premium-tier coating procurement across European automotive assembly plants. REACH substance restrictions simultaneously compress legacy formulation margins while concentrating pricing power among producers with captive resin synthesis capabilities.
Pricing Analysis
Warranty and performance-bond bundling separates premium-tier suppliers from commodity competitors in wind-tower and marine coating segments. Three-tier pricing structure across aerospace-qualified, industrial-maintenance, and commodity-appliance levels tracks certification burden and field-performance data depth. Cost compression in solventborne epoxy runs through feedstock volatility at Chinese and Norwegian smelting operations. Small-scale repair shops exhibit highest price sensitivity; aerospace OEMs demonstrate lowest sensitivity due to qualification lock-in effects.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Hamburg, and Singapore anchor hub-and-spoke patterns for marine and industrial coating delivery. Fluoropolymer resin production concentrates in China, Norway, and the United States, drawing from high-purity alumina and zirconia feedstocks. Single-source vulnerability at integrated PTFE facilities cascades through aerospace primer supply chains. Distribution runs through controlled networks at major European shipyards and German automotive supplier parks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterborne polyurethane formulation chemist scarcity props pricing across qualified applicator networks. Capacity bottlenecks in ECHA-certified contractor pools concentrate margin capture among incumbents with documented compliance records.
For Market Incumbents: Acquire captive fluoropolymer resin synthesis assets to secure feedstock access against Chinese and Norwegian supply concentration. Expand waterborne capacity in Germany's Rhine-Ruhr corridor before EU carbon-border adjustment deadlines harden. Chromate pretreatment phase-out timelines threaten legacy aerospace primer margins; accelerate trivalent and cerium-based system qualification with Toulouse and Hamburg OEMs.
For New Entrants and Emerging Players: Direct-to-applicator digital platforms bypass established distributor control at Hamburg and Rotterdam maintenance yards. Target Indian industrial corridors in Pune and Chennai where domestic producers lack formulation depth in high-temperature ceramic-filled segments. White-goods manufacturers upgrading from commodity enamels present lowest qualification barriers for polyurethane and powder system entry.
For Investors and Strategic Acquirers: ECHA diisocyanate training certification backlogs are the leading indicator that qualified applicator network scarcity will deepen across European maintenance segments. Five-to-ten year viability favors vertically integrated specialists combining captive resin production with aerospace qualification portfolios. Watch for UV-LED curing array adoption rates at German automotive suppliers as automation inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Feedstocks | Secures PTFE and PVDF supply against Norwegian and Chinese smelting concentration risk. |
| Waterborne Capacity Expansion | Captures EU Green Deal procurement acceleration at Stuttgart and Wolfsburg assembly plants. |
| Aerospace Qualification Investment | Builds FAA, EASA, and CAAC protocol depth for turbine component coating specifications. |
| UV-Cure Technology Licensing | Eliminates thermal oven bottlenecks for German automotive supplier automated spray cells. |
| Marine Silicone Foul-Release Trials | Positions for IMO copper-ban displacement at Korean and Japanese shipyard programs. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this high performance coatings assessment. Primary interviews with formulation chemists, automotive procurement leads, marine coating applicators, and wind-farm asset managers combined with ACC, Cefic, and SEC disclosure analysis. Bottom-up segment sizing and top-down market reconciliation validated volume and value estimates across the analysis window.
Data-stream reconciliation merged production capacity disclosures, import-export flows, and end-use procurement patterns into a unified analytical framework. Segmentation dimensions modeled include resin chemistry tier, cure technology type, end-use industry, and regional regulatory cluster. CAGRs derived from trend extrapolation of qualification timelines and technology substitution rates, incorporating aerospace program cadence and offshore wind installation schedules as industry-specific forecast inputs.
The model holds under stable REACH enforcement and ECHA substance restriction timelines; deviation in EU carbon-border adjustment implementation speed or fluoropolymer feedstock disruption would shift volume projections. Forecasts reflect assumptions about waterborne conversion rates and contractor certification pool expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Corrosion Protection Polymer Coating Market
Coatings
Waterborne Wood Coatings Market
Coatings
Emulsion Coatings Market
Coatings
Epoxy Surface Coatings Market
Coatings
Europe Metal Finishing Market
Coatings
High Temperature Coatings Market
Coatings
Global Sputter Coatings Market
Coatings
Self-Healing Microcapsule Systems for Protective Coatings Market
Coatings
South Korea Automotive OEM Coatings Market
Coatings
Can Coatings Market
Coatings
Yacht Coatings Market
Coatings
Solvent Borne Coatings Market
Coatings
Spain Automotive OEM Coatings Market
Coatings
Ultraviolet (UV) Coatings Market
Coatings
Antimicrobial Coil Coating Market
Coatings
Global Solar Panel Coatings Market