
 PVC Pipes and Fittings Market | 2026-2036
PVC Pipes and Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
PVC Pipes and Fittings Market Analytics
ASTM D1784 cell-classification standards for rigid PVC compounds is redrawing competitive boundaries among manufacturers. JM Eagle leverages its integrated resin-to-pipe production footprint to control cost volatility across North American distribution. Orbia anchors Latin American supply through captive chlor-alkali capacity and extensive extrusion networks. China Lesso Group Holdings Limited dominates domestic project tendering by sustaining price competitiveness at municipal scale.
PVC pipes and fittings comprise thermoplastic conduit systems extruded from polyvinyl chloride resin blended with stabilizers, lubricants, and impact modifiers, typically processed via twin-screw extrusion at melt temperatures between 160°C and 200°C to deliver corrosion-resistant fluid transport infrastructure. The primary industrial purpose centers on gravity and pressure-driven conveyance of water, waste, and chemicals across buried and exposed installations. Rigid pipes occupy the largest value share due to structural load-bearing requirements in municipal water supply and sewerage networks. Irrigation applications within the agricultural end-user segment represent the fastest-expanding demand pool as drip and sprinkler systems displace unlined channels in water-stressed regions. Jointing solutions command premium positioning where push-fit or solvent-weld integrity determines system lifecycle performance.
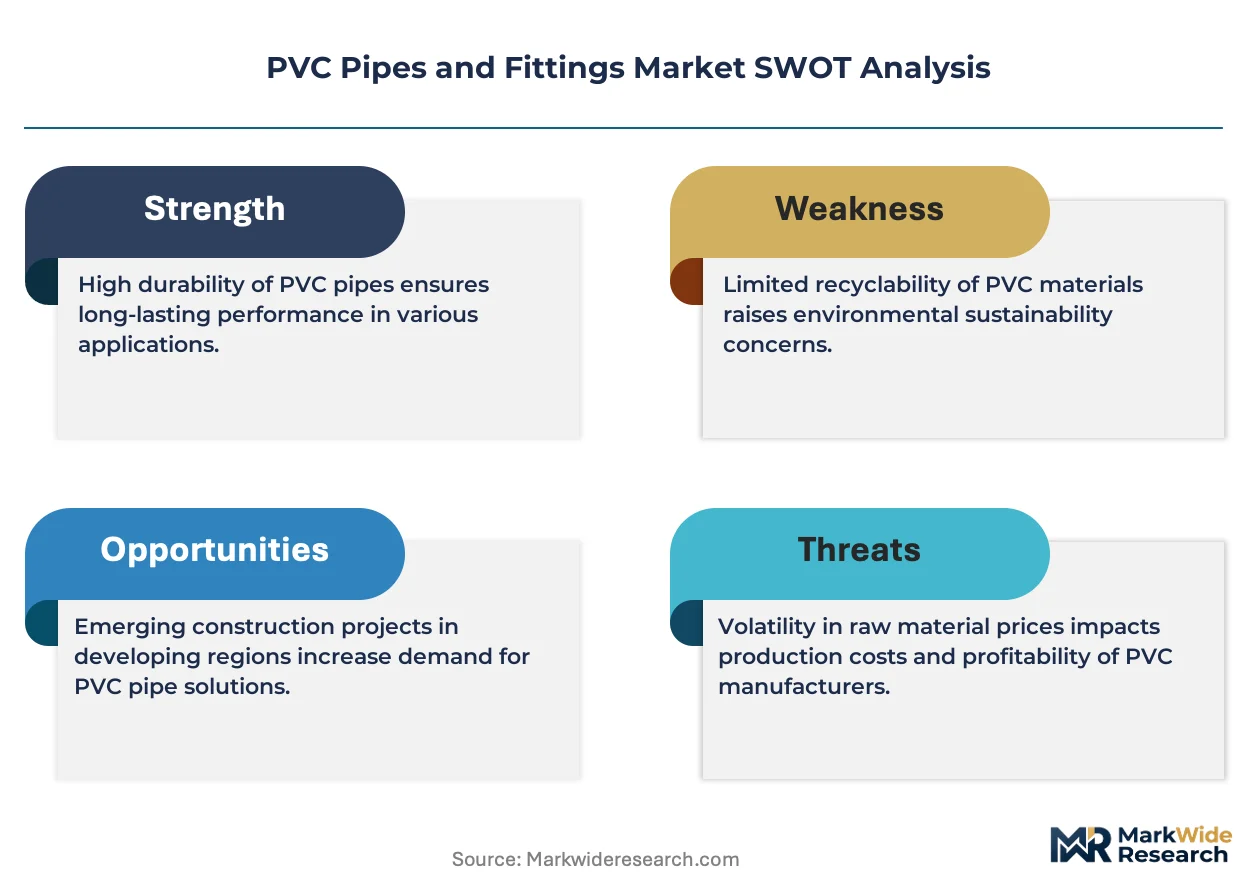
REACH restrictions on lead-based stabilizers and the EU Green Deal's circular-economy mandates are forcing European compounders toward calcium-zinc and organotin formulations. India's BIS certification requirements for potable water pipes, coupled with China's GB standards for drainage applications, create divergent compliance burdens for multinational suppliers. The US EPA Lead and Copper Rule revisions and state-level PFAS scrutiny add further layers to product qualification cycles. Stakeholders must monitor regulatory divergence between jurisdictions to optimize formulation platforms and avoid stranded inventory in cross-border trade.
Market Dynamics
ASTM D1784 cell-classification revisions are compressing formulation flexibility while India's BIS certification mandates and China's GB drainage standards force compounders to maintain parallel qualification tracks across incompatible regulatory regimes.
Growth Catalysts
- India's Jal Jeevan Mission:The rural piped water scheme is accelerating tender volumes for large-diameter rigid PVC pipes across state-level public health engineering departments.
- REACH lead-stabilizer phaseout:European compounders migrating to calcium-zinc formulations are creating first-mover advantages in sustainable product positioning for municipal procurement.
- Drip irrigation conversion:Agricultural water stress in North China Plain and Deccan Plateau regions is displacing unlined channel systems with pressure-rated PVC distribution networks.
Market Restraints
- Resin cost volatility:Ethylene and chlorine feedstock exposure tied to natural gas and crude oil indices creates margin compression for non-integrated extruders.
- Chlor-alkali supply concentration:Captive caustic-chlorine capacity in China and Gulf states limits independent compounder access to cost-competitive raw material streams.
- Cross-linked polyethylene substitution:PEX tubing is capturing residential hot-water segments where PVC thermal limitations exclude the material from specification.
Strategic Opportunities
- Indonesia's transmigration irrigation:Outer island agricultural settlement programs represent underpenetrated demand for pressure-rated distribution mains.
- EU Green Deal circular-economy mandates:Post-consumer PVC recycling quotas are creating feedstock advantages for compounders with mechanical recycling integration.
- Smart leak detection convergence:Embedded sensor fusion with PVC pipe extrusion is enabling predictive maintenance contracts for municipal water utilities.
Industry Challenges
- Multi-jurisdiction formulation management:Simultaneous compliance with India's BIS lead limits, EU REACH organotin restrictions, and US NSF/ANSI 61 certification creates stranded inventory risk across export portfolios.
- Extrusion technician scarcity:Twin-screw process optimization expertise is concentrating among aging workforces in established manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVC Pipes and Fittings Market |
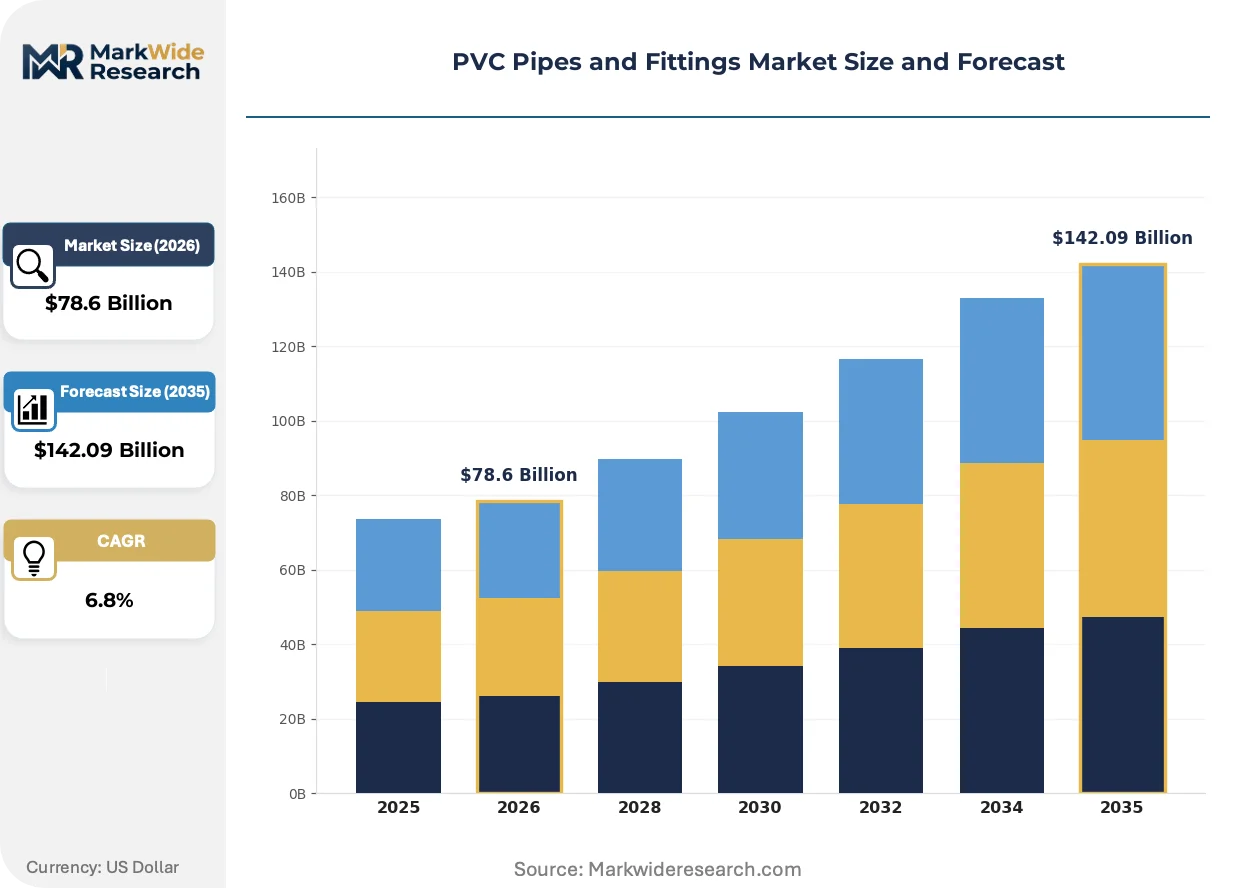
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $142.09 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Pipes, Flexible Pipes, Fittings, Jointing Solutions End User: Construction, Agriculture, Industrial, Residential Application: Water Supply, Sanitation, Drainage, Irrigation Size: 1 inch, 2 inch, 4 inch, 6 inch |
| Companies Covered | Orbia, The Supreme Industries Limited, JM Eagle, Finolex Industries Ltd., Sekisui Chemical Co., Ltd., Aliaxis Holdings SA, Georg Fischer Ltd., Westlake Corporation, China Lesso Group Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVC Pipes and Fittings Market Evolving Landscape
Formulation chemistry, regulatory compliance architecture, and procurement digitization are converging to reshape competitive positioning across the value chain.
High-impact modified PVC (PVC-M) and oriented PVC (PVC-O) compounds are supplanting conventional unplasticized grades in pressure pipe applications. Water utilities in Australia and the Netherlands are specifying biaxially oriented structures for trunk mains where fatigue resistance and hydraulic efficiency justify material premiums. The technology is supplanting ductile iron and concrete in trenchless rehabilitation contracts where wall thickness reduction enables smaller insertion pits.
REACH Annex XVII restrictions on cadmium and lead-based stabilizers are forcing European compounders toward calcium-zinc and mixed-metal systems. The regulatory shift is extending qualification timelines by 12-18 months for potable water applications where migration testing protocols remain unsettled. German and French municipal buyers are now requiring third-party certification to ECHA SVHC screening standards as a pre-qualification gate.
Digital tender platforms are consolidating specification access for tier-two contractors previously dependent on distributor relationships. State-level water boards in India and provincial procurement centers in China are migrating to e-procurement portals where real-time price discovery compresses traditional markup structures. The channel shift is most visible in agricultural irrigation segments where farmer cooperatives bypass wholesale layers to aggregate direct mill orders.
PVC Pipes and Fittings Market Segmentation
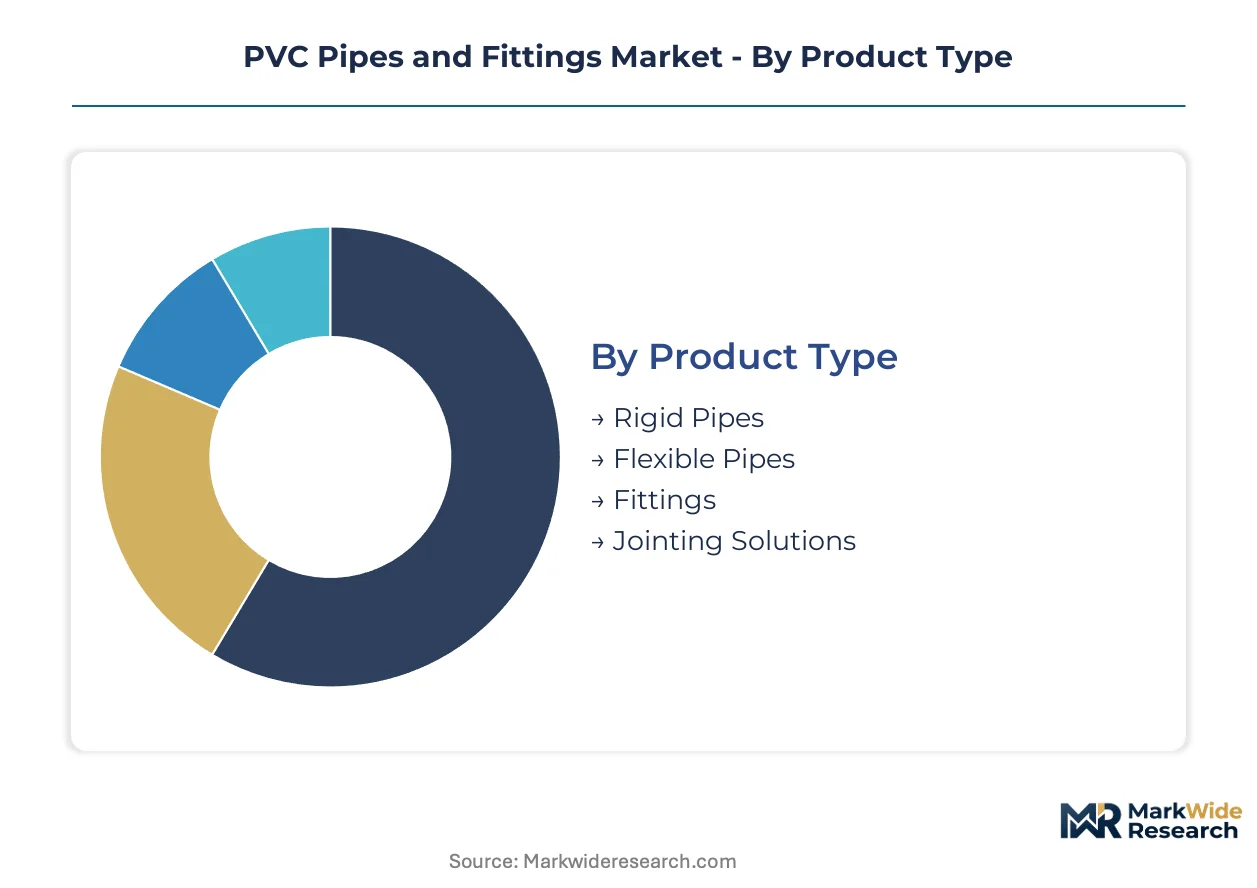
Segmentation in the PVC pipes and fittings market reveals distinct procurement patterns across product types and end-use applications. Channel strategies diverge sharply between bulk municipal tenders and fragmented agricultural distribution networks.
Product Type:
Channel-mix dynamics vary substantially across product categories, with rigid pipes flowing primarily through project-direct procurement while fittings and jointing solutions retain distributor-heavy fulfillment models.
- Rigid Pipes:Extruded unplasticized PVC compounds formulated to ASTM D1784 cell-classification standards for structural load-bearing in buried infrastructure. Municipal water boards in India and urban drainage authorities in China concentrate tender volumes for large-diameter grades, driven by Jal Jeevan Mission acceleration and GB standards compliance mandates. By volume, rigid pipes lead. By growth pace, jointing solutions are expanding most quickly.
- Flexible Pipes:Plasticized PVC formulations with added plasticizers enabling coiled transport and tight-radius installation in trenchless rehabilitation. Demand clusters in agricultural drip-irrigation retrofits across the Deccan Plateau and North China Plain where terrain adaptability offsets pressure-rating limitations.
- Fittings:Injection-molded or fabricated connection elements including elbows, tees, reducers, and flanges. Stock-keeping unit proliferation challenges distributor inventory management, particularly in residential plumbing segments.
- Jointing Solutions:Solvent cements, gaskets, and push-fit mechanisms determining system integrity and lifecycle performance. Premium positioning emerges where leak-free guarantees support predictive maintenance contracts.
By volume, rigid pipes lead. By growth pace, jointing solutions are ahead.
End User:
Cost-tier stratification separates specification-grade municipal procurement from price-sensitive agricultural buying, with industrial and residential occupying intermediate margin positions.
- Construction:Commercial and civil engineering projects specifying pressure-rated systems for high-rise plumbing and site drainage. Building code adoption in Indian metro corridors and Chinese provincial cities drives compliance-grade demand.
- Agriculture:Farmer cooperatives and irrigation departments converting from unlined channels to pressure-rated PVC distribution networks. Water stress in the North China Plain and Deccan Plateau regions accelerates drip and sprinkler system deployment. By volume, agriculture leads. By growth pace, residential is climbing fastest.
- Industrial:Chemical processing and manufacturing facilities requiring corrosion-resistant conveyance for effluent and process fluids. Specification intensity varies with fluid compatibility requirements.
- Residential:Single-family and multi-unit housing driving demand for potable water and DWV (drain-waste-vent) systems. PEX substitution limits hot-water segment penetration.
By volume, agriculture leads. By growth pace, residential is ahead.
Application:
Volume concentration versus margin differentiation defines competitive positioning across fluid-conveyance functions, with sanitation and drainage commanding specification premiums over commodity water supply.
- Water Supply:Potable water distribution networks requiring NSF/ANSI 61 or BIS IS 4985 certification for human consumption safety. Lead-stabilizer phaseouts under REACH and India's tightening heavy-metal limits reshape compounder qualification.
- Sanitation:Sewerage and wastewater conveyance systems prioritizing chemical resistance and joint integrity. Trenchless rehabilitation contracts in Dutch and Australian utilities favor PVC-O biaxially oriented structures for insertion lining. By volume, water supply leads. By growth pace, irrigation shows steepest expansion.
- Drainage:Stormwater and sub-soil drainage applications with lower pressure requirements but high-volume flow capacity. China's GB/T 5836 standards and India's state-level public health engineering specifications create divergent compliance tracks.
- Irrigation:Agricultural water distribution encompassing surface, sprinkler, and drip methodologies. Pressure-compensating emitter integration with PVC lateral lines drives precision agriculture adoption.
By volume, water supply leads. By growth pace, irrigation is ahead.
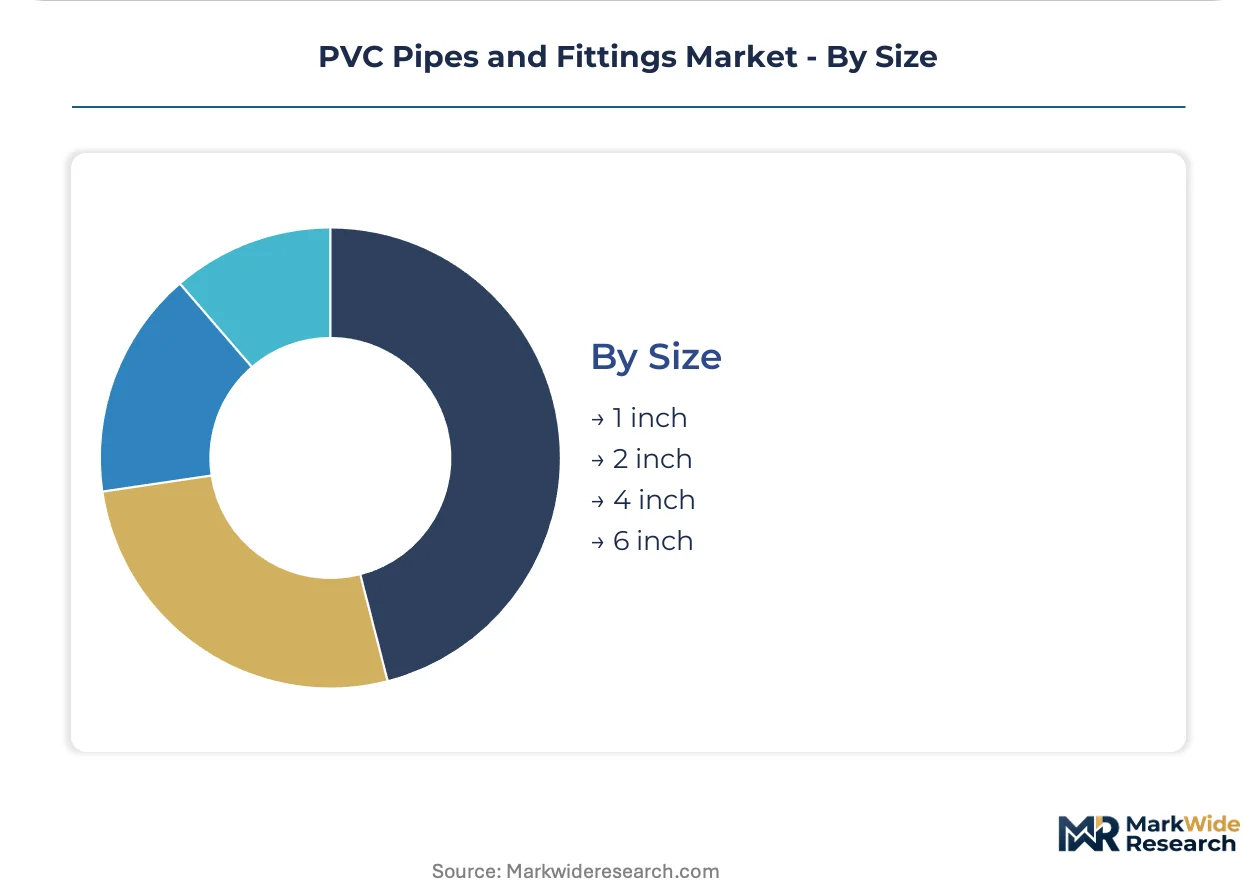
Size:
Customer-type segmentation separates bulk municipal buyers specifying large-diameter trunk mains from retail contractors purchasing smaller trade sizes through wholesale distribution.
- 1 inch:Residential branch lines and small-bore irrigation laterals. High SKU velocity through plumbing merchant channels.
- 2 inch:Commercial building services and medium-scale agricultural distribution. Balances handling convenience with flow capacity.
- 4 inch:Municipal service connections and mainline irrigation headers. Tender aggregation dominates procurement.
- 6 inch:Large-diameter trunk mains for urban water supply and sewerage networks. India's Jal Jeevan Mission and China's urban drainage expansion concentrate demand for rigid PVC grades in this category. By volume, 6 inch leads. By growth pace, 2 inch is gaining share fastest.
By volume, 6 inch leads. By growth pace, 2 inch is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Jal Jeevan Mission and China's urban drainage expansion are accelerating procurement cycles for large-diameter rigid PVC systems. Regulatory divergence between BIS certification mandates and GB standards compliance is fragmenting supplier qualification tracks across Asia-Pacific.
China
Urban drainage networks in the Yangtze River Delta and Pearl River Delta are absorbing record volumes of PVC-O biaxially oriented pipe. GB/T 5836 standards for drainage applications enforce strict compound specifications that favor domestic compounders with captive chlor-alkali capacity. Shanghai and Guangzhou municipal authorities are bundling smart sensor integration into trenchless rehabilitation contracts.
India
Jal Jeevan Mission tenders are concentrating demand for 6-inch rigid pipes across Maharashtra, Gujarat, and Karnataka state public health engineering departments. BIS IS 4985 certification mandates for potable water applications are disqualifying legacy lead-stabilized formulations. The Delhi-Mumbai Industrial Corridor is emerging as a fabrication cluster for pressure-rated distribution systems serving agricultural cooperatives.
United States
EPA Lead and Copper Rule revisions are extending product qualification cycles for municipal water utilities. California and Texas state procurement boards are specifying NSF/ANSI 61 certified compounds for trunk main replacement programs. JM Eagle's integrated resin-to-pipe production footprint dominates distribution across the Southwest and Southeast construction corridors.
Germany
REACH Annex XVII restrictions on cadmium and lead-based stabilizers are forcing compounders toward calcium-zinc systems with 12-18 month qualification delays. The Ruhr industrial region and Bavarian manufacturing clusters are piloting post-consumer PVC recycling integration to meet EU Green Deal circular-economy mandates. Frankfurt and Hamburg municipal buyers now require ECHA SVHC screening as a pre-qualification gate.
Australia
Water utilities in Sydney and Melbourne are specifying PVC-O structures for trunk mains where fatigue resistance justifies material premiums over ductile iron. Trenchless rehabilitation contracts in the Murray-Darling Basin are driving demand for thin-wall insertion lining systems. Perth's desalination distribution network is expanding with pressure-rated compounds certified to AS/NZS 1477 standards.
PVC Pipes and Fittings Market Competitive Landscape
Player mix skews toward integrated resin-to-pipe manufacturers and regional extrusion specialists with captive chlor-alkali positions. Market structure concentrates procurement leverage among municipal tender aggregators in China and India while fragmenting agricultural distribution through farmer cooperative channels. Two strategic archetypes dominate: scale-driven integrated producers controlling feedstock volatility, and compliance-focused compounders leveraging first-mover positioning in lead-free stabilizer transitions. Competitive moves center on backward integration into ethylene-chlorine value chains and mechanical recycling capacity additions to secure EU circular-economy feedstock advantages.
Among North American integrated producers, JM Eagle and Westlake Corporation exemplify the scale-driven archetype with captive resin production. Orbia anchors Latin American supply through regional extrusion networks. China Lesso Group Holdings Limited occupies the domestic project-tendering tier in Asia-Pacific municipal procurement. The Supreme Industries Limited and Finolex Industries Ltd. represent India-focused compounders navigating BIS certification complexity. Sekisui Chemical Co., Ltd. and Georg Fischer Ltd. sit within the premium compliance tier serving specification-intensive European and Japanese utilities. Aliaxis Holdings SA occupies the pan-regional distribution specialist position across multiple compliance jurisdictions.
| Leading Market Players |
|---|
| Orbia |
| The Supreme Industries Limited |
| JM Eagle |
| Finolex Industries Ltd. |
| Sekisui Chemical Co., Ltd. |
| Aliaxis Holdings SA |
| Georg Fischer Ltd. |
| Westlake Corporation |
| China Lesso Group Holdings Limited |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between resin-integrated manufacturers and municipal procurement boards lock in both chlorine-alkali feedstock access and price visibility across multi-year infrastructure buildouts. These arrangements insulate compounders from ethylene volatility while compressing margins for non-integrated extruders competing on spot resin markets.
Pricing Analysis
Certification level creates the primary spread between municipal-grade and agricultural-grade PVC pipe tiers. Three-tier pricing structure across premium, standard, and economy levels reflects BIS IS 4985 potable water compliance, ASTM D1784 cell-classification, and unlabeled drainage specifications. Cost compression in standard grades is intensifying because China's captive chlor-alkali capacity floods regional export markets. Agricultural cooperatives in India and Indonesia exhibit highest price sensitivity, while Dutch and Australian water utilities accept material premiums for PVC-O biaxially oriented fatigue resistance.
Supply Chain Analysis
Port congestion on Asia-Europe container lanes elevates landed costs for specialty stabilizer additives sourced from German and Swiss compounders. Geographic supply concentrates in China, India, and the United States, with captive chlor-alkali integration in Shandong and Gujarat provinces. Raw material dependencies rest on ethylene from naphtha cracking, chlorine from membrane-cell electrolysis, and calcium-zinc stabilizer packages. Single-source vulnerability sits with European organotin additive suppliers facing REACH Annex XVII phaseout timelines. Distribution runs through project-direct tender platforms for municipal grades and wholesale merchant channels for agricultural trade sizes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PVC pipes and fittings market is accelerating through a regulatory inflection as REACH lead-stabilizer phaseouts and India's BIS heavy-metal limits simultaneously reshape compounder qualification requirements across incompatible jurisdictions.
For Market Incumbents: Compound first-mover positioning in calcium-zinc and organotin formulations to capture municipal procurement gates in Europe and India before qualification timelines extend. Secure backward integration into chlor-alkali capacity or long-term chlorine supply agreements to defend margin position against resin volatility. Channel control through distributor exclusivity agreements in agricultural segments resists price erosion from direct mill procurement platforms. For New Entrants and Emerging Players: Predictive maintenance service bundling with sensor-embedded PVC pipe systems represents an under-served layer where incumbent manufacturers lack software integration capabilities. Target Indonesia's transmigration irrigation programs and India's state-level public health engineering departments for pressure-rated distribution mains. Pursue farmer cooperative aggregation models that bypass wholesale markups through digital tender platform registration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with mechanical recycling integration meeting EU Green Deal circular-economy mandates. Long-term viability across the analysis window favors acquisition targets with captive resin production and multi-jurisdiction certification portfolios. Monitor ECHA SVHC screening adoption rates among German and French municipal buyers as the signal for premium-tier demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali Capacity | Captive chlorine supply insulates JM Eagle and Orbia from feedstock volatility in municipal tender cycles. |
| Calcium-Zinc Stabilizer Transition | REACH Annex XVII compliance opens premium positioning for European compounders serving Dutch water utilities. |
| Mechanical Recycling Integration | Post-consumer PVC feedstock advantages align with EU Green Deal quotas for Frankfurt and Hamburg procurement. |
| Smart Sensor Fusion Development | Embedded leak detection enables predictive maintenance contracts with Sydney and Melbourne water authorities. |
| Digital Tender Platform Registration | Direct mill access through India's e-procurement portals compresses distributor layers for agricultural pipe segments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade databases, SEC 10-K filings, BIS certification registries, and ECHA SVHC screening protocols. Interviews with extrusion plant managers, municipal procurement officers at India's state public health engineering departments, chlorine-alkali procurement leads, and agricultural cooperative distribution heads inform demand-side validation. Bottom-up volume triangulation from tender aggregation platforms and top-down resin consumption analysis from chlor-alkali capacity disclosures cross-verify market sizing.
Segmentation dimensions modeled include product type, end-use application, pressure rating class, and regional regulatory cluster across the projection horizon. CAGRs derive from compound annual growth trajectory analysis applied to tender volume trends, irrigation conversion rates, and urban drainage expansion pipelines. Forecast inputs incorporate ASTM D1784 cell-classification adoption curves and REACH stabilizer phaseout implementation timelines.
Underlying assumptions cover continuous BIS enforcement intensity, stable chlorine-alkali capacity utilization in China, and sustained Jal Jeevan Mission funding allocation, with deviation risk concentrated in regulatory divergence acceleration or feedstock price spike events. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Hot Dip Galvanized Steel Pipe Market
Pipes and Tubes
Copper Tube Market
Pipes and Tubes
Stainless Steel Plumbing Pipes Market
Pipes and Tubes
Germany Acid Proof Lining Market
Pipes and Tubes
Piping System and Piping Spools Market
Pipes and Tubes
Portugal PVC Pipes Market
Pipes and Tubes
India PVC Pipes Market
Pipes and Tubes
Steel Pipe Market
Pipes and Tubes
Perfusion Tubing Systems Market
Pipes and Tubes
Aluminium Tubes for OPC Drum Market
Pipes and Tubes
UAE PVC Pipes Market
Pipes and Tubes
China Industrial Hoses Market
Pipes and Tubes
Stainless Steel Tank Container Market
Pipes and Tubes
Thermoplastic Pipe Market
Pipes and Tubes
Clad Pipe Market
Pipes and Tubes
GRP Pipe Market