
 Industrial Draft Tube Crystallizer Market | 2026-2036
Industrial Draft Tube Crystallizer Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Draft Tube Crystallizer Market Insights
Pharmaceutical active ingredient manufacturing is decoupling from bulk chemical crystallization as purity specifications tighten and batch traceability requirements multiply. Swenson Technology leverages its evaporator-crystallizer integration expertise to anchor large-scale chlor-alkali installations across North American salt belt corridors. GEA Group competes through modular skid-mounted systems that reduce field construction time for European specialty chemical producers. Sulzer differentiates via advanced impeller hydrodynamics that cut energy intensity in mechanical stirring configurations.
An industrial draft tube crystallizer is a suspended-growth crystallization vessel featuring an internal draft tube that directs slurry circulation between a boiling zone and a growth zone, typically operating at suspension densities of 15-40% solids by weight and controlled supersaturation below 1.5°C differential. Its primary purpose is to produce uniformly sized, high-purity crystalline solids from aqueous solutions through regulated heat removal and controlled nucleation suppression. Continuous crystallizers dominate installed base volume in bulk chemical applications where uninterrupted operation offsets higher capital outlay, while batch crystallizers command premium positioning in pharmaceutical end uses where recipe flexibility and cleaning validation protocols justify extended cycle times. Vacuum crystallizers are gaining share in zero-liquid-discharge configurations as thermal integration with upstream evaporators improves overall steam economy.
The US EPA enforces effluent limitation guidelines that mandate solids recovery from process wastewater streams, directly stimulating crystallizer retrofits at existing chemical processing facilities. EU REACH registration requirements and the F-Gas Regulation constrain solvent selection and cooling medium options, pushing equipment suppliers toward ammonia and brine-based cooling architectures. China's MEE implements increasingly stringent discharge permits for high-salinity industrial effluent in key chemical manufacturing belts. Stakeholders must monitor how evolving carbon border adjustment mechanisms and regional green taxonomy classifications alter total cost of ownership calculations for crystallization asset investments.
Market Dynamics
Zero-liquid-discharge mandates from the US EPA and China's MEE are forcing chlor-alkali and fine chemical producers to retrofit existing evaporation trains with closed-loop crystallization circuits, compressing project timelines and elevating equipment specification stringency.
Growth Catalysts
- REACH F-Gas Regulation:European chemical manufacturers are abandoning synthetic refrigerants in favor of ammonia-based cooling loops, stimulating replacement demand for cryogenic-compatible crystallizer vessels and heat exchangers.
- Shandong Province Cluster Densification:Chlor-alkali capacity concentration in China's eastern chemical belt is generating bundled procurement of draft tube crystallizers for simultaneous brine recovery and salt purification.
- Mechanical Vapor Recompression:Integration of MVR compressors with crystallizer bodies is cutting steam consumption by half in North American salt belt operations, accelerating payback periods for continuous configurations.
Market Restraints
- Specialty Alloy Input Volatility:Hastelloy and duplex stainless steel price swings are compressing fabricator margins on corrosion-resistant crystallizer shells and agitator shafts.
- Skilled Welder Scarcity:ASME Section VIII pressure vessel certification requirements are colliding with shrinking qualified welder pools in Midwest US fabrication hubs.
- Membrane Crystallization Substitution:Forward osmosis and membrane distillation systems are capturing niche zero-liquid-discharge applications where energy costs dominate total cost of ownership.
Strategic Opportunities
- Battery Material Supply Chain:Lithium carbonate and nickel sulfate crystallization for cathode precursor manufacturing is opening dedicated equipment lines outside traditional chemical strongholds.
- Carbon Border Adjustment Mechanism:EU importers of embodied-carbon-intensive chemicals face 2026 compliance deadlines, creating retrofit windows for energy-efficient crystallizer upgrades with verified carbon footprints.
- Remote Monitoring Convergence:Vibration sensing and predictive analytics layered atop mechanical draft tube assemblies are enabling performance-based service contracts that displace traditional spare parts revenue models.
Industry Challenges
- Clean-in-Place Validation Burden:Pharmaceutical and food-grade crystallizer deployments face 18-24 month FDA or EMA qualification timelines that stall revenue recognition and tie up engineering resources.
- Legacy DCS Integration Friction:Brownfield chemical plants running 1990s-era distributed control systems require costly protocol bridges to connect modern crystallizer automation packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Draft Tube Crystallizer Market |
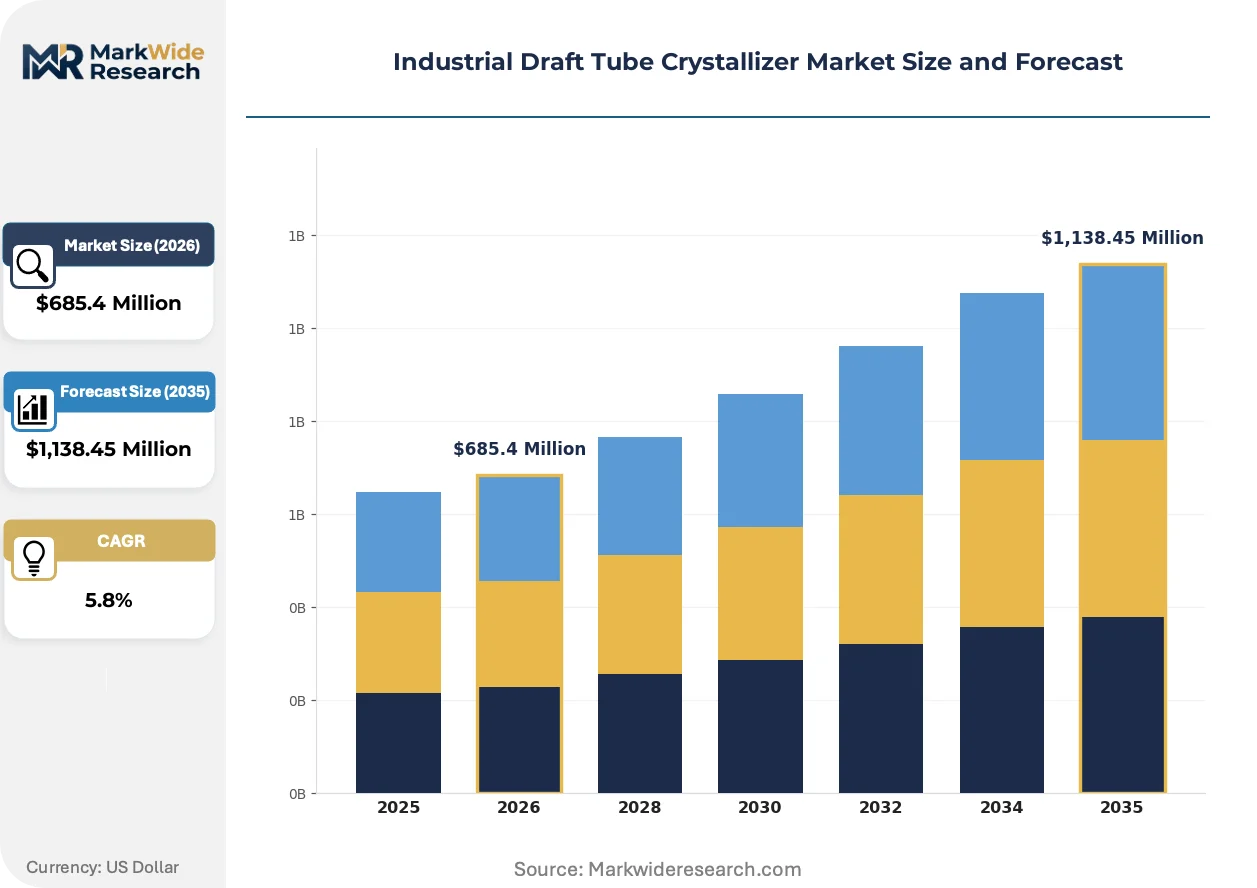
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Crystallizers, Batch Crystallizers, Cooling Crystallizers, Vacuum Crystallizers Technology: Evaporative Cooling, Mechanical Stirring, Anti-solvent Addition, Heat Exchanger End User: Chemicals, Pharmaceuticals, Food & Beverages, Mining Capacity: Small Scale, Medium Scale, Large Scale, Custom Capacity |
| Companies Covered | Swenson Technology, GEA Group, Sulzer, Rosenblad Design Group, Ebner GmbH & Co. KG, Thermal Kinetics, Chem Process Systems, Katsuragi Industry, Boardman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Draft Tube Crystallizer Market Trends and Innovations
Equipment architecture is fragmenting into standardized sub-assemblies that compress field construction schedules and enable geographic sourcing flexibility for project developers facing labor mobility constraints.
Skid-mounted crystallizer trains are modularizing around pre-tested circulation loops, heat exchanger bundles, and solids handling packages that ship as containerized units. Specialty chemical producers in Germany and the Netherlands are specifying these configurations to circumvent unionized construction bottlenecks. The approach is compressing commissioning timelines from months to weeks while shifting quality liability upstream to original equipment fabricators.
China's MEE discharge permit tightening for high-salinity effluent in Jiangsu and Zhejiang provinces is mandating solids recovery rates above 95% for chlor-alkali and dye intermediate manufacturers. This regulatory pressure is accelerating adoption of multiple-effect crystallization sequences with thermal vapor compression. Domestic engineering firms are responding with localized designs that optimize for lower-grade steam availability characteristic of state-owned refinery complexes.
Buyer consolidation among North American chlor-alkali operators is concentrating procurement authority with three major integrated producers who now demand lifecycle performance guarantees rather than equipment-only transactions. Distributor networks that historically stocked spare agitators and seals are being disintermediated as direct OEM service contracts cover predictive maintenance and guaranteed uptime. This shift is most visible across the US Gulf Coast salt dome corridor where operator mergers have halved the number of independent procurement decision-makers since 2019.
Industrial Draft Tube Crystallizer Market Segmentation
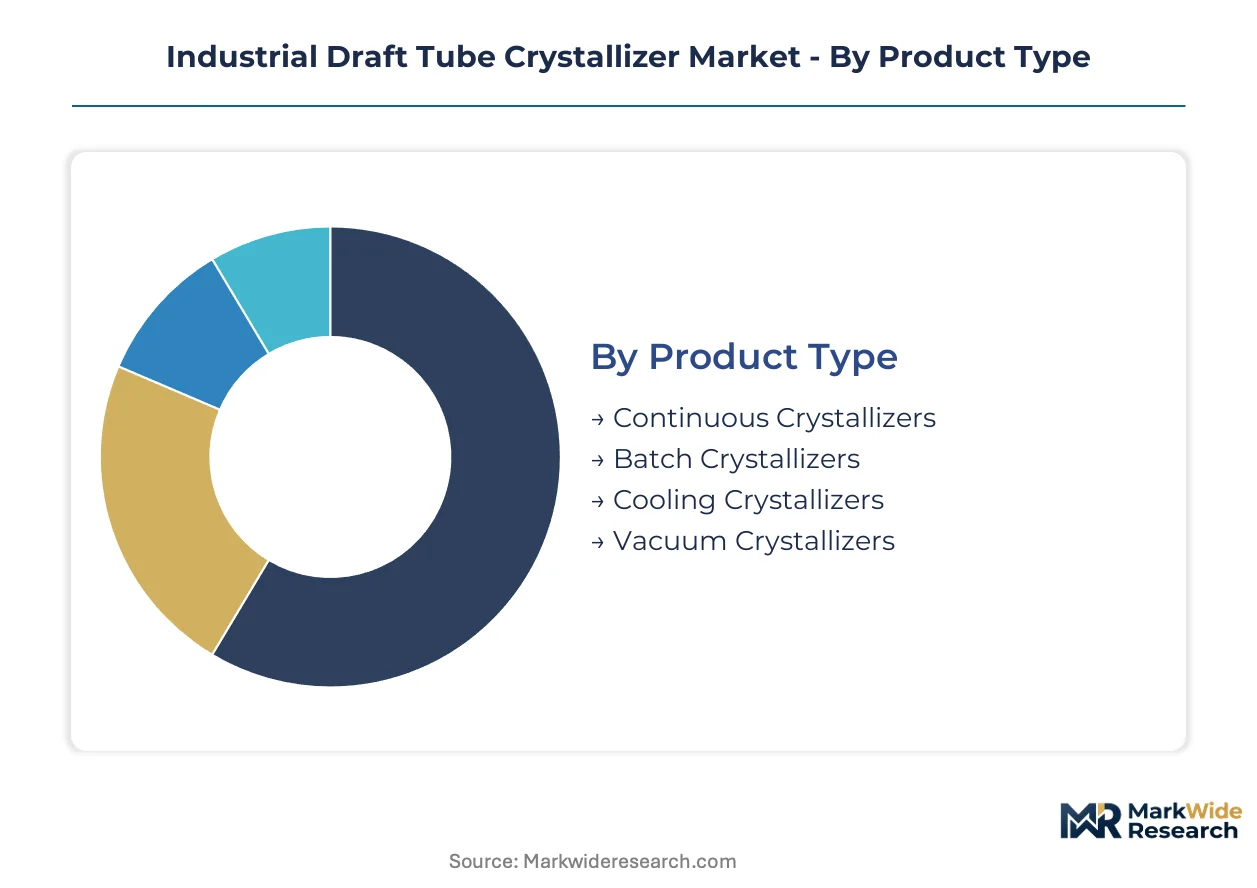
Draft tube crystallizer procurement splits sharply between continuous bulk chemical installations and batch pharmaceutical systems, with technology choices and capacity scaling decisions directly tied to steam economics and cleaning validation burdens. Equipment specification cascades through cooling architecture, end-use purity requirements, and regional labor availability for field construction.
Product Type:
Operating mode determines capital intensity, energy recovery potential, and regulatory compliance architecture across chemical and pharmaceutical value chains.
- Continuous Crystallizers:These systems maintain uninterrupted slurry circulation between boiling and growth zones, achieving suspension densities of 15-40% solids by weight with minimal nucleation disruption. North American chlor-alkali producers across Michigan, Ohio, and Louisiana salt belt corridors specify these configurations for sodium chloride and caustic recovery, driven by EPA effluent guidelines mandating solids capture from process wastewater.
- Batch Crystallizers:Recipe-flexible vessels with discrete heating-cooling cycles enable precise supersaturation control below 1.5°C differential for high-purity active ingredient production. FDA and EMA qualification timelines of 18-24 months concentrate demand among established pharmaceutical manufacturers with dedicated validation engineering teams.
- Cooling Crystallizers:Direct heat removal through jacketed vessels or internal coils serves temperature-sensitive organic compounds.
- Vacuum Crystallizers:Flash evaporation configurations integrate with upstream evaporators for zero-liquid-discharge compliance.
Mature deployment sits with Continuous Crystallizers. Newer deployment is concentrated in Vacuum Crystallizers.
Technology:
Heat and mass transfer mechanisms differentiate energy intensity, maintenance schedules, and compatibility with corrosive process streams.
- Evaporative Cooling:Thermal energy removal through controlled solvent vaporization enables precise supersaturation management in aqueous systems. China's Shandong and Jiangsu province chlor-alkali clusters deploy these systems with multiple-effect sequences and thermal vapor compression, responding to MEE discharge permits demanding solids recovery above 95%.
- Mechanical Stirring:Draft tube-integrated impeller hydrodynamics direct slurry circulation while cutting energy intensity versus external pump-around loops. Advanced impeller geometries from European suppliers serve specialty chemical producers in Germany and the Netherlands seeking modular skid-mounted configurations to circumvent construction bottlenecks.
- Anti-solvent Addition:Precipitation-triggering dilution methods suit temperature-labile pharmaceutical intermediates.
- Heat Exchanger:External circulation loops with plate or shell-and-tube bundles handle high-fouling mother liquors.
Established installations favor Mechanical Stirring. Expanding most quickly are Evaporative Cooling configurations.
End User:
Purity specifications, batch traceability requirements, and cleaning protocols segment equipment architecture and supplier relationships.
- Chemicals:Bulk intermediate and chlor-alkali production demands corrosion-resistant alloys for brine and acid handling. US Gulf Coast integrated producers now require lifecycle performance guarantees rather than equipment-only transactions, consolidating procurement authority among three major operators.
- Pharmaceuticals:Active ingredient manufacturing decouples from bulk chemical crystallization as purity specifications tighten and batch traceability requirements multiply. Clean-in-place validation protocols justify extended cycle times and premium positioning for stainless steel vessels with electropolished surfaces.
- Food & Beverages:Edible salt and citric acid crystallization requires sanitary-grade construction with USDA compliance.
- Mining:Lithium carbonate and nickel sulfate recovery for battery cathode precursors opens dedicated equipment lines outside traditional chemical strongholds.
Volume concentration remains with Chemicals. Steepest expansion trajectory is visible in Mining.
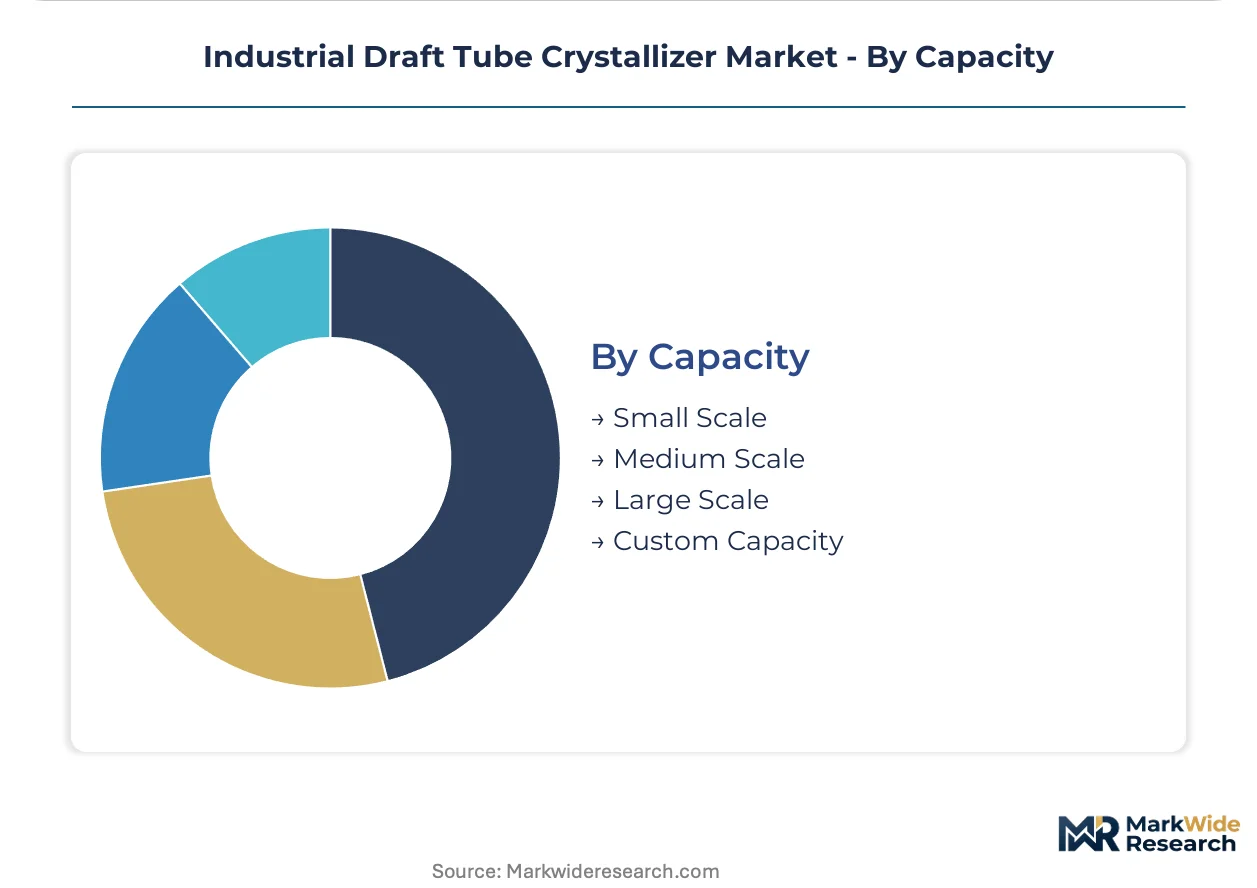
Capacity:
Scale economies and field construction logistics determine modular versus stick-built approaches and geographic sourcing flexibility.
- Large Scale:Integrated chlor-alkali trains and zero-liquid-discharge complexes require field-erected vessels with ASME Section VIII certification. Midwest US fabrication hubs face skilled welder scarcity colliding with pressure vessel quality requirements, compressing project timelines.
- Medium Scale:Specialty chemical and fine chemical batches balance capital efficiency against recipe flexibility. European producers specify containerized skid-mounted trains with pre-tested circulation loops compressing commissioning from months to weeks.
- Small Scale:Pilot-scale and R&D crystallizers serve process development and technology transfer.
- Custom Capacity:Engineering-to-order configurations address unique slurry rheology or space constraints.
Revenue weighting favors Large Scale. Gaining share fastest are Medium Scale modular systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate chlor-alkali capacity expansion, while Germany's chemical parks anchor European crystallizer specification. India's coastal petroleum corridors and the US Gulf Coast salt dome belt each drive distinct procurement patterns shaped by local discharge mandates.
China
Shandong and Jiangsu provinces densify chlor-alkali clusters requiring simultaneous brine recovery and salt purification systems. MEE discharge permits now mandate solids recovery above 95% for high-salinity effluent, compressing project timelines. Domestic engineering firms in Qingdao and Nanjing optimize multiple-effect crystallization sequences for lower-grade steam availability at state-owned refinery complexes.
Germany
Specialty chemical producers in North Rhine-Westphalia specify modular skid-mounted configurations to circumvent unionized construction bottlenecks. REACH F-Gas Regulation accelerates abandonment of synthetic refrigerants, stimulating replacement demand for ammonia-compatible vessels. The Leverkusen and Ludwigshafen chemical parks anchor premium-tier procurement with lifecycle performance guarantees.
United States
EPA effluent limitation guidelines mandate solids recovery from process wastewater, directly stimulating crystallizer retrofits across Michigan, Ohio, and Louisiana salt belt corridors. Buyer consolidation among Gulf Coast chlor-alkali operators concentrates procurement authority with three major integrated producers. Midwest fabrication hubs face skilled welder scarcity colliding with ASME Section VIII pressure vessel certification requirements.
India
Gujarat and Maharashtra coastal zones expand chlor-alkali and dye intermediate manufacturing under tightening state pollution control board discharge norms. Central Pollution Control Board mandates for zero-liquid-discharge compliance accelerate adoption of thermal vapor compression sequences. The Mundra and Dahej petroleum corridors attract bundled crystallizer procurement for caustic recovery and salt purification.
Industrial Draft Tube Crystallizer Market Competitive Landscape
Top-tier vendors anchor integrated evaporator-crystallizer systems for chlor-alkali majors, while regional fabricators compete on skid-mounted specialty chemical configurations. The market structure consolidates around three strategic archetypes: full-system integrators with thermal process expertise, modular equipment specialists compressing field construction, and component suppliers advancing hydrodynamic efficiency. Dominant competitive moves include vertical integration into MVR compressor pairing and predictive maintenance service contracts displacing traditional spare parts revenue.
Among European-headquartered full-system integrators, GEA Group and Sulzer occupy positions spanning modular architecture and advanced impeller engineering respectively. Swenson Technology exemplifies the North American integrated-systems archetype with evaporator-crystallizer bundling expertise. These three entities represent distinct competitive vectors: modular standardization, hydrodynamic efficiency, and thermal process integration.
| Leading Market Players |
|---|
| Swenson Technology |
| GEA Group |
| Sulzer |
| Rosenblad Design Group |
| Ebner GmbH & Co. KG |
| Thermal Kinetics |
| Chem Process Systems |
| Katsuragi Industry |
| Boardman |
| Others |
Pricing and Supply Chain Analysis
Buyer consolidation among three major integrated chlor-alkali producers across the US Gulf Coast salt dome corridor is compressing procurement timelines and demanding lifecycle performance guarantees, forcing fabricators toward modular skid-mounted architectures that shift pricing power upstream to original equipment manufacturers with captive thermal process expertise.
Pricing Analysis
Short lead-time premiums command significant markup over standard delivery schedules as Midwest US fabrication hubs face skilled welder scarcity colliding with ASME Section VIII pressure vessel certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical vessels from bulk chemical configurations and refurbished legacy units. Cost compression in standard-grade continuous crystallizers is intensifying because membrane crystallization substitution threatens niche zero-liquid-discharge applications. Specialty chemical producers in Germany and the Netherlands show least price sensitivity, prioritizing modular configurations that circumvent unionized construction bottlenecks.
Supply Chain Analysis
Refurbishment flows for agitator shafts and heat exchanger bundles are extending asset lifecycles and creating secondary parts markets that compete with OEM spare parts revenue models. Manufacturing concentration rests on China for Hastelloy and duplex stainless steel processing, Germany for precision impeller engineering, and the US for large-scale pressure vessel fabrication. Single-source vulnerability in specialty alloy inputs exposes fabricators to margin compression during nickel price volatility. Distribution runs through direct OEM service contracts that displace traditional distributor networks stocking spare agitators and seals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial draft tube crystallizer market is becoming a vertical-integration race as equipment suppliers pair with MVR compressor manufacturers and predictive analytics platforms to capture recurring service revenue streams beyond equipment-only transactions.
For Market Incumbents:Hedge against membrane crystallization substitution by deepening captive supply of thermal vapor compression technology and securing exclusive aftermarket service contracts with buyer-consolidated chlor-alkali operators across the US salt belt. Lock in multi-year performance guarantees with Shandong and Jiangsu province cluster expansions before domestic Chinese engineering firms achieve full localization of multiple-effect crystallization sequences.
For New Entrants and Emerging Players:Begin with battery material supply chain white space, specifically lithium carbonate and nickel sulfate crystallization for cathode precursor manufacturing outside traditional chemical strongholds. Target medium-scale modular skid-mounted configurations for European specialty chemical producers seeking to circumvent construction bottlenecks, leveraging containerized pre-tested circulation loops that compress commissioning timelines.
For Investors and Strategic Acquirers:The window for entry favors predictive maintenance service platforms with vibration sensing and analytics capabilities layered atop mechanical draft tube assemblies. Over the medium-term horizon, acquire engineering firms with localized Chinese designs optimized for lower-grade steam availability at state-owned refinery complexes. Monitor EU Carbon Border Adjustment Mechanism compliance deadlines as inflection indicators for energy-efficient crystallizer retrofit demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MVR Compressor Manufacturing | Captures thermal integration value that cuts steam consumption by half in North American salt belt operations. |
| Predictive Maintenance Service Platform Launch | Enables performance-based contracts displacing traditional spare parts revenue with Gulf Coast chlor-alkali operators. |
| Modular Skid-Mounted Configuration Standardization | Compresses field construction schedules for European specialty chemical producers facing unionized labor constraints. |
| Zero-Liquid-Discharge Compliance Retrofit Program | Addresses EPA and MEE mandates driving crystallizer upgrades across Michigan, Ohio, and Louisiana corridors. |
| Battery Material Crystallization Line Expansion | Opens dedicated equipment capacity for lithium carbonate and nickel sulfate cathode precursor manufacturing. |
Research Methodology
Document review covered customs and trade databases, ACC and Cefic industry reports, and SEC filings from publicly traded chemical processing firms, complemented by interviews with plant engineers at chlor-alkali facilities, procurement leads at specialty chemical manufacturers, aftermarket service heads at OEMs, and technical R&D directors at crystallizer fabricators. Bottom-up sizing triangulated equipment shipment volumes against top-down validation from regional capacity expansion announcements and regulatory mandate implementation timelines.
Cross-referencing historical installation patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include operating mode, cooling architecture, end-use purity tier, and regional steam availability grade. CAGRs were derived from regression analysis of disclosed capital expenditure cycles and regulatory compliance deadline clustering. Forecast inputs incorporated MEE discharge permit tightening schedules and EU F-Gas Regulation phase-out timelines.
Alloy price volatility, skilled welder availability fluctuations, and membrane technology cost curves are the dominant revision risks that could alter equipment specification trajectories. Practitioners should monitor specialty steel input markets and zero-liquid-discharge regulatory enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Glass Reinforced Epoxy (GRE) Pipes Market
Pipes and Tubes
Acid Resistant Pipe Market
Pipes and Tubes
Global Cured-In-Place Pipe Market
Pipes and Tubes
Steel Roll-On Tube Market
Pipes and Tubes
Drum Funnel Market
Pipes and Tubes
Reinforced Thermoplastic Pipes Market
Pipes and Tubes
Europe Line Pipe Market
Pipes and Tubes
Saudi Arabia PVC Pipes Market
Pipes and Tubes
Carbon Steel Pipe Fittings Market
Pipes and Tubes
FRP Pipe Market
Pipes and Tubes
Copper Tube Market
Pipes and Tubes
Multiflex Tubes Market
Pipes and Tubes
Steel Pipe Market
Pipes and Tubes
Global Titanium Tube Market
Pipes and Tubes
Global Lance Tubes Market
Pipes and Tubes
Europe Pipe Market