
 Bio-Based Construction Polymers Market | 2026-2036
Bio-Based Construction Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Construction Polymers Market Analysis
Modular pre-fabricated panel systems with integrated bio-based insulation is hardening as the default procurement format for mid-rise residential developers. BASF SE anchors European supply through captive biopolymer precursor capacity at its Ludwigshafen complex. NatureWorks LLC dominates North American feedstock integration with corn-derived lactic acid chains. SK Chemicals positions aggressively in Asian markets via specialized copolyester lines for extruded construction films.
Bio-based construction polymers are macromolecular materials derived from renewable biomass feedstocks such as corn starch, sugarcane, or cellulose, formulated to achieve mechanical properties comparable to petroleum-derived counterparts including tensile strengths exceeding 30 MPa for structural-grade polylactic acid. These materials primarily serve to reduce embodied carbon in built environments while maintaining code-compliant thermal, acoustic, and load-bearing performance. Polyurethane formulations for insulation capture the deepest margin pools due to stringent energy-efficiency retrofit mandates across mature building stocks. Polylactic acid represents the fastest-expanding product category as injection-molding compatibility improves for non-structural architectural components. Polyethylene maintains volume leadership in moisture-barrier membranes where cost parity with conventional grades has already been achieved.
EU Green Deal renovation-wave targets and REACH chemical safety registrations jointly compel reformulation of conventional construction adhesives and sealants toward bio-derived alternatives. EMA construction-product standards and national building codes in Germany, France, and the Netherlands now incorporate biogenic carbon accounting for public procurement eligibility. EPA bio-preferred program specifications and state-level low-carbon material mandates in California and New York extend parallel pressure in North America. Stakeholders must monitor feedstock competition from food-system demands and packaging-sector offtake agreements that could constrain construction-grade biopolymer availability regardless of policy support intensity.
Market Dynamics
EU Green Deal renovation mandates are compressing specification timelines for bio-based insulation systems across mid-rise residential construction, forcing rapid reformulation of conventional petroleum-derived materials before 2030 compliance deadlines.
Growth Catalysts
- REACH chemical safety registrations:ECHA's tightening substance restrictions compel adhesive and sealant manufacturers toward bio-derived feedstocks to maintain construction-product market access across Germany and France.
- Public infrastructure tenders:Nordic procurement authorities now embed certified biopolymer content thresholds into road, bridge, and municipal building contracts, concentrating polylactic acid demand in Sweden and Denmark.
- Retrofit mandates:Energy-efficiency renovation targets for Germany's existing building stock deepen specification pull for bio-based polyurethane insulation in envelope applications.
Market Restraints
- Feedstock competition:Corn starch and sugarcane offtake agreements from food-system and packaging-sector buyers constrain construction-grade biopolymer availability regardless of policy support intensity.
- Technical performance gaps:Bio-based polyethylene moisture-barrier membranes face load-bearing limitations in below-grade applications where conventional grades dominate.
- Cost structure rigidity:Lactic acid purification costs for injection-molding-grade polylactic acid maintain price premiums above petroleum-derived ABS and polypropylene in non-structural architectural components.
Strategic Opportunities
- California low-carbon material mandates:State-level building code amendments create procurement pull for biogenic carbon-accounted polymers in public school and affordable housing construction.
- 3D printing convergence:Fused deposition modeling compatibility for polylactic acid filaments opens custom fabrication channels for architectural facade elements and interior partition systems.
- Modular panel distribution:Pre-fabricated envelope systems with integrated bio-based insulation bypass traditional distributor channels, enabling direct manufacturer-to-developer contracting in Netherlands mid-rise projects.
Industry Challenges
- Biogenic carbon certification timelines:Third-party verification protocols for EMA construction-product standards impose 12-18 month approval windows that delay project qualification.
- Polymer processing skill scarcity:Injection-molding technicians trained on petroleum-derived resins require retraining for bio-based material shrinkage and cooling-rate behaviors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Construction Polymers Market |
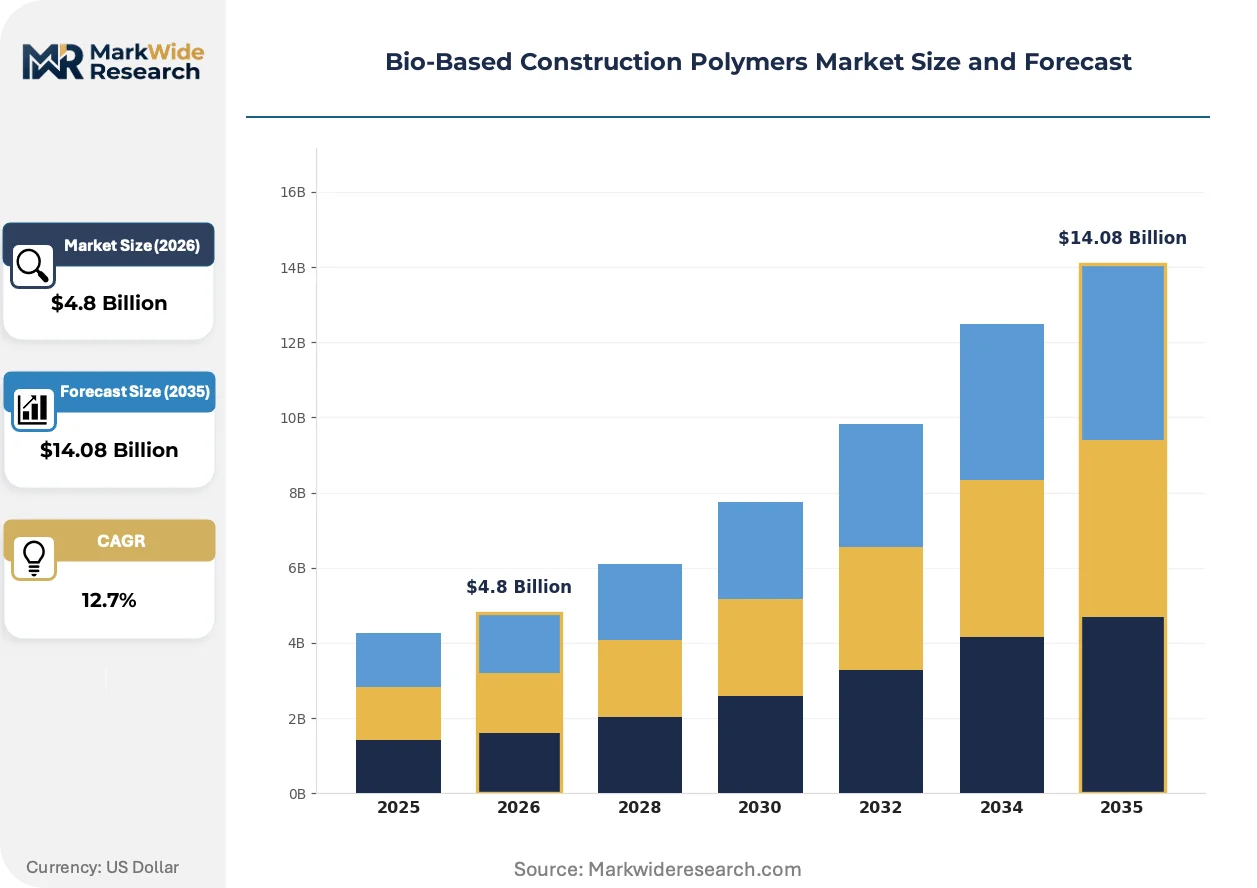
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $14.08 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyurethane, Polylactic Acid Application: Insulation, Flooring, Roofing, Structural Components End User: Residential, Commercial, Industrial, Infrastructure Technology: Biopolymer Synthesis, Composite Materials, Extrusion, Injection Molding |
| Companies Covered | Evonik Industries, BASF SE, DuPont, NatureWorks LLC, SK Chemicals, Mitsubishi Gas Chemical, Toyobo, Teijin Limited, Avient Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Construction Polymers Market Emerging Trajectories
Active reformulation of structural-grade biopolymers is compressing performance gaps with conventional materials while regulatory carbon-accounting frameworks reshape procurement qualification criteria across public and private construction.
Second-generation polylactic acid copolymers with enhanced thermal stability above 60°C are integrating into load-bearing architectural components previously reserved for petroleum-derived engineering plastics. German residential developers specify these grades for window frame profiles and door threshold systems. The material is integrating into specification databases of major European building merchants, compressing switching costs for mid-volume contractors.
EMA construction-product standards now incorporate mandatory biogenic carbon accounting for public procurement eligibility in France, Germany, and the Netherlands. Industrial consequence: adhesive and sealant formulators must document renewable feedstock percentages through mass-balance certification. Insulation-grade bio-based polyurethanes face the steepest compliance burden, with Dutch building inspectors rejecting conventional petroleum-derived alternatives for social housing retrofits.
Buyer concentration among mid-rise residential developers is consolidating specification authority away from general contractors toward in-house procurement teams with dedicated sustainability mandates. Direct manufacturer contracting replaces traditional distributor relationships for envelope systems in Netherlands and Denmark projects. France's largest residential REITs now maintain approved bio-polymer vendor lists with pre-negotiated carbon-intensity thresholds.
Bio-Based Construction Polymers Market Segmentation
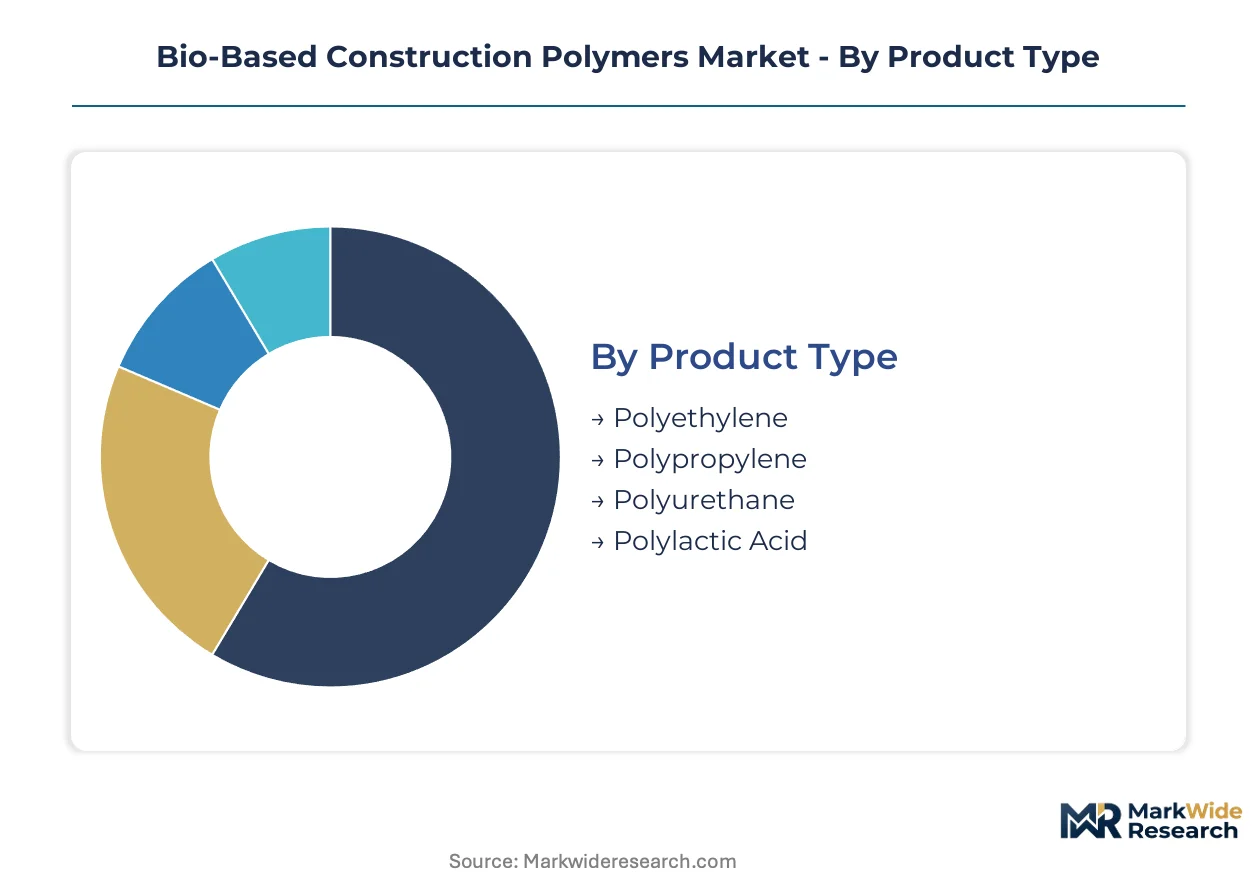
Bio-based construction polymers exhibit divergent performance profiles across product chemistry, application load requirements, and processing technology. Segmentation reveals where supply constraints intersect with specification pull from EU renovation mandates and North American low-carbon building codes.
Product Type:
Manufacturing capacity clusters around precursor availability and polymerization complexity, with integrated producers capturing margin from captive feedstock supply.
- Polyurethane:Derived from bio-polyols reacting with isocyanates, this chemistry achieves thermal conductivity values below 0.025 W/m·K for rigid foam insulation. German and Dutch social housing retrofits specify bio-based polyurethane for envelope systems under tightened EU Green Deal energy-efficiency targets. Supply concentrates at Ludwigshafen and Rotterdam chemical complexes with backward integration into castor oil and soybean oil feedstocks.
- Polylactic Acid:Corn starch fermentation yields lactic acid monomers polymerized to crystalline grades with tensile strength exceeding 50 MPa. Nordic infrastructure tenders in Sweden and Denmark mandate certified biopolymer content thresholds, concentrating specification pull for injection-molding and extrusion grades. Purification costs sustain price premiums above petroleum-derived ABS in non-structural architectural components.
- Polyethylene:Bio-ethylene from sugarcane ethanol dehydration polymerizes to moisture-barrier membranes with cost parity achieved against conventional grades.
- Polypropylene:Bio-propylene routes remain technically immature; construction applications concentrate in non-load-bearing geotextiles and temporary protection films.
Polyurethane absorbs the bulk of installed capacity; polylactic acid is expanding most quickly.
Application:
Performance requirements and code compliance burdens create tiered margin structures across building envelope and interior systems.
- Insulation:Rigid foam boards and spray-applied systems for thermal envelope performance dominate volume offtake. Bio-based polyurethane captures specification in German mid-rise residential and Dutch social housing retrofits where energy-efficiency mandates compress timelines. REACH chemical safety registrations compel adhesive and sealant reformulation toward bio-derived alternatives.
- Structural Components:Load-bearing applications demand flexural modulus above 2 GPa and creep resistance under sustained mechanical stress. Second-generation polylactic acid copolymers with thermal stability above 60°C integrate into window frame profiles and door thresholds previously reserved for petroleum-derived engineering plastics.
- Flooring:Bio-based polyurethane elastomers serve resilient flooring systems in healthcare and education construction.
- Roofing:Membrane and waterproofing applications favor bio-polyethylene for cost-sensitive single-ply systems.
Insulation commands the deepest margin pools; structural components show the steepest specification climb.
End User:
Procurement authority concentration and sustainability mandates differentiate demand intensity across building typologies.
- Residential:Mid-rise developers in the Netherlands and Denmark consolidate specification authority through in-house procurement teams with dedicated carbon-intensity thresholds. Modular pre-fabricated panel systems with integrated bio-based insulation bypass traditional distributor channels for direct manufacturer contracting.
- Infrastructure:Nordic public authorities embed certified biopolymer content into road, bridge, and municipal building contracts. EMA construction-product standards and national building codes in Germany, France, and the Netherlands incorporate biogenic carbon accounting for procurement eligibility.
- Commercial:Office and retail construction shows fragmented adoption pending total-cost-of-ownership validation.
- Industrial:Warehouse and logistics facilities prioritize cost minimization over biogenic carbon credentials.
Residential channels concentrate volume commitment; infrastructure tenders drive fastest qualification expansion.
Technology:
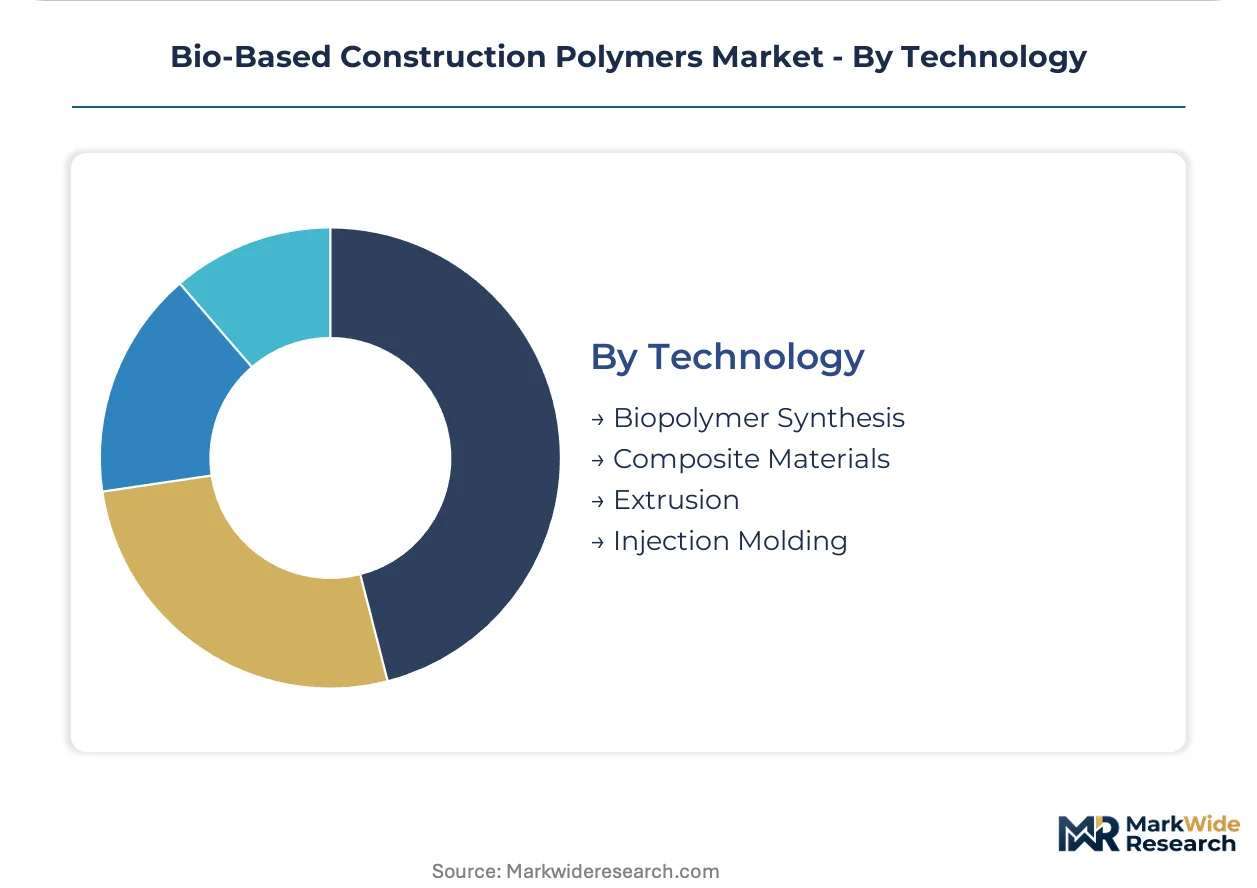
Processing method determines material performance, part complexity, and production economics for bio-based feedstocks.
- Injection Molding:High-pressure processing of polylactic acid and bio-polypropylene enables complex geometries for architectural hardware and interior components. Shrinkage and cooling-rate behaviors differ from petroleum-derived resins, requiring technician retraining. California low-carbon material mandates in public school construction create procurement pull for injection-molded biopolymer fixtures.
- Extrusion:Continuous profile production serves films, sheets, and insulation boards. SK Chemicals positions in Asian markets via specialized copolyester extrusion lines for construction films.
- Biopolymer Synthesis:Fermentation and catalytic polymerization routes from corn starch, sugarcane, and cellulose establish feedstock-to-polymer value capture.
- Composite Materials:Natural fiber reinforcement with bio-based matrices targets semi-structural applications with reduced density requirements.
Injection molding captures the highest value-added output; extrusion handles the greatest throughput volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany and the United States while consumption concentrates in Nordic renovation markets and Dutch social housing retrofits. This geographic mismatch creates supply chain tension as Asian feedstock processors compete for corn starch and sugarcane offtake. Regulatory carbon-accounting frameworks in the EU and North America are reshaping trade flows for construction-grade biopolymers.
Germany
Ludwigshafen hosts the largest integrated bio-polyol production complex serving rigid foam insulation demand. EU Green Deal renovation-wave mandates compel specification of bio-based polyurethane for envelope systems in existing building retrofits. BASF SE anchors supply through captive castor oil and soybean oil feedstock processing at this Rhine chemical cluster.
United States
Midwest corn belt fermentation capacity supplies lactic acid chains for polylactic acid production concentrated in Nebraska and Minnesota. EPA bio-preferred program specifications drive procurement in California public school construction and New York affordable housing projects. NatureWorks LLC dominates North American feedstock integration with corn-derived supply chains.
Netherlands
Rotterdam chemical complexes process bio-ethylene for moisture-barrier membranes with direct distribution to modular panel manufacturers. EMA construction-product standards mandate biogenic carbon accounting for public procurement eligibility in social housing retrofits. Dutch building inspectors now reject conventional petroleum-derived insulation alternatives for mid-rise residential projects.
Sweden
Public infrastructure tenders embed certified biopolymer content thresholds into road, bridge, and municipal building contracts. National building codes incorporate renewable material quotas that concentrate polylactic acid demand for injection-molded architectural components. Stockholm-based procurement authorities enforce 12-18 month third-party verification protocols for EMA compliance.
France
Residential REITs maintain approved bio-polymer vendor lists with pre-negotiated carbon-intensity thresholds for mid-rise development. REACH chemical safety registrations compel adhesive and sealant reformulation toward bio-derived feedstocks to maintain construction-product market access. Paris-region building merchants integrate second-generation polylactic acid grades into specification databases for window frame profiles.
Bio-Based Construction Polymers Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across feedstock integration, polymerization technology, and end-use application expertise. Market structure tilts toward consolidation at the precursor level where backward integration into agricultural supply chains creates defensive moats. Three archetypes dominate: integrated chemical majors with captive biopolymer capacity, specialized fermentation-to-polymer pure-plays, and Asian copolyester specialists targeting extruded construction films. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure offtake agreements ahead of 2030 compliance deadlines.
Among integrated chemical majors, BASF SE and Evonik Industries exemplify the diversified conglomerate archetype with multi-product chemical complexes spanning conventional and bio-based output. NatureWorks LLC occupies a position as the North American pure-play specialist with dedicated corn-derived lactic acid supply chains. SK Chemicals represents the Asian specialist model with focused copolyester lines for regional construction film markets. These three anchors illustrate how geographic feedstock advantages and regulatory proximity shape competitive positioning without requiring specific product or financial claims.
| Leading Market Players |
|---|
| Evonik Industries |
| BASF SE |
| DuPont |
| NatureWorks LLC |
| SK Chemicals |
| Mitsubishi Gas Chemical |
| Toyobo |
| Teijin Limited |
| Avient Corporation |
| Others |
Supply Flow & Price Mechanics
Mid-rise residential developers in the Netherlands and Denmark consolidate procurement authority through in-house sustainability teams, forcing contract-based long-term offtake agreements for bio-based polyurethane insulation. This buyer concentration tilts pricing power toward integrated chemical majors with captive feedstock supply.
Pricing Analysis
Margin tightening in injection-molding-grade polylactic acid reflects lactic acid purification cost premiums above petroleum-derived ABS. Three-tier pricing structure across certified biogenic carbon, standard mass-balance, and uncertified grades separates procurement eligibility for EU public tenders from private commercial projects. Cost-down pressure on bio-based polyethylene moisture barriers accelerates because sugarcane ethanol feedstock competition from packaging buyers constrains volume availability. Infrastructure contractors in Sweden show least price sensitivity due to mandated biopolymer content thresholds, while industrial warehouse developers remain most cost-focused.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Ludwigshafen anchor hub-and-spoke patterns for bio-polyol and polylactic acid delivery to modular panel manufacturers. Supply concentrates in Germany, the United States, and the Netherlands where corn starch fermentation and castor oil processing clusters feed polymerization capacity. Raw material dependencies on corn starch, sugarcane ethanol, and castor oil create vulnerability to agricultural commodity volatility and food-system offtake competition. Single-source vulnerability in lactic acid purification technology constrains construction-grade biopolymer availability regardless of policy support intensity. Distribution runs through direct manufacturer-to-developer contracting for pre-fabricated envelope systems, bypassing traditional building merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
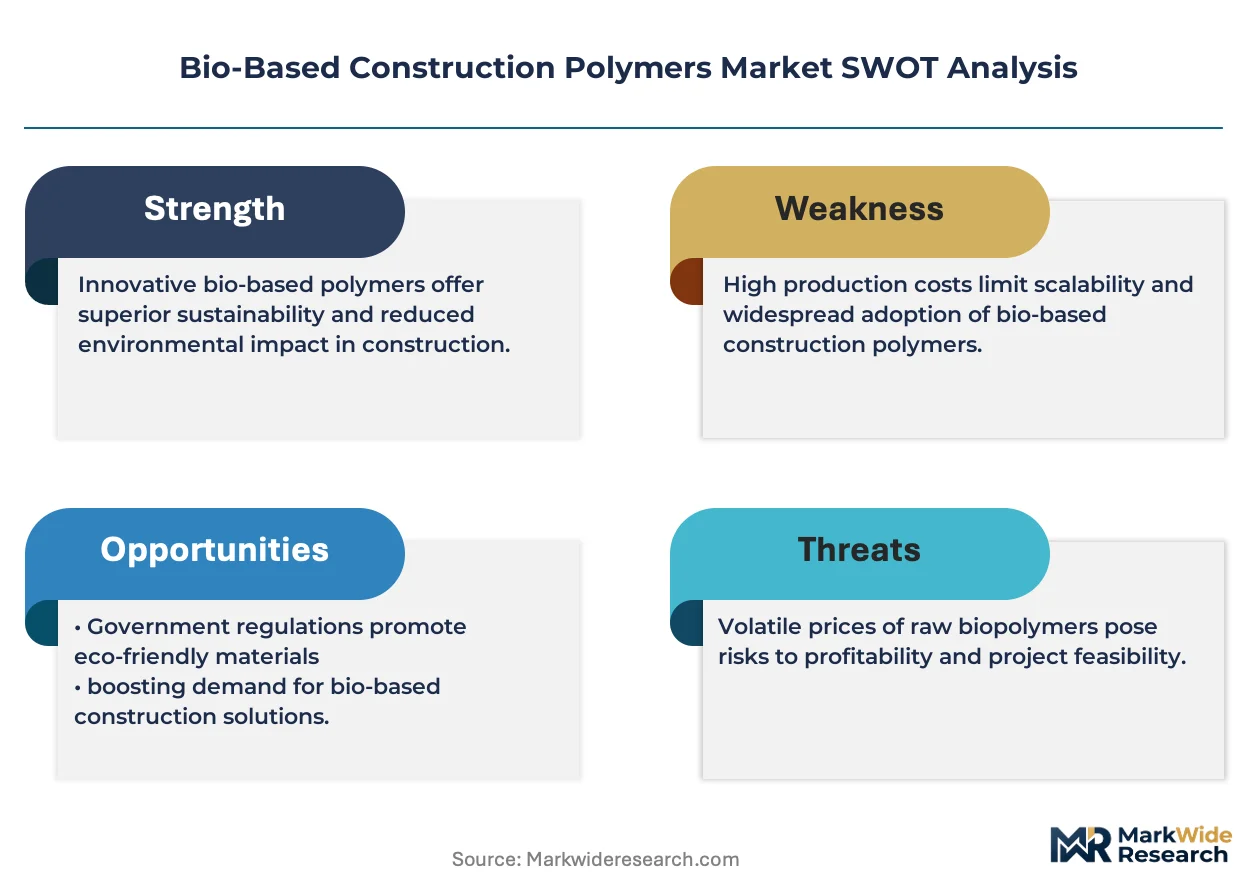
Bio-based construction polymer supply remains constrained by fermentation capacity bottlenecks and agricultural feedstock competition, propping price premiums for certified grades. This supply scarcity favors incumbents with backward integration and creates selective entry windows for technology-differentiated challengers.
For Market Incumbents: Deploy captive castor oil and soybean oil processing capacity to defend margin position against commodity feedstock volatility. Lock in multi-year offtake agreements with Nordic infrastructure authorities and Dutch social housing developers before 2030 compliance deadlines compress specification timelines. Reinforce technical service capabilities to address polymer processing skill scarcity among injection-molding technicians trained on petroleum-derived resins. For New Entrants and Emerging Players: Second-generation polylactic acid copolymers with thermal stability above 60°C offer a technology-first wedge into load-bearing architectural components previously reserved for petroleum-derived engineering plastics. Target California public school construction and New York affordable housing projects where state-level low-carbon material mandates create procurement pull absent federal standardization. Pursue direct distribution partnerships with modular panel manufacturers to bypass established building merchant relationships. For Investors and Strategic Acquirers: The window for entry favors fermentation-to-polymer pure-plays with demonstrated EMA construction-product standard certifications and existing Nordic infrastructure tender qualifications. Long-term viability hinges on securing agricultural feedstock supply agreements insulated from food-system competition. Watch for biogenic carbon certification timeline compression as the inflection signal indicating regulatory acceleration beyond current 12-18 month approval windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Feedstocks | Captive corn starch and castor oil supply insulates BASF and NatureWorks from packaging-sector offtake competition. |
| EMA Construction-Product Standard Certification | Mass-balance documentation enables procurement eligibility for Dutch social housing retrofits and German renovation mandates. |
| Direct Manufacturer-to-Developer Contracting | Pre-fabricated panel distribution bypasses traditional building merchant channels in Netherlands mid-rise projects. |
| Second-Generation Copolymer R&D Investment | Thermal stability above 60°C opens window frame and door threshold applications previously blocked by performance gaps. |
| Long-Term Infrastructure Tender Positioning | Swedish and Danish public procurement authorities embed multi-year biopolymer content thresholds into municipal contracts. |
Methodological Framework
Independent corroboration across primary interviews with plant managers at integrated chemical complexes, procurement leads at mid-rise residential developers, distribution channel partners in building merchant networks, and technical R&D directors in adhesive formulation, plus secondary validation through customs and trade data, SEC 10-K filings, ECHA REACH registration databases, and national building code amendments, underwrites the qualitative findings. Bottom-up volume estimates from polymerization capacity and feedstock availability triangulate against top-down demand projections from renovation mandate targets and public tender pipelines.
Rate-of-change decomposition across the analysis window segments expansion by product chemistry, application load requirement, processing technology, and end-user procurement authority concentration. CAGRs derive from installed capacity utilization trajectories, feedstock cost curve shifts, and regulatory compliance deadline clustering. Modeled inputs include EU Green Deal renovation-wave target penetration rates and California low-carbon material mandate adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under agricultural commodity price spikes and biogenic carbon certification protocol delays. Outputs reflect documented assumptions around fermentation capacity expansion timelines and food-system feedstock competition intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
South America Engineering Plastics Market
Polymers & Resins
Global UV Curable Resins and Formulated Products Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
Casting Resin Market
Polymers & Resins
Polydicyclopentadiene (Pdcpd) Market
Polymers & Resins
Linear Low Density Polyethylene Lldpe Market
Polymers & Resins
Polyamide 11 & 12 Market
Polymers & Resins
Polylysine Market
Polymers & Resins
Southeast Asia Modified Polypropylene Market
Polymers & Resins
Polymer Antioxidants Market
Polymers & Resins
Acrylic Styrene Acrylonitrile Resin Market
Polymers & Resins
Polyol Esters Market
Polymers & Resins
Copolyesters Market
Polymers & Resins
Macroporous Strong Acid Cation Exchange Resin Market
Polymers & Resins
Amorphous Polyethylene Terephthalate (APET) Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market