
 Glass and Metal Cleaner Market | 2026-2036
Glass and Metal Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Glass and Metal Cleaner Market Foresight
Automotive Tier-1 supplier demand is shifting toward residue-free formulations compatible with coated glass and anodized aluminum surfaces. SC Johnson Professional leverages its institutional channel dominance to sustain contract volumes with fleet maintenance operators across North America. Reckitt Benckiser Group plc anchors its position through retail brand strength in consumer electronics cleaning. Ecolab Inc. differentiates via on-site dispensing systems that reduce packaging waste for food and beverage facilities.
Glass and metal cleaners are aqueous or solvent-based formulations containing surfactants, chelating agents, and pH modifiers designed to remove oils, fingerprints, and oxidation without etching substrates; typical specifications require streak-free evaporation below 50°C and compatibility with tempered glass and stainless steel 304/316 grades. Spray formats dominate commercial buildings due to controlled application economics, while wipes capture traction in electronics manufacturing where particulate control is critical. The hospitality segment favors concentrated liquids in refillable containers to minimize storage footprint and comply with sustainability procurement protocols.
EPA Safer Choice standards and OSHA worker exposure limits shape permissible ingredient profiles in the United States, while REACH registration requirements in Europe mandate full toxicological dossiers for surfactant chemistries. The EU F-Gas Regulation indirectly pressures aerosol propellant selections, pushing manufacturers toward compressed air or mechanical trigger alternatives. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as these compounds historically provided anti-fog performance in premium formulations but face accelerating regulatory phase-outs that will require functional replacements within current product pipelines.
Market Dynamics
EV battery manufacturing is forcing reformulation cycles as precision cleaning requirements for aluminum housings and coated display glass outpace legacy solvent capabilities. Tier-1 automotive suppliers now specify residue-free performance at sub-50°C evaporation temperatures, compressing product development timelines across the supply base.
Growth Catalysts
- REACH compliance deadlines:European ECHA registration requirements for surfactant chemistries are accelerating biodegradable formulation adoption among exporters serving EU manufacturing clusters.
- EV battery housing demand:Automotive Tier-1 suppliers require precision-cleaned aluminum enclosures for thermal management systems, creating specification pull for low-residue aqueous systems.
- Compressed air propellants:The EU F-Gas Regulation is displacing hydrofluorocarbon aerosol propellants, opening market share for mechanical trigger and compressed gas delivery formats.
Market Restraints
- Isopropyl alcohol price volatility:Solvent-based formulations face margin compression from petrochemical feedstock fluctuations and energy-intensive distillation requirements.
- Chinese surfactant concentration:Intermediate chemical supply for biodegradable cleaners concentrates in Shandong and Jiangsu provinces, exposing formulators to single-origin disruption risk.
- PFAS functional gap:Accelerating regulatory phase-outs of per- and polyfluoroalkyl substances remove anti-fog performance from premium formulations without mature replacements.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and display fabrication create first-mover advantage for cleaners qualified to BIS and CDSCO standards.
- On-site dispensing systems:Food and beverage facilities are adopting concentrated bulk delivery with automated dilution, reducing packaging waste and logistics cost.
- Electronics wipes segment:Cleanroom-compatible pre-saturated formats capture value in semiconductor wafer handling where particulate control exceeds spray application economics.
Industry Challenges
- Toxicological dossier compilation:REACH full registration requires extensive surfactant safety data, stretching regulatory affairs capacity at mid-size formulators.
- Legacy equipment incompatibility:Aqueous system transitions demand stainless steel 316 compatibility verification against existing aluminum and coated glass processing lines.
- Cross-jurisdictional PFAS tracking:Fragmented national restriction timelines complicate product portfolio planning as US EPA, EU ECHA, and state-level designations diverge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass and Metal Cleaner Market |
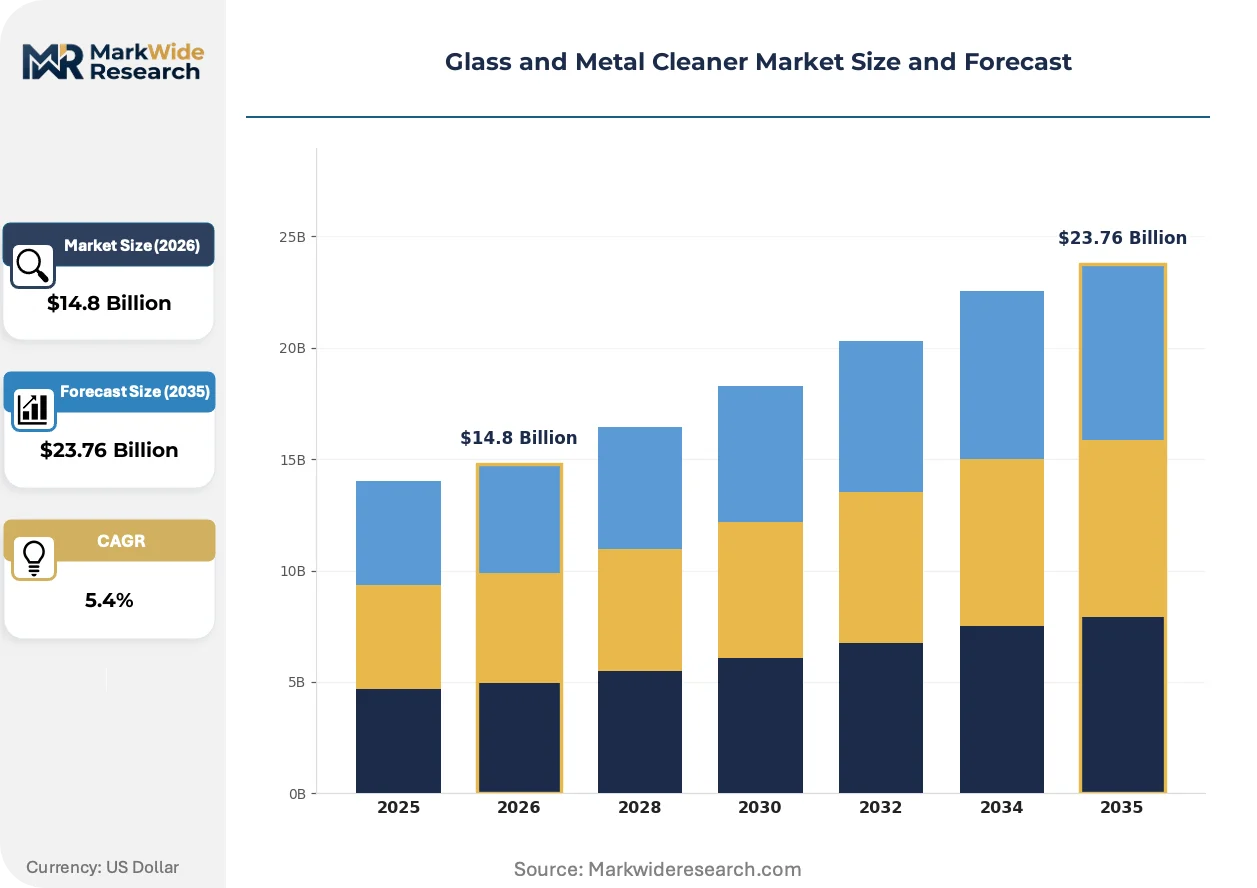
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprays, Liquids, Wipes, Foams, Powders Application: Commercial Buildings, Transportation Vehicles, Food Processing Equipment, Consumer Electronics Packaging Type: Aerosol Cans, Plastic Bottles, Refillable Containers, Disposable Packs, Trigger Sprayers End User Industry: Hospitality, Automotive Tier-1 Suppliers, Food & Beverage Facilities, Electronics Manufacturing |
| Companies Covered | SC Johnson Professional, Reckitt Benckiser Group plc, 3M Company, BASF SE, Dow Inc., Henkel AG & Co. KGaA, Stepan Company, Ecolab Inc., The Clorox Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass and Metal Cleaner Market Shifts & Advancements
Formulation chemistry is pivoting toward bio-based surfactant systems as regulatory pressure compounds with end-user sustainability procurement mandates. Delivery format innovation and service model restructuring are reshaping competitive positioning.
Alkyl polyglucoside surfactant systems are consolidating position in premium glass cleaning applications. Tier-1 automotive suppliers and aerospace maintenance operations specify these sugar-derived compounds for residue-free performance on coated optical substrates. The technology is consolidating supplier tiers as certification requirements favor formulators with in-house carbohydrate chemistry capabilities.
REACH Annex XVII restrictions on volatile organic compounds are forcing solvent portfolio reconstitution across European manufacturing. Formulators serving Germany's automotive and precision engineering clusters must demonstrate biodegradable degradation pathways for all surfactant components. Aqueous concentrate formats with mechanical trigger dispensing are capturing share from legacy aerosol products in facility maintenance contracts.
Refillable concentrate systems are displacing single-use packaging in hospitality and food service procurement. Hotel chains and restaurant groups specify bulk concentrate with reusable trigger bottles to meet internal sustainability scorecards and reduce storage footprint. This model compresses traditional distributor margins while rewarding formulators with direct fleet maintenance relationships and on-site technical service capabilities.
Glass and Metal Cleaner Market Segmentation
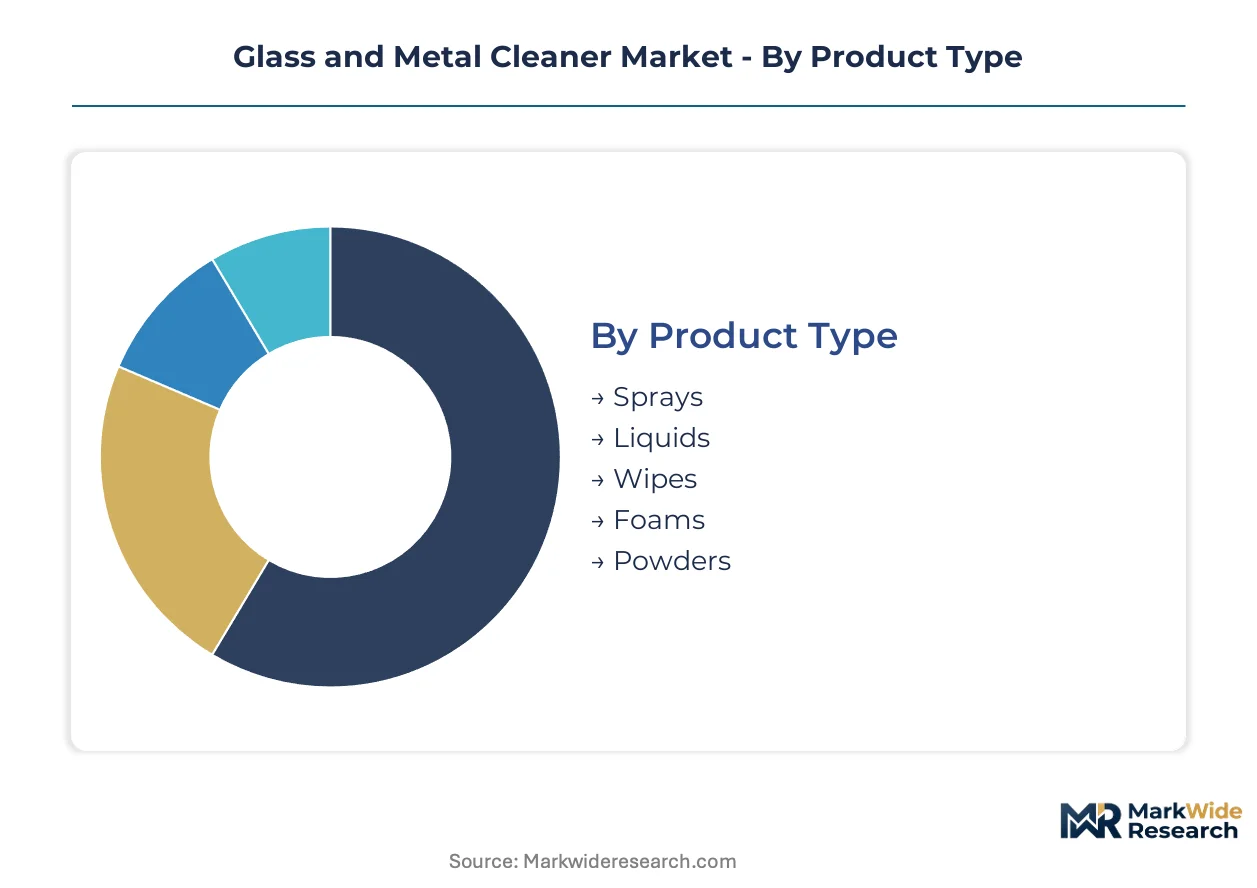
Glass and metal cleaner procurement splits along performance specifications, delivery economics, and regulatory exposure. Each axis reveals distinct margin structures and competitive moats that reshape supplier positioning across manufacturing and facility maintenance verticals.
Product Type:
Spray formats dominate commercial buildings due to controlled application economics, while wipes capture traction in electronics manufacturing where particulate control is critical. The hospitality segment favors concentrated liquids in refillable containers to minimize storage footprint and comply with sustainability procurement protocols.
- Sprays:Aqueous or solvent-based formulations containing surfactants, chelating agents, and pH modifiers designed to remove oils, fingerprints, and oxidation without etching substrates. Demand concentrates in facility maintenance contracts across Germany and the United States where EPA Safer Choice and REACH compliance filter supplier pools.
- Liquids:Concentrated aqueous systems requiring dilution at point of use, enabling bulk procurement and reduced logistics cost. Food and beverage facilities in China specify these formats for compatibility with on-site dispensing systems that reduce packaging waste.
- Wipes:Cleanroom-compatible pre-saturated formats with controlled particulate release for semiconductor wafer handling. Electronics manufacturing clusters in Jiangsu province and Austin, Texas drive specification pull where particulate control exceeds spray application economics.
- Foams:High-viscosity formulations for vertical surface cling on architectural glass and elevator panels. Commercial building service contractors in Dubai and Singapore specify these for reduced runoff and labor efficiency.
- Powders:Dry concentrate formats for industrial-scale dilution in automated wash systems. Automotive Tier-1 suppliers in Stuttgart and Detroit specify these for aluminum battery housing cleaning lines.
Sprays lead on scale; wipes lead on momentum.
Application:
End-use concentration determines formulation chemistry, residue specifications, and delivery format preferences across institutional and industrial procurement channels.
- Commercial Buildings:Daily maintenance of architectural glass, elevator stainless steel, and restroom fixtures drives high-volume, low-concentration consumption. Facility management contracts in New York and London specify streak-free performance at sub-50°C evaporation temperatures.
- Transportation Vehicles:Fleet operators and rail maintenance depots require rapid-dry formulations compatible with coated windshields and anodized aluminum trim. German KBA standards and US DOT specifications shape permissible ingredient profiles for interior and exterior applications.
- Food Processing Equipment:Sanitation protocols demand residue-free cleaning of stainless steel 304/316 surfaces with documented biodegradability. US FDA and EU EFSA compliance requirements filter supplier qualification in meatpacking and dairy processing clusters.
- Consumer Electronics:Precision cleaning of display glass, camera lenses, and aluminum enclosures requires ultra-low particulate and non-ionic surfactant systems. Manufacturing concentration in Shenzhen and Chennai shapes regional formulation preferences.
Commercial buildings anchor volume concentration; food processing equipment exhibits the steepest specification escalation.
Packaging Type:
Regulatory pressure on propellant chemistry and sustainability procurement mandates are restructuring delivery format economics across institutional channels.
- Aerosol Cans:Legacy hydrofluorocarbon propellant systems face displacement under EU F-Gas Regulation, compressing market share in European manufacturing clusters. Remaining demand concentrates in automotive aftermarket channels where portability outweighs regulatory exposure.
- Plastic Bottles:Standard trigger-spray and pour-cap formats for retail and light commercial distribution. China's SAMR packaging standards and California's rigid plastic recycling mandates reshape material specifications.
- Refillable Containers:Concentrate dilution systems with reusable trigger bottles capture hospitality procurement in Paris and Tokyo where sustainability scorecards drive vendor selection. Hotel chains specify these to reduce storage footprint and packaging waste.
- Disposable Packs:Single-use sachets and portion-controlled formats for travel and institutional trial programs. Aviation catering and cruise line provisioning in Miami and Singapore drive specification pull.
- Trigger Sprayers:Mechanical dispensing systems eliminating compressed gas propellants, gaining share from aerosol formats under REACH VOC restrictions. German automotive maintenance facilities specify these for workshop safety compliance.
Plastic bottles maintain volume dominance; refillable containers gain share fastest.
End User Industry:
Industry-specific residue limits, surface compatibility requirements, and regulatory exposure create distinct procurement criteria that fragment supplier positioning.
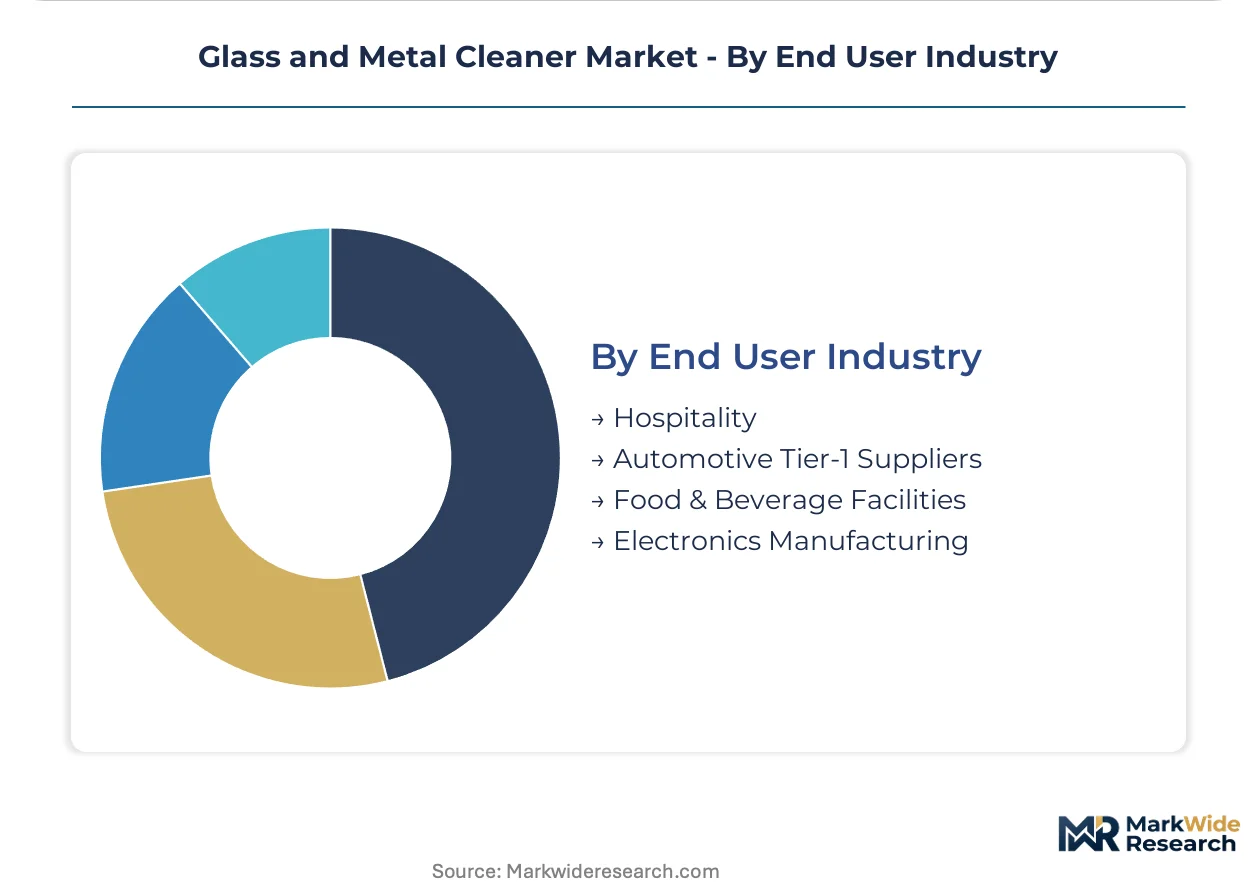
- Hospitality:Hotel chains and restaurant groups prioritize fragrance-free formulations and concentrated refill systems to meet internal sustainability protocols. Procurement in Dubai and Las Vegas emphasizes rapid-turnover cleaning economics for high-traffic properties.
- Automotive Tier-1 Suppliers:Precision cleaning of EV battery housings and coated display glass demands residue-free performance at controlled evaporation temperatures. Manufacturing clusters in Stuttgart, Shanghai, and Detroit specify aqueous systems with documented stainless steel 316 compatibility.
- Food & Beverage Facilities:Sanitation validation requirements under US FDA and EU EFSA mandate complete surfactant biodegradability documentation. Breweries and dairy processors in Wisconsin and Bavaria specify concentrated bulk delivery with automated dilution.
- Electronics Manufacturing:Cleanroom-grade particulate control and anti-static performance specifications dominate procurement for semiconductor and display fabrication. India's PLI scheme incentives for semiconductor manufacturing in Gujarat and Tamil Nadu create qualification urgency for BIS and CDSCO-compliant formulations.
Automotive Tier-1 suppliers concentrate specification authority; electronics manufacturing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as formulators migrate toward jurisdictions with lower compliance costs. Manufacturers serving REACH-bound European markets face margin pressure from toxicological dossier requirements, while exporters from India and Southeast Asia capture share through BIS and CDSCO qualification pathways.
United States
Automotive Tier-1 suppliers in Detroit and Austin drive specification pull for residue-free aqueous systems compatible with EV battery housings. EPA Safer Choice standards and OSHA worker exposure limits filter permissible surfactant chemistries. Manufacturing clusters in Michigan and Texas concentrate precision cleaning demand for coated display glass and anodized aluminum surfaces.
Germany
REACH Annex XVII restrictions on volatile organic compounds force solvent portfolio reconstitution across Stuttgart's automotive and precision engineering clusters. ECHA registration requirements mandate full toxicological dossiers for surfactant chemistries. Bavarian food and beverage facilities specify concentrated bulk delivery with automated dilution to meet EU EFSA compliance.
China
Electronics manufacturing in Jiangsu province and Shenzhen generates cleanroom-grade demand for pre-saturated wipes with controlled particulate release. SAMR packaging standards and dual carbon goals reshape material specifications and propellant selections. Shandong and Jiangsu provinces concentrate intermediate chemical supply for biodegradable surfactant systems.
India
PLI scheme incentives for semiconductor and display fabrication in Gujarat and Tamil Nadu create qualification urgency for BIS and CDSCO-compliant formulations. CDSCO mandates filter supplier pools for electronics manufacturing entrants. Cleanroom-compatible pre-saturated formats capture value in wafer handling operations where particulate control exceeds spray economics.
Japan
Automotive and electronics manufacturing in the Kanto and Kansai regions specify alkyl polyglucoside surfactant systems for residue-free performance on coated optical substrates. METI industrial standards and JIS certification requirements favor formulators with in-house carbohydrate chemistry capabilities. Tokyo-based hospitality chains drive refillable concentrate procurement to meet internal sustainability scorecards.
Glass and Metal Cleaner Market Competitive Landscape
Portfolio diversification dominates the current landscape as established chemical suppliers extend surfactant capabilities into formulated cleaner segments. The vendor base stratifies across three tiers: multinational diversified chemical conglomerates with captive raw material positions, specialized cleaning formulation houses with institutional channel relationships, and regional contract manufacturers serving private-label retail. Strategic archetypes include surfactant-backward-integrated players, on-site dispensing system operators, and cleanroom-grade wipe specialists. M&A activity and geographic expansion through distributor acquisition represent the dominant competitive vectors.
Among diversified chemical conglomerates, BASF SE and Dow Inc. occupy positions anchored by captive surfactant production capabilities. Ecolab Inc. exemplifies the on-site dispensing archetype through automated dilution systems for food and beverage facilities. SC Johnson Professional represents institutional channel dominance with fleet maintenance contract relationships across North America. These three companies illustrate how raw material control, service model innovation, and distribution depth respectively define competitive positioning in this fragmented market.
| Leading Market Players |
|---|
| SC Johnson Professional |
| Reckitt Benckiser Group plc |
| 3M Company |
| BASF SE |
| Dow Inc. |
| Henkel AG & Co. KGaA |
| Stepan Company |
| Ecolab Inc. |
| The Clorox Company |
| Others |
Supply & Pricing Matrix
Alkyl polyglucoside surfactant adoption is compressing cost curves for premium formulations while concentrating supplier qualification authority among carbohydrate chemistry specialists. This dual effect squeezes mid-tier formulators lacking in-house biotech capabilities and redirects procurement leverage toward REACH-certified European producers.
Pricing Analysis
Distributor margins in institutional channels absorb the steepest compression as Ecolab and SC Johnson Professional enforce volume rebates against independent regional suppliers. Three-tier pricing structure across premium, standard, and economy levels separates cleanroom-grade wipes from facility maintenance sprays and private-label retail formats. Cost compression in solvent-based tiers is intensifying because isopropyl alcohol feedstock volatility erodes formulation margins. Automotive Tier-1 suppliers exhibit the lowest price sensitivity due to residue-free specification premiums, while hospitality procurement teams drive aggressive concentrate dilution economics.
Supply Chain Analysis
REACH and CDSCO certification gating restricts qualified surfactant supply to formulators with documented toxicological dossiers and in-house carbohydrate chemistry capabilities. Intermediate chemical production concentrates in Shandong province, Jiangsu province, and the US Gulf Coast, drawing from bio-based feedstock streams and petrochemical derivatives. Single-source vulnerability in Chinese surfactant intermediates exposes formulators to regional environmental enforcement disruptions. Distribution runs through institutional chemical distributors in North America and direct technical sales teams for European automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Glass and Metal Cleaner Market functions as a stable compounder anchored by irreversible regulatory migration toward biodegradable surfactant systems. REACH compliance deadlines and PFAS phase-outs create predictable specification upgrade cycles that sustain replacement demand.
For Market Incumbents: To counter margin erosion from private-label concentrate formats, BASF and Dow should deepen backward integration into alkyl polyglucoside feedstocks and acquire regional distributors with automotive Tier-1 relationships. Captive surfactant production and direct fleet maintenance contracts defend pricing power against formulation commoditization. For New Entrants and Emerging Players: Capture India's PLI scheme-driven electronics manufacturing qualification window by securing BIS and CDSCO certifications for cleanroom-compatible wipes ahead of multinational incumbents. Gujarat and Tamil Nadu semiconductor clusters offer the most penetrable geography, with technical partnership routes through existing chemical distributors providing fastest market access. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-size European formulators with REACH dossiers but limited geographic reach, offering rollup platforms for Indian and Southeast Asian expansion. The five-to-ten-year viability thesis rests on surfactant chemistry transition permanence. Watch for CDSCO qualification announcements from contract manufacturers as inflection signals for regional share capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Surfactants | Captures margin from alkyl polyglucoside supply scarcity under REACH Annex XVII pressure. |
| On-site Dispensing System Deployment | Ecolab's automated dilution model reduces packaging waste for Bavarian dairy processing facilities. |
| CDSCO Qualification Investment | First-mover certification for Gujarat semiconductor fabs ahead of PLI scheme capacity ramps. |
| Refillable Concentrate Format Launch | Tokyo hospitality chains specify reusable trigger bottles to meet internal sustainability scorecards. |
| PFAS-free Anti-fog R&D Partnership | Functional replacement development addresses EU ECHA and US EPA accelerating restriction timelines. |
Research Methodology
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each market informing cross-regional pattern detection. The analysis combines structured interviews with formulation chemists, automotive Tier-1 procurement directors, hospitality facility managers, and regulatory affairs specialists at ECHA and EPA with secondary validation from REACH registration databases, SAMR packaging standards filings, SEC 10-K chemical segment disclosures, and customs trade flow records. Bottom-up demand modeling triangulates against top-down market sizing across each regional cluster.
Granularity extends to product type, application vertical, packaging format, and end-user industry dimensions, with additional modeling of certification tier effects on supplier qualification pools. Value projections across the analysis window derive from segment-level volume forecasts multiplied by pricing stratification across premium, standard, and economy tiers, with CAGRs calibrated to historical surfactant chemistry transition rates and regulatory deadline impacts. EV battery manufacturing demand and PFAS substitution timelines served as primary industry-specific forecast inputs.
REACH enforcement intensity, isopropyl alcohol feedstock volatility, and Indian PLI scheme implementation pace are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding regulatory timeline adherence and surfactant technology substitution curves. A model refresh is warranted upon material change in EU ECHA PFAS restriction finalization or CDSCO electronics manufacturing qualification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Industrial Cleaners Market
Cleaning Chemicals
Europe Metal Cleaning Chemicals Market
Cleaning Chemicals
Firefighting Chemicals Market
Cleaning Chemicals
Global Cationic Reagent Market
Cleaning Chemicals
Southeast Asia Surface Treatment Chemicals Market
Cleaning Chemicals
Water-Saving Cleaning Chemical Systems for Professional Use Market
Cleaning Chemicals
Home Insecticides Market
Cleaning Chemicals
Bleaching Chemicals Market
Cleaning Chemicals
Micellar Cleansing Water Market
Cleaning Chemicals
Cleaning Nozzles Market
Cleaning Chemicals
Floor Wax Market
Cleaning Chemicals
Document Cleaning Powder Market
Cleaning Chemicals
Instrument Cleaners and Detergents Market
Cleaning Chemicals
Cement Surface Treatment Chemicals Market
Cleaning Chemicals
North America Metal Cleaning Chemicals Market
Cleaning Chemicals
Industrial Degreaser Market