
 Water and Wastewater Pipe Market | 2026-2036
Water and Wastewater Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Water and Wastewater Pipe Market Intelligence
The adoption of high-performance, corrosion-resistant materials like HDPE and advanced ductile iron is redrawing the competitive landscape for municipal utilities. JM Eagle Inc. leverages its significant manufacturing scale in North America to serve large-scale public works projects. China Lesso Group Holdings Limited dominates the Asian market through a vast portfolio of plastic piping solutions. Meanwhile, Georg Fischer Ltd. differentiates with specialized jointing systems and engineered solutions for industrial applications.
Water and wastewater pipes are engineered conduits designed to transport potable water, sewage, and stormwater under pressure or gravity. These systems are specified by material, like PVC or ductile iron, and performance metrics including pressure ratings and diameter. Plastic materials command a majority share of new installations due to corrosion resistance and lower lifecycle costs. The large diameter pipe segment is expanding for major water transmission and stormwater drainage projects.
Regulations from the US EPA and standards like the EU's CE marking mandate material safety and performance for potable water contact. Global ISO standards provide a baseline for quality assurance in pipe manufacturing, influencing material selection. Future investment decisions will balance initial material costs against total lifecycle expense and long-term water loss reduction.
Market Dynamics
The central dynamic shaping the market is the dual pressure of replacing deteriorating water infrastructure in developed economies while simultaneously building new, large-scale systems in rapidly urbanizing nations, driving material innovation and specialized installation methods.
Growth Catalysts
- Government-Led Programs:National initiatives in countries like India are channeling significant public funds into expanding potable water access and modernizing sanitation networks, creating large-scale, long-term demand for all pipe types.
- Trenchless Technologies:The adoption of horizontal directional drilling and pipe bursting for HDPE and PVC pipe installation is reducing project costs and timelines in congested urban areas, accelerating infrastructure renewal cycles.
- Aging Infrastructure Replacement:Municipal utilities in North America and Europe are systematically replacing decades-old cast iron and asbestos cement pipes to reduce water loss and comply with stricter public health mandates.
Market Restraints
- Raw Material Volatility:Price fluctuations in key feedstocks, including PVC resins, polyethylene, and iron ore, create margin pressure for manufacturers and introduce uncertainty into project bidding for contractors.
- High Initial Capital Outlay:The significant upfront investment required for large-diameter transmission lines and associated civil engineering works can delay or defer critical infrastructure projects, especially in capital-constrained municipalities.
- Logistical Complexity:Transporting and handling large-diameter pipes, particularly sections over 48 inches, presents considerable logistical challenges that increase project costs and require specialized equipment and expertise.
Strategic Opportunities
- Smart Pipe Integration:Embedding fiber optics and acoustic sensors into new pipe systems offers a path to real-time leak detection and pressure monitoring, creating a new market for high-value, data-enabled infrastructure.
- Rural Water Systems:Underdeveloped rural water and sanitation networks across Southeast Asia and Africa represent a major area for expansion, particularly for lower-cost, easy-to-install plastic piping solutions.
- Wastewater Reuse Projects:Increasing focus on water circularity and reuse is driving demand for specialized, corrosion-resistant piping systems capable of transporting treated effluent for industrial or agricultural applications.
Industry Challenges
- Skilled Labor Shortages:A deficit of certified welders for HDPE pipe fusion and trained operators for trenchless installation equipment creates bottlenecks, slowing project execution and increasing labor costs for specialized work.
- Legacy System Integration:Connecting modern plastic or ductile iron pipes to aging networks made of disparate materials like clay or concrete often requires custom-fabricated adapters and presents risks of joint failure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water and Wastewater Pipe Market |
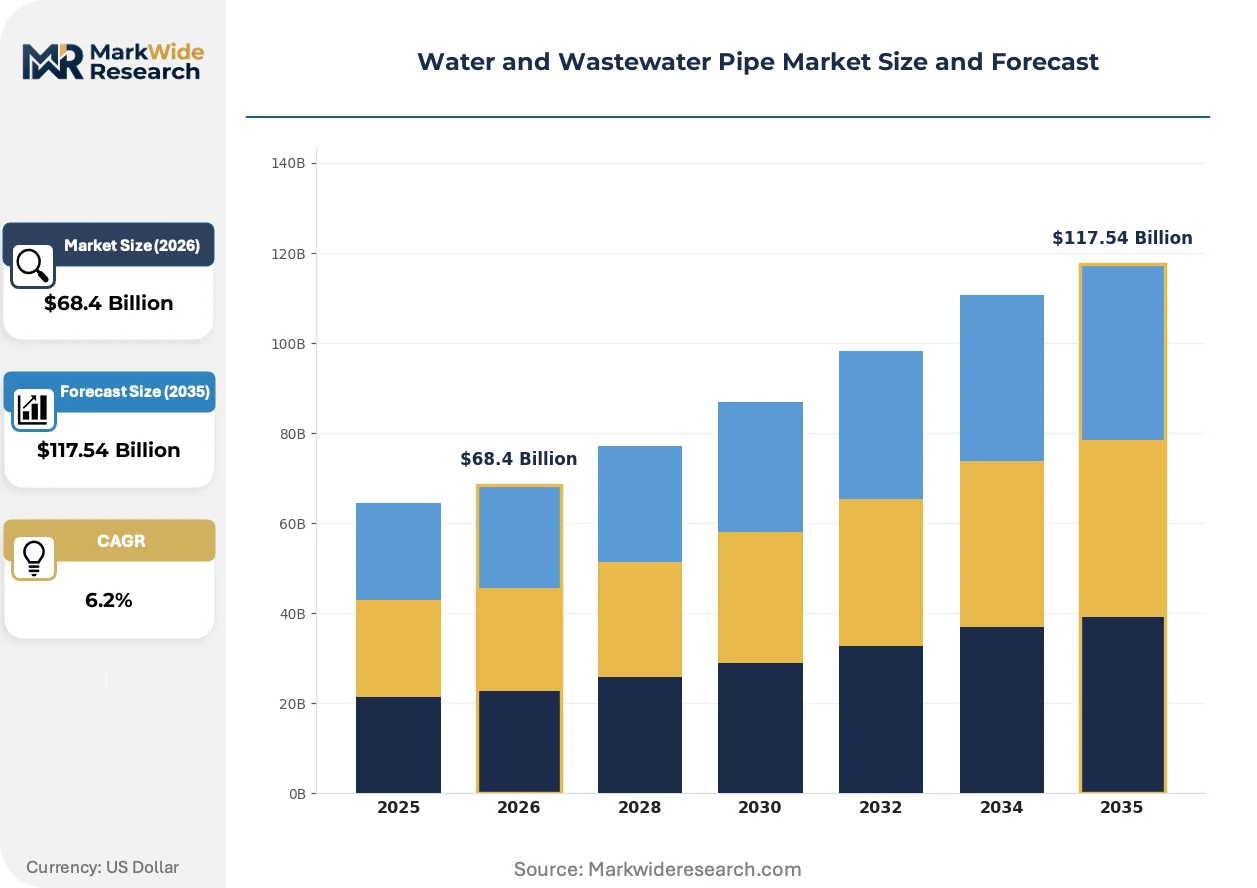
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $117.54 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: PVC, HDPE, Ductile Iron, Stainless Steel, Concrete, Fiberglass Pipe Diameter: Small Diameter, Medium Diameter, Large Diameter, Extra Large Diameter Application: Municipal Water Supply, Industrial Effluent Management, Agricultural Irrigation, Residential Plumbing, Stormwater Drainage End User: Water Utilities, Manufacturing Plants, Agricultural Farms, Residential Complexes, Commercial Facilities |
| Companies Covered | JM Eagle Inc., China Lesso Group Holdings Limited, Saint-Gobain, Tenaris S.A., Advanced Drainage Systems Inc., Aliaxis Group S.A., Georg Fischer Ltd., Sekisui Chemical Co. Ltd., Tata Steel Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water and Wastewater Pipe Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive shift toward assessing total lifecycle cost and system resilience, moving procurement decisions beyond initial material expense. This reevaluation prioritizes long-term performance, water loss reduction, and operational efficiency for utility asset managers.
Trenchless installation methods, including horizontal directional drilling and pipe bursting, provide a less disruptive alternative to traditional open-cut excavation. Municipal utilities in dense urban centers are the primary adopters, seeking to minimize traffic and business disruption during infrastructure upgrades. This technology is fragmenting the conventional installation market, creating a premium segment for specialized contractors with advanced boring and guidance capabilities.
Global ISO standards provide a foundational framework for quality assurance in pipe manufacturing, influencing material selection for public works. These standards establish benchmarks for pressure ratings, material purity for potable water contact, and joint integrity. The potable water segment is most affected as utilities worldwide increasingly reference ISO certifications to ensure public safety and secure project financing from international development banks.
Municipal buyers are modifying evaluation criteria to favor total lifecycle cost over initial material price. This behavioral change reduces the emphasis on commodity-grade pipes, creating an advantage for materials like HDPE and advanced ductile iron that promise lower long-term maintenance and reduced water leakage. This shift is most pronounced in water-stressed regions of the US Southwest and the Middle East, where minimizing non-revenue water is a critical operational priority.
Water and Wastewater Pipe Market Segmentation
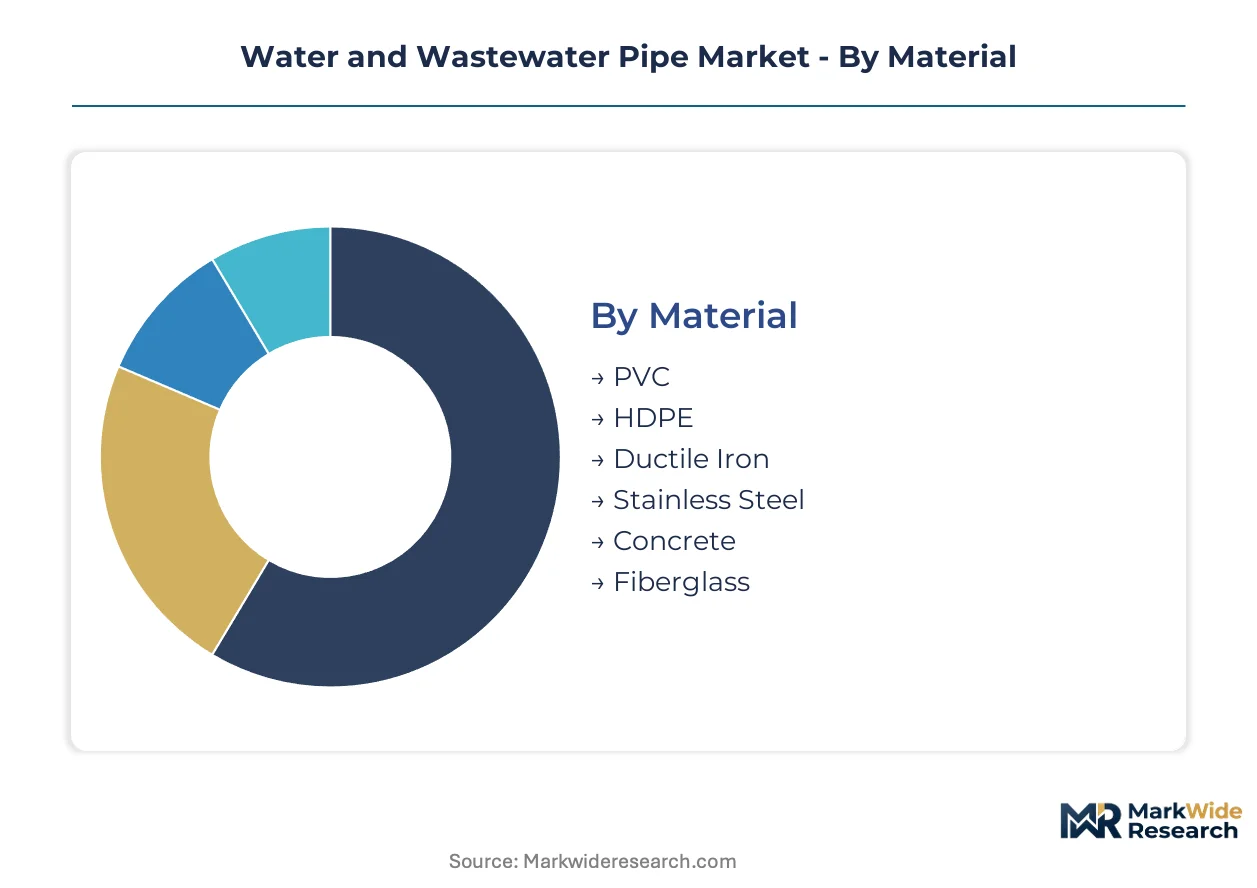
Understanding the Water and Wastewater Pipe Market through segmentation reveals distinct demand patterns and technological preferences across various applications and end-user groups. This granular view helps identify regions with infrastructure deficits and areas driving material innovation and specialized installation methods.
Material:
The material segment highlights distinct product lifecycles and performance characteristics, with some materials dominating domestic infrastructure projects while others are favored for export-led initiatives in developing economies.
- HDPE:High-density polyethylene pipes offer superior corrosion resistance and flexibility, making them ideal for trenchless installation methods like horizontal directional drilling. Demand concentrates in North America and Europe for aging infrastructure replacement projects, reducing urban disruption.
- Ductile Iron:These pipes provide high tensile strength and pressure resistance, suitable for large-diameter water transmission mains and high-pressure sewage systems. Utilities in India and Southeast Asian nations frequently specify ductile iron for new, large-scale water distribution networks due to its durability.
- PVC:Polyvinyl chloride pipes are cost-effective and lightweight, finding extensive use in residential plumbing and smaller-scale municipal distribution networks.
- Stainless Steel:Stainless steel pipes serve specialized industrial applications requiring high purity and extreme corrosion resistance, particularly in chemical processing plants.
- Concrete:Concrete pipes are traditionally used for large-diameter stormwater drainage and gravity-fed sewage systems due to their strength and cost-effectiveness.
- Fiberglass:Fiberglass pipes offer excellent chemical resistance and a high strength-to-weight ratio, often employed in wastewater treatment plants and corrosive industrial environments.
PVC holds the largest share; momentum sits with HDPE.
Pipe Diameter:
Pipe diameter categories reflect the diverse functional requirements of water and wastewater systems, from localized distribution to long-distance transmission and large-volume stormwater management.
- Large Diameter:Pipes exceeding 24 inches are critical for major water transmission lines, municipal trunk sewers, and significant stormwater drainage projects. These pipes are expanding for large-scale infrastructure developments in urbanizing areas like Mumbai, India, and Jakarta, Indonesia.
- Extra Large Diameter:Pipes over 48 inches are utilized for regional water conveyance, large-scale flood control, and industrial process water transfer, requiring specialized logistical and installation expertise. Demand for these pipes is growing in arid regions of the US Southwest for long-distance water transport.
- Small Diameter:Pipes typically under 6 inches serve residential service connections, localized irrigation, and small-scale commercial plumbing.
- Medium Diameter:Pipes ranging from 6 to 24 inches are common in municipal distribution networks and industrial process piping, balancing flow capacity with installation flexibility.
The large diameter segment accounts for the highest volume; the extra large diameter segment is expanding most quickly.
Application:
Application segments delineate the specific end-uses for water and wastewater pipes, each driven by unique regulatory frameworks and infrastructure development priorities.
- Municipal Water Supply:This segment involves pipes for potable water distribution from treatment plants to end-users, driven by public health mandates and infrastructure replacement programs. Significant government-led programs in India are expanding potable water access, creating substantial demand.
- Industrial Effluent Management:Pipes in this application transport wastewater from manufacturing and processing facilities, often requiring specialized materials due to chemical content or high temperatures. Increasing focus on water circularity in Germany drives demand for these systems.
- Agricultural Irrigation:Pipes deliver water to agricultural fields, with demand influenced by water scarcity and efficiency mandates in regions like the US Central Valley.
- Residential Plumbing:These pipes form the internal water supply and drainage systems within homes, guided by building codes and material safety standards.
- Stormwater Drainage:Pipes manage rainwater runoff in urban areas, preventing flooding and protecting infrastructure, with demand tied to urbanization and climate change adaptation.
Municipal Water Supply represents the largest application area; Industrial Effluent Management shows the steepest expansion trajectory.
End User:
End-user segments reflect the primary organizations or entities responsible for pipe procurement, installation, and maintenance, each with distinct purchasing criteria and project scales.
- Water Utilities:These entities manage public water supply and wastewater treatment systems, driving large-scale procurement for infrastructure development and rehabilitation projects. Municipal utilities in North America and Europe are systematically replacing aging infrastructure.
- Manufacturing Plants:Industrial facilities use pipes for process water, cooling systems, and effluent discharge, prioritizing material compatibility and operational reliability. Chemical and food processing plants in Germany require specialized solutions.
- Agricultural Farms:Farms utilize piping for irrigation systems, with decisions often balancing initial cost against water efficiency and durability in outdoor environments.
- Residential Complexes:Developers and contractors for multi-unit housing projects procure pipes for internal water and drainage systems, emphasizing cost-effectiveness and ease of installation.
- Commercial Facilities:This segment includes pipes for offices, retail centers, and other commercial buildings, focusing on compliance with local building codes and system longevity.
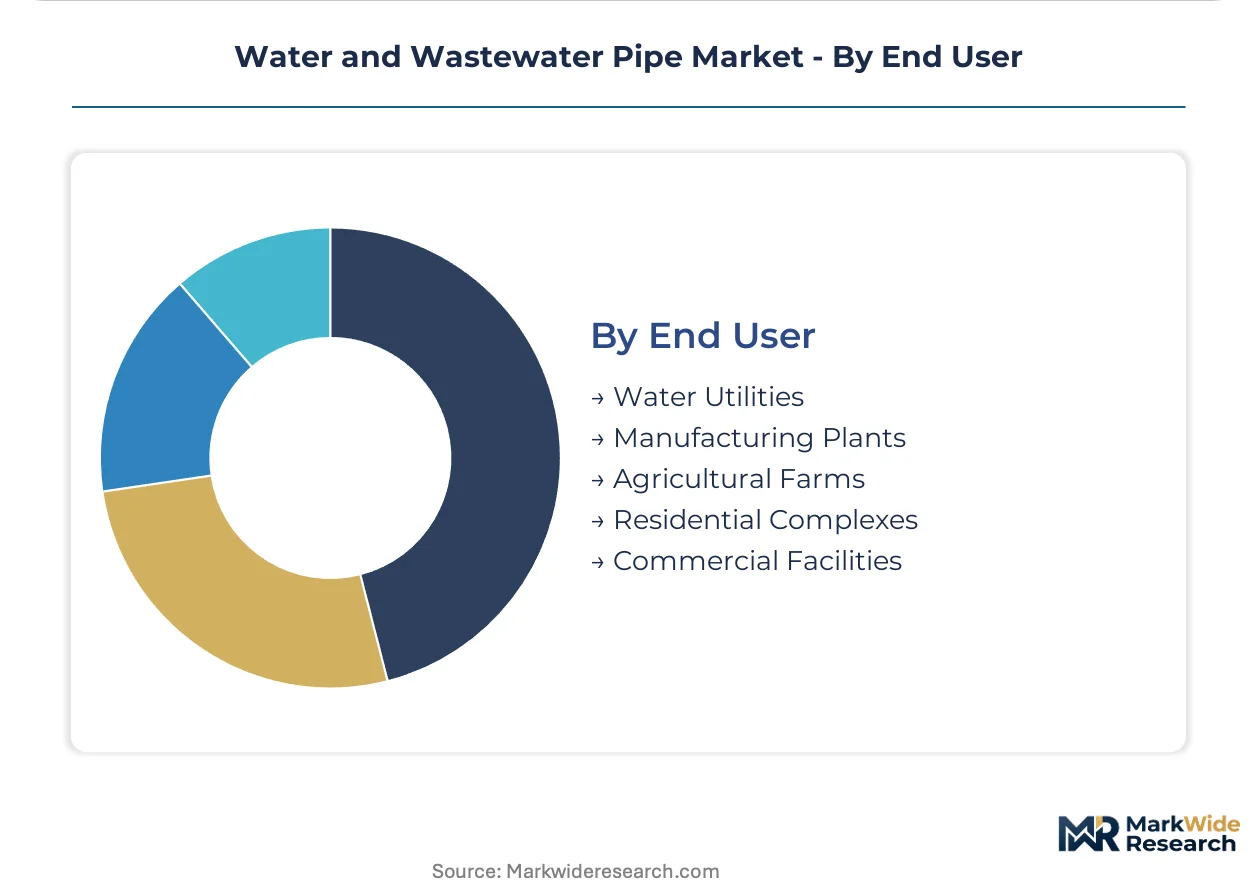
Water Utilities account for the largest procurement volume; Manufacturing Plants are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Water and Wastewater Pipe Market exhibits a complex interplay between mature economies focusing on infrastructure renewal and developing nations prioritizing new system construction. This dynamic creates distinct demand patterns for pipe materials and installation technologies. Export-import balances frequently shift based on regional raw material availability and local manufacturing capabilities.
India
National initiatives in India are channeling significant public funds into expanding potable water access and modernizing sanitation networks. The government's Jal Jeevan Mission, for instance, aims to provide piped water to all rural households. Cities like Mumbai are witnessing large-scale infrastructure developments, driving substantial demand for ductile iron and large-diameter pipes.
United States
Municipal utilities in the United States are systematically replacing decades-old cast iron and asbestos cement pipes to reduce water loss. The US EPA regulations mandate stricter public health standards for potable water contact, accelerating infrastructure renewal. The US Southwest, particularly in arid regions, focuses on minimizing non-revenue water, driving demand for advanced materials like HDPE.
Germany
European environmental mandates in Germany emphasize water circularity and wastewater reuse projects, driving demand for specialized piping systems. The EU's CE marking ensures material safety and performance for potable water applications. The Rhine-Ruhr region, with its dense industrial base, requires corrosion-resistant piping for industrial effluent management.
China
Rapid urbanization in China necessitates the construction of new, large-scale water and wastewater systems across its expanding cities. The country's dual carbon goals influence material selection toward more sustainable and energy-efficient pipe production. The Yangtze River Delta region is a hub for new municipal water transmission and distribution network projects.
Brazil
Significant infrastructure gaps in Brazil, particularly in underdeveloped rural water and sanitation networks, represent a major area for expansion. ANVISA regulations guide material safety for potable water applications. The state of São Paulo, a densely populated area, requires continuous investment in expanding and upgrading its water supply infrastructure.
Water and Wastewater Pipe Market Key Industry Players
Listed leaders compete with private specialists across manufacturing scale and technological differentiation in the water and wastewater pipe market. The market structure features a mix of large, diversified conglomerates, specialized regional providers, and material-focused innovators. Strategic archetypes include high-volume commodity producers, engineered solutions providers for complex projects, and niche material specialists. Capacity expansion and portfolio diversification represent dominant competitive moves among these players, alongside strategic partnerships for advanced installation methods.
Within the engineered solutions segment, Georg Fischer Ltd. differentiates with specialized jointing systems and engineered solutions tailored for industrial applications. JM Eagle Inc. exemplifies the high-volume commodity producers, leveraging its significant manufacturing scale in North America to serve large-scale public works projects. China Lesso Group Holdings Limited anchors the Asian market, representing large-scale plastic piping solutions across a vast portfolio. These companies illustrate the varied approaches to market penetration, from geographic dominance to specialized product offerings, and highlight the diverse strategies employed for value creation in this sector.
| Leading Market Players |
|---|
| JM Eagle Inc. |
| China Lesso Group Holdings Limited |
| Saint-Gobain |
| Tenaris S.A. |
| Advanced Drainage Systems Inc. |
| Aliaxis Group S.A. |
| Georg Fischer Ltd. |
| Sekisui Chemical Co. Ltd. |
| Tata Steel Limited |
Cost & Logistics Intelligence
Project-based contracts for large-diameter pipe systems lock in both supply access and price visibility for municipal utilities. This structure mitigates raw material volatility and ensures long-term project execution for critical infrastructure.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing, which prioritizes long-term material supply agreements. Price differentiation stems from material quality and specialized jointing systems, with ISO certifications commanding a premium. Pricing pressure stems from raw material volatility in PVC resins and iron ore, impacting manufacturer margins. Smaller municipal and agricultural buyers are more price-sensitive, while large-scale water utilities prioritize long-term performance.
Supply Chain Analysis
Long lead times for specialized large-diameter pipes necessitate strategic inventory management for project developers. Geographic supply concentrates in China for plastic piping, India for ductile iron, and North America for HDPE, drawing from PVC resins, polyethylene, and iron ore. Logistical complexity for extra-large diameter pipes presents a structural risk. Distribution typically runs through direct sales to water utilities and specialized contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Water and Wastewater Pipe Market is entering a cyclical recovery, driven by renewed government infrastructure spending in developed and developing economies. This investment addresses aging systems and expands access to critical services.
For Market Incumbents: Shield core market share by deepening vertical integration into raw material production, particularly for HDPE and ductile iron. Invest in advanced manufacturing capabilities to counter specialized material threats from fiberglass and stainless steel. Expand geographic footprint in high-growth regions like India and Southeast Asia through strategic partnerships. Focus R&D on smart pipe integration to offer data-enabled infrastructure.
For New Entrants and Emerging Players: Lead with specialized trenchless installation technologies, targeting urban infrastructure renewal projects in North America and Europe. The most penetrable segment lies in rural water systems across Southeast Asia, where lower-cost plastic piping solutions are critical. Offer bundled solutions combining pipe supply with certified installation services as a go-to-market angle. Focus on HDPE and PVC materials for ease of deployment.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap engineered solutions providers with strong intellectual property in jointing systems or smart pipe technologies. The long-term viability of this market hinges on sustainable infrastructure development and water loss reduction. Target companies with established market presence in high-growth regions and strong government ties. The signal to watch is the acceleration of national water security mandates in water-stressed regions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases production volume for high-demand materials like HDPE and ductile iron. |
| Backward Integration | Secures supply of critical raw materials such as PVC resins and iron ore. |
| Joint Venture | Facilitates market entry and technology transfer in developing economies for new systems. |
| Product Diversification | Expands offerings into specialized segments like smart pipes and wastewater reuse systems. |
| Certification Investment | Ensures compliance with global ISO standards and regional regulations for potable water. |
Research Approach
Operator-level perspectives from water utility managers, civil engineering contractors, and material procurement specialists anchored the qualitative base for this analysis. Primary interviews were combined with secondary validation from US EPA reports, EU CE marking guidelines, and ISO standards. This approach facilitated bottom-up and top-down triangulation of market dynamics. National infrastructure development plans provided crucial context.
Sensitivity analysis examined various scenarios for infrastructure investment and raw material costs across the analysis window. The analytical framework modeled segmentation dimensions including material type, pipe diameter, application, and end-user. Compound annual growth rates were derived from historical trends and projected government infrastructure budgets. Urbanization rates and water scarcity mandates served as key forecast inputs.
Underlying assumptions cover stable geopolitical conditions and predictable raw material supply, with deviation risk concentrated in economic downturns or unforeseen policy changes. Forecasts reflect these assumptions, acknowledging potential impacts from fluctuating commodity prices. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Global Municipal Pipes Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
Stainless Steel Plumbing Pipes Market
Pipes and Tubes
Global Flexible Pipes Market
Pipes and Tubes
North America Hydraulic Fluid Connectors Market
Pipes and Tubes
Coiled Tubing Manufacturing Market
Pipes and Tubes
Saudi Arabia Copper Pipes and Tubes Market
Pipes and Tubes
Global Polyethylene Pipes and Fittings Market
Pipes and Tubes
Global Cured-In-Place Pipe Market
Pipes and Tubes
Stainless Steel Tank Container Market
Pipes and Tubes
Acid Resistant Pipe Market
Pipes and Tubes
HDPE Corrugated Pipe Market
Pipes and Tubes
Saudi Arabia PPR Pipes Market
Pipes and Tubes
Germany Acid Proof Lining Market
Pipes and Tubes
Plastic Pipes and Fittings Market
Pipes and Tubes
GCC PVC Pipes Market